
 Aviation Carbon Fiber Market | 2026-2036
Aviation Carbon Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Carbon Fiber Market Analysis
Commercial aviation is pivoting toward higher carbon fiber content in next-generation narrowbody programs. Hexcel Corporation sustains its position through captive aerospace prepreg capacity and long-term airframe contracts. Toray Industries, Inc. dominates PAN-based precursor supply chains across Japanese and US manufacturing nodes. SGL Carbon SE specializes in automotive-to-aerospace carbon fiber transfer, leveraging European process expertise.
Aviation carbon fiber denotes high-performance polyacrylonitrile-derived or pitch-based fibers, typically modulus-rated above 230 GPa and tensile strength exceeding 3,500 MPa, engineered for primary and secondary aircraft structures where specific stiffness and fatigue resistance outweigh metallic alternatives. Prepreg formats lead value capture due to autoclave-cured wing and fuselage applications, while resin transfer molding gains traction in engine component geometries requiring complex net-shape fabrication. Carbon fiber composites occupy the fastest-expanding application tier as original equipment manufacturers redesign load-bearing structures around thermoplastic matrix systems.
FAA certification standards and the EU Green Deal emissions framework jointly pressure airframers toward documented lifecycle carbon reductions in material selection. EASA material qualification protocols and REACH chemical compliance add European regulatory layers that shape supplier market access and product formulation choices. Stakeholders must monitor thermoplastic recycling pathway maturation and precursor energy intensity disclosures as procurement criteria harden.
Market Dynamics
Thermoplastic prepreg qualification timelines are compressing as airframers face FAA reauthorization mandates and EU Green Deal emissions deadlines simultaneously. This dual-regulatory squeeze forces material suppliers to accelerate certification pathways while maintaining structural performance thresholds for primary aircraft structures.
Growth Catalysts
- EU Green Deal:Binding emissions reduction targets force commercial airlines to prioritize lightweight composite structures in fleet renewal programs, directly expanding carbon fiber procurement volumes for narrowbody platforms.
- Autoclave-cured wing applications:Prepreg formats command premium positioning in primary structures where specific stiffness requirements exceed metallic alternatives, sustaining value capture despite processing complexity.
- United States manufacturing nodes:Boeing supplier base concentration anchors North American demand, with precursor-to-prepreg vertical coordination reducing qualification friction for new airframe contracts.
Market Restraints
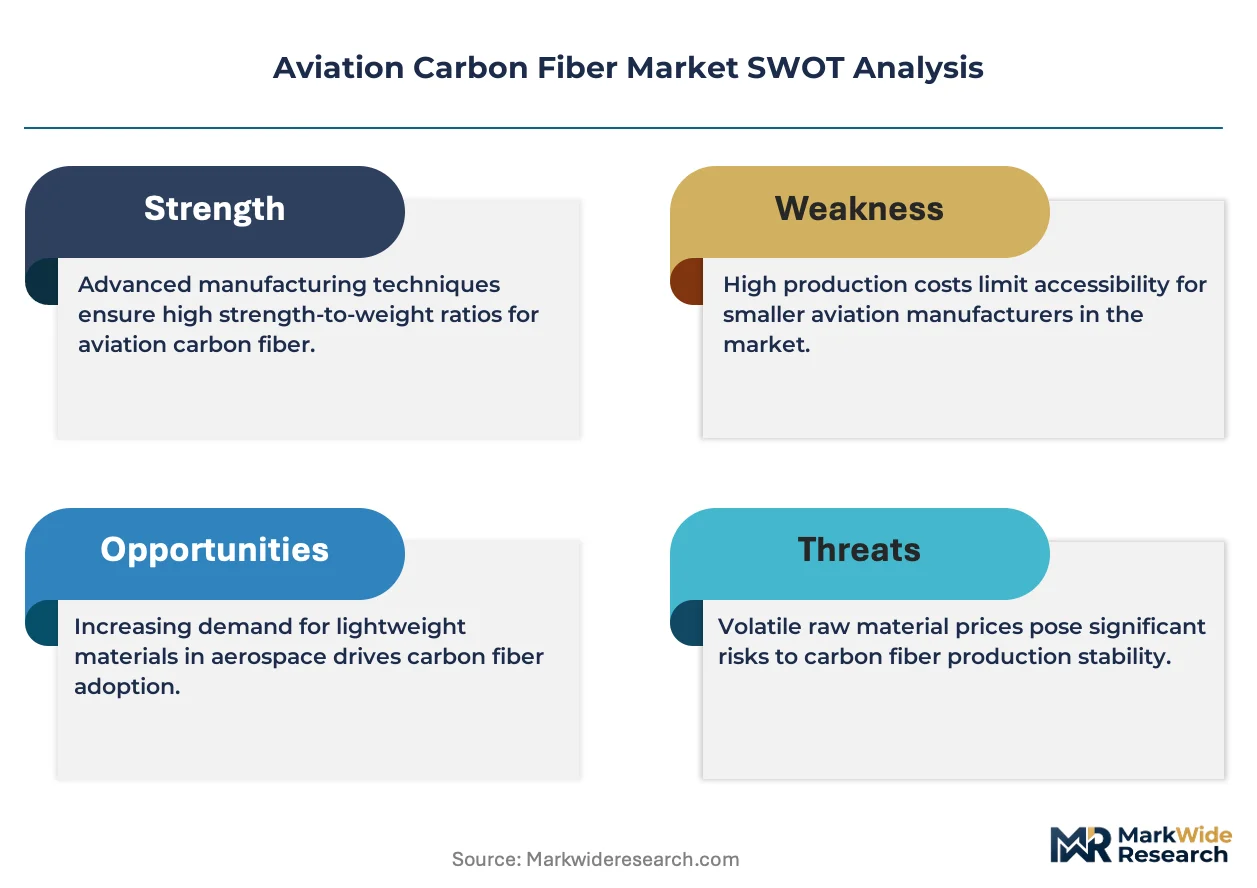
- Acrylonitrile feedstock volatility:PAN-based precursor production remains exposed to petrochemical input swings, compressing margin predictability for fiber manufacturers without long-term supply agreements.
- Japanese precursor dominance:Toray Industries and consolidated Japanese suppliers control critical PAN supply nodes, creating geographic concentration risk for Western airframers seeking supply assurance.
- EASA material qualification protocols:Extended certification timelines for thermoplastic matrix systems delay revenue recognition and freeze working capital in pre-production inventory.
Strategic Opportunities
- Resin transfer molding:Complex net-shape engine component geometries offer white space beyond traditional wing and fuselage applications, enabling tier-two suppliers to bypass prepreg incumbent lock-in.
- REACH chemical compliance:Reformulation requirements for European market access create openings for water-based sizing agents and reduced-VOC curing systems that meet ECHA disclosure thresholds.
- Thermoplastic recycling pathway maturation:Closed-loop fiber recovery technologies align with documented lifecycle carbon reduction procurement criteria emerging in airline sustainability frameworks.
Industry Challenges
- Autoclave operator scarcity:Specialized technician pipelines for high-pressure curing operations lag capacity expansion timelines, constraining throughput at composite fabrication facilities.
- FAA-EASA harmonization gaps:Divergent damage tolerance certification standards for primary structures force redundant testing protocols, extending program development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Carbon Fiber Market |
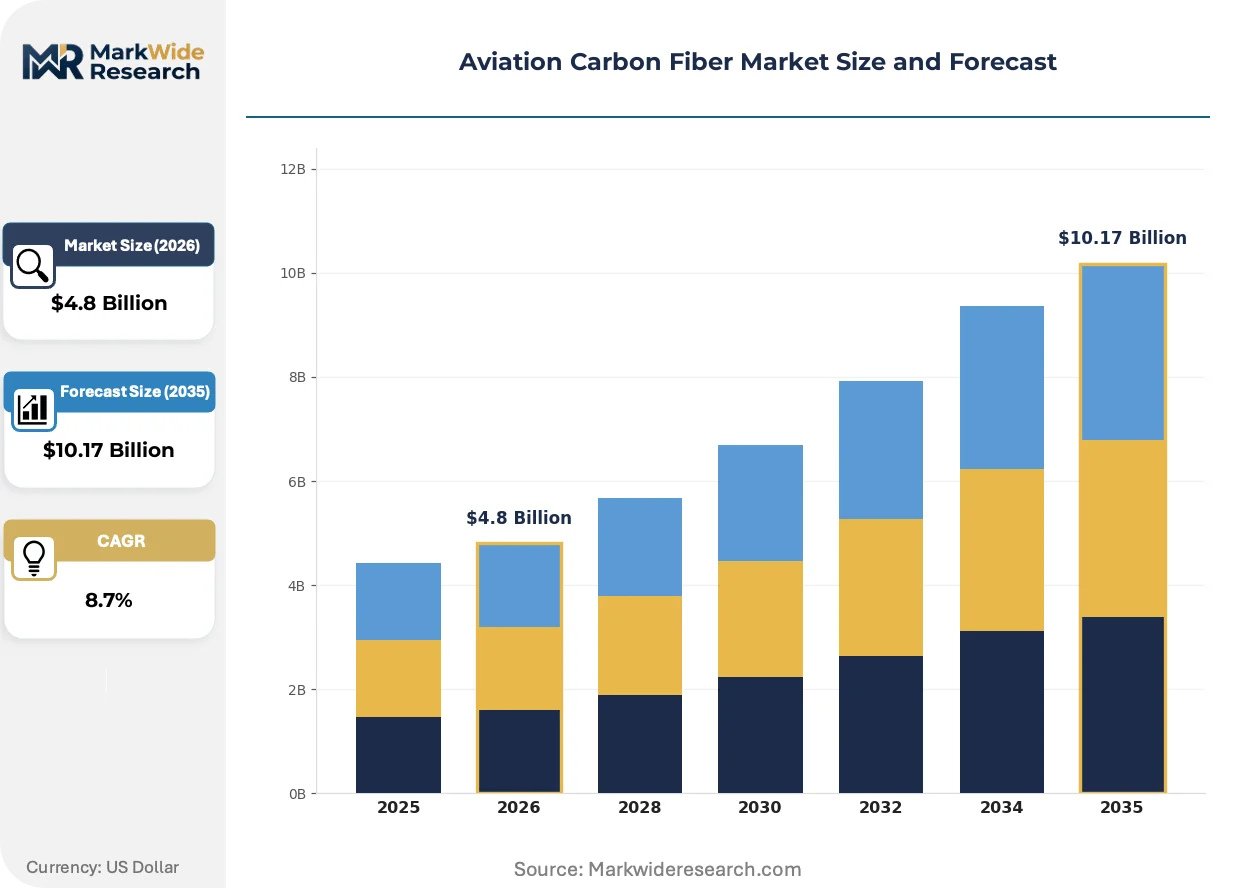
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prepreg, Reinforced Plastics, Carbon Fiber Composites, Carbon Fiber Fabrics Application: Aerospace Structures, Aircraft Interiors, Engine Components, Landing Gear End User: Commercial Aviation, Military Aviation, Business Aviation, General Aviation Manufacturing Process: Filament Winding, Layup, Resin Transfer Molding, Pultrusion |
| Companies Covered | Toray Industries, Inc., Hexcel Corporation, SGL Carbon SE, Solvay S.A., TEIJIN LIMITED, Mitsubishi Chemical Group, DuPont de Nemours, Inc., Bally Ribbon Mills, BGF Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Carbon Fiber Market Emerging Trajectories
Material-process convergence is redefining competitive boundaries between fiber producers and airframe integrators. Three developments dominate the current transformation cycle.
Thermoplastic matrix systems are consolidating their position in next-generation load-bearing structures. Airbus and Boeing procurement teams specify PEEK and PPS-based prepregs for wing ribs and access panels where reparability and weldability outweigh thermoset processing familiarity. This shift compresses the traditional autoclave-dominated supply chain into continuous compression molding and automated fiber placement workflows.
REACH chemical compliance deadlines are forcing reformulation across European-qualified product lines. ECHA substance restrictions on legacy hardeners and sizing chemistries compel suppliers to validate alternative formulations without compromising interlaminar fracture toughness. German and French airframe subcontractors face the steepest requalification burdens as they hold the largest installed bases of legacy epoxy systems.
Airline technical procurement teams now mandate precursor energy intensity disclosures as standard RFP criteria. Sustainability-linked sourcing contracts reward fiber manufacturers with verified low-carbon acrylonitrile supply chains, particularly in Scandinavian carrier fleets where national emissions accounting rules penetrate downstream procurement. This behavioral shift elevates energy transparency to parity with mechanical performance specifications in supplier selection.
Aviation Carbon Fiber Market Segmentation
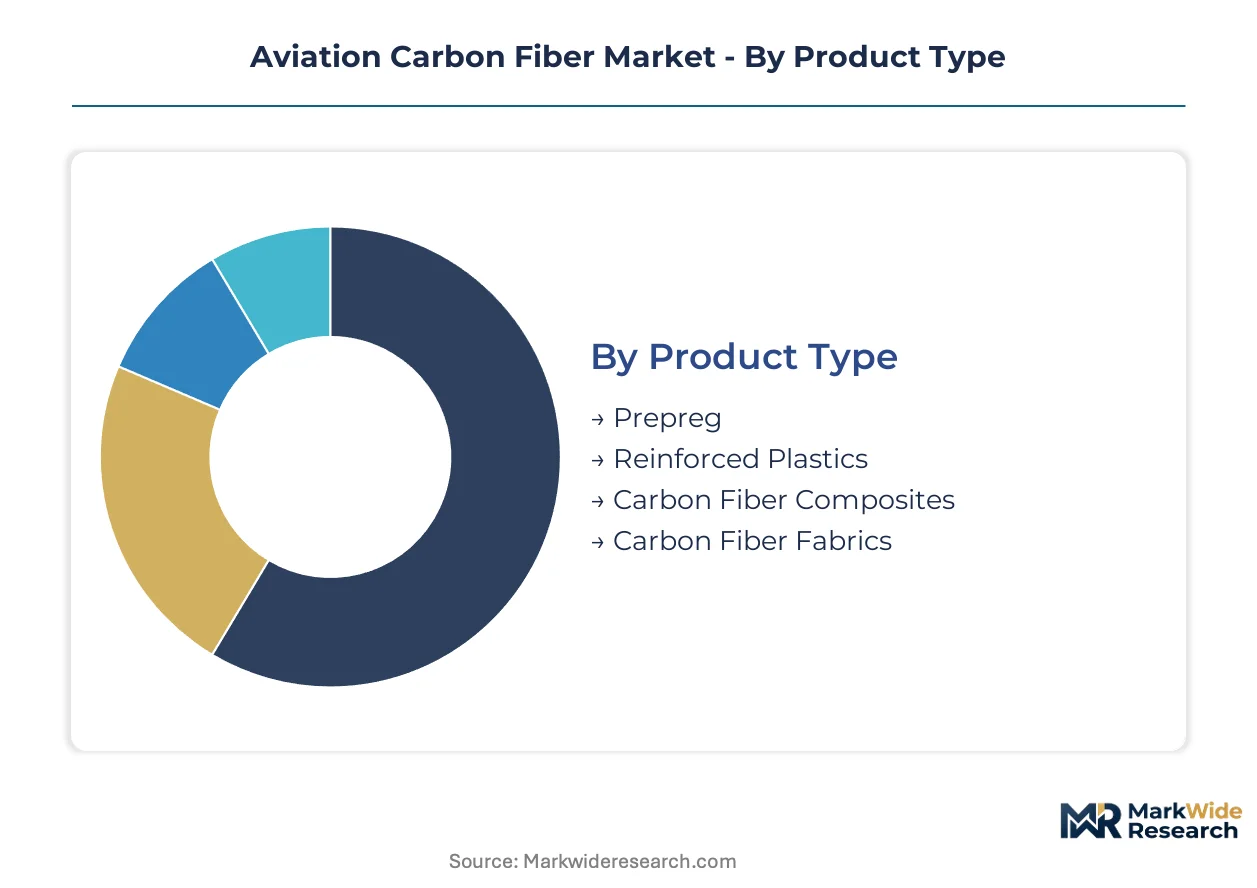
Aviation carbon fiber procurement splits across material formats, structural applications, and airframe integration points. Each dimension carries distinct qualification burdens and margin profiles that shape supplier positioning.
Product Type:
Material format selection hinges on autoclave access versus out-of-autoclave processing economics.
- Prepreg:Resin-impregnated unidirectional tapes and woven fabrics dominate primary wing and fuselage structures. Boeing 787 and Airbus A350 programs anchor demand in the United States and France, where autoclave-cured specific stiffness requirements exceed metallic alternatives. Thermoplastic prepreg qualification timelines are compressing under FAA and EASA dual-regulatory pressure.
- Carbon Fiber Composites:Consolidated laminate structures integrate fiber and matrix into net-shape geometries for load-bearing applications. Airbus procurement teams specify these for next-generation narrowbody wing ribs where reparability and weldability outweigh thermoset familiarity. Airline sustainability frameworks now mandate precursor energy intensity disclosures as standard RFP criteria.
- Reinforced Plastics:Short-fiber or chopped configurations serve non-structural brackets and interior mounting points.
- Carbon Fiber Fabrics:Woven textile formats enable draping over complex mold geometries for secondary structures and repair patches.
Prepreg leads volumes today; carbon fiber composites are gaining share fastest.
Application:
Structural criticality determines fiber grade, certification pathway, and supplier tier access.
- Aerospace Structures:Primary wing skins, spars, and fuselage barrels require T800H and IM7-grade fibers with tensile strength exceeding 5,600 MPa. Boeing and Airbus long-term airframe contracts concentrate demand in Seattle and Toulouse manufacturing nodes. EASA material qualification protocols extend certification timelines for thermoplastic matrix systems in these applications.
- Engine Components:Fan blades, cowls, and thrust reverser cascades demand oxidation-resistant carbon-carbon and ceramic matrix hybrids. GE Aviation and Rolls-Royce procurement specifications drive resin transfer molding adoption for complex net-shape geometries. REACH chemical compliance deadlines force reformulation of legacy hardeners in European-qualified product lines.
- Aircraft Interiors:Seat frames, galley structures, and overhead bin components utilize intermediate-modulus fibers.
- Landing Gear:Strut and brace applications remain metallic-dominated with selective composite substitution.
Aerospace structures dominate revenue capture; engine components are climbing the fastest.
End User:
Fleet renewal cycles and emissions compliance timelines differentiate procurement urgency across aviation sectors.
- Commercial Aviation:Narrowbody fleet expansion at Southwest, Ryanair, and IndiGo drives standardized composite wing contracts. EU Green Deal binding emissions targets force lightweight material prioritization in Boeing 737 MAX and Airbus A320neo programs. Airline technical procurement teams now reward fiber manufacturers with verified low-carbon acrylonitrile supply chains.
- Military Aviation:F-35 and Eurofighter programs specify classified fiber grades with stealth-compatible surface treatments. Pentagon and NATO procurement offices prioritize domestic precursor supply assurance over cost minimization. Japanese PAN-based precursor dominance creates geographic concentration risk for Western defense contractors.
- Business Aviation:Gulfstream and Dassault Falcon programs utilize intermediate-modulus prepregs for cabin pressure vessels.
- General Aviation:Cirrus and Tecnam light aircraft incorporate wet layup fabrics for cost-sensitive airframes.
Commercial aviation anchors demand today; military aviation is expanding most quickly.
Manufacturing Process:
Capital equipment intensity and technician availability constrain process selection at the facility level.
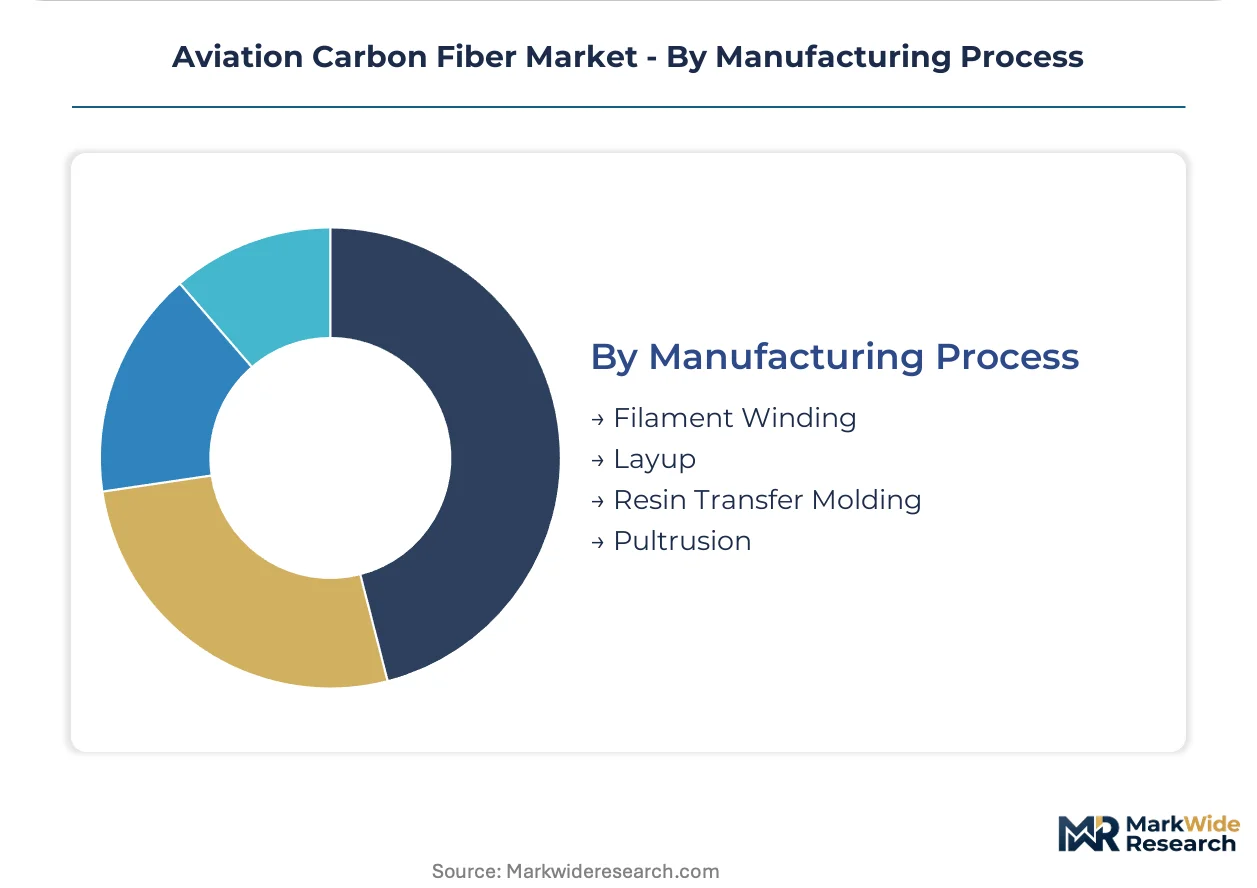
- Layup:Automated fiber placement and hand layup of prepreg plies remain the baseline for primary structures. Boeing Charleston and Airbus Hamburg facilities maintain the largest installed bases of multi-tape placement heads. Autoclave operator scarcity constrains throughput expansion at composite fabrication facilities.
- Resin Transfer Molding:Closed-mold infusion enables complex net-shape fabrication without autoclave curing. Safran and Leonardo engine component suppliers bypass prepreg incumbent lock-in through this pathway. FAA-EASA harmonization gaps in damage tolerance certification force redundant testing protocols.
- Filament Winding:Continuous fiber deposition suits pressure vessels and cylindrical structures.
- Pultrusion:Constant cross-section profiles serve stringers and stiffener applications.
Layup dominates installed capacity today; resin transfer molding is gaining adoption fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping carbon fiber production geography as manufacturers seek jurisdictions with streamlined aerospace qualification pathways and favorable energy costs for precursor synthesis.
United States
Boeing's supplier base anchors North American demand through vertically coordinated precursor-to-prepreg operations. FAA reauthorization mandates compress thermoplastic qualification timelines for 737 MAX and 777X programs. Seattle and Charleston manufacturing clusters concentrate autoclave-cured wing fabrication capacity.
Japan
Toray Industries and consolidated suppliers control critical PAN-based precursor supply nodes serving global airframers. METI industrial policy supports aerospace-grade fiber R&D through targeted subsidies. Nagoya and Tokyo Bay industrial corridors host the densest concentration of high-modulus precursor production worldwide.
Germany
Airbus Hamburg and Premium Aerotec operations drive thermoplastic matrix adoption for A320neo wing structures. REACH chemical compliance deadlines force reformulation of legacy hardeners and sizing agents. Bavarian and Hamburg aerospace clusters face the steepest EASA requalification burdens for epoxy system replacements.
France
Safran and Airbus Toulouse procurement teams specify resin transfer molding for engine component geometries. EU Green Deal emissions frameworks mandate documented lifecycle carbon reductions in material selection. Occitanie and Île-de-France regions concentrate composite fabrication for narrowbody and widebody programs.
China
COMAC C919 fleet expansion creates domestic demand for intermediate-modulus prepregs previously import-dependent. MIIT dual carbon goals pressure state-owned fiber producers to disclose energy intensity metrics. Yangtze River Delta manufacturing nodes are scaling carbon fiber capacity for commercial aviation qualification.
Aviation Carbon Fiber Market Vendor Landscape
Capacity expansion dominates the current landscape as incumbent suppliers race to secure qualified thermoplastic prepreg positions before FAA and EASA dual-certification deadlines converge. The vendor base concentrates around three strategic archetypes: integrated precursor-to-prepreg operators, specialty resin formulators, and automotive-to-aerospace transfer specialists. M&A activity and strategic partnerships represent the dominant competitive moves, with fiber producers seeking captive resin technology and airframers locking in multi-year supply assurance.
Within the integrated precursor-to-prepreg tier, Toray Industries, Inc. and Hexcel Corporation exemplify vertical coordination strategies that reduce qualification friction for new airframe contracts. SGL Carbon SE occupies a position bridging automotive scale economies with aerospace certification expertise, representing the transfer-specialist archetype in European supply chains.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| Hexcel Corporation |
| SGL Carbon SE |
| Solvay S.A. |
| TEIJIN LIMITED |
| Mitsubishi Chemical Group |
| DuPont de Nemours, Inc. |
| Bally Ribbon Mills |
| BGF Industries Inc. |
| Others |
Supply Flow & Price Mechanics
Boeing and Airbus procurement teams command contract-based long-term offtake structures that compress margin variability for qualified prepreg suppliers. FAA and EASA dual-certification timelines concentrate buyer power among airframers with established thermoplastic qualification pathways, forcing fiber manufacturers to absorb requalification costs upfront.
Pricing Analysis
Distributor margins on aerospace-grade prepregs compress as direct-to-OEM contracts expand under multi-year airframe programs. Three-tier pricing structure across T800H-grade primary structures, intermediate-modulus engine components, and standard-modulus interior applications reflects certification burden and autoclave processing intensity. Price differentiation hinges on EASA qualification status and precursor energy intensity disclosure compliance. Cost compression in thermoplastic resin systems is intensifying because REACH reformulation deadlines force parallel validation investments. Tier-two resin transfer molding suppliers exhibit highest price sensitivity; Boeing and Airbus direct procurement teams show lowest.
Supply Chain Analysis
Scrap fiber recovery and remanufacturing flows remain underdeveloped, constraining circularity claims in airline sustainability frameworks. Precursor production concentrates in Japan, the United States, and Germany, with Toray Industries and Hexcel Corporation anchoring PAN-based supply nodes. Acrylonitrile feedstock, epoxy hardener chemistries, and thermoplastic resin systems constitute critical input dependencies. Single-source vulnerability around Japanese PAN precursor creates geographic concentration risk for Western airframers. Distribution runs through qualified tier-one aerostructures suppliers with captive autoclave capacity at Boeing Charleston and Airbus Hamburg facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal emissions deadlines and FAA reauthorization mandates jointly accelerate thermoplastic procurement timelines beyond organic fleet expansion rates.
For Market Incumbents: Acquire captive thermoplastic resin formulation capabilities to secure dual-certification positions before EASA protocol harmonization closes. Defensive consolidation around automated fiber placement equipment in South Carolina and Lower Saxony addresses autoclave operator scarcity threatening throughput expansion. Backward integration into low-carbon acrylonitrile supply chains counters emerging sustainability-linked sourcing criteria from Scandinavian carriers. For New Entrants and Emerging Players: Launch via resin transfer molding partnerships with Safran and GE Aviation engine component programs to bypass prepreg incumbent lock-in. White space concentrates in complex net-shape thrust reverser cascades and fan blade geometries where thermoset qualification burdens exclude established suppliers. Target Chinese COMAC C919 qualification pathways as the most penetrable geography given domestic content mandates and MIIT dual carbon disclosure requirements. For Investors and Strategic Acquirers: Defense contractors and national aerospace champions are the most active acquirer in this space, prioritizing precursor supply assurance over margin maximization. Five-to-ten-year viability hinges on thermoplastic recycling pathway maturation enabling documented lifecycle carbon reductions. Monitor EASA-FAA damage tolerance harmonization progress as the critical inflection signal for redundant testing cost elimination.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Prepreg Qualification Acceleration | Compresses EASA material protocol timelines ahead of EU Green Deal deadlines for Airbus narrowbody programs. |
| Backward Integration into Precursor Production | Secures PAN-based supply nodes against Japanese geographic concentration risk for Boeing supplier base. |
| Resin Transfer Molding Capacity Expansion | Enables Safran and Leonardo bypass of autoclave-constrained prepreg incumbents in engine component supply. |
| REACH-Compliant Formulation Investment | Replaces legacy hardener chemistries for German and French airframe subcontractor market access. |
| Closed-Loop Fiber Recovery Partnership | Aligns with Scandinavian carrier sustainability-linked sourcing contracts mandating energy intensity transparency. |
Methodological Framework
Multiple input streams — composite fabrication facility audits, airframer procurement specification reviews, and precursor producer energy disclosure analysis — were reconciled to construct segment-level demand estimates. Primary interviews with Boeing and Airbus material qualification engineers, Hexcel and Toray supply chain directors, EASA certification officers, and airline technical procurement managers were cross-validated against secondary sources including FAA airworthiness directives, ECHA REACH substance registrations, EU Green Deal implementation reports, and customs trade data for acrylonitrile and carbon fiber filament flows. Bottom-up build from individual program content assumptions and top-down reconciliation against fleet expansion projections ensured methodological robustness.
Data-stream reconciliation across the projection horizon applied a structural model linking narrowbody delivery schedules, thermoplastic adoption curves, and regulatory milestone timing. Segmentation dimensions included material format tier, structural application criticality, airframe integration point, and regional manufacturing cluster. CAGRs were derived from compound growth path optimization against qualification timeline constraints. Industry-specific inputs encompassed autoclave capacity utilization rates at Charleston and Hamburg facilities, and precursor energy intensity disclosure penetration rates in airline RFP criteria.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FAA-EASA harmonization delays or acrylonitrile feedstock price volatility. Practitioners should monitor thermoplastic recycling technology maturation and EASA damage tolerance protocol revisions for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Space Electronics Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market
Aerospace and Aircraft Materials
Europe Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Sealants Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Ablative Coatings Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Europe Advanced Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace 3D Printing Consumables Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Advanced Materials for Flying Cars Market
Aerospace and Aircraft Materials
Aramid Honeycomb Market