
 Civil Helicopter Market | 2026-2036
Civil Helicopter Market Size, Share, and Industry Trends Forecast 2026-2036
Civil Helicopter Market Analysis
The EU Green Deal's aviation decarbonization targets are consolidating pressure on OEMs to develop hybrid-electric propulsion architectures and sustainable aviation fuel-compatible turboshaft designs. Airbus Helicopters leverages its Clean Sky 2 partnerships to advance high-compression engine technology, while Bell Textron Inc. sustains competitive pressure through its integrated military-to-civil technology transfer pipeline. Leonardo S.p.A. differentiates via specialized tiltrotor competence and Mediterranean basin aftermarket dominance.
A civil helicopter is a rotary-wing aircraft certified for non-military operations, typically featuring one or two main rotors with diameters ranging from 8 meters on light models to over 20 meters on heavy-lift configurations, powered by turboshaft engines generating 300 to 3,000 shaft horsepower for vertical takeoff, hover, and low-speed maneuverability in confined zones. Light helicopters occupy the highest volume tier due to flight training and private ownership economics, while medium helicopters capture disproportionate value in offshore oil transport and emergency medical services where payload-range optimization commands premium positioning. Turboshaft engine technology leads R&D allocation as fuel efficiency and noise reduction become decisive procurement criteria.
FAA Part 27 and Part 29 airworthiness standards govern US civil rotorcraft certification, with EASA CS-27 and CS-29 providing parallel European frameworks that increasingly incorporate noise and emissions boundaries. The FAA's recent Urban Air Mobility integration initiatives are reshaping low-altitude corridor access rules, directly influencing next-generation helicopter and eVTOL hybrid platform development. Stakeholders must monitor regulatory divergence between FAA performance-based standards and EASA's prescriptive certification pathways, as this fragmentation will determine aftermarket parts interoperability and fleet exportability across Atlantic markets.
Market Dynamics
The civil helicopter market faces intensifying pressure from FAA Part 135 operational mandates and EASA CS-29 certification recalibration, forcing fleet operators to accelerate modernization timelines while OEMs absorb elevated R&D burdens for hybrid-electric architectures.
Growth Catalysts
- Emergency Medical Services Expansion:North American and European healthcare systems are enlarging rotorcraft fleets to reach trauma centers within the golden hour, with hospital networks prioritizing twin-engine IFR-capable platforms for all-weather patient transport.
- CS-29 Certification Standards:EASA's tightened airworthiness benchmarks are compressing accident rates and extending airframe lifecycles, creating replacement demand among legacy operators seeking compliance-aligned new-build deliveries.
- Urban Air Mobility Infrastructure:United States municipal investments in vertiport networks and low-altitude corridor management are sustaining medium-twin procurement for inter-city shuttle services and executive transport.
Market Restraints
- Turboshaft Engine Supply Concentration:Critical powerplant manufacturing concentrates among three Western suppliers, exposing operators to lead-time volatility and aftermarket parts pricing power asymmetries.
- Fuel Cost Volatility:Jet-A price fluctuations directly compress operating margins for high-utilization offshore oil transport fleets, eroding the economic case for aging single-engine platforms.
- eVTOL Substitution Threat:Electric vertical takeoff aircraft developers are targeting sub-50 nautical mile routes currently served by light helicopters, pressuring entry-level rotorcraft residual values.
Strategic Opportunities
- EU Green Deal Aviation Decarbonization:Sustainable aviation fuel mandates and hybrid-electric development incentives are opening procurement pathways for next-generation powertrain architectures that OEMs can position as compliance-ready solutions.
- Offshore Wind Energy Logistics:North Sea and Baltic Sea wind farm construction is generating demand for heavy-lift helicopters capable of precision component placement beyond crane barge reach.
- Digital Predictive Maintenance:Health and usage monitoring system integration with cloud analytics platforms is converging with operator fleet management software, enabling subscription-based aftermarket revenue streams.
Industry Challenges
- Certification Timeline Compression:FAA and EASA parallel validation processes for modified airframes are extending type certificate amendment cycles, delaying revenue recognition for derivative models.
- Pilot Training Pipeline Constraints:Military-to-civil transition pathways are narrowing as armed forces retain experienced aviators, forcing civilian flight schools to absorb ab initio training burdens without simulator infrastructure scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Civil Helicopter Market |
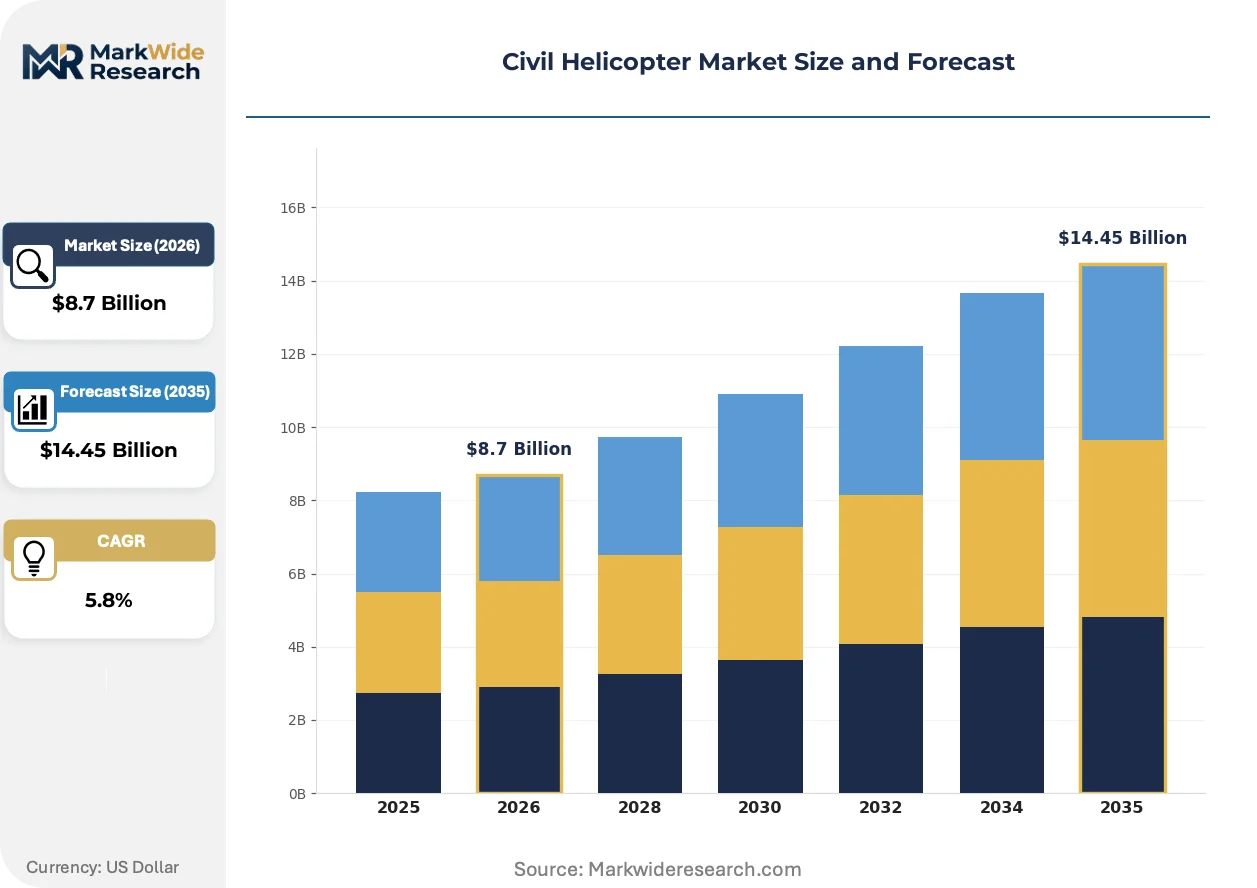
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Helicopters, Medium Helicopters, Heavy Helicopters, Super Heavy Helicopters End User: Corporate, Emergency Medical Services, Law Enforcement, Tourism Usage Type: Private, Commercial, Military, Oil & Gas Technology: Fly-by-Wire, Avionics, Turboshaft Engines, Aerodynamic Structures |
| Companies Covered | Lockheed Martin (Sikorsky), Robinson Helicopter Company, Airbus Helicopters, Kawasaki Heavy Industries Ltd., Kaman Corporation, Bell Textron Inc., The Boeing Company, Hindustan Aeronautics Limited, Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Civil Helicopter Market Emerging Trajectories
Propulsion architecture evolution and regulatory fragmentation are simultaneously compressing development cycles and expanding performance envelopes across the civil rotorcraft sector.
Hybrid-electric powertrains are converging with traditional turboshaft designs to enable segmented flight profiles where batteries handle hover phases and combustion engines sustain cruise. Offshore energy operators in the North Sea are piloting these configurations to reduce fuel burn during repetitive platform approach patterns. This convergence is compressing the performance gap between light singles and medium twins while forcing engine manufacturers to retool thermal management competencies.
EU Green Deal aviation decarbonization targets are mandating sustainable aviation fuel blending quotas and noise contour restrictions at consolidated metropolitan heliports. European EMS operators are responding by specifying H215 and AW139 variants with optimized main rotor tips and exhaust suppressors. Mediterranean basin authorities are accelerating these procurement timelines ahead of 2030 interim benchmarks.
Buyer consolidation among super-mid offshore fleet operators is compressing procurement decision cycles and unbundling aftermarket service contracts from airframe purchases. Large integrated energy service companies are negotiating direct engine maintenance agreements with powerplant OEMs, bypassing traditional helicopter distributor networks. This pattern is most visible in the US Gulf of Mexico and Brazilian pre-salt basins where three operators control sixty percent of heavy-twin utilization hours.
Civil Helicopter Market Segmentation
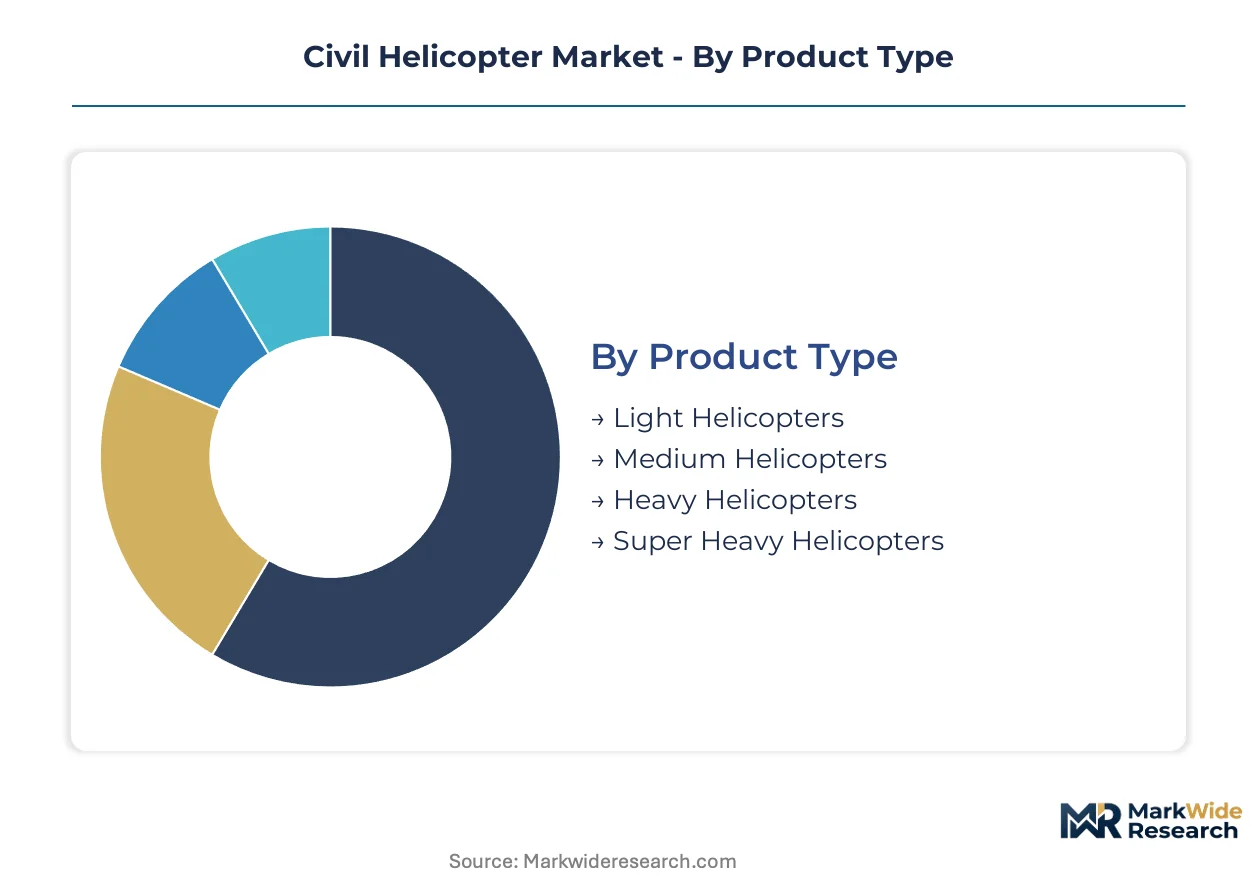
Segmentation reveals how procurement power concentrates across weight classes and mission profiles. OEMs configure production lines around these divisions, with certification costs and powerplant sourcing determining viable market entry points.
Product Type:
Supply concentration tilts toward platforms where engine-airframe integration complexity creates durable competitive moats.
- Light Helicopters:Single-engine designs with 8-12 meter rotor diameters dominate flight training and private ownership economics. Demand clusters in the United States flight school networks and Brazilian agribusiness patrols, constrained by eVTOL substitution threats on sub-50 nautical mile routes.
- Medium Helicopters:Twin-turboshaft configurations generating 1,000-2,000 shaft horsepower capture premium positioning in offshore oil transport and emergency medical services where payload-range optimization commands fleet investment. North Sea energy logistics and US Gulf of Mexico operations sustain procurement volumes despite fuel cost volatility.
- Heavy Helicopters:External load specialists with 16-20 meter rotors serve construction and firefighting missions requiring 4,000+ kilogram sling capacity.
- Super Heavy Helicopters:Niche platforms exceeding 20 meter rotor spans address military-civil dual-use heavy lift and specialized infrastructure placement.
Today's leader: Medium Helicopters. Tomorrow's challenger: Light Helicopters.
End User:
Application-specific certification requirements fragment procurement specifications across mission-critical performance envelopes.
- Emergency Medical Services:Twin-engine IFR-capable platforms with medical interior certifications dominate hospital network fleet expansion. North American healthcare systems prioritize all-weather patient transport within the golden hour trauma window, driving specifications for enhanced crashworthiness and vibration isolation.
- Corporate:Executive transport configurations emphasize cabin quieting and avionics integration for point-to-point urban mobility. US municipal vertiport investments sustain medium-twin procurement for inter-city shuttle services.
- Law Enforcement:Surveillance-equipped variants with thermal imaging and searchlight integration serve border patrol and urban policing missions.
- Tourism:Sightseeing operators favor high-visibility cabin designs with reduced noise footprints for scenic overflight routes.
Emergency Medical Services anchors current procurement volumes; Corporate transport exhibits the steepest expansion trajectory as urban air mobility infrastructure matures.
Usage Type:
Operational intensity patterns determine aftermarket revenue attachment rates and fleet replacement cycles.
- Commercial:High-utilization charter and utility operators drive health and usage monitoring system adoption for predictive maintenance. Integrated energy service companies in the US Gulf of Mexico and Brazilian pre-salt basins negotiate direct engine maintenance agreements, bypassing traditional distributor networks.
- Oil & Gas:Offshore platform transport fleets face margin compression from Jet-A price fluctuations, eroding economic viability of aging single-engine platforms and accelerating twin-turbine modernization timelines.
- Private:Owner-flown aircraft generate lower annual flight hours but sustain avionics upgrade demand for airspace compliance.
- Military:Civil-certified derivatives of defense platforms leverage technology transfer pipelines for dual-use procurement.
Commercial usage commands the installed base; Oil & Gas is gaining share fastest as offshore wind energy logistics creates new heavy-lift demand.
Technology:
R&D allocation concentrates where regulatory pressure intersects with operational cost reduction potential.
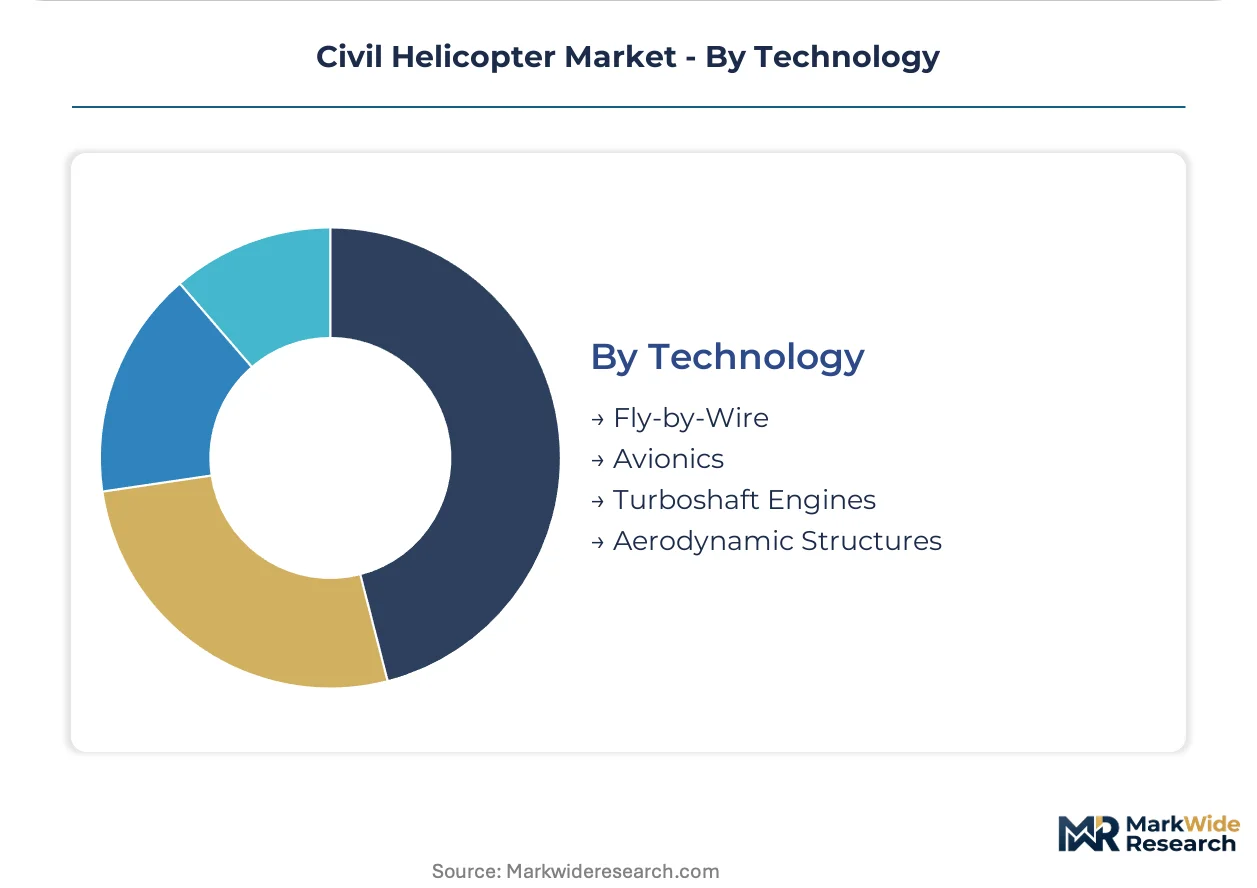
- Turboshaft Engines:Powerplants generating 300-3,000 shaft horsepower absorb the dominant share of manufacturer engineering resources. EU Green Deal aviation decarbonization targets are mandating sustainable aviation fuel compatibility and hybrid-electric architecture development, with Clean Sky 2 partnerships advancing high-compression thermal efficiency.
- Fly-by-Wire:Digital flight control systems reduce pilot workload and enable precision maneuvering in degraded visual environments. EMS operators in Mediterranean basin markets specify these configurations for all-weather patient transport safety margins.
- Avionics:Integrated glass cockpit suites with synthetic vision and terrain awareness systems address FAA Part 135 operational mandates for reduced crew training burdens.
- Aerodynamic Structures:Optimized main rotor tip designs and exhaust suppressors respond to EASA noise contour restrictions at consolidated metropolitan heliports.
Turboshaft Engines retains technology investment leadership; Fly-by-Wire represents the fastest-climbing capability tier as autonomy pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The civil helicopter industry traces its commercial lineage to post-war United States manufacturing, where Vertol and Bell established rotary-wing production methodologies subsequently adopted across European and Asian defense industrial bases.
United States
Urban air mobility infrastructure investments and offshore energy transport needs sustain fleet modernization across Gulf Coast operations. FAA Part 135 operational requirements and Part 29 airworthiness standards govern certification pathways for twin-turbine platforms. Houston and New Orleans anchor heavy-twin utilization for platform shuttle services, while Los Angeles and New York metropolitan vertiport networks drive medium-twin procurement for executive transport.
France
EU Green Deal aviation decarbonization targets are consolidating pressure on OEMs to develop hybrid-electric propulsion architectures. EASA CS-29 certification standards provide parallel European frameworks that increasingly incorporate noise and emissions boundaries. Marseille and the Provence-Alpes-Côte d'Azur region concentrate Mediterranean basin aftermarket dominance through specialized maintenance facilities serving North African operators.
Italy
Tiltrotor competence and specialized aerostructures differentiate domestic OEM positioning within NATO procurement pipelines. EASA noise contour restrictions at consolidated metropolitan heliports accelerate EMS fleet specifications with optimized main rotor tips. The Lazio region around Rome hosts government and corporate transport demand, while Tuscany's aerospace cluster supports composite component manufacturing for civil derivatives.
Japan
Flight training and private ownership economics drive light helicopter demand across archipelago geography unsuited for fixed-wing infrastructure. METI industrial policy supports dual-use technology transfer from defense programs into civil-certified platforms. The Kanto region surrounding Tokyo concentrates corporate and EMS operator bases, while Kyushu maintains manufacturing competencies for powerplant component sourcing.
Brazil
Agribusiness patrols and pre-salt basin offshore logistics generate sustained procurement for single and twin-turbine configurations. ANVISA regulatory alignment with FAA standards facilitates fleet exportability across Latin American markets. São Paulo state anchors executive transport demand, while Rio de Janeiro's offshore energy corridor sustains heavy-twin utilization for platform crew change operations.
Civil Helicopter Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a consolidated OEM tier where airframe-engine integration complexity creates durable competitive moats. Three Western suppliers dominate critical powerplant manufacturing, exposing operators to lead-time volatility while compressing aftermarket parts pricing power. Strategic archetypes separate integrated military-civil technology transfer pipelines, specialized tiltrotor competence holders, and high-volume light single producers. Dominant competitive moves include hybrid-electric architecture partnerships and direct engine maintenance agreement bypassing of traditional distributor networks.
Within the integrated defense-aerospace tier, Lockheed Martin (Sikorsky) and The Boeing Company represent capital-intensive platforms leveraging military program scale. Airbus Helicopters and Leonardo S.p.A. occupy positions within the European consolidated OEM structure, with the latter exemplifying specialized competence in tiltrotor configurations. Bell Textron Inc. anchors the Textron conglomerate's rotary-wing positioning across civil and military segments. Robinson Helicopter Company exemplifies the high-volume light single archetype focused on flight training and private ownership economics.
| Leading Market Players |
|---|
| Lockheed Martin (Sikorsky) |
| Robinson Helicopter Company |
| Airbus Helicopters |
| Kawasaki Heavy Industries Ltd. |
| Kaman Corporation |
| Bell Textron Inc. |
| The Boeing Company |
| Hindustan Aeronautics Limited |
| Leonardo S.p.A. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists with multi-decade airframe production legacies anchor supply discipline across the civil helicopter sector, translating captive manufacturing depth into pricing power that resists commoditization even as fuel cost volatility compresses operator margins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement negotiations, with premium tiers capturing IFR-certified twin-turbine platforms and economy tiers serving ab initio training schools. Price differentiation rests on certification grade—FAA Part 29 versus Part 27 compliance—and aftermarket service bundling intensity. Cost compression in the light single segment is intensifying because eVTOL developers are pressuring residual values on sub-50 nautical mile routes. Flight training operators exhibit highest price sensitivity, while offshore energy service companies demonstrate lowest sensitivity due to payload-range optimization requirements.
Supply Chain Analysis
Single-source vulnerability sits with turboshaft engine manufacturing concentrated among three Western suppliers in the United States, France, and the United Kingdom. Critical inputs draw from precision-forged turbine discs, nickel-based superalloy castings, and composite rotor blade prepregs sourced from Japan and Germany. Tariff exposure on aerospace-grade aluminum and titanium mill products creates margin volatility for airframe assemblers. Distribution runs through OEM-authorized service centers and independent MRO facilities that negotiate direct powerplant maintenance agreements with engine manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The civil helicopter market functions as a stable compounder, with emergency medical services fleet expansion providing durable demand visibility across North American and European healthcare procurement cycles.
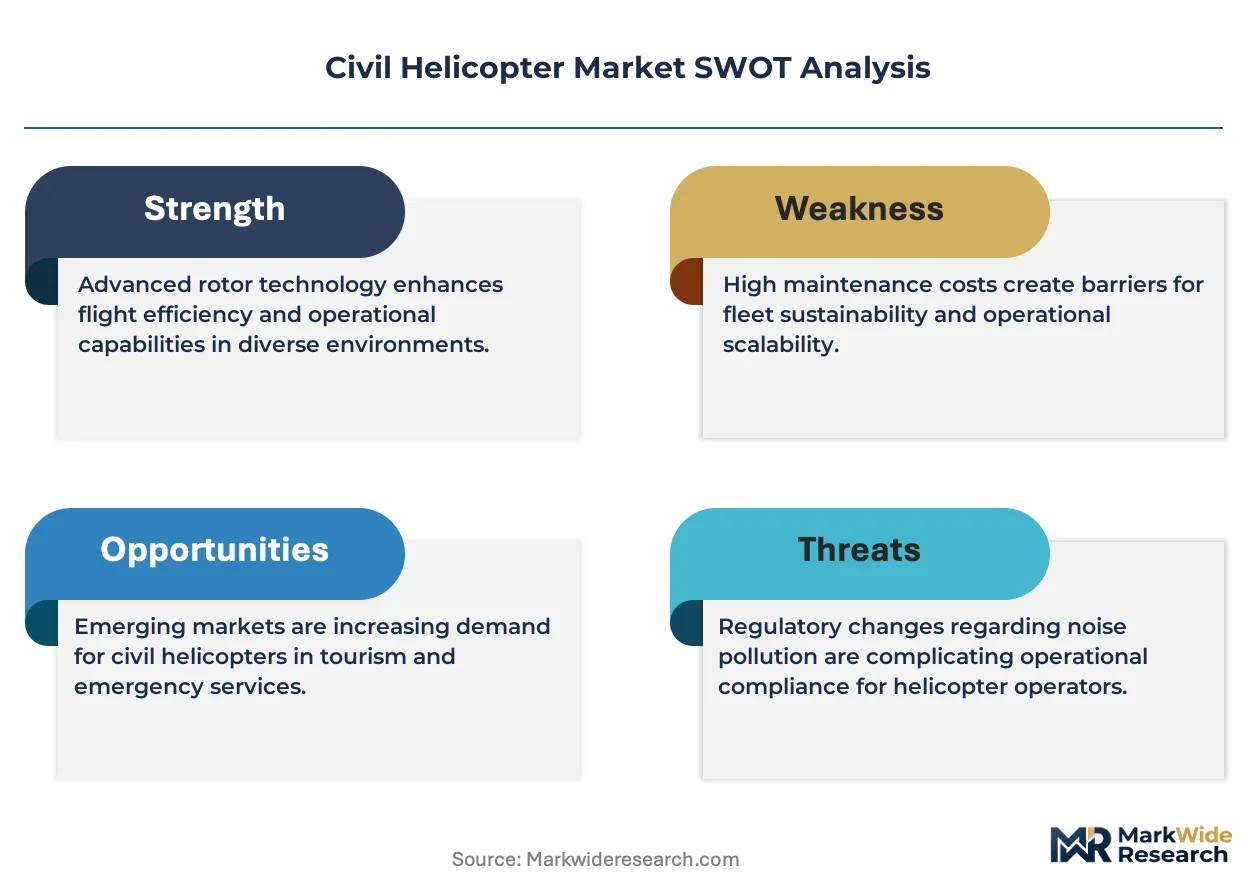
For Market Incumbents: Extend hybrid-electric architecture partnerships to secure EU Green Deal compliance positioning ahead of sustainable aviation fuel mandates. Deepen backward integration into composite aerostructure manufacturing to capture margin currently flowing to Italian and French tier-one suppliers. Lockheed Martin and Airbus Helicopters must accelerate CS-29 certification alignment to defend against Leonardo's tiltrotor technology transfer pipeline. For New Entrants and Emerging Players: Offshore wind energy logistics operators in the North Sea and Baltic Sea represent an underserved buyer archetype demanding heavy-lift platforms with precision component placement capability beyond crane barge reach. Municipal vertiport authorities in secondary US metropolitan areas offer white-space access with lower competitive density than Los Angeles or New York corridors. Pursue lease-to-own financing structures that bypass traditional helicopter distributor networks. For Investors and Strategic Acquirers: Valuations sit cheapest among regional MRO specialists with established EASA Part 145 certifications and Mediterranean basin aftermarket footprints. Long-term viability hinges on recurring revenue attachment rates from health and usage monitoring system subscriptions. Watch for FAA Urban Air Mobility corridor rulemaking as the inflection signal that validates next-generation platform development bets.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Partnership | Airbus leverages Clean Sky 2 funding to advance high-compression engine technology for EU decarbonization compliance. |
| Direct Engine Maintenance Agreement | Offshore operators in the US Gulf of Mexico bypass traditional distributors to negotiate powerplant OEM contracts. |
| Vertiport Infrastructure Investment | US municipal authorities anchor medium-twin procurement for inter-city executive shuttle services. |
| CS-29 Certification Alignment | EASA's tightened airworthiness benchmarks compress accident rates and extend replacement demand cycles. |
| Digital Predictive Maintenance Platform | Cloud analytics integration with health and usage monitoring systems enables subscription aftermarket revenue streams. |
Methodological Framework
Direct dialogue with fleet operations directors, MRO facility managers, turboshaft engine procurement leads, and EASA certification engineers grounded the qualitative foundation. Secondary validation drew from FAA type certificate databases, EASA CS-29 amendment records, offshore energy operator fleet disclosures, and vertiport development authority filings. Bottom-up airframe delivery tallies and top-down OEM revenue segmentation were triangulated to reconcile volume estimates.
Unit shipment and value projections across the modeling period reflect discrete event simulation of fleet replacement cycles, segmented by weight class, mission profile, and regulatory compliance tier. CAGRs were derived from logistic diffusion curves fitted to historical procurement patterns and policy mandate timelines. Forecast inputs incorporated Jet-A price volatility scenarios and pilot training pipeline capacity constraints specific to rotary-wing certification pathways.
Underlying measurement precision varies by segment; emergency medical services and offshore oil transport carry tighter precision than tourism and private ownership categories due to consolidated operator reporting. Forecasts reflect documented assumptions on regulatory harmonization and sustainable aviation fuel blending trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Oxygen System Market
Aircraft
Air Deflector Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
Fixed Wing Aircraft Rivets Market
Aircraft
Commercial Aircraft Fadec Market
Aircraft
Aerobatic Aircraft Market
Aircraft
Firefighting Aircraft Market
Aircraft
Search and Rescue Helicopter Market
Aircraft
Enhanced Flight Vision Systems ( EFVS) Market
Aircraft
Hybrid Aircraft Market
Aircraft
Global Business Jets Market
Aircraft
North America Commercial Aircraft Market
Aircraft
Middle East and Africa Aviation Market
Aircraft
North America Turboprop Aircraft Market
Aircraft
Airplane and Helicopter Hangar Doors Market
Aircraft
Aviation Market