
 Global Aircraft Transparencies Market | 2026-2036
Global Aircraft Transparencies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Transparencies Market Intelligence
EASA CS-25 Appendix H bird-strike qualification is bifurcating the supplier base between certified tier-one manufacturers and uncertified challengers. PPG Industries leverages its integrated acrylic-to-interlayer supply chain to sustain qualification across multiple OEM platforms. GKN Aerospace anchors European aftermarket demand through its proprietary transparency repair network. Saint-Gobain differentiates via laminated glass expertise for military fighter canopies where optical clarity and electromagnetic shielding converge.
Aircraft transparencies comprise optically engineered windows, windscreens, and canopies that maintain cabin pressurization, optical clarity, and impact resistance across flight envelopes; these assemblies typically incorporate stretched acrylic, interlayer films, and conductive coatings to manage structural loads, de-icing, and electromagnetic interference. The product type mix tilts toward cockpit windscreens where laminate complexity and recertification cycles protect margin pools, while cabin windows compete on weight reduction and replacement frequency. Military aviation applications command premium pricing through armor integration and stealth-compatible coatings, whereas commercial aviation segments scale through fleet renewal programs.
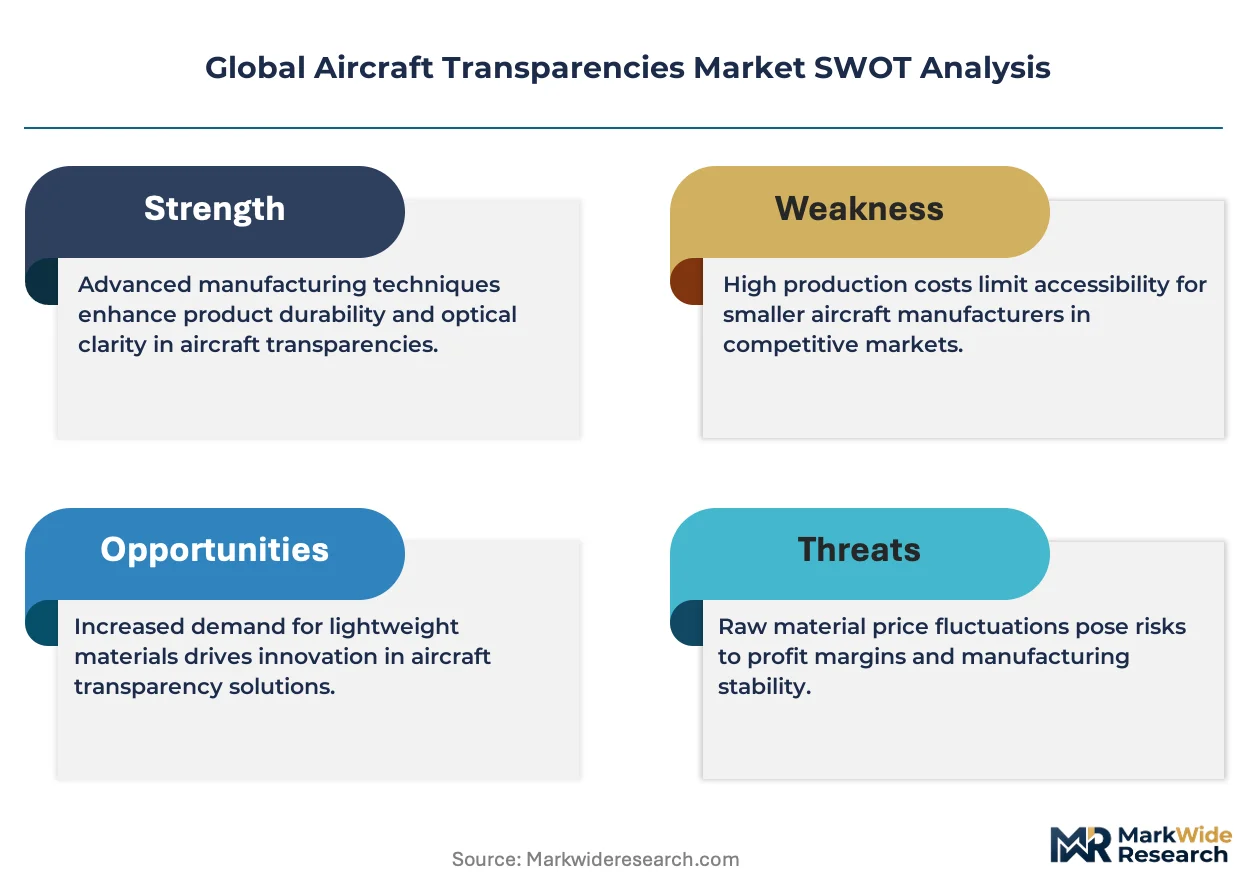
FAA Part 25.775, EASA CS-25, and ISO 7137 shape design standards, test protocols, and aftermarket documentation requirements that determine market access for new entrants. The FAA mandates specific impact-energy thresholds and post-impact pressure-retention durations that drive material selection toward multi-ply laminates. Stakeholders must monitor evolving sustainability mandates from the EU Green Deal and emerging MEE guidelines in China that will recast supply chain qualification criteria.
Market Dynamics
FAA bird-strike qualification thresholds and EASA CS-25 Appendix H certification requirements are compressing the qualified supplier base while airlines accelerate narrow-body fleet renewals. This regulatory tightening concentrates procurement among vertically integrated manufacturers with captive interlayer production and in-house testing capabilities.
Growth Catalysts
- FAA Part 25.775 Impact Standards:Mandated post-impact pressure-retention durations are forcing material upgrades toward multi-ply laminates, sustaining replacement cycles across aging commercial fleets.
- Airline Fleet Renewal Programs:Narrow-body and wide-body platform modernizations at Delta, United, and Lufthansa Group are expanding windscreen and cabin window procurement volumes.
- Stretched Acrylic Process Advances:Molecular orientation improvements are reducing weight penalties while maintaining optical clarity, accelerating adoption in single-aisle aircraft.
Market Restraints
- Petrochemical Input Volatility:Acrylic monomer and PVB interlayer prices fluctuate with propylene and butyraldehyde feedstock costs, compressing margin predictability for laminate fabricators.
- Qualified Supplier Concentration:North American and Western European certification holders control critical test data archives, limiting new entrant access to OEM qualification programs.
- Electromagnetic Interference Trade-offs:Conductive coating integration for de-icing and shielding degrades optical transmission, constraining design freedom for next-generation cockpit displays.
Strategic Opportunities
- India Defense Modernization:Indigenous fighter programs under the country's defense procurement framework are creating demand for armored canopies with integrated stealth-compatible coatings.
- EU Green Deal Sustainability Mandates:Emerging lifecycle assessment requirements for cabin interiors are opening qualification pathways for recycled-content interlayers and low-carbon acrylic production.
- Digital Twin Integration:Convergence of sensor-embedded transparencies with predictive maintenance platforms is enabling condition-based replacement contracts versus calendar-driven overhauls.
Industry Challenges
- Certification Timeline Compression:EASA and FAA harmonization delays for new laminate formulations extend qualification cycles to 18-24 months, freezing design iterations mid-program.
- Laminating Technician Scarcity:Specialized autoclave operation and optical inspection expertise is concentrating at legacy manufacturing clusters, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Transparencies Market |
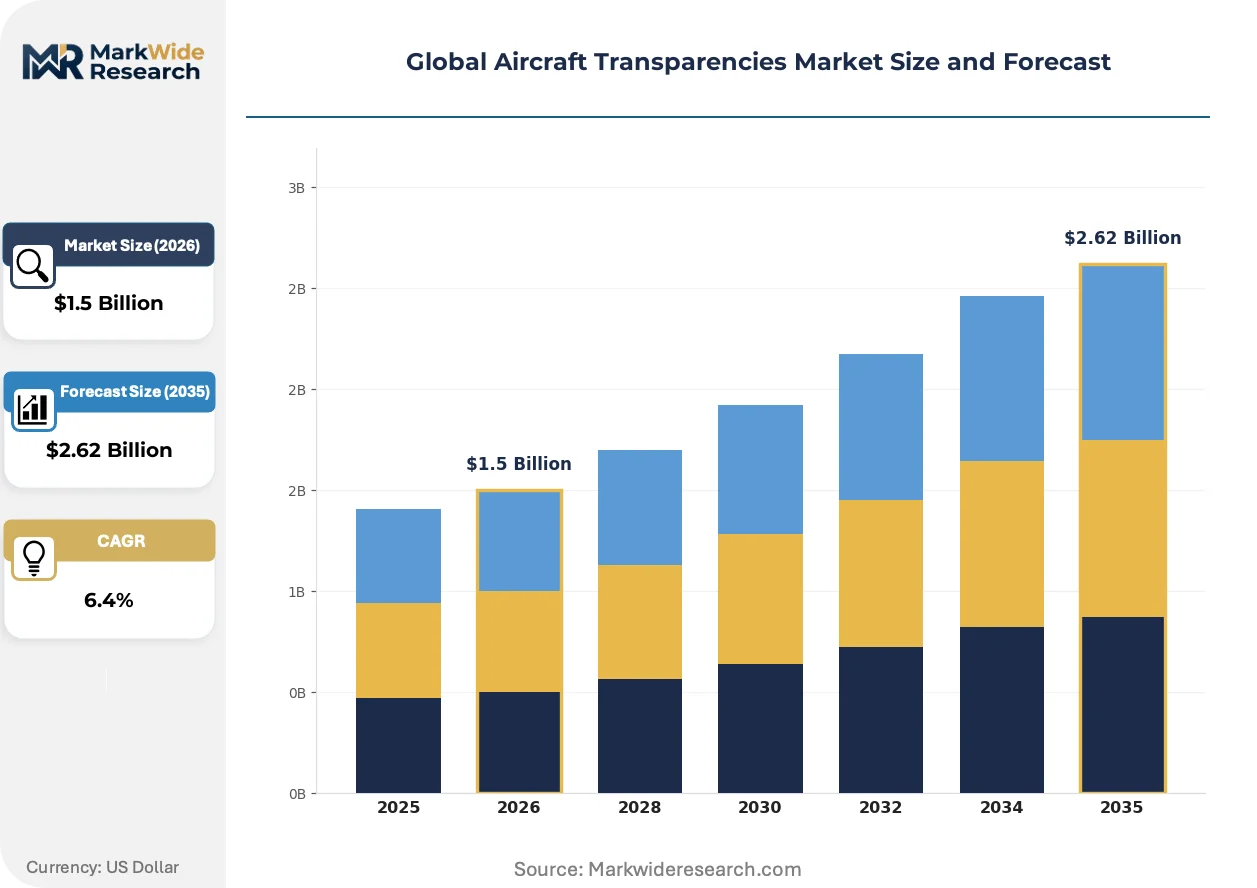
| Market Size in 2026 | $1.5 Billion |
| Market Size in 2035 | $2.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canopy, Cockpit Window, Windscreen, Cabin Window Material: Acrylic, Polycarbonate, Laminated Glass, Tempered Glass Application: Commercial Aviation, Military Aviation, Business Jets, Unmanned Aerial Vehicles End User: Aircraft Manufacturers, Maintenance Providers, Defense Contractors, Private Operators |
| Companies Covered | PPG Industries, Inc., GKN Aerospace, Saint-Gobain, The Nordam Group LLC, Lee Aerospace, Gentex Corporation, Control Logistics Inc., Llamas Plastics Inc., Texstars, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Transparencies Market Strategic Shifts & Innovations
Material substitution and regulatory stringency are converging to reshape transparency architecture, with sustainability mandates and digital integration emerging as parallel transformation vectors.
Thermoplastic polyurethane interlayers are decomposing traditional PVB dominance in cockpit windscreen applications. Airbus and Boeing procurement teams are qualifying these materials for improved impact energy absorption across next-generation single-aisle platforms. This substitution is compressing incumbent interlayer suppliers' margin pools while enabling thinner overall laminate stacks.
EASA CS-25 Appendix H bird-strike amendments are tightening post-impact visibility requirements for transport-category aircraft. Laminate fabricators must now demonstrate optical distortion limits under load conditions that exceed prior standards. European MRO networks are responding by consolidating repair station certifications and investing in automated optical inspection equipment.
Airline technical procurement teams are unbundling transparency replacement from heavy maintenance visits. LCCs and regional carriers in Southeast Asia are negotiating standalone window and windscreen contracts with component OEMs, bypassing traditional airframe integrator channels. This disintermediation is most visible in Indonesia and Vietnam, where rapid fleet expansion outpaces established MRO infrastructure.
Global Aircraft Transparencies Market Segmentation
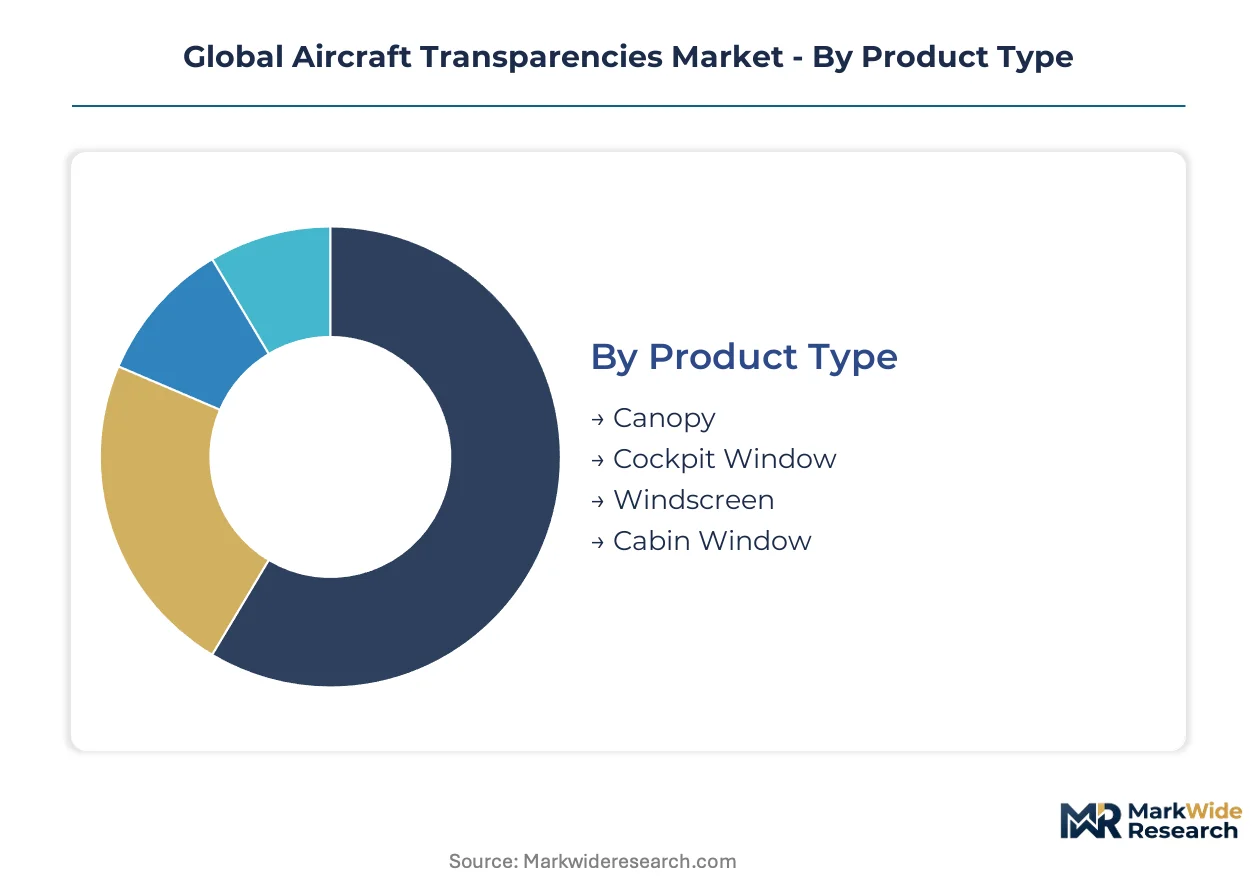
Segmentation in aircraft transparencies reveals how regulatory thresholds and performance specifications fragment procurement patterns across aerospace supply chains. Material certification tiers and application-specific load requirements create distinct margin pools that suppliers must navigate through targeted qualification investments.
Product Type:
FAA Part 25.775 and EASA CS-25 Appendix H impose divergent structural and optical requirements across transparency categories, forcing specialized laminate architectures for each position on the airframe.
- Windscreen:Multi-ply laminates incorporating stretched acrylic, interlayer films, and conductive coatings manage bird-strike energy absorption while preserving optical clarity under pressurized flight envelopes. Demand concentrates at Boeing and Airbus final assembly lines in the United States and France, where narrow-body fleet renewals are accelerating procurement volumes for next-generation single-aisle platforms.
- Cockpit Window:Side-panel assemblies prioritize weight reduction and electromagnetic interference shielding through optimized interlayer thickness and transparent conductive oxide deposition. Airlines in Germany and the United Kingdom are driving replacement cycles as aging wide-body fleets require recertification against amended EASA visibility standards.
- Cabin Window:Injection-molded acrylic or stretched sheet configurations balance passenger viewing angles with structural pressurization loads.
- Canopy:Fighter and trainer applications integrate armor layers and stealth-compatible coatings for military specifications.
Windscreen procurement handles the majority of throughput; cabin window replacement programs are expanding most quickly on share as airlines unbundle component contracts from heavy maintenance visits.
Material:
Cost tiers separate qualified aerospace grades from commercial alternatives, with certification archives and test data libraries creating defensive moats around incumbent supply positions.
- Acrylic:Stretched molecular orientation processes yield biaxial strength improvements and weight advantages for commercial aviation applications. PPG Industries and Saint-Gobain anchor supply through captive monomer-to-sheet production in the United States and France, leveraging decades of FAA and EASA qualification data to exclude unvalidated challengers.
- Laminated Glass:Soda-lime or borosilicate compositions with polyvinyl butyral or thermoplastic polyurethane interlayers dominate military fighter canopies where electromagnetic shielding and ballistic resistance converge. India's indigenous fighter programs under the defense procurement framework are expanding demand for armored transparency assemblies with integrated stealth coatings.
- Polycarbonate:High-impact resistance and formability suit specialized military and unmanned aerial vehicle applications with constrained optical transmission requirements.
- Tempered Glass:Thermal toughening processes create surface compression layers for legacy general aviation and certain commercial cabin applications.
Acrylic commands the dominant production position; thermoplastic polyurethane interlayers are climbing the fastest as Airbus and Boeing procurement teams qualify alternative chemistries for improved impact energy absorption.
Application:
Volume concentration and margin structure diverge sharply between commercial scale and military premium positioning.
- Commercial Aviation:Narrow-body and wide-body platform production at Boeing in the United States and Airbus in France sustains windscreen and cabin window procurement at scale. Fleet renewal programs at Delta, United, and Lufthansa Group are expanding replacement volumes as aircraft age profiles trigger regulatory inspection cycles.
- Military Aviation:Fighter, transport, and rotary-wing specifications integrate armor, de-icing, and electromagnetic shielding functions that multiply unit costs relative to commercial equivalents. India's defense modernization and indigenous fighter development are creating qualification opportunities for armored canopy suppliers with stealth-compatible coating capabilities.
- Business Jets:Custom cabin configurations and lower production volumes favor specialized transparency fabricators with flexible manufacturing footprints.
- Unmanned Aerial Vehicles:Sensor integration and reduced pressurization requirements enable lighter material specifications and simplified laminate stacks.
Commercial aviation absorbs the dominant procurement volume; military applications command the steepest expansion trajectory as geopolitical tensions accelerate fighter and unmanned platform development across India, the United States, and European NATO members.
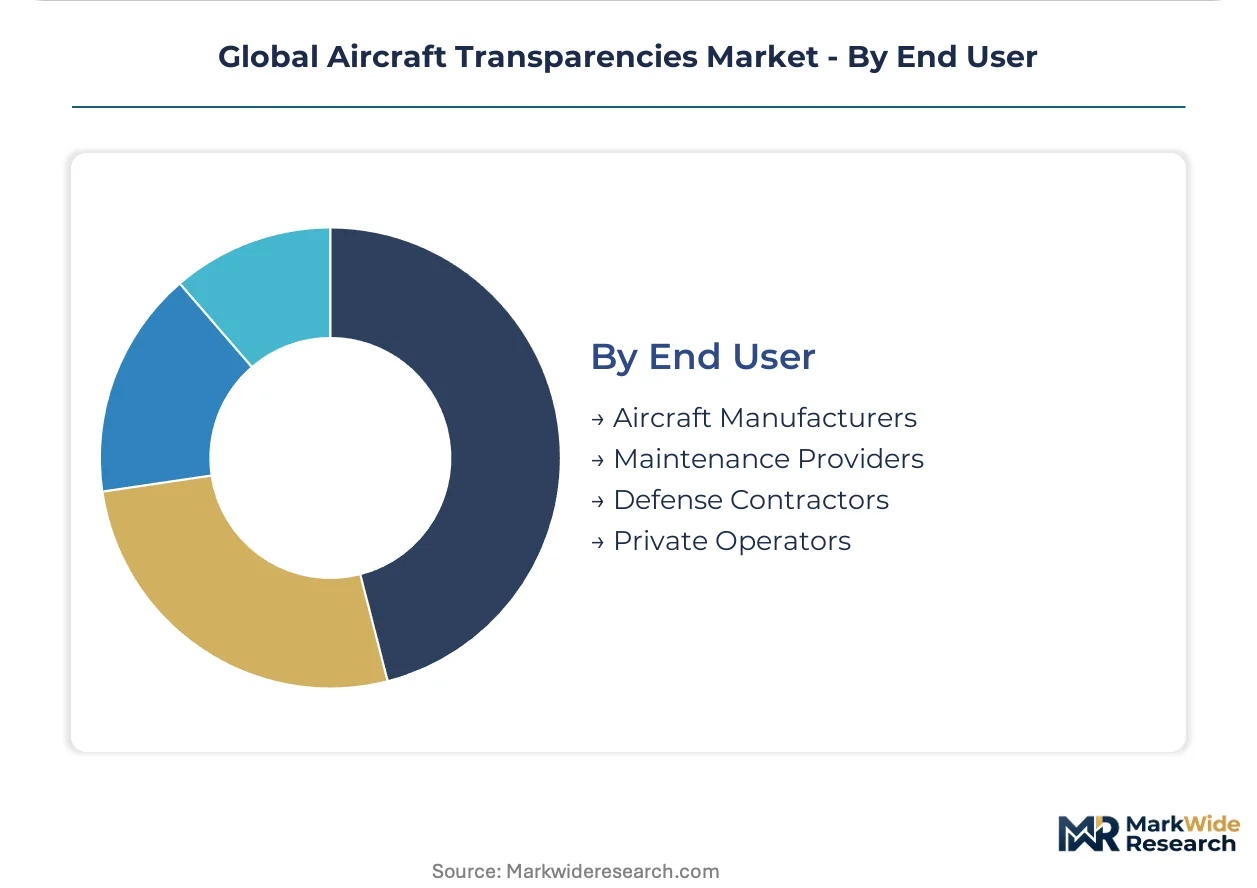
End User:
Procurement authority patterns determine whether transparency contracts flow through airframe integrators or direct to component OEMs.
- Aircraft Manufacturers:Boeing, Airbus, and Embraer source windscreens and cockpit assemblies through qualified supplier partnerships with multi-year qualification commitments. Final assembly line scheduling in the United States, France, and Brazil dictates transparency delivery cadences and inventory positioning.
- Maintenance Providers:Lufthansa Technik in Germany and ST Engineering in Singapore operate repair station networks with EASA and FAA certifications for transparency overhaul and replacement. Southeast Asian carriers in Indonesia and Vietnam are negotiating standalone window contracts that bypass traditional airframe integrator channels.
- Defense Contractors:Lockheed Martin, BAE Systems, and Dassault Aviation manage canopy procurement through military specification programs with classified performance requirements.
- Private Operators:Fractional ownership and charter fleets generate sporadic replacement demand through authorized service centers.
Aircraft manufacturers handle the majority of new-build throughput; maintenance providers are gaining share fastest as airlines disintermediate component procurement from heavy maintenance visits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airline procurement teams and defense ministries cluster transparency demand in manufacturing ecosystems anchored by final assembly lines and certified MRO networks. Buyer archetypes split between fleet-renewal commercial carriers and indigenous fighter programs, each imposing distinct qualification burdens on regional supply bases.
United States
Boeing's final assembly lines in Washington and South Carolina sustain windscreen procurement volumes for narrow-body and wide-body platforms. FAA Part 25.775 certification archives at the regulator's Wichita Aircraft Certification Office create defensive moats around incumbent suppliers. The Nordam Group operates repair station networks in Oklahoma and Texas that handle aftermarket transparency overhaul for domestic carriers.
France
Airbus final assembly at Toulouse-Blagnac anchors European demand for cockpit windscreens and cabin windows. EASA CS-25 Appendix H bird-strike amendments emanating from the Cologne headquarters tighten optical distortion limits under load. Saint-Gobain maintains laminated glass production in northern France serving military fighter canopy programs with electromagnetic shielding specifications.
Germany
Lufthansa Technik's Hamburg headquarters drives aftermarket replacement cycles for aging wide-body fleets requiring recertification against amended visibility standards. The EU Green Deal sustainability mandates from Brussels are pressuring German carriers to evaluate recycled-content interlayers. GKN Aerospace operates transparency repair stations in Bavaria serving Central European MRO demand.
India
Indigenous fighter development under the defense procurement framework is creating demand for armored canopies with stealth-compatible coatings. DGFT import substitution policies are redirecting transparency procurement toward domestic fabrication capabilities. Hindustan Aeronautics facilities in Bangalore and Hyderabad are integrating foreign laminate expertise into local production lines.
United Kingdom
BAE Systems military specification programs at Warton and Samlesbury drive premium canopy procurement for Eurofighter Typhoon platforms. The Civil Aviation Authority's adoption of EASA certification protocols maintains regulatory alignment for commercial aftermarket demand. GKN Aerospace's transparency repair network serves RAF and commercial carrier fleets from western England manufacturing clusters.
Global Aircraft Transparencies Market Key Industry Players
Player mix skews toward vertically integrated material suppliers with captive interlayer production and in-house testing capabilities. Three archetypes dominate: aerospace-grade acrylic specialists with monomer-to-sheet supply chains, laminated glass fabricators serving military electromagnetic shielding requirements, and MRO-focused repair station operators with EASA and FAA dual certifications. Competitive moves concentrate on backward integration into interlayer chemistry and geographic expansion of certified repair networks.
Among North American material suppliers, PPG Industries and Lee Aerospace exemplify the integrated acrylic specialist archetype, while Gentex Corporation occupies a position within the advanced coating and sensor-integration tier. European competitors cluster around Saint-Gobain's laminated glass expertise and GKN Aerospace's MRO network density. These named entities represent the certification-heavy supply base that regulatory tightening continues to favor.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| GKN Aerospace |
| Saint-Gobain |
| The Nordam Group LLC |
| Lee Aerospace |
| Gentex Corporation |
| Control Logistics Inc. |
| Llamas Plastics Inc. |
| Texstars |
| Others |
Cost & Logistics Intelligence
Capacity utilization at stretched acrylic monomer plants in the United States and France shapes both supply concentration and price floors for laminate fabricators. Boeing and Airbus procurement teams leverage multi-year offtake agreements to lock in aerospace-grade material access, compressing margin pools for second-tier suppliers without captive monomer production.
Pricing Analysis
Cost-plus contracts with propylene and butyraldehyde indexation dominate windscreen procurement between tier-one laminate fabricators and airframe integrators. Price differentiation rests on FAA Part 25.775 certification archives and EASA CS-25 Appendix H test data libraries that incumbent suppliers control. Cost compression in cabin window tiers is intensifying because Southeast Asian carriers are unbundling component contracts from heavy maintenance visits. Regional carriers in Indonesia and Vietnam exhibit the highest price sensitivity, while military fighter programs in India demonstrate the lowest due to armor integration and stealth-coating specifications.
Supply Chain Analysis
Strait of Hormuz transit risk underwrites petrochemical feedstock security planning for acrylic monomer producers serving aerospace transparency markets. Supply concentrates in the United States, France, and Germany where PPG Industries, Saint-Gobain, and GKN Aerospace anchor production. The laminate stack draws from stretched acrylic sheet, PVB or thermoplastic polyurethane interlayers, and transparent conductive oxide coatings. Single-source vulnerability concentrates at qualified interlayer suppliers with EASA and FAA dual certification. Distribution runs through airframe integrator channels for new-build programs and certified MRO networks for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as airline procurement teams disintermediate component sourcing from traditional airframe integrator channels, creating niches for specialized transparency fabricators with flexible manufacturing footprints.
For Market Incumbents: Secure backward integration into thermoplastic polyurethane interlayer chemistry to defend margin pools against material substitution threats from Airbus and Boeing procurement teams qualifying alternative laminate stacks. Anchor capacity expansion in India to capture indigenous fighter canopy demand under DGFT import substitution policies. For New Entrants and Emerging Players: Lead with recycled-content interlayer qualification pathways opened by EU Green Deal sustainability mandates targeting German carrier procurement teams. Target standalone cabin window contracts with Southeast Asian low-cost carriers in Indonesia and Vietnam where rapid fleet expansion outpaces established MRO infrastructure. Pursue direct airline technical procurement relationships that bypass traditional airframe integrator channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among MRO-focused repair station operators with EASA and FAA dual certifications serving aging wide-body fleet replacement cycles. Long-term viability favors acquisition targets with captive test data archives and in-house optical inspection capabilities. Monitor EASA-FAA harmonization delays for new laminate formulations as the signal indicating qualification timeline compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Interlayer Chemistry | Captive supply of thermoplastic polyurethane secures margin pools as Airbus and Boeing qualify alternative laminate stacks. |
| Certified Repair Network Expansion | EASA and FAA dual-certified MRO stations in Southeast Asia capture unbundled airline procurement bypassing integrator channels. |
| Recycled-Content Interlayer Development | EU Green Deal lifecycle assessment requirements create qualification pathways for sustainable material alternatives. |
| Digital Twin Platform Integration | Sensor-embedded transparency convergence with predictive maintenance enables condition-based replacement contracts. |
| India Defense Procurement Localization | DGFT import substitution policies redirect armored canopy fabrication toward domestic HAL facilities in Bangalore. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FAA certification archives, EASA regulatory filings, and OEM procurement disclosures. Primary interviews engaged procurement directors at commercial airlines, platform engineers at airframe integrators, plant managers at acrylic monomer facilities, and certification leads at MRO repair stations. Secondary validation drew from FAA Wichita Aircraft Certification Office documentation, EASA CS-25 Appendix H amendment records, customs trade data for aerospace-grade acrylic, and SEC filings from listed material suppliers. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Segmentation dimensions modeled include product type, material chemistry, application sector, and end-user procurement authority. CAGRs were derived from fleet renewal program schedules, regulatory recertification cycle frequencies, and defense procurement framework timelines. Forecast inputs incorporated narrow-body and wide-body production rates at Boeing and Airbus final assembly lines, plus indigenous fighter development milestones under India's defense procurement framework.
The analysis sits within stated boundaries; outcomes outside sustained airline fleet renewal momentum or accelerated EASA-FAA harmonization would require recalibration. Forecasts reflect assumptions regarding certification timeline stability and petrochemical feedstock price volatility. Practitioners should keep alternative scenarios live as EU Green Deal sustainability mandate enforcement and DGFT import substitution policy implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Commercial Aircraft Market
Aircraft
Military Transport Aircraft Market
Aircraft
Winglets Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Military Aircraft Market
Aircraft
Global Business Aircraft Market
Aircraft
Europe Business Jet Market
Aircraft
Heavy-Lift Helicopter Market
Aircraft
Global Aircraft Tugs Market
Aircraft
North America Commercial Aircraft Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
Military Rotorcraft Market
Aircraft
Online in-Flight Shopping Market
Aircraft
Europe Commercial Aircraft Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market