
 Aircraft Hydraulic Actuators Market | 2026-2036
Aircraft Hydraulic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Hydraulic Actuators Market Analysis
A capability gap in precision machining and integrated electronic-hydraulic controls is rotating competitive advantage toward vertically integrated suppliers. Raytheon Technologies Corporation leverages its Collins Aerospace division's captive forging and surface treatment capacity to control lead times on flight control actuators. Safran SA anchors European supply through Liebherr-Safran Landing Systems, its joint venture dominating landing gear actuator production for Airbus platforms. Parker Hannifin Corporation competes across the aftermarket with distributed service centers that shorten MRO turnaround for cargo door and thrust reverser systems.
Aircraft hydraulic actuators are electromechanical devices that convert pressurized hydraulic fluid, typically at 3,000 to 5,000 psi operating pressure, into linear or rotary mechanical force for positioning flight surfaces, landing gear, and engine components. Linear actuators dominate OEM installations for primary flight control surfaces where high force density and fail-safe positioning remain mandatory. Rotary actuators sustain above-average growth in thrust reverser applications as engine OEMs demand lighter, more compact packages that integrate position sensing. The MRO provider segment concentrates margin pools because hydraulic seals and piston rods require scheduled replacement cycles driven by flight hour accumulation rather than calendar time.
The FAA enforces airworthiness standards under 14 CFR Part 25 that mandate redundant hydraulic channels for transport category aircraft, directly shaping actuator architecture and qualification testing burdens. EASA's CS-25 certification requirements and the EU's REACH regulation on chromium-plating alternatives are forcing suppliers to qualify new surface coatings and seal elastomers before European market access. Military procurement through the Pentagon's Defense Federal Acquisition Regulation Supplement imposes traceability and counterfeit prevention protocols that extend production timelines but protect incumbent suppliers. Stakeholders must monitor how fly-by-wire architectures and electrically actuated backups reshape the long-term specification mix for hydraulic systems without assuming immediate displacement.
Market Dynamics
The transition toward fly-by-wire architectures with electrically actuated backups is compressing specification cycles for hydraulic actuators while maintaining stringent airworthiness mandates. OEMs now demand actuators that bridge hydraulic reliability with electromechanical integration, forcing suppliers to requalify core designs under accelerated timelines.
Growth Catalysts
- FAA 14 CFR Part 25 redundancy mandates:Transport category aircraft must maintain dual hydraulic channels, sustaining demand for fail-safe actuator architectures across narrow-body and wide-body production lines.
- Thrust reverser weight reduction targets:Engine OEMs specify compact rotary actuator packages with integrated position sensing, accelerating material substitution toward titanium and advanced aluminum alloys.
- United States defense procurement:The Pentagon's Defense Federal Acquisition Regulation Supplement traceability protocols protect incumbent suppliers while extending multi-year actuator contracts for tactical and strategic airframes.
Market Restraints
- Specialized alloy supply concentration:Titanium and high-strength aluminum sourcing clusters in limited forging capacity, exposing lead time volatility for precision-machined piston rods.
- EASA REACH chromium-plating restrictions:The EU's ban on hexavalent chromium surface treatments forces qualification of alternative coatings, extending certification timelines before European market access.
- Electromechanical actuator substitution:Electrically powered alternatives for secondary flight surfaces threaten hydraulic share in non-critical positioning applications.
Strategic Opportunities
- India civil aviation expansion:IndiGo and Air India's fleet modernization programs create demand for landing gear and cargo door actuators as domestic MRO infrastructure develops.
- Electronic-hydraulic control convergence:Integration of smart position sensors with traditional hydraulic power units enables predictive maintenance contracts and recurring revenue streams.
- Japan defense aircraft recapitalization:METI procurement for F-X fighter development prioritizes domestic actuator supply chain partnerships, opening joint venture pathways for foreign tier-1 suppliers.
Industry Challenges
- Precision machining skill scarcity:Tolerances below 0.001 inch for flight control actuator cylinders require specialized aerospace machinists, constraining production ramp rates.
- Dual certification burden:Simultaneous FAA and EASA qualification for new seal elastomers and surface coatings doubles testing costs and extends time-to-revenue for design refreshes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Hydraulic Actuators Market |
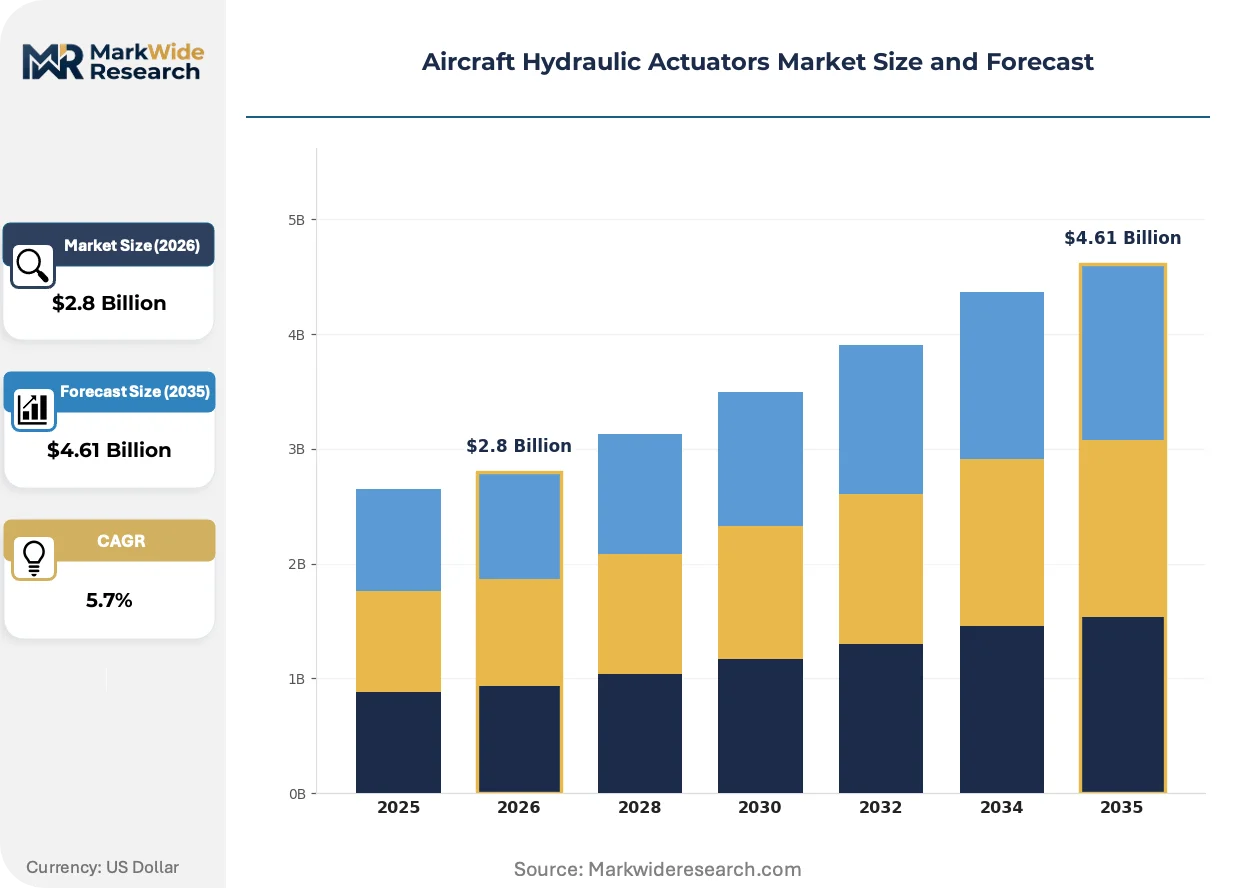
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Rotary Actuators, Miniature Actuators, Micro Actuators Application: Landing Gear Systems, Flight Control Systems, Thrust Reverser Systems, Cargo Door Systems End User: OEMs, MRO Providers, Military, Commercial Airlines Connectivity: Wired, Wireless, CAN Bus, Ethernet |
| Companies Covered | Raytheon Technologies Corporation, Curtiss-Wright Corporation, Honeywell International Inc., Safran SA, Parker Hannifin Corporation, Moog Inc., Eaton Corporation Inc., Liebherr Group, Woodward Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Hydraulic Actuators Market Emerging Trajectories
Actuator architecture is converging toward intelligent, condition-monitored systems that reduce unscheduled maintenance while preserving hydraulic power density. This shift redefines supplier value propositions around data-enabled service models rather than discrete component sales.
Additive manufacturing of titanium actuator housings is supplanting subtractive machining for low-volume, complex-geometry flight control components. Tier-1 suppliers at Boeing and Airbus are qualifying laser powder bed fusion for secondary structure brackets, compressing lead times from fourteen weeks to four. The technology is supplanting traditional forging-for-machining workflows in prototyping and limited production runs.
EASA's CS-25 certification amendments for flight-critical systems now mandate extended environmental testing for hydraulic seals across temperature extremes from minus 65 to plus 275 degrees Fahrenheit. European suppliers must revalidate existing qualified designs under these expanded parameters, diverting engineering resources from new product development. Landing gear actuator manufacturers face the steepest compliance burden given their exposure to runway debris and thermal cycling.
Airline procurement teams now unbundle actuator overhaul services from OEM original equipment purchases, directing MRO volume toward independent service centers with FAA/EASA dual repair station certifications. This fragmentation compresses margin pools for integrated suppliers while elevating parts-traceability requirements. The shift is most visible in North American cargo operator fleets, where door and thrust reverser actuator turnaround times directly impact aircraft utilization rates.
Aircraft Hydraulic Actuators Market Segmentation
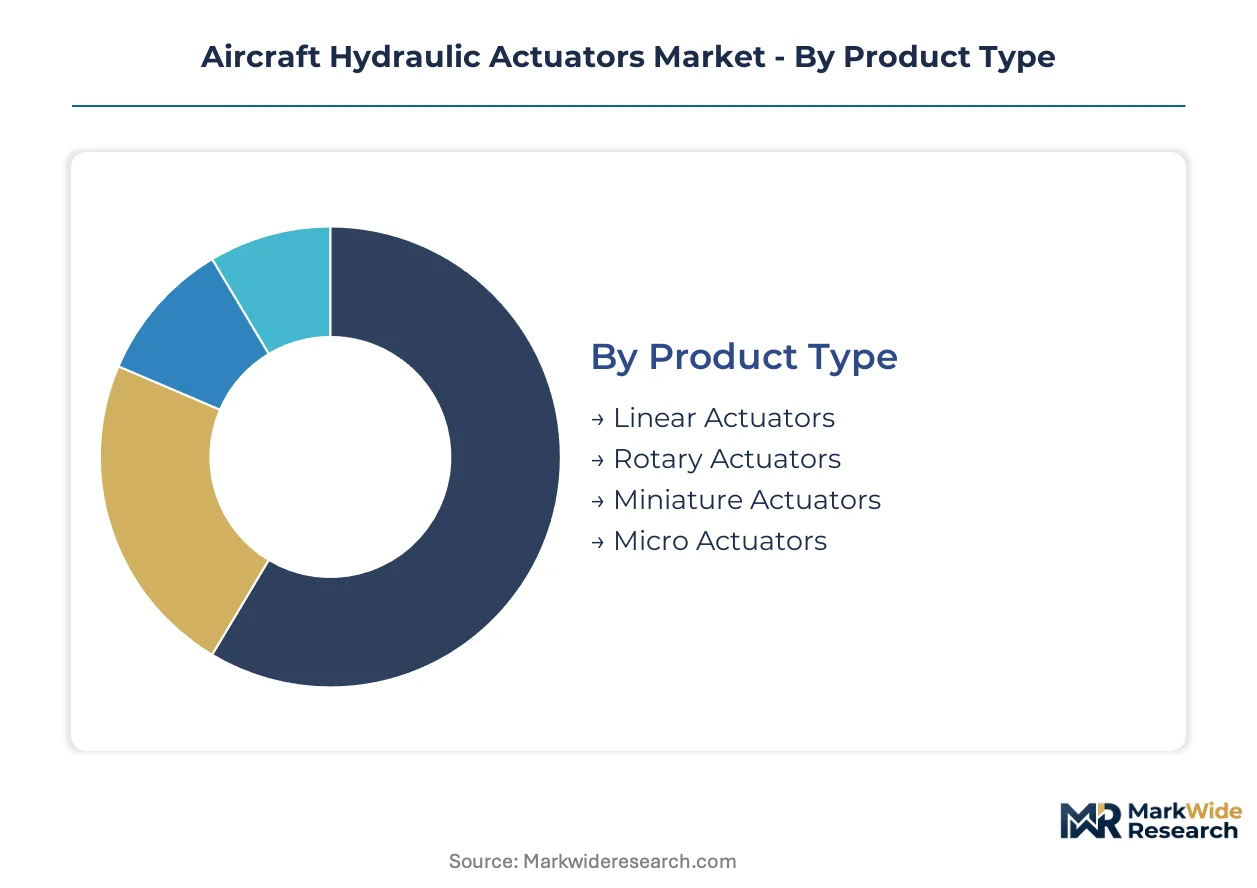
Hydraulic actuator procurement splits sharply between flight-critical OEM specifications and aftermarket MRO volume pools. Understanding these segment boundaries clarifies where suppliers must maintain dual certification capabilities versus specialized service center networks.
Product Type:
Margin pools concentrate in large-bore linear actuators where precision machining tolerances and specialized alloy sourcing create supply scarcity.
- Linear Actuators:These devices convert hydraulic pressure into straight-line mechanical force for primary flight control surfaces, typically operating at 3,000 to 5,000 psi. Boeing and Airbus narrow-body programs in the United States and France anchor demand for high-force-density units with fail-safe positioning architectures.
- Rotary Actuators:Compact packages that transform fluid pressure into rotational motion, increasingly specified with integrated position sensing for thrust reverser applications. Engine OEMs in the United States and United Kingdom are driving material substitution toward titanium housings to meet weight reduction targets.
- Miniature Actuators:Reduced-scale units for auxiliary systems and secondary flight surfaces where space constraints dominate specification.
- Micro Actuators:Precision components for cockpit instrumentation and sensor positioning in unmanned aerial platforms.
Linear actuators hold installed capacity across legacy fleets. Rotary actuators are rotating up the share rankings as engine OEMs prioritize weight reduction.
Application:
Application segmentation tracks directly to FAA 14 CFR Part 25 redundancy mandates, with flight-critical systems commanding premium certification burdens.
- Landing Gear Systems:Heavy-duty actuators for gear extension and retraction, exposed to runway debris and thermal cycling. Airbus A320 and Boeing 737 production lines in France and the United States sustain volume for Liebherr-Safran and Collins Aerospace.
- Flight Control Systems:Primary surface positioning for ailerons, elevators, and rudders where dual hydraulic channels remain mandatory. EASA CS-25 amendments are extending environmental testing requirements for seal qualification across temperature extremes.
- Thrust Reverser Systems:Compact rotary packages with position feedback integration for engine OEM specifications.
- Cargo Door Systems:Lower-criticality positioning where MRO turnaround time directly impacts freighter utilization rates.
Flight control systems maintain the steepest compliance burden. Thrust reverser systems are climbing the fastest as engine OEMs demand lighter packages.
End User:
Customer type determines whether procurement flows through multi-year OEM contracts or fragmented aftermarket service networks.
- OEMs:Original equipment manufacturers specify actuators during airframe development, locking in decade-long supply agreements with qualification requirements. Boeing's production footprint in Washington and South Carolina, plus Airbus final assembly in Toulouse and Hamburg, concentrate procurement volume.
- MRO Providers:Independent maintenance facilities capture seal and piston rod replacement cycles driven by flight hour accumulation. FAA and EASA dual repair station certifications are becoming mandatory for North American cargo operator contracts.
- Military:Pentagon procurement through Defense Federal Acquisition Regulation Supplement protocols imposes traceability and counterfeit prevention requirements.
- Commercial Airlines:Direct procurement concentrates in low-cost carriers with in-house technical capabilities.
OEMs retain specification control over new programs. MRO providers are expanding share as airlines unbundle overhaul services from original equipment purchases.
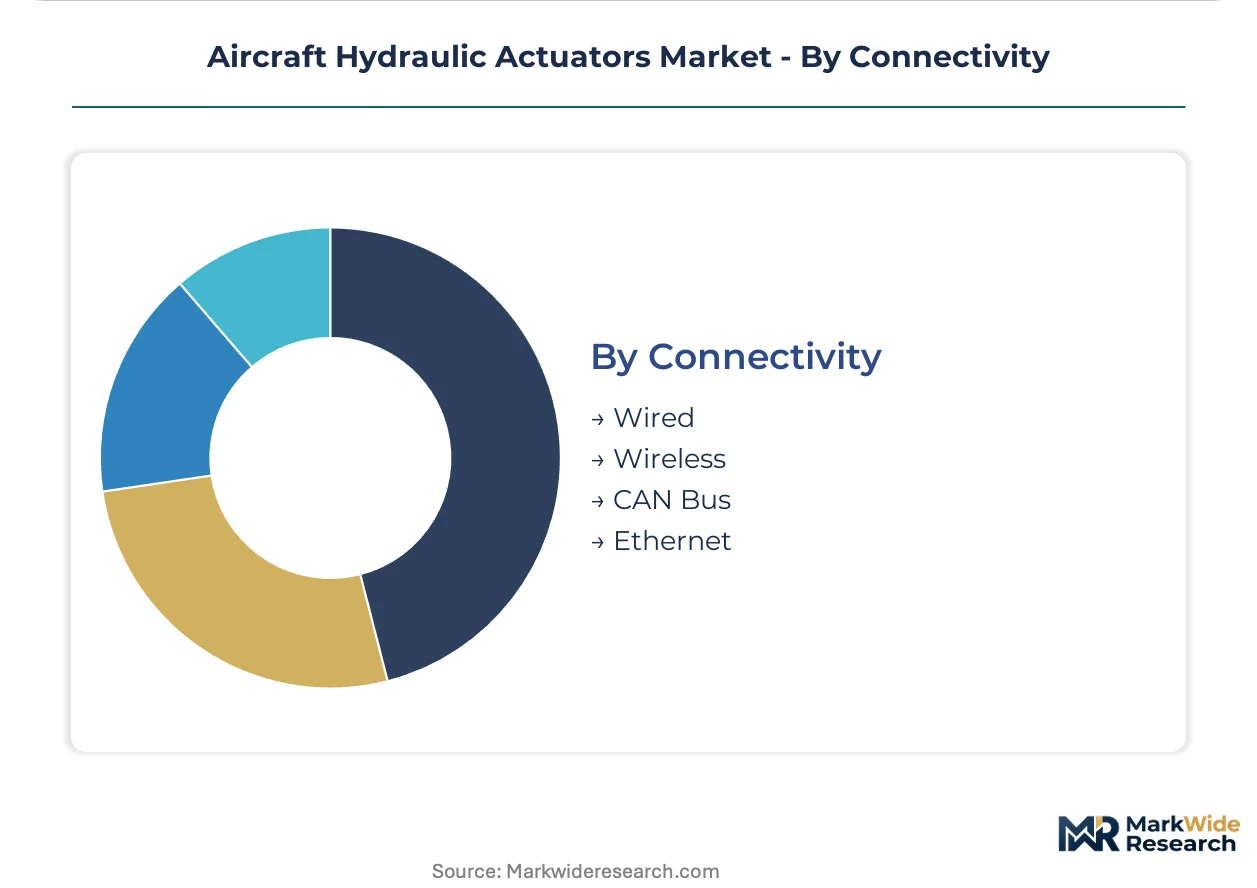
Connectivity:
Data interface selection is converging toward architectures that enable predictive maintenance without displacing hydraulic power density.
- Wired:Traditional analog and discrete signal transmission for flight-critical systems where electromagnetic interference immunity remains non-negotiable. Legacy Boeing 737 and Airbus A320 fleets in the United States and Germany maintain substantial installed base.
- CAN Bus:Controller Area Network protocols enabling multi-drop sensor integration with reduced wiring weight. Thrust reverser and landing gear applications are adopting this standard for position feedback loops.
- Wireless:Emerging architectures for non-critical monitoring where latency tolerance permits radio frequency transmission.
- Ethernet:High-bandwidth digital backbone for integrated vehicle health management systems in next-generation platforms.
Wired architectures dominate flight-critical certification. CAN Bus is gaining share fastest as smart actuator integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where Boeing's production footprint and Pentagon procurement sustain premium actuator volumes, while European suppliers absorb EASA REACH compliance costs that compress margins on chromium-plating alternatives.
United States
Boeing's final assembly lines in Washington and South Carolina anchor OEM demand for flight control and landing gear actuators. The FAA enforces 14 CFR Part 25 redundancy mandates that sustain dual-channel hydraulic architectures across narrow-body and wide-body platforms. The Pentagon's Defense Federal Acquisition Regulation Supplement traceability protocols protect incumbent suppliers through multi-year military contracts for tactical airframes.
France
Airbus final assembly in Toulouse and Hamburg concentrates procurement for A320 and A350 programs, with Liebherr-Safran Landing Systems dominating landing gear actuator supply. EASA CS-25 certification amendments extend environmental testing requirements for hydraulic seals across temperature extremes. The Auvergne-Rhône-Alpes aerospace cluster around Lyon hosts precision forging capacity for titanium piston rods.
Germany
Airbus Hamburg operations and MTU Aero Engines sustain demand for thrust reverser rotary actuators with integrated position sensing. The country's national aviation regulator enforces EU REACH restrictions on hexavalent chromium surface treatments, forcing qualification of alternative coatings. Bavaria's aerospace supply chain around Munich specializes in precision-machined actuator cylinders for flight-critical systems.
Japan
METI procurement for F-X fighter development prioritizes domestic actuator supply chain partnerships, opening joint venture pathways for foreign tier-1 suppliers. The country's industrial standards body mandates traceability protocols for flight-critical hydraulic components. The Nagoya aerospace cluster in Chubu region concentrates subsystem integration for regional jet programs.
India
IndiGo and Air India's fleet modernization programs create demand for landing gear and cargo door actuators as domestic MRO infrastructure develops. The Directorate General of Civil Aviation enforces airworthiness standards aligned with FAA and EASA frameworks for imported equipment. Bangalore's aerospace park in Karnataka hosts emerging precision machining capacity for secondary flight surface actuators.
Aircraft Hydraulic Actuators Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated OEM-tier suppliers commanding specification control while specialized fabricators compete on aftermarket turnaround speed. The market structure consolidates around three dominant tiers: aerospace conglomerates with captive forging capacity, independent motion control specialists with distributed service networks, and regional precision machinists serving non-critical applications. Strategic moves concentrate on electronic-hydraulic control convergence and additive manufacturing qualification for titanium housings.
Among diversified aerospace conglomerates, Raytheon Technologies Corporation and Safran SA exemplify the vertically integrated archetype, each anchoring regional supply through captive surface treatment and forging capacity. Parker Hannifin Corporation occupies a position within the motion control specialist tier, competing across aftermarket channels with distributed MRO service centers. These three entities collectively represent the competitive spectrum from upstream material control to downstream service fragmentation.
| Leading Market Players |
|---|
| Raytheon Technologies Corporation |
| Curtiss-Wright Corporation |
| Honeywell International Inc. |
| Safran SA |
| Parker Hannifin Corporation |
| Moog Inc. |
| Eaton Corporation Inc. |
| Liebherr Group |
| Woodward Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with tier-1 aerospace OEMs lock in titanium forging access and price visibility across multi-year production cycles, insulating incumbent suppliers from spot market volatility while binding them to qualification timelines.
Pricing Analysis
Configured-to-order pricing for flight-critical actuators commands substantial premiums over standard catalog units due to FAA 14 CFR Part 25 dual-channel certification requirements and specialized alloy specifications. Pricing stratifies across OEM-tier, aftermarket service, and non-certified commercial tiers based on traceability documentation depth and flight-hour warranty coverage. Cost compression in the aftermarket tier is intensifying as airlines unbundle overhaul services and direct volume toward independent MRO providers with faster turnaround capabilities. Low-cost carriers with in-house technical capabilities exhibit highest price sensitivity, while military procurement through Pentagon DFARS protocols shows lowest sensitivity due to traceability mandates.
Supply Chain Analysis
Inventory buffers for precision-machined piston rods and specialized hydraulic seals extend lead times when titanium forging capacity tightens, exposing actuator manufacturers to production scheduling risk. Supply concentrates in the United States, France, and Germany where Boeing, Airbus, and precision aerospace clusters anchor demand. Raw material dependencies center on titanium forgings, high-strength aluminum alloys, and qualified seal elastomers. Single-source vulnerability persists for flight-critical seal formulations subject to EASA REACH chromium-plating restrictions. Distribution runs through OEM direct procurement for new platforms and fragmented independent service centers for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized aerospace machining capabilities below 0.001-inch tolerances for flight control cylinders represent the binding constraint on production expansion, creating asymmetric returns for suppliers with captive precision forging capacity.
For Market Incumbents: Consolidate backward integration into titanium forging and surface treatment capacity to protect lead time advantages as EASA REACH compliance extends qualification timelines for alternative coatings. Deepen electronic-hydraulic control convergence investments to capture predictive maintenance revenue streams before electromechanical substitutes penetrate secondary flight surface applications. Lock in multi-year capacity reservations with Airbus and Boeing narrow-body programs to defend specification control. For New Entrants and Emerging Players: Predictive maintenance service gaps in the cargo door and thrust reverser actuator segments present white-space opportunities where incumbent OEMs under-serve independent MRO providers demanding faster turnaround. Target India's developing domestic MRO infrastructure as the most penetrable geography, where IndiGo and Air India fleet expansion outpaces qualified local actuator service capacity. Enter through joint venture partnerships with established precision machinists to bypass dual FAA-EASA certification barriers. For Investors and Strategic Acquirers: Regional precision machinists with existing aerospace certifications and open forging capacity represent the optimal acquisition target archetype for platform consolidation plays. Long-term viability hinges on positioning within fly-by-wire architectures that preserve hydraulic power density for primary flight surfaces while integrating smart position sensing. Monitor EASA CS-25 amendment implementation timelines as the inflection signal indicating which suppliers have completed requalification of seal elastomers under expanded temperature testing parameters.| Strategic Initiative | Industry Significance |
|---|---|
| Electronic-Hydraulic Control Convergence | Integration of smart position sensors with hydraulic power units enables predictive maintenance contracts at Collins Aerospace and Parker Hannifin service networks. |
| Additive Manufacturing Qualification | Laser powder bed fusion certification for titanium actuator housings compresses prototyping lead times from fourteen weeks to four at Boeing and Airbus tier-1 suppliers. |
| Dual Certification Investment | Simultaneous FAA and EASA qualification for alternative chromium-free surface coatings protects European market access against REACH regulatory restrictions. |
| India MRO Infrastructure Partnership | Joint venture pathways with domestic precision machinists in Bangalore aerospace park capture landing gear actuator demand from IndiGo and Air India fleet programs. |
| Military Traceability Compliance | Defense Federal Acquisition Regulation Supplement protocols secure multi-year Pentagon contracts for tactical airframe actuators with counterfeit prevention documentation. |
Methodological Framework
Operator-level perspectives from OEM procurement directors, MRO facility managers, aerospace forging specialists, and regulatory compliance officers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews across these stakeholder roles with secondary validation drawing from FAA airworthiness directives, EASA CS-25 certification amendments, Pentagon procurement disclosures, and customs trade data for titanium and high-strength aluminum flows. Bottom-up actuator shipment estimates triangulated against top-down airframe production forecasts from Boeing and Airbus final assembly disclosures.
Sensitivity analysis around titanium price volatility, EASA REACH implementation timing, and electromechanical substitution rates tested forecast robustness across the projection horizon. Segmentation modeling incorporated product type, application criticality, end-user procurement channel, and connectivity architecture dimensions. CAGRs derived from regression analysis of historical production data correlated with flight hour accumulation patterns and fleet modernization program announcements. Industry-specific inputs included thrust reverser weight reduction specifications from engine OEMs and additive manufacturing qualification timelines from tier-1 supplier disclosures.
Underlying assumptions cover sustained narrow-body production rates, EASA REACH compliance deadlines, and defense procurement continuity, with deviation risk concentrated in electromechanical actuator penetration speed and specialized alloy supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Americas Aircraft Lighting Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Aircraft Hydraulic System Market
Aircraft Power Systems
Military Power Solutions Market
Aircraft Power Systems
Global Aircraft Micro Turbine Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Gearbox Market
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Aircraft Auxiliary Power Unit Market
Aircraft Power Systems
Aircraft Battery Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aircraft Actuator Market
Aircraft Power Systems
Aircraft Fluid Power Components Market
Aircraft Power Systems
Global Aircraft Electrification Market
Aircraft Power Systems
Aircraft Thrust Reverser Market
Aircraft Power Systems
Fly-By-Wire System Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market