
 Asia-Pacific Aircraft Manufacturing Market | 2026-2036
Asia-Pacific Aircraft Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Aircraft Manufacturing Market Analytics
Modular propulsion-airframe integration is broadening buyer choice across the Asia-Pacific Aircraft Manufacturing Market. Commercial Aircraft Corporation of China leverages state-backed vertical integration to control critical supply tiers for its C919 platform. Hindustan Aeronautics Limited anchors India's indigenous fighter and helicopter programs through captive engine and avionics capabilities. Korea Aerospace Industries competes in the regional trainer and light-attack segment through technology partnerships with Western primes.
Asia-Pacific aircraft manufacturing encompasses the design, assembly, and systems integration of fixed-wing and rotary-wing platforms with maximum takeoff weights ranging from sub-six-ton trainers to over seventy-seven-ton widebodies, employing aluminum-lithium alloys, carbon-fiber reinforced polymers, and additive-manufactured titanium brackets to achieve specific fuel-burn and payload-range targets for commercial and defense operators. Commercial jets command the dominant value pool given order backlogs from full-service and low-cost carriers, while composite materials represent the fastest-advancing technology segment as airframers substitute metal structures to meet performance benchmarks. Military aircraft sustain resilient demand through India's indigenous Tejas production and Australia's F-35 final assembly and check-out facility.
China's MIIT enforces GB standards and dual carbon goals that mandate progressive fuel-efficiency improvements, while India's CEA and DGFT coordinate import-substitution policies through PLI-linked aerospace incentives. Japan's METI and PMDA align certification timelines with FAA and EMA benchmarks to preserve export market access for Mitsubishi Heavy Industries and Kawasaki Heavy Industries. Stakeholders must track how divergent carbon-accounting rules across Beijing, New Delhi, and Tokyo reshape supplier qualification and cross-border component flows.
Market Dynamics
China's MIIT dual carbon goals are compressing design cycles across the Asia-Pacific Aircraft Manufacturing Market as airframers substitute aluminum with carbon-fiber reinforced polymers to meet fuel-efficiency mandates.
Growth Catalysts
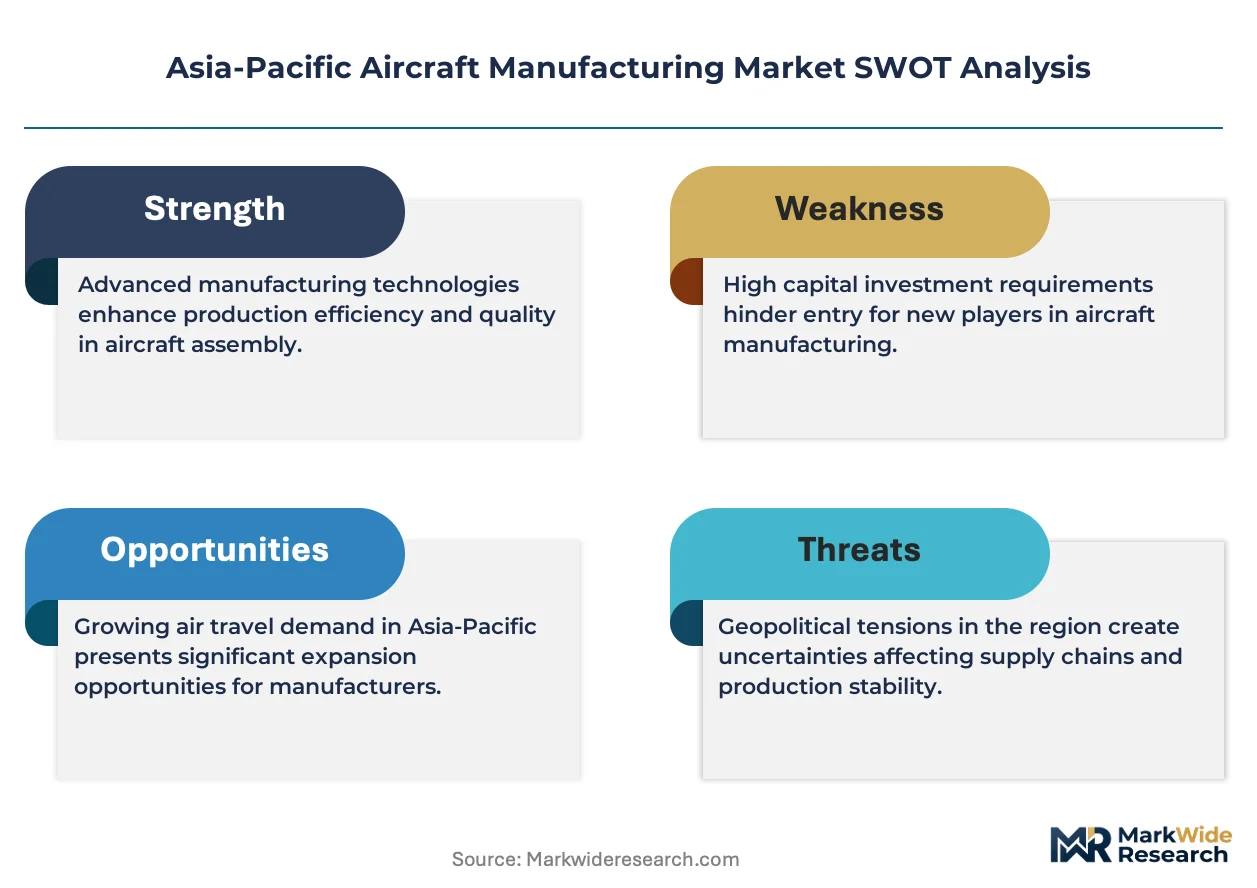
- MIIT Dual Carbon Mandates:Beijing's GB standards enforce progressive fuel-efficiency improvements that push OEMs toward composite-intensive airframes and electric-hybrid propulsion architectures.
- Low-Cost Carrier Fleet Renewal:Southeast Asian budget airlines are accelerating narrowbody orders to replace aging fleets and capture post-pandemic traffic recovery across Indonesia, Vietnam, and the Philippines.
- Aluminum-Lithium Alloys:Advanced metallurgy reduces structural weight by fifteen percent versus conventional aluminum, enabling payload-range improvements that satisfy operator unit-cost targets.
Market Restraints
- Titanium Input Volatility:Sponge titanium prices fluctuate with Russian supply disruptions, squeezing margins on additive-manufactured brackets and engine components.
- Carbon Fiber Concentration:Toray, Teijin, and SGL Carbon control seventy percent of aerospace-grade precursor supply, creating qualification bottlenecks for second-tier airframers.
- Import-Substitution Friction:India's DGFT licensing requirements delay Western avionics integration for indigenous platforms, extending certification timelines beyond original projections.
Strategic Opportunities
- Vietnam MRO Expansion:Da Nang and Ho Chi Minh City are developing maintenance capabilities that capture regional fleet growth without full manufacturing investment.
- PLI-Linked Aerospace Incentives:India's CEA production-linked incentive schemes subsidize domestic component fabrication for defense and civil programs alike.
- Digital Twin Convergence:Integration of physics-based modeling with real-time sensor feedback compresses flight-test hours and accelerates type certification for new variants.
Industry Challenges
- Composite Repair Certification:Technician scarcity in bonded-structure NDT techniques creates MRO backlogs that ground aircraft longer than metal-airframe equivalents.
- Cross-Border Carbon Accounting:Divergent emissions-reporting rules across Beijing, New Delhi, and Tokyo force suppliers to maintain three parallel qualification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Aircraft Manufacturing Market |
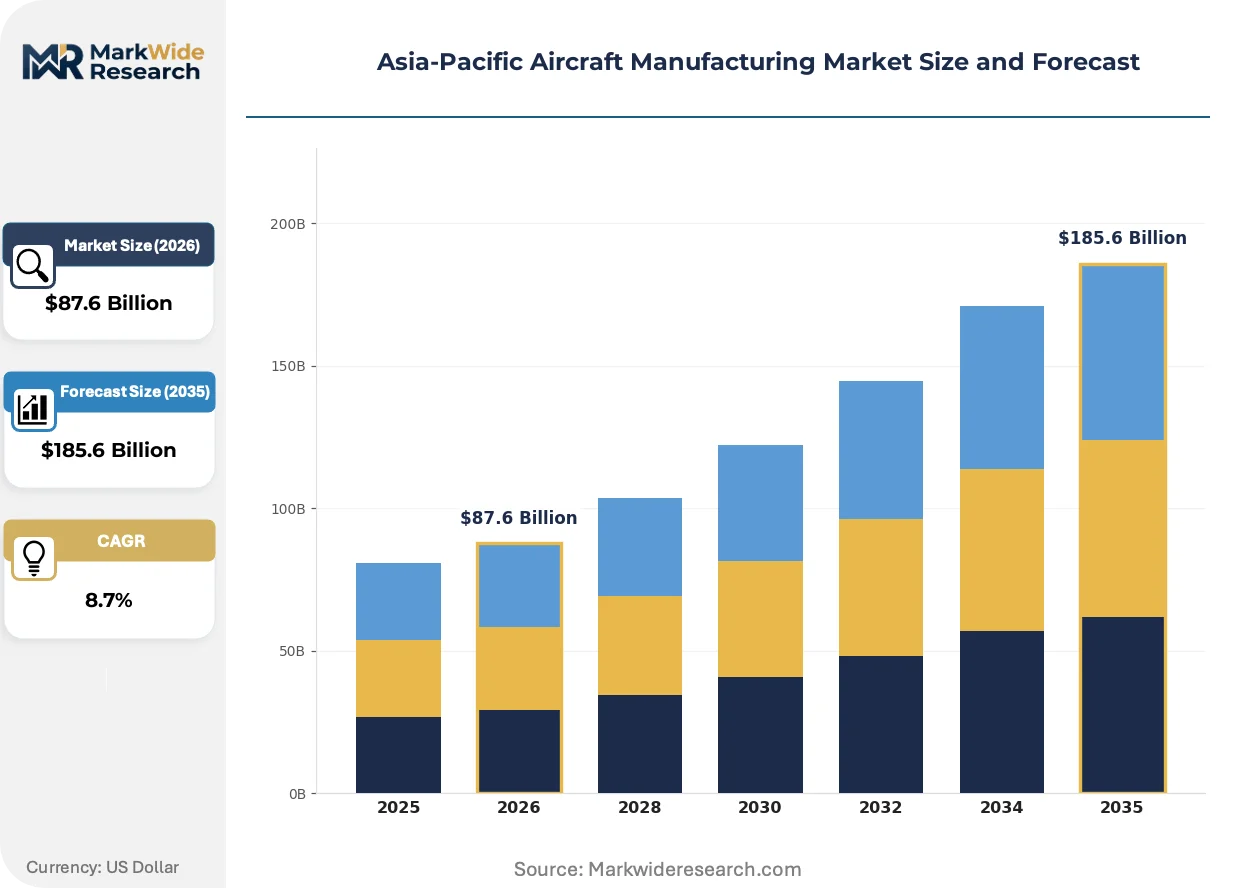
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $185.6 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
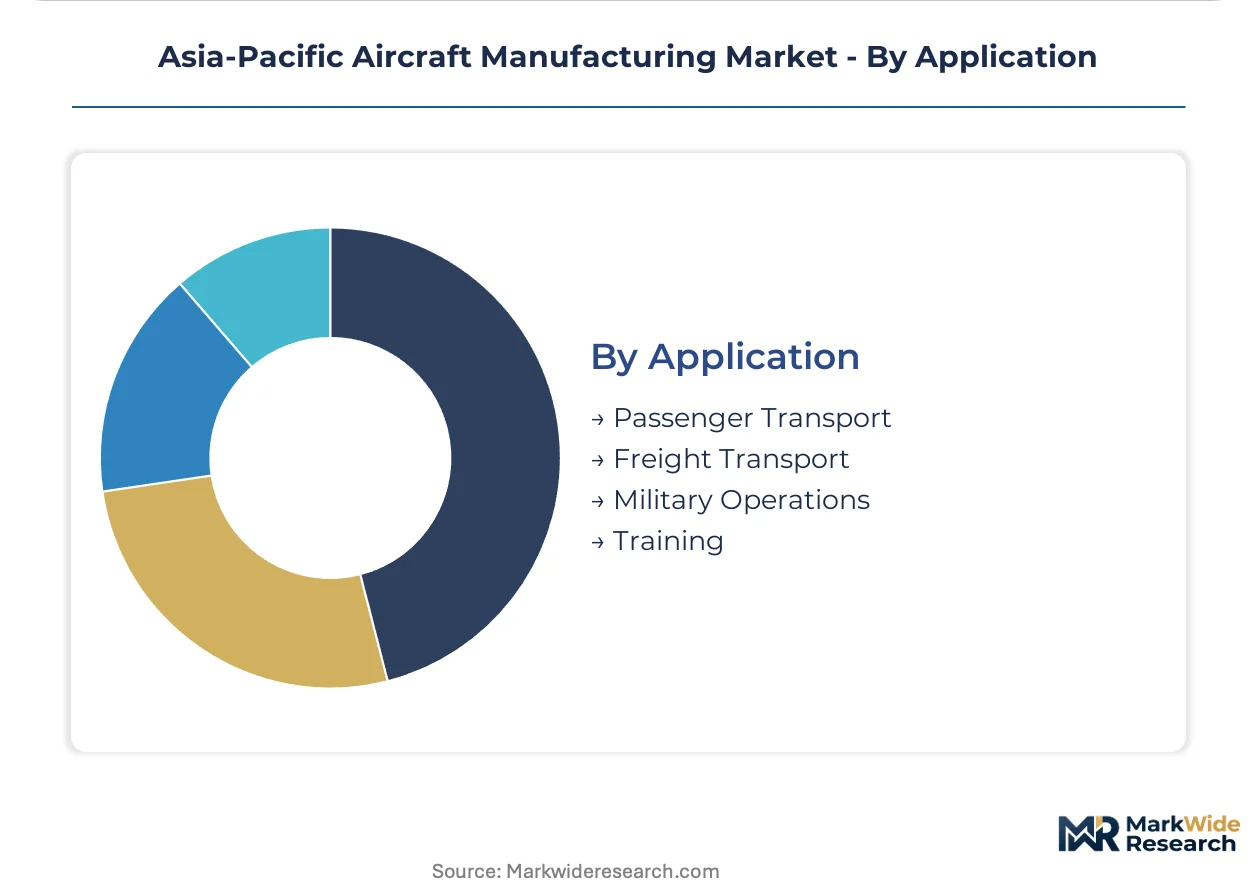
| Segmentation | Product Type: Commercial Jets, Regional Aircraft, Military Aircraft, Helicopters Technology: Advanced Manufacturing, Automation, 3D Printing, Composite Materials End User: Airlines, Government, Private Operators, Cargo Application: Passenger Transport, Freight Transport, Military Operations, Training |
| Companies Covered | Commercial Aircraft Corporation of China, Ltd., Aviation Industry Corporation of China, Hindustan Aeronautics Limited, Korea Aerospace Industries, Ltd., Mitsubishi Heavy Industries, Kawasaki Heavy Industries, Subaru Corporation, ST Engineering Aerospace, Singapore Technologies Engineering Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Aircraft Manufacturing Market Evolving Landscape
Propulsion-airframe integration is the dominant design axis reshaping competitive positioning across the Asia-Pacific Aircraft Manufacturing Market as electrification and hydrogen architectures mature.
Hybrid-electric distributed propulsion is electrifying regional aircraft development, with motor-in-wing configurations enabling boundary-layer ingestion that cuts fuel burn by twenty percent. Japanese METI-funded consortia are flight-testing megawatt-class systems for fifty-seat platforms. This architecture is electrifying the sub-regional segment previously dominated by turboprops, compressing the addressable market for conventional engine OEMs.
China's GB 36886-2018 and subsequent MIIT amendments mandate progressive NOx and CO2 reductions that force airframers to redesign nacelles and combustors simultaneously. The industrial consequence is tighter coupling between engine and airframe development schedules, eliminating the traditional stagger that allowed independent optimization. Widebody programs targeting Chinese type certification are most affected, with COMAC and AVIC suppliers reconfiguring test rigs to capture dual compliance data.
Airlines are unbundling power-by-the-hour contracts into discrete component-level service agreements, disrupting the traditional engine OEM aftermarket lock-in. Lessors and low-cost carriers in Indonesia and Malaysia now procure rotor-blade and hot-section maintenance separately, driving MRO providers to certify on multiple engine platforms simultaneously. This fragmentation is most visible in the narrowbody aftermarket serving Southeast Asian budget operators, where third-party shops capture volume previously reserved for factory-affiliated networks.
Asia-Pacific Aircraft Manufacturing Market Segmentation
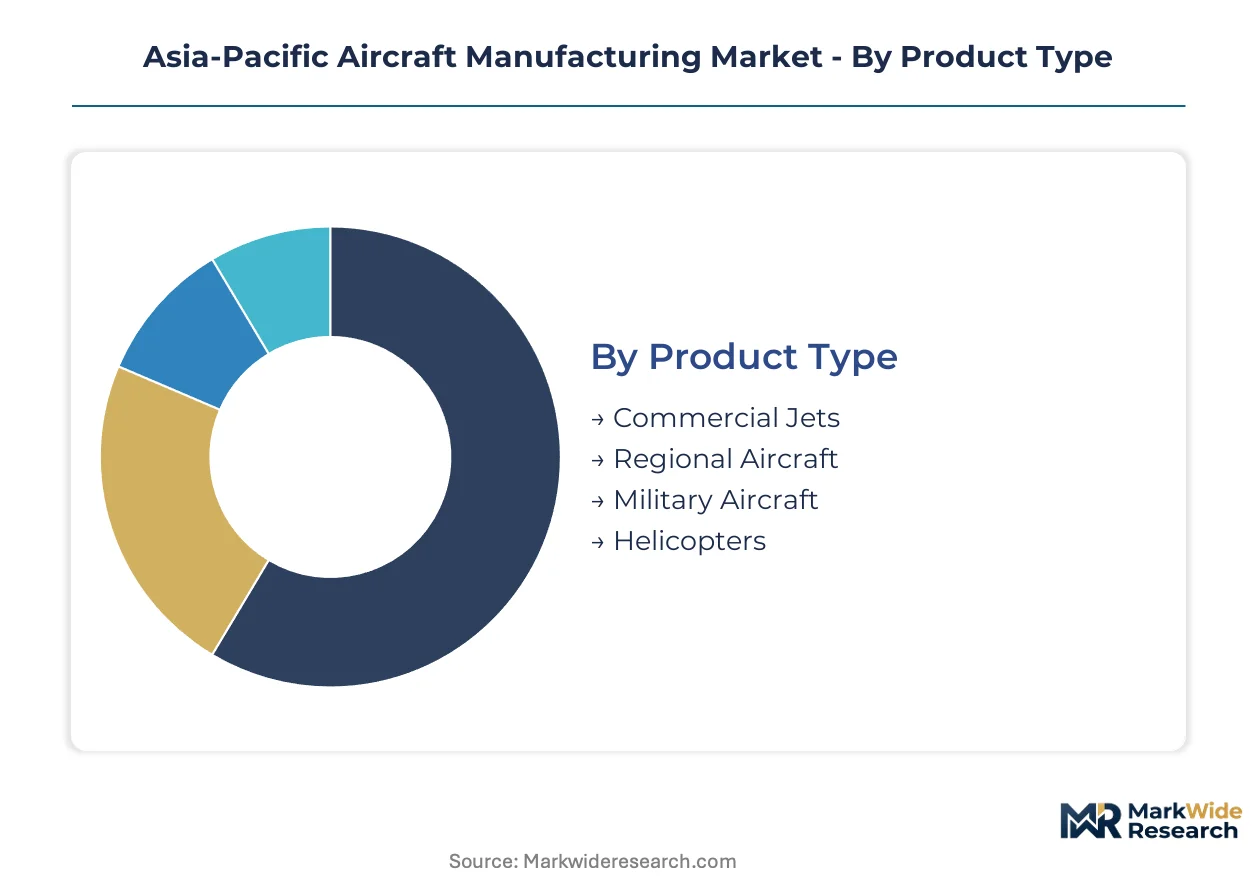
Segmentation in Asia-Pacific aircraft manufacturing reveals how supply chain specialization and regulatory pressure concentrate value capture. Buyers configure procurement around platform scale, technology maturity, and end-use certification requirements.
Product Type:
Supply concentration tilts toward platforms with multi-year order backlogs and captive engine ecosystems.
- Commercial Jets:Narrowbody and widebody platforms dominate assembly line utilization across COMAC facilities in Shanghai and Tianjin. China's MIIT fuel-efficiency mandates accelerate composite wing adoption for C919 derivatives serving domestic trunk routes.
- Military Aircraft:Indigenous fighter programs absorb titanium machining capacity at Hindustan Aeronautics Limited and Korea Aerospace Industries. India's DGFT import-licensing requirements extend avionics integration timelines for Tejas production blocks.
- Regional Aircraft:Turboprop and sub-70-seat jet platforms serve thin routes across Indonesia's archipelago and Australia's remote communities.
- Helicopters:Light and medium rotorcraft address offshore energy, emergency medical services, and military utility roles across Southeast Asian littoral zones.
Commercial Jets absorb the bulk of installed capacity; Military Aircraft is expanding most quickly.
Technology:
Cost tier differentiation separates qualified aerospace-grade suppliers from industrial-grade commodity producers.
- Composite Materials:Carbon-fiber reinforced polymers and epoxy resin systems reduce structural weight versus aluminum-lithium alternatives. Toray and Teijin precursor supply constraints create qualification bottlenecks for second-tier airframers in Vietnam and Malaysia.
- Advanced Manufacturing:Aluminum-lithium alloy extrusion and automated fiber placement command premium pricing for fatigue-critical wing and fuselage sections. China's Yangtze River Delta cluster anchors AVIC supplier development for C919 wing boxes.
- Automation:Robotic drilling and fastening systems reduce airframe assembly labor hours at Mitsubishi Heavy Industries and Kawasaki Heavy Industries facilities.
- 3D Printing:Additive-manufactured titanium brackets and ducting consolidate part counts for engine nacelles and auxiliary power units.
Composite Materials captures the highest margin tier; 3D Printing is gaining share fastest.
End User:
Customer type determines contract structure, with government programs favoring cost-plus development and airlines demanding fixed-price production.
- Airlines:Full-service and low-cost carriers in Indonesia, Vietnam, and the Philippines drive narrowbody fleet renewal. Southeast Asian budget operators unbundle power-by-the-hour contracts into discrete component-level service agreements.
- Government:Defense procurement sustains indigenous fighter, trainer, and helicopter programs through India's CEA production-linked incentives and Australia's F-35 final assembly facility.
- Private Operators:Corporate and business aviation demand concentrates in Australia's mining sector and Singapore's financial services hub.
- Cargo:E-commerce logistics growth drives converted freighter demand across China's domestic express networks.
Airlines command the dominant order volume; Government programs show the steepest expansion trajectory.
Application:
Application segmentation tracks how mission profile shapes airframe specification and certification pathway.
- Passenger Transport:Commercial and regional aircraft configurations prioritize fuel burn per seat-mile and turnaround efficiency. Low-cost carrier density layouts dominate Southeast Asian narrowbody deliveries.
- Military Operations:Combat, surveillance, and transport missions require hardened avionics and defensive systems integration. Australia's F-35 final assembly and check-out facility anchors regional sustainment capability.
- Freight Transport:Dedicated freighter and converted passenger-to-cargo platforms serve intra-Asia express networks and long-haul general cargo lanes.
- Training:Basic and advanced jet trainers address pilot pipeline requirements for air forces transitioning to fourth-generation fighter fleets.
Passenger Transport absorbs the bulk of installed capacity; Freight Transport is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in China's Yangtze River Delta while consumption spreads across Southeast Asian low-cost carrier networks. This geographic split shapes supplier location decisions and regulatory compliance architectures throughout the region.
China
COMAC and AVIC anchor the Yangtze River Delta cluster where C919 narrowbody assembly lines absorb composite wing structures from captive suppliers. MIIT dual carbon mandates enforce progressive fuel-efficiency improvements through GB standards that redesign nacelles and combustors simultaneously. Shanghai and Tianjin facilities reconfigure test rigs to capture dual compliance data for domestic certification.
India
Hindustan Aeronautics Limited drives indigenous fighter and helicopter production through captive engine and avionics capabilities at Bengaluru and Hyderabad facilities. CEA production-linked incentive schemes subsidize domestic component fabrication while DGFT import-licensing requirements extend avionics integration timelines. The Tejas program absorbs titanium machining capacity as production blocks scale.
Japan
Mitsubishi Heavy Industries and Kawasaki Heavy Industries maintain automated fiber placement and robotic drilling systems at Nagoya-area facilities. METI aligns certification timelines with FAA and EASA benchmarks to preserve export market access. Japanese consortia flight-test megawatt-class hybrid-electric systems for fifty-seat regional platforms under state-funded research programs.
South Korea
Korea Aerospace Industries competes in regional trainer and light-attack segments through technology partnerships with Western primes at Sacheon facilities. The country's aerospace supply base concentrates around Busan-Ulsan industrial corridors where composite precursor processing meets automated assembly requirements. Defense procurement sustains indigenous platform development alongside offset arrangements.
Australia
The F-35 final assembly and check-out facility at Williamtown anchors regional sustainment capability for fifth-generation fighter fleets. Government defense procurement prioritizes hardened avionics integration and through-life support contracts. Melbourne and Adelaide clusters develop maintenance capabilities that capture regional fleet growth without full manufacturing investment.
Asia-Pacific Aircraft Manufacturing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions in the Asia-Pacific Aircraft Manufacturing Market. State-backed vertical integration at COMAC and AVIC contrasts with technology-licensing models at Korea Aerospace Industries and partnership-dependent structures at Japanese heavy industrials. Strategic archetypes include captive-system integrators, licensed-technology assemblers, and component-tier specialists. Competitive moves concentrate on M&A for composite precursor supply and capacity expansion in automated fiber placement.
Among China-based state enterprises, Commercial Aircraft Corporation of China, Ltd. and Aviation Industry Corporation of China exemplify the captive-system integrator archetype through Yangtze River Delta supplier ecosystems. Hindustan Aeronautics Limited occupies a parallel position in India's defense-centric structure. Korea Aerospace Industries, Ltd. represents the licensed-technology model through Western prime partnerships that access regional trainer markets without full platform development burden.
| Leading Market Players |
|---|
| Commercial Aircraft Corporation of China, Ltd. |
| Aviation Industry Corporation of China |
| Hindustan Aeronautics Limited |
| Korea Aerospace Industries, Ltd. |
| Mitsubishi Heavy Industries |
| Kawasaki Heavy Industries |
| Subaru Corporation |
| ST Engineering Aerospace |
| Singapore Technologies Engineering Ltd. |
| Others |
Value Network & Pricing Analysis
Sponge titanium price volatility cascades through aerospace supply chains into three distinct pricing tiers for engine brackets and auxiliary power unit components, with China's Yangtze River Delta cluster absorbing input cost shocks through state-backed volume commitments while Southeast Asian second-tier airframers face spot-market exposure.
Pricing Analysis
Margin tightening in composite-intensive airframe tiers reflects Toray and Teijin precursor supply constraints that compress qualification windows for new entrants. Three-tier pricing structure across aerospace-grade, industrial-grade, and commodity-grade certification levels separates qualified suppliers from aspirants. Cost-down pressure on narrowbody programs accelerates as Indonesian and Vietnamese low-cost carriers unbundle power-by-the-hour contracts into discrete component purchases. Airlines in Southeast Asia exhibit highest price sensitivity, while defense procurement through India's CEA production-linked incentives demonstrates lowest sensitivity due to cost-plus contract structures.
Supply Chain Analysis
Refurbishment flows for carbon-fiber reinforced polymer structures concentrate in Melbourne and Adelaide MRO clusters, feeding repaired nacelle components back into Australia's F-35 sustainment network. Raw material sourcing draws from Japanese Toray facilities for aerospace-grade precursor, Chinese AVIC smelters for aluminum-lithium extrusions, and Russian sponge titanium processors for engine-grade inputs. Single-source vulnerability in aerospace-grade carbon fiber creates qualification bottlenecks for Vietnam and Malaysia airframers seeking C919 supplier tier entry. Distribution runs through Shanghai and Tianjin assembly hubs for COMAC platforms, with secondary nodes at Bengaluru and Hyderabad for India's Tejas production blocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Toray and Teijin's seventy-percent grip on aerospace-grade precursor supply props pricing power across composite-intensive programs, constraining second-tier airframer expansion regardless of order backlog depth.
For Market Incumbents: To counter emerging MRO providers in Vietnam's Da Nang and Ho Chi Minh City corridors, COMAC and AVIC should deepen backward integration into automated fiber placement capacity within the Yangtze River Delta cluster while accelerating MIIT dual carbon compliance certification for captive suppliers. Certification investment in bonded-structure NDT technician pipelines defends aftermarket lock-in against third-party shop fragmentation. For New Entrants and Emerging Players: Regional cargo operators in Indonesia's archipelago network represent an underserved buyer archetype requiring sub-70-seat turboprop platforms with unbundled maintenance contracts. White-space targets include hybrid-electric propulsion integration for fifty-seat regional jets and titanium additive manufacturing for engine bracket consolidation. Go-to-market positioning through technology licensing with Korea Aerospace Industries' Western prime partnerships reduces platform development burden. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated fiber placement specialists in Japan's Nagoya-area industrial corridor with METI-funded research program exposure. Long-term viability across the analysis window hinges on dual-use civil-military certification capabilities that preserve optionality through regulatory regime shifts. Watch for MIIT amendments to GB 36886-2018 standards as the inflection signal for composite airframe mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Precursor Supply Agreement | Long-term Toray or Teijin offtake secures qualification pathways for C919 derivative programs. |
| Automated Fiber Placement Capacity Expansion | Yangtze River Delta facility additions reduce wing box fabrication labor hours for AVIC suppliers. |
| Hybrid-Electric Propulsion Consortium | METI-funded Japanese flight-test programs capture fifty-seat regional platform architecture leadership. |
| MRO Capability Buildout in Vietnam | Da Nang and Ho Chi Minh City maintenance hubs capture narrowbody fleet growth without manufacturing investment. |
| Production-Linked Incentive Utilization | India's CEA schemes subsidize domestic titanium machining for Tejas and civil component programs. |
Research Methodology
Document review covered MIIT GB standard filings, COMAC and AVIC supplier qualification records, and Japan METI research program disclosures, complemented by interviews with airframe platform engineers, airline fleet procurement directors, MRO operations managers, and carbon fiber composite specialists. Secondary validation drew from aerospace trade customs data, FAA and EASA type certification databases, and defense procurement contract announcements. Bottom-up assembly line capacity assessments triangulated against top-down order backlog valuations.
Segment-level outputs across the projection horizon reflect platform type, technology tier, end-user contract structure, and application mission profile dimensions. CAGRs emerged from installed base depreciation curves married to order intake trajectories. Forecast inputs incorporated MIIT dual carbon mandate compliance timelines, DGFT import-licensing processing durations, and hybrid-electric propulsion technology readiness thresholds.
Revisions become necessary when MIIT amends GB fuel-efficiency standards beyond current composite airframe assumptions, when Russian sponge titanium supply disruptions extend beyond current contingency planning, or when India's PLI scheme eligibility criteria shift. Practitioners should monitor precursor qualification backlog lengths at Toray and Teijin, C919 production ramp rates at Shanghai and Tianjin, and METI consortium flight-test schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Aeronautic Propeller Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Europe Aircraft Engines Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Aircraft Band Clamps Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Middle-East and Africa Commercial Aircraft Market
Aircraft
Aeronautical Wind Tunnel Market
Aircraft
South Korea Aviation Market
Aircraft
India Aviation Market
Aircraft
Japan Aviation Market