
 Europe Attack Helicopter Market | 2026-2036
Europe Attack Helicopter Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Attack Helicopter Market Foresight
France is reconfiguring its attack helicopter industrial base through sustained investment in next-generation rotorcraft manufacturing. Airbus SE leverages integrated supply chains across Toulouse and Marignane to dominate European medium and heavy helicopter production. Leonardo S.p.A. anchors Italy's position through specialized avionics and weapon systems integration for domestic and export programs. Boeing competes selectively on NATO interoperability contracts while navigating European offset requirements.
An attack helicopter is a rotary-wing military aircraft engineered for close air support, anti-armor operations, and armed reconnaissance, typically featuring tandem crew seating, stub-wing hardpoints for guided missiles and cannon pods, and armor protection rated against small-arms fire up to 23mm. These platforms serve as maneuver force multipliers in combined-arms operations, delivering precision fires while operating below fixed-wing altitude envelopes. Medium Helicopters occupy the core revenue pool due to balanced payload-range profiles suited to European terrain and basing density. Weapon Systems within the Technology dimension command premium positioning as nations prioritize standoff missile integration and helmet-mounted cueing. The Manned operation mode retains structural dominance despite unmanned technology maturation, reflecting crewed situational judgment requirements in contested electromagnetic environments.
EMA certification standards and EU Defence Fund eligibility criteria shape product development roadmaps and market access conditions for non-European suppliers. REACH compliance on materials and the EU Green Deal's emerging sustainable aviation fuel mandates are pressuring engine and airframe manufacturers to adapt propulsion architectures. Military end users must weigh PESCO collaborative procurement against sovereign industrial retention as platform decisions unfold.
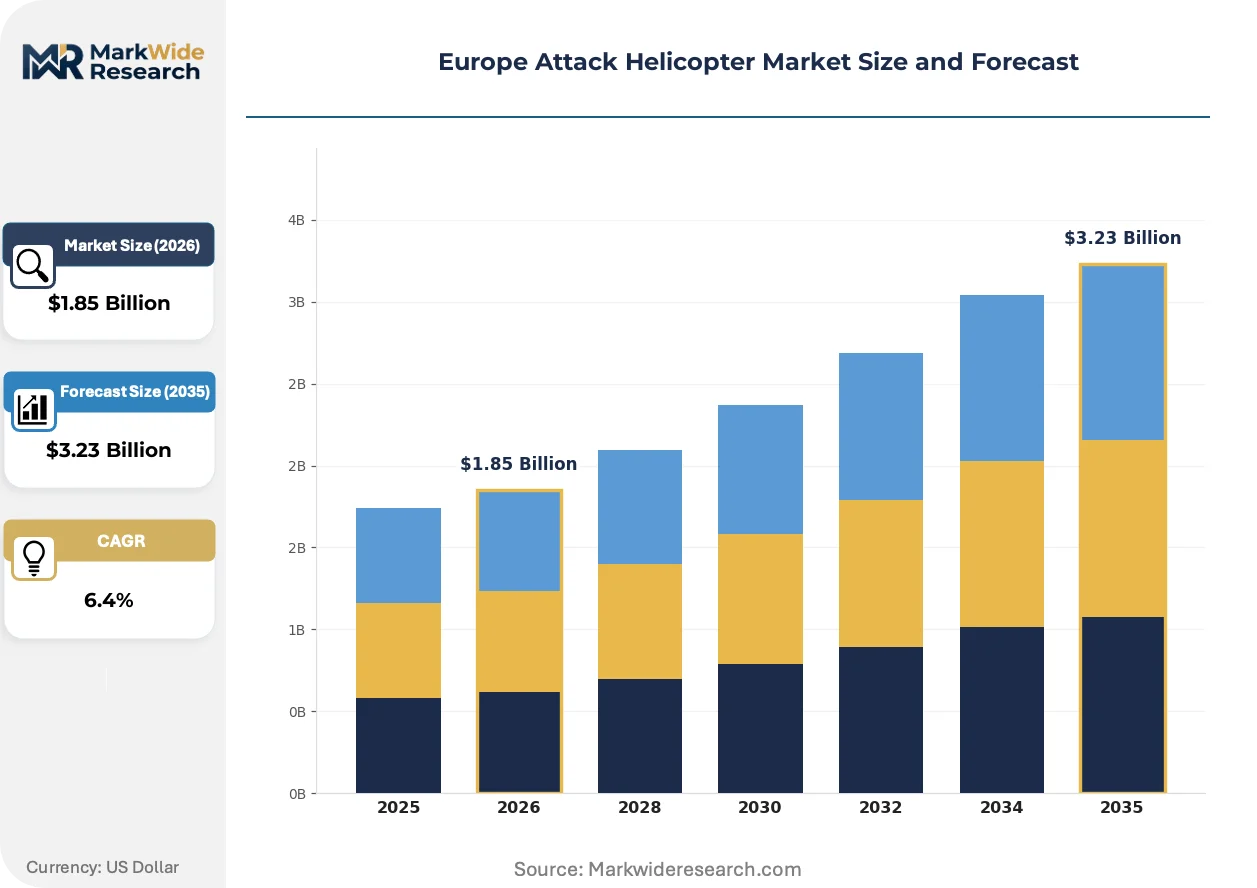
Market Dynamics
European attack helicopter procurement is bifurcating between sovereign fleet replacement and PESCO collaborative development, creating tension between national industrial retention and cross-border cost efficiency.
Growth Catalysts
- EU Defence Fund co-financing:Joint research and development subsidies reduce individual member state fiscal burden for next-generation rotorcraft programs.
- Poland's H225M Caracal procurement:Warsaw's accelerated modernization timeline establishes demand anchor for medium-lift attack helicopter variants across Eastern Europe.
- Helmet-mounted cueing systems:Integration of Thales TopOwl and Elbit DASH architectures enables precision standoff missile employment in degraded visual environments.
Market Restraints
- Turboshaft engine supply concentration:Safran and Rolls-Royce dominate European propulsion, creating single-source vulnerability for new platform certification.
- REACH compliance costs:ECHA restrictions on hexavalent chromium plating and cadmium coatings force airframe redesign and supply chain requalification.
- Unmanned combat aerial vehicle substitution:Turkish Bayraktar TB2 and indigenous European UCAV programs displace manned attack helicopter roles in permissive threat environments.
Strategic Opportunities
- Romania and Bulgaria fleet gaps:Both NATO members operate Soviet-era Mi-24/35 platforms requiring full replacement, creating near-term procurement windows.
- EU Green Deal sustainable aviation fuel mandates:Emerging SAF requirements for military aviation incentivize hybrid-electric propulsion demonstrators.
- Convergence of manned-unmanned teaming:Airbus and Leonardo development of optionally piloted architectures enables single-platform flexibility across mission profiles.
Industry Challenges
- Flight test engineer scarcity:Specialized rotorcraft handling qualities certification expertise concentrates at Marignane and Cascina Costa, creating recruitment bottlenecks.
- EMA military type certification timelines:Novel avionics architectures face multi-year validation cycles, compressing operational availability windows for replacement programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Attack Helicopter Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Helicopters, Medium Helicopters, Heavy Helicopters, Super Heavy Helicopters End User: Military, Government, Law Enforcement, Private Security Technology: Avionics Systems, Weapon Systems, Surveillance Systems, Communication Systems Operation Mode: Manned, Unmanned, Remote-Controlled, Hybrid |
| Companies Covered | Airbus SE, Leonardo S.p.A., The Boeing Company, Textron Inc., Rostec State Corporation, Lockheed Martin Corporation, Bell Helicopters, Russian Helicopters, Sikorsky-Lockheed Martin, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Attack Helicopter Market Shifts & Advancements
Attack helicopter development is pivoting toward modular open systems architectures that accelerate sensor and weapon integration without full platform recertification.
Fly-by-wire flight control systems with full authority digital engine control are rendering obsolete mechanical linkages and hydromechanical fuel control units in new European designs. Airbus Helicopters and Leonardo are incorporating active inceptor sidesticks in their latest medium-lift attack variants. This shift compresses development cycles for handling qualities upgrades while reducing airframe weight and maintenance burden.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing airframe manufacturers to eliminate legacy fire-resistant hydraulic fluids and non-stick coatings. The regulation's industrial consequence extends beyond materials substitution to full system requalification for transmission and rotor head components. French and German OEMs are responding with fluorine-free alternatives, though thermal performance gaps persist in high-load dynamic seals.
Defense ministries are consolidating maintenance, repair, and overhaul contracts under long-term availability agreements rather than transactional spares purchasing. This behavioral shift disrupts traditional component supplier relationships and transfers inventory risk to prime contractors. The United Kingdom's Ministry of Defence Apache Integrated Support and Enhancement program exemplifies this model, with similar structures emerging in Germany and Italy.
Europe Attack Helicopter Market Segmentation
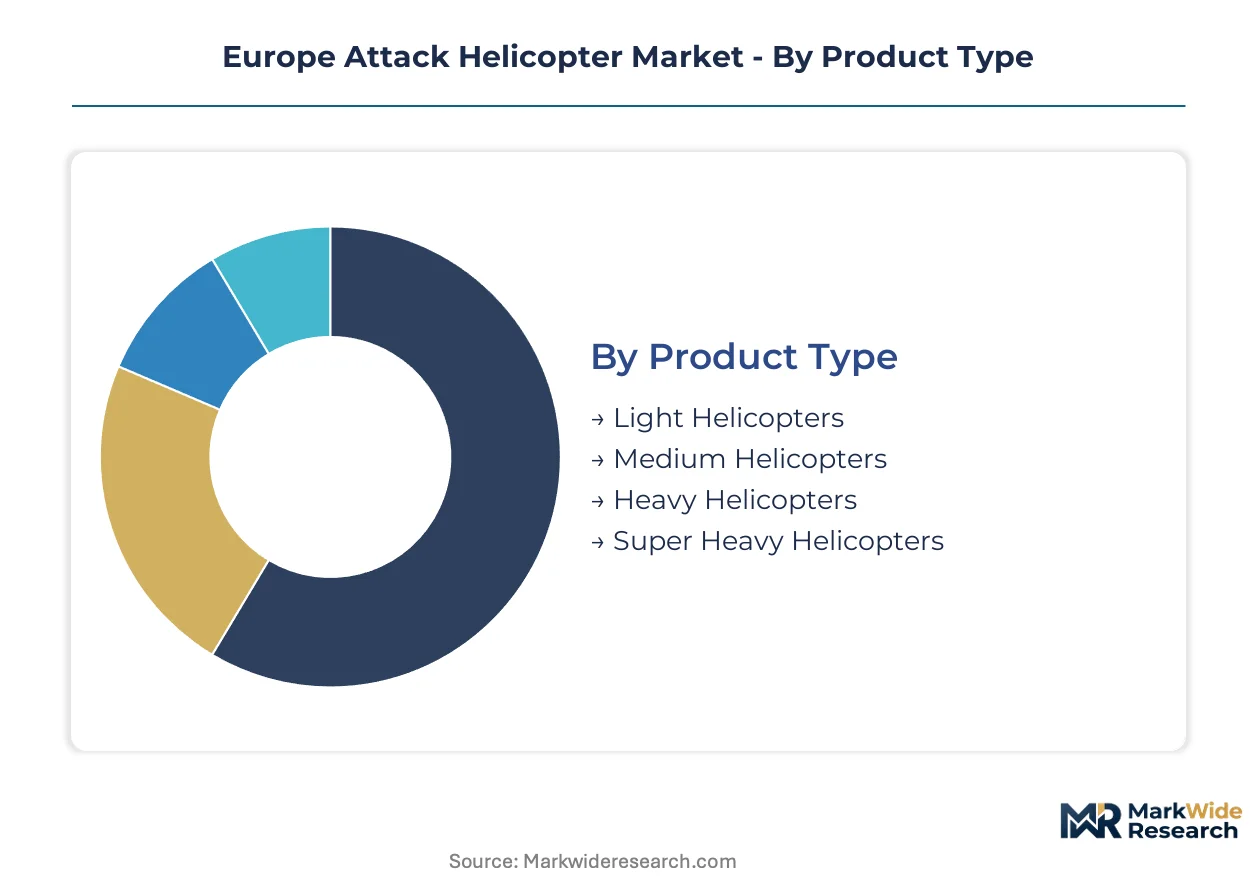
Attack helicopter procurement across Europe fragments along operational weight classes and mission architectures. National defense ministries prioritize segments that balance NATO interoperability with sovereign industrial participation.
Product Type:
Mature medium-lift platforms anchor current fleet structures while emerging heavy-lift variants attract next-generation investment.
- Medium Helicopters:Twin-engine rotorcraft with 4-6 ton payload capacity dominate NATO close air support missions. Poland's H225M Caracal procurement and Germany's Tiger fleet sustain demand concentration in Eastern and Central Europe. EMA certification timelines for new entrants compress procurement windows for proven airframes.
- Heavy Helicopters:8-12 ton platforms engineered for anti-armor saturation and armed escort roles. France's ongoing Tiger HAD upgrades and future FLRAA alignment efforts concentrate investment at Marignane. Turboshaft engine supply constraints from Safran limit production elasticity for new orders.
- Light Helicopters:Scout and reconnaissance platforms below 4 tons.
- Super Heavy Helicopters:Specialized transport-attack hybrid configurations exceeding 15 tons.
Medium Helicopters retain volume leadership; Heavy Helicopters hold the steepest expansion curve.
End User:
Customer concentration tilts toward state actors with sovereign certification authority over third-party operators.
- Military:National armed forces operating under NATO collective defense frameworks. Joint strike coordination requirements and PESCO collaborative procurement drive standardization around Airbus and Leonardo platforms. REACH compliance on materials adds qualification overhead for non-European suppliers seeking EDA contract eligibility.
- Law Enforcement:Border patrol and counter-terrorism units requiring armed overwatch capabilities. Italian Guardia di Finanza and Spanish Guardia Civil configurations establish reference architectures for Mediterranean surveillance missions. EUROSUR integration mandates accelerate cross-border interoperability investments.
- Government:Non-military state agencies with emergency response mandates.
- Private Security:Contractor-operated platforms for asset protection and critical infrastructure defense.
Military end users command procurement volume; Law Enforcement segments expand most quickly amid border militarization trends.
Technology:
Cost tiers separate integrated prime contractor systems from modular subsystem upgrades.
- Weapon Systems:Hardpoint-integrated missiles, cannon pods, and precision munitions. Thales Scorpion helmet-mounted cueing and MBDA Mistral integration dominate French and German platform specifications. Standoff range requirements in contested electromagnetic environments prioritize fire-and-forget architectures over line-of-sight systems.
- Avionics Systems:Glass cockpit architectures with digital mission computers. Leonardo's integrated avionics packages for the AW249 and Airbus Helionix suites establish dual-source competition for NATO upgrade programs. EASA-EMA harmonization on software assurance standards extends certification timelines for novel architectures.
- Surveillance Systems:Electro-optical and infrared sensor payloads.
- Communication Systems:Secure datalinks and NATO interoperability radios.
Weapon Systems retain volume leadership; Avionics Systems hold the steepest expansion curve.
Operation Mode:
Application requirements segment between crewed situational judgment and unmanned persistence missions.
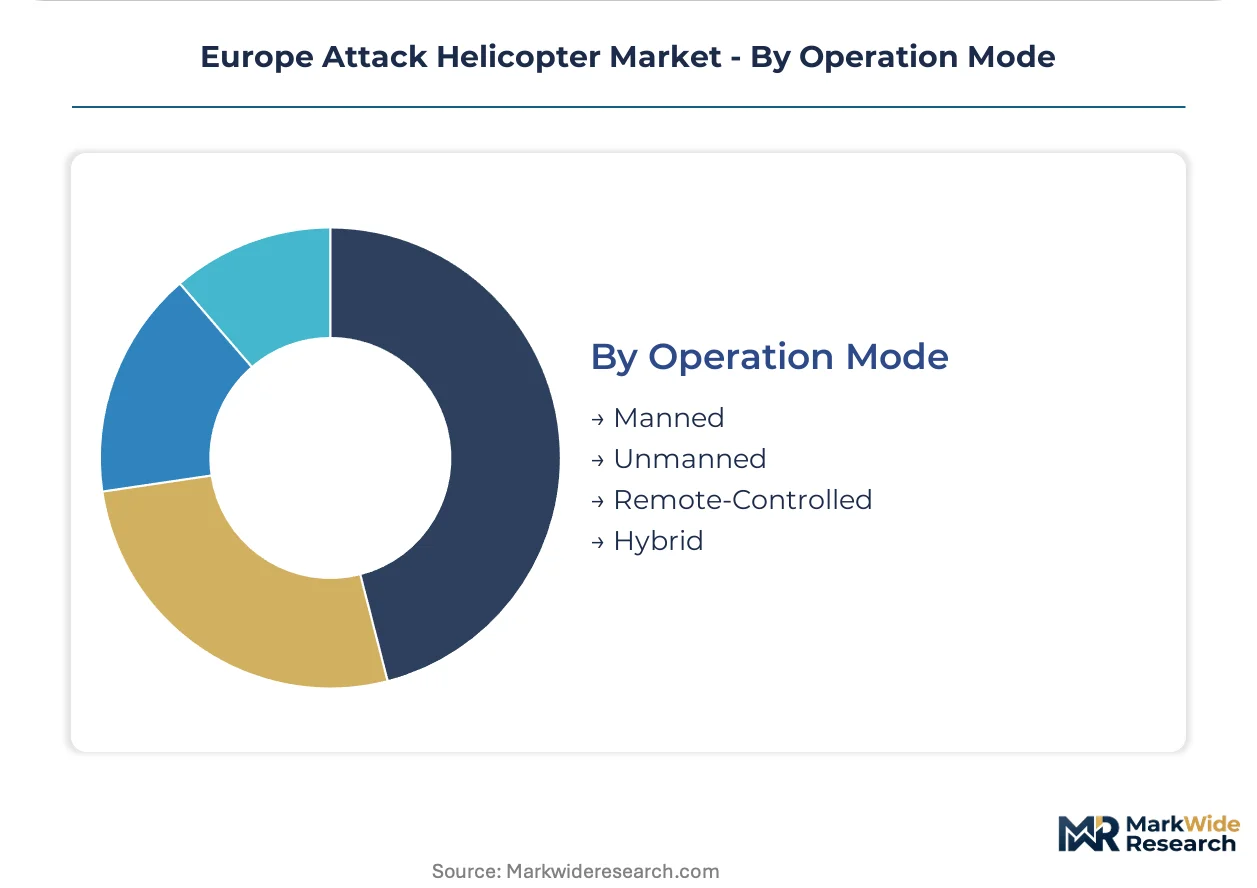
- Manned:Traditional tandem-crew configurations with pilot and weapons system operator. Crewed platforms retain structural dominance across European procurement, reflecting electromagnetic contested environment operations where autonomous decision-making remains restricted. Airbus and Leonardo production lines at Marignane and Cascina Costa concentrate handling qualities certification expertise for piloted architectures.
- Unmanned:Fully autonomous rotary-wing platforms without onboard crew. Turkish Bayraktar TB2 displacement of attack helicopter roles in permissive environments constrains European investment, though PESCO collaborative programs explore loyal wingman concepts. EDA-funded projects examine manned-unmanned teaming rather than full substitution.
- Remote-Controlled:Line-of-sight or satellite-linked operator control.
- Hybrid:Optionally piloted architectures enabling mode transition.
Manned operation retains volume leadership; Hybrid configurations hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor underpins Central European logistics networks that sustain rotorcraft component distribution. NATO's integrated air defense system links command nodes across member states. Cross-border maintenance agreements reduce fleet downtime for multinational operations.
Poland
Warsaw's accelerated H225M Caracal procurement establishes Eastern Europe's largest attack helicopter fleet renewal. The Polish Ministry of National Defence channels EU Defence Fund co-financing into domestic offset requirements for Airbus assembly work. Świdnik's aviation cluster hosts final integration lines for medium-lift variants serving regional export demand.
Germany
Berlin's Tiger fleet sustainment and future FLRAA alignment concentrate investment in heavy-lift attack capabilities. The Bundeswehr navigates PESCO collaborative procurement against sovereign industrial retention mandates for engine and avionics production. Donauwörth's Airbus Helicopters facility anchors handling qualities certification expertise for NATO interoperability standards.
France
Paris sustains next-generation rotorcraft manufacturing through sustained Tiger HAD upgrades and future combat air system integration. The Direction Générale de l'Armement enforces EMA military type certification timelines that compress operational availability windows. Marignane's integrated supply chains dominate European medium and heavy helicopter production for domestic and export programs.
Italy
Rome prioritizes AW249 development to replace aging A129 Mangusta fleets with domestically integrated avionics architectures. Leonardo's specialized weapon systems integration programs leverage PESCO frameworks for cross-border subsystem standardization. Cascina Costa's production lines concentrate electro-optical sensor payload manufacturing for Mediterranean surveillance missions.
United Kingdom
London's Apache Integrated Support and Enhancement program consolidates maintenance contracts under long-term availability agreements rather than transactional spares purchasing. The Ministry of Defence balances EMA certification alignment with sovereign flight test engineering capacity at Yeovilton. British Army Aviation regiments coordinate NATO interoperability standards through joint training exercises with European partners.
Europe Attack Helicopter Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in propulsion, avionics, and precision munitions. The European attack helicopter market consolidates around state-affiliated primes with captive certification authority and transatlantic OEMs navigating offset requirements. Two strategic archetypes dominate: full-spectrum integrators with EMA design organization approval, and subsystem houses supplying sensor and weapon packages across multiple airframes. Competitive moves concentrate on long-term availability contracting and collaborative PESCO program bidding.
Within the full-spectrum integrator tier, Airbus SE and Leonardo S.p.A. occupy positions defined by EMA certification holdings and sovereign supply chain integration. The Boeing Company represents the transatlantic archetype competing selectively on NATO interoperability contracts. These three anchors illustrate how geographic origin and regulatory access shape competitive positioning more than product differentiation alone.
| Leading Market Players |
|---|
| Airbus SE |
| Leonardo S.p.A. |
| The Boeing Company |
| Textron Inc. |
| Rostec State Corporation |
| Lockheed Martin Corporation |
| Bell Helicopters |
| Russian Helicopters |
| Sikorsky-Lockheed Martin |
| Others |
Supply & Pricing Matrix
Safran and Rolls-Royce turboshaft engine manufacturing concentrates in France and the United Kingdom, anchoring margin capture at the propulsion tier while airframe integrators absorb REACH compliance and certification cost inflation downstream.
Pricing Analysis
REACH Annex XVII and EMA military type certification dictate the pricing tier structure across European attack helicopter procurement. Three-tier pricing structure across premium, standard, and economy levels separates full-spectrum integrators with EMA design organization approval from subsystem suppliers and offset-compliant foreign OEMs. Price differentiation rests on certification tier and sovereign industrial participation depth. Cost compression in the standard tier is intensifying because PESCO collaborative procurement pools demand across member states. Law enforcement agencies exhibit highest price sensitivity due to constrained domestic budgets, while military end users prioritize operational availability over unit cost.
Supply Chain Analysis
Airbus Helicopters at Marignane and Leonardo at Cascina Costa hold final assembly and flight test capacity for European attack helicopter production. Component manufacturing draws from France, Germany, and Italy for avionics and weapon systems, with Poland emerging as an Eastern European integration hub. Raw material dependencies center on titanium alloys for rotor heads, composite prepregs for airframes, and rare earth elements for electro-optical sensors. Single-source vulnerability in turboshaft engine supply from Safran creates certification bottleneck risk. Distribution runs through national procurement agencies and EDA collaborative frameworks rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European attack helicopter procurement is entering a cyclical recovery phase driven by NATO collective defense spending acceleration and Tiger fleet replacement timelines across member states.
For Market Incumbents: Pre-empt Turkish UCAV displacement by accelerating optionally piloted architecture development at Airbus and Leonardo. Capture long-term availability contracting momentum through inventory risk absorption. Deepen backward integration into helmet-mounted cueing systems to offset Thales and Elbit margin capture. Defend against PESCO collaborative procurement fragmentation by anchoring cross-border maintenance agreements. For New Entrants and Emerging Players: Romanian and Bulgarian Mi-24/35 replacement windows represent the most penetrable entry point for non-European suppliers willing to navigate EDA offset requirements. PESCO subsystem standardization programs offer white-space entry for specialized avionics and sensor houses lacking EMA certification. Target law enforcement border surveillance configurations as a lower-certification-threshold beachhead. Pursue joint venture structures with Polish Świdnik cluster partners to satisfy domestic content mandates. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed aerospace component suppliers holding EMA-approved manufacturing organization certificates. Long-term viability across a five-to-ten-year window favors targets with locked PESCO program participation and sovereign flight test engineering capacity. Monitor EU Defence Fund co-financing allocation announcements as the primary inflection signal for procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Term Availability Contracting | Transfers inventory risk to Airbus and Leonardo while locking in Polish and German fleet sustainment revenue. |
| EMA Design Organization Investment | Accelerates certification timelines for novel avionics architectures at Marignane and Cascina Costa facilities. |
| PESCO Collaborative Program Bidding | Pools R&D subsidies across France, Germany, and Italy while preserving national industrial participation quotas. |
| Optionally Piloted Architecture Development | Enables Airbus and Leonardo to compete against Turkish UCAV substitution in permissive threat environments. |
| REACH-Compliant Materials Substitution | Forces fluorine-free hydraulic fluid requalification at Safran and Rolls-Royce propulsion suppliers. |
Research Methodology
The analysis maps medium-lift attack helicopter procurement, heavy-lift platform development, weapon systems integration, and avionics certification pathways, each validated through program managers at national defense ministries, procurement officers at the European Defence Agency, supply chain directors at Airbus and Leonardo, and flight test engineers at Marignane and Cascina Costa. Primary interview findings triangulate against EDA collaborative procurement databases, EMA military type certification records, EU Defence Fund allocation disclosures, and NATO standardization agreement documentation. Bottom-up fleet replacement timelines across Poland, Germany, France, Italy, and the United Kingdom reconcile with top-down defense spending projections.
The analytical framework holds fixed NATO collective defense commitment levels and EU Green Deal sustainable aviation fuel mandate timelines while varying PESCO program participation intensity and turboshaft engine supply elasticity across the projection horizon. Segmentation dimensions modeled include operational weight class, end-user sovereignty tier, technology subsystem category, and operation mode architecture. CAGRs derive from fleet age profiles, replacement cycle acceleration, and co-financing availability rather than extrapolated historical trends. Industry-specific forecast inputs incorporate EMA certification backlog estimates and REACH compliance cost pass-through assumptions.
Practitioners should monitor Turkish UCAV export penetration rates, EU Defence Fund co-financing allocation shifts, and EMA certification timeline extensions for early signals of demand displacement or procurement acceleration. Forecasts reflect assumptions regarding NATO interoperability standard maintenance and sovereign industrial retention policy continuity. Quarterly review of PESCO collaborative program announcements and EDA contract award disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Docking System Market
Aircraft
Japan Aviation Market
Aircraft
Heavy-Lift Helicopter Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Airplane and Helicopter Hangar Doors Market
Aircraft
Airplane Landing Gear Market
Aircraft
Two-Seater Ultralight Helicopters Market
Aircraft
Aircraft Pushback Tugs Market
Aircraft
Aircraft Autopilot System Market
Aircraft
Crashworthy Aircraft Seats Market
Aircraft
Aircraft Wheels Market
Aircraft
Aircraft Landing Gear Market
Aircraft
Commercial Helicopter Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
Special Mission Aircraft Market