
 North America Aircraft Band Clamps Market | 2026-2036
North America Aircraft Band Clamps Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aircraft Band Clamps Market Insights
The gap between premium aerospace-grade band clamps and commodity hardware is realigning procurement strategies across the supply chain. TransDigm Group leverages its vertically integrated manufacturing footprint to sustain margin advantages in high-specification clamp assemblies. Eaton Corporation anchors its position through channel control with major airframers, while Voss Industries specializes in corrosion-resistant alloys for naval aviation applications.
Aircraft band clamps are metallic or composite fastening devices designed to secure hoses, ducts, and wiring bundles within airframe structures, typically manufactured through precision stamping, roll-forming, and heat-treating processes to meet tensile strength and vibration-resistance specifications. Stainless steel variants dominate installed base volumes due to fatigue durability under thermal cycling, though carbon fiber and composite materials are gaining traction in next-generation airframe weight-reduction programs. Commercial aviation end users represent the deepest margin pool given fleet renewal cycles, while MRO providers constitute the fastest-growing installation type segment as aging aircraft extend service lives.
FAA airworthiness directives and SAE International fastener standards collectively shape product certification requirements and OEM qualification pathways in this market. The U.S. Department of Defense MIL-SPEC framework imposes additional material traceability and testing protocols for military aerospace applications. Stakeholders must monitor evolving EPA regulations on chrome plating processes and emerging NTSB safety recommendations affecting clamp retention in critical systems.
Market Dynamics
Fleet renewal timelines across United States and Canadian commercial aviation are compressing procurement cycles for airframe fasteners. FAA airworthiness directives now mandate more frequent clamp replacement intervals in critical systems, forcing MRO providers to hold larger safety stocks and OEMs to accelerate qualification programs for next-generation hardware.
Growth Catalysts
- Commercial Aviation Fleet Expansion:United States-based carriers are adding narrow-body aircraft at rates not seen since 2019, expanding installed base volumes for band clamp assemblies in fuel and hydraulic line applications.
- FAA Airworthiness Directives:Recent safety mandates targeting engine nacelle and pylon clamp retention are triggering replacement waves across aging Boeing 737NG and Airbus A320ceo fleets operated by North American carriers.
- Composite Material Adoption:Carbon fiber-reinforced polymer clamps are penetrating next-generation airframe programs, offering weight reductions that translate directly to fuel efficiency gains for operators.
Market Restraints
- Nickel Alloy Price Volatility:Inconel and other high-temperature alloys essential for engine-zone applications face supply constraints from concentrated mining operations, squeezing margins on aerospace-grade clamp production.
- OEM Qualification Barriers:Boeing and Airbus supplier approval processes demand 18-36 month validation cycles, freezing out smaller stampers lacking capital for testing infrastructure and SAE International certification compliance.
- SAE Fastener Standard Stringency:Evolving tensile and fatigue specifications under AS 21919 and related standards require continuous metallurgical process upgrades, favoring capital-rich incumbents over mid-tier competitors.
Strategic Opportunities
- Canadian Naval Aviation Modernization:Royal Canadian Air Force maritime patrol and search-and-rescue fleet upgrades present untapped demand for corrosion-resistant clamp assemblies in salt-spray environments.
- Additive Manufacturing Convergence:Hybrid production combining precision stamping with selective laser melting enables complex geometries for integrated clamp-bracket assemblies, reducing part counts in duct routing.
- MRO Channel Expansion:Third-party maintenance providers in Texas and Arizona are consolidating purchasing power, creating direct sourcing opportunities that bypass traditional distributor markups.
Industry Challenges
- Specialized Welding Certification:Aerospace-grade TIG and laser welding for clamp band joints requires AWS D17.1 qualified technicians, a skill pool concentrated among retiring workers in the U.S. Southwest manufacturing corridor.
- Dual-Use Export Control Complexity:ITAR and EAR regulations governing clamp shipments with military applications create compliance overhead that delays response times to commercial inquiries from Mexican and Caribbean MRO facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aircraft Band Clamps Market |
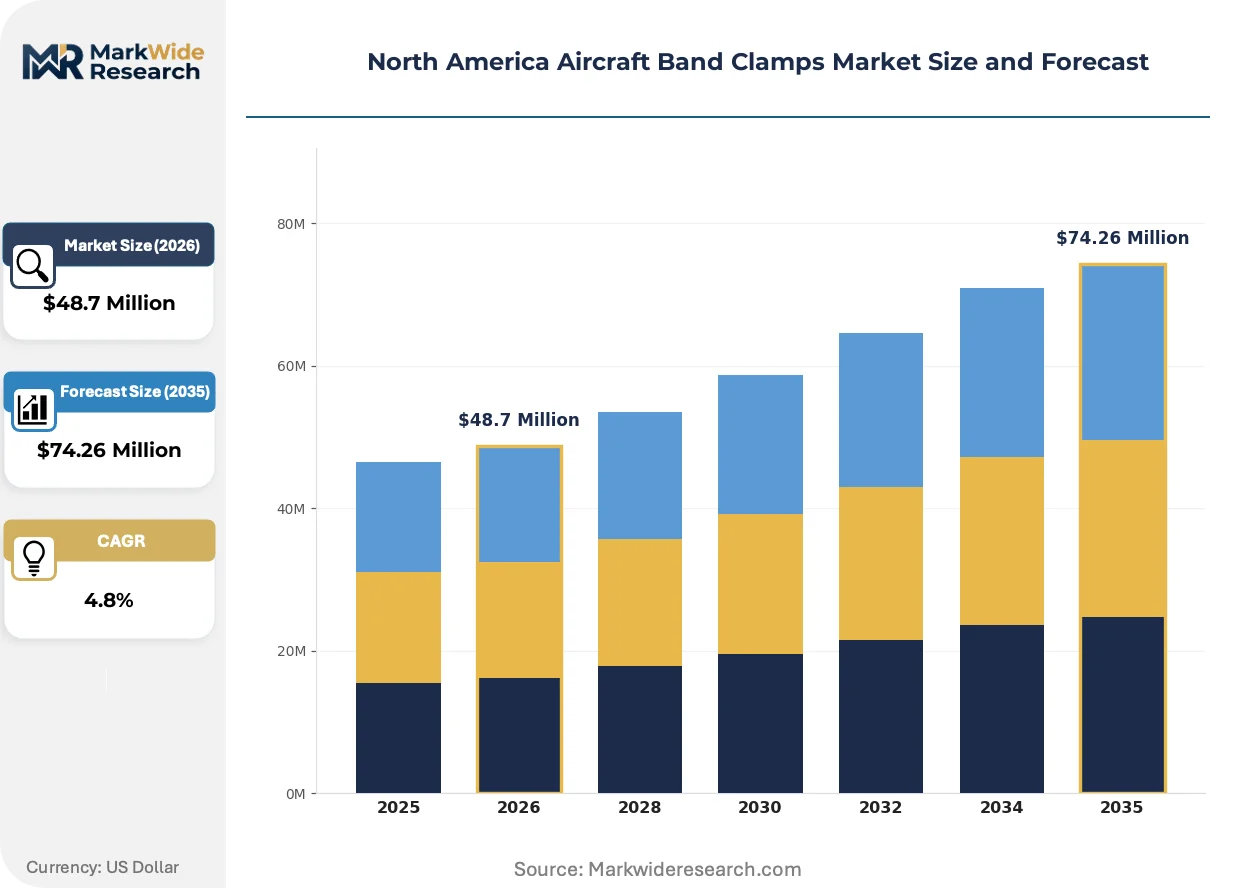
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $74.26 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Band, Double Band, Adjustable, Fixed Material: Stainless Steel, Aluminum, Carbon Fiber, Composite End User: Commercial Aviation, Military Aerospace, MRO Providers, OEMs Installation Type: Permanent, Temporary, Repair, Replacement |
| Companies Covered | TransDigm Group, Eaton Corporation, Voss Industries, Caillau, Teconnex Ltd, Ho-Ho Kus, J&M Products, National Utilities, Pacmet Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aircraft Band Clamps Market Trends and Innovations
Digital thread integration across design-to-manufacturing workflows is compressing development timelines for next-generation clamp assemblies. Smart factory investments by tier-one suppliers are reshaping quality assurance protocols and traceability requirements.
Automated optical inspection systems are automating defect detection in roll-formed band edges and heat-treated spring segments. Tier-one suppliers in Wichita and Montreal are deploying these systems at 100% inspection rates, replacing manual sampling protocols. The technology is automating throughput scaling without proportional labor expansion, tightening tolerance bands below 0.001 inch on critical dimensions.
EPA regulations on hexavalent chrome plating processes are forcing conversion to trivalent chromium or zinc-nickel alternatives for corrosion protection. Surface treatment houses serving the aerospace supply chain face capital equipment replacement cycles of 24-36 months. Clamps destined for engine nacelle applications in United States-assembled aircraft are most affected, with OEMs now requiring process validation data prior to source approval.
Consolidated procurement platforms operated by major airline groups are displacing fragmented distributor relationships. United, Delta, and American Airlines have centralized fastener purchasing through integrated supply agreements, squeezing independent distributors and favoring direct OEM relationships. The shift is most visible in high-volume consumable categories including standard-duty hose clamps for line maintenance operations.
North America Aircraft Band Clamps Market Segmentation
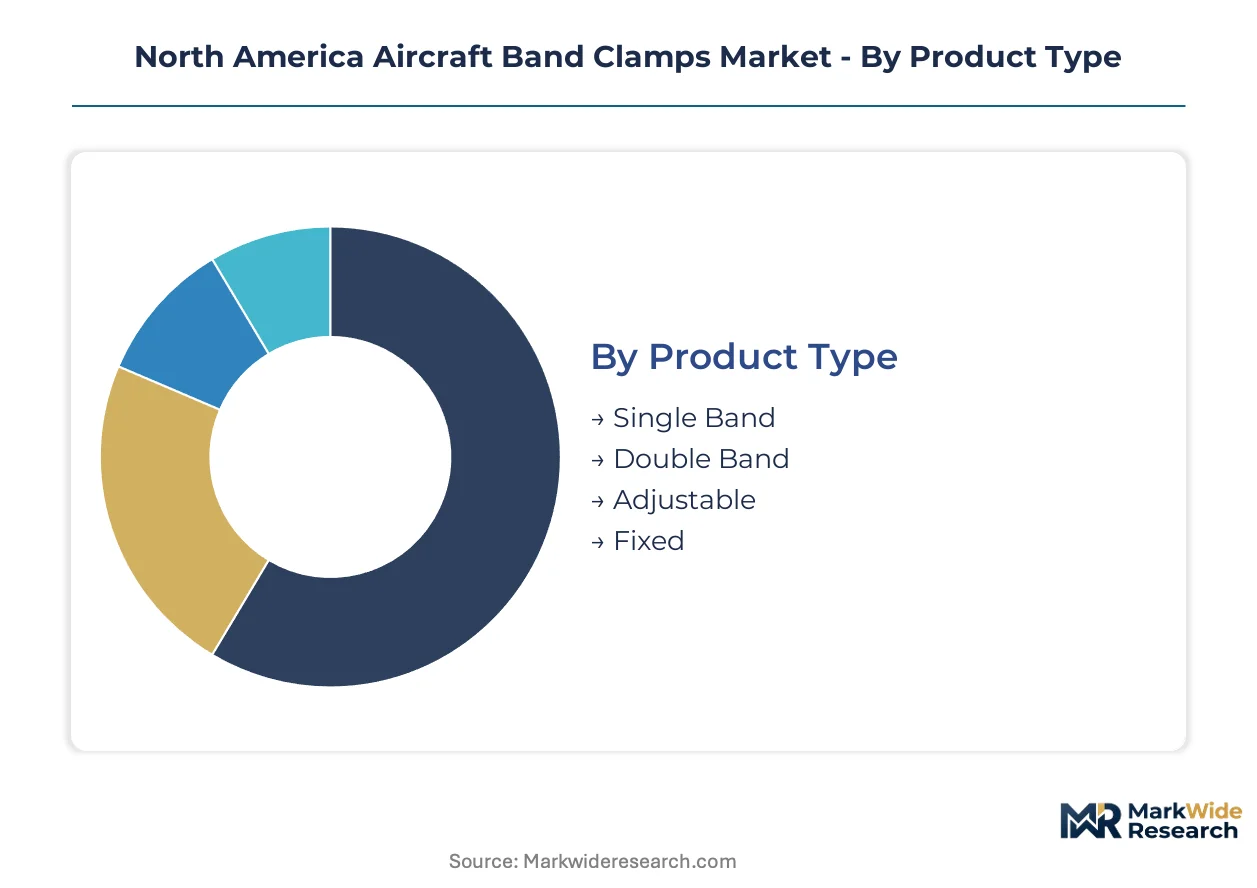
Aircraft band clamp procurement varies sharply across performance tiers and operational contexts. Specification-grade hardware for engine zones commands qualification rigor that commodity line maintenance clamps bypass entirely. Understanding where customization ends and standardization begins clarifies margin distribution across the supply chain.
Product Type:
Standardization dominates high-volume fuel and hydraulic line applications, while customized geometries secure specialized duct routing in next-generation airframes.
- Single Band:Simple circumferential clamp design with uniform pressure distribution for straight hose runs. Demand concentrates in Boeing 737 MAX and Airbus A320neo fuel system retrofits across Southwest U.S. MRO facilities, where FAA airworthiness directives mandate replacement intervals.
- Double Band:Dual-strap configuration distributing clamping force across wider surface areas for large-diameter ducts. Commercial aviation engine nacelle applications in Texas and Arizona assembly corridors drive specification, with SAE AS 21919 fatigue requirements forcing metallurgical upgrades.
- Adjustable:Screw-mechanism designs accommodating diameter variation in field repair scenarios. MRO providers in Montreal and Toronto stock these for line maintenance flexibility.
- Fixed:Pre-sized bands for original equipment installation with no field adjustability. OEM assembly lines in Wichita and Montreal specify these for initial airframe builds.
Leading the category by volume: Single Band. Growing fastest: Double Band.
Material:
Cost tiers separate commodity stainless from premium alloys and emerging composites, with thermal performance requirements dictating selection boundaries.
- Stainless Steel:Austenitic grades 304 and 316 dominate installed base volumes due to corrosion resistance and fatigue durability under thermal cycling. Commercial fleet maintenance across U.S. Southwest corridors consumes the majority, with EPA hexavalent chrome regulations now forcing surface treatment conversions.
- Aluminum:Lightweight alternative for non-engine zones where temperature exposure remains below 150°C. Regional jet programs in Canada specify these for secondary systems.
- Carbon Fiber:Reinforced polymer construction delivering 40-60% weight reduction versus metallic equivalents. Boeing 787 and Airbus A350 programs in Washington and South Carolina drive qualification, with fuel efficiency gains justifying premium positioning.
- Composite:Hybrid material systems combining fiber reinforcement with thermoplastic matrices. Next-generation narrow-body development programs evaluate these for integrated clamp-bracket assemblies.
Stainless steel commands volume leadership. Carbon fiber expands most quickly as airframe weight reduction accelerates.
End User:
Customer type determines procurement channel, with consolidated airline purchasing displacing fragmented distributor relationships in high-volume segments.
- Commercial Aviation:Fleet operators including United, Delta, and American Airlines driving consumable demand through integrated supply agreements. Direct OEM relationships now bypass traditional distribution for standard-duty hose clamps.
- Military Aerospace:U.S. Department of Defense and Royal Canadian Air Force procurement under MIL-SPEC frameworks with enhanced material traceability. Naval aviation applications in salt-spray environments demand corrosion-resistant alloys.
- MRO Providers:Third-party maintenance facilities in Texas and Arizona consolidating purchasing power. These operators represent the steepest expansion trajectory as aging aircraft extend service lives.
- OEMs:Boeing, Airbus, and Bombardier assembly operations with 18-36 month supplier qualification cycles. Wichita and Montreal manufacturing corridors concentrate demand.
Commercial aviation holds volume dominance. MRO providers gain share fastest.
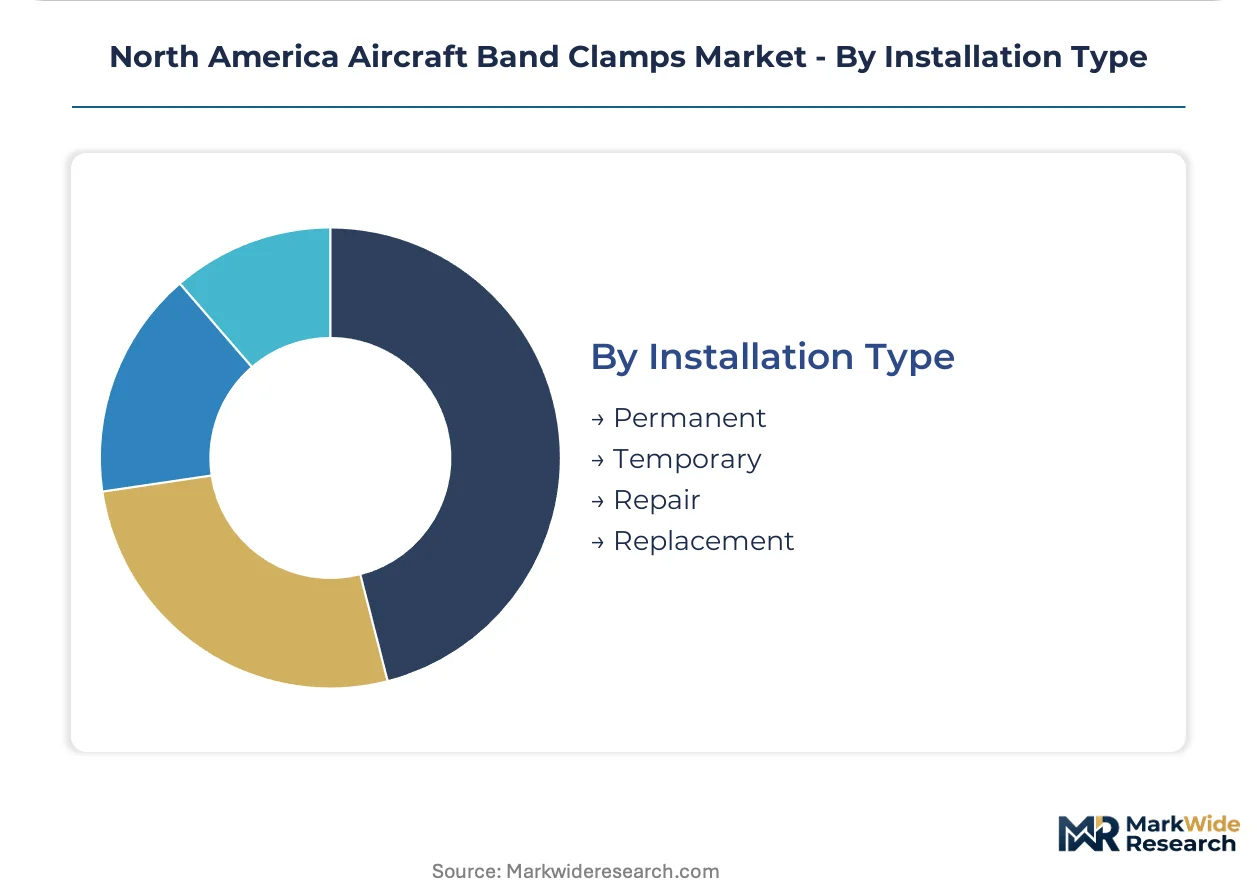
Installation Type:
Application maturity separates permanent factory installations from temporary field repairs, with replacement cycles accelerating under regulatory pressure.
- Permanent:Factory-installed clamps designed for airframe service life without scheduled replacement. OEM assembly lines in the U.S. Southwest specify these with full traceability documentation.
- Temporary:Field-installable solutions for maintenance deferrals or ferry flight authorizations. Line maintenance operations at Dallas-Fort Worth and Phoenix Sky Harbor utilize these under FAA minimum equipment list protocols.
- Repair:Clamp assemblies restoring function to damaged duct or hose retention systems. Canadian search-and-rescue fleet operators in Victoria and Halifax drive demand for corrosion-resistant variants.
- Replacement:Scheduled component changeouts driven by airworthiness directive compliance. Recent FAA mandates targeting engine nacelle clamp retention trigger waves across aging 737NG and A320ceo fleets.
Permanent installation leads by volume. Replacement activity climbs fastest on regulatory mandate acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wichita, Kansas anchors North American aircraft band clamp demand through its dense concentration of Boeing, Spirit AeroSystems, and Bombardier assembly operations. The U.S. Southwest manufacturing corridor stretching from Dallas-Fort Worth to Phoenix generates the majority of procurement volume for precision fastening hardware.
United States
Commercial fleet expansion at American Airlines, Delta, and United drives consumable demand through centralized supply agreements. FAA airworthiness directives mandating clamp replacement in engine nacelle systems trigger compliance waves across aging 737NG and A320ceo fleets. Texas and Arizona MRO facilities in Dallas-Fort Worth and Phoenix consolidate purchasing power for line maintenance operations.
Canada
Royal Canadian Air Force maritime patrol and search-and-rescue fleet modernization creates demand for corrosion-resistant alloys in salt-spray environments. Transport Canada certification requirements align with evolving SAE International fastener standards for cross-border supply chain integration. Montreal and Toronto aerospace clusters concentrate OEM assembly and tier-one supplier operations for Bombardier programs.
Mexico
Querétaro and Baja California manufacturing corridors attract aerospace supplier investments seeking proximity to U.S. Southwest assembly operations. Mexican MRO facilities face ITAR and EAR compliance complexity that delays response times for dual-use clamp shipments. Guadalajara and Monterrey industrial zones develop specialized surface treatment capabilities for trivalent chromium conversion.
North America Aircraft Band Clamps Market Competitive Landscape
Premium-margin players sit above commodity-margin players across qualification rigor and material specification tiers. The vendor base stratifies into capital-rich incumbents with 18-36 month OEM approval cycles, mid-tier stampers serving MRO channels, and specialized corrosion-resistant alloy fabricators. Dominant competitive moves include backward integration into captive heat-treating capacity and strategic partnerships with consolidated airline procurement platforms.
Within the vertically integrated tier, TransDigm Group and Eaton Corporation occupy positions sustained through channel control and manufacturing footprint advantages. Voss Industries exemplifies the specialization archetype, anchoring naval aviation applications where material traceability requirements under MIL-SPEC frameworks create qualification barriers. These three entities represent distinct competitive vectors: scale-driven consolidation, distribution dominance, and application-specific engineering depth.
| Leading Market Players |
|---|
| TransDigm Group |
| Eaton Corporation |
| Voss Industries |
| Caillau |
| Teconnex Ltd |
| Ho-Ho Kus |
| J&M Products |
| National Utilities |
| Pacmet Aerospace |
| Others |
Pricing and Supply Chain Analysis
AWS D17.1 qualified TIG welders concentrated in the U.S. Southwest manufacturing corridor command wage premiums that widen spreads between aerospace-grade and commodity clamp tiers. Labor-cost differentials between certified aerospace technicians and general metalworkers translate directly into three-tier pricing stratification across SAE-certified, commercial-grade, and generic hardware categories.
Pricing Analysis
Clamping-force retention guarantees in engine nacelle applications anchor value-based pricing at the premium tier, with OEMs paying for failure-mode mitigation rather than raw material weight. Three-tier pricing structure across premium, standard, and economy levels separates SAE AS 21919-certified engine-zone hardware from commercial fleet maintenance clamps and generic line-replacement units. Price differentiation hinges on metallurgical certification depth and captive heat-treating capacity, with cost compression in the standard tier intensifying as consolidated airline procurement platforms squeeze distributor markups. MRO providers in Texas and Arizona exhibit highest price sensitivity due to inventory velocity pressures, while OEM assembly lines in Wichita and Montreal demonstrate lowest sensitivity given qualification switching costs.
Supply Chain Analysis
AWS D17.1 certified welders and SAE-qualified metallurgists cluster in the U.S. Southwest, Montreal aerospace corridors, and Querétaro supplier parks, creating workforce chokepoints that constrain throughput scaling. Supply concentrates in the United States, Canada, and Mexico under USMCA framework, with raw material dependencies on Inconel and austenitic stainless grades from domestic mills and nickel alloy feedstock from concentrated mining operations. Single-source vulnerability runs through heat-treating houses serving FAA-certified clamp producers, where capacity constraints delay qualification timelines. Distribution runs through consolidated airline procurement platforms and tier-one supplier direct relationships, bypassing traditional fastener distributors in high-volume consumable categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
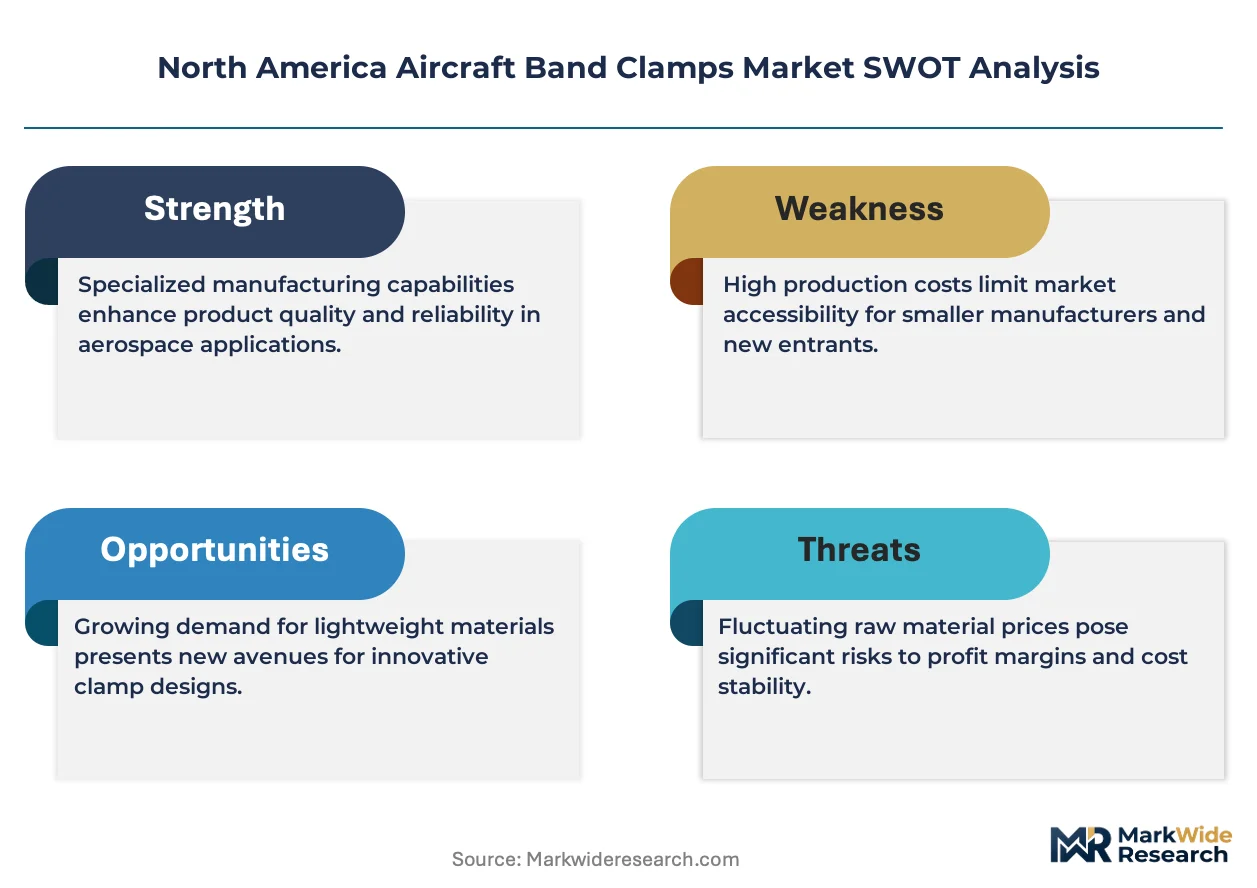
This market is consolidating around capital-rich incumbents capable of absorbing 18-36 month OEM qualification cycles, with SAE standard stringency forcing mid-tier stampers toward distressed exit or acquisition.
For Market Incumbents: Anchor market position through backward integration into captive heat-treating capacity in the U.S. Southwest, eliminating third-party metallurgical bottlenecks that delay FAA airworthiness directive compliance shipments. Secure channel control with consolidated airline procurement platforms before MRO purchasing power consolidates further, while investing in automated optical inspection systems to tighten tolerance bands below competitor reach. For New Entrants and Emerging Players: The price-point gap between premium SAE-certified engine clamps and economy line-replacement hardware creates entry space for mid-tier specialists targeting Canadian naval aviation modernization programs. Royal Canadian Air Force maritime patrol fleet upgrades present the most penetrable segment given corrosion-resistant alloy requirements that favor specialized fabricators over commodity producers. Pursue direct sourcing relationships with Texas and Arizona MRO facilities consolidating purchasing power outside traditional distributor networks. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with captive heat-treating and established SAE qualification pathways. Target acquisition archetypes include distressed stampers in the U.S. Southwest holding dormant FAA approvals and corrosion-resistant alloy fabricators serving naval aviation applications. Watch NTSB safety recommendations on clamp retention in critical systems as the inflection signal that accelerates replacement demand and qualification urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treating | Eliminates metallurgical bottlenecks and secures FAA traceability documentation. |
| Automated Optical Inspection Deployment | Tightens tolerance bands below 0.001 inch at 100% inspection rates. |
| Direct MRO Channel Relationships | Bypasses distributor markups as Texas and Arizona facilities consolidate purchasing. |
| Canadian Naval Aviation Qualification | Captures Royal Canadian Air Force maritime patrol fleet modernization demand. |
| Composite Material Process Development | Positions for Boeing 787 and Airbus A350 weight-reduction program expansion. |
Research Methodology
FAA airworthiness directive databases, SAE International fastener standards archives, and SEC filings from publicly traded aerospace suppliers formed the secondary backbone of this analysis. Primary interviews with airframe fastener procurement managers, MRO inventory planners, heat-treating facility operators, and SAE committee members combined with secondary validation to triangulate supply-side capacity and demand-side procurement patterns. Bottom-up sizing of installation volumes across commercial fleet, military aerospace, and MRO channels reconciled against top-down OEM production forecasts.
Historical trendline analysis of fleet renewal cycles, airworthiness directive issuance patterns, and material substitution rates informed the projection framework. Segmentation modeling spanned product type, material grade, end-user category, and installation context across the analysis window. CAGRs derived from fitted trendlines adjusted for regulatory mandate acceleration and composite material penetration curves, with nickel alloy price volatility and OEM qualification cycle duration as key forecast sensitivity inputs.
Inputs from FAA directive archives and SAE standards committees were available through the study window; gaps in proprietary OEM supplier qualification timelines introduce uncertainty bands around market share estimates. Forecasts reflect documented assumptions regarding fleet renewal rates and regulatory enforcement intensity. Material deviation in nickel alloy supply constraints, NTSB safety recommendation scope, or EPA plating regulation enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
North America Aircraft Manufacturing Market
Aircraft
Global Business Aircraft Market
Aircraft
North America Helicopters Market
Aircraft
Global Commercial Aircraft Windows and Windshields Market
Aircraft
Asia-Pacific Fighter Aircraft Market
Aircraft
Japan Aircraft Windshield Wiper and Washer System Market
Aircraft
Aircraft Elevator Market
Aircraft
Aircraft Wheels Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
Helicopter Wheels Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Asia-Pacific Freighter Aircraft Market
Aircraft
Amphibious Aircraft Market
Aircraft
Global Helicopter Market
Aircraft
Aviation Market
Aircraft
Water Bomber Market