
 Utility Aircraft Market | 2026-2036
Utility Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Aircraft Market Outlook
The EU Green Deal is decoupling utility aircraft procurement from pure fossil-fuel dependency across European emergency responder fleets. Textron leverages its turboprop manufacturing scale to supply multi-role platforms for law enforcement and cargo transportation missions. Daher Aerospace anchors the light-twin segment with airframes optimized for hot-and-high operations in demanding climates. Leonardo competes in the special-missions space with integrated surveillance and search-and-rescue configurations.
Utility aircraft are fixed-wing, rotary-wing, or hybrid aerial platforms engineered for payload capacities between 1,000 and 10,000 pounds, typically operating at altitudes below 25,000 feet with stall speeds optimized for unimproved runway performance; these aircraft serve commercial, governmental, and humanitarian roles requiring short-field capability and operational flexibility. Fixed-wing configurations dominate the cargo transportation application segment due to fuel efficiency and range advantages over rotarycraft on established routes. Electric propulsion technology represents the fastest-growing technology category as aviation authorities in multiple jurisdictions draft certification frameworks for battery-powered utility platforms. Turboprop systems sustain margin pools in aerial firefighting, where power-to-weight ratios and rapid turnaround times determine contract awards.
The FAA's Part 23 rewrite and EASA's CS-23 standards are converging on performance-based certification criteria that reduce development costs for innovative utility aircraft designs, while China's CAAC implements GB standards for domestic unmanned aerial vehicle integration into low-altitude airspace. ISO 9001 and AS9100 quality frameworks govern supplier qualification across the utility aircraft supply chain, particularly for emergency responder and law enforcement procurement channels. Stakeholders must monitor how dual-use technology export controls from the US Department of Commerce reshape component sourcing for surveillance-configured platforms.
Market Dynamics
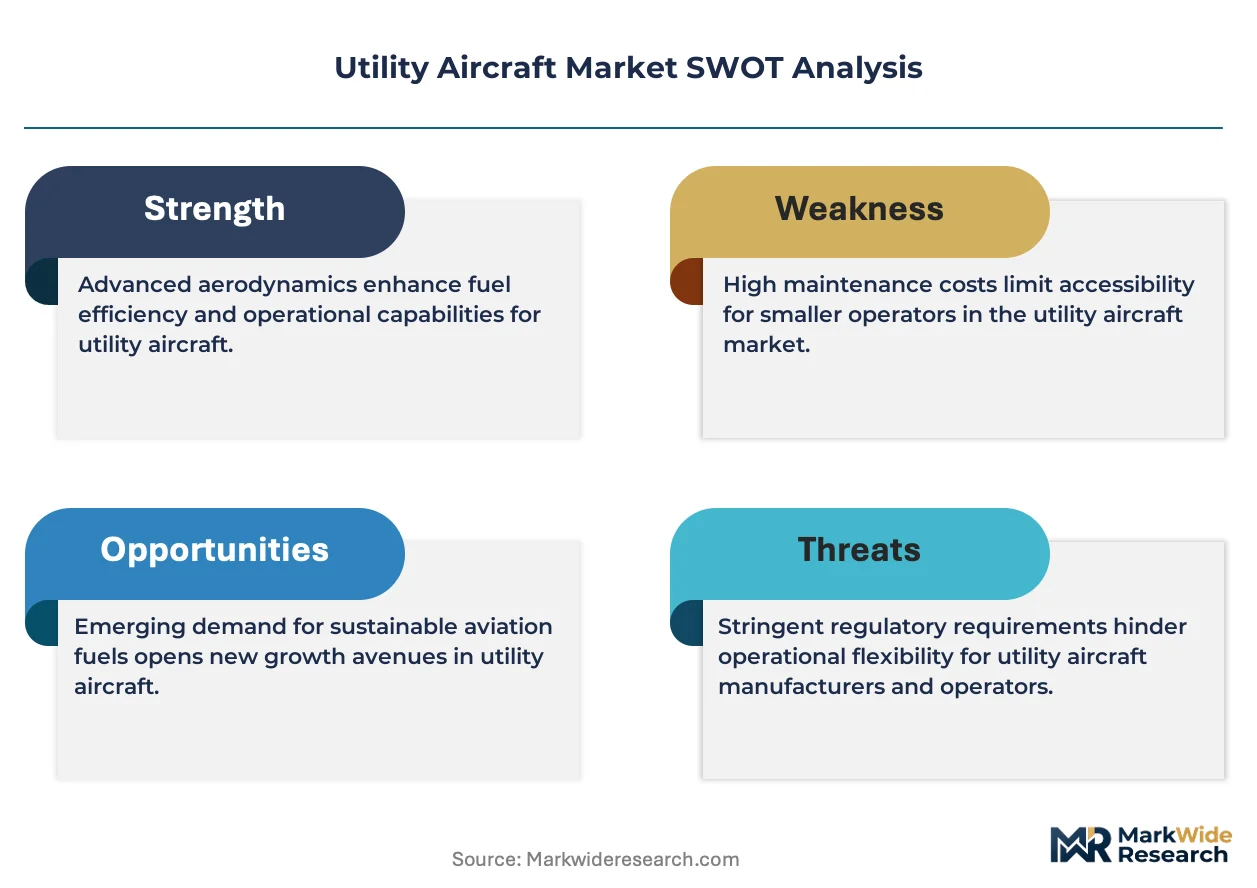
The convergence of performance-based certification frameworks with electric propulsion maturation is compressing development timelines while fragmenting supplier tiers across the utility aircraft value chain.
Growth Catalysts
- FAA Part 23 Reform:The FAA's streamlined certification pathways reduce validation costs for small aircraft manufacturers, accelerating platform entry into commercial service.
- Agricultural Fleet Expansion:Brazilian agribusiness operators are scaling aerial application capabilities for crop dusting and precision surveying across expanded cultivation zones.
- Emergency Responder Electrification:The EU Green Deal mandates are redirecting European public procurement toward reduced-carbon utility platforms for search-and-rescue and medical evacuation missions.
Market Restraints
- Aviation-Grade Battery Cost Volatility:Lithium-ion cell prices and thermal management system inputs create margin pressure for electric platform developers.
- Critical Component Concentration:Turboprop engine and avionics supply chains concentrate among a limited set of certified suppliers, creating single-source vulnerability.
- Dual-Use Export Controls:US Department of Commerce restrictions on surveillance-grade sensors and communication systems complicate cross-border platform configuration.
Strategic Opportunities
- Australia's Remote Infrastructure Gap:Mining corridor medical evacuation and cargo resupply routes remain underserved by scheduled aviation services.
- Hybrid-Electric Range Extension:Convergence of battery-electric propulsion with range-extender turbine architectures opens thin-route economics previously closed to pure-electric designs.
- Unmanned Cargo Certification:China's CAAC GB standards for low-altitude UAV integration create regulatory runway for autonomous freight platforms in controlled airspace.
Industry Challenges
- Powertrain Engineering Talent Scarcity:The intersection of aerospace certification discipline with electric propulsion system design demands hybrid skill sets in short supply.
- AS9100 Supplier Qualification Timelines:Emergency responder and law enforcement procurement channels impose extended quality framework validation cycles on component vendors.
- Legacy Avionics Integration Complexity:New propulsion architectures must interface with established flight control and navigation systems without full platform recertification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Aircraft Market |
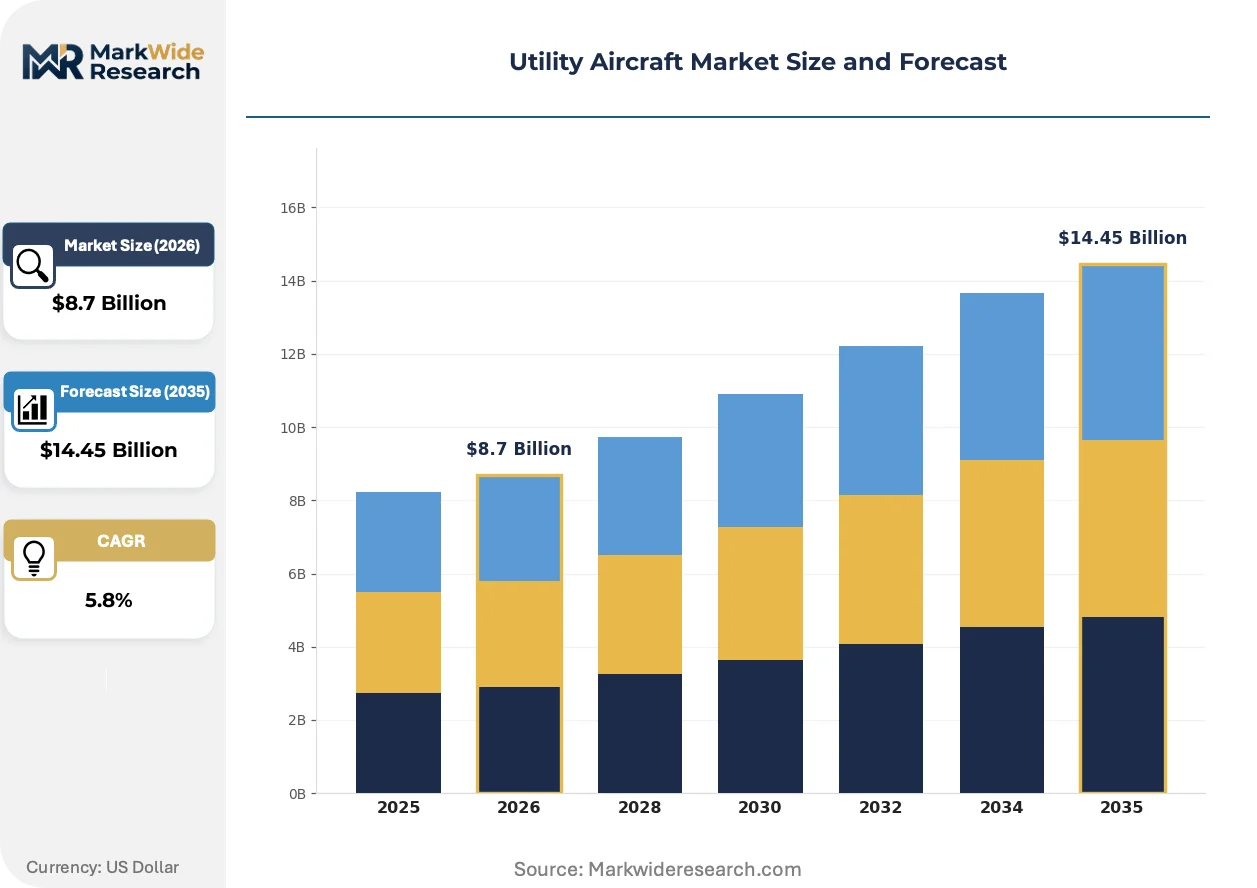
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotocraft, Hybrids, Unmanned Aerial Vehicles Application: Search & Rescue, Surveillance, Cargo Transportation, Aerial Firefighting End User: Aviation Authorities, Agricultural Companies, Emergency Responders, Law Enforcement Technology: Electric Propulsion, Turboprop, Jet Engine, Hybrid Systems |
| Companies Covered | Textron, Daher Aerospace, Lockheed Martin Corporation, Harbin Aircraft Industry Group, Changhe Aircraft Industries Group, Airbus, Leonardo, Piaggio Aero Industries, Bombardier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Aircraft Market Strategic Shifts
Active experimentation with hydrogen fuel cell range extenders and autonomous flight control systems is diverging development roadmaps between established turboprop incumbents and electric-native entrants.
Hybrid-electric propulsion architectures are converging with fixed-wing cargo platforms to enable thin-route economics on segments below 300 nautical miles. Regional freight operators in Scandinavia and the Pacific Northwest are piloting these configurations for island-hopping and remote community resupply. The technology is converging with existing ground infrastructure limitations to create new point-to-point networks bypassing hub-and-spoke constraints.
EASA's CS-23 standards are aligning with FAA Part 23 on performance-based criteria, reducing redundant certification testing for manufacturers targeting transatlantic markets. This harmonization compresses validation timelines for innovative airframe designs. European special-missions operators are responding by accelerating procurement cycles for multi-role platforms that can pivot between surveillance, cargo, and passenger configurations.
After-sales service unbundling is disrupting traditional manufacturer-captive maintenance models across law enforcement and emergency responder fleets. Third-party technical service providers in Texas and Queensland are capturing line maintenance and component overhaul work previously retained by OEM networks. This shift is most pronounced in jurisdictions with established civilian aviation maintenance ecosystems and regulatory acceptance of non-OEM repair stations.
Utility Aircraft Market Segmentation
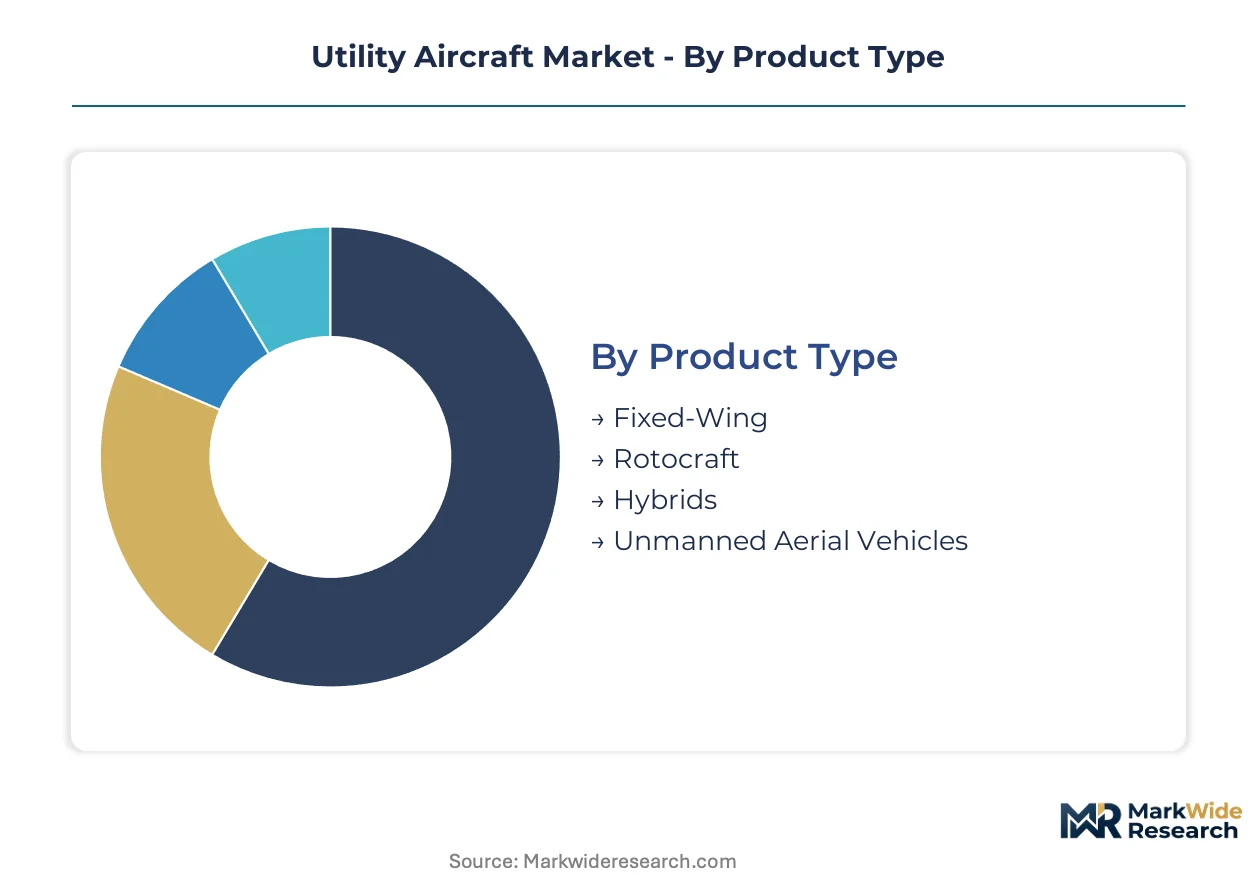
Utility aircraft segmentation reveals how certification pathways, operational envelopes, and procurement budgets fragment demand across radically different platform architectures. Each category carries distinct regulatory burdens that shape manufacturer R&D allocation and customer acquisition costs.
Product Type:
FAA Part 23 governs fixed-wing and rotary-wing platforms through established airworthiness criteria, while EASA CS-23 and China's CAAC GB standards create parallel validation tracks for unmanned systems and hybrid configurations entering commercial service.
- Fixed-Wing:Conventional airframes with payload capacities between 1,000 and 10,000 pounds dominate cargo corridors where fuel efficiency outweighs vertical-lift flexibility. Brazilian agricultural operators are expanding fleets for crop dusting across expanded cultivation zones, drawn by established maintenance networks and pilot training infrastructure.
- Rotocraft:Rotary-wing platforms deliver payload to unimproved landing zones without runway dependency, commanding premium positioning in medical evacuation and offshore logistics. Australia's remote mining corridors rely on these aircraft for personnel transport where fixed-wing infrastructure remains absent.
- Hybrids:Convergent architectures blending fixed-wing cruise efficiency with rotary-wing vertical capability face extended certification timelines under evolving performance-based standards.
- Unmanned Aerial Vehicles:Remotely piloted and autonomous platforms operate under nascent regulatory frameworks with jurisdiction-specific operational altitude and beyond-visual-line-of-sight restrictions.
Leading the category by volume: Fixed-Wing. Growing fastest: Hybrids.
Application:
Procurement patterns diverge sharply between mission-critical public-sector contracts and commercial operators optimizing asset utilization across seasonal demand cycles.
- Search & Rescue:Configured platforms integrate thermal imaging, rescue hoists, and extended-range fuel systems for sustained operations over maritime and alpine terrain. EU Green Deal mandates are redirecting European emergency responder fleets toward reduced-carbon propulsion alternatives, accelerating fleet renewal timelines.
- Surveillance:Sensor-integrated airframes carry electro-optical, radar, and signals intelligence payloads for border patrol and infrastructure monitoring missions. US Department of Commerce dual-use export controls complicate cross-border platform configuration for surveillance-grade sensors and communication systems.
- Cargo Transportation:Payload-optimized designs prioritize volume efficiency and rapid turnaround for scheduled freight and ad-hoc resupply contracts.
- Aerial Firefighting:Tanker and command-and-control platforms require rapid-deployment certification and specialized retardant delivery systems.
Contract concentration: Cargo Transportation. Steepest expansion trajectory: Search & Rescue.
End User:
Customer procurement authority determines specification rigor, with regulatory bodies and emergency responders imposing AS9100 and ISO 9001 supplier qualification requirements absent in commercial agricultural channels.
- Aviation Authorities:National regulators acquire calibration, inspection, and training platforms to maintain airspace system integrity and certify operational personnel.
- Agricultural Companies:Brazilian agribusiness operators scale aerial application capabilities for precision surveying and crop protection across expanded cultivation zones.
- Emergency Responders:Public safety agencies procure multi-role platforms pivoting between medical evacuation, disaster relief, and search missions under compressed procurement cycles.
- Law Enforcement:Police and border control agencies specify surveillance-configured aircraft with integrated sensor suites and secure communications, subject to extended quality framework validation cycles on component vendors.
Procurement volume leader: Agricultural Companies. Fastest contract growth: Emergency Responders.
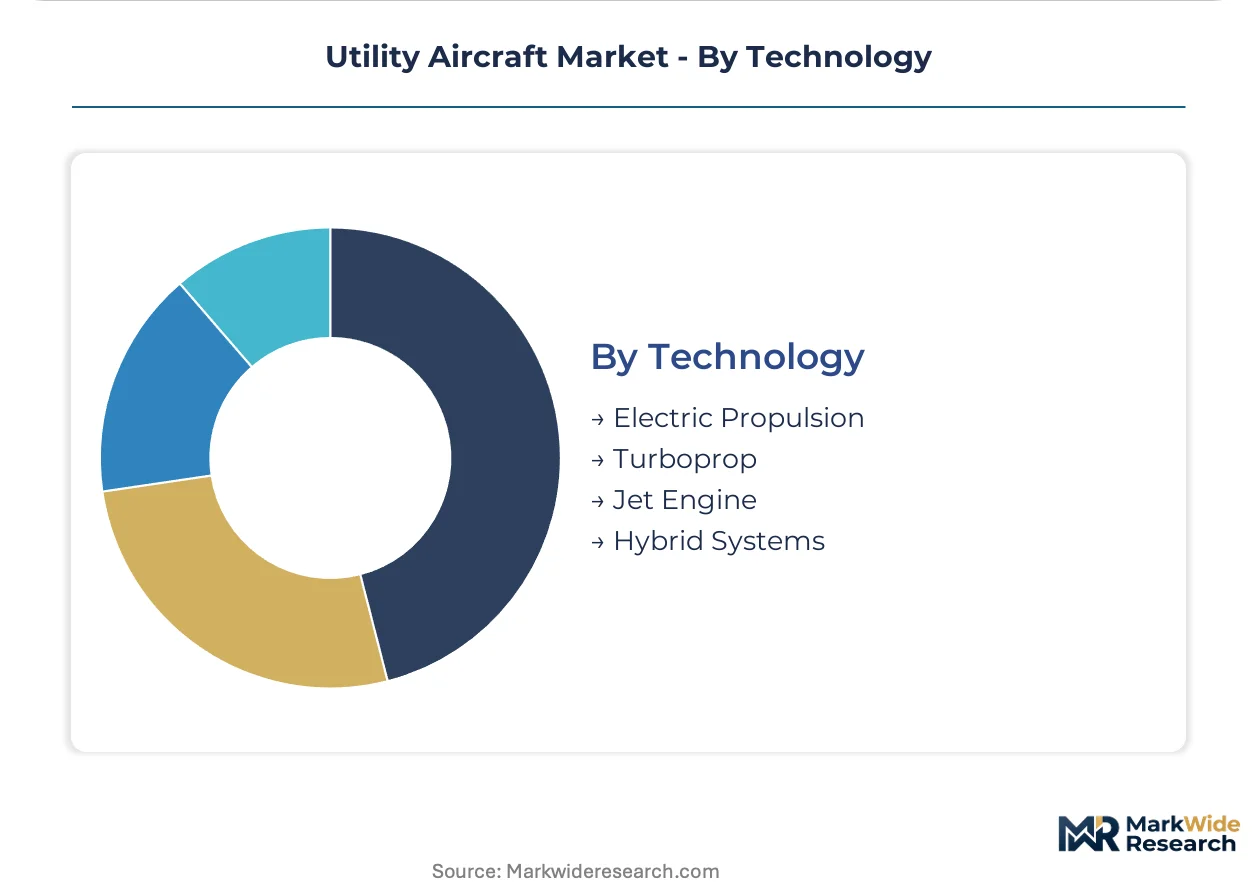
Technology:
Powertrain selection determines certification pathway complexity, with electric and hybrid systems navigating evolving battery thermal management standards while turboprop and jet platforms leverage decades of established validation precedent.
- Electric Propulsion:Battery-native architectures face aviation-grade lithium-ion cost volatility and thermal management system margin pressure, though multiple jurisdictions are drafting certification frameworks for battery-powered utility platforms.
- Turboprop:Mature powertrains sustain margin pools in aerial firefighting where power-to-weight ratios and rapid turnaround times determine contract awards, with supply chains concentrating among a limited set of certified suppliers creating single-source vulnerability.
- Jet Engine:High-thrust configurations serve specialized high-speed transport and large-payload applications with established maintenance networks.
- Hybrid Systems:Range-extender architectures combining battery-electric propulsion with turbine generators open thin-route economics previously closed to pure-electric designs.
Technology leader by installed base: Turboprop. Gaining share fastest: Hybrid Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wichita, Kansas anchors North American utility aircraft manufacturing through a dense cluster of airframe integrators and component suppliers serving agricultural, cargo, and special-missions operators.
United States
The FAA's Part 23 reform reduces certification costs for small aircraft developers, accelerating platform entry into commercial service. Agricultural operators in the Midwest and Great Plains expand aerial application fleets for precision crop management. Wichita's manufacturing corridor concentrates turboprop assembly and avionics integration for law enforcement and emergency responder contracts.
Brazil
Agribusiness operators scale aerial surveying and crop dusting capabilities across expanded cultivation zones in Mato Grosso and São Paulo states. ANVISA coordinates with aviation regulators on aerial pesticide application standards. São José dos Campos hosts Embraer-linked suppliers configuring utility platforms for remote infrastructure monitoring.
Australia
Mining corridor medical evacuation and cargo resupply routes in Queensland and Western Australia drive demand for short-field capable aircraft. CASA maintains performance-based certification alignment with FAA standards for simplified type validation. Perth and Brisbane maintenance clusters capture third-party overhaul work from OEM-captive service networks.
China
CAAC's GB standards for low-altitude UAV integration create regulatory runway for autonomous freight platforms in controlled airspace. Harbin and Nanchang industrial zones concentrate state-owned airframe production for domestic special-missions procurement. The Yangtze River Delta hosts emerging electric propulsion suppliers targeting certification for battery-powered utility designs.
Germany
EU Green Deal mandates redirect emergency responder fleet procurement toward reduced-carbon propulsion alternatives for search-and-rescue missions. EASA's CS-23 harmonization with FAA Part 23 compresses validation timelines for innovative airframe designs. Bavaria's aerospace cluster around Munich specializes in sensor integration for surveillance-configured platforms.
Utility Aircraft Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification complexity and special-missions integration depth. The vendor base stratifies between established turboprop incumbents with decades of airworthiness precedent and electric-native entrants navigating nascent battery-thermal standards. Three archetypes dominate: full-spectrum aerospace conglomerates with defense and commercial divisions; specialized light-aircraft manufacturers optimizing for hot-and-high performance; and state-backed industrial groups serving protected domestic procurement channels. Competitive moves concentrate on hybrid-electric propulsion partnerships and after-sales service unbundling to capture third-party maintenance revenue.
Among diversified aerospace conglomerates, Textron and Lockheed Martin Corporation occupy positions spanning civil and defense utility applications. Daher Aerospace exemplifies the specialized light-twin segment with airframes engineered for demanding climate operations. Leonardo represents European special-missions integration, anchoring surveillance and search-and-rescue configurations. Harbin Aircraft Industry Group and Changhe Aircraft Industries Group sit within state-backed procurement structures serving domestic Chinese requirements.
| Leading Market Players |
|---|
| Textron |
| Daher Aerospace |
| Lockheed Martin Corporation |
| Harbin Aircraft Industry Group |
| Changhe Aircraft Industries Group |
| Airbus |
| Leonardo |
| Piaggio Aero Industries |
| Bombardier |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal mandates are gating qualified supply access and premium-tier pricing for European emergency responder fleets, with reduced-carbon propulsion certification becoming the threshold for contract eligibility in public procurement channels.
Pricing Analysis
Value-based pricing anchored to mission uptime and payload throughput dominates emergency responder and law enforcement contracts, where operational availability clauses determine contract awards. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified special-missions platforms from commercial agricultural configurations and basic cargo haulers. Cost compression in electric propulsion tiers is intensifying because aviation-grade lithium-ion cell volatility and thermal management system margins pressure developers. Agricultural operators in Brazil exhibit highest price sensitivity due to seasonal utilization patterns, while Australian mining corridor medical evacuation services accept premium positioning for runway-independent capability.
Supply Chain Analysis
Refurbishment flows for turboprop engines and avionics modules create secondary supply channels that extend component life cycles and buffer OEM pricing power. Manufacturing concentration rests on the United States, Brazil, and China for airframe assembly, with Germany and France anchoring sensor integration and special-missions outfitting. Critical dependencies center on lithium-ion cells from East Asian suppliers, precision avionics from North American and European vendors, and composite airframe materials from specialized chemical producers. Single-source vulnerability concentrates in turboprop engine certification, where limited qualified suppliers create procurement bottlenecks. Distribution runs through OEM-captive networks for emergency responder fleets and third-party technical service providers for commercial agricultural operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with upstream control over battery thermal management systems and downstream capture of third-party maintenance revenue representing the decisive levers for margin defense.
For Market Incumbents: Deploy hybrid-electric propulsion partnerships to neutralize electric-native entrants before battery certification frameworks mature. Lock in long-term turboprop engine supply agreements to mitigate single-source vulnerability from concentrated suppliers. Accelerate after-sales service unbundling to capture third-party overhaul revenue from law enforcement and emergency responder fleets in Texas and Queensland. For New Entrants and Emerging Players: Australia's remote mining corridor medical evacuation operators represent an underserved buyer archetype with thin-route economics and infrastructure gaps. Target hybrid-electric range-extender configurations for island-hopping cargo operators in Scandinavia and the Pacific Northwest. Pursue CAAC GB certification pathways for autonomous freight platforms in China's controlled low-altitude airspace. For Investors and Strategic Acquirers: EASA-FAA Part 23 harmonization announcements are the leading indicator that certification timeline compression will favor agile airframe developers over legacy incumbents. Position acquisition screening toward specialized light-twin manufacturers with hot-and-high operational expertise and established AS9100 supplier networks. Watch for battery thermal management standard finalization as the signal that electric platform economics will cross threshold viability.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Partnership | Combines battery-electric efficiency with turbine range extension for thin-route cargo economics. |
| AS9100 Supplier Qualification Acceleration | Compresses validation cycles for emergency responder procurement channels requiring quality framework compliance. |
| Third-Party Maintenance Network Capture | Diverts line maintenance and component overhaul revenue from OEM-captive service models in Texas and Queensland. |
| Performance-Based Certification Investment | Aligns with FAA Part 23 and EASA CS-23 convergence to reduce redundant testing for transatlantic market entry. |
| Autonomous Freight Platform Development | Positions for CAAC GB standards implementation in China's low-altitude UAV integration corridor. |
Study Parameters
Independent corroboration across airframe manufacturer executives, turboprop engine procurement leads, emergency responder fleet managers, and agricultural operator technical directors underwrites the qualitative findings in this analysis. Primary fieldwork combined structured interviews with secondary validation from FAA certification databases, EASA CS-23 regulatory filings, ANVISA aerial application standards, and CAAC GB unmanned system protocols. Bottom-up segmentation modeling triangulated with top-down market sizing across fixed-wing, rotary-wing, hybrid, and unmanned platform categories.
Comparable-period anchoring to historical certification timelines and fleet renewal cycles established the forecast window boundaries across the projection horizon. Segmentation dimensions modeled include product architecture, application mission type, end-user procurement authority, and propulsion technology tier. CAGRs were derived from installation base growth trajectories and replacement demand patterns, with inputs from agricultural fleet expansion rates in Brazil and mining corridor infrastructure gaps in Australia.
Revisions become necessary when aviation-grade battery cost volatility, dual-use export control tightening, or regulator harmonization delays materialize beyond modeled assumptions. Forecasts reflect documented judgment on electrification adoption curves and certification pathway evolution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market
Aircraft
Aircraft Cargo Systems Market
Aircraft
Asia-Pacific Aviation Market
Aircraft
Global Business Jets Market
Aircraft
Electric VTOL (Evtol) Aircraft Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Electric Aircraft Market
Aircraft
India Aviation Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Reusable Launch Vehicles Market
Aircraft
Middle-East and Africa Commercial Aircraft Market
Aircraft
Europe Light and Very Light Jets Market
Aircraft
Hybrid Aircraft Market
Aircraft
North America Light and Very Light Jets Market
Aircraft
Helicopter Flight Management System Market
Aircraft
Aircraft Container & Pallet Loader Market