
 Middle East and Africa Aviation Market | 2026-2036
Middle East and Africa Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Aviation Market Foresight
Composite materials are displacing traditional aluminum alloys in airframe construction and is realigning lifecycle cost calculations for regional carriers. Emirates leverages its Dubai hub to sustain one of the world's largest wide-body fleets, while Qatar Airways anchors its competitive stance through Doha's strategic geographic position between Europe and Asia-Pacific. flydubai competes aggressively in the narrow-body segment, offering point-to-point connectivity across secondary cities that legacy carriers overlook.
Middle East and Africa aviation encompasses the design, manufacture, operation, and servicing of fixed-wing and rotary-wing aircraft across commercial, business, and cargo applications, with modern turbofan engines achieving thrust-to-weight ratios exceeding five-to-one for long-haul efficiency. The primary commercial purpose centers on passenger and freight transport across vast desert and oceanic distances where surface infrastructure remains sparse. Commercial Jets dominate fleet orders from Gulf-based airlines, while Helicopters command premium margins in offshore oil-and-gas logistics serving Nigeria and Angola. Cargo Aircraft represent the fastest-expanding segment as e-commerce fulfillment drives dedicated freighter demand into Addis Ababa and Nairobi hubs.
Saudi Arabia's General Authority of Civil Aviation, the UAE's General Civil Aviation Authority, and South Africa's Civil Aviation Authority enforce divergent certification standards that shape market access for foreign lessors and maintenance providers. South Africa's CAA mandates specific technical documentation for imported components, while UAE-GCAA bilateral agreements facilitate faster airworthiness approvals for Dubai Aerospace Enterprise leasing portfolios. Stakeholders must monitor how SAFA inspections and emerging carbon-offset frameworks recalibrate fleet renewal timelines without explicit regulatory deadlines.
Market Dynamics
Fleet modernization across Gulf carriers is compressing replacement cycles as carbon-fiber-reinforced polymers displace aluminum in primary airframe structures, forcing maintenance networks to retool for composite repair protocols.
Growth Catalysts
- Composite Material Mandates:UAE-GCAA airworthiness directives now prioritize carbon-fiber inspections, accelerating MRO infrastructure investment across Dubai's aviation cluster.
- Geographic Hub Positioning:Doha's location between Europe and Asia-Pacific generates sixth-freedom traffic that sustains ultra-long-haul fleet economics.
- Offshore Logistics Demand:Nigerian and Angolan deepwater oil operations require heavy-lift helicopter capacity that commands premium day-rate contracts.
Market Restraints
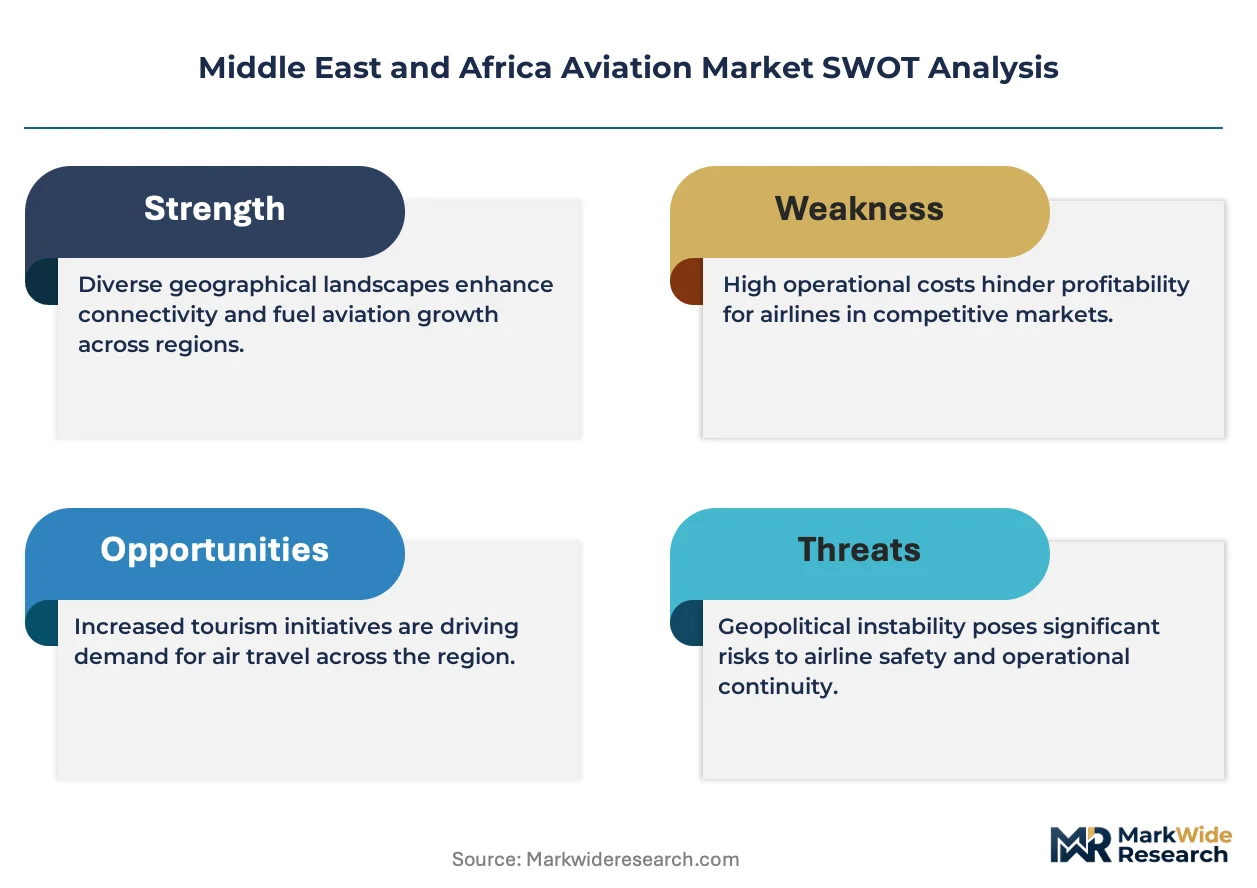
- Input Cost Volatility:Jet fuel price swings expose thin-margin narrow-body operators to earnings compression during hedging gaps.
- Supply Concentration Risk:Single-source dependency on US and EU engine OEMs creates delivery timeline vulnerability for African carriers without lessor backing.
- Regulatory Friction:South Africa's CAA technical documentation requirements delay component imports by 30-90 days versus UAE bilateral pathways.
Strategic Opportunities
- Underpenetrated East African Hubs:Addis Ababa and Nairobi cargo terminals lack dedicated freighter gates for e-commerce volume expansion.
- Regulatory Tailwind:Saudi Arabia's General Authority of Civil Aviation privatization roadmap opens ground handling concessions to foreign joint ventures.
- Technology Convergence:Predictive maintenance algorithms fused with satellite connectivity reduce unscheduled engine removals for long-haul fleets.
Industry Challenges
- Composite Repair Certification Gap:Licensed technicians for carbon-fiber structural repair remain scarce outside Dubai and Johannesburg training centers.
- Capex Intensity for Freighter Conversion:Passenger-to-cargo modification programs require 18-24 month shop visits that strain lessor asset utilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Aviation Market |
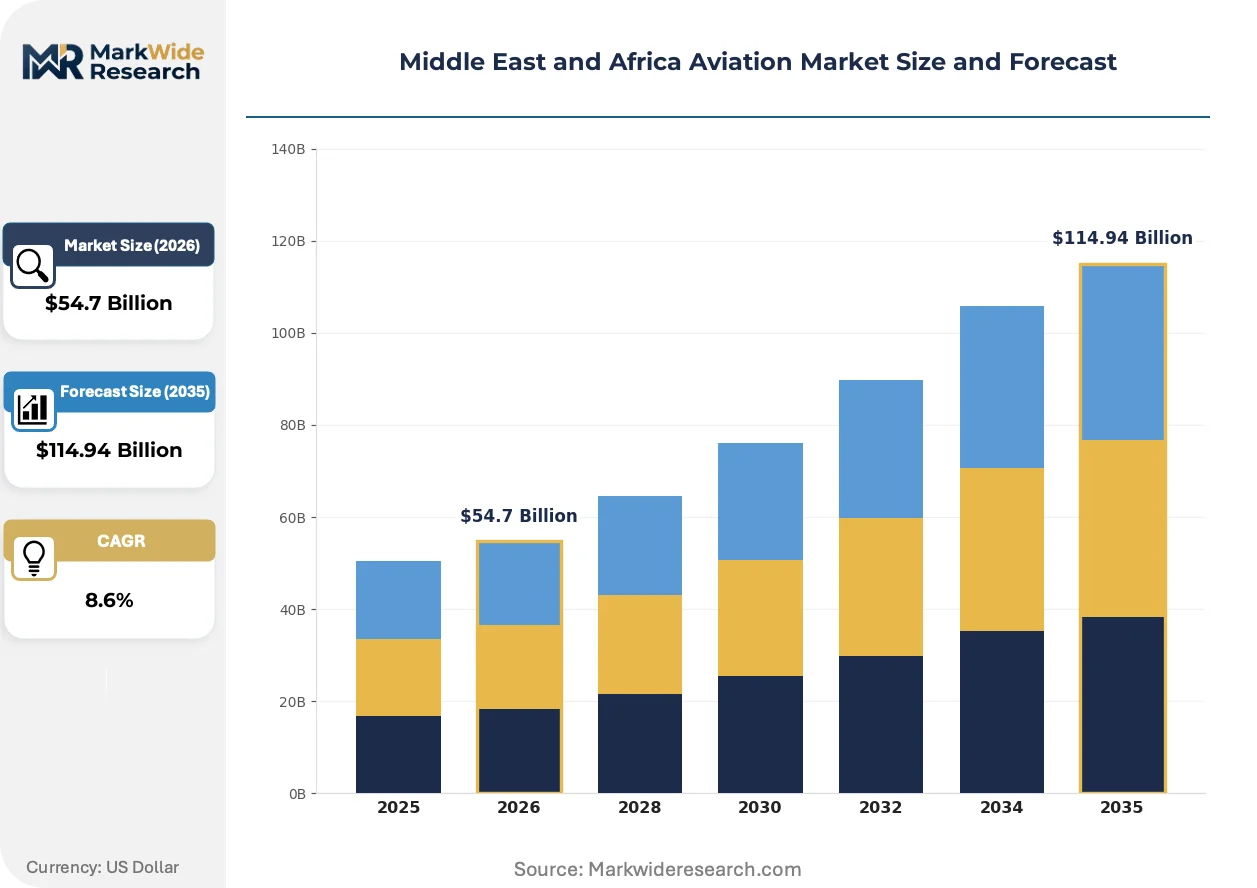
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $114.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Commercial Jets, Business Jets, Helicopters, Cargo Aircraft End User: Airlines, Private Owners, Charter Services, Cargo Operators Service Type: Maintenance, Ground Handling, Flight Training, Leasing Technology: avionics, Propulsion Systems, Safety Systems, Navigation Tech |
| Companies Covered | Emirates, Qatar Airways, Etihad Airways, flydubai, flynas, Air Arabia, Airbus SE, The Boeing Company, Dubai Aerospace Enterprise, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Aviation Market Shifts & Advancements
Aviation technology in the Middle East and Africa is pivoting toward fuel efficiency mandates and digital operations, with material science and regulatory compliance reshaping fleet planning and maintenance workflows.
Additive manufacturing is expanding into flight-critical titanium brackets and ducting components, with Emirates Engineering and Lufthansa Technik Middle East adopting powder-bed fusion for non-structural parts. The technology reduces lead times from 16 weeks to 72 hours for obsolete components. This capability is expanding into airworthiness-certified production, compressing inventory carrying costs for aging wide-body fleets.
Carbon-offset disclosure frameworks are expanding into SAFA inspection protocols, with EU-ETS linkage forcing Gulf carriers to document fuel burn per available seat-mile on European routes. The regulation triggers fleet renewal decisions earlier than depreciation schedules would suggest. Long-haul operators are responding by accelerating A350 and 787 deliveries while retiring four-engine types ahead of book value.
After-sales service unbundling is fragmenting traditional power-by-the-hour contracts, with African carriers negotiating line-item maintenance separately from spare parts provisioning. The shift transfers inventory risk to operators but reduces fixed cost exposure. This pattern is most visible among Ethiopian Airlines' regional subsidiaries and Kenyan low-cost entrants.
Middle East and Africa Aviation Market Segmentation
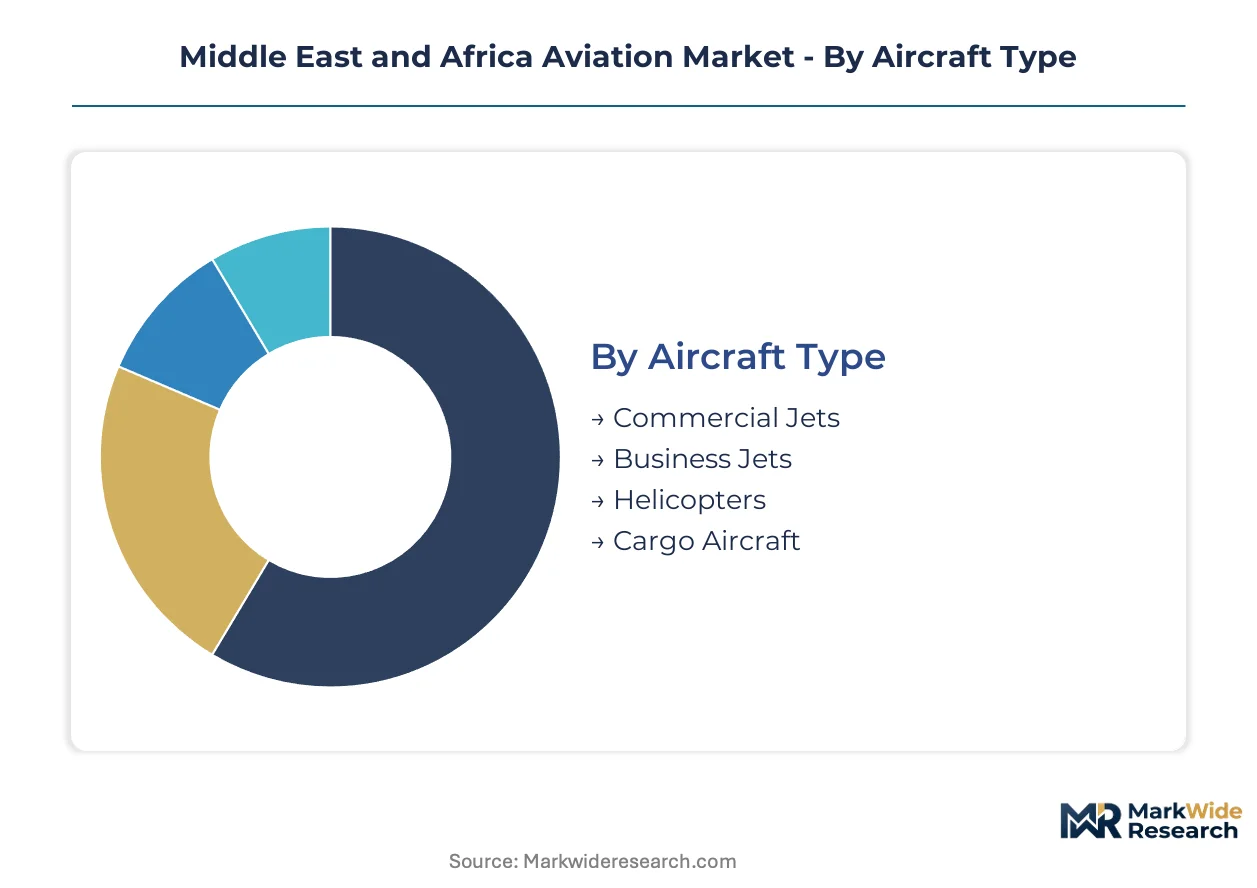
Fleet composition across the Middle East and Africa diverges sharply by operating economics and regulatory exposure. Buyers select aircraft categories and service models based on hub connectivity requirements, offshore logistics mandates, and bilateral airworthiness pathways.
Aircraft Type:
Carriers prioritize thrust-to-weight efficiency and airframe material compliance when acquiring fleet assets.
- Commercial Jets:Twin-aisle and narrow-body turbofans dominate Gulf carrier order books, with carbon-fiber-reinforced polymer fuselages displacing aluminum alloys in new deliveries. Emirates and Qatar Airways anchor demand in Dubai and Doha for long-haul wide-bodies serving sixth-freedom traffic flows.
- Helicopters:Heavy-lift rotorcraft command premium day-rates in Nigerian and Angolan deepwater oil operations, where offshore logistics contracts specify all-weather payload capacity. Eurocopter and Leonardo platforms predominate in African energy sector procurement.
- Business Jets:Long-range jets serve Saudi private ownership and South African charter networks requiring intercontinental range without scheduled airline constraints.
- Cargo Aircraft:Dedicated freighter demand concentrates at Addis Ababa and Nairobi hubs, where e-commerce fulfillment drives conversion of aging passenger wide-bodies.
Volume sits with Commercial Jets; growth tilts toward Cargo Aircraft.
End User:
Procurement authority separates by balance sheet capacity and regulatory compliance burden.
- Airlines:Full-service and low-cost carriers across the GCC states negotiate power-by-the-hour contracts with lessors, transferring residual value risk while retaining operational control. Ethiopian Airlines and Kenya Airways anchor East African narrow-body renewal cycles.
- Cargo Operators:Express integrators and dedicated freighter lessors dominate dedicated cargo demand, with Dubai-based lessors leveraging UAE-GCAA bilateral agreements for faster airworthiness approvals. E-commerce volume growth through Addis Ababa and Nairobi drives freighter gate expansion.
- Private Owners:Saudi and UAE high-net-worth individuals acquire long-range business jets through Dubai Aerospace Enterprise leasing structures, bypassing direct ownership complexity.
- Charter Services:South African operators serve mining executive transport and safari tourism routes, where thin infrastructure necessitates point-to-point rotary and fixed-wing capacity.
Revenue concentrates with Airlines; margin expansion favors Cargo Operators.
Service Type:
Service procurement splits between asset-light operators seeking variable cost structures and integrated carriers insourcing critical capabilities.
- Maintenance:Composite repair certification scarcity outside Dubai and Johannesburg training centers creates bottleneck premiums for carbon-fiber structural work. Emirates Engineering and Lufthansa Technik Middle East deploy additive manufacturing for obsolete titanium brackets, compressing lead times from 16 weeks to 72 hours.
- Ground Handling:Saudi Arabia's General Authority of Civil Aviation privatization roadmap opens airport concessions to foreign joint ventures, reshaping competitive access at Jeddah and Riyadh terminals.
- Flight Training:Simulator capacity concentrates in Dubai's aviation cluster, where Emirates and flydubai anchor type-rating demand for A350 and 787 fleets.
- Leasing:Dubai Aerospace Enterprise and AerCap portfolios dominate regional lessor penetration, with UAE bilateral pathways accelerating delivery timelines versus South African CAA documentation requirements.
Spend pools in Maintenance; concession opportunities emerge in Ground Handling.
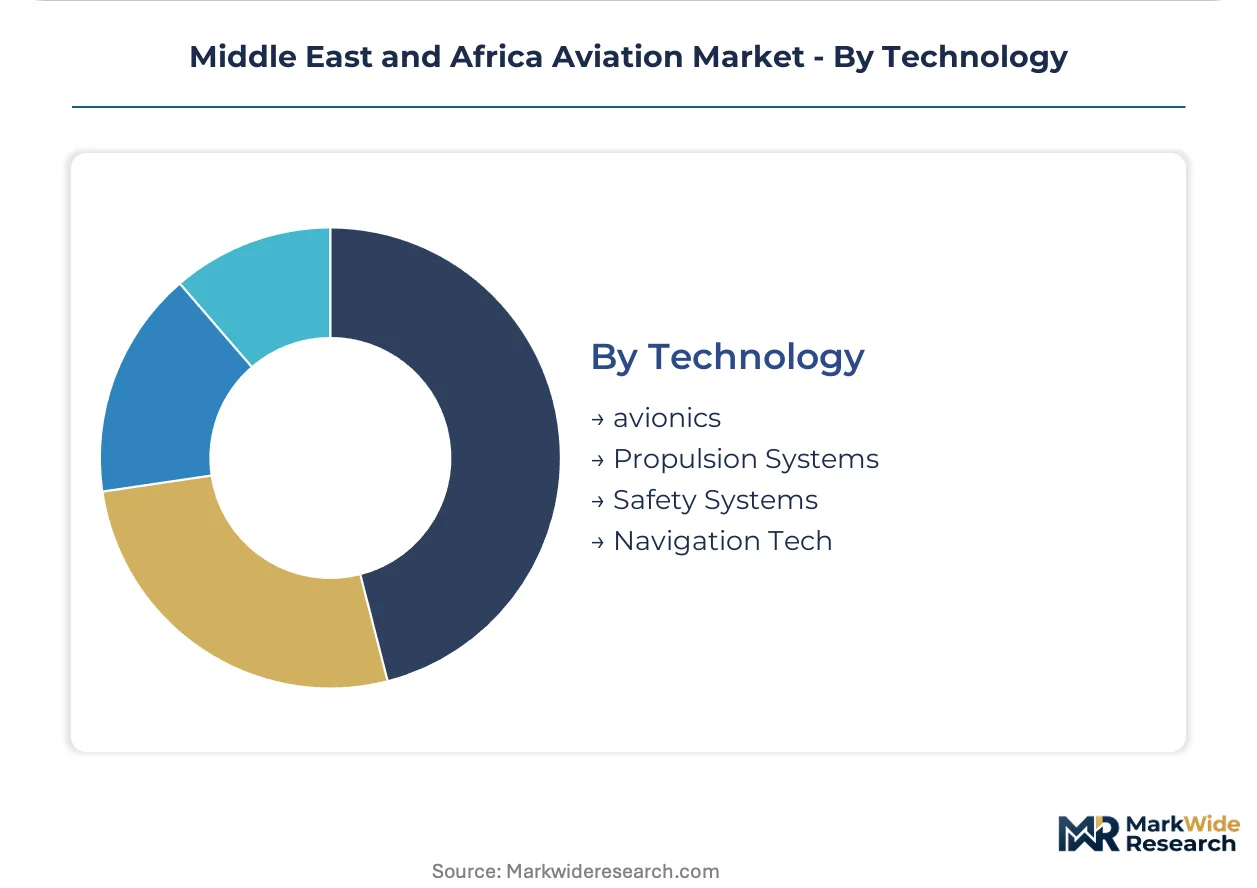
Technology:
Technology adoption separates by certification pathway and retrofit economics.
- Propulsion Systems:High-bypass turbofans achieving thrust-to-weight ratios exceeding five-to-one enable long-haul efficiency for Gulf carrier ultra-long-haul routes. Geared turbofan technology penetrates narrow-body fleets at flydubai and Air Arabia.
- Avionics:Satellite connectivity integration supports predictive maintenance algorithms that reduce unscheduled engine removals. Gulf carriers mandate real-time health monitoring for leased wide-body assets.
- Safety Systems:Enhanced ground proximity warning and runway overrun protection satisfy UAE-GCAA airworthiness directives prioritizing carbon-fiber inspection protocols.
- Navigation Tech:Required navigation performance authorization enables precision approaches at secondary African airports lacking ground-based augmentation.
Investment intensity clusters in Propulsion Systems; retrofit demand favors Avionics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's aviation cluster concentrates fleet maintenance, pilot training, and lessor headquarters within Jebel Ali Free Zone tax incentives. Saudi Arabia's General Authority of Civil Aviation privatization roadmap redirects ground handling concessions toward foreign joint ventures. South Africa's Civil Aviation Authority enforces stricter technical documentation standards than Gulf regulators.
United Arab Emirates
Emirates and flydubai anchor wide-body and narrow-body fleet renewal cycles at Dubai International Airport. The UAE's General Civil Aviation Authority maintains bilateral airworthiness pathways that accelerate lessor delivery timelines. Dubai Aerospace Enterprise consolidates leasing portfolios within Jebel Ali Free Zone, where zero corporate tax rates attract foreign MRO providers.
Saudi Arabia
Riyadh and Jeddah terminals absorb capacity from the General Authority of Civil Aviation's airport privatization program. SAFA inspection protocols now incorporate carbon-offset disclosure requirements linked to EU-ETS frameworks. The Eastern Province's Dammam hub serves offshore helicopter logistics for Aramco oilfield operations.
Qatar
Hamad International Airport generates sixth-freedom traffic between Europe and Asia-Pacific that sustains Qatar Airways' ultra-long-haul economics. The Qatar Civil Aviation Authority aligns certification standards with UAE-GCAA bilateral agreements. Doha's aviation cluster lacks dedicated freighter gates despite e-commerce volume growth through the hub.
South Africa
Johannesburg and Cape Town charter operators serve mining executive transport and safari tourism routes. The country's Civil Aviation Authority mandates 30-90 day delays for imported component technical documentation. Durban's maintenance facilities compete with Dubai for carbon-fiber structural repair certification capacity.
Nigeria
Lagos and Port Harcourt helicopter operators command premium day-rates for deepwater oil-and-gas logistics contracts. The Nigerian Civil Aviation Authority struggles with SAFA inspection compliance gaps that restrict European route access. Offshore logistics demand concentrates around Escravos and Bonny Island energy infrastructure.
Middle East and Africa Aviation Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-service Gulf carriers and narrow-body low-cost operators occupying distinct competitive tiers. Fleet scale and hub geography determine positioning more than manufacturing integration. Three archetypes dominate: hub-and-spoke legacy carriers with government backing, point-to-point low-cost entrants, and captive lessors with bilateral regulatory advantages. Competitive moves cluster around fleet renewal acceleration and MRO network expansion rather than horizontal consolidation.
Among Gulf-based full-service carriers, Emirates and Qatar Airways exemplify the hub-and-spoke archetype through sixth-freedom traffic capture. Etihad Airways occupies a position within the same tier with adjusted network scale. Dubai Aerospace Enterprise represents the captive lessor model, leveraging UAE regulatory pathways to compress delivery timelines for regional operators.
| Leading Market Players |
|---|
| Emirates |
| Qatar Airways |
| Etihad Airways |
| flydubai |
| flynas |
| Air Arabia |
| Airbus SE |
| The Boeing Company |
| Dubai Aerospace Enterprise |
| Others |
Supply & Pricing Matrix
Carbon-fiber-reinforced polymer adoption in airframe construction simultaneously compresses manufacturing lead times and concentrates repair certification premiums within Dubai and Johannesburg training centers. This material transition forces Gulf carriers to absorb upfront fleet premiums while African operators without lessor backing face extended delivery timelines from South Africa's Civil Aviation Authority documentation requirements.
Pricing Analysis
Volume concentrates with commercial jet deliveries to Emirates and Qatar Airways, while margin expansion favors helicopter day-rate contracts in Nigerian and Angolan offshore logistics. Three-tier pricing structure across premium wide-body, standard narrow-body, and economy regional jet levels separates fleet acquisition costs. Cost compression in narrow-body segments is intensifying because flydubai and Air Arabia compete aggressively on point-to-point routes. Charter operators in South Africa exhibit highest price sensitivity due to thin-margin safari tourism dependency, while Saudi private owners show lowest sensitivity through Dubai Aerospace Enterprise leasing structures.
Supply Chain Analysis
Single-source vulnerability sits with US and EU engine OEMs for turbofan propulsion systems, creating delivery timeline exposure for Ethiopian Airlines and Kenya Airways without lessor intermediation. Manufacturing concentrates in the United States, France, and Germany for airframe assemblies and engine components. Supply chains draw from titanium alloys, carbon-fiber prepregs, and avionics semiconductor inputs. Tariff exposure runs through EU-ETS carbon-offset linkage affecting Gulf carrier European route economics. Distribution runs through Dubai Aerospace Enterprise and AerCap leasing portfolios leveraging UAE-GCAA bilateral pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where captive MRO capabilities and additive manufacturing adoption determine who captures lifecycle value from aging wide-body fleets.
For Market Incumbents: Hedge against composite repair certification scarcity by securing exclusive training partnerships with Emirates Engineering and Lufthansa Technik Middle East. Lock in long-term power-by-the-hour contracts with flydubai and Air Arabia before unbundling trends fragment service procurement. Vertical integration into predictive maintenance algorithms reduces unscheduled engine removal exposure for leased assets. For New Entrants and Emerging Players: East African cargo operators represent the most penetrable buyer archetype, with Addis Ababa and Nairobi terminals lacking dedicated freighter gates for e-commerce volume expansion. Target Nigerian helicopter logistics contractors seeking alternatives to Eurocopter and Leonardo platform dependency. Pursue SAFA inspection compliance partnerships as the go-to-market angle for European route access. For Investors and Strategic Acquirers: Exit pathways concentrate in captive lessor acquisitions by aerospace conglomerates seeking UAE regulatory pathway access. Long-term viability hinges on carbon-offset framework alignment and composite repair network scale. Watch for SAFA inspection protocol harmonization across GCC regulators as the inflection signal for regional consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Repair Certification Investment | Dubai and Johannesburg training centers capture premium margins from carbon-fiber structural work scarcity. |
| Freighter Gate Expansion | Addis Ababa and Nairobi cargo terminals address e-commerce fulfillment bottlenecks through dedicated infrastructure. |
| Predictive Maintenance Algorithm Deployment | Satellite-enabled health monitoring reduces unscheduled engine removals for Qatar Airways' ultra-long-haul fleet. |
| Ground Handling Concession Partnership | Saudi Arabia's General Authority of Civil Aviation privatization opens Jeddah and Riyadh terminals to foreign joint ventures. |
| Additive Manufacturing Capability Buildout | Powder-bed fusion adoption at Emirates Engineering compresses obsolete titanium bracket lead times from 16 weeks to 72 hours. |
Research Methodology
Document review covered fleet order databases, airworthiness directive filings, and MRO capacity registries, complemented by interviews with airline fleet planning executives, MRO operations directors, lessor asset managers, and civil aviation authority certification leads. Secondary sources included UAE-GCAA bilateral agreement texts, South Africa's CAA technical documentation requirements, SAFA inspection protocols, and customs trade data for aircraft component flows. Bottom-up triangulation across operator procurement patterns and top-down validation through OEM delivery schedules anchored market sizing.
Historical fleet deployment patterns cross-referenced against panel input from aviation consultants and regulatory affairs specialists shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include aircraft type, end-user procurement authority, service procurement model, and technology certification pathway. CAGRs derived from fitted trend extrapolation adjusted for fleet renewal acceleration triggers and carbon-offset compliance deadlines. Forecast inputs incorporated composite material adoption curves and e-commerce cargo volume trajectories through East African hubs.
Revisions become necessary when UAE-GCAA bilateral pathways face renegotiation, SAFA inspection protocols tighten without warning, or jet fuel price volatility exceeds hedging program capacity. Forecasts reflect documented assumptions about fleet replacement timelines and regulatory harmonization progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Europe Helicopters Market
Aircraft
Afterburner Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
Aircraft Window Frame Market
Aircraft
US Aviation Market
Aircraft
Southeast Asia Business Jet Market
Aircraft
Aircraft Inspection Covers Market
Aircraft
Commercial Aircraft Landing Gear Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Sailplane Market
Aircraft
Commercial Aircraft in-Seat Power System Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market
Aircraft
Aircraft Leasing Market
Aircraft
Aviation Crew Management System Market