
 Aircraft Container & Pallet Loader Market | 2026-2036
Aircraft Container & Pallet Loader Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Container & Pallet Loader Market Analytics
FAA ground support equipment emissions standards is rebalancing the cost-of-entry calculus for new loader manufacturers seeking North American certification. TransDigm Group leverages its aerospace components ecosystem to sustain pricing power across integrated loader subsystems. Satco, Inc. anchors its position through specialized manufacturing of lightweight aluminum pallet platforms. ACL Airshop competes via extensive global rental pool networks that reduce airline capital deployment.
Aircraft container and pallet loaders are motorized or manually operated ground support vehicles designed to lift, transfer, and position unit load devices (ULDs) between aircraft cargo holds and terminal transport systems, typically handling loads from 3,500 kg to 14,000 kg depending on platform configuration. These systems employ hydraulic scissor-lift mechanisms or electric belt-drive conveyors to achieve precise vertical alignment with aircraft door sills, ensuring damage-free cargo transfer during narrow-body and wide-body turnaround operations. Automatic loaders command the premium segment as airports prioritize reduced tarmac dwell times and labor cost containment. Composite materials represent the fastest-expanding material category as operators pursue fuel savings through reduced ground equipment weight. Electric systems are displacing hydraulic architectures in new procurement decisions as operating economics shift toward total cost of ownership metrics.
FAA certification requirements, EASA CS-GSE standards, and ICAO carbon reduction frameworks collectively elevate product compliance burdens while creating preferential access corridors for certified suppliers. Ground handling companies in Europe face additional constraints from EU Green Deal operational mandates that restrict diesel-powered equipment at major hubs. Stakeholders must monitor regulatory divergence between FAA and EASA electrification timelines when allocating R&D budgets across product portfolios.
Market Dynamics
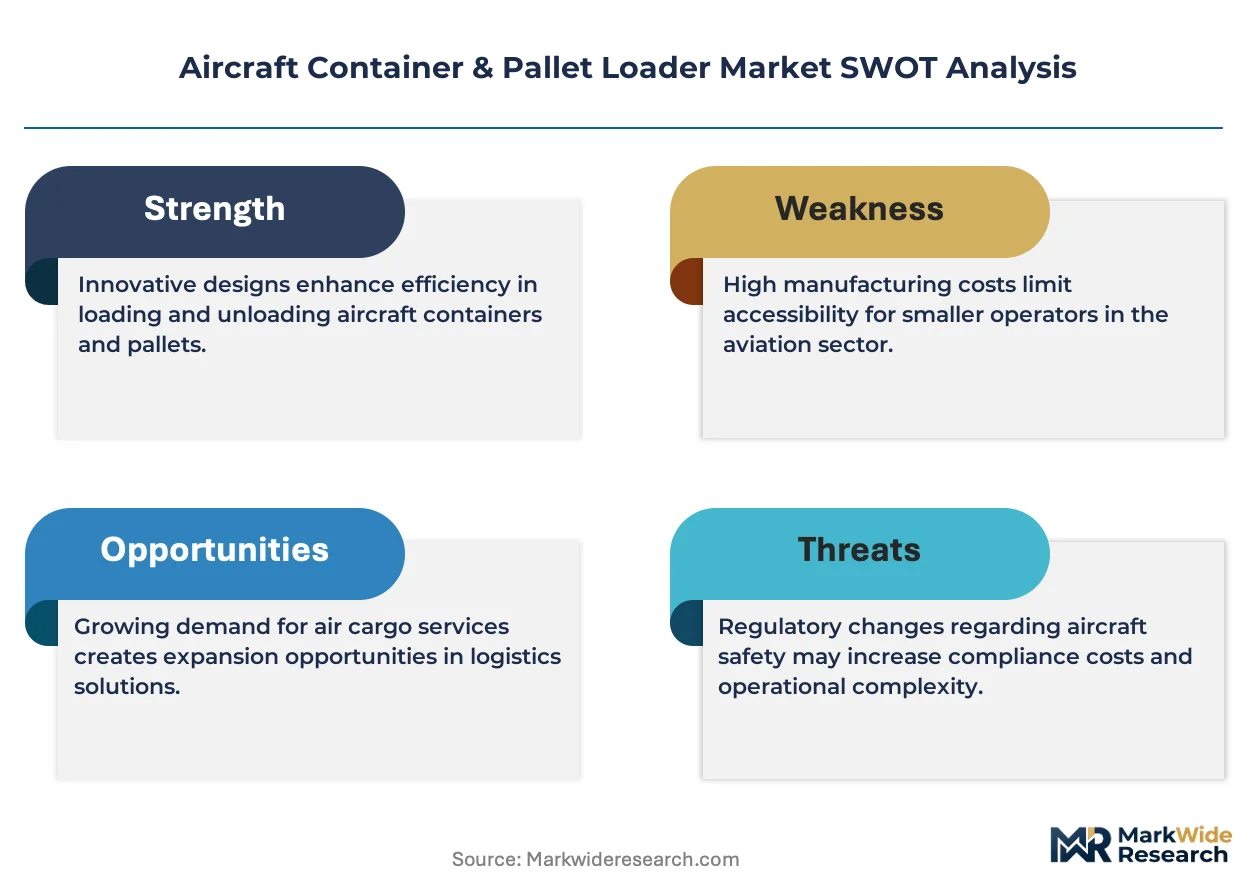
Electrification mandates from the FAA and EASA are compressing the operational economics of hydraulic loader fleets, forcing ground handlers to accelerate replacement cycles ahead of mechanical end-of-life.
Growth Catalysts
- ICAO Carbon Reduction Frameworks:International emissions targets are mandating fleet turnover at major hubs, creating replacement demand for electric architectures.
- Composite Material Platforms:Lightweight carbon-fiber and aluminum structures are reducing fuel burn during equipment repositioning, lowering total operating costs for high-cycle operators.
- India:Airport infrastructure investments under the UDAN regional connectivity scheme are multiplying cargo handling capacity requirements at tier-2 and tier-3 aviation nodes.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Cathode material processing concentrates in China, exposing electric loader manufacturers to input cost volatility and geopolitical supply risk.
- EASA CS-GSE Certification Complexity:European airworthiness standards for ground support equipment impose 18-24 month type-approval timelines that deter new market entrants.
- Manual Loader Substitution:Low-cost mechanical alternatives retain cost advantage for small-footprint operations with low daily ULD throughput.
Strategic Opportunities
- EU Green Deal Operational Mandates:Diesel equipment phase-outs at Amsterdam Schiphol, Frankfurt, and Paris Charles de Gaulle are creating captive demand for zero-emission replacements.
- Telematics-Enabled Predictive Maintenance:Sensor-integrated loaders converging with fleet management software are opening recurring revenue streams through uptime-guarantee service contracts.
- Indonesia:Underdeveloped ground handling infrastructure at expanding cargo hubs presents first-mover advantage for electric loader deployment.
Industry Challenges
- FAA-EASA Regulatory Divergence:Misaligned electrification timelines and certification reciprocity gaps force manufacturers to maintain parallel compliance pathways, inflating R&D overhead.
- Mechatronics Talent Scarcity:The integration of electric drivetrains with hydraulic legacy systems requires specialized technicians that ground handling contractors struggle to recruit and retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Container & Pallet Loader Market |
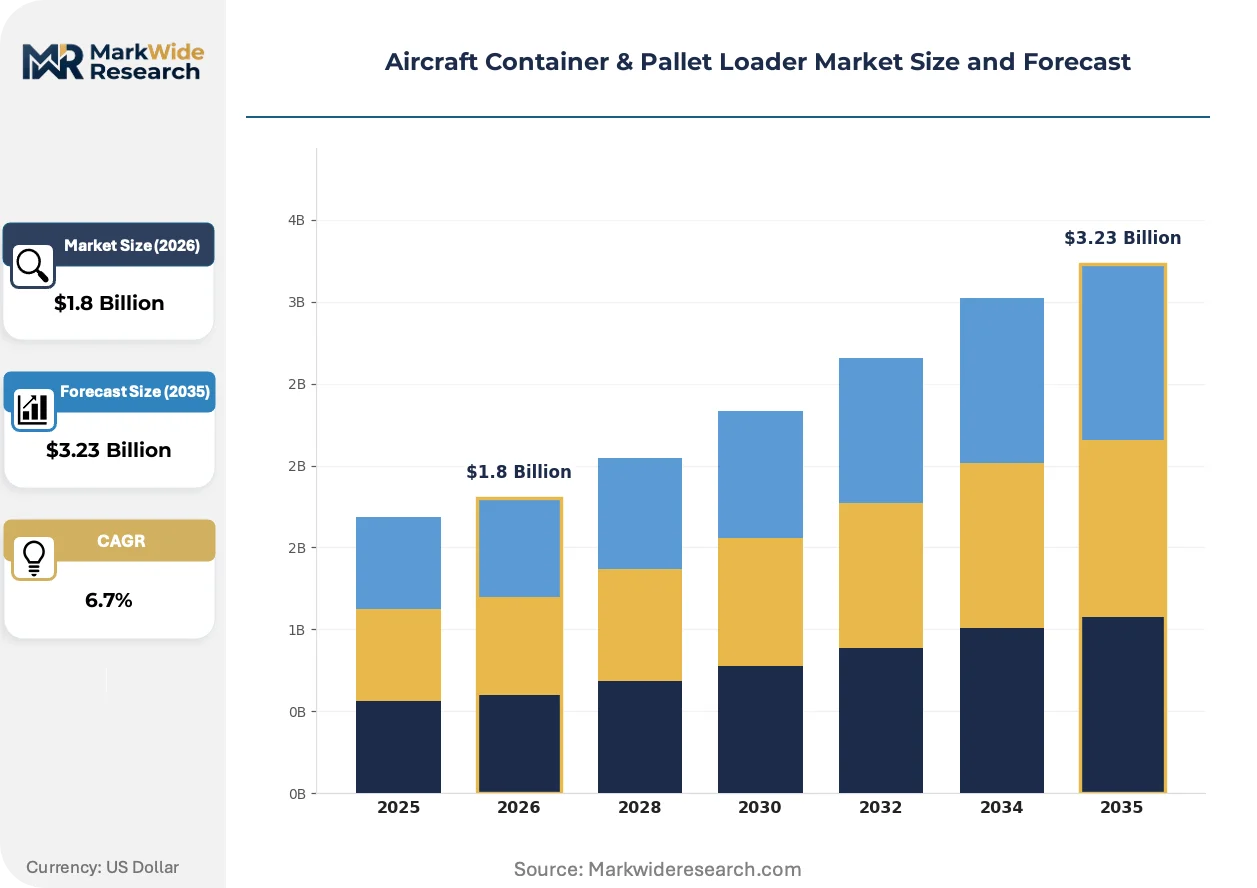
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
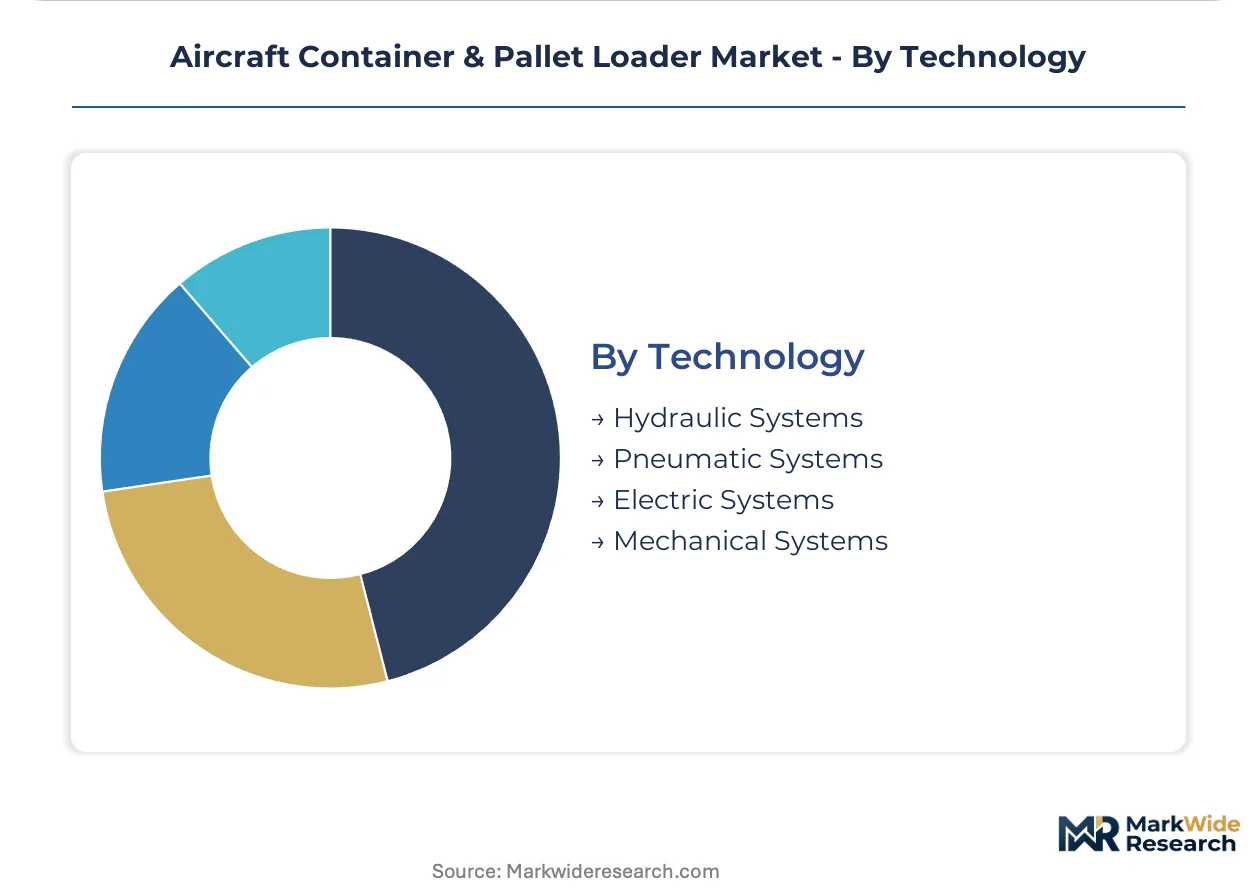
| Segmentation | Product Type: Automatic Loaders, Manual Loaders, Semi-Automatic Loaders, Hybrid Loaders Material: Aluminum, Steel, Composite Materials, Plastic End User: Aerospace OEMs, Airlines, Freight Forwarders, Ground Handling Companies Technology: Hydraulic Systems, Pneumatic Systems, Electric Systems, Mechanical Systems |
| Companies Covered | TransDigm Group, Satco, Inc., ACL Airshop, Nordisk Aviation Products, DoKaSch GmbH, VRR Aviation, Cargo Composites, PalNet GmbH, Envirotainer AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Container & Pallet Loader Market Evolving Landscape
Autonomous navigation and battery-electric propulsion are converging to redefine loader operating models, shifting value capture from equipment sales toward integrated fleet solutions.
Autonomous belt-drive loaders are automating precision alignment with aircraft cargo doors, eliminating operator error during high-stakes turnaround windows. Major ground handlers at Singapore Changi and Dubai International are piloting these systems for narrow-body fleets. The technology is automating labor cost structures while compressing tarmac dwell times to sub-25-minute benchmarks.
The FAA's updated ground support equipment emissions standards are prohibiting new diesel loader certifications for airport operators receiving federal infrastructure grants. This regulatory pressure is accelerating electric platform adoption among US regional carriers and independent ground handlers. Equipment lessors are responding by front-loading electric assets into North American rental pools.
Airlines are unbundling capital ownership from operational capability, preferring equipment-as-a-service contracts that transfer residual value risk to vendors. Ground handling companies at London Heathrow and Frankfurt are leading this shift, substituting multi-year leases for outright purchase. The model concentrates most visibly among European flag carriers facing balance-sheet constraints from post-pandemic fleet renewal obligations.
Aircraft Container & Pallet Loader Market Segmentation

Loader procurement decisions fragment across operational intensity, regulatory exposure, and fleet integration depth. Understanding these segment boundaries clarifies where electric architectures displace legacy systems and which customer types absorb premium automation features.
Product Type:
Standalone automatic loaders command integrated fleet deployments where turnaround compression justifies capital intensity, while manual configurations persist in decentralized low-throughput operations.
- Automatic Loaders:Belt-drive and scissor-lift platforms with precision alignment systems eliminate operator error during narrow-body and wide-body cargo transfers. Singapore Changi and Dubai International ground handlers are piloting autonomous variants for sub-25-minute turnaround benchmarks.
- Manual Loaders:Mechanical push-pull platforms with hydraulic assist handle 3,500-7,000 kg loads for regional carriers and cargo terminals with limited daily ULD cycles. India UDAN scheme tier-2 airports favor these for capital-constrained infrastructure builds.
- Semi-Automatic Loaders:Hybrid platforms combining powered elevation with manual horizontal positioning.
- Hybrid Loaders:Dual-mode systems switching between electric and mechanical operation for flexibility across mixed fleet environments.
Automatic loaders lead volumes today; hybrid configurations are gaining share fastest.
Material:
Material selection trades structural durability against fuel burn during equipment repositioning, with carbon-intensive hubs prioritizing weight reduction for operating cost containment.
- Composite Materials:Carbon-fiber reinforced platforms reduce tare weight by 30-40% versus steel equivalents, cutting diesel or electric consumption during frequent repositioning cycles. EU Green Deal hubs at Amsterdam Schiphol and Frankfurt mandate these for new procurement.
- Aluminum:Extruded alloy structures balance corrosion resistance with moderate weight savings for coastal and high-humidity operations.
- Steel:Conventional welded platforms dominate legacy fleet replacement cycles where acquisition cost outweighs lifetime fuel exposure.
- Plastic:Polymer-based non-structural components reduce maintenance in chemical exposure environments.
Steel retains installed base dominance; composite materials show steepest expansion trajectory.
End User:
Customer archetypes diverge sharply on ownership preference, with asset-heavy operators resisting capital deployment while service providers seek fleet flexibility.
- Ground Handling Companies:Independent contractors at London Heathrow and Frankfurt are substituting equipment-as-a-service contracts for outright purchase, transferring residual value risk to vendors amid post-pandemic balance sheet constraints.
- Airlines:Flag carriers unbundle capital ownership from operational capability, concentrating rental pool demand among European and Asia-Pacific network operators.
- Freight Forwarders:Cargo integrators prioritize throughput velocity over ownership structure at dedicated express hubs.
- Aerospace OEMs:Manufacturers specify loader configurations for greenfield delivery and MRO facility provisioning.
Ground handling companies drive current procurement volumes; freight forwarders are expanding fleet investment most aggressively.
Technology:
Propulsion architecture selection now hinges on regulatory compliance timelines rather than pure operating economics, compressing hydraulic system replacement cycles ahead of mechanical end-of-life.
- Electric Systems:Battery-electric drivetrains with lithium-ion packs and regenerative braking eliminate point-source emissions at terminal gates. FAA infrastructure grant prohibitions on new diesel certifications are accelerating US regional carrier adoption.
- Hydraulic Systems:Conventional fluid-power architectures face stranded asset risk as EASA CS-GSE standards and EU Green Deal mandates restrict diesel equipment at major European hubs.
- Pneumatic Systems:Compressed-air actuation persists in specialized cold-climate applications where battery performance degrades.
- Mechanical Systems:Purely mechanical linkages retain niche relevance for minimal-maintenance backup operations.
Hydraulic systems dominate installed base; electric architectures are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The aircraft container and pallet loader industry traces its commercial origins to post-war European aviation hubs, where mechanized cargo handling first displaced manual loading at Amsterdam Schiphol and London Heathrow. German engineering firms pioneered hydraulic scissor-lift architectures in the 1960s. Today, regulatory divergence between FAA and EASA electrification mandates is fragmenting procurement patterns across three continents.
United States
Regional carriers and independent ground handlers at Atlanta Hartsfield-Jackson and Dallas Fort Worth International are accelerating fleet turnover as FAA infrastructure grant conditions prohibit new diesel loader certifications. The FAA's updated ground support equipment emissions standards are compressing replacement cycles for hydraulic architectures. Equipment lessors are front-loading electric assets into North American rental pools to capture this captive demand.
Germany
Frankfurt Airport's ground handling contractors are substituting equipment-as-a-service contracts for outright purchase, transferring residual value risk to vendors amid post-pandemic balance sheet constraints. EASA CS-GSE certification requirements impose 18-24 month type-approval timelines that deter new market entrants. Bavaria-based manufacturers occupy the premium-tier supply position for composite-material platforms serving EU Green Deal mandates.
India
Airport infrastructure investments under the UDAN regional connectivity scheme are multiplying cargo handling capacity requirements at tier-2 and tier-3 aviation nodes in Maharashtra and Karnataka. The country's national aviation regulator aligns with ICAO carbon reduction frameworks while permitting diesel equipment at developing hubs. Delhi Indira Gandhi International anchors fleet modernization programs among ground handling companies expanding beyond metro markets.
Singapore
Changi Airport ground handlers are piloting autonomous belt-drive loaders for narrow-body fleets, automating precision alignment to compress tarmac dwell times below 25-minute benchmarks. The Civil Aviation Authority of Singapore enforces emissions standards that exceed baseline ICAO requirements. The city-state's cargo hub status concentrates demand for automatic loader architectures across Southeast Asian transshipment operations.
United Arab Emirates
Dubai International's ground handling contractors are deploying electric platforms to maintain slot access under tightening environmental operating permits issued by the General Civil Aviation Authority. The emirate's position as a global cargo transshipment node creates concentrated demand for high-cycle loader fleets. Abu Dhabi is following with parallel electrification commitments at its expanding aviation cluster.
Aircraft Container & Pallet Loader Market Competitive Landscape
The competitive structure tilts toward diversified aerospace component conglomerates with captive aftermarket channels. Vendor positioning fragments across three tiers: integrated subsystem suppliers leveraging aerospace components ecosystems, specialized manufacturing houses focused on lightweight material platforms, and rental pool operators unbundling capital ownership from operational capability. Dominant competitive moves include backward integration into composite material supply and geographic expansion through equipment-as-a-service contract structures.
Among diversified aerospace conglomerates, TransDigm Group exemplifies the integrated subsystem archetype through its components ecosystem. Specialized manufacturing houses include Satco, Inc. and Nordisk Aviation Products, which occupy positions anchored in lightweight platform fabrication. On the rental and logistics vector, ACL Airshop represents the fleet-solutions archetype through global pool network deployment. DoKaSch GmbH and PalNet GmbH sit within the German-engineering tier that historically pioneered hydraulic architectures now facing stranded asset risk.
| Leading Market Players |
|---|
| TransDigm Group |
| Satco, Inc. |
| ACL Airshop |
| Nordisk Aviation Products |
| DoKaSch GmbH |
| VRR Aviation |
| Cargo Composites |
| PalNet GmbH |
| Envirotainer AB |
| Others |
Value Network & Pricing Analysis
Certification-tier divergence between EASA CS-GSE approved systems and uncertified alternatives manifests in pricing spreads exceeding three-to-one, with premium electric architectures commanding bundled service contracts while commodity hydraulic units trade on spot procurement. This bifurcation concentrates supply chain investment toward cathode material processing capabilities in China and precision manufacturing clusters in Germany, reshaping vendor margin structures.
Pricing Analysis
Bundled equipment-as-a-service contracts versus unbundled capital purchase splits the market into recurring revenue streams and transactional spot markets. Three-tier pricing structure across premium automatic, standard semi-automatic, and economy manual levels tracks certification grade and after-sales telemetry integration. Cost compression in the hydraulic tier intensifies because EASA diesel restrictions strand legacy fleet values. Ground handling companies exhibit highest price sensitivity due to post-pandemic balance sheet constraints, while freight forwarders absorb premium pricing for throughput velocity.
Supply Chain Analysis
Mechatronics technician scarcity in Bavaria and Baden-Württemberg constrains output from German precision manufacturing hubs, while lithium-ion cell assembly concentrates in China's Yangtze River Delta and South Korea's Gyeonggi Province. Supply chains draw from carbon-fiber prepregs in Japan, aluminum extrusions in Austria, and rare-earth magnet processing in Inner Mongolia. Single-source vulnerability in cathode material supply exposes electric loader manufacturers to geopolitical disruption. Distribution runs through OEM direct sales for flag carriers and rental pool networks for independent ground handlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratchet effects, with FAA infrastructure grant conditions prohibiting new diesel certifications and forcing accelerated replacement cycles regardless of mechanical condition.
For Market Incumbents: Acquire composite material fabrication capabilities to secure lightweight platform supply against EU Green Deal procurement mandates. Incumbent loader manufacturers must consolidate telematics software stacks to defend service contract margins from autonomous navigation specialists. EASA CS-GSE certification reciprocity gaps threaten market access; parallel compliance investment is essential. For New Entrants and Emerging Players: Enter via Indonesia's underdeveloped ground handling infrastructure, where first-mover electric deployment captures cargo hub expansion before incumbent rental pools establish presence. Battery-electric architectures with modular battery swapping address archipelago logistics constraints. Partner with regional Indonesian carriers for pilot deployments rather than competing for Jakarta slot access. For Investors and Strategic Acquirers: Consolidation pressure builds where EASA 18-24 month type-approval timelines deter new entrants and concentrate share among certified suppliers. Long-term viability favors vendors with captive aftermarket channels and composite material backward integration. Watch FAA-EASA regulatory divergence resolution as inflection signal; alignment would flatten certification premiums while sustained divergence entrenches dual-compliance specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Sensor-integrated loaders at Singapore Changi enable predictive maintenance service contracts. |
| Composite Material Backward Integration | Carbon-fiber platform manufacturing in Germany secures EU Green Deal procurement preference. |
| Equipment-as-a-Service Launch | London Heathrow ground handlers substitute leases for purchase, transferring residual value risk. |
| Autonomous Navigation Partnership | Dubai International pilots eliminate operator error during sub-25-minute turnaround windows. |
| Indonesian Market Entry | First-mover electric deployment captures cargo hub expansion before rental pool saturation. |
Research Methodology
Bottom-up ground handler fleet modeling reconciled against top-down OEM shipment tracking forms the analytical core of this study. Primary interviews with ground handling procurement directors, airline fleet planners, airport authority engineering officers, and electric drivetrain component suppliers combined with secondary validation from FAA certification databases, EASA CS-GSE type-approval records, ICAO carbon reduction framework documentation, and customs trade flow data. Triangulation across these sources reconciles equipment deployment patterns with manufacturer output.
Input-output matrices map electric and hydraulic propulsion architectures against product type, material composition, end-user category, and geographic regulatory cluster across the analysis window. Segmentation dimensions include automatic versus manual platform configuration, composite versus steel material grade, ground handling company versus airline ownership model, and battery-electric versus hydraulic technology. CAGRs derive from installed base turnover rates and replacement cycle compression under emissions mandates. Industry-specific forecast inputs incorporate lithium-ion battery cost curves and EASA certification queue lengths.
The model holds under sustained regulatory enforcement of FAA infrastructure grant conditions and EASA diesel restrictions; deviation in electrification timeline alignment or cathode material supply disruption would shift replacement cycle assumptions. Forecasts reflect these boundary conditions and assumption sets. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
America Freighter Aircraft Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Commercial Aircraft Market
Aircraft
Aircraft Hangar Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
Attack Helicopter Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
Single-Seat Gyrocopter Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Europe Military Helicopters Market
Aircraft
North America General Aviation Market
Aircraft
Japan Aerospace and Defense Market
Aircraft
Aircraft Autopilot System Market
Aircraft
GCC Business Jet Market
Aircraft
Aircraft Cables Market