
 Global Air Insulated Switchgear Market | 2026-2036
Global Air Insulated Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Global Air Insulated Switchgear Market Intelligence
A capital-intensity divergence between integrated European manufacturers and regional Asian assemblers is unwinding competitive dynamics in air insulated switchgear. ABB leverages its vacuum interruption technology leadership to sustain premium positioning across medium voltage installations. Siemens anchors its footprint through localized production hubs that compete on delivery speed for utility tenders. Schneider Electric differentiates via digital switchgear platforms that extend lifecycle services beyond hardware sales.
Air insulated switchgear comprises electrical switching and protection equipment where atmospheric air serves as the primary dielectric medium between live conductors and grounded enclosures, typically rated from 1 kV through 800 kV depending on configuration and clearance engineering. The assembly functions to isolate fault currents, distribute power across bus sections, and protect downstream infrastructure in substations and industrial facilities. Medium voltage AIS dominates installed base volumes across transmission networks, while vacuum interruption technology leads new order intake due to its elimination of sulfur hexafluoride handling. Smart grid systems represent the fastest-growing application dimension as grid operators demand interoperable monitoring and remote-operated disconnectors.
The IEC 62271 series governs switchgear design validation and type testing protocols, while the EU F-Gas Regulation progressively restricts SF6 deployment in new installations, accelerating air and vacuum-based alternatives. India's Central Electricity Authority mandates BIS certification for imported switchgear, creating compliance barriers that favor domestic manufacturers like Larsen & Toubro. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving grid codes reshape sourcing strategies for insulation components and interrupting mediums.
Market Dynamics
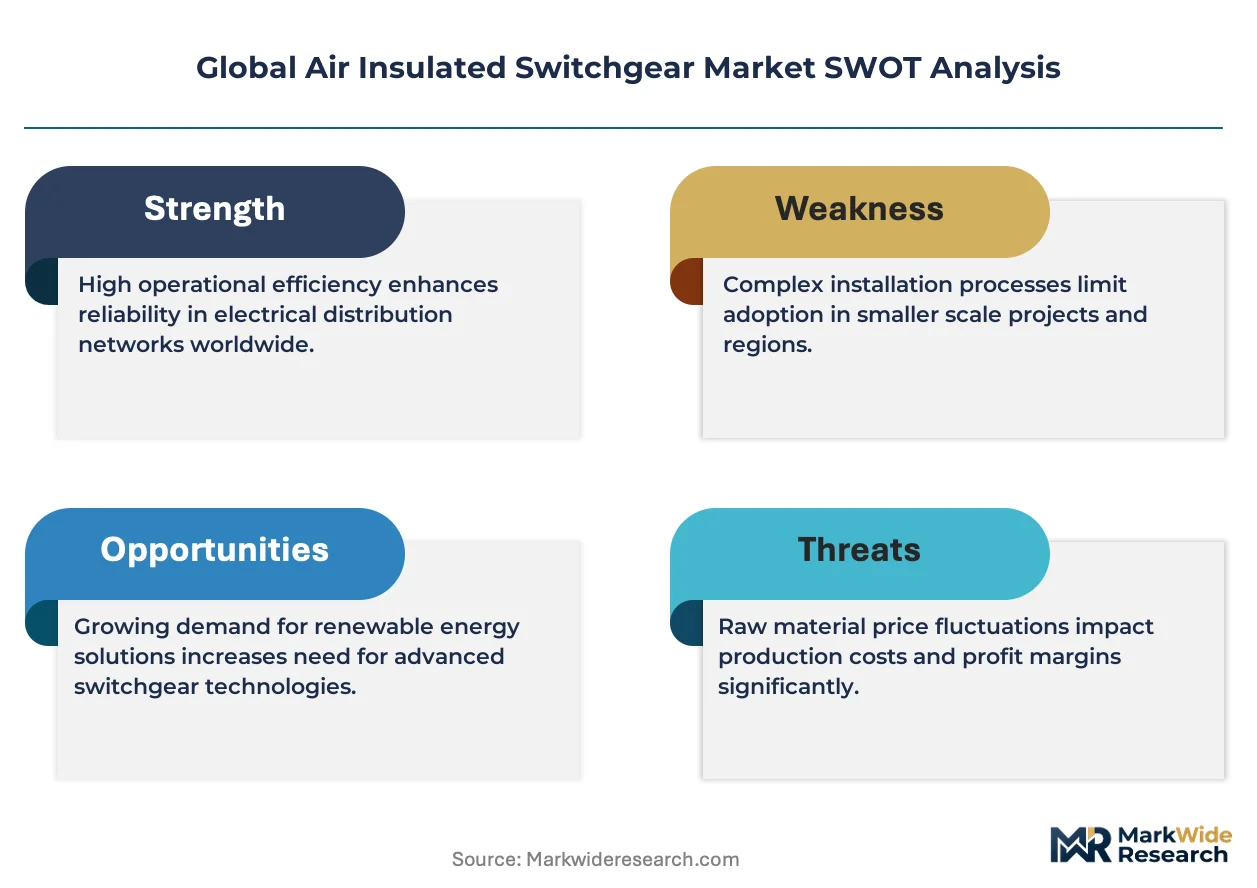
Vacuum interruption technology is fragmenting traditional sulfur hexafluoride dependencies across transmission infrastructure, forcing utilities to reengineer substation architectures around air-based dielectric clearances and modular panel designs.
Growth Catalysts
- EU F-Gas Regulation:Progressive phase-down mandates for SF6 in new switchgear installations are accelerating utility procurement of vacuum-interrupted AIS panels across European transmission networks.
- Utility-scale solar deployment:Southeast Asian state utilities are expanding high-voltage substation capacity to interconnect gigawatt-scale photovoltaic farms with national grids.
- Domestic manufacturing incentives:India's PLI scheme for electrical equipment is channeling capital toward localized AIS panel production, reducing import dependency for state transmission utilities.
Market Restraints
- Copper and electrical steel volatility:Raw material price swings for conductor bars and magnetic cores compress assembler margins on fixed-price utility tenders.
- High-voltage clearance engineering:Air insulation at 420 kV and above requires substantial physical footprint expansion, limiting urban substation retrofit feasibility.
- SF6 legacy asset lock-in:Existing gas-insulated installations carry decades of operational life, delaying replacement cycles despite regulatory pressure.
Strategic Opportunities
- Digital switchgear convergence:Integration of IEC 61850-compliant monitoring with vacuum interruption creates lifecycle service revenue streams beyond hardware margins.
- Rural electrification corridors:India's Deen Dayal Upadhyaya Gram Jyoti Yojana mandates medium-voltage distribution expansion into previously unserved districts.
- Carbon-border adjustment alignment:EU CBAM scope expansion toward electrical equipment incentivizes low-carbon AIS sourcing for export-oriented manufacturers.
Industry Challenges
- IEC 62271 type-testing bottlenecks:Certification timelines for new voltage classes extend 18-24 months, delaying product launches and tender participation.
- Legacy protocol integration:Smart grid retrofit projects require bridging proprietary SCADA systems with open-architecture monitoring platforms.
- Specialized field engineering scarcity:Vacuum interrupter maintenance and gas-free commissioning demand technician training programs that outpace workforce development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Air Insulated Switchgear Market |
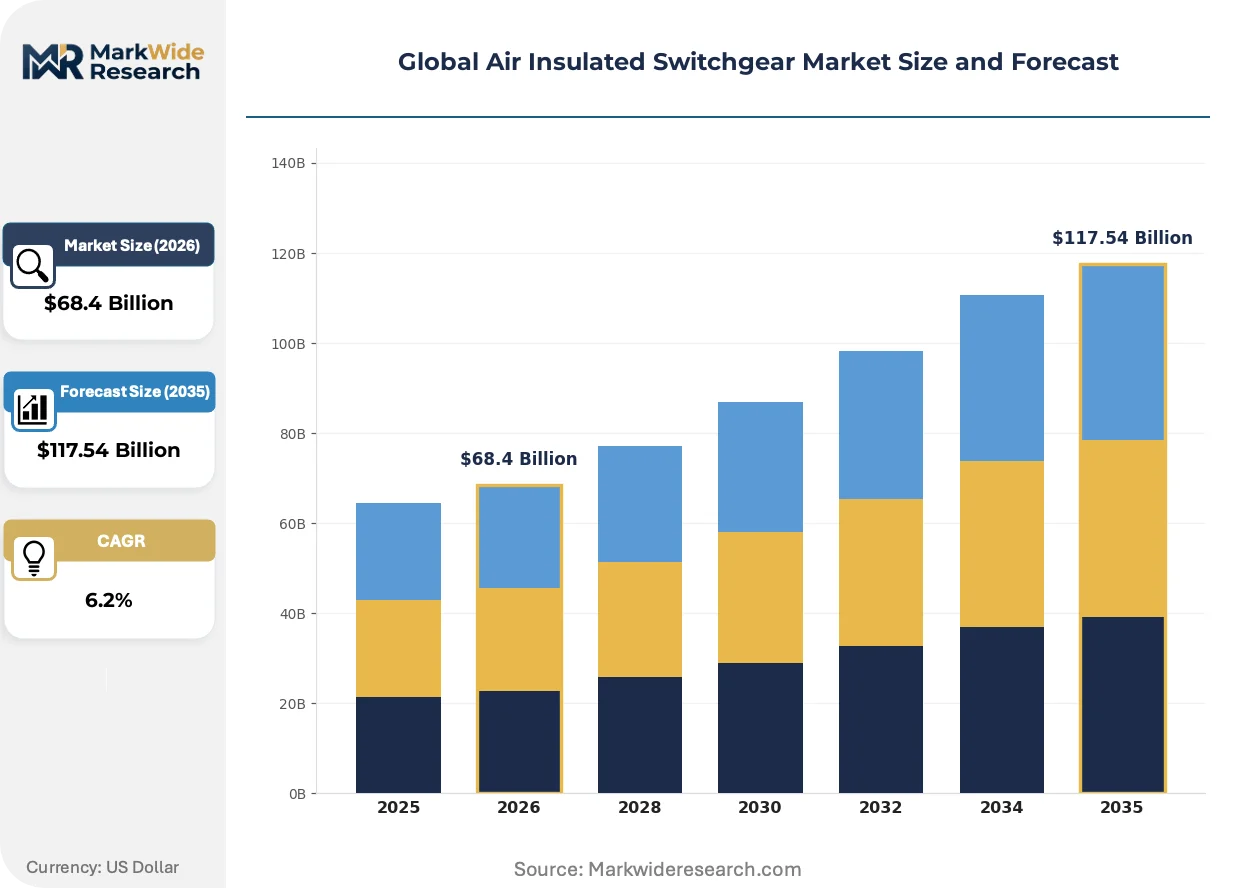
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage Technology: Vacuum Interruption, SF6 Interruption, Air Blast, Oil Interruption Application: Power Generation, Transmission Networks, Renewable Installations, Smart Grid Systems End User: Utilities, Independent Power Producers, Grid Operators, Industrial Facilities |
| Companies Covered | ABB, Siemens, Schneider Electric, Hitachi Energy, Eaton Corporation, Mitsubishi Electric, General Electric, Toshiba Corporation, Larsen & Toubro Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Air Insulated Switchgear Market Strategic Shifts & Innovations
Interoperability mandates and material substitution pressures are converging to reshape how switchgear is specified, commissioned, and monetized across voltage classes.
Vacuum interruption technology is fragmenting the historical dominance of SF6-dependent circuit breakers in medium-voltage applications. Distribution utilities in Germany and France are specifying vacuum-based 36 kV panels for new urban substations, compressing the addressable market for gas-handling service providers and reconfiguring maintenance contract structures around solid-state arc quenching.
The EU F-Gas Regulation's 2024 tightening of SF6 leak thresholds is compelling transmission operators to accelerate air-insulated alternatives for 145 kV and 245 kV ratings. German network operators now face mandatory reporting thresholds that render conventional gas-insulated switchgear economically unviable for greenfield projects, shifting procurement specifications toward extended clearance designs.
Lifecycle service unbundling is disrupting traditional hardware-plus-maintenance bundling in utility procurement. Indian state electricity boards are separating capital equipment purchase from decade-long AMC contracts, enabling specialized digital service providers to compete for monitoring and predictive maintenance revenues independent of original panel manufacturers.
Global Air Insulated Switchgear Market Segmentation
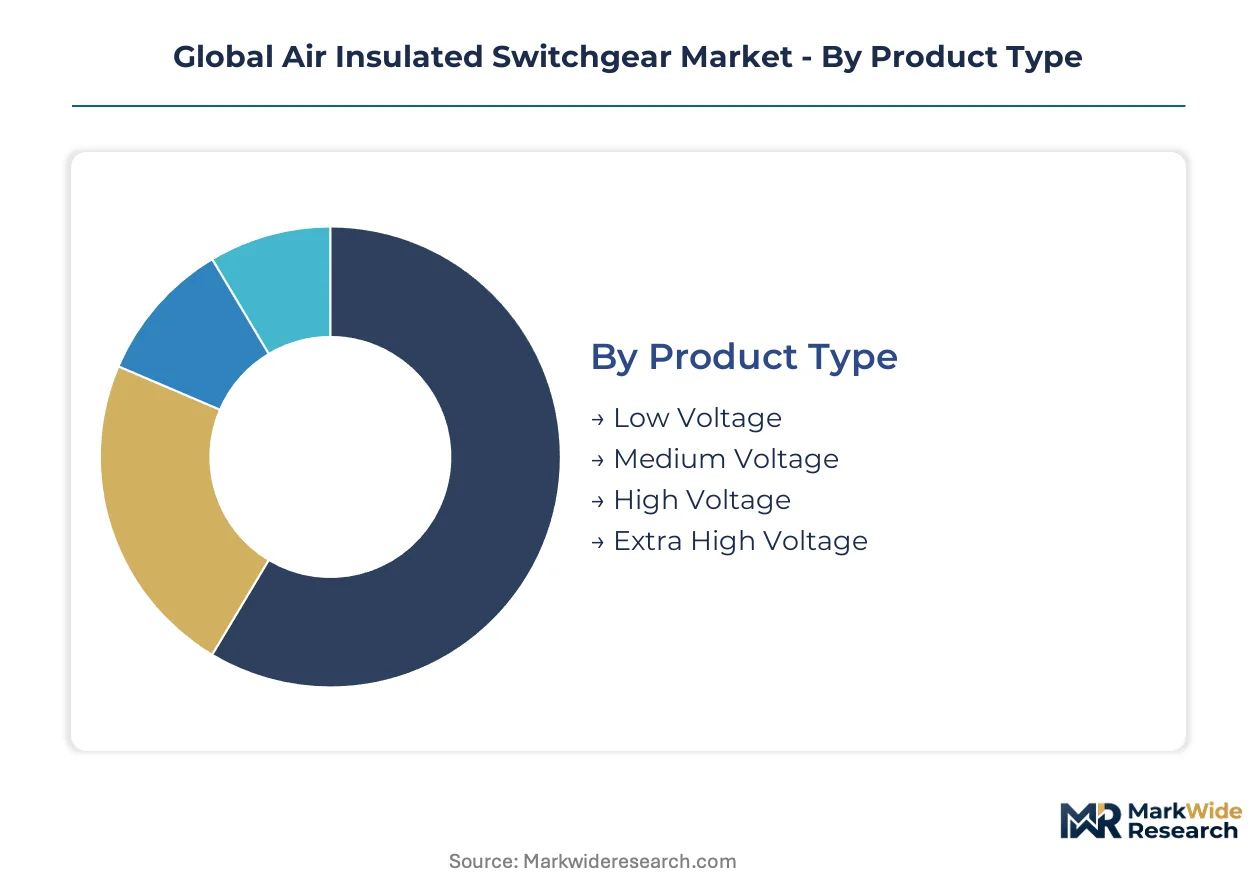
Air insulated switchgear procurement channels diverge sharply by voltage class and end-use sophistication. Specification committees at transmission utilities prioritize different performance attributes than industrial facility managers, fragmenting go-to-market pathways for manufacturers.
Product Type:
Channel economics favor different voltage tiers across tender types and direct sales routes. Low and medium voltage panels flow through electrical distributors and EPC contractors, while high and extra high voltage configurations demand direct utility engagement with extended qualification cycles.
- Low Voltage:Panels rated up to 1 kV serve commercial buildings and light industrial feeder circuits. Indian state distribution companies procure these through centralized tender portals for rural electrification schemes, compressing margin structures through volume aggregation.
- Medium Voltage:The 1 kV to 52 kV range accommodates distribution substations and industrial switchyards. German utilities specify vacuum-interrupted 36 kV panels for urban substation retrofits, bypassing SF6 handling complexities under tightened EU F-Gas Regulation thresholds.
- High Voltage:Ratings from 52 kV to 245 kV require extended air clearance engineering. Grid operators in Southeast Asia deploy these for utility-scale solar interconnection, where physical footprint constraints matter less than in dense European cities.
- Extra High Voltage:Systems above 245 kV demand custom substation architecture. Transmission utilities in India specify these for interstate corridor projects under CEA-mandated BIS certification protocols.
Medium voltage dominates installed base. Extra high voltage is where expansion concentrates as national grids accommodate bulk renewable transfers.
Technology:
Cost tiers separate mature interruption methods from emerging vacuum and air-blast alternatives that command premium positioning through regulatory compliance advantages.
- Vacuum Interruption:Sealed vacuum interrupters eliminate arc quenching media handling. French and German distribution networks now specify these exclusively for new 36 kV installations, displacing SF6-dependent alternatives under progressive phase-down mandates.
- SF6 Interruption:Sulfur hexafluoride remains entrenched in legacy high-voltage assets. Existing installations carry decades of operational life, delaying replacement despite EU F-Gas Regulation tightening leak reporting thresholds.
- Air Blast:Compressed air interruption serves specialized high-current applications. Limited new deployment occurs outside specific utility maintenance protocols.
- Oil Interruption:Mineral oil quenching persists in aging transformer-circuit breaker combinations. Environmental containment requirements accelerate retirement schedules.
SF6 interruption retains legacy lock-in. Vacuum interruption is climbing the fastest as procurement specifications rewrite around gas-free alternatives.
Application:
Customer maturity varies across application dimensions, with smart grid deployments demanding integrated monitoring capabilities that traditional transmission specifications rarely require.
- Power Generation:Thermal and hydro plant switchyards require synchronized protection coordination. Indian IPPs source medium voltage AIS through domestic manufacturing incentives under the PLI scheme for electrical equipment.
- Transmission Networks:High-voltage substations form the backbone of national grid infrastructure. State transmission utilities in India modernize aging installations with indigenously manufactured panels, reducing import dependency.
- Renewable Installations:Solar and wind farms demand compact, modular switchgear for collection point aggregation. Southeast Asian utilities specify these for gigawatt-scale photovoltaic interconnection projects.
- Smart Grid Systems:IEC 61850-compliant monitoring enables remote operation and predictive maintenance. German distribution operators separate capital equipment from decade-long service contracts, opening revenue streams for digital specialists.
Transmission networks dominate installed base. Smart grid systems represent the steepest expansion trajectory as grid codes mandate interoperable monitoring.
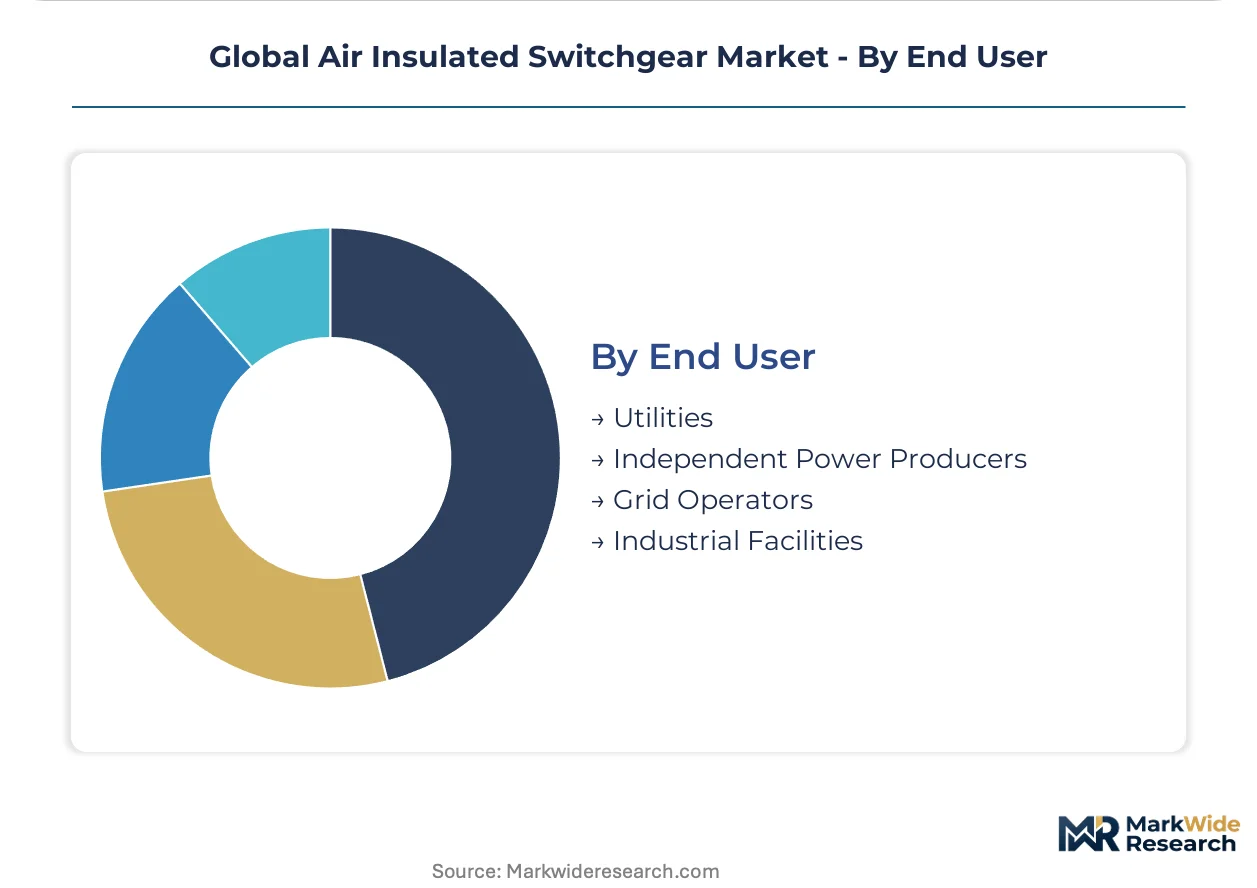
End User:
Procurement authority concentrates differently across user categories, with utilities retaining specification control while industrial facilities delegate to EPC integrators.
- Utilities:State-owned transmission and distribution companies drive volume procurement through centralized tenders. India's CEA mandates BIS certification for imported equipment, creating compliance barriers that favor domestic manufacturers.
- Independent Power Producers:Merchant generation facilities prioritize delivery speed and lifecycle cost. These developers source through EPC contractors with established utility relationships.
- Grid Operators:Transmission system operators manage interstate power flows. German operators face mandatory SF6 reporting that renders gas-insulated switchgear economically unviable for greenfield projects.
- Industrial Facilities:Manufacturing plants and data centers specify medium voltage protection for captive substations. Procurement flows through electrical distributors rather than direct manufacturer engagement.
Utilities dominate installed base. Grid operators are where specification disruption concentrates as regulatory pressure rewrites procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German utilities command premium pricing for vacuum-interrupted panels under EU F-Gas Regulation mandates, while Indian state tenders compress margins through volume aggregation and domestic manufacturing incentives. This pricing-power asymmetry shapes capital allocation across manufacturing footprints.
Germany
Distribution network operators specify vacuum-based 36 kV installations exclusively for urban substation retrofits. The EU F-Gas Regulation's 2024 leak reporting thresholds render SF6-dependent switchgear economically unviable for greenfield projects. Siemens anchors manufacturing in Bavaria to compete on delivery speed for utility tenders.
India
State transmission utilities modernize aging substations with domestically manufactured AIS panels under PLI scheme incentives. The Central Electricity Authority mandates BIS certification for imported equipment, creating compliance barriers that favor Larsen & Toubro. Production clusters concentrate in Maharashtra and Gujarat for western grid corridor projects.
United States
Independent power producers prioritize delivery speed and lifecycle cost for merchant generation facilities. FERC interconnection standards shape procurement specifications for high-voltage substation expansions. Texas and California lead deployment for utility-scale solar and data center load growth.
France
Distribution utilities specify vacuum interruption for new 36 kV installations, displacing gas-handling alternatives under progressive phase-down mandates. EDF's grid modernization programs channel procurement toward extended clearance designs. Industrial clusters around Lyon support specialized panel assembly for nuclear and renewable interconnection.
Japan
Tokyo Electric Power and regional utilities deploy medium voltage AIS for earthquake-resilient substation architectures. METI efficiency standards accelerate retirement of oil-interruption legacy assets. Manufacturing concentrates in the Chubu region around Nagoya for precision-engineered vacuum interrupter components.
Global Air Insulated Switchgear Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across voltage classes and geographies. Integrated European manufacturers leverage vacuum interruption R&D to sustain premium positioning, while regional Asian assemblers compete on delivery speed and localized compliance. Three archetypes dominate: full-stack technology owners, regional production specialists, and digital service unbundlers. Competitive moves concentrate on strategic partnerships for smart grid interoperability and capacity expansion into PLI-subsidized manufacturing zones.
Among integrated technology owners, ABB and Siemens exemplify divergent paths to market position. ABB leverages its vacuum interruption heritage to anchor premium-tier specifications across European transmission tenders. Siemens occupies a position as the production-localization archetype, with manufacturing hubs calibrated to utility delivery timelines. Schneider Electric represents the digital convergence vector, with switchgear platforms extending toward lifecycle service revenues beyond hardware margins.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Hitachi Energy |
| Eaton Corporation |
| Mitsubishi Electric |
| General Electric |
| Toshiba Corporation |
| Larsen & Toubro Limited |
| Others |
Cost & Logistics Intelligence
Vacuum interrupter substitution for sulfur hexafluoride-dependent arc quenching systems is redrawing procurement geography while compressing configured-to-order premiums across European transmission tenders. This material transition simultaneously elevates sourcing concentration around precision-ceramic manufacturing clusters and erodes legacy gas-handling service margins that once anchored project pricing.
Pricing Analysis
Configured-to-order pricing for 245 kV extra high voltage installations commands substantial premiums over standardized medium voltage panel configurations. Three-tier pricing structure across premium, standard, and economy levels reflects IEC 62271 certification grade and vacuum interrupter provenance rather than brand heritage alone. Cost compression in economy-tier rural electrification tenders is intensifying because Indian state utilities aggregate volumes through centralized procurement portals. Industrial facility managers demonstrate highest price sensitivity, while German transmission system operators prioritize regulatory compliance over unit economics.
Supply Chain Analysis
Extended lead times for IEC type-tested vacuum interrupters now stretch 18-24 months, forcing EPC contractors to pre-position inventory ahead of tender awards. Manufacturing concentration centers on Germany, Japan, and India for precision ceramic-metal seal assemblies, with copper conductor bars and electrical steel laminations drawing from Chinese and South Korean smelters. Single-source vulnerability in specialized vacuum interrupter ceramics creates procurement risk for non-integrated assemblers. Distribution runs through direct utility engagement for high voltage configurations and electrical distributor networks for low and medium voltage commercial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IEC 61850 interoperability mandates are transforming switchgear from capital hardware into platform-enabled service ecosystems, with digital lifecycle unbundling creating new monetization layers beyond panel sales.
For Market Incumbents: Compound technology leadership in vacuum interruption through captive ceramic-metal seal manufacturing capacity in Bavaria or Nagoya clusters. Consolidate position by acquiring specialized digital monitoring providers before service contracts separate from hardware procurement. The EU F-Gas Regulation's progressive tightening represents an existential threat to SF6 service revenue streams that must be offset through predictive maintenance platform subscriptions. For New Entrants and Emerging Players: BIS certification fast-track for medium voltage vacuum panels unlocks participation in India's PLI-subsidized state transmission tenders. Target rural electrification corridors under Deen Dayal Upadhyaya Gram Jyoti Yojana mandates where domestic content requirements disadvantage unqualified imports. Partner with established EPC contractors possessing utility relationships rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European gas-handling service providers facing stranded revenue as SF6 installations age out. Long-term viability hinges on successful pivot toward digital monitoring and predictive maintenance recurring revenue. Watch for IEC 62271-100 revision announcements as inflection indicators accelerating vacuum interruption specification mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Vertical Integration into Vacuum Interrupter Ceramics | Captive ceramic-metal seal production secures supply continuity for 245 kV panel assembly against 18-month lead times. |
| Digital Platform Licensing | IEC 61850-compliant monitoring subscriptions extract recurring revenue from German utility asset management contracts. |
| PLI-Aligned Manufacturing Expansion | Maharashtra and Gujarat production hubs qualify for Indian domestic content incentives in state transmission tenders. |
| Extended Clearance Engineering Partnership | Collaboration with substation architects enables 420 kV urban retrofit feasibility despite footprint constraints. |
| Technician Certification Programs | Gas-free commissioning training addresses workforce scarcity blocking vacuum interrupter deployment velocity. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, EPC contractor procurement leads, switchgear manufacturing executives, and aftermarket service directors; and secondary validation through IEC standards documentation, FERC interconnection filings, EU regulatory impact assessments, and Indian CEA tender archives. Bottom-up triangulation across project-level procurement data and top-down reconciliation with national grid investment programs anchored volume estimates.
Across the projection horizon, the analytical framework modeled demand through voltage class, interruption technology, application dimension, and end-user procurement authority. CAGRs derived from utility capital expenditure trajectories, renewable interconnection queue velocities, and regulatory phase-down schedules rather than extrapolated historical shipments. Forecast inputs incorporated SF6 banked inventory retirement curves and vacuum interrupter manufacturing capacity expansion announcements.
The analysis sits within stated boundaries; outcomes outside sustained EU F-Gas Regulation enforcement or accelerated Indian PLI scheme disbursement would require recalibration. Forecasts reflect documented assumptions regarding grid code harmonization timelines and raw material price stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
Optical Current Transformer Market
Electrical Power Equipment
Motor Generator Set Market
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
Alternating Current (AC) Electric Drives Market
Electrical Power Equipment
Industrial Power Supply Market
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
North America Gas Insulated Switchgear Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
Middle East and Africa High Voltage Switchgear Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
Busway-Bus Duct Market
Electrical Power Equipment
AC Drives Market