
 Motor Generator Set Market | 2026-2036
Motor Generator Set Market Size, Share, and Industry Trends Forecast 2026-2036
Motor Generator Set Market Foresight
EPA Tier 4 Final is shifting the cost-of-entry calculus for diesel motor generator set manufacturers, forcing aftertreatment integration that adds substantial engineering expense. Cummins Inc. anchors North American supply through its captive engine architecture and extensive service network. Caterpillar Inc. leverages vertical integration from engine block to switchgear, sustaining margin control across the product stack. Mitsubishi Heavy Industries competes in the high-megawatt utility segment with advanced gas turbine alternator packages.
A motor generator set combines a prime mover—typically a reciprocating engine or turbine—with an electrical generator mounted on a common shaft or coupled through a gearbox, converting mechanical energy into electrical output at specified voltage and frequency for industrial, commercial, or standby service. Standby units dominate revenue share across healthcare and data center installations where regulatory mandates require emergency power availability, while continuous-duty natural gas configurations are gaining traction in distributed generation and microgrid architectures. The industrial end user segment occupies the deepest margin pool due to custom engineering requirements and long-term service contracts.
FERC interconnection standards, EPA emissions frameworks, and ISO 8528 performance classifications collectively shape product certification pathways and market access conditions for motor generator set suppliers. The EU Green Deal and associated F-Gas Regulation are accelerating natural gas and biofuel engine development as diesel faces progressive restriction in European commercial applications. Stakeholders must monitor evolving carbon border mechanisms and grid modernization timelines to align product portfolios with shifting procurement criteria across utility and industrial accounts.
Market Dynamics
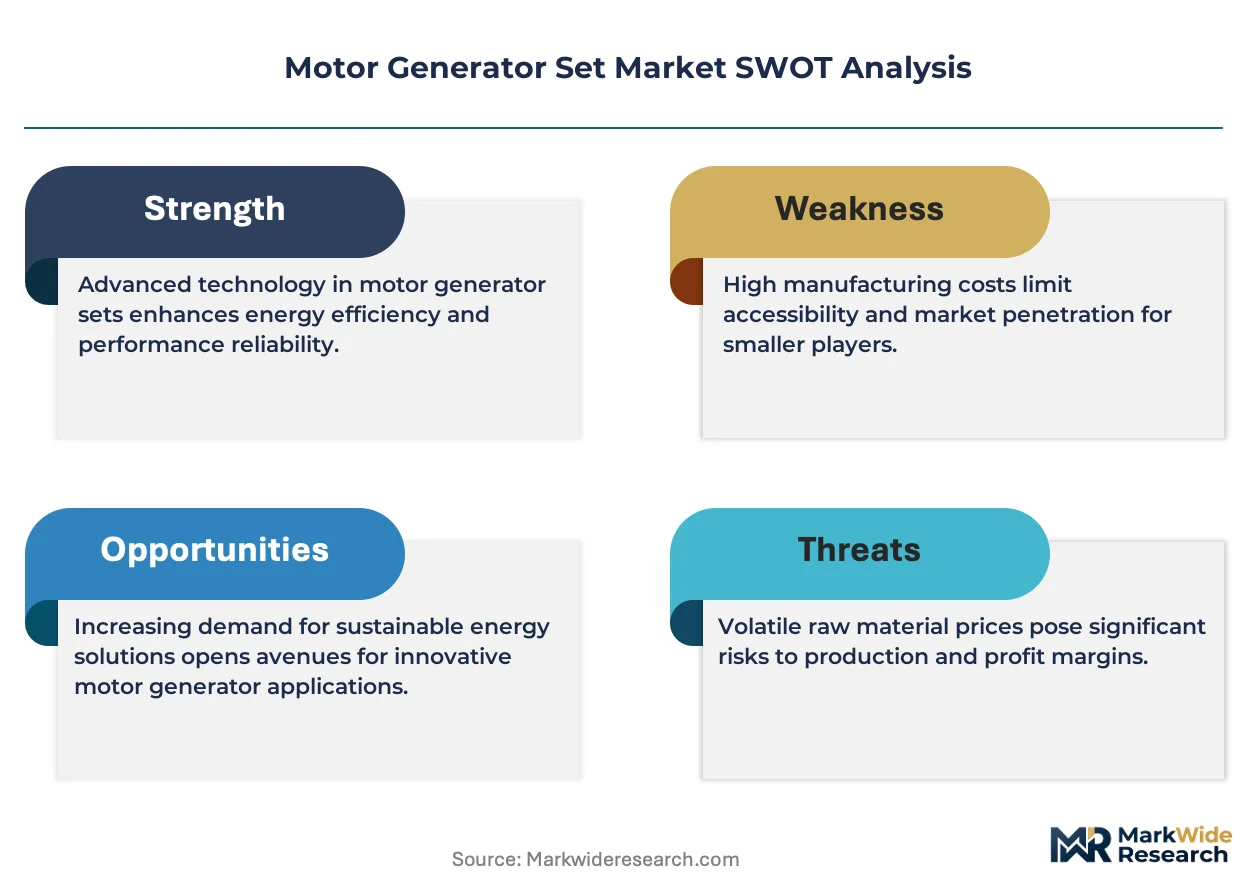
EPA Tier 4 Final emissions mandates are forcing diesel motor generator set manufacturers to absorb substantial aftertreatment engineering costs, compressing margins and accelerating natural gas alternatives.
Growth Catalysts
- Data center expansion:Hyperscale cloud facilities in Northern Virginia, Frankfurt, and Singapore are mandating continuous-duty motor generator sets for uninterruptible power architecture.
- Grid instability in India:Manufacturing clusters across Gujarat and Maharashtra are accelerating procurement as CEA regulations tighten reliability standards for critical infrastructure.
- ISO 8528 certification:Healthcare facilities globally are requiring certified standby units for emergency power compliance, locking in replacement cycles.
Market Restraints
- Aftertreatment cost inflation:Diesel particulate filters and selective catalytic reduction systems add substantial material cost to EPA Tier 4 Final compliant units.
- Engine supply concentration:Captive engine production by dominant manufacturers limits third-party alternator packagers in North America and Europe.
- Electrochemical substitution:Lithium-ion battery energy storage systems are capturing short-duration backup applications below 4-hour runtime requirements.
Strategic Opportunities
- Microgrid deployment:Industrial campuses in Texas and California are integrating natural gas motor generator sets with solar PV for islanding capability.
- Biofuel engine development:EU Green Deal incentives are accelerating HVO-compatible prime mover platforms for commercial installations.
- Remote monitoring services:Predictive maintenance subscriptions are creating recurring revenue streams alongside equipment sales.
Industry Challenges
- Emissions calibration complexity:Field technicians require specialized training on aftertreatment diagnostics and regeneration protocols.
- Multi-standard certification:Manufacturers must navigate concurrent EPA, EU Stage V, and India CEV norms for export market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Motor Generator Set Market |
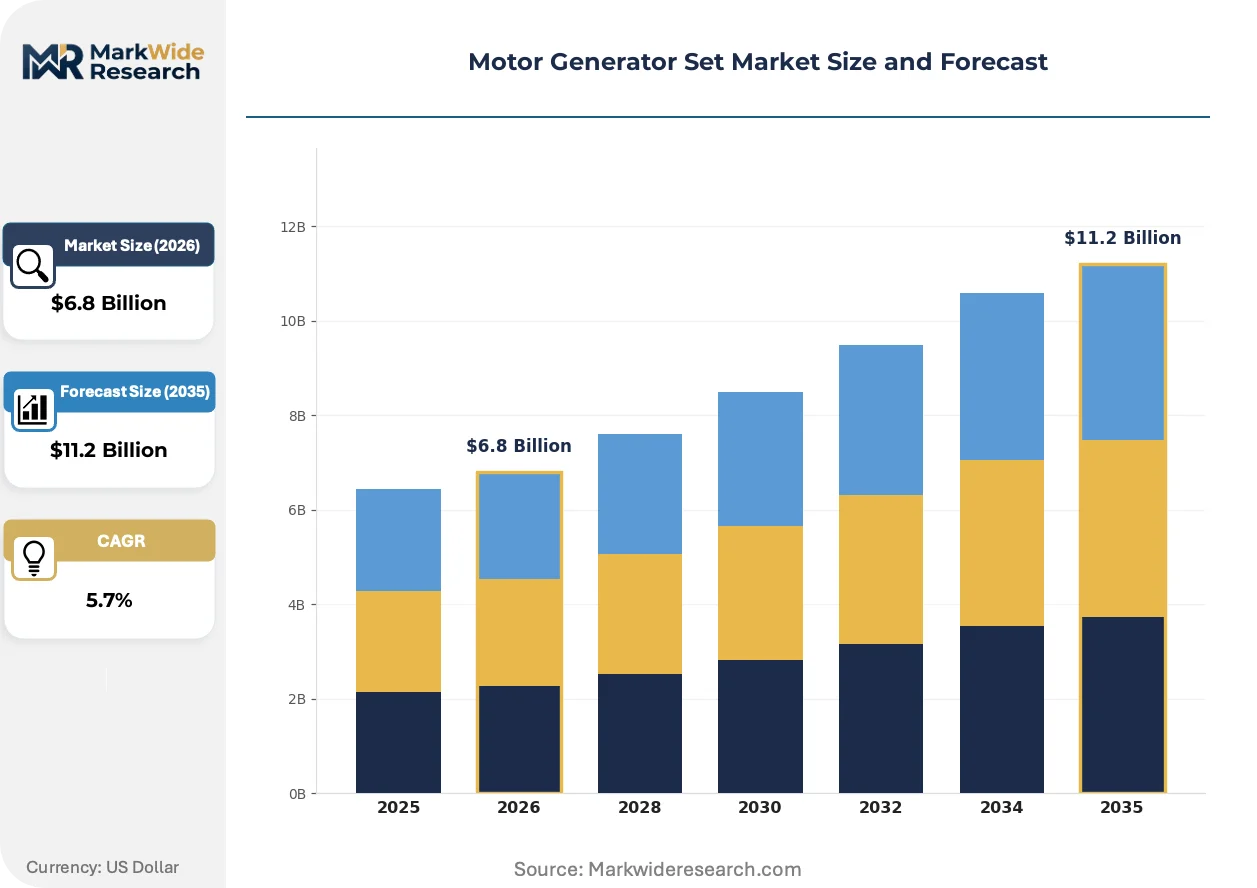
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Standby, Continuous, Marine Fuel Type: Diesel, Natural Gas, LPG, Biofuel End User: Residential, Commercial, Industrial, Utilities Application: Power Generation, Backup Power, Remote Location, Emergency Services |
| Companies Covered | Caterpillar Inc., Cummins Inc., Generac Holdings Inc., Kohler Co., Mitsubishi Heavy Industries, ABB Ltd., General Electric, Siemens AG, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Motor Generator Set Market Shifts & Advancements
Digital integration and fuel flexibility are converging to redefine motor generator set architecture. Real-time condition monitoring, alternative fuel compatibility, and modular power blocks are compressing traditional equipment lifecycles.
Natural gas prime movers with lean-burn combustion architecture are overtaking diesel configurations in continuous-duty distributed generation applications. Data center operators in Ashburn, Dublin, and Singapore are specifying gas-fired units for baseload microgrids. This fuel switch is overtaking diesel's historical dominance in installations above 2 MW.
EU F-Gas Regulation and associated carbon border adjustments are tightening emissions accountability for imported equipment. Manufacturers serving European industrial accounts must document lifecycle carbon intensity. Gas turbine alternator packages and biofuel-ready reciprocating engines are capturing preference in German and Dutch utility tenders.
Buyers are unbundling long-term service contracts from initial equipment procurement. Large industrial accounts in India and Southeast Asia are negotiating separate maintenance agreements with third-party providers. This fragmentation is most visible in pharmaceutical and semiconductor manufacturing clusters where specialized uptime guarantees override manufacturer service捆绑.
Motor Generator Set Market Segmentation
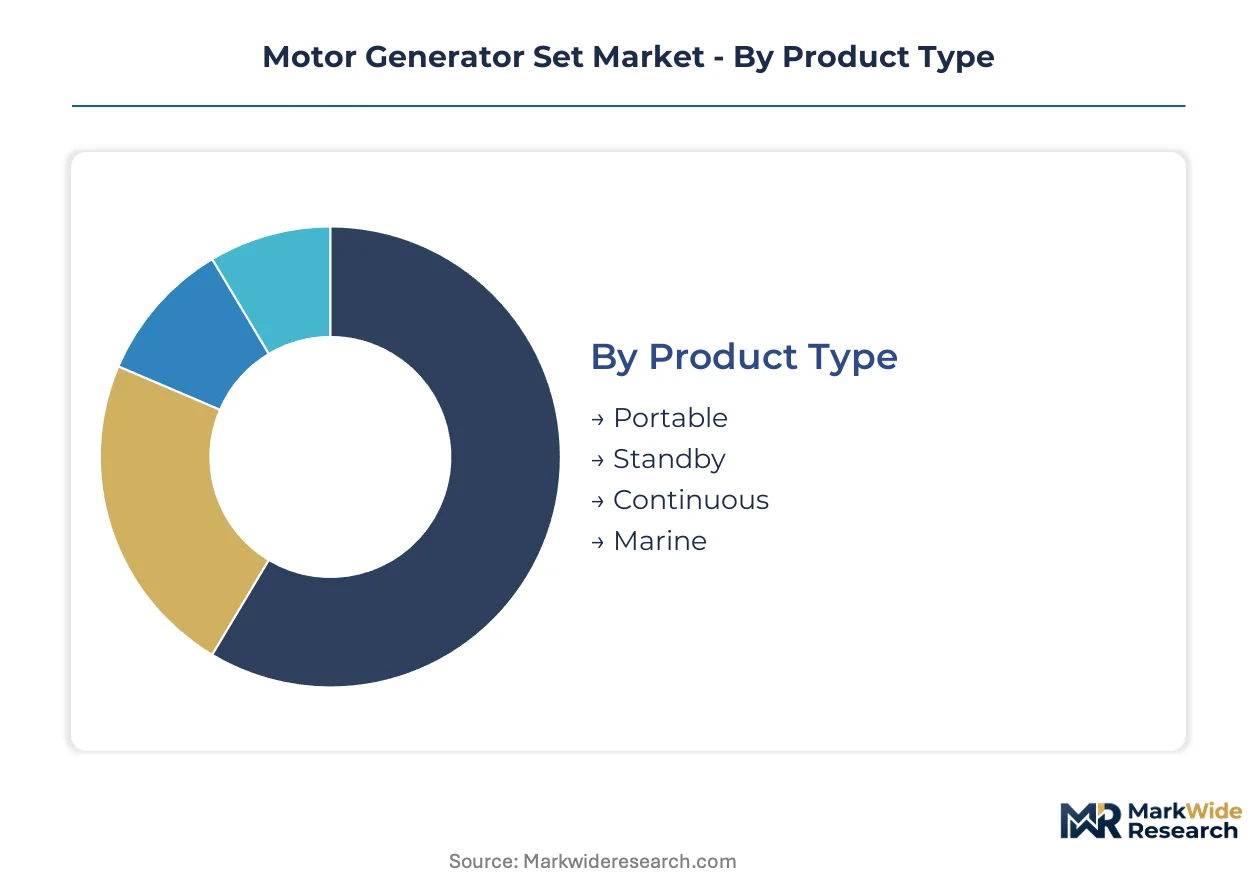
Motor generator set procurement patterns diverge sharply across duty cycles, fuel chemistry, and end-use criticality. Capital allocation decisions hinge on whether installations serve intermittent backup or continuous baseload functions.
Product Type:
Capital intensity escalates dramatically from mobile units to permanent continuous-duty installations requiring foundation engineering and exhaust aftertreatment.
- Portable:Compact skid-mounted or trailer configurations deliver sub-500 kW output for construction sites and temporary events. Demand concentrates in India's infrastructure corridors where grid extension lags behind industrial zone development.
- Standby:Automatic transfer switch integration enables sub-10-second response for healthcare facilities and data centers. Hospitals in Frankfurt and Singapore mandate certified standby architectures under local electrical codes, locking in replacement procurement cycles.
- Continuous:Prime-rated units operate at variable load for extended durations without derating. These installations require substantial civil works and fuel storage infrastructure.
- Marine:Vibration-dampened alternator packages meet Lloyd's Register and DNV classification society standards for offshore platforms and commercial shipping.
Standby configurations absorb the bulk of installed capacity across regulated critical infrastructure; continuous-duty units are expanding most quickly in distributed generation microgrids.
Fuel Type:
Emissions compliance costs are restructuring the fuel hierarchy, with aftertreatment requirements altering total cost of ownership calculations across prime mover technologies.
- Diesel:Reciprocating engines with high compression ratios deliver superior transient response for emergency starting. EPA Tier 4 Final mandates in the United States and EU Stage V in Europe are forcing selective catalytic reduction and diesel particulate filter integration, adding substantial material cost.
- Natural Gas:Lean-burn combustion architecture achieves lower NOx emissions without aftertreatment complexity. Data center operators in Northern Virginia and Dublin specify gas-fired units for baseload microgrids above 2 MW, displacing diesel's historical dominance.
- LPG:Propane storage eliminates fuel degradation concerns in standby applications with infrequent exercise cycles. Remote commercial installations in Australia and Canada favor LPG where natural gas pipeline access remains limited.
- Biofuel:Hydrotreated vegetable oil (HVO) compatibility enables carbon intensity reduction without engine modification. EU Green Deal incentives in Germany and the Netherlands are accelerating biofuel-ready platform development.
Diesel retains the deepest installed base across legacy infrastructure; natural gas is climbing the fastest in new continuous-duty procurement.
End User:
Margin structures vary substantially across customer categories, with industrial accounts commanding custom engineering and long-term service bundling.
- Residential:Single-phase output units below 20 kW serve outage-prone suburban markets. Hurricane corridors in Florida and Gulf Coast states drive seasonal demand spikes for air-cooled standby packages.
- Commercial:Three-phase installations protect retail, hospitality, and office assets against revenue loss from grid interruptions. Shopping complexes in Maharashtra and Gujarat specify synchronized paralleling capability for phased load restoration.
- Industrial:Custom-engineered medium-voltage packages serve semiconductor fabrication and pharmaceutical manufacturing with 99.999% uptime requirements. These installations generate the deepest margin pools through decade-long maintenance contracts.
- Utilities:Grid-forming synchronous machines provide black-start capability and spinning reserve for transmission system operators. Peaker plant configurations in Texas ERCOT territory integrate with battery storage for hybrid resource adequacy.
Industrial end users command the highest engineering intensity; commercial installations are gaining share fastest as small and medium enterprises formalize backup power protocols.
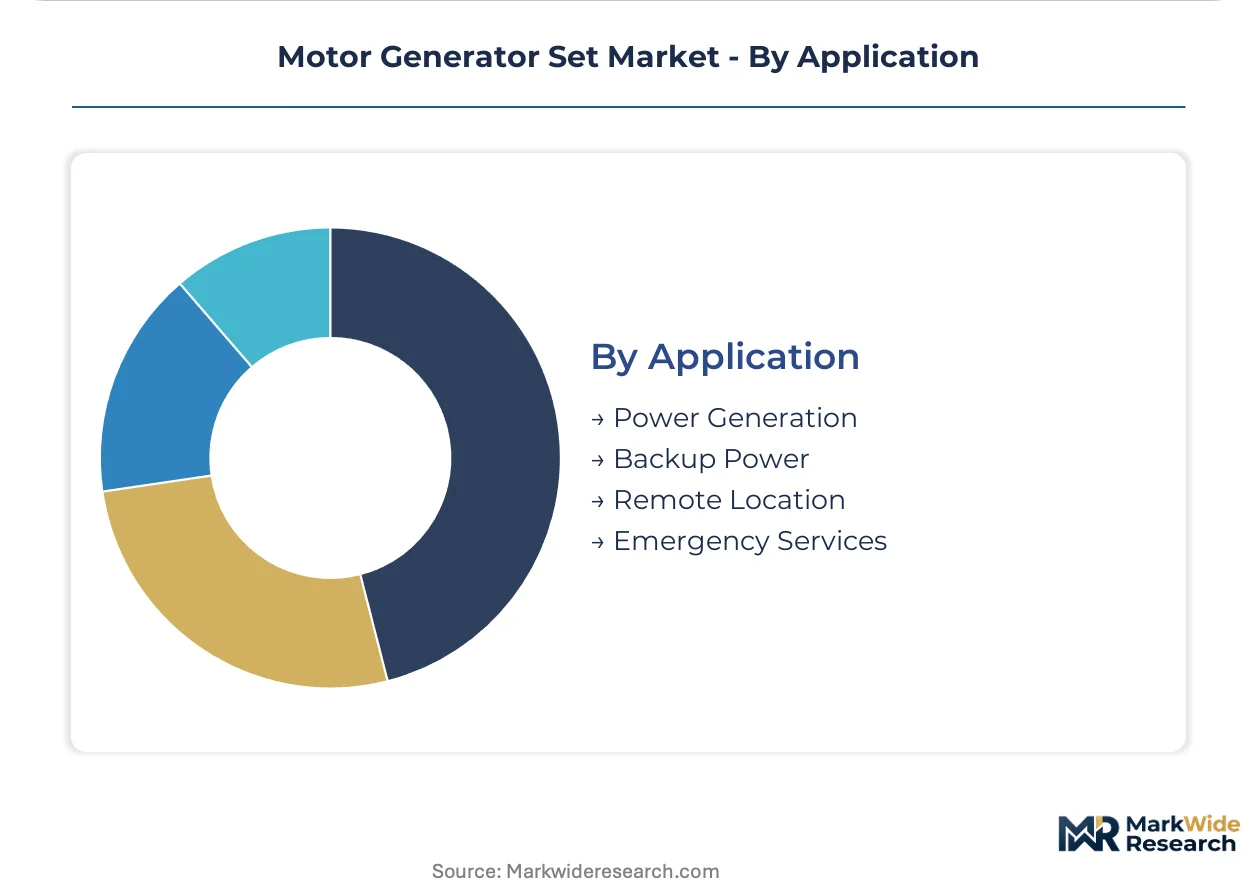
Application:
Runtime duration requirements determine fuel storage sizing, alternator thermal class selection, and control system sophistication.
- Power Generation:Prime power installations operate as the sole electrical source for off-grid mining camps and remote military forward operating bases. These configurations prioritize fuel efficiency over transient response.
- Backup Power:Emergency standby systems protect life safety loads in hospitals, airports, and nuclear facilities. NFPA 110 and ISO 8528-5 compliance mandates govern acceptance testing and maintenance logging.
- Remote Location:Solar-diesel hybrid architectures serve telecom towers and rural electrification projects in sub-Saharan Africa and Southeast Asian archipelagos. Battery-buffered cycling reduces engine runtime and maintenance intervals.
- Emergency Services:Rapid-deployment mobile units support disaster response and grid restoration following extreme weather events. FEMA and state emergency management agencies in the United States maintain strategic stockpiles.
Backup power applications anchor revenue concentration in developed markets; remote location deployment is expanding most quickly in frontier economies with limited grid penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Gujarat and Maharashtra concentrate manufacturing investment where grid reliability remains inconsistent. Tax incentives under India's PLI scheme accelerate industrial cluster formation. Data center developments in Northern Virginia and Frankfurt drive continuous-duty procurement.
United States
Hyperscale data center construction in Loudoun County and Prince William County sustains demand for multi-megawatt natural gas units. EPA Tier 4 Final mandates force aftertreatment integration across diesel standby configurations. ERCOT's resource adequacy challenges in Texas trigger peaker plant investments integrating motor generator sets with battery storage.
Germany
Industrial manufacturing in North Rhine-Westphalia requires certified backup power under VDE standards and EU machinery directives. The EU Green Deal and F-Gas Regulation accelerate HVO-compatible engine development for commercial installations. Chemical complexes in Ludwigshafen and Leverkusen specify biofuel-ready prime movers for carbon intensity reduction.
India
Manufacturing clusters across Gujarat's Sanand and Maharashtra's Pune-Chakan corridor accelerate procurement amid CEA reliability mandates. State-level industrial policies offer capital subsidies for captive power infrastructure. Semiconductor fabrication projects in Dholera and Greater Noida specify medium-voltage synchronous machines with 99.999% uptime guarantees.
China
Data center expansion in the Yangtze River Delta and Greater Bay Area drives demand for distributed generation assets. National dual carbon goals and provincial emissions standards constrain diesel deployment in eastern coastal provinces. Cloud computing campuses in Shanghai and Shenzhen specify natural gas configurations for baseload microgrid operation.
Singapore
Tropical data center developments in Jurong and Tuas mandate continuous-duty redundancy under tropical climate certifications. The Energy Market Authority's grid resilience frameworks require islanding capability for critical digital infrastructure. Maritime engineering in Tuas Port integrates vibration-dampened alternator packages meeting Lloyd's Register classification standards.
Motor Generator Set Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct margin tiers. The market structure consolidates around captive engine manufacturers with alternator packaging capabilities and independent system integrators serving regional accounts. Three archetypes dominate: vertically integrated engine-to-switchgear suppliers, alternator specialists sourcing third-party prime movers, and regional packagers serving price-sensitive emerging markets. Competitive moves concentrate on biofuel engine certification and predictive maintenance service bundling.
Among North American industrial conglomerates, Caterpillar Inc. and Cummins Inc. anchor the premium tier through captive engine architecture and extensive service networks. Mitsubishi Heavy Industries occupies a distinct position in high-megawatt utility applications with gas turbine alternator packages. These three exemplify how scale-driven manufacturers leverage backward integration into core components to control margin structures across standby and continuous-duty segments.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Generac Holdings Inc. |
| Kohler Co. |
| Mitsubishi Heavy Industries |
| ABB Ltd. |
| General Electric |
| Siemens AG |
| Toshiba Corporation |
| Others |
Supply & Pricing Matrix
EPA Tier 4 Final compliance gates both qualified supply and premium-tier pricing access, as manufacturers absorbing selective catalytic reduction and diesel particulate filter engineering costs pass through margin compression to buyers seeking certified standby configurations for healthcare and data center installations.
Pricing Analysis
Lead-time-driven pricing stratification rewards expedited delivery with substantial premiums while spot inventory commands discounts against standard order cycles. Three-tier pricing structure across EPA-certified premium, standard ISO 8528-compliant, and economy non-certified levels differentiates buyers by uptime criticality. Cost compression in diesel configurations is intensifying because aftertreatment integration adds material burden without commensurate performance gain. Commercial installations in India's manufacturing corridors exhibit highest price sensitivity, while semiconductor fabrication facilities in Germany and Singapore demonstrate least elasticity due to 99.999% uptime requirements.
Supply Chain Analysis
Workforce availability constraints in Wisconsin, Indiana, and Ohio limit alternator winding and switchgear assembly capacity for North American demand. Engine block casting draws from captive foundries in the United States, precision alternator laminations sources from Japanese and German electrical steel specialists, and control system electronics rests on Taiwanese semiconductor supply. Single-source vulnerability concentrates in selective catalytic reduction substrate supply from German and Austrian ceramic manufacturers. Distribution runs through manufacturer-direct channels for industrial accounts above 2 MW, with authorized dealer networks serving commercial and residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The motor generator set market reads as a cost-of-compliance story where EPA Tier 4 Final and EU Stage V emissions frameworks erect barrier-to-entry moats favoring manufacturers with captive aftertreatment engineering capabilities and established service networks.
For Market Incumbents: Deepen backward integration into alternator lamination supply and switchgear manufacturing to defend margin structures against lithium-ion battery substitution in sub-4-hour backup applications. Expand predictive maintenance service subscriptions to lock in recurring revenue alongside equipment sales, countering third-party service fragmentation in Indian pharmaceutical and semiconductor manufacturing clusters. For New Entrants and Emerging Players: EU Green Deal biofuel compatibility mandates in Germany and the Netherlands open a window for HVO-ready prime mover platforms targeting chemical complexes in Ludwigshafen and Leverkusen. White-space concentrates in remote monitoring software subscriptions for existing installed bases, with third-party maintenance agreements in Maharashtra and Gujarat offering fastest penetration path for service-only market entry. For Investors and Strategic Acquirers: Semiconductor fabrication project announcements in India's Dholera and Greater Noida corridors are the leading indicator that medium-voltage synchronous machine demand with 99.999% uptime specifications is accelerating. Long-term viability centers on manufacturers with captive engine architecture and certified biofuel development pipelines. Target acquisition profile: regional packagers in Southeast Asia with established CEA compliance capabilities and service network density.| Strategic Initiative | Industry Significance |
|---|---|
| Biofuel Engine Certification | HVO compatibility unlocks EU Green Deal incentives for German and Dutch utility tenders. |
| Predictive Maintenance Subscription | Remote monitoring services create recurring revenue streams alongside equipment sales in data center markets. |
| Aftertreatment Integration | Captive selective catalytic reduction engineering secures EPA Tier 4 Final compliance for North American healthcare installations. |
| Microgrid Control System Development | Grid-forming capability addresses ERCOT resource adequacy challenges in Texas peaker plant configurations. |
| Regional Service Network Expansion | Dedicated uptime guarantees capture Indian semiconductor and pharmaceutical manufacturing cluster procurement. |
Research Methodology
Document review covered EPA certification databases, FERC interconnection filings, and EU machinery directive compliance records, complemented by interviews with plant engineers at hyperscale data center operators, procurement directors at Indian manufacturing conglomerates, aftermarket service heads at regional generator packagers, and utility planning officers at ERCOT and European transmission system operators. Secondary validation drew from customs trade data for engine and alternator imports, SEC 10-K disclosures from diversified industrial conglomerates, and CEA regulatory mandate documentation. Bottom-up installation tracking across duty cycle, fuel type, and end-use segments was cross-referenced against top-down market sizing from equipment manufacturer revenue disclosures.
Historical shipment data was cross-referenced against panel input from industry stakeholders to construct demand projections across the analysis window. The analytical framework modeled segmentation dimensions including duty cycle classification, fuel chemistry, end-user criticality tier, and regional regulatory cluster. CAGRs were derived from regression analysis of capital expenditure patterns and replacement cycle timing. Forecast inputs incorporated data center power density trends, grid reliability indices by geography, and emissions compliance cost trajectories for diesel aftertreatment systems.
The model assumes a particular technology adoption path favoring natural gas prime movers in continuous-duty applications; alternative pathways for lithium-ion battery energy storage with extended duration capability would alter the outlook for diesel standby demand. Forecasts reflect assumptions regarding CEA enforcement timelines in India, EU carbon border adjustment implementation, and hyperscaler data center construction cadence in Northern Virginia and Frankfurt. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
United States Electric Space Heaters Market
Electrical Power Equipment
Global Explosion-Proof Electric Motors and Actuators Market
Electrical Power Equipment
Fault Circuit Indicator Market
Electrical Power Equipment
Unitary Heaters Market
Electrical Power Equipment
Protective Relay Market
Electrical Power Equipment
Global Low Voltage Electric Drives Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
GCC Induction Motor Market
Electrical Power Equipment
Containerized Substation Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
Global Switchgear Monitoring Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
US Air Filter Market