
 Subsea Cables Equipment Market | 2026-2036
Subsea Cables Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Subsea Cables Equipment Market Outlook
Project finance and leasing structures for cable-laying vessels is fragmenting the competitive landscape, allowing smaller contractors to bid on segments previously reserved for fully capitalized players. Prysmian S.p.A leverages its integrated manufacturing and installation fleet to sustain pricing power across long-haul interconnectors. SubCom, LLC anchors its position through deep-water installation expertise and proprietary burial technologies. NEC Corporation competes aggressively in the Asia-Pacific basin with state-backed financing for trans-Pacific routes.
Subsea cables equipment encompasses the specialized vessels, ploughs, trenchers, jointing systems, and monitoring apparatus required to install, maintain, and repair submarine cable infrastructure, typically operating at depths exceeding 1,000 meters with pressure ratings surpassing 100 bar to ensure signal and power integrity across oceanic distances. The primary commercial purpose is to establish and preserve subsea connectivity for intercontinental data traffic and offshore energy transmission. Cable laying equipment dominates capital expenditure as offshore wind arrays and intercontinental fiber routes extend route kilometers, while optical fiber technology leads technology segmentation due to its bandwidth superiority over copper for transoceanic data transmission. Jointing kits represent a concentrated margin pool given the technical precision required for deep-sea splices and the limited supplier base certified for pressure-rated assembly.
The International Cable Protection Committee guidelines, the EU Marine Strategy Framework Directive, and national seabed licensing regimes in coastal states collectively shape installation windows, burial depth mandates, and environmental impact thresholds that equipment must satisfy. The US Coast Guard and FCC coordinate cable landing permits with submarine security reviews, adding compliance layers for trans-Atlantic routes. Stakeholders must monitor evolving exclusive economic zone regulations and vessel emission standards that could reshape fleet deployment economics and equipment specification requirements.
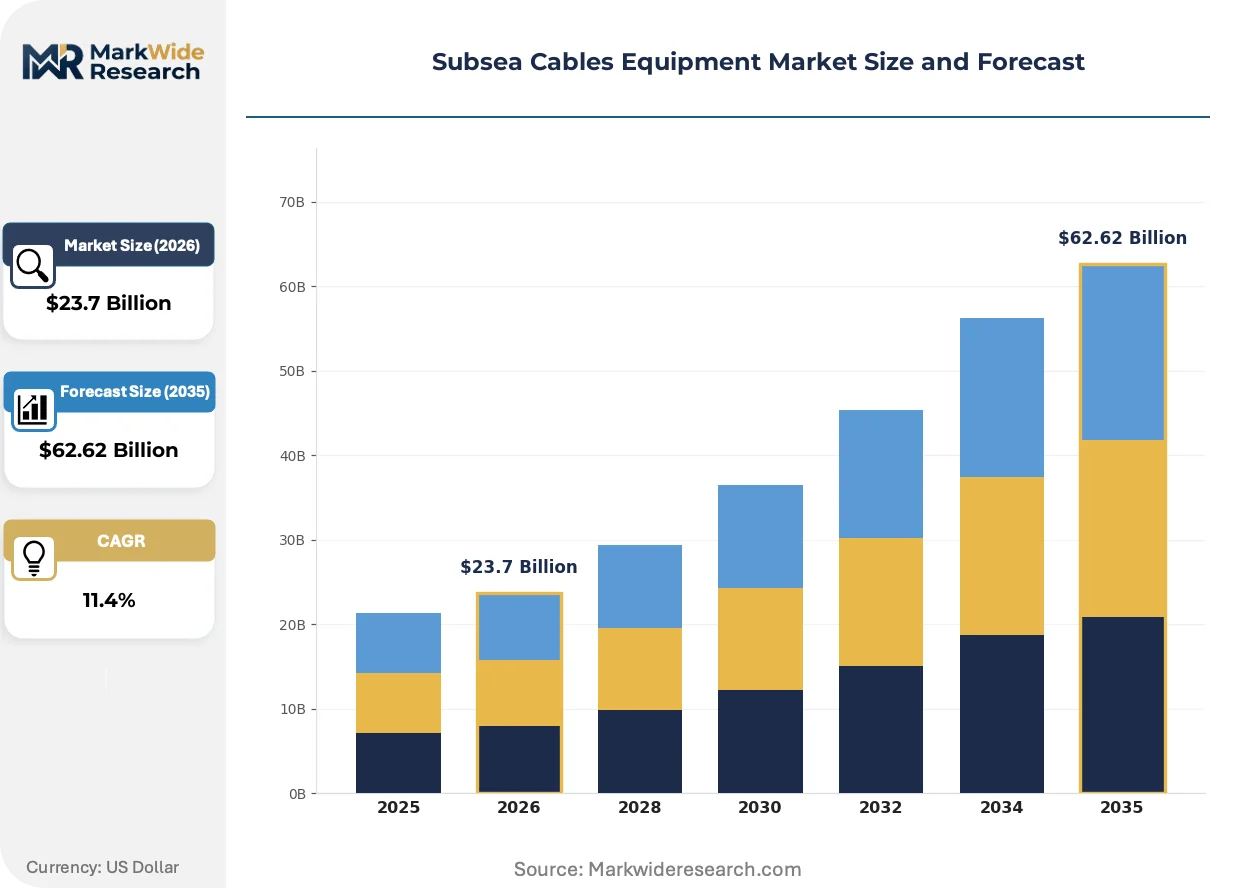
Market Dynamics
Offshore wind developers are compressing installation windows while simultaneously extending route kilometers, forcing equipment suppliers to reconcile throughput velocity with seabed protection mandates under the EU Marine Strategy Framework Directive.
Growth Catalysts
- Offshore wind auction pipelines:National seabed licensing regimes in the United Kingdom, Germany, and Denmark are mandating burial depth specifications that expand demand for ploughs and trenchers rated beyond 1,000 meters.
- Intercontinental data traffic:Trans-Pacific and trans-Atlantic fiber routes are multiplying cable runs, concentrating procurement along the North Sea corridor where vessel availability constrains project timelines.
- EU Green Deal compliance:Environmental impact thresholds for seabed disturbance are tightening, elevating certified jointing kits and pressure-rated assembly systems as non-negotiable procurement categories.
Market Restraints
- Specialized vessel scarcity:Cable-laying vessels capable of operating at 100 bar pressure ratings concentrate in Norwegian and Dutch fleets, creating geographic supply bottlenecks during peak installation seasons.
- High-alloy steel input costs:Pressure hull materials and dynamic positioning systems face commodity volatility that compresses margin structures for equipment manufacturers without captive fabrication facilities.
- Extended certification timelines:The International Cable Protection Committee guidelines and FCC submarine security reviews add 18-24 month pre-installation phases that delay revenue recognition for contractors.
Strategic Opportunities
- Floating offshore wind:Dynamic cable systems for tethered platforms represent an underpenetrated application requiring flexible jointing technologies distinct from static burial specifications.
- Asia-Pacific route expansion:State-backed financing for trans-Pacific fiber infrastructure is opening procurement channels outside the North Sea corridor for burial technology specialists.
- Real-time monitoring convergence:Integration of distributed acoustic sensing with existing cable infrastructure creates aftermarket service revenue streams for monitoring apparatus suppliers.
Industry Challenges
- Deep-water splicing certification:The limited supplier base certified for pressure-rated joint assembly creates talent scarcity that extends project staffing timelines and inflates labor premiums.
- Legacy vessel emission standards:Reconfiguring existing cable-laying fleets to meet tightening IMO sulfur caps requires capital outlays that strain smaller contractors without project finance backing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Cables Equipment Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cable Laying Equipment, Cable Repair Equipment, Submarine Cable, Jointing Kit End User: Telecommunication Providers, Research Institutions, Energy Companies, Government Agencies Technology: Optical Fiber, Copper, Hybrid, Submersible Application: Data Transmission, Power Transmission, Marine Research, Communication Systems |
| Companies Covered | Alcatel Submarine Networks, Prysmian S.p.A, SubCom, LLC, NEC Corporation, Nexans, NKT A/S, HENGTONG GROUP CO., LTD., ZTT, LS Cable & System Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Cables Equipment Market Strategic Shifts
Digital twin technology and autonomous seabed survey systems are compressing pre-installation phases while elevating precision requirements for burial depth compliance across exclusive economic zones.
Remote monitoring architectures are virtualizing cable integrity assessment. Distributed acoustic sensing systems now detect third-party intrusion and thermal anomalies across transoceanic routes without physical vessel dispatch. Offshore wind operators in the North Sea corridor are adopting these systems at accelerated cadence to minimize insurance premiums. This virtualization is compressing the traditional maintenance vessel deployment model into software-driven subscription revenue.
The EU Green Deal's seabed protection mandates are reshaping equipment specification requirements. Burial depth thresholds now vary by substrate type, forcing plough manufacturers to develop modular tool configurations. Contractors operating in German and Danish waters face the most stringent compliance layers, responding with pre-installation environmental impact assessments that extend project timelines but reduce regulatory rejection risk.
Consolidation among offshore wind developers is concentrating procurement authority into fewer hands with standardized technical specifications. Joint venture structures between utilities and infrastructure funds are displacing fragmented developer bidding that previously tolerated equipment heterogeneity. This concentration is most visible in United Kingdom Round 4 and Round 5 auction awards, where pre-qualified contractor lists now favor suppliers with integrated manufacturing and installation capabilities.
Subsea Cables Equipment Market Segmentation
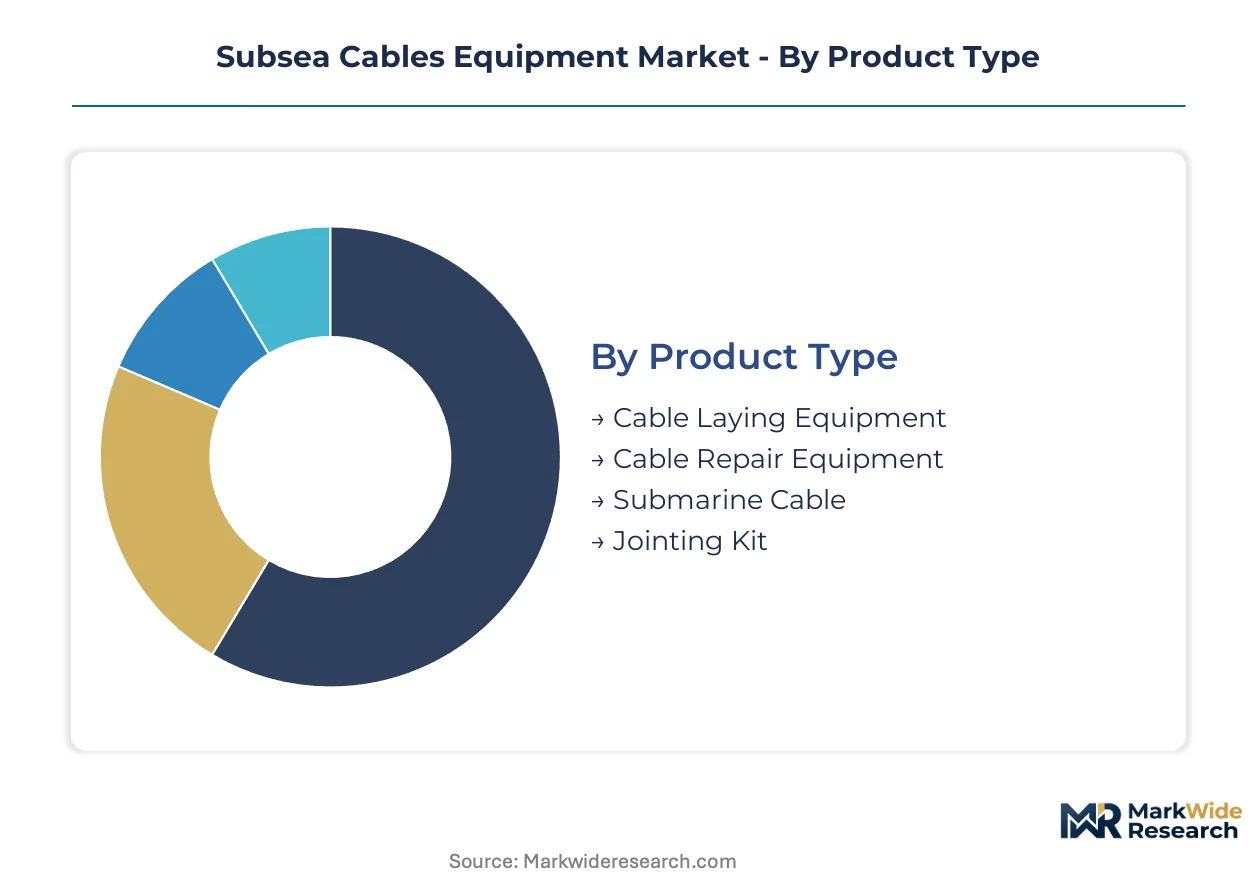
Segmentation in subsea cables equipment reveals distinct procurement patterns across installation phases, customer sophistication, and transmission requirements. Equipment specification varies sharply between intercontinental fiber routes and offshore wind array deployments. Understanding these divides exposes margin concentration and technology substitution risks.
Product Type:
Cost tier determines capital intensity and financing structure across installation equipment categories.
- Cable Laying Equipment:Specialized vessels, ploughs, and trenchers rated for 1,000-meter depths absorb the largest procurement budgets in offshore wind and interconnector projects. Norwegian and Dutch fleet operators concentrate supply, creating geographic bottlenecks during peak North Sea installation seasons.
- Jointing Kit:Pressure-rated splice assemblies certified for 100 bar operation command premium pricing due to limited supplier bases certified by the International Cable Protection Committee. Deep-water splicing certification scarcity extends project staffing timelines across trans-Pacific routes.
- Cable Repair Equipment:Remotely operated vehicles and seabed retrieval systems address fault response with lower capital barriers than full laying fleets.
- Submarine Cable:The cable itself represents raw material procurement distinct from installation apparatus, with optical fiber variants dominating transoceanic data specifications.
Cable laying equipment commands the established base. The steepest expansion runs through jointing kits as burial depth mandates tighten.
End User:
Customer type shapes procurement authority concentration and technical specification standardization.
- Telecommunication Providers:Hyperscale cloud operators and subsea consortiums drive trans-Pacific and trans-Atlantic fiber route procurement with multi-year vessel charter commitments. FCC submarine security reviews and landing permit coordination add 18-24 month pre-installation phases.
- Energy Companies:Offshore wind developers in the United Kingdom, Germany, and Denmark compress installation windows while extending route kilometers, forcing throughput velocity reconciliation with EU Marine Strategy Framework Directive seabed protection mandates.
- Government Agencies:National security and research infrastructure procurement emphasizes vessel emission compliance and exclusive economic zone regulatory alignment over pure cost optimization.
- Research Institutions:Marine science observatory networks generate sporadic demand for specialized deep-water monitoring apparatus with extended sensor integration requirements.
Telecommunication providers command the established base. The steepest expansion runs through energy companies as offshore wind auction pipelines mature.
Technology:
Maturity curves and bandwidth economics differentiate transmission medium selection.
- Optical Fiber:Silica-based single-mode fiber dominates transoceanic data transmission with terabit-scale capacity and minimal signal attenuation across 10,000-kilometer routes. EU Green Deal environmental impact thresholds elevate certified assembly systems as non-negotiable procurement categories.
- Hybrid:Power-plus-data composite configurations serve offshore wind export cables and island interconnections with combined high-voltage and fiber optic elements.
- Copper:Legacy coaxial systems persist in regional submarine links and specialized defense applications with lower bandwidth requirements.
- Submersible:Pressure-resistant encapsulation technologies enable dynamic cable systems for floating offshore wind tethered platforms.
Optical fiber commands the established base. The steepest expansion runs through hybrid configurations as offshore wind arrays multiply.
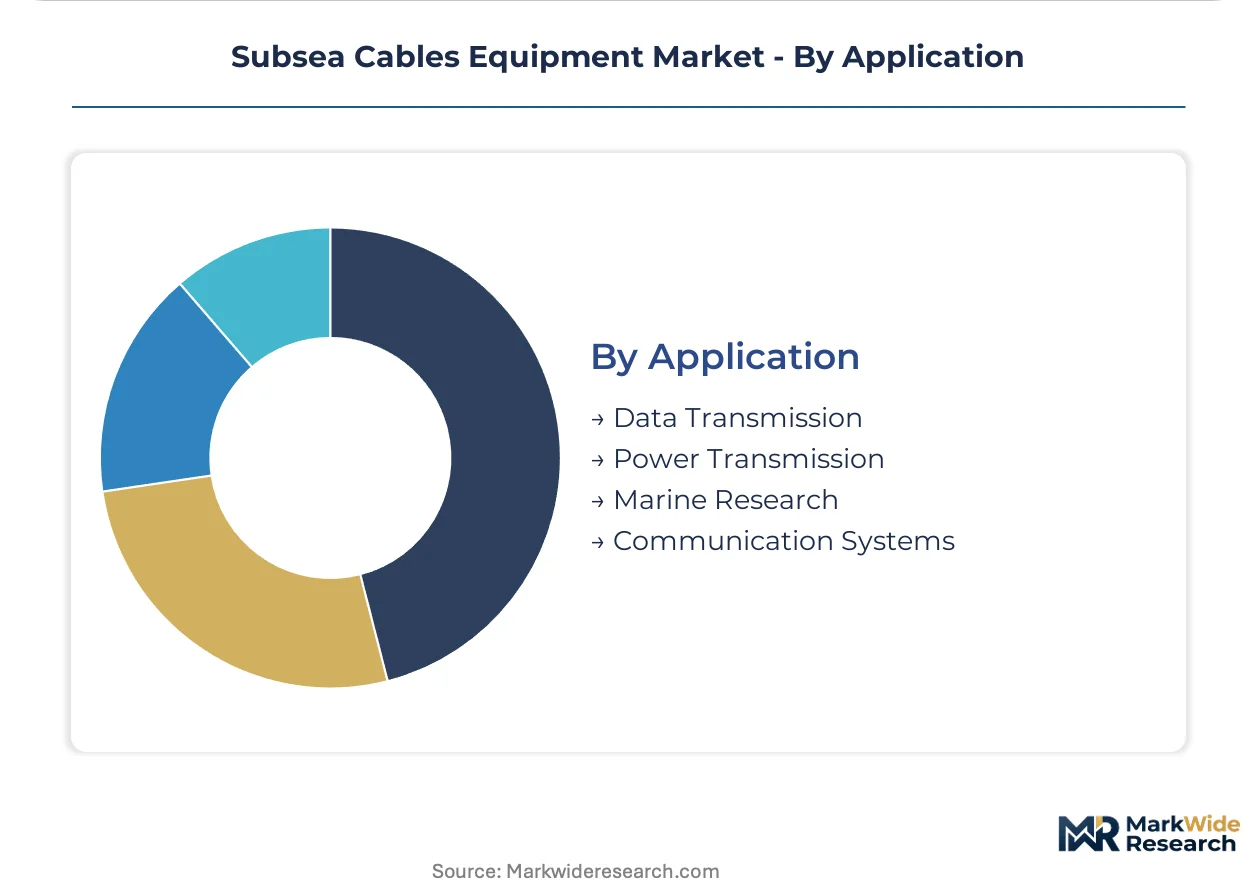
Application:
Volume concentration and route economics vary across deployment purpose.
- Data Transmission:Intercontinental fiber infrastructure connecting cloud regions drives vessel utilization rates and burial technology specialization. State-backed financing for trans-Pacific routes opens procurement channels outside the North Sea corridor.
- Power Transmission:High-voltage direct current submarine interconnectors and offshore wind export cables demand distinct jointing specifications from fiber-optic systems.
- Communication Systems:Coastal and island link networks generate fragmented demand with heterogeneous technical requirements.
- Marine Research:Cabled ocean observatory infrastructure represents niche deployment with extended sensor integration timelines.
Data transmission commands the established base. The steepest expansion runs through power transmission as floating offshore wind platforms commercialize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment flows track the imbalance between cable manufacturing concentration in East Asia and installation demand clustering along European offshore wind corridors. Import dependency for specialized vessels shapes procurement timelines in Atlantic markets.
United Kingdom
Round 4 and Round 5 offshore wind auctions are compressing installation windows across the North Sea. The Crown Estate seabed licensing regime mandates burial depth specifications that expand demand for deep-rated ploughs. Aberdeen and Great Yarmouth anchor vessel mobilization hubs where Norwegian and Dutch fleet operators stage equipment ahead of construction seasons.
Germany
Baltic Sea offshore wind pipelines and North Sea interconnector projects are extending route kilometers through environmentally sensitive substrates. The Federal Maritime and Hydrographic Agency enforces the strictest EU Marine Strategy Framework Directive compliance layers for seabed disturbance. Rostock and Emden industrial clusters concentrate jointing kit certification facilities and pressure-rated assembly workshops.
China
State-backed financing for trans-Pacific fiber routes is expanding cable-laying vessel construction at domestic shipyards. The Ministry of Industry and Information Technology coordinates seabed licensing with national security reviews for landing stations. Shanghai and Tianjin port complexes anchor manufacturing integration between optical fiber production and installation equipment fabrication.
United States
Atlantic Coast offshore wind lease auctions are activating procurement for burial technologies previously deployed in European waters. The FCC coordinates submarine cable landing permits with Coast Guard security reviews that extend pre-installation phases. Boston and Virginia Beach emerging as cable landing concentration points where environmental impact assessments face multi-agency coordination.
Japan
Island interconnection projects and transpacific fiber route maintenance are sustaining demand for repair-capable vessel charters. METI offshore wind roadmaps are mandating dynamic cable specifications for floating platform tethering. Nagasaki and Kobe industrial zones concentrate pressure-rated jointing expertise inherited from submarine power cable manufacturing.
Subsea Cables Equipment Market Competitive Environment
On the supply side, the industry is consolidating around integrated manufacturing-installation capabilities while fragmenting at the specialized equipment tier. Vessel ownership separates capital-intensive fleet operators from project-financed charter contractors. Three archetypes dominate: vertically integrated cable manufacturers with captive installation fleets; independent burial technology specialists licensing plough and trencher designs; and regional vessel operators aggregating demand through pooling arrangements. Competitive moves center on backward integration into pressure hull fabrication and strategic partnerships to secure high-alloy steel supply.
Within the integrated-manufacturer tier, Prysmian S.p.A and Nexans exemplify European-headquartered players combining cable production with installation fleet control. Alcatel Submarine Networks represents the telecommunications infrastructure specialist archetype. HENGTONG GROUP CO., LTD. and ZTT occupy positions among China-based fabricators expanding from domestic optical fiber supply into installation equipment provision. These named entities anchor market structure without exhausting the competitive set.
| Leading Market Players |
|---|
| Alcatel Submarine Networks |
| Prysmian S.p.A |
| SubCom, LLC |
| NEC Corporation |
| Nexans |
| NKT A/S |
| HENGTONG GROUP CO., LTD. |
| ZTT |
| LS Cable & System Ltd. |
| Others |
Value Chain & Pricing Dynamics
North Sea vessel mobilization corridors from Aberdeen and Great Yarmouth concentrate freight costs for cable-laying equipment, amplifying price differentiation between Norwegian fleet operators with captive hull fabrication and Dutch charter contractors exposed to high-alloy steel volatility.
Pricing Analysis
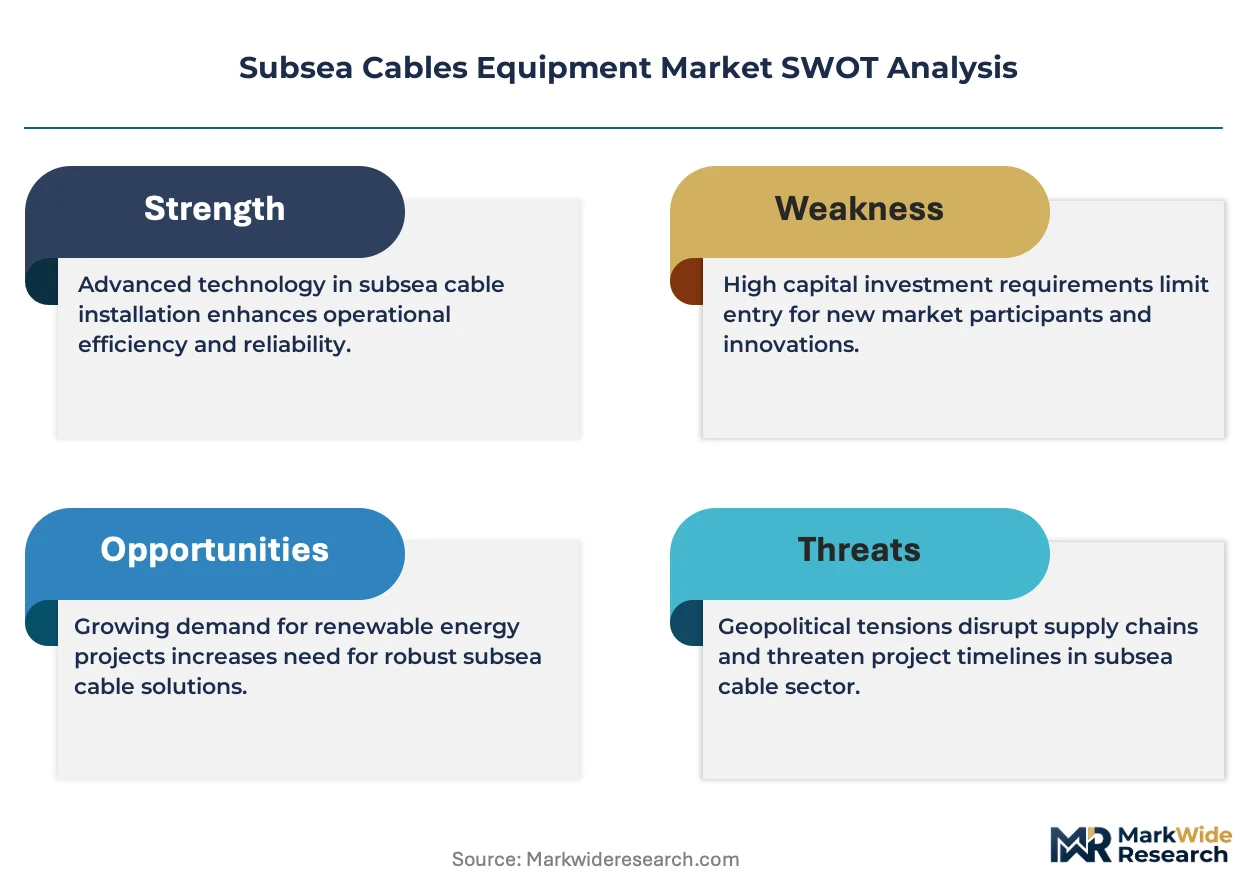
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade from the International Cable Protection Committee and volume scale of vessel charter commitments. Cost compression in the standard tier is intensifying because smaller contractors without project finance backing face margin pressure from extended pre-installation phases. Offshore wind developers in the United Kingdom and Germany demonstrate the least price sensitivity due to EU Green Deal compliance mandates, while regional telecommunication providers in fragmented Asia-Pacific markets drive hardest bargaining.
Supply Chain Analysis
Export-control restrictions on dynamic positioning systems and pressure-rated jointing technologies limit flows from Norwegian and Japanese suppliers to Chinese shipyards. Geographic supply concentration centers on Norway, the Netherlands, and China for specialized vessels, with South Korea and Japan anchoring high-alloy steel input production. Raw material dependencies draw from nickel-chromium alloys, high-strength steel plate, and precision optical fiber. Single-source vulnerability around certified jointing kit suppliers creates structural risk. Distribution runs through project-financed charter pools and integrated manufacturer direct sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Offshore wind auction pipelines across the North Sea corridor are accelerating equipment procurement velocity, with floating platform tethering requirements representing a technological inflection that reshapes jointing specifications.
For Market Incumbents: Entrench pricing power by securing captive fabrication facilities for pressure hull materials and dynamic positioning systems. Prysmian S.p.A's integrated manufacturing-installation model demonstrates how backward integration into vessel ownership defends margins against emerging charter-based competitors. Prioritize certification investment for EU Marine Strategy Framework Directive compliance to lock out non-compliant challengers in German and Danish waters. For New Entrants and Emerging Players: Asia-Pacific route expansion outside the North Sea corridor offers white-space penetration for burial technology specialists lacking European fleet presence. State-backed financing for trans-Pacific fiber infrastructure in China and Japan creates procurement channels accessible without Norwegian vessel ownership. Target joint venture structures with domestic shipyards to bypass geographic supply bottlenecks. For Investors and Strategic Acquirers: Independent burial technology specialists with modular plough designs and proprietary trencher IP represent compelling acquisition targets. Long-term viability hinges on exposure to floating offshore wind commercialization and real-time monitoring convergence. Watch distributed acoustic sensing adoption rates across North Sea offshore wind arrays as the signal indicating whether maintenance virtualization accelerates or stalls.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pressure Hull Fabrication | Norwegian and Dutch fleet operators secure margin control against high-alloy steel volatility. |
| Jointing Kit Certification Expansion | International Cable Protection Committee accreditation opens EU Green Deal-compliant procurement channels. |
| Floating Platform Dynamic Cable Development | Modular jointing technologies address tethered offshore wind specifications distinct from static burial. |
| Real-Time Monitoring Service Launch | Distributed acoustic sensing integration creates software-driven subscription revenue from existing infrastructure. |
| Asia-Pacific Route Partnership | State-backed trans-Pacific financing opens procurement outside North Sea vessel concentration. |
Study Parameters
Initial hypotheses were tested against primary input from cable-laying vessel operators, offshore wind project developers, telecommunication procurement officers, and burial technology R&D directors and refined through secondary validation against SEC filings from listed manufacturers, customs trade data for high-alloy steel imports, EU Marine Strategy Framework Directive implementation reports, and International Cable Protection Committee guideline updates. Bottom-up equipment shipment tracking and top-down project pipeline aggregation were triangulated to reconcile volume estimates.
Demand-supply balance across the projection horizon anchored the analytical framework, with segmentation dimensions spanning installation phase, end-user type, transmission technology, and application purpose. CAGRs were derived from route kilometer expansion in offshore wind and fiber infrastructure, vessel utilization rate assumptions, and burial depth mandate escalation under the EU Green Deal. Industry-specific inputs included North Sea auction pipeline timelines and trans-Pacific landing permit approval patterns.
The forecast holds incumbent behavior within observed patterns; aggressive fleet expansion by state-backed Chinese shipyards or rapid floating wind commercialization would shift outcomes. Material shifts in IMO sulfur cap enforcement timelines or exclusive economic zone regulatory fragmentation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Frameless Brushless DC Motors Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
Digital Fault Recorder (DFR) Market
Electrical Power Equipment
AV Power Conditioners Market
Electrical Power Equipment
South America Gas Insulated Switchgear Market
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
United States Electric Space Heaters Market
Electrical Power Equipment
MV Protection Relay Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Solid Vacuum Reclosers Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market
Electrical Power Equipment
Power Line Carrier System Market
Electrical Power Equipment
Alternate Current (AC) Drives Market