
 Industrial Power Supply Market | 2026-2036
Industrial Power Supply Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Power Supply Market Outlook
Aftermarket service revenue is tilting toward predictive maintenance contracts as OEMs seek recurring income streams. Siemens AG leverages its digital twin platforms to anchor long-term service agreements across European heavy industry. Delta Electronics Inc competes on manufacturing scale in Asia, while ABB Ltd specializes in integrated power and automation bundles for process industries.
Industrial power supply denotes engineered electrical conversion and conditioning equipment designed to deliver stable, regulated voltage and current to machinery, typically operating across input ranges of 85-264 VAC and output tolerances within ±1%. These systems protect sensitive automation loads from grid disturbances, harmonic distortion, and transient events. AC power supplies retain the largest revenue pool in mature manufacturing economies, though switching technology is displacing linear architectures where energy density and thermal efficiency matter most. Digital technology segments are capturing margin expansion through remote monitoring capabilities that reduce field service costs.
EU Ecodesign Directive and CE marking requirements shape product design minimums for efficiency and electromagnetic compatibility across European industrial deployments. The US Department of Energy efficiency standards and OSHA electrical safety regulations similarly constrain market access and product specifications for equipment sold into North American facilities. Stakeholders must weigh whether to develop region-specific product variants or pursue modular platforms that bridge regulatory divergence.
Market Dynamics
The EU Ecodesign Directive's tightening efficiency mandates are forcing a wholesale redesign of industrial power supply architectures, compressing legacy linear designs while accelerating digital platform adoption across European heavy industry.
Growth Catalysts
- Semiconductor fabrication expansion:Taiwan and South Korea fabs are scaling 300mm wafer capacity, requiring ultra-stable power conditioning for lithography and etching equipment with sub-microsecond transient response.
- CE marking harmonization:The EU's electromagnetic compatibility directive creates a single compliance pathway, reducing certification duplication for power supply vendors targeting German automotive and French aerospace clusters.
- Digital twin integration:Predictive load modeling is anchoring long-term service contracts, as OEMs embed power quality analytics into maintenance agreements for steel and chemical processing plants.
Market Restraints
- Magnetic core material concentration:Grain-oriented electrical steel supply concentrates in Japanese and South Korean mills, exposing European power supply manufacturers to input cost volatility and allocation risk.
- RoHS substance restrictions:The EU's hazardous substance limits constrain high-temperature solder and thermal interface material choices, complicating designs for harsh-environment industrial deployments.
- Silicon carbide substrate scarcity:Wide-bandgap semiconductor wafers remain supply-constrained, limiting switching frequency gains for compact, high-efficiency power conversion modules.
Strategic Opportunities
- India manufacturing corridor electrification:The country's PLI scheme for industrial automation is creating first-time demand for regulated power infrastructure in Gujarat and Tamil Nadu automotive clusters.
- Battery energy storage coupling:Hybrid AC-DC architectures integrating lithium-ion buffering are opening retrofit opportunities for grid-stabilized industrial microgrids in German chemical parks.
- ISO 50001 energy management:Certification mandates across Japanese automotive supply chains are driving premium power supply upgrades with embedded metering and efficiency verification.
Industry Challenges
- Power electronics engineering shortage:Magnetic design and thermal management expertise pools concentrate at mid-career levels, constraining R&D velocity for next-generation high-frequency converters.
- Legacy 400Hz aircraft ground power integration:Defense and commercial aviation maintenance facilities require backward-compatible architectures, complicating modular platform standardization.
- Functional safety certification timelines:IEC 61508 SIL assessments for process industry applications extend qualification cycles, delaying revenue recognition for specialized hazardous-location designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Power Supply Market |
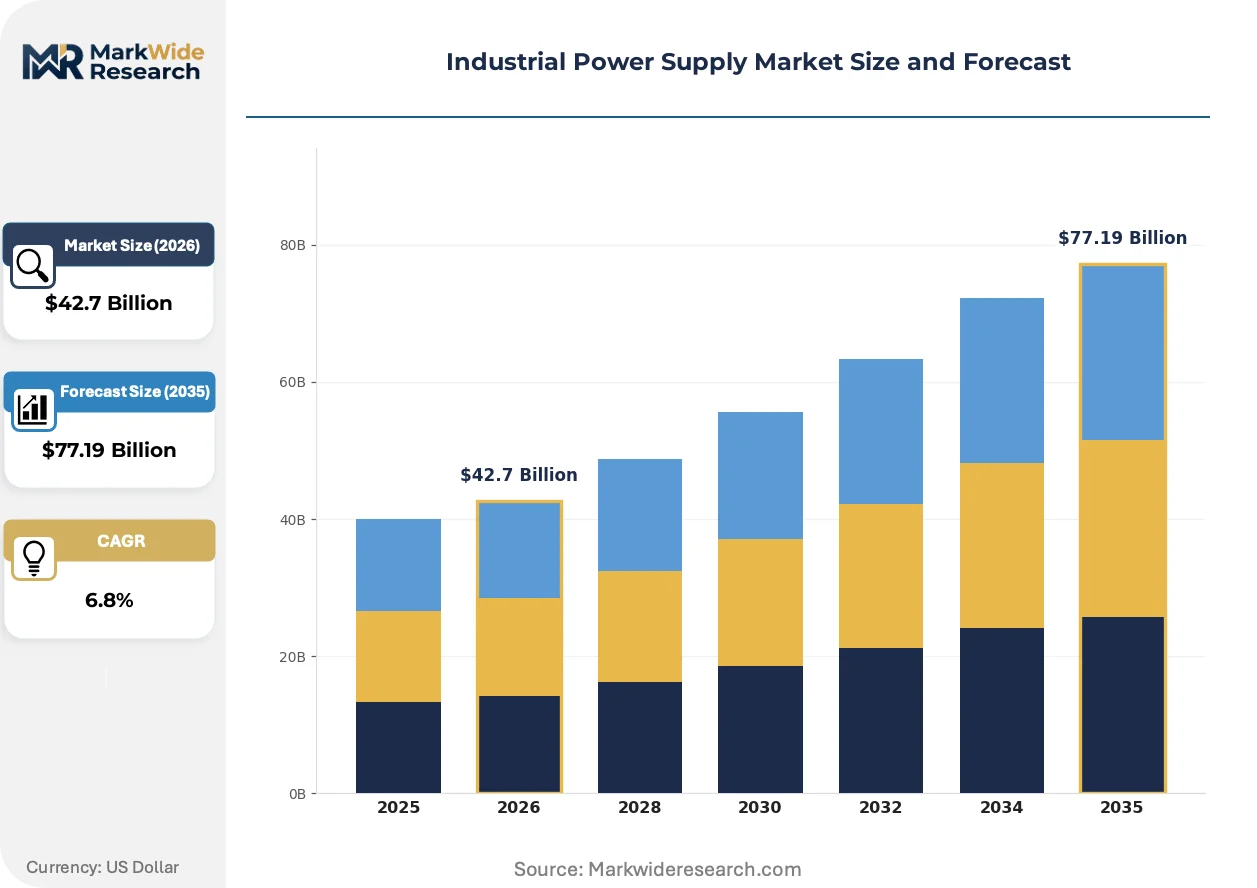
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $77.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Power Supplies, DC Power Supplies, UPS, Switching Power Supplies Technology: Linear Technology, Switching Technology, Digital Technology, Renewable Technology Application: Manufacturing, Automation, Transportation, Telecommunications End User: OEMs, Energy Sector, Manufacturing Plants, Data Centers |
| Companies Covered | Siemens AG, Delta Electronics Inc, ABB Ltd, TDK Corporation, Mean Well Enterprises Co Ltd, XP Power PLC, Murata Manufacturing Co Ltd, Phoenix Contact GmbH & Co KG, Advanced Energy Industries Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Power Supply Market Strategic Shifts
Silicon carbide and gallium nitride wide-bandgap semiconductors are compressing thermal management requirements while enabling power density gains that reshape form factor standards across industrial automation.
Wide-bandgap switching devices operate at frequencies tenfold above silicon IGBTs, collapsing magnetic component volume in compact servo drives and robotic power modules. Japanese machine tool builders and German automotive press manufacturers are specifying these architectures for space-constrained cabinet installations. The technology is collapsing the traditional trade-off between efficiency and power density that governed linear-to-switching transitions.
The EU F-Gas Regulation's phase-down of fluorinated greenhouse gases is accelerating dry-type transformer and natural convection cooling adoption in food processing and pharmaceutical cleanroom environments. Industrial power supply vendors are redesigning thermal architectures to eliminate SF6 and PFAS-based dielectric fluids. French and Dutch chemical processing clusters face the steepest retrofit timelines, driving near-term demand for air-cooled medium-voltage rectifier systems.
Buying committees at automotive OEMs are unbundling hardware procurement from lifecycle service agreements, forcing power supply vendors to price conversion equipment and predictive maintenance contracts separately. Tier-1 German suppliers now source DC bus systems through direct manufacturer relationships while contracting predictive analytics through specialized software vendors. This bifurcation is most pronounced in Bavarian and Baden-Württemberg electric vehicle battery manufacturing facilities, where CAPEX and OPEX budgets sit under different procurement functions.
Industrial Power Supply Market Segmentation
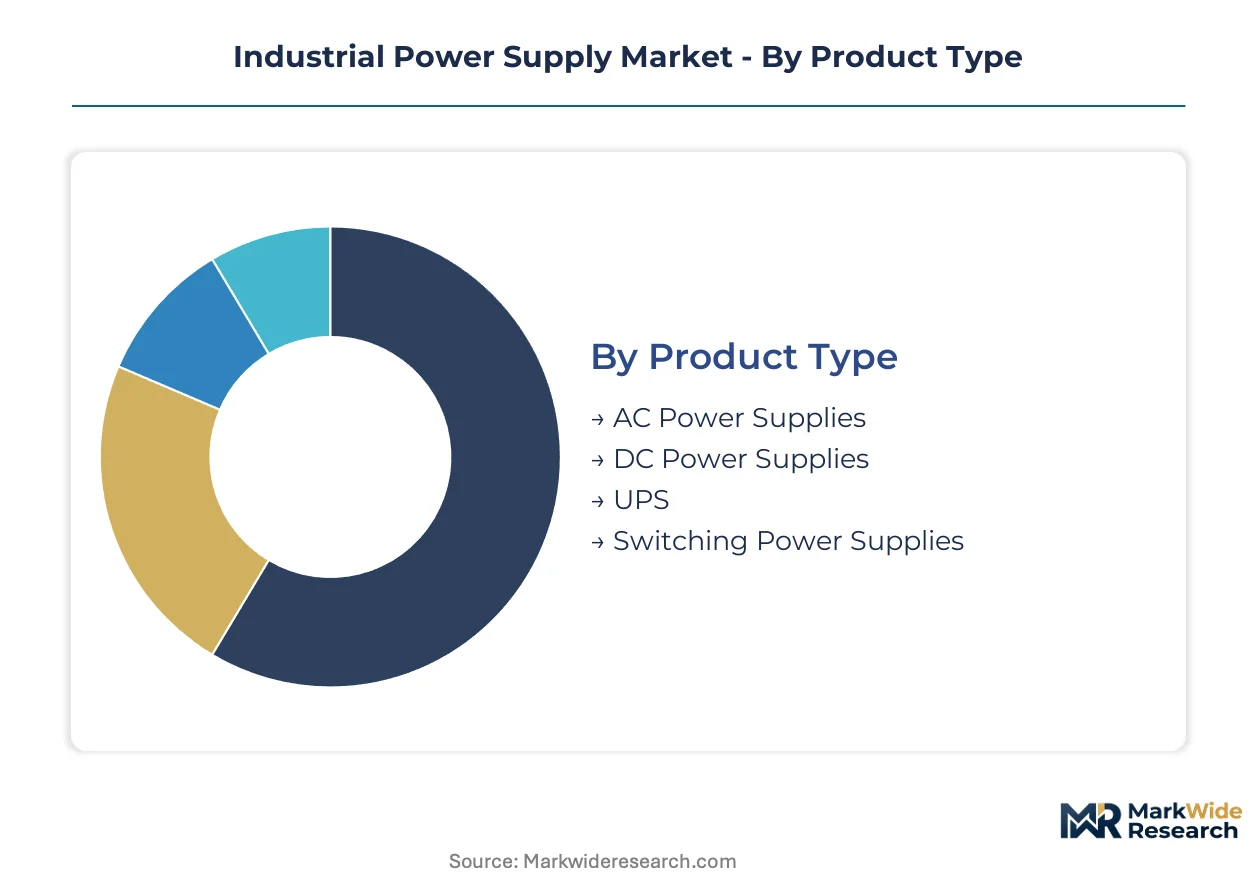
Industrial power supply segmentation reveals divergent margin structures across conversion architectures. Product type and technology choices determine thermal management requirements, regulatory compliance pathways, and service attach rates that reshape vendor profitability.
Product Type:
Cost tier differentiation separates commodity switching modules from premium uninterruptible systems with embedded power quality analytics.
- AC Power Supplies:These units convert incoming grid voltage to stable alternating current for motor drives and inductive loads. German automotive press manufacturers and Japanese machine tool builders specify these for legacy three-phase equipment in Baden-Württemberg and Aichi Prefecture clusters. AC Power Supplies hold installed capacity. Switching Power Supplies is rotating up the share rankings.
- DC Power Supplies:Rectifier-based architectures deliver precise direct current for electrolytic processes and battery formation. Demand concentrates in South Korean battery gigafactories and German chemical parks where voltage ripple tolerance falls below 50 millivolts for lithium-ion cell conditioning.
- UPS:Battery-backed systems bridge grid interruptions for semiconductor lithography and pharmaceutical batch processes. Taiwanese fabs and Dutch ASML supply chain partners mandate sub-4-millisecond transfer times.
- Switching Power Supplies:High-frequency conversion enables compact form factors for robotic servo drives and programmable logic controller racks.
AC Power Supplies hold installed capacity. Switching Power Supplies is rotating up the share rankings.
Technology:
Application requirements dictate architecture selection between linear stability and switching efficiency trade-offs.
- Linear Technology:Analog regulation circuits deliver ultra-low noise floors below 1 millivolt RMS for test and measurement instrumentation. Swiss precision equipment manufacturers and German calibration laboratories specify these for metrology-grade voltage references despite thermal inefficiency.
- Switching Technology:Pulse-width modulation at 100+ kilohertz collapses magnetic component volume. Indian automotive wiring harness plants and Vietnamese electronics assembly facilities adopt these for space-constrained cabinet installations where efficiency certification drives procurement.
- Digital Technology:Firmware-controlled conversion enables remote monitoring and adaptive load response through embedded communication protocols.
- Renewable Technology:Maximum power point tracking and grid-tie inverters integrate photovoltaic and wind generation into industrial microgrids.
Switching Technology dominates shipment volumes. Digital Technology is climbing the fastest as predictive maintenance contracts attach to hardware sales.
Application:
Volume concentration varies sharply between continuous-process industries and discrete manufacturing cycles.
- Manufacturing:Assembly line power conditioning spans welding robotics, conveyor systems, and quality inspection equipment. Demand clusters in Mexico's Bajío automotive corridor and Thailand's Eastern Economic Zone where Japanese OEMs enforce voltage sag ride-through specifications.
- Automation:Servo drive networks and motion control systems require synchronized multi-axis power delivery. German packaging machinery builders and Italian textile equipment manufacturers specify these with EtherCAT power integration.
- Transportation:Electric vehicle charging infrastructure and rail signaling systems need galvanic isolation and electromagnetic compatibility hardening.
- Telecommunications:Base station rectifiers and data center bus converters operate at 48-volt DC distribution standards.
Manufacturing commands the largest installed base. Automation is gaining share fastest as collaborative robotics penetration deepens.
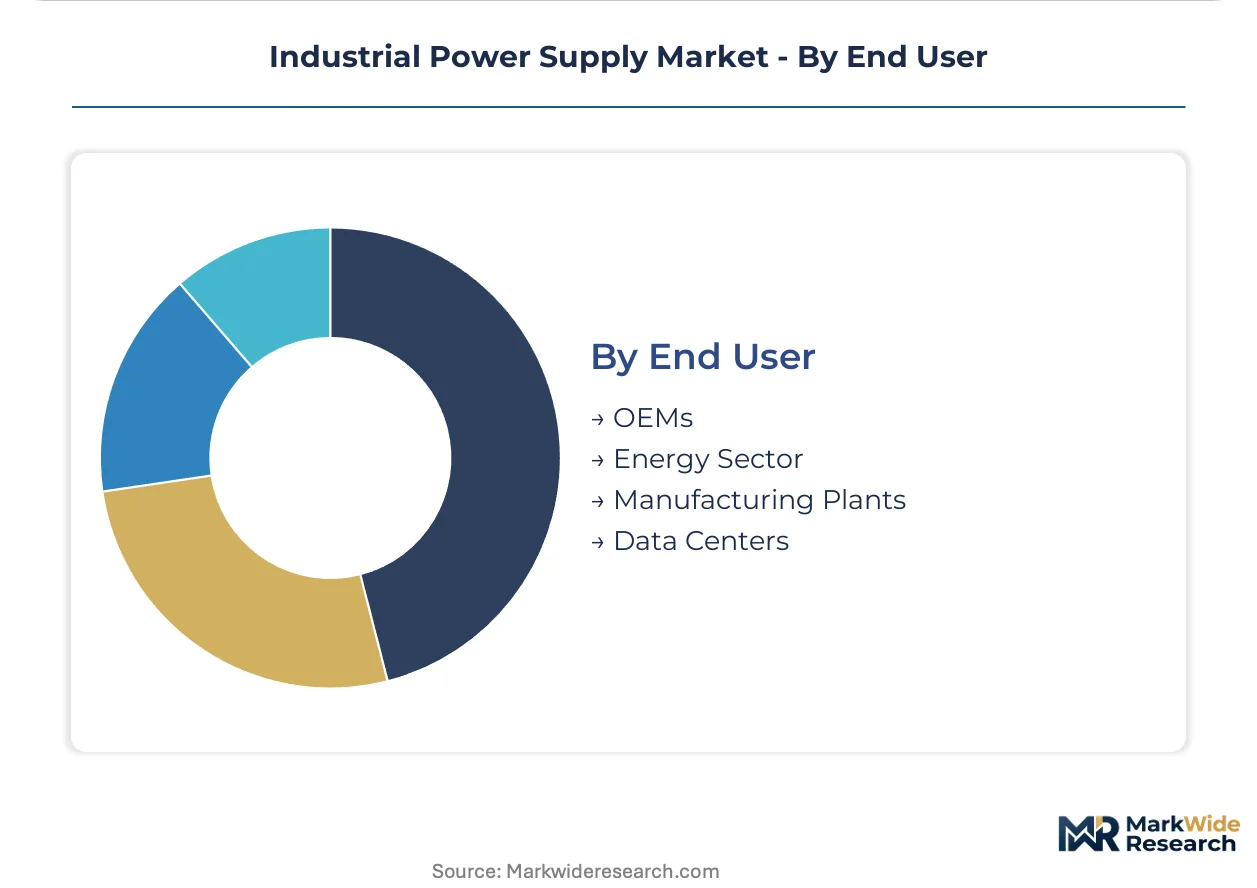
End User:
Customer type determines procurement complexity, with energy sector tenders demanding extended warranty terms versus OEM volume pricing.
- OEMs:Original equipment manufacturers integrate power supplies into capital goods for resale, prioritizing form factor standardization and supply chain security. German machine tool OEMs and Japanese industrial robot builders qualify dual-source power modules to mitigate semiconductor allocation risk.
- Energy Sector:Utility-scale battery storage and substation automation require IEC 61850 communication compliance and seismic rating certifications. Projects in Saudi Arabia's NEOM and Australia's Pilbara region specify these for remote desert installations.
- Manufacturing Plants:End-user facilities purchase direct for retrofit and expansion projects with compressed lead time requirements.
- Data Centers:Hyperscale operators specify 96% efficiency minimums for server rack power distribution units with hot-swappable redundancy.
OEMs anchor design-win volumes. Data Centers is expanding most quickly as cloud infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial power supply consumption patterns diverge sharply between geographies. German chemical parks prioritize ultra-stable DC rectification for electrolytic processes. Taiwanese semiconductor fabs demand sub-microsecond transient response systems. Indian automotive clusters seek first-time regulated infrastructure.
Germany
Baden-Württemberg automotive press manufacturers and Bavarian electric vehicle battery facilities drive demand for synchronized multi-axis power delivery. The EU Ecodesign Directive tightens minimum efficiency requirements for industrial electrical equipment. North Rhine-Westphalia's chemical processing corridor requires hybrid AC-DC architectures with lithium-ion buffering for grid-stabilized microgrids.
Taiwan
300mm wafer fabrication expansion requires ultra-stable power conditioning for lithography and etching equipment. CE marking harmonization under the EU electromagnetic compatibility directive simplifies certification pathways for vendors targeting European supply chains. Hsinchu Science Park fabs mandate sub-4-millisecond UPS transfer times for semiconductor batch processes.
South Korea
Battery gigafactories in Gyeonggi Province demand rectifier-based DC architectures with voltage ripple tolerance below 50 millivolts for lithium-ion cell conditioning. The country's national industrial regulator enforces efficiency verification standards across automotive supply chains. Busan-Ulsan manufacturing belt is scaling power infrastructure investments for electrolytic process expansion.
India
Gujarat and Tamil Nadu automotive clusters generate first-time demand for regulated power infrastructure under the PLI scheme for industrial automation. The Bureau of Indian Standards mandates electromagnetic compatibility compliance for equipment deployments. Pune-Nashik manufacturing corridor adopts high-frequency switching modules for space-constrained cabinet installations.
United States
Data center operators in Northern Virginia and Texas specify 96% efficiency minimums for server rack power distribution units. OSHA electrical safety regulations constrain product specifications for industrial facility deployments. Arizona semiconductor fabrication expansion requires ultra-stable conditioning for advanced lithography systems.
Industrial Power Supply Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. European engineering houses anchor premium positioning through digital twin integration and predictive maintenance contracts. Asian manufacturers compete on production scale and cost-optimized switching module output. The vendor base organizes around three archetypes: integrated automation conglomerates, specialized power conversion houses, and contract manufacturing specialists. Dominant competitive moves include geographic expansion into India's manufacturing corridor and technology licensing agreements for wide-bandgap semiconductor integration.
Among European-based integrated suppliers, Siemens AG and ABB Ltd occupy positions exemplifying the bundled power-and-automation archetype, anchoring long-term service agreements through digital platform penetration. Delta Electronics Inc represents the scale-driven manufacturing tier competing on volume output across Asian industrial clusters. Phoenix Contact GmbH & Co KG sits within the specialized connectivity and power distribution segment, reflecting German engineering concentration in modular industrial infrastructure.
| Leading Market Players |
|---|
| Siemens AG |
| Delta Electronics Inc |
| ABB Ltd |
| TDK Corporation |
| Mean Well Enterprises Co Ltd |
| XP Power PLC |
| Murata Manufacturing Co Ltd |
| Phoenix Contact GmbH & Co KG |
| Advanced Energy Industries Inc |
| Others |
Value Chain & Pricing Dynamics
Japanese and South Korean grain-oriented electrical steel mills concentrate magnetic core material supply, anchoring margin pools in European power supply vendors who face allocation risk and input cost volatility when contracting for transformer-grade laminations.
Pricing Analysis
Long-term offtake agreements dominate procurement for semiconductor-grade power conditioning equipment, while spot purchasing persists for commodity switching modules. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified medical-grade supplies from basic CE-marked industrial units. Cost compression in economy-tier switching modules intensifies as Vietnamese and Indian contract manufacturers scale capacity. Automotive OEM procurement committees exhibit lowest price sensitivity due to functional safety certification requirements, while electronics assembly facilities in Southeast Asia drive hardest bargain on unit economics.
Supply Chain Analysis
Foxconn, Jabil, and Flex hold concentrated electronics manufacturing services capacity for power supply module assembly across Taiwan, China, and Mexico. Production draws from Japanese ferrite core suppliers, German magnetic wire specialists, and Chinese aluminum heatsink fabricators. Single-source vulnerability concentrates in silicon carbide substrate supply from Wolfspeed and Coherent facilities. Distribution runs through authorized industrial distributors like Arrow and Avnet in North America, plus direct OEM relationships for high-volume automotive and semiconductor fab contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating through German automotive OEM unbundling of hardware procurement from lifecycle service agreements, fragmenting vendor pricing power across separate CAPEX and OPEX budget owners.
For Market Incumbents: Harden predictive maintenance contract attach rates through embedded power quality analytics that lock in recurring revenue streams. Deepen backward integration into wide-bandgap semiconductor sourcing to mitigate silicon carbide allocation risk from Japanese and South Korean substrate suppliers. Secure dual-source qualification for magnetic core laminations to defend margin position against grain-oriented electrical steel price volatility. For New Entrants and Emerging Players: Pursue white-space opportunity in India's Gujarat and Tamil Nadu automotive clusters where PLI scheme incentives create first-time demand for regulated power infrastructure without entrenched incumbent relationships. Target battery gigafactory DC rectifier segments in South Korea where voltage ripple specifications below 50 millivolts create technical barriers that filter out commodity competitors. Lead with ISO 50001 energy management certification to access Japanese automotive supply chain procurement channels. For Investors and Strategic Acquirers: Capital is best deployed toward specialized power conversion houses with captive wide-bandgap semiconductor design capabilities and existing SIL 2/3 functional safety certifications for process industry applications. Long-term viability over the coming decade hinges on digital twin integration depth and predictive analytics attach rates rather than hardware shipment volumes alone. Monitor CE marking harmonization implementation timelines as inflection signal for European market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Wide-Bandgap Semiconductor Integration | Silicon carbide and gallium nitride adoption collapses thermal management requirements while enabling power density gains for compact servo drives. |
| Predictive Maintenance Platform Development | Embedded power quality analytics anchor long-term service agreements with German steel and chemical processing plant operators. |
| India Manufacturing Corridor Expansion | Gujarat and Tamil Nadu automotive clusters under PLI scheme generate first-time demand for regulated power infrastructure. |
| EU Ecodesign Directive Compliance Investment | Efficiency mandate redesign accelerates digital platform adoption across Baden-Württemberg and Bavarian heavy industry. |
| Battery Energy Storage Coupling | Hybrid AC-DC architectures with lithium-ion buffering open retrofit opportunities for grid-stabilized microgrids in North Rhine-Westphalia chemical parks. |
Study Parameters
Cross-validation between primary field engagement and secondary source triangulation anchors the qualitative findings in this analysis. Plant engineers, OEM procurement teams, aftermarket service heads, and power electronics R&D directors contributed structured interviews across German automotive clusters, Taiwanese semiconductor fabs, and Indian manufacturing corridors. Secondary validation incorporated SEC 10-K filings from listed power supply vendors, IEC technical committee documentation, EU Ecodesign Directive regulatory impact assessments, and customs trade data for magnetic core material flows. Bottom-up shipment modeling and top-down industrial automation capex aggregation were reconciled to establish volume baselines.
Calibration against historical efficiency mandate implementation curves and semiconductor fab construction cycles informed the projection framework across the analysis window. Segmentation dimensions modeled include conversion architecture type, switching frequency tier, embedded monitoring capability, end-use industry vertical, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating wide-bandgap semiconductor cost decline trajectories and predictive maintenance contract penetration assumptions. Forecast inputs specifically weighted EU F-Gas Regulation phase-down timelines and India PLI scheme incentive disbursement patterns.
Sensitivities concentrate around silicon carbide substrate supply expansion rates, EU Ecodesign Directive enforcement intensity, and German automotive OEM unbundling of procurement functions. Forecasts reflect documented assumptions regarding wide-bandgap semiconductor adoption curves and predictive analytics attach rate evolution. Quarterly review of CE marking harmonization progress, BIS electromagnetic compatibility mandate implementation, and Japanese grain-oriented electrical steel mill capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
3rd Rail Current Collector Market
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
Alternator Regulator Market
Electrical Power Equipment
Packaged Substation Market
Electrical Power Equipment
Transformer Oil Testers Market
Electrical Power Equipment
South America Medium Voltage Switchgear Market
Electrical Power Equipment
Electric Radiators Market
Electrical Power Equipment
Busway-Bus Duct Market
Electrical Power Equipment
Recloser Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Copper Ground Rod Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
India Gas Insulated Switchgear Market