
 North America Power Inverter Market | 2026-2036
North America Power Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
North America Power Inverter Market Intelligence
UL 1741 certification is reorganizing competitive access across the North America Power Inverter Market, forcing manufacturers to redesign control architectures before products qualify for utility interconnection. Enphase Energy leverages its microinverter specialization to dominate residential rooftop channels where module-level power electronics command premium positioning. SMA Solar Technology AG anchors its presence through centralized inverter scale and longstanding relationships with utility-scale developers. Schneider Electric SE differentiates through integrated energy management platforms that bundle power conversion with storage control software.
A power inverter converts direct current electricity into alternating current through semiconductor switching at frequencies typically ranging from 50 to 60 hertz, enabling photovoltaic arrays, battery banks, and fuel cells to feed standard electrical grids or power standalone loads. String inverters occupy the cost-optimized middle ground in commercial and utility installations where centralized string architecture balances efficiency against balance-of-system expenses. Microinverters capture residential margin pools by eliminating string mismatch losses and enabling per-panel monitoring, though per-watt premiums limit penetration beyond rooftop segments. Battery inverters represent the fastest-growing product category as hybrid and off-grid technology configurations expand across residential and commercial end users seeking resilience against grid instability.
FERC Order 2222 and IEEE 1547-2018 collectively reshape inverter functionality requirements, mandating grid-supportive capabilities including ride-through, volt-var control, and frequency-watt response that legacy units lack. EPA greenhouse gas regulations and state-level renewable portfolio standards in California, Texas, and New York accelerate replacement cycles and expand addressable demand for compliant equipment. NHTSA and Transport Canada rules on electric vehicle charging infrastructure indirectly stimulate bidirectional inverter development for vehicle-to-grid applications. Stakeholders must monitor how evolving interconnection standards and state-level storage mandates redefine product qualification timelines and competitive positioning across residential, commercial, and utility segments.
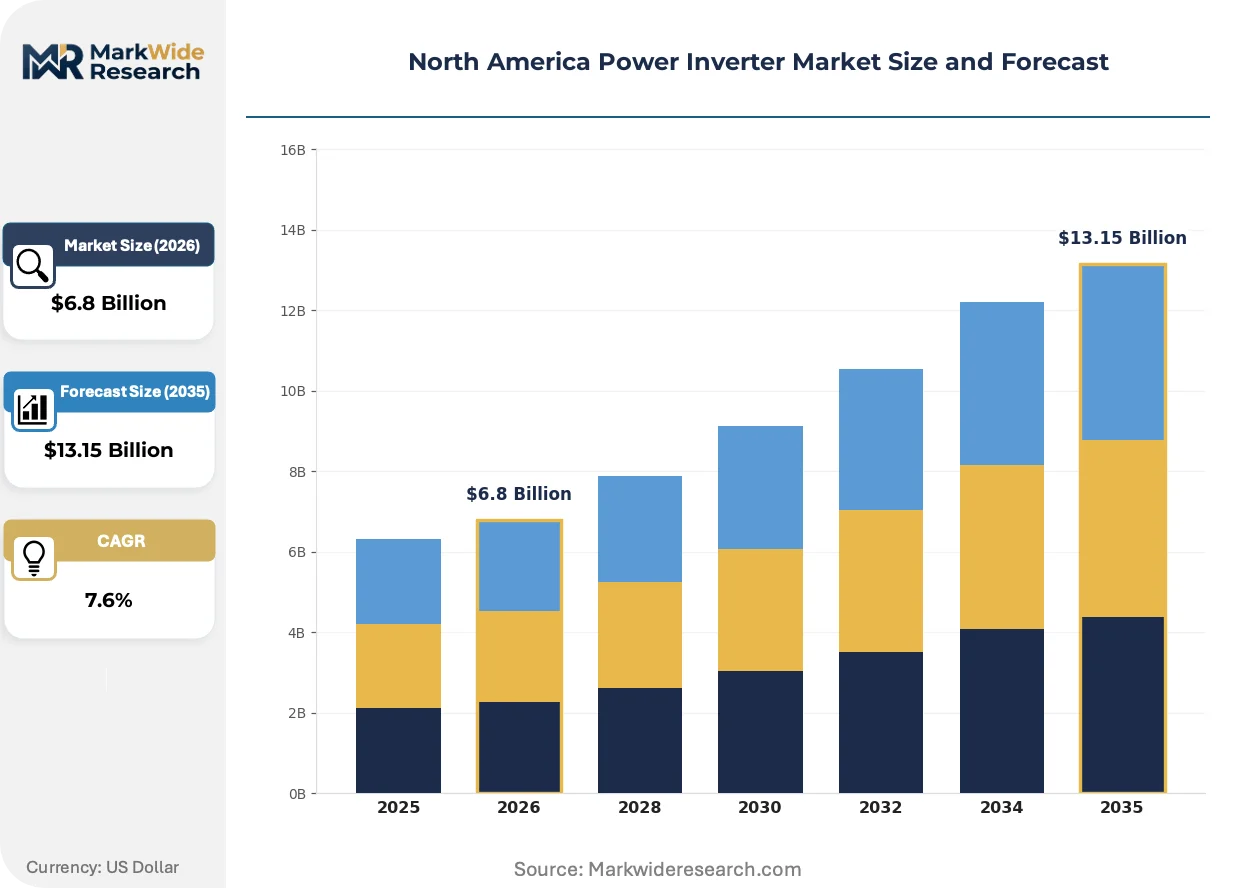
Market Dynamics
UL 1741-SA certification deadlines are compressing product development cycles across the North America Power Inverter Market, forcing manufacturers to prioritize grid-forming capabilities over legacy voltage-source designs. This regulatory inflection point favors firms with in-house firmware architectures capable of rapid control-loop iteration.
Growth Catalysts
- California SGIP incentives:State-level storage rebates accelerate residential battery inverter attachment rates, particularly in fire-prone utility districts where backup power commands premium valuation.
- Texas ERCOT grid instability:Repeated weather-driven outages drive suburban homeowners toward hybrid inverters with islanding capability, creating sustained demand for residential resilience products.
- Silicon carbide semiconductors:Wider bandgap materials enable higher switching frequencies that reduce magnetics size and cooling overhead in next-generation string inverter platforms.
Market Restraints
- IGBT and MOSFET supply concentration:Asian foundry dominance in power semiconductor fabrication exposes inverter OEMs to lead-time volatility and input cost spikes during capacity crunches.
- IEEE 1547-2018 compliance complexity:Multi-state certification requirements fragment product portfolios, forcing redundant testing cycles that extend time-to-revenue for new platform launches.
- Electrolytic capacitor lifespans:Thermal degradation of aluminum electrolytic components in outdoor enclosures limits warranty periods and drives replacement economics unfavorable to long-term ownership.
Strategic Opportunities
- Mexico distributed generation reform:Net metering expansion in Baja California and Sonora creates first-mover positioning for residential inverter vendors with Spanish-language support infrastructure.
- Vehicle-to-grid convergence:Bidirectional charging standards integration enables automotive OEMs to specify inverter-compatible home energy systems, opening a co-development channel.
- Utility-scale storage mandates:New York's accelerated renewable targets require co-located solar-plus-storage configurations that favor central inverter architectures with integrated DC-coupled battery interfaces.
Industry Challenges
- Firmware engineering scarcity:Grid-code compliance expertise concentrates in a narrow talent pool, inflating compensation costs and slowing control algorithm validation timelines.
- Legacy SCADA integration:Utility-scale projects demand Modbus and DNP3 protocol compatibility with aging distribution management systems, complicating software stack architecture decisions.
- UL 1741-SA certification backlog:Testing laboratory capacity constraints extend qualification timelines by six to nine months, delaying product launches past peak construction seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Power Inverter Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverter, Microinverter, Central Inverter, Battery Inverter Technology: Grid-Tied, Off-Grid, Hybrid, Standalone End User: Residential, Commercial, Industrial, Utilities Installation Type: Roof-mounted, Ground-mounted, Portable, Others |
| Companies Covered | Enphase Energy, SolarEdge Technologies, SMA Solar Technology AG, ABB Ltd., Schneider Electric SE, Delta Electronics Inc., Eaton Corporation, General Electric (GE Renewable Energy), Fronius International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Power Inverter Market Strategic Shifts & Innovations
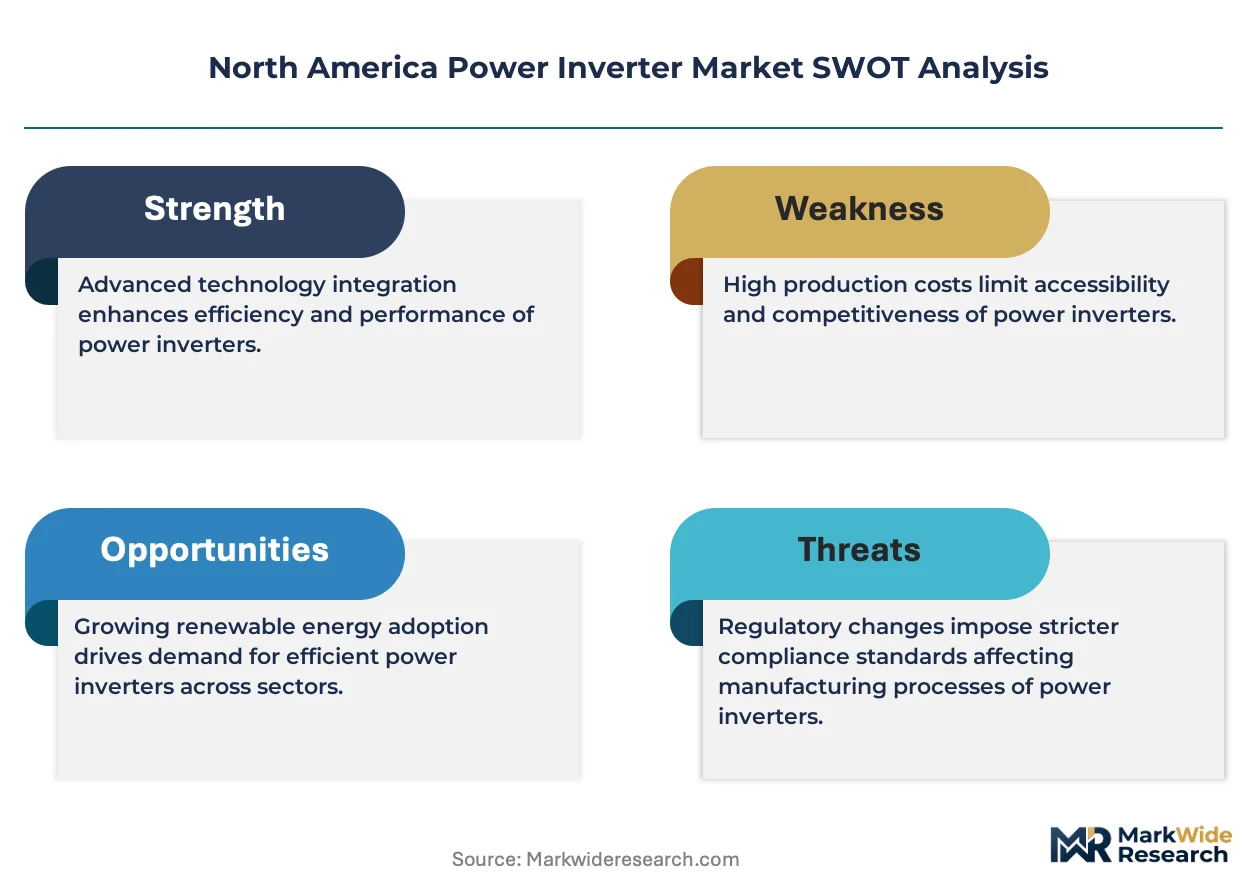
Power conversion topology is fragmenting into parallel development tracks optimized for either cost-minimized utility deployment or feature-dense residential resilience. This divergence pressures mid-market string inverter vendors to clarify segment commitment or risk margin compression from both directions.
Silicon carbide MOSFETs are bifurcating inverter design philosophy between high-frequency compact architectures and traditional silicon-based cost-optimized platforms. Utility-scale developers in Texas and California are adopting SiC-based central inverters for 1500V DC systems where efficiency gains offset semiconductor premiums. The technology is bifurcating vendor R&D budgets toward either premium efficiency leadership or manufacturing scale economies, with limited middle ground for undifferentiated competitors.
FERC Order 2222 aggregation rules are mandating distributed energy resource interoperability standards that inverter manufacturers must embed at the firmware level. This policy compresses competitive differentiation around software-defined grid services rather than hardware efficiency metrics alone. Commercial and industrial behind-the-meter installations across PJM and CAISO territories are responding by specifying inverters with pre-certified autonomous grid-support functionality.
Buyer preference is hardening around integrated energy management platforms that unify solar, storage, and load control through single-vendor software ecosystems. Traditional equipment-only procurement models in the residential channel are losing share to bundled hardware-software offerings with subscription-based monitoring. This pattern concentrates in California's suburban markets where time-of-use rate structures reward automated demand response coordination.
North America Power Inverter Market Segmentation
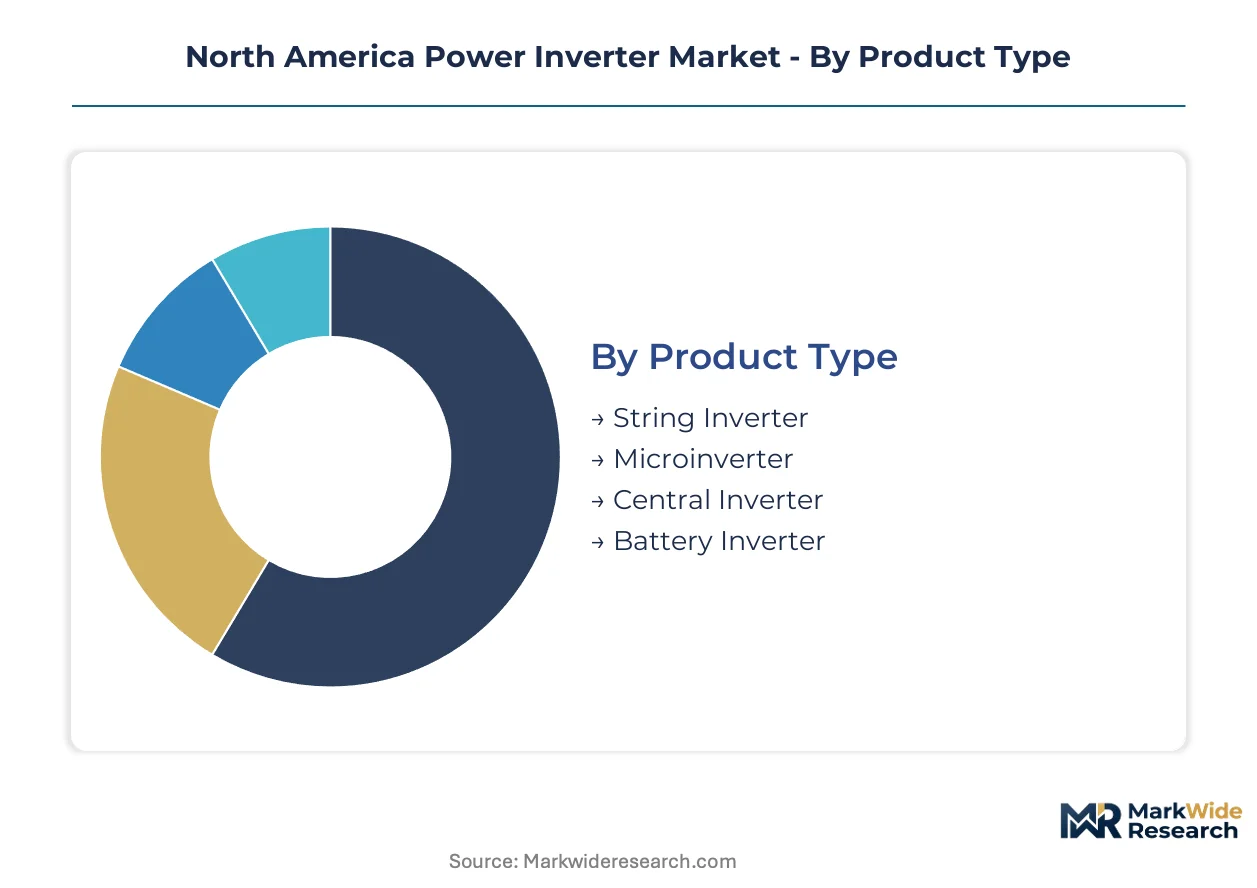
Power inverter segmentation in North America reflects divergent optimization targets across grid-scale efficiency, residential resilience, and commercial flexibility. Technology choices cascade through certification requirements, semiconductor material selection, and firmware architecture decisions that lock in competitive positioning.
Product Type:
Margin pools concentrate in residential microinverters and utility-scale central inverters, while string inverters face compression from both directions.
- String Inverter:These units aggregate DC input from multiple solar panels into a single AC output stage, typically rated between 3kW and 150kW. Commercial installations across Texas and California favor string architectures where balance-of-system cost reduction outweighs module-level optimization premiums. String inverters hold installed capacity. Battery inverters are rotating up the share rankings.
- Microinverter:Module-level power electronics convert DC to AC at each individual panel, eliminating string mismatch losses and enabling per-panel monitoring. Suburban California rooftops command premium positioning for these units where shading complexity and fire safety codes justify per-watt premiums. Microinverter attachment rates climb fastest in SGIP-eligible districts where storage pairing mandates sophisticated AC coupling.
- Central Inverter:Utility-scale conversion platforms handling 1MW+ blocks of DC capacity through centralized transformer coupling. ERCOT and CAISO interconnection queues favor these architectures for 1500V DC solar farms where economies of scale dominate procurement decisions.
- Battery Inverter:Bidirectional conversion hardware enabling DC-coupled or AC-coupled storage integration with grid-forming capabilities. Texas residential demand surges for hybrid configurations that island during weather-driven outages.
Central inverters dominate utility-scale procurement volumes. Battery inverters are climbing the fastest expansion trajectory.
Technology:
Application requirements split the technology map between grid-interactive compliance burdens and off-grid simplicity.
- Grid-Tied:Synchronous inverters matching grid frequency and voltage without storage capability, optimized for pure solar export. IEEE 1547-2018 ride-through mandates force firmware redesigns that extend development cycles for these units. Grid-tied maintains volume leadership. Hybrid is rotating up the share rankings.
- Off-Grid:Standalone conversion systems with battery charging logic and no grid interconnection capability. Remote installations across northern Canada and Mexican rural electrification programs sustain demand for these simpler architectures.
- Hybrid:Integrated solar-plus-storage inverters with islanding capability and bidirectional power flow. California's time-of-use rate structures and backup power premiums concentrate residential demand for these feature-dense platforms.
- Standalone:Diesel or battery-fed inverters for backup power without renewable input, common in critical infrastructure applications where fuel security outweighs solar economics.
Grid-tied units face replacement pressure from hybrid alternatives. Off-grid holds niche positioning in remote geographies.
End User:
Customer type determines pricing power, with utilities extracting scale discounts and residential segments absorbing premium positioning.
- Residential:Single-family and multifamily rooftop installations typically 5-20kW in capacity. California suburban markets and Texas resilience buyers drive specification toward monitoring-enabled, warranty-backed platforms with installer network support. Residential commands margin premiums. Commercial is rotating up the share rankings.
- Commercial:Behind-the-meter installations for retail, warehousing, and office facilities, usually 50kW-1MW. PJM demand response programs and California NEM 3.0 economics reshape procurement toward storage-integrated solutions.
- Industrial:Manufacturing and heavy process loads with high power quality requirements and voltage sag sensitivity. These buyers specify central inverters with active filtering and power factor correction.
- Utilities:Investor-owned and public power entities procuring bulk solar and storage resources. FERC Order 2222 aggregation rules mandate interoperability standards that concentrate vendor selection around pre-certified grid-support functionality.
Utilities anchor procurement volumes. Commercial behind-the-meter is gaining share fastest.
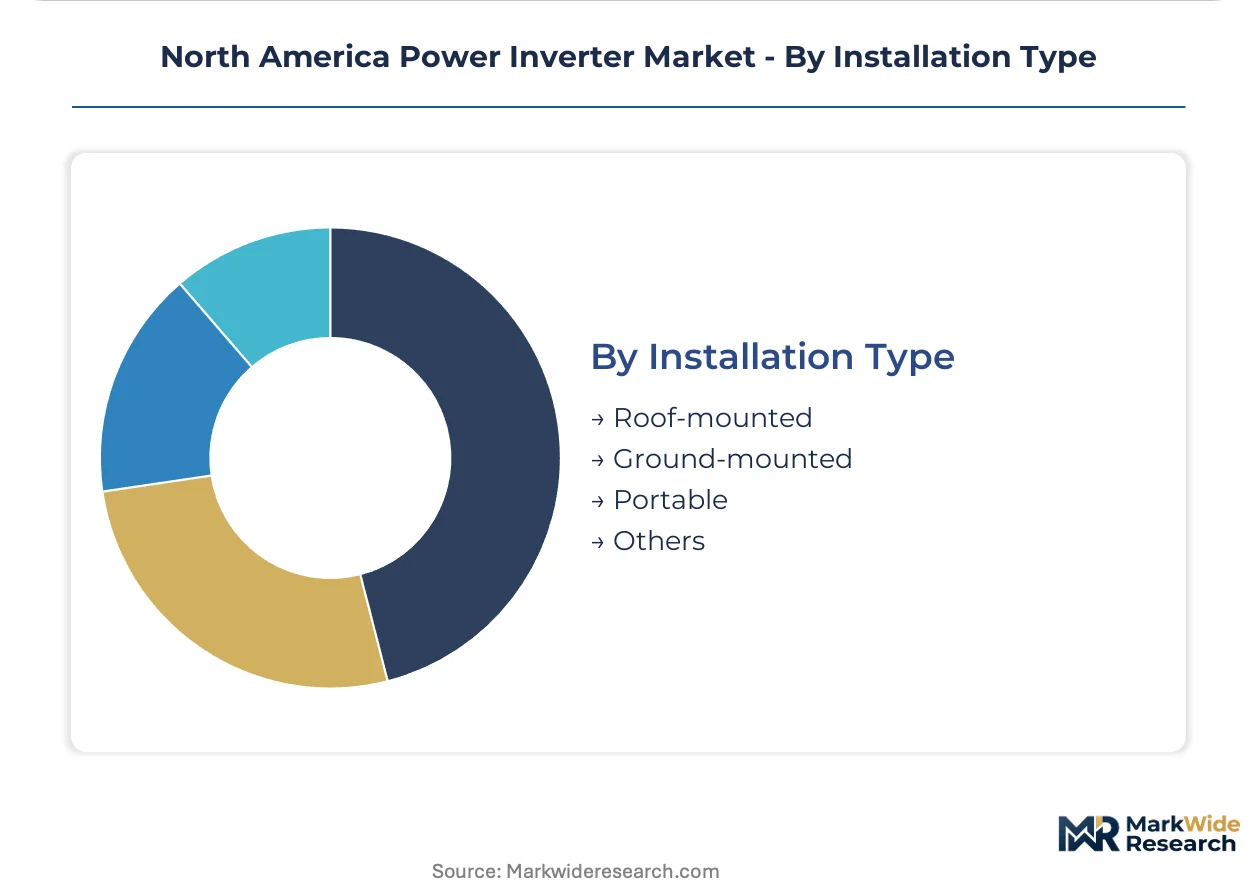
Installation Type:
Mounting configuration constrains thermal management, wiring topology, and maintenance access economics.
- Roof-mounted:Residential and commercial building-integrated arrays where weight, wind loading, and fire setback codes constrain inverter placement. California Title 24 requirements accelerate microinverter preference for these installations. Roof-mounted dominates residential attachment. Ground-mounted is rotating up the share rankings.
- Ground-mounted:Utility-scale and large commercial arrays on dedicated land with optimized tilt and tracking. Texas and California solar farms favor central or string inverter architectures with skid-mounted or containerized housing.
- Portable:Mobile inverter units for construction, events, and emergency response, typically gasoline-generator replacements or solar-generator combinations. These units prioritize plug-and-play interfaces over efficiency optimization.
- Others:Floating solar, agrivoltaic, and building-integrated photovoltaic configurations with specialized environmental sealing and corrosion resistance requirements.
Ground-mounted arrays capture utility-scale deployment. Portable is climbing fastest in disaster response procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale developers and suburban residential buyers concentrate procurement across three distinct national markets with divergent regulatory timelines and grid infrastructure maturity.
United States
ERCOT grid instability and California SGIP storage incentives drive hybrid inverter demand across Texas suburbs and fire-prone utility districts. FERC Order 2222 mandates distributed energy resource interoperability standards that reshape firmware requirements for grid-tied equipment. Installation clusters concentrate in California's Central Valley solar farms and Houston-area residential developments seeking islanding capability.
Canada
Remote electrification programs and northern mining operations sustain off-grid inverter demand in Yukon and Northwest Territories. Transport Canada rules on electric vehicle charging infrastructure stimulate bidirectional inverter development for vehicle-to-grid pilot programs. Industrial procurement centers on Ontario's manufacturing corridor where power quality requirements favor central inverter architectures with active filtering.
Mexico
Net metering expansion in Baja California and Sonora creates residential inverter opportunities as distributed generation reform accelerates. The country's national energy regulator implements interconnection standards that favor equipment with pre-certified grid-support functionality. Commercial deployment clusters in Monterrey's industrial parks and Mexico City's commercial districts where behind-the-meter storage integration commands premium positioning.
North America Power Inverter Market Key Industry Players
Player mix skews toward diversified electrical equipment conglomerates with power electronics divisions, creating a tiered structure where pure-play solar specialists compete against industrial-scale manufacturers with broader energy portfolios. Strategic archetypes include microinverter-focused residential channel specialists, utility-scale central inverter scale players, and integrated energy management platform bundlers. Dominant competitive moves center on firmware architecture investments for grid-forming compliance and strategic partnerships with automotive OEMs for vehicle-to-grid convergence.
Among North American residential channel specialists, Enphase Energy and SolarEdge Technologies exemplify the module-level power electronics archetype where per-panel optimization commands suburban rooftop premiums. SMA Solar Technology AG anchors the utility-scale tier with German engineering heritage and longstanding developer relationships. Schneider Electric SE occupies a position bridging industrial electrical equipment scale with software-defined energy management integration.
| Leading Market Players |
|---|
| Enphase Energy |
| SolarEdge Technologies |
| SMA Solar Technology AG |
| ABB Ltd. |
| Schneider Electric SE |
| Delta Electronics Inc. |
| Eaton Corporation |
| General Electric (GE Renewable Energy) |
| Fronius International |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between utility-scale developers and inverter OEMs lock in semiconductor allocation and provide price visibility across volatile raw material cycles. These contracts tether pricing to silicon wafer and copper magnetics indices, transferring commodity risk while securing capacity for grid-scale deployment timelines.
Pricing Analysis
Cost-plus contracts with LME aluminum and silicon wafer indexation dominate utility-scale procurement, while residential channels favor fixed-price bundled hardware-software packages. Price differentiation hinges on UL 1741-SA certification tier and volume scale, with certified central inverters commanding premiums over uncertified alternatives. Cost compression in string inverter tiers is intensifying due to silicon carbide MOSFET adoption spreading from premium to mid-market segments. Utility buyers exhibit lowest price sensitivity, prioritizing grid-forming firmware and warranty length over per-watt economics.
Supply Chain Analysis
China and Taiwan anchor power semiconductor fabrication, with Malaysia and Mexico handling final assembly and testing for North American delivery. IGBT and silicon carbide wafer supply draws from Asian foundry concentration, while aluminum enclosures and magnetics source from domestic metal processors. Single-source vulnerability in 1500V-rated semiconductor modules exposes OEMs to allocation constraints during capacity crunches. Distribution runs through EPC contractors and electrical distributors, with direct OEM relationships gaining share in utility-scale procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates around firmware specialization as FERC Order 2222 and IEEE 1547-2018 splinter competitive requirements across grid-interactive, grid-forming, and islanding configurations. Demand-side shift toward integrated energy management platforms creates niches for software-native entrants alongside hardware incumbents.
For Market Incumbents: Shield residential channel position through captive installer network expansion and preemptive UL 1741-SA certification for full product portfolios. Firmware engineering scarcity threatens margin pools as grid-code compliance costs inflate; backward integration into power semiconductor sourcing mitigates foundry allocation risk. Prioritize Texas and California utility relationships where storage mandates accelerate replacement cycles. For New Entrants and Emerging Players: UL 1741-SA certification fast-track through third-party firmware licensing opens residential microinverter white space in Mexico's net metering expansion zones. Texas ERCOT resilience demand and California SGIP districts present the most penetrable geographies for hybrid inverter specialization. Channel partnership with regional electrical distributors accelerates market access without captive sales force investment. For Investors and Strategic Acquirers: Grid-forming firmware specialists with automotive OEM vehicle-to-grid development contracts represent the priority acquisition archetype. Long-term viability favors platforms spanning residential, commercial, and utility segments with software-defined energy management integration. Signal to monitor: bidirectional charging standard ratification by SAE International and Transport Canada as inflection indicator for residential V2G attach rates.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Platform Migration | 1500V central inverter efficiency gains offset semiconductor premiums in ERCOT and CAISO queues. |
| Grid-Forming Firmware Certification | UL 1741-SA pre-qualification compresses interconnection timelines for utility-scale developers. |
| Vehicle-to-Grid Partnership | Automotive OEM co-development opens residential bidirectional charging attach rate expansion. |
| Mexico Distribution Buildout | Spanish-language support infrastructure captures net metering reform in Baja California and Sonora. |
| Integrated Energy Management Platform | Single-vendor solar-storage-load control bundles displace equipment-only procurement in California suburban markets. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with utility procurement officers, IPP project developers, EPC contractors, and inverter OEM product managers; and secondary validation against FERC interconnection filings, EIA generation capacity databases, IEEE standards documentation, and state-level SGIP program records. Bottom-up project pipeline aggregation triangulated against top-down manufacturer shipment estimates.
Across the analysis window, the forecasting framework modeled segmentation by product architecture, end-user scale tier, grid-interconnection technology, and regional regulatory cluster. CAGRs derived from unit shipment trajectories and average selling price evolution by certification tier. Key inputs included ERCOT interconnection queue data, California NEM 3.0 adoption curves, and silicon carbide semiconductor penetration assumptions.
Decision-makers should treat outputs as directional under stable interconnection standard timelines and continued state storage incentive funding; material deviation in federal tax credit policy or foundry capacity expansion would warrant model refresh. Recalibration cycles align with material shifts in IEEE 1547 revision schedules and FERC distributed energy resource aggregation rulemakings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
South America Medium Voltage Switchgear Market
Electrical Power Equipment
Global Air Insulated Switchgear Market
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
Magneto Optic Current Transformer Market
Electrical Power Equipment
North America Protective Relays Market
Electrical Power Equipment
Bucket Water Heater Market
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
Storage Water Heater Market
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
Asia-Pacific Air-Insulated Switchgear Market
Electrical Power Equipment
United States Electric Space Heaters Market
Electrical Power Equipment
Switching Residential Voltage Regulator Market
Electrical Power Equipment
Digital Fault Recorder (DFR) Market
Electrical Power Equipment
Train Contactor Market
Electrical Power Equipment
Subsea Cables Equipment Market