
 Middle East and Africa High Voltage Switchgear Market | 2026-2036
Middle East and Africa High Voltage Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa High Voltage Switchgear Market Insights
EU F-Gas Regulation alignment is expanding procurement criteria for Gulf utilities, compelling suppliers to certify low-emission switchgear designs. Siemens AG leverages its European manufacturing base to pre-certify SF6 alternatives for Middle Eastern tender requirements. ABB Ltd anchors regional service networks across Saudi Arabia and the UAE, sustaining long-term maintenance contracts with national transmission operators. Alfanar Group competes on localized assembly capacity, positioning its Riyadh facilities to meet domestic content thresholds in Saudi infrastructure bids.
High voltage switchgear encompasses electrical disconnect, protection, and control apparatus rated above 36 kV, engineered with vacuum, SF6, or air insulation mediums to interrupt fault currents and isolate grid segments. The equipment forms critical nodes in transmission networks, substations, and heavy industrial power distribution where reliability and arc containment determine system uptime. Gas insulated switchgear commands premium positioning in the Gulf's space-constrained urban substations and offshore platforms, while air insulated variants retain cost advantages for rural African transmission corridors. Digital technology integration across monitoring and diagnostic functions represents the fastest-growing capability layer, though analog and conventional architectures still dominate installed bases requiring phased retrofit cycles.
Saudi Standards, Metrology and Quality Organization (SASO) and South African Bureau of Standards (SABS) enforce product conformity and grid code compliance, filtering market access to certified manufacturers. The UAE's Ministry of Energy and Infrastructure coordinates federal electrification standards with emirate-level building codes, creating layered approval pathways for switchgear deployment in Dubai's dense commercial zones versus Abu Dhabi's industrial corridors. Stakeholders must monitor evolving Gulf Cooperation Council harmonization timelines and African Power Pool interconnectivity roadmaps to anticipate procurement standardization and cross-border project financing shifts.
Market Dynamics
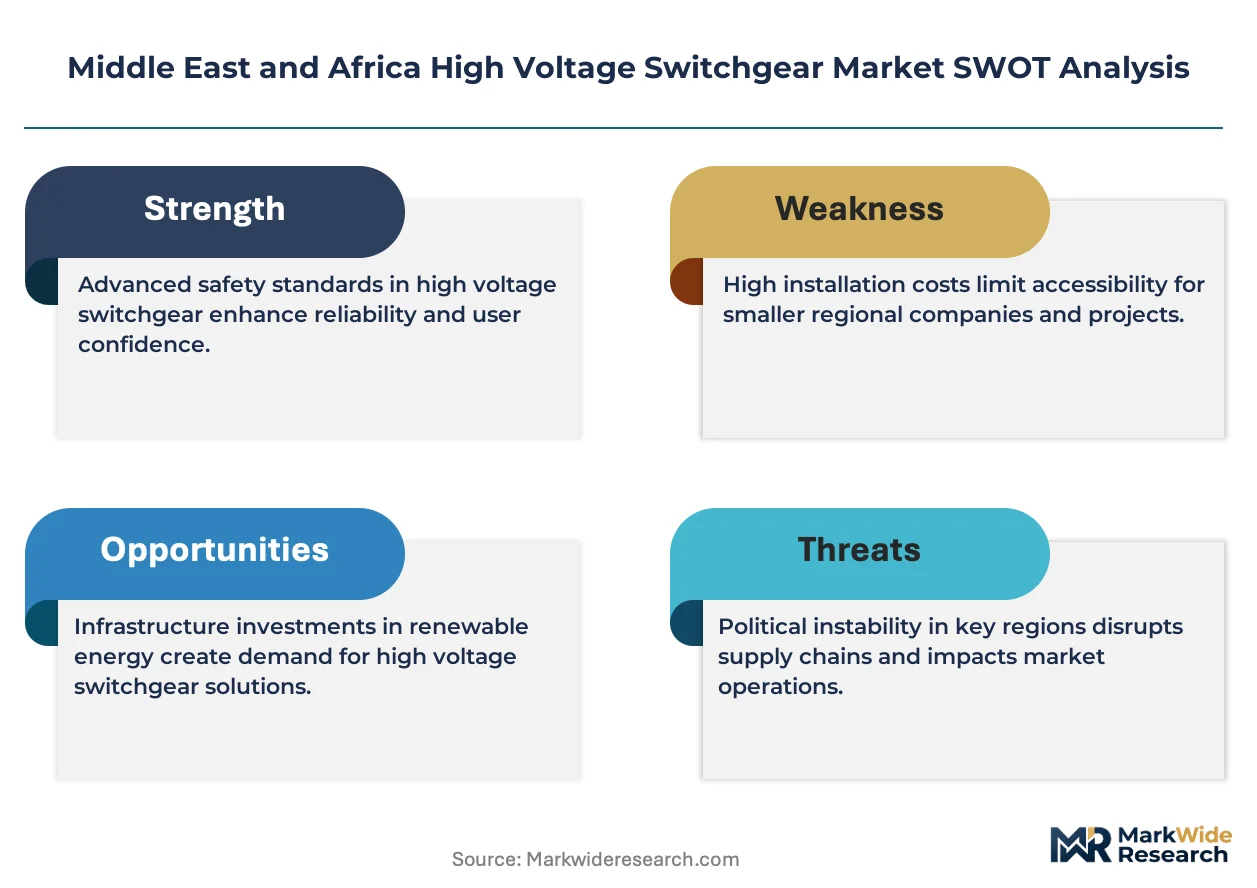
EU F-Gas Regulation alignment is compelling Gulf utilities to rewrite procurement specifications, redirecting capital toward SF6-free gas insulated systems and compressing certification timelines for European suppliers with pre-validated alternative designs.
Growth Catalysts
- Utility-scale renewable integration:South African solar developers and Gulf wind operators are scaling high voltage switchgear procurement to connect gigawatt-scale generation to national grids.
- SASO domestic content thresholds:Saudi infrastructure bids now mandate localized assembly, stimulating Riyadh-based manufacturing capacity for transmission expansion programs.
- SF6 phase-out mandates:The EU F-Gas Regulation is reshaping Gulf tender criteria, accelerating demand for vacuum and air-insulated alternatives in space-constrained urban substations.
Market Restraints
- Copper and aluminum price volatility:Raw material cost swings compress margins for air insulated switchgear producers serving price-sensitive African transmission corridors.
- European supply concentration:SF6-free gas insulated system manufacturing clusters in Germany and Switzerland create import dependency for Gulf utilities seeking rapid certification.
- Technical limitation of vacuum interrupters:Current designs face ampacity ceilings above 72.5 kV that constrain deployment in ultra-high voltage transmission nodes.
Strategic Opportunities
- Egyptian transmission expansion:National utility execution of desert-to-delta power corridors creates procurement windows for digital-enabled switchgear with integrated monitoring.
- Regulatory tailwind from GCC harmonization:Pending Gulf Cooperation Council standard alignment will streamline cross-border project financing and reduce duplicate certification costs.
- Technology convergence of switchgear and edge computing:Embedded diagnostic processors are enabling predictive maintenance contracts that unbundle hardware from service revenue streams.
Industry Challenges
- Specialized commissioning engineer scarcity:Gas insulated system installation and SF6 handling certification programs lag deployment timelines in Saudi Arabia and the UAE.
- Legacy analog retrofit complexity:Phased digital upgrades of installed base equipment require interoperability engineering that extends project cycles and inflates integration costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa High Voltage Switchgear Market |
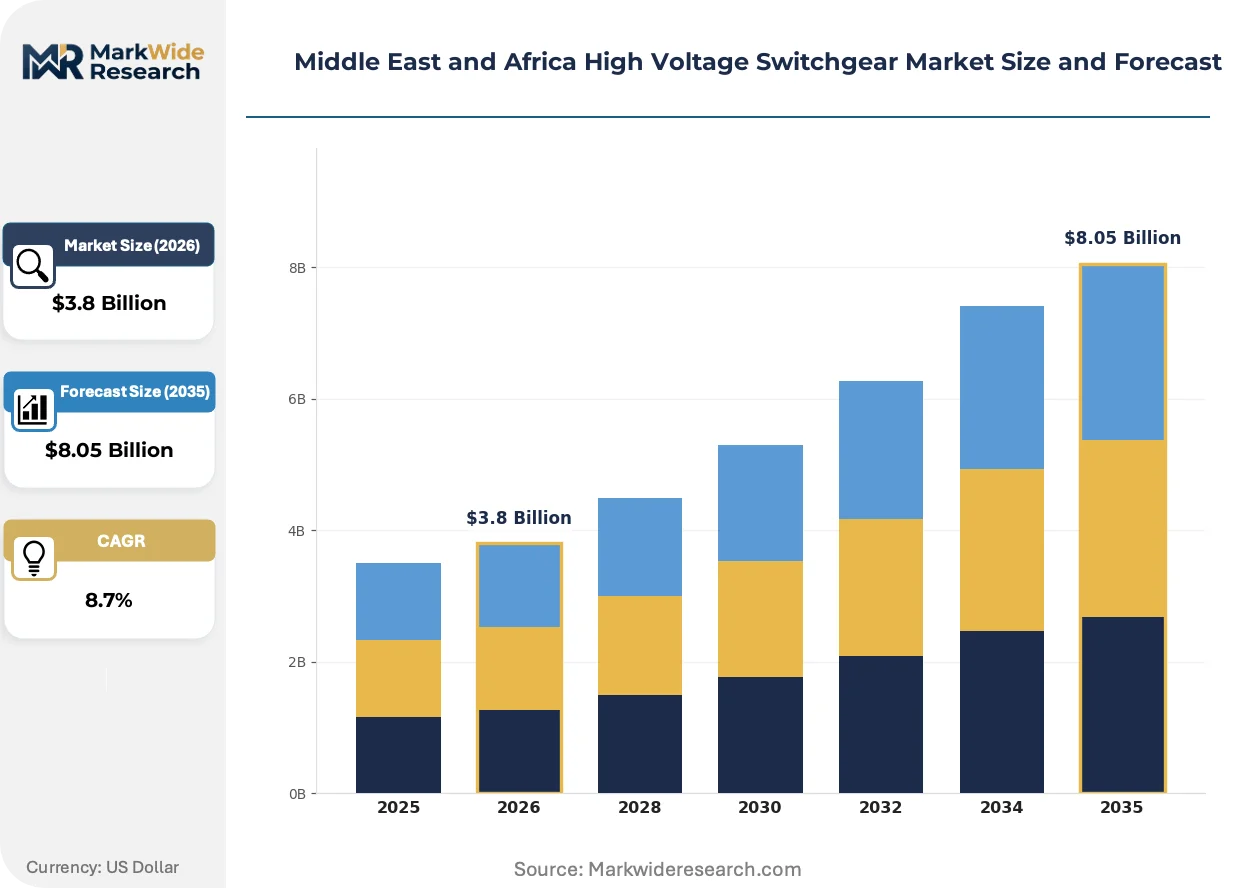
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Insulated Switchgear, Air Insulated Switchgear, Hybrid Switchgear, Others End User: Utilities, Industrial, Commercial, Renewable Energy Installation: Indoor, Outdoor, Underground, Mobile Technology: Digital, Analog, Smart, Conventional |
| Companies Covered | Schneider Electric SE, Siemens AG, ABB Ltd, Hitachi Energy Ltd, General Electric Company, Alfanar Group, Larsen & Toubro Limited, Mitsubishi Electric Corporation, Bharat Heavy Electricals Limited, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa High Voltage Switchgear Market Trends and Innovations
Digital technology integration is compressing the traditional divide between primary switching equipment and grid management software, enabling real-time fault prediction and remote arc containment that redefines operational uptime expectations.
Hybrid gas-vacuum interruption technology is unifying the compact footprint of SF6 insulation with the environmental compliance of vacuum breaking. Saudi Aramco and UAE transmission operators are piloting these systems in offshore platforms and dense Dubai substations where space constraints meet sustainability mandates. This convergence is collapsing the historical premium gap between gas insulated and air insulated architectures.
The EU F-Gas Regulation is mandating comprehensive leak monitoring and end-of-life gas recovery protocols that extend manufacturer liability chains. Gulf utilities are importing these compliance frameworks into tender documents ahead of formal GCC adoption, forcing suppliers to certify cradle-to-grave environmental accountability. Air insulated switchgear retains cost advantage in rural African corridors where regulatory enforcement remains fragmented.
Buyers are consolidating procurement authority into centralized technical committees that bypass traditional distributor networks. Saudi Electricity Company and Etihad Water and Electricity now direct-source through framework agreements with certified manufacturers, compressing channel margins and demanding embedded service commitments. This concentration is most visible in Saudi Arabia's transmission expansion program, where multi-year maintenance contracts now accompany hardware awards as standard terms.
Middle East and Africa High Voltage Switchgear Market Segmentation
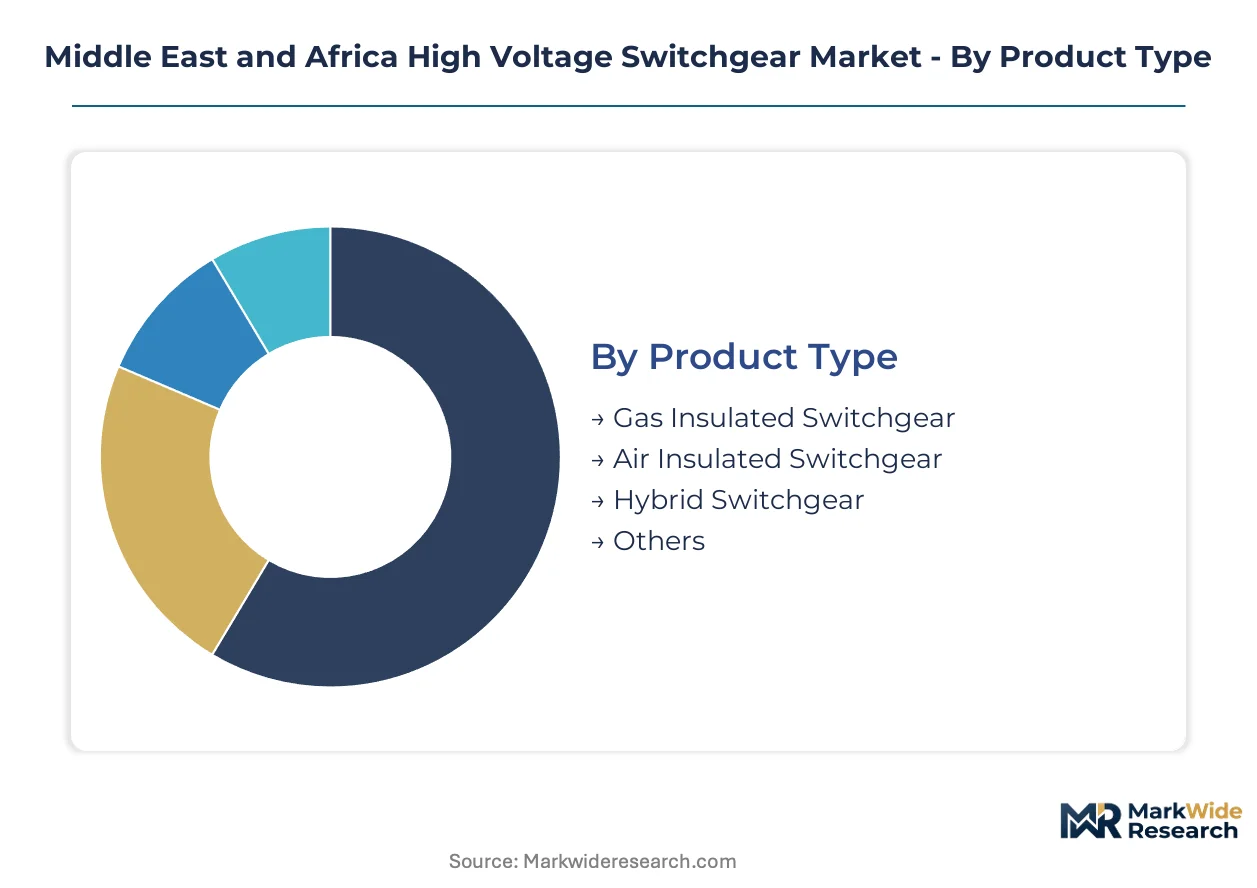
High voltage switchgear procurement across the Middle East and Africa fragments across four critical dimensions: product architecture determines footprint and environmental compliance; end-use concentration shapes volume timing; installation context dictates engineering specifications; and technology tier separates legacy replacement from greenfield digital deployment.
Product Type:
Integration depth varies sharply—gas insulated systems embed into dense urban infrastructure and offshore platforms, while air insulated variants operate as standalone nodes in rural transmission corridors.
- Gas Insulated Switchgear:SF6 or alternative gas-insulated designs achieve compact footprints through phase encapsulation, enabling 145 kV ratings in one-tenth the space of air insulated equivalents. Saudi Aramco and UAE transmission operators specify these for Dubai substations and Gulf offshore platforms where real estate constraints collide with EU F-Gas Regulation alignment pressures.
- Air Insulated Switchgear:Open-air conductor arrangements with porcelain or composite insulators deliver cost efficiency at voltage classes through 245 kV. Procurement concentrates in Egypt's desert-to-delta corridors and South African rural networks where capital efficiency outweighs space constraints and regulatory enforcement remains fragmented.
- Hybrid Switchgear:Combines gas insulation for busbars with vacuum interruption for circuit breakers.
- Others:Solid dielectric and minimum oil designs serving niche retrofit applications.
Volume placements concentrate in Air Insulated Switchgear; the faster expansion belongs to Gas Insulated Switchgear.
End User:
Cost tier stratification separates centralized utility procurement—driven by national transmission expansion programs—from fragmented industrial and commercial buyers prioritizing operational continuity over capital efficiency.
- Utilities:National transmission operators in Saudi Arabia, the UAE, and Egypt execute framework agreements for substation infrastructure. Saudi Electricity Company and Etihad Water and Electricity direct-source through multi-year maintenance contracts that bundle hardware with embedded service commitments.
- Industrial:Heavy manufacturing, petrochemical, and mining operations require arc-resistant switchgear for process continuity.
- Commercial:Data centers, airports, and hospital complexes specify compact indoor installations with integrated monitoring.
- Renewable Energy:South African solar developers and Gulf wind operators scale procurement to connect gigawatt-scale generation to national grids, with digital-enabled switchgear commanding premium positioning for remote fault prediction capabilities.
Revenue concentration sits with Utilities; Renewable Energy is climbing the fastest.
Installation:
Application context determines enclosure engineering—indoor and underground deployments demand corrosion-resistant sealing for Gulf humidity, while outdoor and mobile configurations prioritize seismic and thermal cycling resilience.
- Indoor:Metal-enclosed designs with IP-rated sealing protect against Gulf coastal humidity and dust intrusion in Dubai commercial zones and Riyadh industrial facilities.
- Outdoor:Open-air installations with weatherproofing for temperature extremes and sand exposure.
- Underground:Compact gas insulated systems for dense urban corridors with severe surface space constraints.
- Mobile:Skid-mounted or trailer configurations for emergency restoration and temporary construction power.
Deployment frequency peaks with Outdoor installations; Underground configurations are gaining share fastest.
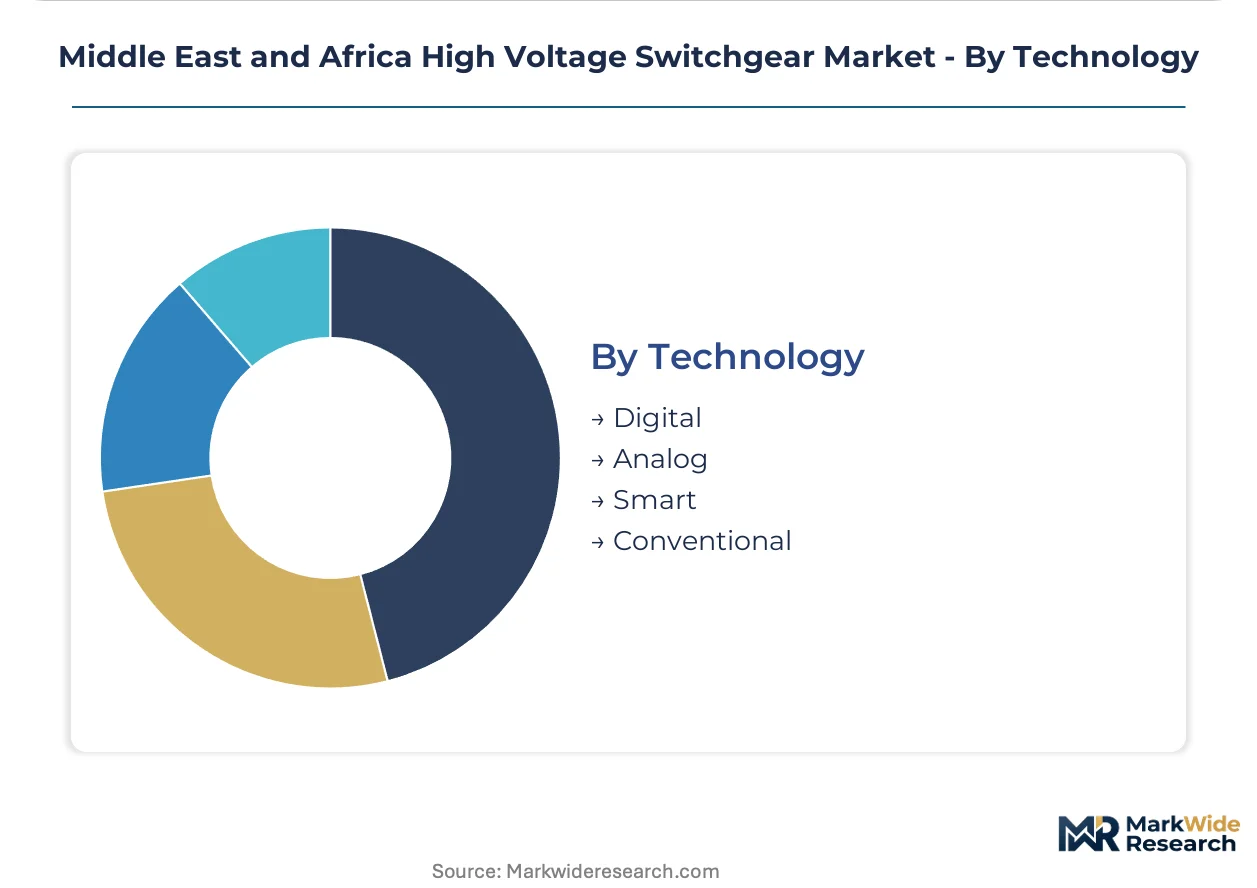
Technology:
Customer type separates state utilities with phased digital roadmaps from private operators demanding immediate predictive maintenance capabilities.
- Digital:Embedded diagnostic processors enable real-time fault prediction and remote arc containment, redefining operational uptime expectations. Saudi Electricity Company pilots these for predictive maintenance contracts that unbundle hardware from service revenue streams.
- Smart:Partial digital integration with communication protocols for SCADA connectivity.
- Analog:Electromechanical protection and manual operation dominate installed bases requiring phased retrofit cycles.
- Conventional:Non-digital architectures with basic monitoring for price-sensitive African transmission corridors.
Installed base dominance remains with Analog; Digital platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in European and Asian manufacturing clusters while consumption pulls disproportionately toward Gulf utilities executing transmission expansion. Saudi Arabia, the UAE, and Egypt absorb the dominant procurement volumes as national electrification programs accelerate.
Saudi Arabia
Saudi Electricity Company directs multi-billion dollar procurement for desert-to-urban transmission corridors and gigawatt-scale renewable integration. SASO domestic content mandates now require localized assembly for infrastructure bids, stimulating Riyadh-based manufacturing investments. The Eastern Province industrial cluster anchors petrochemical power demand while NEOM Northwest tests next-generation digital substation architectures.
United Arab Emirates
Etihad Water and Electricity consolidates procurement authority through direct-source framework agreements with certified manufacturers. MOHAP and federal energy regulators coordinate emirate-level building codes that layer approval pathways for Dubai commercial zones versus Abu Dhabi industrial corridors. Offshore platform electrification and dense urban substations drive premium gas insulated system demand.
Egypt
The Egyptian Electricity Transmission Company executes desert-to-delta power corridor programs requiring high voltage switching nodes for capacity expansion. National regulators enforce grid code compliance filtering market access to certified manufacturers. New Cairo and the Suez Canal Economic Zone concentrate industrial load growth demanding reliable arc containment systems.
South Africa
Eskom and independent renewable developers scale procurement to connect utility-scale solar and wind generation to the national grid. SABS product conformity standards enforce technical specifications for transmission equipment. The Northern Cape solar cluster and Eastern Cape wind corridors represent the fastest-growing demand nodes for digital-enabled switchgear with remote monitoring capabilities.
Qatar
Kahramaa directs infrastructure procurement for stadium-to-utility network expansion following major event-driven electrification investments. National regulators align tender specifications with emerging GCC harmonization timelines. Lusail City and Ras Laffan industrial zones concentrate demand for compact substation solutions in space-constrained coastal environments.
Middle East and Africa High Voltage Switchgear Market Competitive Landscape
The competitive structure tilts toward diversified electrical equipment conglomerates with established regional service networks. European and Asian manufacturers anchor premium technology tiers while localized assemblers capture domestic content-mandated procurement. Three archetypes dominate: integrated technology providers with pre-certified SF6 alternatives, regional specialists leveraging in-country assembly capacity, and scale-driven industrial conglomerates with captive utility relationships. Competitive intensity centers on certification speed for environmental compliance and multi-year maintenance contract bundling.
Among European-based integrated providers, Siemens AG and ABB Ltd exemplify the technology-certification archetype with pre-validated alternative gas designs. Alfanar Group represents the localization-focused tier, anchoring Saudi domestic content requirements through Riyadh assembly facilities. These three occupy distinct positioning vectors—Siemens AG and ABB Ltd leverage European regulatory alignment for Gulf tender compliance, while Alfanar Group converts proximity advantages into infrastructure bid participation.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Siemens AG |
| ABB Ltd |
| Hitachi Energy Ltd |
| General Electric Company |
| Alfanar Group |
| Larsen & Toubro Limited |
| Mitsubishi Electric Corporation |
| Bharat Heavy Electricals Limited |
| Others |
Pricing and Supply Chain Analysis
Centralized utility procurement by Saudi Electricity Company and Etihad Water and Electricity anchors contract-based long-term offtake pricing, compressing channel margins and bundling multi-year maintenance commitments into hardware awards. This buyer concentration shifts pricing power toward volume-scale negotiations and certification-speed premiums for SF6-free alternatives.
Pricing Analysis
Margin tightening in air insulated switchgear reflects copper and aluminum price volatility, forcing producers serving African transmission corridors toward cost-down negotiations. Three-tier pricing structure across SF6-free premium, conventional gas insulated standard, and air insulated economy levels separates EU F-Gas Regulation-aligned designs from legacy equipment. Gulf utilities demonstrate lowest price sensitivity given domestic content mandates and sustainability compliance deadlines, while rural African operators prioritize capital efficiency over environmental certification.
Supply Chain Analysis
Commissioning engineer scarcity in Germany and Switzerland constrains SF6-free gas insulated system output, extending lead times for Gulf utilities seeking rapid certification. Manufacturing gravity centers on European precision engineering for alternative gas designs and Chinese scale production for vacuum interrupter components. Raw material flows draw from Chilean copper, Guinean bauxite for aluminum, and specialized steel from South Korea. Single-source vulnerability in European SF6-free certification programs creates procurement bottlenecks. Distribution runs through direct-source framework agreements that bypass traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a technology-transition phase as vacuum and air-insulated architectures displace SF6-dependent systems under EU F-Gas Regulation alignment pressures across Gulf tender specifications.
For Market Incumbents: Acquire specialized commissioning engineering capabilities to address gas insulated system installation bottlenecks in Saudi Arabia and the UAE. Deepen backward integration into alternative gas insulation supply chains to reduce European import dependency. Accelerate SASO pre-certification programs to defend position against localization mandates.
For New Entrants and Emerging Players: The premium-to-economy price gap in digital-enabled switchgear creates entry space for mid-tier providers offering predictive maintenance contracts. Target Egyptian transmission expansion programs where grid code compliance filters favor certified manufacturers with embedded service networks. Pursue white-label assembly partnerships with Riyadh-based facilities to satisfy domestic content thresholds.
For Investors and Strategic Acquirers: The window for entry favors regional service network operators with multi-year maintenance contract portfolios. Long-term viability hinges on technology transition completion toward SF6-free architectures and digital integration layers. Watch GCC harmonization timeline acceleration as the inflection signal for cross-border project financing standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| SF6-Free Certification Investment | EU F-Gas Regulation alignment secures Gulf utility tender participation for European manufacturers. |
| Localized Assembly Capacity | SASO domestic content thresholds in Saudi Arabia filter market access to Riyadh-based facilities. |
| Predictive Maintenance Contract Bundling | Saudi Electricity Company framework agreements now require embedded service commitments as standard terms. |
| Digital Substation Architecture Pilot | NEOM Northwest tests next-generation monitoring systems that redefine operational uptime expectations. |
| Commissioning Engineer Training Programs | Gas insulated system installation certification lags deployment timelines across UAE transmission expansion. |
Research Methodology
Multi-period observation of tender award patterns, regulatory adoption timelines, and technology substitution rates anchored the trend analysis, supplemented by interviews with utility planning officers, EPC contractors, grid operators, and aftermarket service heads. Primary fieldwork combined with secondary validation from SEC filings, customs and trade data, national grid operator procurement disclosures, and IEC standard revision documentation. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Segment-weighting across product architecture, end-use concentration, installation context, and technology tier informed the analytical framework throughout the projection horizon. CAGRs derived from fitted growth curves applied to utility-scale renewable integration pipelines, transmission expansion program budgets, and industrial electrification roadmaps. Modeled inputs incorporated SASO domestic content mandate enforcement schedules and GCC harmonization timeline scenarios.
Inputs from national utility procurement databases and regulatory filing repositories were available through the study window; gaps in real-time tender award pricing introduce uncertainty bands around competitive positioning assessments. Forecasts reflect documented assumptions regarding regulatory adoption speed and technology substitution elasticity. Material deviation in EU F-Gas Regulation GCC adoption timelines or copper price volatility spikes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Europe Electric Space Heaters Market
Electrical Power Equipment
Electrodialysis System Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
Composite Line Post Insulators Market
Electrical Power Equipment
SF6 Gas Circuit Breaker Market
Electrical Power Equipment
Global Hazardous Location Motor Starters Market
Electrical Power Equipment
Global Electrical SCADA Market
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
Electric Radiators Market
Electrical Power Equipment
North America Air-Insulated Switchgear Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
Portable Space Heater Market
Electrical Power Equipment
Electric Insulator Market
Electrical Power Equipment
Solid Vacuum Reclosers Market
Electrical Power Equipment
Europe Alternating Current (AC) Drive Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market