
 AC Drives Market | 2026-2036
AC Drives Market Size, Share, and Industry Trends Forecast 2026-2036
AC Drives Market Intelligence
CE marking under the EU Ecodesign Directive is redrawing competitive boundaries for AC drive suppliers seeking European industrial contracts. ABB leverages its integrated automation portfolio to anchor large manufacturing plant deployments across multiple continents. Danfoss Group specializes in energy-efficient solutions for food processing and water treatment applications, sustaining premium positioning through dedicated R&D centers.
An AC drive, or adjustable speed drive, is an electronic device that controls the speed, torque, and direction of an alternating current electric motor by varying the frequency and voltage of the power supplied to the motor, typically operating across input voltages from 208V to 690V and output frequencies from 0 to 400 Hz. Its primary industrial purpose is to optimize energy consumption, reduce mechanical stress on equipment, and enable precise process control in motor-driven systems. Voltage Source Inverter configurations dominate unit shipments due to their cost efficiency and broad compatibility with standard induction motors, while Silicon Carbide technology is gaining traction in premium segments where switching losses and thermal performance determine total cost of ownership. Pulse Width Modulated drives maintain the largest installed base across pump and fan applications, though Direct Torque Control architectures are penetrating high-dynamic machine tool environments where response speed outweighs hardware simplicity.
The US Department of Energy enforces minimum efficiency standards for electric motors and associated controls under federal regulations, while the EU F-Gas Regulation indirectly shapes drive specifications through its impact on compressor system designs. China's GB standards for adjustable speed electrical power drive systems mandate electromagnetic compatibility and efficiency testing protocols that filter non-compliant imports. Stakeholders must monitor how evolving efficiency tiers across these jurisdictions reshape product development priorities and certification roadmaps.
Market Dynamics
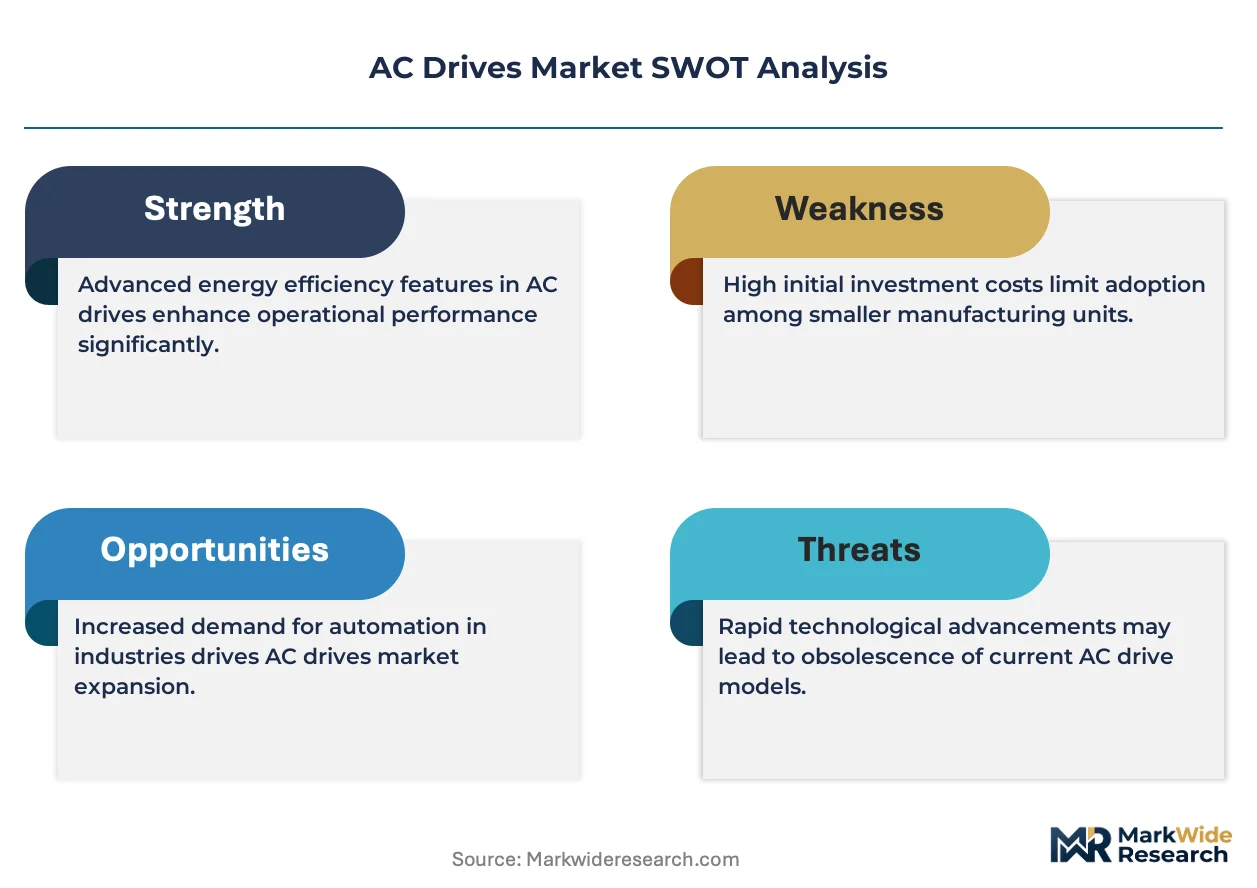
IEC 61800 efficiency thresholds are compressing product lifecycles and forcing R&D recalibration across the AC drives supply base. Suppliers must now certify to tighter electromagnetic compatibility and energy performance tiers before securing industrial contracts in regulated jurisdictions.
Growth Catalysts
- Water treatment infrastructure:Variable speed pump controls are expanding across municipal and industrial water facilities. Filtration and distribution networks require precise flow modulation that only inverter-driven systems deliver.
- EU F-Gas Regulation:Compressor system redesigns triggered by fluorinated gas phase-down mandates are accelerating drive retrofits in HVAC and refrigeration installations.
- Silicon Carbide semiconductors:Wide-bandgap devices are reducing switching losses in premium drive segments where thermal management determines operational economics.
Market Restraints
- Copper and rare earth magnet volatility:Input cost swings for motor laminations and permanent magnet materials compress margin predictability for drive-motor integrated suppliers.
- Supply concentration in power module fabrication:A limited supplier base for high-voltage IGBT and SiC modules creates single-source vulnerability for drive manufacturers scaling above 500 kW output.
- Legacy motor incompatibility:Older induction motor designs lack insulation ratings for the voltage stress imposed by modern PWM carrier frequencies, forcing full system replacement rather than drive-only retrofit.
Strategic Opportunities
- India industrial automation:The PLI scheme for manufacturing and BIS efficiency mandates are creating certified product demand in a market with low current drive penetration relative to installed motor base.
- Direct Torque Control convergence:Sensorless vector control algorithms combined with real-time motor parameter estimation are opening machine tool and robotics applications previously reserved for servo systems.
- Edge analytics integration:Embedded condition monitoring and predictive maintenance capabilities are enabling outcome-based service contracts that extend supplier revenue streams beyond hardware shipment.
Industry Challenges
- Power electronics engineering scarcity:Design expertise in thermal management, EMC mitigation, and gate driver protection is concentrated among aging specialist workforces in Germany, Japan, and the United States.
- Multi-jurisdiction certification timelines:Parallel testing for CE marking, UL listing, and China's GB compliance adds 8-14 months to product release schedules for global platform drives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AC Drives Market |
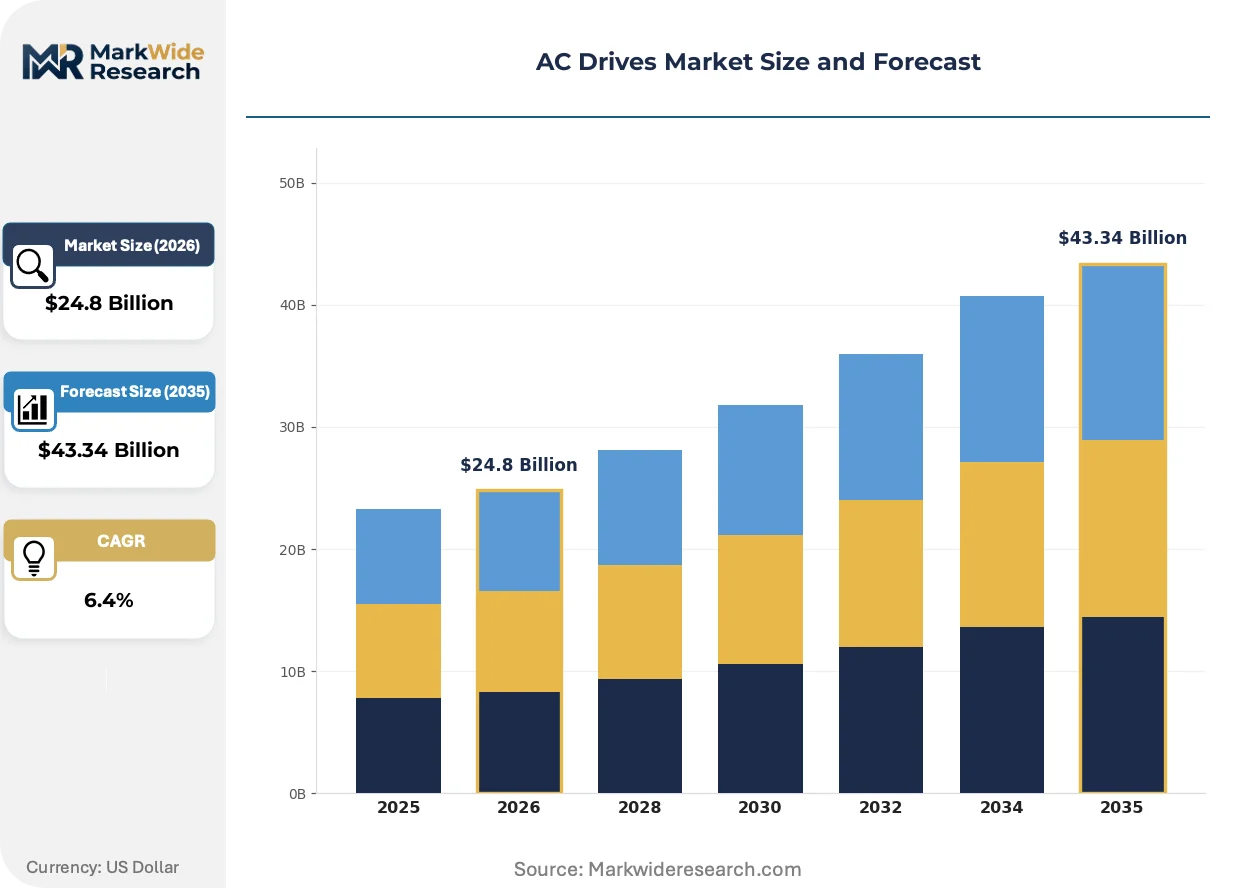
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Voltage Source Inverter, Current Source Inverter, Pulse Width Modulated, Flux Vector, Direct Torque Control Technology: IGBT, MOSFET, Silicon Carbide, DSP Control, Microcontroller Based Application: Pumps, Fans, Compressors, Conveyor Systems, Machine Tools End User Industry: Manufacturing Plants, Food Processing, Oil Refining, Water Treatment, Textile Production |
| Companies Covered | ABB, Danfoss Group, Schneider Electric, Siemens, Yaskawa Electric Corporation, Rockwell Automation, Fuji Electric, Emerson Electric, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AC Drives Market Strategic Shifts & Innovations
Power semiconductor architecture is bifurcating the AC drives landscape into cost-optimized silicon IGBT portfolios and performance-optimized SiC platforms. This technological schism is reshaping supplier specialization and customer segmentation simultaneously.
Silicon Carbide MOSFET technology is fragmenting the premium drive segment. SiC devices enable higher switching frequencies with reduced thermal losses, allowing compact cabinet designs and passive cooling in harsh environments. Oil and gas upstream operators and offshore marine propulsion buyers are adopting SiC-based drives where space constraints and cooling infrastructure limitations dominate total cost calculations. The technology is fragmenting supplier R&D allocation between silicon legacy platforms and wide-bandgap development tracks.
China's GB standards for adjustable speed electrical power drive systems are tightening electromagnetic compatibility test protocols. The revised testing mandates filter non-compliant imports and accelerate domestic supplier qualification cycles. Industrial automation integrators in China are now specifying GB-certified drives exclusively, forcing multinational suppliers to establish localized testing and certification capabilities.
Service unbundling is altering aftermarket revenue capture. End-users are separating drive hardware procurement from commissioning, maintenance, and spare parts agreements. Water treatment utilities and food processing plants are sourcing drives through distributor channels while contracting service directly with system integrators or in-house automation teams. This pattern is most pronounced in North American and Western European markets where vertical integration between OEM and service provider has historically been strongest.
AC Drives Market Segmentation
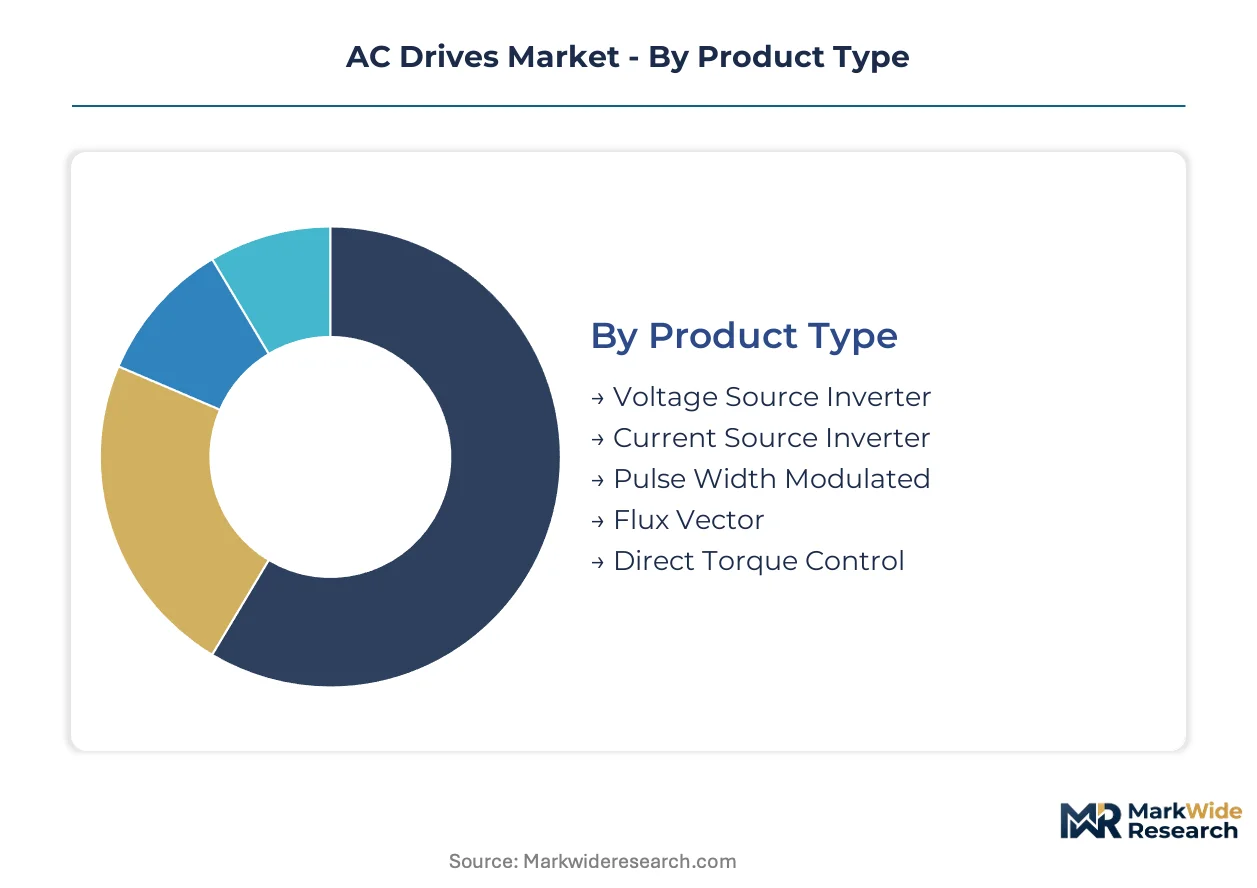
AC drive segmentation reflects divergent technical requirements across power electronics architectures, semiconductor materials, and end-use duty cycles. Procurement decisions hinge on whether applications prioritize first-cost minimization, energy recovery, or precision torque response under variable load conditions.
Product Type:
CE marking under the EU Ecodesign Directive and IEC 61800 efficiency tiers differentiate product type selection across regulated industrial markets.
- Voltage Source Inverter:Capacitor-fed DC link topology dominates unit economics through simplified gate drive requirements and broad induction motor compatibility. Municipal water treatment facilities in Germany and manufacturing retrofits across China's Yangtze River Delta specify VSI configurations for pump and fan duty where cost efficiency outweighs regenerative capability.
- Pulse Width Modulated:Carrier-frequency modulation enables precise voltage control with mature silicon IGBT implementations. HVAC compressor retrofits triggered by the EU F-Gas Regulation and North American commercial building efficiency codes are concentrating procurement in PWM architectures for their proven electromagnetic compatibility performance.
- Current Source Inverter:Inductor-based DC link suits high-power synchronous motor applications above 2 MW.
- Flux Vector:Rotor flux orientation algorithms enable servo-grade performance from standard induction motors.
- Direct Torque Control:Stator flux and torque direct regulation eliminates modulator delay for machine tool spindle applications.
Voltage Source Inverter handles the majority of throughput; Direct Torque Control is expanding most quickly on share.
Technology:
Cost tier stratification separates legacy silicon platforms from wide-bandgap premium offerings where thermal performance determines total ownership economics.
- Silicon Carbide:Wide-bandgap MOSFETs slash switching losses and enable passive cooling in cabinet-constrained installations. Offshore marine propulsion systems in Norway and upstream oil and gas platforms in the Gulf of Mexico specify SiC drives where space limitations and cooling infrastructure elimination justify semiconductor cost premiums.
- IGBT:Bipolar junction technology maintains cost leadership through established fabrication scale and module standardization. India's PLI scheme beneficiaries and Southeast Asian manufacturing greenfield projects default to IGBT platforms for sub-500 kW applications where procurement budgets constrain technology selection.
- MOSFET:Unipolar switching suits low-voltage drives below 480V with reduced conduction losses.
- DSP Control:Digital signal processor architectures execute complex vector algorithms in real-time.
- Microcontroller Based:Integrated peripheral sets reduce BOM cost for fixed-function pump and fan drives.
IGBT maintains dominant volume position; Silicon Carbide is climbing the fastest as wide-bandgap costs converge with silicon at premium power ratings.
Application:
Customer type segmentation separates specification-driven OEM integrators from aftermarket retrofit contractors with divergent service and commissioning requirements.
- Pumps:Variable speed control matches hydraulic output to system demand curves in centrifugal and positive displacement configurations. China's municipal water distribution networks and desalination facilities in Saudi Arabia deploy inverter-driven pumping for energy recovery and pressure modulation compliance.
- Fans:Affinity laws reward speed reduction with cubic energy savings in centrifugal blower duty. US data center cooling retrofits and European industrial ventilation upgrades specify fan-optimized drives with automatic energy optimization algorithms.
- Compressors:Rotary and reciprocating gas compression requires torque control across pulsating load profiles.
- Conveyor Systems:Regenerative braking and coordinated multi-motor control dominate bulk material handling specifications.
- Machine Tools:Spindle orientation and rapid traverse demand sub-millisecond torque response.
Pumps handle the majority of throughput; Compressors are gaining share fastest on HVAC and refrigeration retrofit cycles.
End User Industry:
Supply concentration in power module fabrication shapes end user access to drive technologies above 500 kW output thresholds.
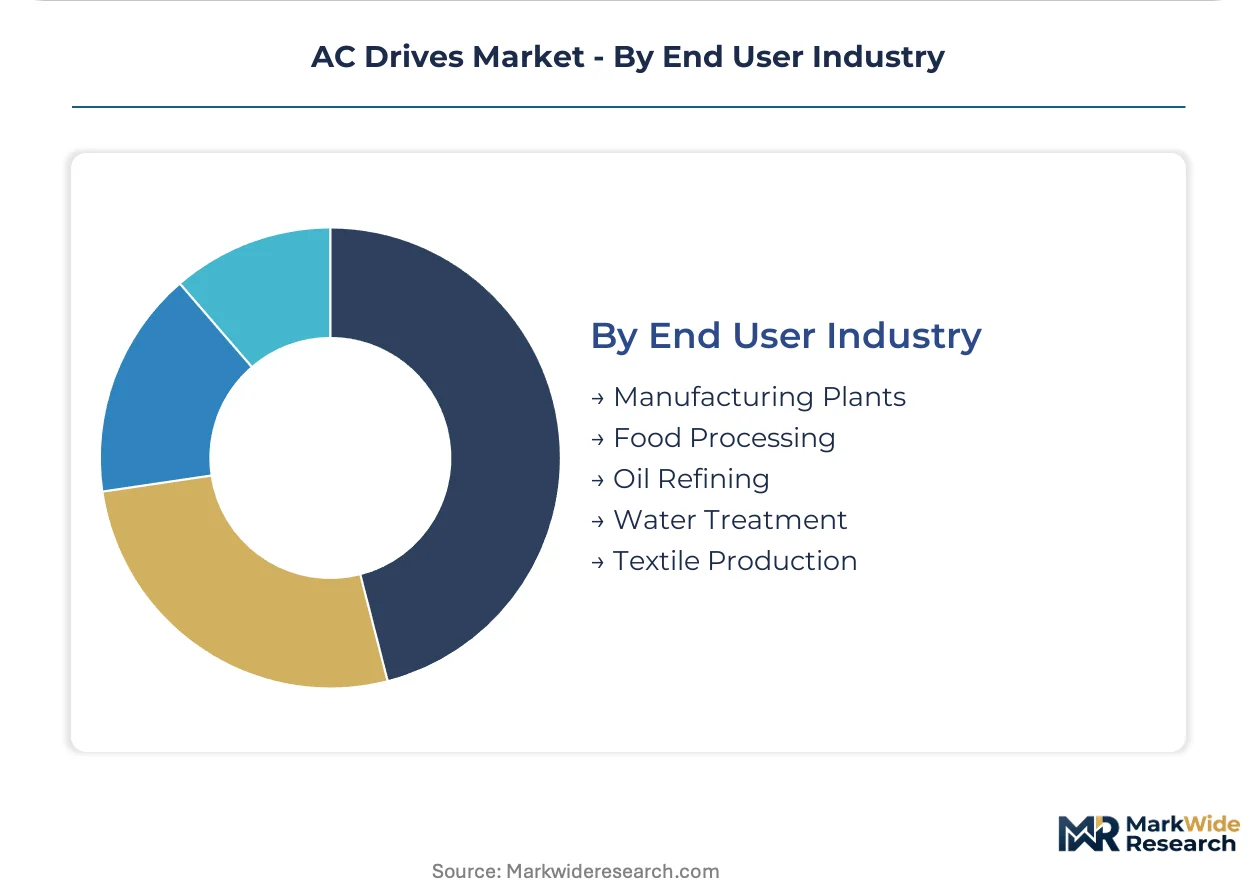
- Water Treatment:Filtration, distribution, and wastewater processing require precise flow modulation across variable demand profiles. Germany's Ruhr district utilities and Australia's Melbourne Water specify IEC 61800-9-2 efficiency class drives for variable speed pump control in energy-intensive aeration and high-service pumping stations.
- Manufacturing Plants:Discrete and process automation integrate drives into PLC-coordinated production lines. Automotive stamping and paint operations in Michigan and Bavaria demand coordinated multi-axis control with safety-integrated torque off functionality.
- Food Processing:Hygienic design and washdown rating requirements constrain enclosure and cooling architecture selection.
- Oil Refining:Hazardous area classification and regenerative requirements dominate downstream processing specifications.
- Textile Production:Winding and tension control applications favor compact drives with precise speed holding.
Manufacturing Plants handle the majority of throughput; Water Treatment is expanding most quickly on infrastructure investment cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial efficiency mandates and infrastructure renewal programs are redrawing procurement patterns across major AC drive markets. National regulations on motor efficiency and carbon intensity now determine supplier qualification timelines and product specification requirements.
China
MIIT's GB standards for adjustable speed electrical power drive systems mandate electromagnetic compatibility and efficiency testing that filters non-compliant imports. The dual carbon goals accelerate inverter deployment in steel, cement, and chemical plants. Industrial automation retrofits concentrate in the Yangtze River Delta, where manufacturing capacity expansion drives variable speed pump and fan control demand.
Germany
CE marking under the EU Ecodesign Directive compresses product lifecycles and forces R&D recalibration for European industrial contracts. The F-Gas Regulation triggers compressor system redesigns that accelerate drive retrofits in HVAC and refrigeration. Manufacturing plant deployments cluster in Bavaria and North Rhine-Westphalia, where automotive stamping and process automation integrate coordinated multi-axis control systems.
United States
The Department of Energy enforces minimum efficiency standards for electric motors and associated controls under federal regulations. Data center cooling retrofits and commercial building efficiency codes concentrate procurement in fan-optimized drives with automatic energy optimization algorithms. Industrial automation integrators in Michigan and Texas specify safety-integrated torque off functionality for discrete manufacturing lines.
India
The PLI scheme for manufacturing and BIS efficiency mandates create certified product demand in a market with low current drive penetration relative to installed motor base. Municipal water distribution networks and textile production facilities specify variable speed controls for centrifugal pump duty. Manufacturing greenfield projects in Gujarat and Maharashtra default to cost-efficient platforms for sub-500 kW applications.
Japan
METI efficiency guidelines and JIS standards shape domestic procurement specifications for premium drive segments. Machine tool spindle applications and robotics integration demand sub-millisecond torque response from sensorless vector control architectures. Precision manufacturing clusters in the Nagoya and Osaka regions specify Direct Torque Control for high-dynamic environments where response speed outweighs hardware simplicity.
AC Drives Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with integrated automation portfolios alongside specialized power electronics houses. Market structure exhibits tiered consolidation, with scale-driven suppliers anchoring large manufacturing plant deployments and niche specialists capturing premium segments through dedicated R&D centers. Two strategic archetypes dominate: full-system automation integrators leveraging cross-selling advantages, and component-focused specialists optimizing switching losses and thermal performance. Competitive moves concentrate on strategic partnerships for SiC module supply security and geographic expansion into underpenetrated industrial automation markets.
Among diversified European-based industrial groups, ABB, Danfoss Group, and Schneider Electric occupy positions spanning cost-optimized silicon platforms through performance-optimized wide-bandgap offerings. These conglomerates represent the integrated automation archetype, anchoring multi-continent manufacturing plant deployments through cross-selling of motors, drives, and control systems. Siemens exemplifies the technology convergence play, bridging legacy IGBT volume positions with SiC development tracks for cabinet-constrained installations. Japanese specialists including Yaskawa Electric Corporation, Fuji Electric, and Mitsubishi Electric sit within the precision control tier, serving machine tool and robotics applications where Direct Torque Control algorithms displace servo systems. Rockwell Automation and Emerson Electric anchor North American industrial automation demand, while the residual "Others" category captures regional fabricators and emerging wide-bandgap specialists.
| Leading Market Players |
|---|
| ABB |
| Danfoss Group |
| Schneider Electric |
| Siemens |
| Yaskawa Electric Corporation |
| Rockwell Automation |
| Fuji Electric |
| Emerson Electric |
| Mitsubishi Electric |
| Others |
Cost & Logistics Intelligence
Silicon Carbide MOSFET substitution for silicon IGBT modules redraws supply geography toward Japan and Germany while compressing pricing premiums in premium drive tiers. This material transition simultaneously elevates thermal performance thresholds and concentrates procurement leverage among buyers with cabinet-constrained installation requirements.
Pricing Analysis
Certification level under IEC 61800 and GB standards creates the primary spread between premium and standard drive tiers. Three-tier pricing structure across SiC-enabled premium, IGBT standard, and microcontroller-based economy levels dominates procurement. Cost compression in economy drives is intensifying because India's PLI scheme beneficiaries demand sub-500 kW platforms at aggressive price points. Municipal water utilities exhibit highest price sensitivity due to public budget constraints, while offshore oil and gas operators show lowest sensitivity where passive cooling elimination justifies semiconductor premiums.
Supply Chain Analysis
Japan and Germany anchor high-voltage IGBT and SiC module fabrication for premium drive outputs above 500 kW. China's Yangtze River Delta concentrates VSI and PWM drive assembly for cost-optimized segments. The supply chain draws from copper laminations, rare earth permanent magnets, and silicon carbide wafers as critical inputs. Single-source vulnerability in wide-bandgap substrate production creates exposure for manufacturers scaling SiC platforms. Distribution runs through industrial automation integrators in regulated markets and distributor channels for aftermarket retrofit contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory certification entrenchment creates switching costs that lock industrial buyers into qualified supplier relationships. IEC 61800 and GB standard compliance timelines extend product development cycles, deepening incumbent advantages.
For Market Incumbents: Consolidate SiC module supply security through captive partnerships with Japanese substrate fabricators before capacity constraints tighten. Deepen backward integration into gate driver and thermal management component production to defend margin position against Chinese domestic suppliers capturing PLI scheme volumes. Priority rests on establishing localized GB testing capabilities in China before revised electromagnetic compatibility protocols filter non-compliant imports.
For New Entrants and Emerging Players: Aftermarket service unbundling in North American water treatment utilities represents the most penetrable white-space where incumbents under-serve with bundled OEM offerings. Target edge analytics integration and predictive maintenance software layers where established suppliers lack dedicated development resources. Go-to-market leverage rests on outcome-based contracting that extends revenue streams beyond hardware shipment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European power electronics specialists holding IEC 61800 certification portfolios but lacking SiC development tracks. Long-term viability favors targets with regulatory entrenchment in water treatment and food processing verticals where efficiency mandates drive replacement cycles. Signal to monitor: GB standard revision timelines that accelerate domestic qualification advantages for China-anchored suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| SiC Module Supply Agreement | Secures wide-bandgap capacity for cabinet-constrained marine and oil platform deployments. |
| GB Certification Localization | Accelerates China market access before tightened electromagnetic compatibility protocols take effect. |
| Edge Analytics Platform Launch | Enables outcome-based service contracts extending revenue beyond hardware shipment. |
| Backward Integration into Thermal Components | Reduces exposure to power electronics engineering scarcity in Germany and Japan. |
| Water Treatment Vertical Partnership | Captures municipal infrastructure renewal cycles across Germany's Ruhr district and Australia's Melbourne Water. |
Research Approach
Desk research of IEC 61800 technical documentation, MIIT regulatory filings, and customs trade data preceded structured interviews with plant engineers at water treatment facilities, procurement leads at industrial automation integrators, aftermarket service heads, and power electronics R&D directors. Primary fieldwork combined with secondary validation from SEC filings of diversified industrial conglomerates and technical papers from semiconductor suppliers. Bottom-up unit shipment estimates across power rating tiers triangulated with top-down market value reconstruction.
Variance decomposition separates volume growth from price mix effects across the projection horizon. Segmentation dimensions span product architecture, semiconductor material, power rating tier, end-use application, and regional regulatory cluster. CAGRs derive from installed base turnover modeling and greenfield capacity addition tracking. Forecast inputs incorporate efficiency mandate implementation schedules and power module fabrication capacity expansion announcements.
Underlying assumptions cover continued IEC 61800 tier progression and stable copper and rare earth magnet supply, with deviation risk concentrated in SiC substrate capacity constraints and China import certification timeline shifts. Recalibration cycles align with material shifts in wide-bandgap semiconductor cost convergence and municipal infrastructure appropriation cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Optical Current Transformer Market
Electrical Power Equipment
Alternator Regulator Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Europe Electric Space Heaters Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Recloser Market
Electrical Power Equipment
Load Bank Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Capacitor Market
Electrical Power Equipment
Power Line Carrier System Market
Electrical Power Equipment
Electrical Steel for Electric Vehicle Market
Electrical Power Equipment
MV Protection Relay Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
Nuclear Cables Sales Market
Electrical Power Equipment
Utility Poles Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market