
 Oil and Gas Data Monetization Market | 2026-2036
Oil and Gas Data Monetization Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Data Monetization Market Intelligence
Edge-to-cloud data architectures is rewriting how upstream operators package and sell subsurface intelligence. Schlumberger leverages its subsurface expertise to anchor premium data products around reservoir characterization workflows. Microsoft Corporation competes through Azure Energy data foundations that extend cloud-native tooling to independent producers. Baker Hughes Company differentiates via digital twin integrations that sustain recurring revenue from turbine performance datasets.
Oil and gas data monetization encompasses the conversion of operational, subsurface, and market data into tradable products or services through analytics platforms, API licensing, and subscription models, typically involving petabyte-scale seismic surveys, real-time SCADA streams, and derivative pricing feeds sold to trading desks or joint-venture partners. The primary industrial purpose centers on transforming latent data assets into revenue streams that de-risk capital allocation across drilling programs and midstream logistics. Data analytics services within the Service Type dimension dominate current margin pools, as operators pay premium rates for predictive maintenance algorithms trained on proprietary failure signatures. Exploration Optimization under Application is growing fastest, driven by supermajor appetite for machine-learned prospect ranking that compresses cycle times from lease acquisition to spud date. Blockchain technology within the Technology dimension remains nascent but occupies a strategic position for emissions data provenance and carbon credit verification.
The US Environmental Protection Agency and Securities and Exchange Commission shape demand through methane reporting mandates and climate disclosure rules that force operators to purchase third-party emissions datasets for audit trails. The EU Green Deal and CSRD extend this regulatory pressure across European jurisdictions, creating cross-border compliance markets for verified environmental data products. ISO 27001 and IEC 62351 standards govern data security and industrial communication protocols, raising barriers for unaccredited analytics vendors seeking access to operator networks. Stakeholders must weigh whether to build captive data marketplaces or partner with established cloud platforms as regulatory granularity intensifies and buyer expectations for real-time verification harden.
Market Dynamics
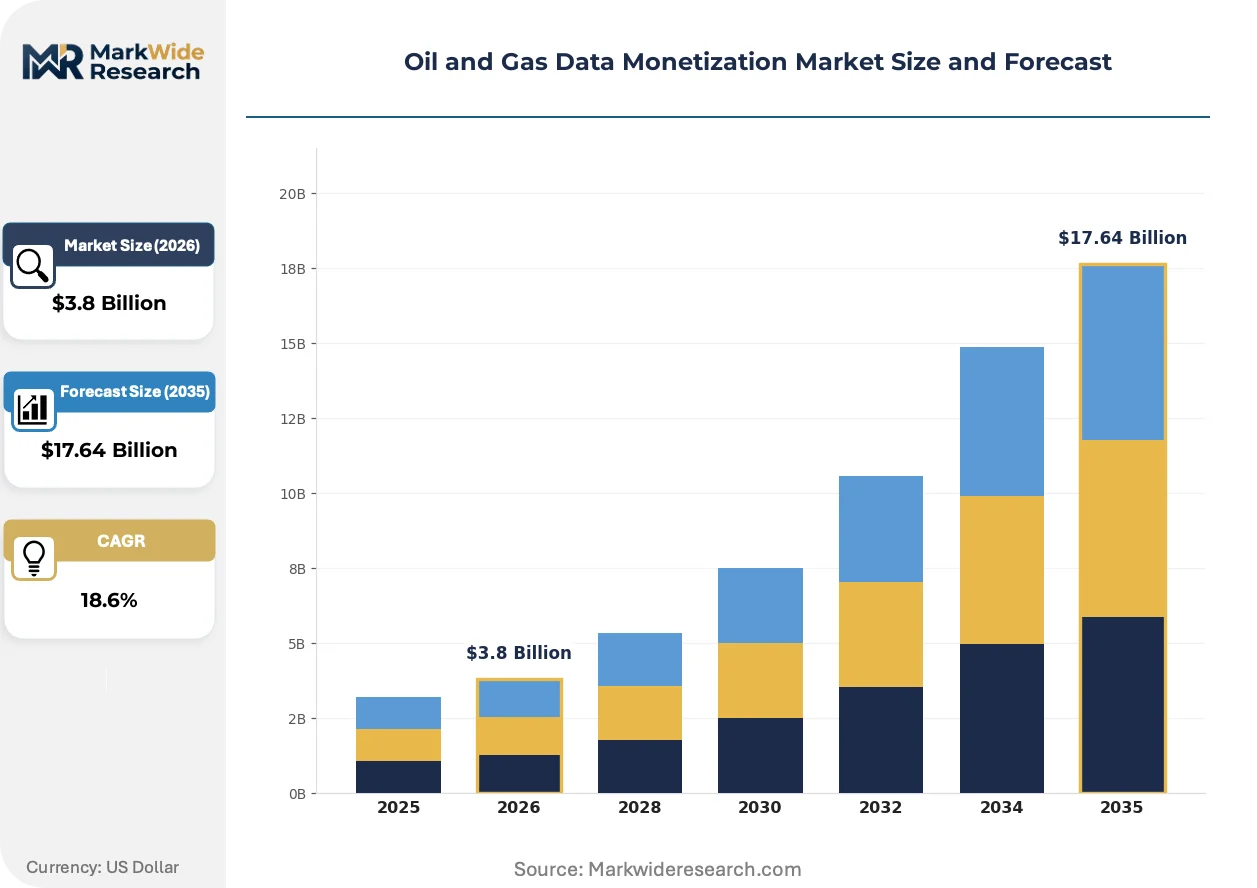
Edge-to-cloud data architectures are compressing the cost structure for subsurface intelligence packaging, forcing operators to choose between captive data marketplaces and hyperscaler partnerships as regulatory granularity intensifies.
Growth Catalysts
- EU Green Deal methane mandates:European operators must purchase verified emissions datasets for audit trails under CSRD reporting rules, creating compliance-driven demand for environmental data products.
- Permian Basin producer consortiums:Pooled subsurface datasets in West Texas and New Mexico attract institutional capital by de-risking drilling program valuations through shared intelligence.
- Real-time SCADA integration:Midstream operators deploy streaming analytics to optimize commodity movements and capture arbitrage opportunities across pipeline networks.
Market Restraints
- Petabyte-scale storage costs:Seismic survey archives and historical production logs require sustained capital allocation to cloud infrastructure with limited near-term monetization pathways.
- ISO 27001 certification barriers:Unaccredited analytics vendors face exclusion from operator networks due to stringent data security and industrial communication protocol requirements under IEC 62351.
- Data sovereignty fragmentation:Cross-border transfer restrictions between the United States, European Union, and China complicate unified data marketplace development.
Strategic Opportunities
- Blockchain emissions provenance:Nascent distributed ledger applications for carbon credit verification create new revenue streams from immutable environmental data trails.
- Machine-learned prospect ranking:Exploration Optimization applications compress cycle times from lease acquisition to spud date for supermajor appetite.
- API licensing models:Subscription-based derivative pricing feeds to trading desks replace traditional one-time data sales with recurring revenue structures.
Industry Challenges
- Subsurface data scientist scarcity:Reservoir characterization expertise combined with cloud-native engineering skills remains concentrated among legacy service firms.
- Legacy SCADA integration complexity:Decades-old industrial control systems require expensive retrofitting to interface with modern analytics platforms.
- Joint-venture data ownership disputes:Ambiguous contractual frameworks governing pooled datasets generate licensing friction between operator partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Data Monetization Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Asset Management, Exploration Optimization, Production Scheduling, Risk Assessment Service Type: Data Analytics, Data Integration, Cloud Services, Consulting End User: Oil Producers, Service Providers, Regulatory Bodies, Geophysical Companies Technology: Machine Learning, Big Data, Internet of Things, Blockchain |
| Companies Covered | Schlumberger, Halliburton, Baker Hughes Company, IBM Corporation, Microsoft Corporation, Oracle Corporation, SAP SE, Accenture plc, Informatica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Data Monetization Market Strategic Shifts & Innovations
Digital twin technology is virtualizing physical asset performance into tradable datasets, while regulatory disclosure mandates and buyer consolidation are rewriting how subsurface intelligence is packaged and priced.
Digital twin platforms are virtualizing turbine performance datasets into recurring revenue products. Independent producers subscribe to real-time equipment health monitoring rather than purchasing discrete consulting engagements. Baker Hughes and similar industrial technology providers anchor premium offerings around predictive maintenance algorithms trained on proprietary failure signatures.
The Securities and Exchange Commission climate disclosure rules are forcing operators to procure third-party emissions datasets for audit trails. This regulatory pressure extends across European jurisdictions through the EU Green Deal and CSRD methane reporting mandates. Midstream and upstream segments respond by investing in verified environmental data products that satisfy cross-border compliance markets.
Supermajor procurement patterns favor subscription-based exploration intelligence over traditional one-time seismic licensing. Trading desks and joint-venture partners now demand API-accessible derivative pricing feeds with real-time refresh cycles. This shift concentrates most visibly in the Permian Basin, where producer consortiums pool datasets to attract institutional capital with de-risked drilling valuations.
Oil and Gas Data Monetization Market Segmentation
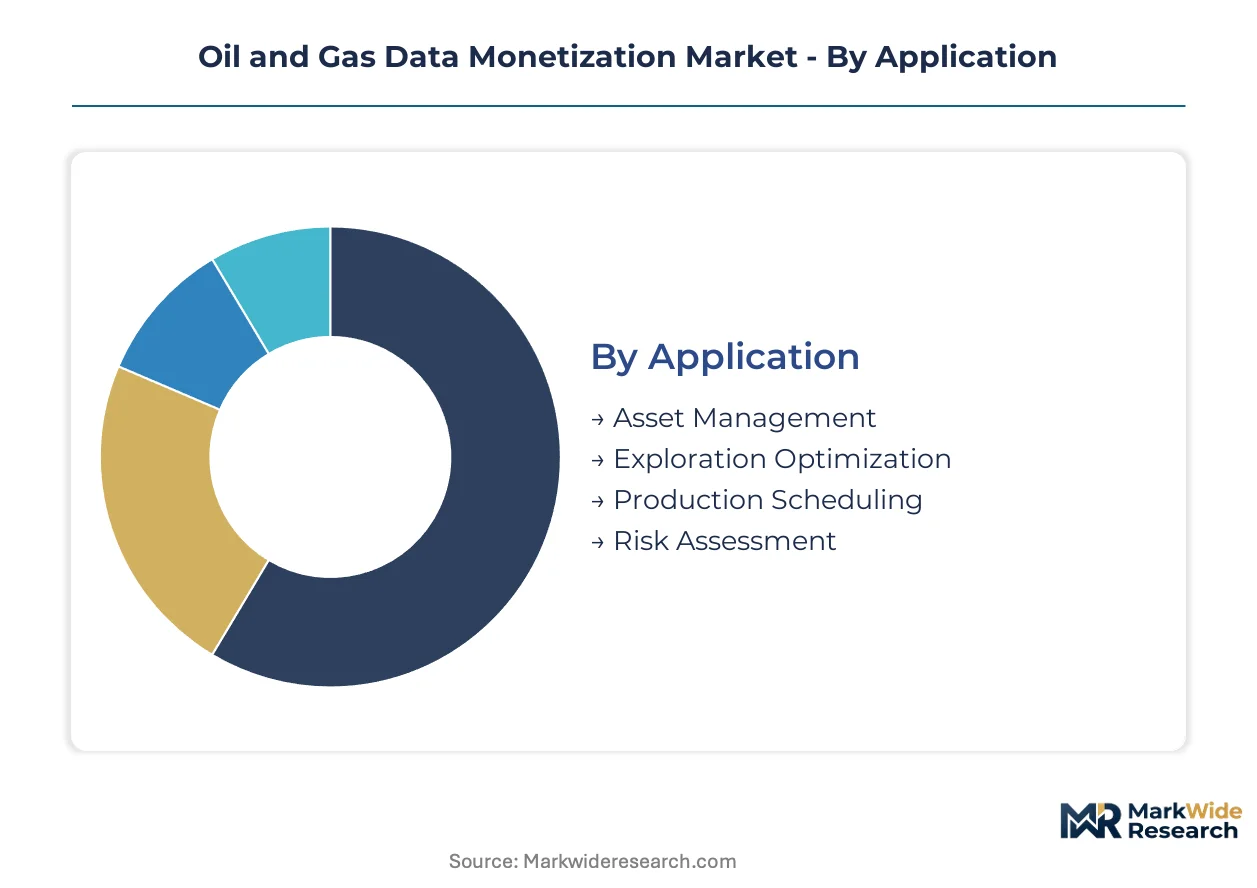
Segmentation in oil and gas data monetization reveals how value migrates from raw operational feeds to refined intelligence products. Each dimension captures distinct purchasing logic, from supermajor exploration budgets to midstream trading desk subscriptions.
Application:
Upstream and midstream operators deploy these applications across the full spectrum of capital allocation decisions, from lease acquisition to pipeline arbitrage.
- Exploration Optimization:Machine-learned prospect ranking compresses cycle times from lease acquisition to spud date. Supermajors in the Permian Basin and offshore Brazil pay premium rates for seismic-derived play fairway models that de-risk wildcat drilling.
- Asset Management:Predictive maintenance algorithms trained on proprietary failure signatures generate recurring revenue from turbine performance datasets. Midstream operators subscribe to real-time equipment health monitoring rather than discrete consulting engagements.
- Production Scheduling:Real-time SCADA integration enables dynamic well allocation and facility load balancing across multi-pad developments.
- Risk Assessment:Derivative pricing feeds and emissions audit trails satisfy SEC climate disclosure and EU CSRD reporting mandates.
The dominant share belongs to Asset Management, while Exploration Optimization is closing the gap fastest.
Service Type:
Margin concentration varies sharply by delivery model, with cloud-native platforms capturing recurring revenue streams that on-premise deployments cannot match.
- Data Analytics:Petabyte-scale seismic surveys and production logs feed predictive models for reservoir characterization and failure detection. Operators pay premium rates for algorithms trained on proprietary subsurface signatures.
- Cloud Services:Azure Energy data foundations and competing hyperscaler platforms extend API-accessible tooling to independent producers. Subscription models replace traditional one-time data sales with recurring revenue structures.
- Data Integration:Legacy SCADA retrofitting and edge-to-cloud pipeline construction require sustained professional services engagement.
- Consulting:Reservoir characterization expertise combined with cloud-native engineering skills remains concentrated among legacy service firms.
Data Analytics commands the largest revenue pool, though Cloud Services is expanding most quickly as independent producers abandon captive infrastructure.
End User:
Purchasing authority fragments across technical and commercial functions, with procurement patterns diverging between national oil companies and independents.
- Oil Producers:Supermajors and independents buy exploration intelligence and emissions datasets to satisfy investor due diligence and regulatory audit trails. Permian Basin producer consortiums pool subsurface datasets to attract institutional capital.
- Service Providers:Schlumberger and Baker Hughes anchor premium offerings around digital twin integrations and predictive maintenance algorithms.
- Regulatory Bodies:EPA methane reporting mandates and EU CSRD rules create compliance-driven demand for verified environmental data products.
- Geophysical Companies:Seismic contractors license derivative datasets to trading desks and joint-venture partners.
Oil Producers account for the dominant share, while Regulatory Bodies are gaining purchasing influence fastest through emissions disclosure mandates.
Technology:
Technology selection determines data product architecture, with machine learning and distributed ledgers occupying opposite ends of the maturity spectrum.
- Machine Learning:Neural networks trained on historical production logs and failure signatures power predictive maintenance and prospect ranking workflows. Supermajor appetite for compressed exploration cycle times drives sustained investment.
- Blockchain:Distributed ledger applications for carbon credit verification and emissions data provenance remain nascent but strategically positioned as EU Green Deal methane mandates harden.
- Big Data:Petabyte-scale storage and processing infrastructure supports seismic survey archives and real-time SCADA streams.
- Internet of Things:Edge sensors and streaming analytics optimize commodity movements across pipeline networks.
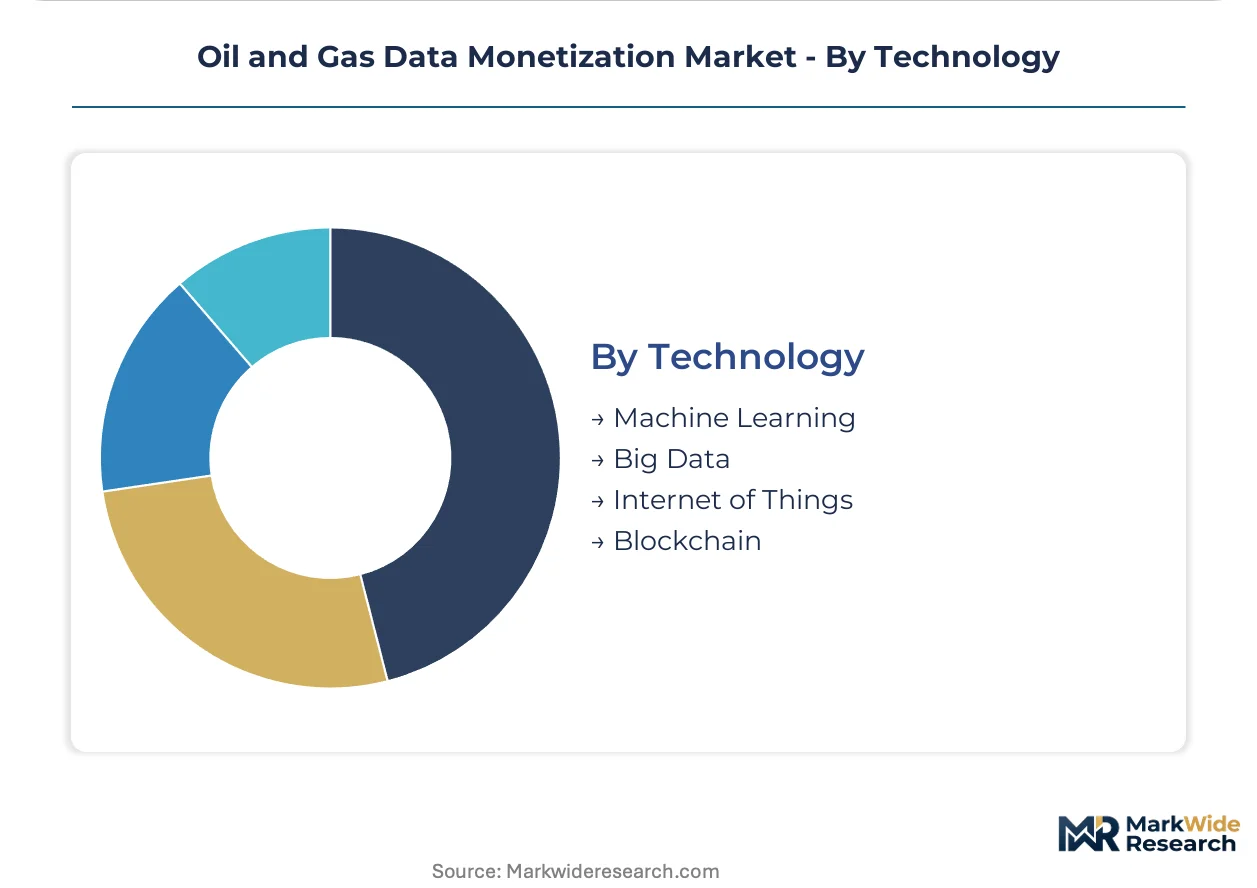
Machine Learning holds the dominant position, while Blockchain is climbing the fastest as carbon credit verification markets mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States exports subsurface intelligence products to European operators seeking CSRD-compliant emissions datasets, while Middle Eastern national oil companies import predictive maintenance algorithms from Western technology providers.
United States
Permian Basin producer consortiums pool seismic and production logs to attract institutional capital through de-risked drilling valuations. EPA methane reporting mandates and SEC climate disclosure rules compel operators to purchase third-party emissions datasets for audit trails. Houston anchors the dominant cluster of data analytics vendors serving upstream and midstream segments.
United Kingdom
North Sea decommissioning schedules drive demand for legacy reservoir data products that optimize late-life asset management. The UK regulator enforces emissions verification standards aligned with EU CSRD reporting frameworks. Aberdeen concentrates specialist firms offering subsurface data packaging and digital twin integration services.
Norway
Equinor-led offshore developments require machine-learned prospect ranking to compress exploration cycle times in frontier basins. Norwegian petroleum regulations mandate comprehensive production data sharing through national repositories. Stavanger hosts technology centers specializing in edge-to-cloud architectures for subsea sensor networks.
Saudi Arabia
Aramco's mega-project portfolio consumes petabyte-scale seismic surveys and real-time SCADA analytics for reservoir optimization. The kingdom's national data governance framework restricts cross-border transfer of subsurface intelligence while encouraging domestic cloud infrastructure investment. Dhahran anchors the primary concentration of captive data science capabilities.
Brazil
Pre-salt layer exploration demands advanced seismic processing and reservoir characterization workflows from international service providers. ANP regulatory requirements enforce production data transparency to attract foreign investment into marginal field developments. Rio de Janeiro clusters the headquarters of national oil company data monetization initiatives.
Oil and Gas Data Monetization Market Key Industry Players
Channel-controlling players compete with product-specialist players across three distinct tiers. Hyperscaler platforms and legacy oilfield service firms anchor the premium tier through integrated cloud-native offerings. Independent software vendors and regional analytics boutiques occupy the mid-market through specialized exploration optimization tools. Competitive moves concentrate on strategic partnerships between operators and technology providers, alongside vertical integration into proprietary data marketplace development.
Within the legacy service tier, Schlumberger and Baker Hughes Company exemplify archetypes that combine subsurface engineering heritage with digital platform investments. Microsoft Corporation occupies a position among hyperscaler entrants extending cloud infrastructure to independent producers. These three anchors represent contrasting strategic postures: captive data product development, industrial equipment digital twin integration, and horizontal platform enablement.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| Baker Hughes Company |
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| SAP SE |
| Accenture plc |
| Informatica |
| Others |
Cost & Logistics Intelligence
ISO 27001 certification chokepoints determine both the premium-to-economy pricing spread across data analytics tiers and the geographic clustering of accredited supply nodes. Operators exclude unaccredited vendors from procurement networks, compressing margins for non-compliant providers while concentrating pricing power among certified hyperscaler partnerships.
Pricing Analysis
Next-generation blockchain-enabled emissions provenance commands substantial premiums over current-generation cloud analytics subscriptions and prior-generation on-premise perpetual licenses. Three-tier pricing structure across premium, standard, and economy levels stratifies by data refresh frequency, API call volume, and certification depth. Pricing pressure stems from hyperscaler commoditization of basic storage and compute layers. Independent producers exhibit highest price sensitivity, while supermajors prioritize real-time verification capabilities over cost minimization.
Supply Chain Analysis
Extended payment terms from national oil companies in Saudi Arabia and Brazil strain working capital for seismic processing vendors and edge sensor manufacturers. Supply concentrates in the United States, Norway, and the United Kingdom for reservoir characterization expertise and subsea sensor fabrication. Critical dependencies include gallium arsenide semiconductors, high-density storage arrays, and specialized fiber-optic cable. Single-source vulnerability runs through Taiwan-based chip fabrication for industrial IoT components. Distribution runs through direct enterprise sales teams and hyperscaler marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. CSRD and SEC disclosure mandates create switching costs that lock operators into verified data providers.
For Market Incumbents: Entrench position by deepening API ecosystem integrations that embed predictive maintenance algorithms into operator workflows. Acquire boutique subsurface data science teams in Stavanger and Aberdeen to capture scarce reservoir-cloud hybrid talent. Hyperscaler platform consolidation represents the primary substitution threat.
For New Entrants and Emerging Players: Mid-market independent producers in the Permian Basin represent the most penetrable entry point, as these operators lack captive data science capabilities and seek de-risked drilling valuations. Blockchain-based emissions verification for EU export compliance offers a second white-space target. Pursue partnership-first go-to-market positioning with established cloud platforms rather than building proprietary infrastructure.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platform-enabling technology providers over point-solution vendors. Long-term viability rests on recurring revenue structures replacing one-time seismic licensing. Target acquisition archetypes include digital twin specialists with proven turbine performance datasets and API-native exploration optimization tools. Watch for inflection when supermajor procurement committees mandate real-time SCADA integration as a baseline requirement.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Partnership | Hyperscaler alliances extend Azure Energy foundations to independent Permian Basin producers. |
| Digital Twin Integration | Baker Hughes leverages turbine performance datasets to sustain recurring subscription revenue. |
| Blockchain Emissions Provenance | Distributed ledger applications verify carbon credits under EU Green Deal methane mandates. |
| API Licensing Model | Subscription-based derivative pricing feeds replace traditional one-time seismic data sales. |
| Certification Investment | ISO 27001 accreditation opens operator networks previously closed to unaccredited analytics vendors. |
Research Approach
A standing panel of chief data officers at supermajors, reservoir engineering directors, midstream trading desk heads, and cloud platform specialists provided ongoing calibration throughout the study. Primary interviews combined with secondary validation from SEC climate disclosure filings, EPA methane inventory reports, EU CSRD regulatory texts, and hyperscaler energy vertical capex disclosures. Bottom-up segment sizing triangulated against top-down market aggregation.
Scenario-bracketing framed analytical development across the projection horizon. Segmentation dimensions modeled include service type, application, end user, and technology maturity tier. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption S-curves. Forecast inputs incorporated petabyte-scale storage cost curves and machine learning model deployment rates.
Macroeconomic conditions sit as an overlay; deviation in energy commodity prices, cloud infrastructure investment cycles, or cross-border data transfer policy would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology interoperability standards. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Injection Well Market
Oil & Gas
Europe Wireline Logging Services Market
Oil & Gas
Latin America Artificial Lift System Market
Oil & Gas
Oil and Gas Data Management Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
Cuttings Re-Injection Services Market
Oil & Gas
Spacer Fluid Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Floating Liquefied Natural Gas (FLNG) Terminals Market
Oil & Gas
US Oil and Gas Analytics Market
Oil & Gas
Vietnam Oil and Gas Midstream Market
Oil & Gas
Malaysia Oil and Gas Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
South America LNG Bunkering Market
Oil & Gas
Underwater Monitoring System for Oil and Gas Market