
 ESE Lightning Rod Market | 2026-2036
ESE Lightning Rod Market Size, Share, and Industry Trends Forecast 2026-2036
ESE Lightning Rod Market Insights
Data center end-use demand is hardening as hyperscale facilities multiply across humid subtropical zones. Indelec leverages its French engineering heritage to dominate European certification benchmarks for early streamer emission technology. ABB sustains broad geographic coverage through integrated electrical protection portfolios that bundle lightning rods with switchgear and grounding systems. Pentair competes on installation environment versatility, anchoring its position in coastal industrial plants where salt corrosion degrades conventional terminals.
An early streamer emission lightning rod functions as an active air terminal that generates an upward connecting streamer earlier than a passive Franklin rod, typically triggering 30–60 microseconds ahead of competing points to expand the protected radius up to 120 meters depending on installation height. The device serves primarily to reduce structural lightning strike probability for high-value assets where passive coverage would require multiple masts. Enhanced air terminal product types lead current revenue pools due to their balance of proven field performance and moderate premium over classical designs, while dissipation array systems occupy niche margins in explosive atmosphere environments such as petrochemical tank farms. Electrostatic technology dominates the technology dimension through simpler maintenance protocols, though ionization approaches are gaining traction in renewable energy facilities where blade height complicates conventional protection geometry.
The NFPA 780 standard in the United States and the IEC 62305 series govern product certification and installation spacing calculations, with CE marking under the EU Construction Products Regulation governing market access across European member states. India's BIS certification requirements and China's GB 50057 standard create additional compliance layers for manufacturers seeking to supply Asian infrastructure projects. Stakeholders must monitor evolving wind turbine height regulations and data center uptime tier requirements, as these specifications directly determine protected radius calculations and thus unit economics per site.
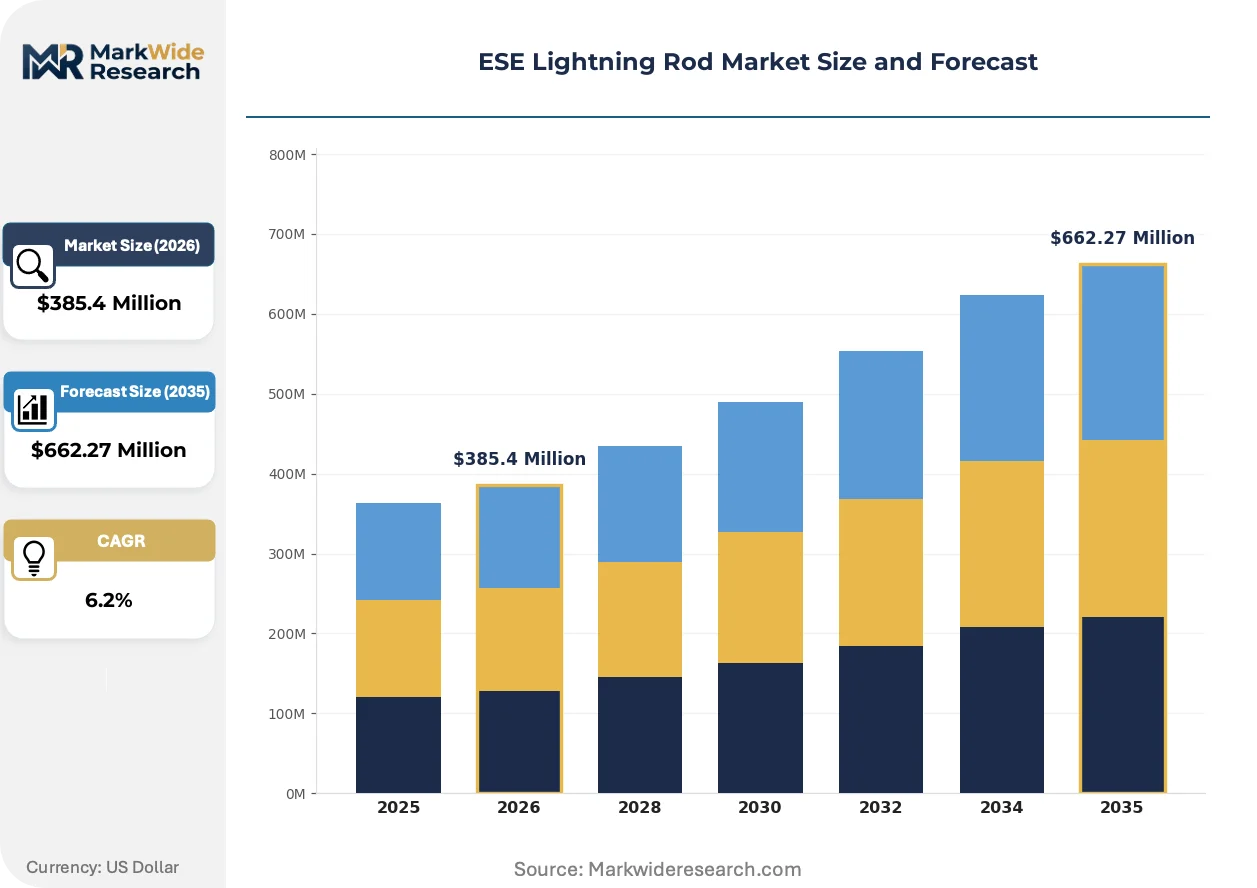
Market Dynamics
Certification requirements under NFPA 780 and IEC 62305 are compressing supplier margins while elevating technical barriers for early streamer emission technology adoption across data center and industrial verticals.
Growth Catalysts
- Data center electrification:Hyperscale facilities in humid subtropical zones require expanded lightning protection coverage per uptime tier specifications, driving specification of active air terminals over passive Franklin rod arrays.
- Industrial corridor densification:Southeast Asian manufacturing clusters are mandating upgraded lightning protection for electrified production lines, accelerating replacement of conventional terminals with early streamer emission systems.
- Wind turbine height escalation:Blade tip elevations exceeding 150 meters complicate geometric protection calculations, forcing wind farm operators toward ionization-based solutions with extended radius coverage.
Market Restraints
- Copper and aluminum price volatility:Terminal construction depends on conductive alloys whose commodity swings directly compress manufacturing margins without corresponding pricing power.
- Certification timeline friction:CE marking under the EU Construction Products Regulation and India's BIS requirements impose 12-18 month validation cycles that delay revenue recognition for new product variants.
- Passive rod substitution:Franklin rod systems retain specification preference in cost-sensitive municipal and agricultural installations where protected radius requirements remain modest.
Strategic Opportunities
- Renewable energy blade protection:Offshore wind installations in the North Sea and Baltic corridors require corrosion-resistant active terminals with remote monitoring integration.
- Petrochemical explosive atmosphere compliance:Dissipation array systems face expanding specification in tank farm environments where IEC 62305-2 risk management mandates exceed passive protection capabilities.
- Integrated electrical protection bundling:Switchgear and grounding system manufacturers can capture incremental margin by embedding early streamer emission terminals within turnkey substation contracts.
Industry Challenges
- Field calibration expertise scarcity:Installation crews require specialized training in protected radius verification and grounding impedance testing that exceeds conventional electrical contractor capabilities.
- Legacy system integration complexity:Retrofit projects in existing industrial plants must reconcile early streamer emission trigger timing with established surge protection device coordination without creating protection gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ESE Lightning Rod Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rod Air Terminal, Enhanced Air Terminal, Early Streamer Emission, Dissipation Array System, Cap Terminal Installation Environment: Commercial Complexes, Communication Towers, Industrial Plants, Educational Institutions, Power Stations Technology: Electrostatic, Radioactive, Magnetic, Classical Franklin, Ionization End Use Industry: Renewable Energy Facilities, Data Centers, Transportation Hubs, Manufacturing Units, Warehouses |
| Companies Covered | Indelec, ABB, Pentair, Raychem RPG, Alpha Automation, A.N. Wallis, Alltec, Raycap, East Coast Lightning Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ESE Lightning Rod Market Trends and Innovations
Active air terminal technology is converging with predictive maintenance platforms and remote monitoring architectures, compressing service models while elevating performance verification standards.
Electrostatic discharge measurement systems are automating field performance validation for installed early streamer emission terminals. Data center operators in Germany and the United States are deploying these diagnostic tools during semi-annual uptime audits. The technology is automating what previously required manual climb-down inspections, reducing labor allocation per site while tightening compliance documentation.
The EU Construction Products Regulation is tightening CE marking requirements for lightning protection components under harmonized standard EN 62305-3. Manufacturers must now submit extended test data on upward streamer initiation consistency across humidity ranges. European industrial procurement teams are delaying vendor qualification until revised certificates issue, compressing near-term order visibility for non-compliant suppliers.
Specification authority is migrating from general contractors to specialized lightning protection engineering consultants. Large-scale infrastructure projects in Singapore and Malaysia are engaging certified LPS designers during schematic phases rather than subcontractor selection. This shift elevates technical dialogue above price competition, favoring vendors with documented IEC 62305 calculation software and third-party validation libraries.
ESE Lightning Rod Market Segmentation
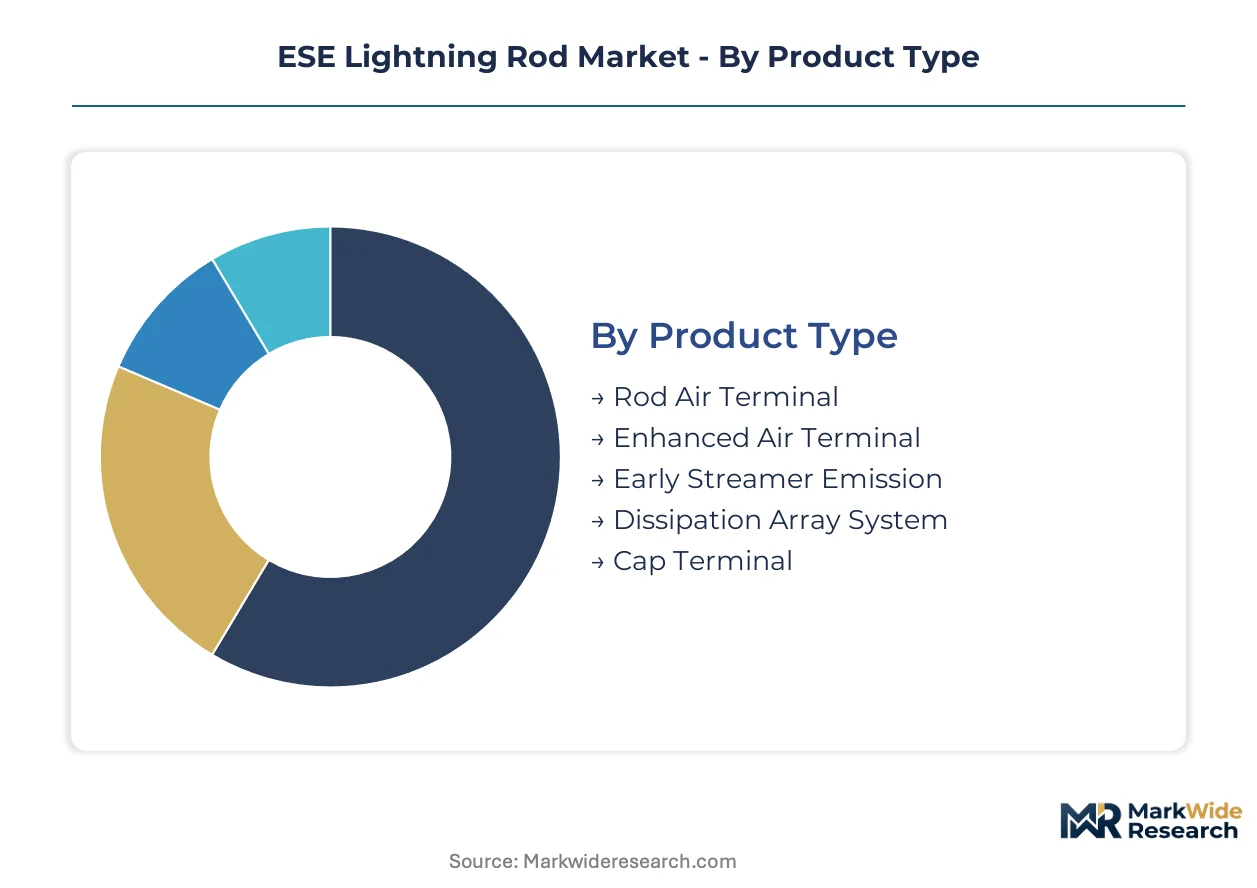
ESE lightning rod procurement patterns diverge sharply across installation environments and technology platforms. Upgrade cycles for legacy Franklin systems versus greenfield early streamer emission specifications create distinct margin profiles and customer retention dynamics for manufacturers.
Product Type:
Replacement timelines for conventional air terminals are compressing as NFPA 780 and IEC 62305-3 certification windows tighten, forcing facility managers toward validated active systems.
- Enhanced Air Terminal:Hybrid designs incorporating optimized tip geometry and controlled impedance paths. Data center operators in Germany and the United States specify these for Tier III and Tier IV facilities where protected radius calculations must satisfy uptime audit protocols.
- Early Streamer Emission:Active terminals generating upward streamers 30–60 microseconds ahead of competing points. Wind farm developers across the North Sea and Baltic corridors deploy these for blade tip elevations exceeding 150 meters where passive geometry fails.
- Rod Air Terminal:Classical passive designs retaining cost advantage in agricultural and municipal installations with modest coverage requirements.
- Dissipation Array System:Multi-point configurations for explosive atmosphere environments such as petrochemical tank farms where IEC 62305-2 risk assessments mandate enhanced protection.
- Cap Terminal:Streamlined profiles for architectural integration in commercial complexes where aesthetic constraints override pure performance optimization.
Enhanced Air Terminal sits at the top of the volume ranking, with Early Streamer Emission climbing the fastest.
Installation Environment:
Cost tiers stratify sharply between mission-critical infrastructure commanding premium active systems and commodity installations tolerating passive alternatives.
- Industrial Plants:Electrified production lines in Southeast Asian manufacturing corridors drive specification of early streamer emission systems with remote monitoring integration.
- Data Centers:Hyperscale facilities in humid subtropical zones require expanded coverage per tier specifications, creating concentrated demand for certified active terminals with documentation packages.
- Power Stations:Grid-scale generation assets with high consequence of failure.
- Communication Towers:Broadcast and cellular infrastructure with height-driven exposure profiles.
- Commercial Complexes:Mixed-use developments balancing protection performance with architectural integration requirements.
Industrial Plants command the largest installed base, with Data Centers expanding most quickly.
Technology:
Application-specific performance requirements are fragmenting the technology landscape across electrostatic, ionization, and legacy approaches.
- Electrostatic:Dominant technology leveraging field enhancement without radioactive components. Simpler maintenance protocols drive preference among facility managers with constrained technical staffing across United States and German industrial parks.
- Ionization:Gaining specification in renewable energy facilities where turbine blade height complicates conventional protection geometry and remote access increases maintenance cost sensitivity.
- Classical Franklin:Passive rod systems retaining municipal and agricultural specification where protected radius requirements remain modest.
- Radioactive:Niche deployment in legacy installations with specific regulatory grandfathering provisions.
- Magnetic:Experimental configurations with limited commercial penetration outside specialized test installations.
Electrostatic technology holds the volume lead, with Ionization gaining share fastest.
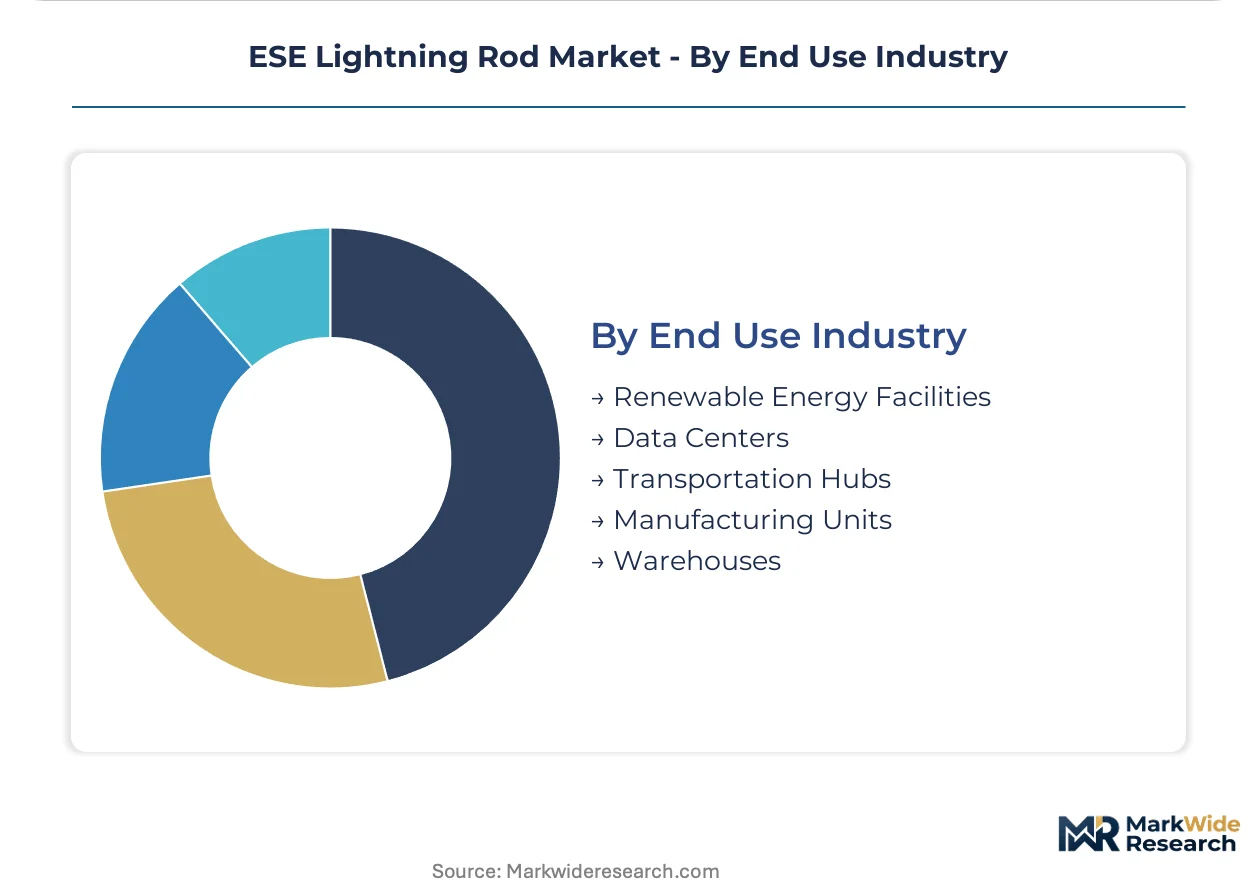
End Use Industry:
Customer type segmentation reveals diverging procurement authority structures between owner-operated assets and third-party managed infrastructure.
- Renewable Energy Facilities:Offshore wind installations in the North Sea and Baltic corridors require corrosion-resistant terminals with integrated condition monitoring. Blade tip heights exceeding 150 meters force ionization-based solutions.
- Data Centers:Hyperscale operators in Singapore and Malaysia engage certified LPS designers during schematic phases, elevating technical dialogue above price competition.
- Manufacturing Units:Electrified production lines in Southeast Asian corridors mandating upgraded protection standards.
- Transportation Hubs:Airports and rail terminals with high passenger throughput and continuous operations requirements.
- Warehouses:Logistics facilities with automated storage systems vulnerable to electrical disruption.
Renewable Energy Facilities anchor current procurement volume, with Data Centers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast Asian manufacturing corridors are accelerating lightning protection upgrades as industrial electrification intensifies, while data center clusters in humid subtropical zones drive specification of active air terminals over passive alternatives.
United States
Hyperscale data center construction across Virginia's Loudoun County and Texas's Hays County is expanding procurement of early streamer emission systems to satisfy Tier III and Tier IV uptime specifications. The NFPA 780 standard governs installation spacing calculations and certification requirements for air terminals. Facility operators in Phoenix and Dallas-Fort Worth are engaging certified lightning protection designers during schematic phases rather than subcontractor selection.
Germany
Offshore wind installations in the North Sea and Baltic corridors require corrosion-resistant active terminals with integrated condition monitoring for blade tip elevations exceeding 150 meters. CE marking under the EU Construction Products Regulation mandates extended test data on upward streamer initiation consistency across humidity ranges. Industrial procurement teams in Hamburg and Bremen are delaying vendor qualification until revised certificates issue.
China
Electrified production lines in the Yangtze River Delta and Pearl River Delta manufacturing belts are mandating upgraded lightning protection standards under the GB 50057 standard. The country's national standardization administration is tightening certification windows for imported early streamer emission systems. Facility managers in Suzhou and Shenzhen are replacing conventional terminals with validated active systems to satisfy risk management protocols.
India
Data center operators in Mumbai and Bengaluru are expanding procurement of early streamer emission technology to protect critical infrastructure in high-lightning-density zones. BIS certification requirements impose validation cycles that delay revenue recognition for new product variants. Manufacturing units in Gujarat and Tamil Nadu are mandating upgraded protection for automated production lines.
Singapore
Large-scale infrastructure projects are engaging certified LPS designers during schematic phases, elevating technical dialogue above price competition. The country's building and construction authority maintains stringent enforcement of IEC 62305-3 compliance for mission-critical facilities. Data center developments in Jurong and Tuas are specifying active air terminals with documentation packages to satisfy audit protocols.
ESE Lightning Rod Market Competitive Landscape
Certification-driven portfolio diversification dominates the current landscape as manufacturers navigate tightening NFPA 780 and IEC 62305 validation requirements. The vendor base organizes into three tiers: integrated electrical protection conglomerates bundling lightning rods with switchgear and grounding systems; specialized early streamer emission technology firms with concentrated European engineering heritage; and regional installation service providers with limited manufacturing capability. Strategic archetypes include certification-anchored premium specialists, scale-driven portfolio diversifiers, and geography-bound service integrators. Competitive moves center on technology licensing agreements to accelerate CE marking compliance and backward integration into conductive alloy sourcing to buffer commodity price volatility.
Among the specialized technology tier, Indelec represents the certification-anchored archetype with French engineering heritage dominating European benchmark standards. ABB occupies a position exemplifying the integrated electrical protection model, bundling lightning protection with broader power infrastructure portfolios. Pentair sits within the installation-environment-specialist category, anchoring competitive positioning in coastal industrial applications where corrosion resistance determines specification outcomes.
| Leading Market Players |
|---|
| Indelec |
| ABB |
| Pentair |
| Raychem RPG |
| Alpha Automation |
| A.N. Wallis |
| Alltec |
| Raycap |
| East Coast Lightning Equipment |
| Others |
Pricing and Supply Chain Analysis
Data center operators in the United States and Germany demanding certified active terminals with full documentation packages are forcing manufacturers to absorb extended validation cycles and premium conductive alloy sourcing, compressing margins while elevating entry costs for non-compliant suppliers.
Pricing Analysis
Copper and aluminum alloy costs pass through directly to terminal pricing without full offsetting power, creating margin compression for manufacturers lacking captive metal sourcing. Pricing stratifies across certified premium tiers for IEC 62305-validated systems, mid-grade enhanced air terminals for industrial plants, and economy passive rods for municipal installations. Cost compression in the mid-tier is intensifying because Southeast Asian procurement teams are consolidating vendor lists around documented compliance packages. Agricultural and small municipal buyers exhibit the highest price sensitivity, while hyperscale data center operators prioritize certification integrity over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from German offshore wind developers and U.S. data center contractors are forcing manufacturers to qualify secondary suppliers for conductive alloys and ceramic insulator components, extending procurement timelines. Manufacturing concentrates in France, Germany, and China, with final assembly drawing from copper rod stock sourced from Chile and recycled aluminum from domestic European smelters. Single-source vulnerability sits with high-purity copper cathode supply from concentrated mining jurisdictions. Distribution runs through specialized lightning protection engineering consultants who now control specification authority in Singapore and Malaysia, displacing general contractor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ESE lightning rod market functions as a stable compounder anchored by regulatory mandates that harden certification requirements faster than technology obsolescence cycles.
For Market Incumbents: Anticipate margin pressure from commodity alloy volatility by securing long-term offtake agreements with Chilean copper producers and European aluminum smelters. Defensive positioning requires accelerating CE marking compliance under the EU Construction Products Regulation's tightened EN 62305-3 requirements before revised certificates become mandatory for vendor qualification in Hamburg and Bremen industrial procurement. For New Entrants and Emerging Players: The price-point gap between premium IEC 62305-certified systems and economy Franklin rod alternatives creates white-space opportunity in mid-tier industrial plants across India's Gujarat and Tamil Nadu manufacturing corridors. Target renewable energy blade protection as the most penetrable segment, where turbine height escalation above 150 meters invalidates passive geometry. A licensing partnership with established European engineering firms accelerates certification credibility without 12-18 month validation cycles. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized early streamer emission technology firms possessing concentrated European engineering heritage and third-party validation libraries. Long-term viability rests on recurring revenue from predictive maintenance platform subscriptions rather than transactional hardware sales. Watch for inflection when specification authority permanently shifts from general contractors to certified LPS designers in additional Asian markets beyond Singapore and Malaysia.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Acceleration | CE marking under EN 62305-3 opens access to German offshore wind procurement. |
| Backward Integration into Conductive Alloys | Captive copper sourcing buffers commodity volatility compressing manufacturing margins. |
| Predictive Maintenance Platform Launch | Remote monitoring integration captures recurring revenue from data center uptime audits. |
| Geographic Expansion into India | BIS certification compliance unlocks Mumbai and Bengaluru data center protection contracts. |
| Technology Licensing Agreement | Partnership with European heritage firms accelerates validation for new market entrants. |
Research Methodology
Bottom-up data center and wind farm procurement modeling reconciled against top-down conductive alloy consumption tracking forms the analytical core of this study. Primary interviews with certified lightning protection designers, data center facility engineers, offshore wind project developers, and industrial procurement managers in Germany, the United States, and Singapore were cross-validated against secondary sources including IEC 62305 certification databases, NFPA 780 technical committee filings, EU Construction Products Regulation harmonized standards, and customs trade data for copper and aluminum alloy imports.
Input-output matrices mapping terminal unit shipments to installation environment buildouts across the projection horizon generated volume and value estimates. Segmentation dimensions modeled include product type, installation environment, technology platform, and end-use industry, with protected radius calculations and certification tier requirements serving as industry-specific forecast inputs. CAGRs were derived from regression analysis of historical procurement patterns against infrastructure investment cycles.
Caveats apply where copper price volatility, CE marking timeline delays, or wind turbine height regulation changes could materially shift the outlook. Deviation in specification authority migration speed from general contractors to specialized consultants would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
Frameless Brushless DC Motors Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Global Low Voltage Electric Drives Market
Electrical Power Equipment
Solar Combiner Boxes Market
Electrical Power Equipment
Fault Circuit Indicator Market
Electrical Power Equipment
Magnetic Optical Current Transformer Market
Electrical Power Equipment
North America Gas Insulated Switchgear Market
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
Smart Electric Heater Market
Electrical Power Equipment
Middle East and Africa High Voltage Switchgear Market
Electrical Power Equipment
Power Line Carrier System Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
Nuclear Cables Sales Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Fuse Link Market