
 Alternating Current (AC) Electric Drives Market | 2026-2036
Alternating Current (AC) Electric Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Alternating Current (AC) Electric Drives Market Outlook
IE3 premium efficiency tier adoption is collapsing the cost gap between standard and high-performance AC electric drives. ABB Ltd leverages its integrated power electronics portfolio to dominate high-voltage industrial installations. Siemens AG anchors European demand through its digital drive platforms that bundle hardware with predictive analytics software. Yaskawa Electric Corporation specializes in servo drive architectures for precision robotics applications across Asia-Pacific manufacturing bases.
Alternating current electric drives are power conversion systems that modulate voltage and frequency to control AC motor torque and speed, typically operating across 0.1 kW to 100 MW ranges with switching frequencies between 2 kHz and 16 kHz depending on insulated-gate bipolar transistor or silicon carbide power stage design. These systems serve primarily to reduce energy consumption in motor-driven processes and enable precise motion control in automated machinery. Variable frequency drives command the largest installed base among product types due to their ubiquity in pump and fan applications, while servo drives capture disproportionate margin pools in robotics and semiconductor manufacturing where positioning accuracy below one arc-minute commands price premiums. Soft starters retain defensive positions in mining and heavy material handling where mechanical stress reduction outweighs full variable speed requirements.
IEC 60034-30-1 efficiency class mandates and EU Ecodesign Directive Lot 30 regulations are compelling drive-motor system upgrades across European industrial facilities, while China's GB 18613 motor efficiency standards enforce parallel compliance timelines for domestic and imported equipment. OSHA lockout-tagout requirements and NFPA 70 electrical codes in the United States shape safety interlock architectures and enclosure ratings for drive installations in manufacturing environments. Stakeholders must monitor silicon carbide device cost curves and embedded AI-based condition monitoring integration as these elements determine which suppliers capture replacement cycle volumes without explicit year-dependent commitments.
Market Dynamics
Silicon carbide power semiconductors are compressing switching losses and thermal management costs, forcing incumbent insulated-gate bipolar transistor architectures into defensive repositioning across industrial drive portfolios.
Growth Catalysts
- IEC 60034-30-1 mandates:EU Ecodesign Directive Lot 30 compels motor-drive system retrofits across German and Italian manufacturing facilities, accelerating replacement cycles for sub-IE3 efficiency classes.
- China coastal automation:Manufacturing clusters in Jiangsu and Guangdong provinces deploy variable frequency drives at scale for pump and fan energy optimization in chemical processing plants.
- Servomechanism precision demands:Semiconductor lithography and battery electrode coating operations require positioning accuracy below one arc-minute, expanding addressable margin pools for high-frequency drive architectures.
Market Restraints
- Silicon carbide substrate costs:Wafer processing bottlenecks and limited 6-inch substrate supply concentrate pricing power with Japanese and US substrate manufacturers.
- Copper and rare earth magnet volatility:Permanent magnet synchronous motor dependencies expose drive system costs to neodymium-dysprosium price swings from Chinese separation and refining operations.
- Functional safety certification timelines:IEC 61800-5-2 safe torque-off and safe stop implementations extend development cycles by 8-14 months for new drive platform introductions.
Strategic Opportunities
- India industrial electrification:Bureau of Energy Efficiency standards and state-level industrial efficiency incentives create replacement demand in Maharashtra and Gujarat textile processing corridors.
- Embedded AI condition monitoring:Vibration signature analysis and bearing degradation prediction bundled into drive firmware enables predictive maintenance revenue streams.
- Electrolyzer hydrogen production:Gigawatt-scale green hydrogen projects in Denmark and Spain require megawatt-class drives for alkaline and proton exchange membrane stack compression systems.
Industry Challenges
- Power electronics engineering scarcity:Insulated-gate bipolar transistor and silicon carbide gate driver design expertise concentrates with legacy automotive inverter teams, constraining drive OEM hiring pipelines.
- Legacy fieldbus integration:PROFIBUS and DeviceNet installations in established process plants resist migration to EtherCAT and PROFINET without full automation system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternating Current (AC) Electric Drives Market |
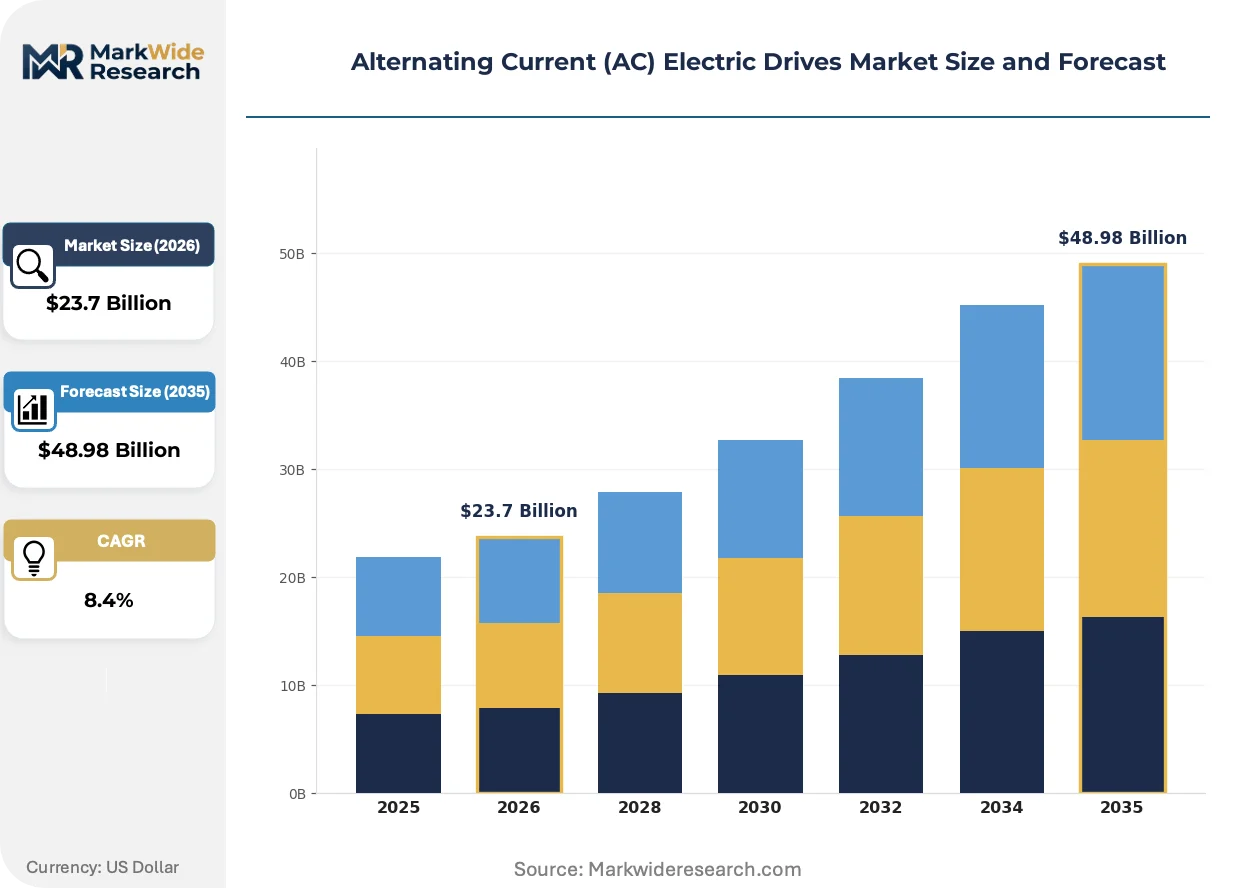
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Variable Frequency Drives, Servo Drives, Soft Starters, Direct On-Line Drives End User: Manufacturing, Automotive, HVAC, Mining Technology: Induction Motors, Synchronous Motors, Permanent Magnet Motors, Others Application: Industrial Automation, Electric Vehicles, Renewable Energy Systems, Robotics |
| Companies Covered | ABB Ltd, Siemens AG, Schneider Electric SE, Danfoss Group, Rockwell Automation Inc, Yaskawa Electric Corporation, Mitsubishi Electric Corporation, Fuji Electric Co., Ltd, Parker Hannifin Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternating Current (AC) Electric Drives Market Strategic Shifts
Power semiconductor material transitions and embedded intelligence layers are restructuring competitive differentiation, compressing hardware margins while expanding software and service attach rates.
Silicon carbide metal-oxide-semiconductor field-effect transistors enable higher switching frequencies with reduced cooling overhead, shrinking drive enclosure volumes by 30-40 percent. Automotive inverter spin-off suppliers are transferring 800-volt electric vehicle designs into industrial drive platforms. This semiconductor substitution is supplanting insulated-gate bipolar transistor dominance in 11-kilowatt and above power classes.
EU F-Gas Regulation phase-down schedules accelerate refrigerant compressor drive upgrades in commercial cold chain infrastructure. The regulation bans hydrofluorocarbon refrigerants with global warming potential above 150, forcing supermarket and logistics warehouse operators to replace fixed-speed compressors with variable frequency drive systems. Italian and Spanish food retail chains face 2027 compliance deadlines, compressing procurement timelines.
Outcome-based performance contracts are displacing capital expenditure purchase models in water utility and district heating sectors. Danish and Dutch municipal operators now compensate drive suppliers based on verified kilowatt-hour savings against baseline consumption. This contractual transformation shifts risk to vendors while extending customer lifetime value through multi-year service entanglements.
Alternating Current (AC) Electric Drives Market Segmentation
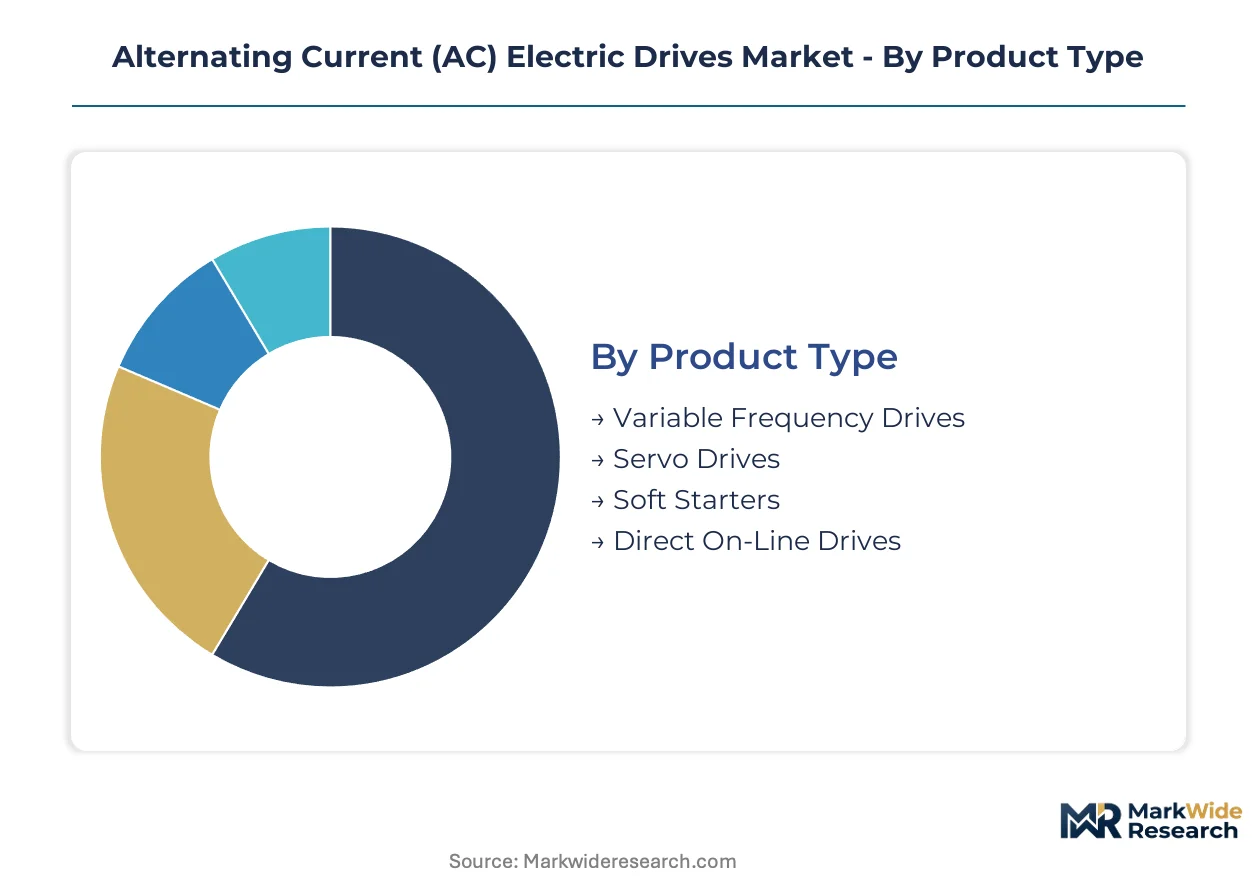
AC electric drive segmentation reveals how power conversion architectures align with distinct torque-speed requirements and energy efficiency mandates across industrial infrastructure. Product type and end-use configurations determine switching frequency specifications, enclosure ratings, and software integration depth.
Product Type:
Soft starters face the most acute substitution pressure as variable frequency drives encroach on cost-sensitive pump and fan applications where full speed control was previously uneconomical.
- Variable Frequency Drives:These systems modulate both voltage and frequency through pulse-width modulation, enabling continuous speed adjustment across 0.1 kW to 100 MW ranges. Demand concentrates in German chemical processing facilities and Jiangsu province water treatment plants where EU Ecodesign Directive Lot 30 and China's GB 18613 standards compel motor system retrofits.
- Servo Drives:High-bandwidth architectures with positioning accuracy below one arc-minute serve semiconductor lithography and battery electrode coating operations. Japanese automotive component suppliers in Aichi prefecture deploy these for multi-axis robotics in electric vehicle powertrain assembly.
- Soft Starters:Limit inrush current and mechanical stress through thyristor-based voltage ramping, retaining defensive positions in Australian iron ore crushing circuits where torque shock reduction outweighs variable speed requirements.
- Direct On-Line Drives:Fixed-speed contactor configurations persist in Indian agricultural pump sets and Southeast Asian rice milling operations where capital constraints override efficiency optimization.
Variable frequency drives retain volume leadership across installed base; servo drives hold the steepest expansion curve in precision manufacturing corridors.
End User:
Cost tier stratification separates premium efficiency mandates in European automotive from price-optimized procurement patterns in emerging market mining operations.
- Manufacturing:Discrete automation and process industries deploy drives for conveyor systems, extruders, and machine tool spindles. Italian packaging machinery OEMs integrate compact servo drives for motion synchronization in pharmaceutical blister packaging lines.
- Automotive:Electric vehicle powertrain testing and battery formation equipment require regenerative drive capabilities. South Korean battery cell manufacturers in Gyeonggi province specify 800-volt compatible architectures for gigafactory expansion.
- HVAC:Commercial building chillers and air handling units prioritize part-load efficiency. French supermarket chains retrofit refrigerant compressor drives to meet EU F-Gas Regulation hydrofluorocarbon phase-down schedules.
- Mining:Dragline excavators and conveyor belt systems demand ruggedized enclosures with IP65 ratings and active rectifier front ends for regenerative braking in Chilean copper extraction operations.
Manufacturing commands the broadest application footprint; automotive applications are climbing the fastest as electrification accelerates powertrain testing infrastructure.
Technology:
Motor technology selection hinges on rare earth magnet supply security and efficiency tier compliance rather than raw performance specifications.
- Induction Motors:Squirrel-cage rotors without permanent magnets eliminate supply chain exposure to Chinese neodymium processing. These dominate Brazilian sugar mill crushing drives where maintenance simplicity outweighs premium efficiency targets.
- Synchronous Motors:Field-excited rotors enable power factor correction in large compressor installations. Norwegian offshore platform operators specify these for gas injection compressors in North Sea oil recovery.
- Permanent Magnet Motors:Neodymium-iron-boron rotors achieve highest efficiency classes but face cost volatility. Danish wind turbine nacelle manufacturers integrate these for generator pitch control despite magnet price uncertainty.
- Others:Switched reluctance and synchronous reluctance architectures gain traction in traction applications where magnet-free operation is mandatory.
Induction motors retain volume leadership across legacy installed base; permanent magnet configurations are expanding most quickly in efficiency-critical renewable energy integration.
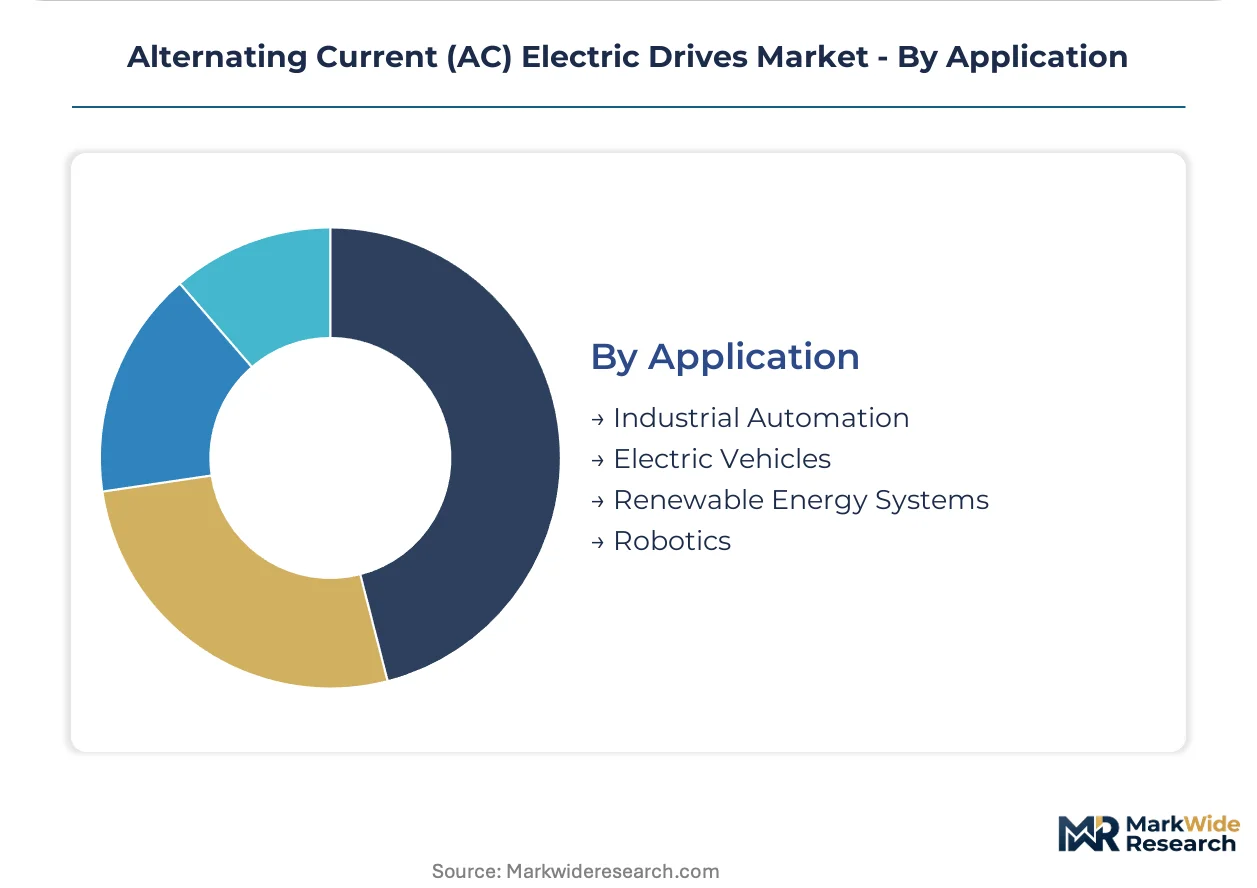
Application:
Application segmentation tracks how drive architectures adapt to motion control precision requirements versus energy optimization priorities.
- Industrial Automation:Programmable logic controller integration and deterministic fieldbus protocols dominate. German automotive tier suppliers deploy EtherCAT-connected servo drives for power seat assembly lines.
- Electric Vehicles:Onboard chargers and thermal management systems require compact 400-volt and 800-volt compatible drives. Spanish bus manufacturers in Zaragoza integrate these for electric transit fleet electrification.
- Renewable Energy Systems:Solar inverter and wind turbine pitch control applications demand grid code compliance. Polish onshore wind developers specify drives with LVRT capability for grid connection stability.
- Robotics:Collaborative robot joints and SCARA systems require harmonic distortion below 5 percent and safety-rated torque monitoring. Singapore precision electronics assembly facilities prioritize these specifications.
Industrial automation retains volume leadership; robotics applications hold the steepest expansion curve as collaborative systems penetrate small-batch manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German industrial buyers absorb premium-tier pricing for IE3-compliant drive-motor systems, while Indian textile processors prioritize capital efficiency over efficiency class upgrades. Chinese coastal manufacturers occupy the middle ground, trading specification depth for procurement scale.
China
Jiangsu and Guangdong province manufacturers deploy variable frequency drives at scale for chemical processing pump optimization. GB 18613 motor efficiency standards enforce parallel compliance timelines for domestic and imported equipment. Shenzhen and Suzhou industrial clusters drive procurement volumes as automation accelerates across electronics assembly and battery cell manufacturing.
Germany
Rhineland chemical processors and Bavarian automotive suppliers retrofit sub-IE3 motor systems under regulatory pressure. EU Ecodesign Directive Lot 30 compels drive-motor system upgrades across industrial facilities. Stuttgart and Munich manufacturing corridors concentrate demand for servo drive architectures in precision assembly applications.
United States
Texas oilfield services and Great Lakes automotive suppliers balance efficiency mandates against capital cycle timing. OSHA lockout-tagout requirements and NFPA 70 electrical codes shape safety interlock architectures for drive installations. Houston and Detroit industrial bases anchor replacement demand as aging infrastructure reaches end-of-life.
India
Maharashtra and Gujarat textile processors face Bureau of Energy Efficiency standards driving replacement cycles in dyeing and finishing operations. State-level industrial efficiency incentives reduce payback periods for variable frequency drive retrofits. Ahmedabad and Mumbai manufacturing corridors concentrate procurement as electrification expands beyond tier-one cities.
Japan
Aichi prefecture automotive component suppliers deploy high-bandwidth servo drives for electric vehicle powertrain assembly. METI energy efficiency guidelines and JIS standards shape product specification requirements. Nagoya and Toyota City manufacturing clusters drive demand for multi-axis robotics integration in precision assembly lines.
Alternating Current (AC) Electric Drives Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the AC electric drives landscape. The vendor base stratifies into three tiers: integrated industrial conglomerates with power electronics portfolios, motion control specialists with servo architectures, and regional fabricators serving price-sensitive replacement markets. European and Japanese conglomerates anchor premium positioning through bundled hardware-software platforms. Competitive moves center on silicon carbide power semiconductor integration and embedded AI condition monitoring firmware development.
Within the integrated industrial tier, ABB Ltd and Siemens AG exemplify conglomerate-scale positioning spanning high-voltage installations through digital drive platforms. Yaskawa Electric Corporation occupies a specialist position in servo drive architectures for precision robotics applications. These three entities represent distinct competitive vectors: ABB anchors heavy industrial project execution, Siemens bundles predictive analytics software, and Yaskawa concentrates high-frequency motion control expertise.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Schneider Electric SE |
| Danfoss Group |
| Rockwell Automation Inc |
| Yaskawa Electric Corporation |
| Mitsubishi Electric Corporation |
| Fuji Electric Co., Ltd |
| Parker Hannifin Corp |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Japanese silicon carbide wafer foundries shapes price floors across 11-kilowatt and above drive classes, concentrating supply-side leverage with substrate manufacturers while compressing margins for insulated-gate bipolar transistor legacy portfolios. EU Ecodesign Directive Lot 30 compliance timelines and China's GB 18613 enforcement create tiered demand elasticity, with German chemical processors absorbing premium-tier pricing and Indian textile operators deferring upgrades.
Pricing Analysis
EU Ecodesign Directive Lot 30 dictates the pricing tier structure across European industrial procurement, separating IE3 premium efficiency systems from standard-tier alternatives through mandatory retrofit timelines. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Cost compression in economy-tier variable frequency drives is intensifying because automotive inverter spin-off suppliers transfer 800-volt electric vehicle designs into industrial platforms. Indian agricultural pump set buyers exhibit highest price sensitivity; German automotive tier suppliers demonstrate lowest elasticity for servo drive architectures.
Supply Chain Analysis
Tai Strait transit underwrites rare earth magnet supply security for permanent magnet synchronous motor configurations, exposing drive system costs to logistics disruption. Manufacturing concentrates in China, Japan, and Germany for power semiconductor fabrication, control electronics assembly, and precision mechanical components. Raw material dependencies span silicon carbide substrates, neodymium-iron-boron magnets, and electrolytic copper windings. Single-source vulnerability concentrates with Japanese 6-inch substrate manufacturers. Distribution runs through authorized industrial distributor networks and direct OEM procurement channels for large project installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across precision manufacturing corridors creates specialist niches as semiconductor lithography and battery electrode coating operations demand positioning accuracy below one arc-minute, diverging from energy optimization priorities in process industries.
For Market Incumbents: Fortify silicon carbide power electronics portfolios through backward integration into substrate sourcing or captive gate driver design capacity. Lock in German and Italian manufacturing facility retrofit volumes under EU Ecodesign Directive Lot 30 compliance timelines. Defend against automotive inverter spin-off suppliers by accelerating embedded AI condition monitoring firmware development.
For New Entrants and Emerging Players: IEC 61800-5-2 safe torque-off certification fast-track opens procurement access to European automotive and material handling sectors where functional safety mandates extend incumbent development cycles. Target Indian Maharashtra and Gujarat textile processing corridors where Bureau of Energy Efficiency standards drive replacement demand with limited established vendor presence. Pursue outcome-based performance contracting for water utility retrofits to bypass capital expenditure barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors motion control specialists with servo architecture expertise over commodity variable frequency drive fabricators. Five-to-ten year viability hinges on silicon carbide transition completion and embedded AI integration depth. Acquisition target archetype: regional fabricators with installed base access and service infrastructure. Signal to watch: automotive inverter supplier entry into industrial drive portfolios as technology transfer accelerates.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Stage Transition | Reduces thermal management costs and enclosure volumes for ABB and Siemens high-voltage installations. |
| Embedded AI Condition Monitoring Integration | Enables predictive maintenance revenue streams through vibration signature analysis bundled in Yaskawa firmware. |
| EU Ecodesign Compliance Certification | Unlocks German and Italian manufacturing facility retrofit procurement under Lot 30 mandates. |
| India Industrial Electrification Partnership | Captures Maharashtra and Gujarat textile processing corridor replacement cycles through state efficiency incentives. |
| Electrolyzer Drive System Development | Positions suppliers for Denmark and Spain gigawatt-scale green hydrogen compression applications. |
Study Parameters
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and control systems integrators and secondary validation through SEC 10-K filings, customs and trade data, IEC standard documentation, and national energy efficiency program disclosures anchors the qualitative findings. Bottom-up triangulation from installed base estimates and replacement cycle timing converges with top-down demand modeling across manufacturing, automotive, HVAC, and mining end-use segments.
Sensitivity analysis across silicon carbide cost curve trajectories, rare earth magnet price volatility bands, and regulatory compliance timeline scenarios informs the projection framework. Segmentation dimensions span product type, end user, motor technology, and application precision requirements. CAGRs derive from replacement cycle velocity, efficiency mandate enforcement intensity, and automation capital expenditure patterns. Industry-specific inputs include semiconductor lithography equipment orders and electric vehicle powertrain testing infrastructure buildout.
Underlying assumptions cover IEC 60034-30-1 efficiency class adoption curves, China coastal automation investment continuity, and silicon carbide substrate supply expansion, with deviation risk concentrated in neodymium-dysprosium price swings and functional safety certification timeline extensions. Practitioners should keep alternative scenarios live as EU F-Gas Regulation phase-down schedules and India Bureau of Energy Efficiency standard revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
HV Bushing Market
Electrical Power Equipment
Fault Circuit Indicator Market
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
Digital Fault Recorder (DFR) Market
Electrical Power Equipment
SF6 Gas Circuit Breaker Market
Electrical Power Equipment
3rd Rail Current Collector Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
Subsea Cables Equipment Market
Electrical Power Equipment
Bucket Water Heater Market
Electrical Power Equipment
Magnetic Optical Current Transformer Market
Electrical Power Equipment
United States Electric Space Heaters Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
Canada Electric Space Heater Market
Electrical Power Equipment
Europe Gas Insulated Switchgear Market
Electrical Power Equipment
Smart Electric Heater Market