
 North America Power Transformer Market | 2026-2036
North America Power Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Power Transformer Market Insights
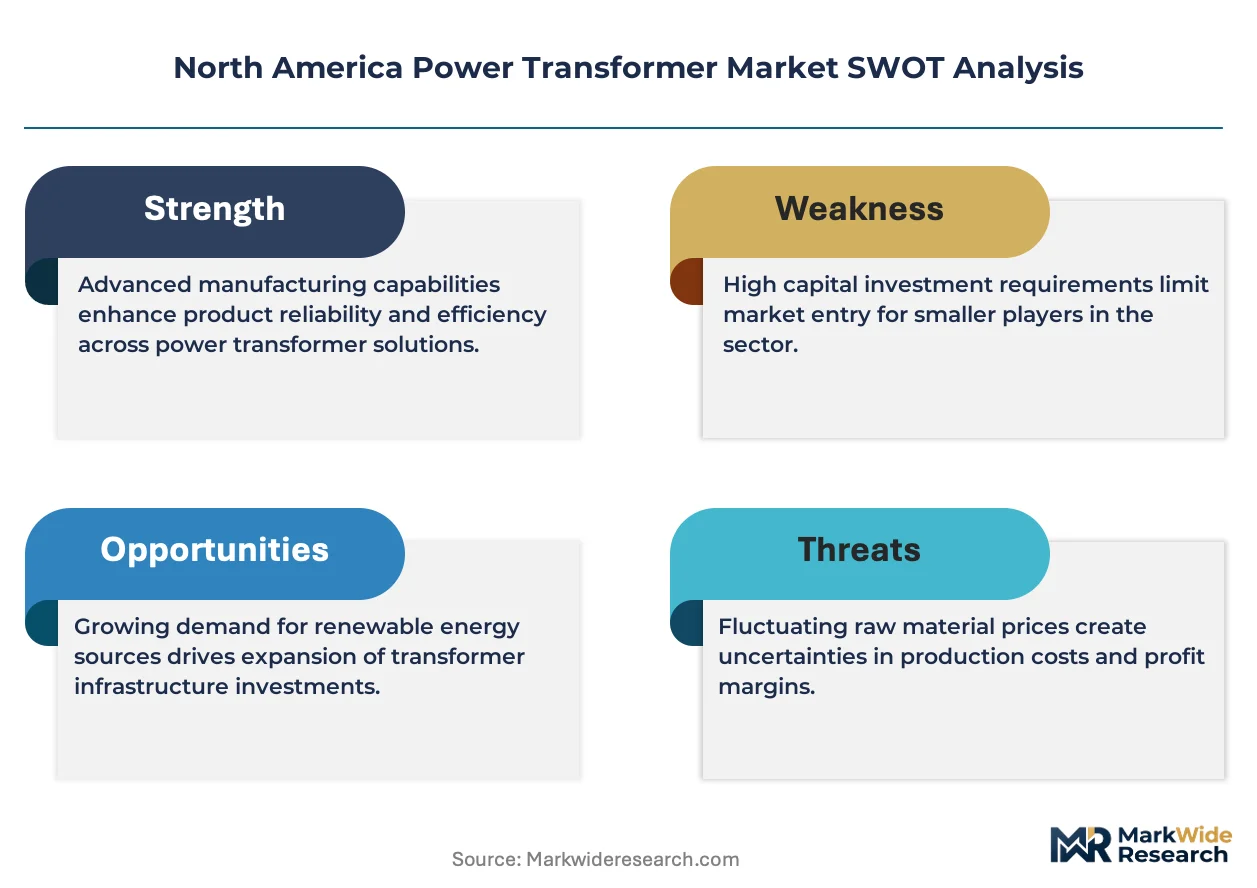
Aftermarket service revenue is tilting toward lifecycle asset management contracts as utilities defer greenfield capital. Siemens Energy anchors its North American presence through regional service hubs and refurbishment capabilities for aging infrastructure. General Electric leverages its Waukesha manufacturing footprint to compete on lead times for large power-class units. Virginia Transformer Corp specializes in domestic production of extra-high-voltage designs, sustaining margin pools that imports struggle to match.
A power transformer is an electromagnetic apparatus that transfers electrical energy between circuits through magnetic induction, typically operating at frequencies of 50 or 60 hertz with voltage ratings spanning from kilovolt to ultra-high-voltage classes above 765 kV; its core function is to step voltage up for efficient long-distance transmission or step it down for safe distribution to end users. Step-up configurations dominate new order books as renewable generation clusters require voltage elevation before grid injection, while smart technology segments capture expanding value through embedded sensors and predictive diagnostics. Oil-filled designs still occupy the bulk of installed base megavolt-ampere capacity, though dry-type variants are gaining share in urban substations and offshore wind platforms where fire safety constraints apply.
FERC Order 2023 and NERC reliability standards are tightening efficiency and interoperability requirements for grid-connected assets across the United States, while Canadian provincial regulators and the EPA's revised SF6 emissions guidelines are adding compliance layers that favor sealed-tank designs and alternative insulating mediums. State-level renewable portfolio standards in California, Texas, and New York are mandating transformer upgrades capable of handling bidirectional power flows from distributed solar and battery storage. Stakeholders must monitor how evolving efficiency tiers and carbon-accounting rules reshape procurement criteria before the next major replacement cycle locks in technology choices for decades.
Market Dynamics
Utility-scale renewable interconnection mandates are compressing procurement cycles for high-voltage step-up transformers across the United States and Canada, forcing manufacturers to recalibrate lead times and capacity allocation.
Growth Catalysts
- FERC Order 2023:Grid modernization mandates accelerate replacement of aging transmission infrastructure with high-efficiency units capable of bidirectional power flows.
- Data center load clusters:Hyperscale facilities in Texas and Virginia are driving concentrated demand for extra-high-voltage step-up configurations.
- SF6 phase-down regulations:EPA emissions guidelines favor sealed-tank designs and alternative insulating mediums in new procurement specifications.
Market Restraints
- Grain-oriented electrical steel concentration:Supply dependency on Asian specialty steel mills creates input cost volatility and extended lead times.
- Extra-high-voltage testing infrastructure scarcity:Limited domestic high-potential test facilities constrain validation throughput for 500 kV+ designs.
- Copper and aluminum price correlation:Raw material index fluctuations compress margin visibility on fixed-price utility contracts.
Strategic Opportunities
- Canadian provincial offshore wind:Atlantic Canada lease rounds create first-mover positioning for platform-compatible dry-type transformer designs.
- Lifecycle asset management contracts:Utilities deferring greenfield capital open recurring revenue streams for refurbishment and monitoring services.
- Smart sensor convergence:Embedded dissolved gas analysis and thermal monitoring integration enables predictive maintenance value capture.
Industry Challenges
- Specialized winding technician scarcity:Retirement-driven talent gaps in precision coil manufacturing constrain output scaling.
- NERC CIP-014 physical security compliance:Substation hardening requirements extend project timelines and complicate site logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Power Transformer Market |
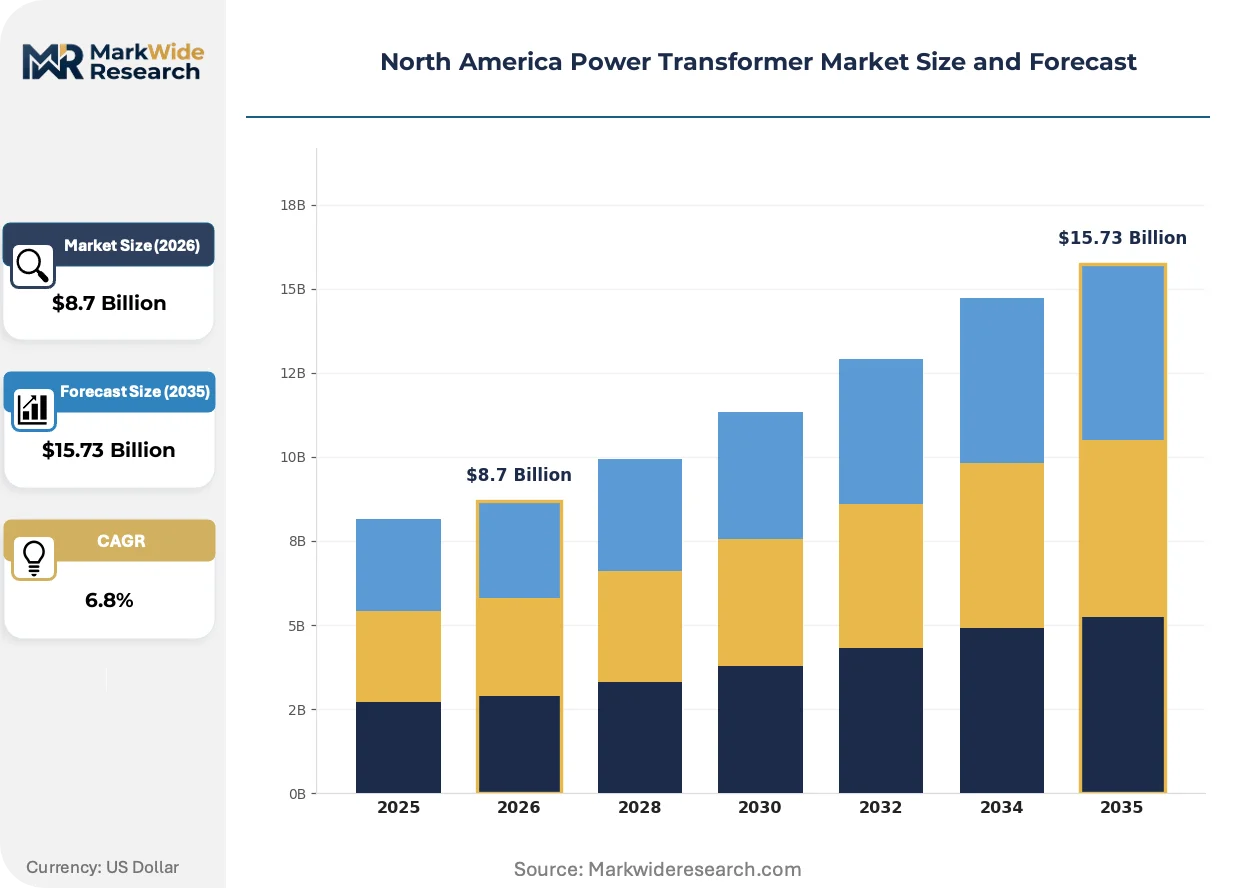
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Step-up, Step-down, Auto, Three-phase Application: Electric Utility, Industrial, Renewable Energy, Commercial End User: Transmission Companies, Distribution Utilities, Power Plants, Industrial Users Technology: Conventional, Smart, Dry-type, Oil-filled |
| Companies Covered | General Electric, Siemens Energy AG, Eaton Corporation PLC, ABB Ltd, Schneider Electric SE, Virginia Transformer Corp, Hammond Power Solutions, Prolec-GE Waukesha, Inc., Hitachi Energy Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Power Transformer Market Trends and Innovations
Digital instrumentation and alternative insulation chemistries are redefining transformer lifecycle economics, shifting buyer evaluation criteria from first cost to total asset performance.
Natural ester insulating fluids derived from seed oils are rendering obsolete conventional mineral oil in environmentally sensitive installations. Coastal utilities and urban substation operators in California and New York specify these biodegradable alternatives for fire safety and spill containment. The technology is rendering obsolete legacy tank designs that cannot accommodate higher viscosity thermal profiles.
FERC Order 2023 mandates efficiency and interoperability standards for grid-connected assets across the United States. The regulation compels utilities to specify transformers with standardized communication protocols and upgraded core steel grades. Texas and California transmission operators are front-loading procurement to lock in compliant designs before compliance deadlines tighten.
Long-term service agreements are displacing transactional maintenance contracts among North American utilities. Asset owners in Ontario and the US Midwest now prioritize lifecycle cost guarantees over unit purchase price in vendor selection. This shift concentrates aftermarket revenue with manufacturers possessing regional refurbishment capabilities and spare parts warehousing.
North America Power Transformer Market Segmentation
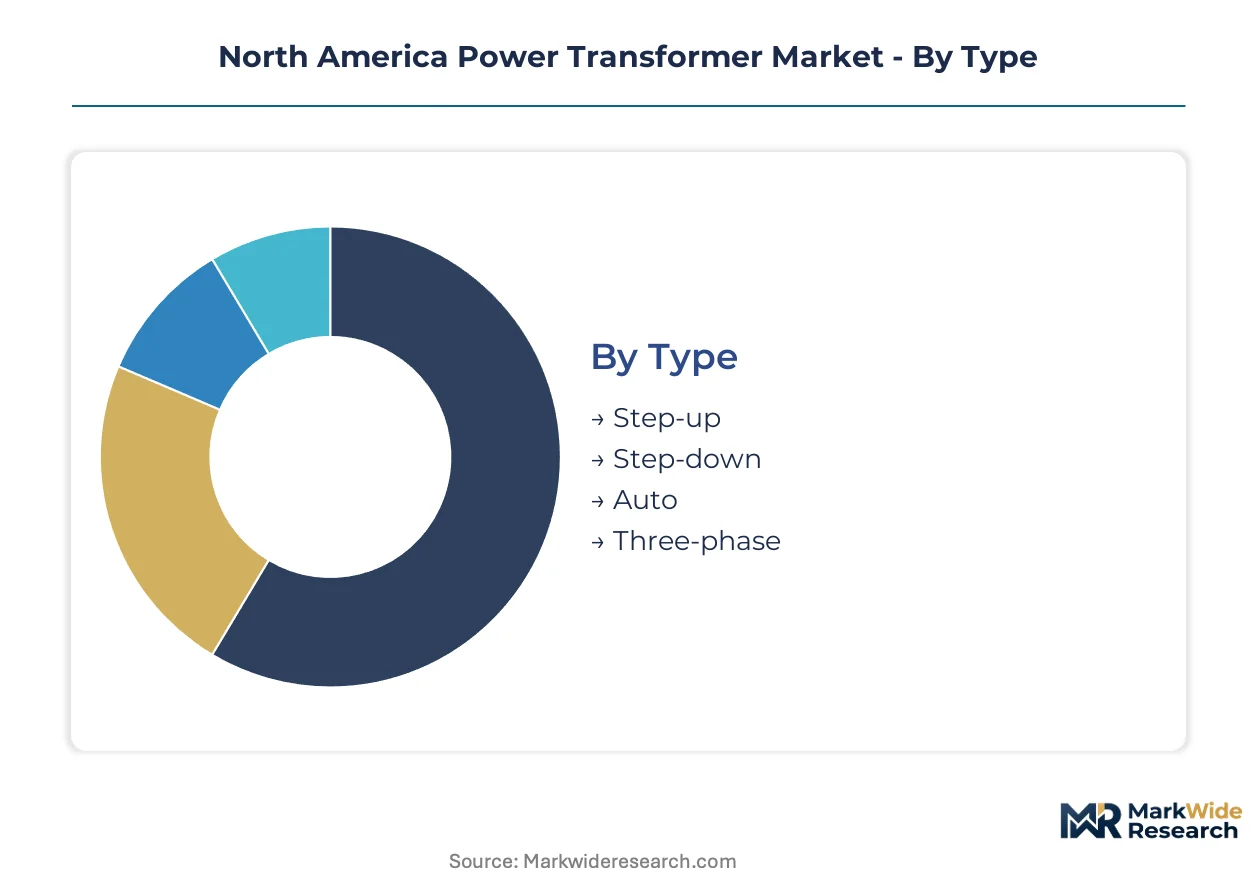
Power transformer procurement patterns diverge sharply across voltage classes and end-use contexts. Understanding these segment boundaries clarifies where specification standards, lead time pressures, and technology substitution risks concentrate.
Type:
Mature designs dominate installed base capacity while emerging configurations capture renewable interconnection growth.
- Step-up:These units elevate generator output voltage for efficient long-distance transmission. Utility-scale solar clusters in Texas and California are compressing procurement cycles for 345 kV+ step-up configurations as interconnection queues lengthen.
- Step-down:Voltage reduction units feed distribution networks at substation interfaces. Aging infrastructure replacement across the US Midwest and Ontario is sustaining steady demand for 138 kV/69 kV step-down designs despite capital deferral trends.
- Auto:Single-winding designs offer compact footprints for voltage ratio applications below 3:1. Limited adoption in North America reflects preference for isolation between primary and secondary circuits in utility specifications.
- Three-phase:Standard polyphase configurations handle bulk power transfer across transmission corridors. The design remains the default specification for utility procurement in both the United States and Canada.
Step-down configurations handle the majority of installed base throughput; step-up designs are expanding most quickly on share as renewable generation accelerates.
Application:
Cost tier differentiation separates capital-intensive utility infrastructure from commercial and industrial deployments with shorter payback horizons.
- Electric Utility:Transmission and distribution operators specify large power-class units with 30-40 year service life expectations. FERC Order 2023 compliance deadlines are accelerating procurement of high-efficiency replacements across US grid operators.
- Industrial:Heavy manufacturing and petrochemical facilities require reliable step-down capacity for process loads. Gulf Coast chemical complexes and Great Lakes automotive plants are driving demand for ruggedized designs with enhanced short-circuit withstand.
- Renewable Energy:Wind and solar generation clusters need voltage elevation before grid injection. Offshore wind lease rounds in Atlantic Canada are creating first-mover opportunities for platform-compatible transformer specifications.
- Commercial:Data centers, hospitals, and large retail complexes specify smaller distribution-class units. Hyperscale facility expansion in Northern Virginia and Dallas-Fort Worth is concentrating demand for compact substation designs.
Electric Utility applications absorb the dominant share of megavolt-ampere capacity; Renewable Energy deployments are climbing the fastest on volume contribution.
End User:
Customer type determines specification authority, with transmission companies holding the most stringent technical requirements.
- Transmission Companies:Regional transmission organizations and independent system operators procure extra-high-voltage units for interstate corridors. ERCOT and CAISO interconnection standards are reshaping transformer specifications toward bidirectional power flow capability.
- Distribution Utilities:Municipal and investor-owned utilities source medium-voltage distribution transformers. Ontario's Hydro One and Texas municipal utilities are prioritizing lifecycle asset management contracts over unit purchases.
- Power Plants:Generator step-up transformers at thermal, nuclear, and renewable facilities require matched impedance characteristics. Combined-cycle gas turbine installations in the US Southeast are sustaining demand for large power-class step-up designs.
- Industrial Users:Captive power consumers specify dedicated transformer capacity for manufacturing processes. Alberta oil sands operators and Pennsylvania shale gas processors require explosion-resistant tank designs for hazardous location classification.
Transmission Companies command the highest specification tier; Distribution Utilities represent the steepest expansion trajectory as grid modernization accelerates.
Technology:
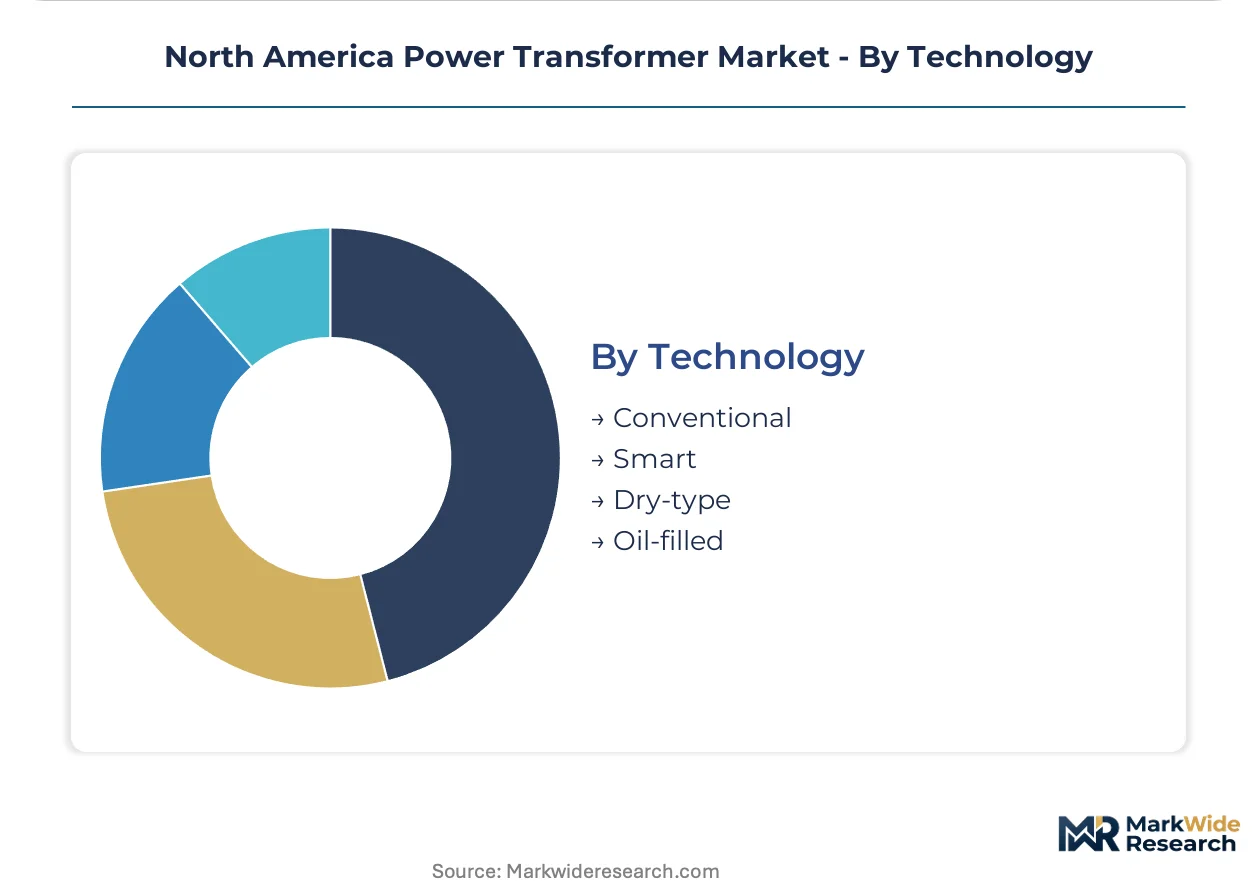
Supply concentration in core steel and winding expertise favors incumbent oil-filled designs while dry-type and smart segments gain share in niche applications.
- Conventional:Standard electromagnetic designs with mineral oil insulation and passive cooling dominate replacement cycles. The installed base across the United States and Canada locks in continued demand for compatible refurbishment services.
- Smart:Embedded sensors and communication modules enable dissolved gas analysis and thermal monitoring. California and New York utilities are mandating predictive diagnostic capability in new procurement specifications.
- Dry-type:Cast resin or vacuum pressure impregnated designs eliminate liquid insulation for fire-sensitive installations. Urban substations in Manhattan and Toronto are specifying dry-type replacements where spill containment is impractical.
- Oil-filled:Liquid-immersed designs with mineral or natural ester fluid retain cost advantages for large power ratings. Sealed-tank configurations are displacing conservator designs as EPA SF6 emissions guidelines tighten.
Oil-filled technology retains the dominant share of new and replacement capacity; Smart transformer configurations are gaining share fastest as digitalization mandates spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North American jurisdictions, with the United States prioritizing transmission-scale interconnection capacity while Canadian provinces emphasize lifecycle asset refurbishment and offshore wind readiness.
United States
ERCOT interconnection queues and CAISO renewable mandates are compressing procurement cycles for 345 kV+ step-up transformers. FERC Order 2023 compels grid operators to specify bidirectional power flow capability and standardized communication protocols. Northern Virginia data center clusters and Texas solar farms represent the densest demand concentrations.
Canada
Ontario's Hydro One and provincial utilities are prioritizing refurbishment contracts over greenfield procurement as capital budgets tighten. Environment and Climate Change Canada guidelines on SF6 emissions are accelerating sealed-tank specifications. Atlantic Canada offshore wind lease rounds are creating first-mover opportunities for platform-compatible dry-type designs.
Mexico
CFE transmission expansion and private renewable energy auctions are sustaining import demand for medium-voltage distribution transformers. CRE regulatory reforms are standardizing efficiency requirements for grid-connected assets. Baja California and Sonora industrial corridors are absorbing concentrated capacity for manufacturing and mining loads.
North America Power Transformer Market Competitive Landscape
Capability concentration sits with domestic extra-high-voltage specialists; scale advantage sits with diversified industrial conglomerates with integrated energy portfolios. The market structures around three tiers: multinational OEMs with full voltage-class coverage, regional fabricators with refurbishment expertise, and niche specialists in dry-type or smart-embedded designs. Dominant competitive moves include backward integration into core steel supply chains and geographic expansion through regional service hub establishment.
Within the multinational OEM tier, General Electric and Siemens Energy occupy positions as scale-driven incumbents with integrated manufacturing and service networks. Virginia Transformer Corp exemplifies the domestic specialist archetype, concentrating on extra-high-voltage designs where import competition faces margin and lead-time disadvantages. Hammond Power Solutions represents the mid-market distribution-focused segment, serving commercial and industrial substation applications with standardized product platforms.
| Leading Market Players |
|---|
| General Electric |
| Siemens Energy AG |
| Eaton Corporation PLC |
| ABB Ltd |
| Schneider Electric SE |
| Virginia Transformer Corp |
| Hammond Power Solutions |
| Prolec-GE Waukesha, Inc. |
| Hitachi Energy Ltd |
| Others |
Pricing and Supply Chain Analysis
Waukesha's manufacturing cluster anchors North American extra-high-voltage capacity, concentrating pricing power among domestic fabricators capable of 500 kV+ validation. Regional service hub density determines aftermarket margin capture as utilities shift toward lifecycle contracts over unit procurement.
Pricing Analysis
Long-term offtake agreements dominate utility-scale procurement, insulating manufacturers from spot volatility in copper and grain-oriented electrical steel. Price differentiation hinges on NERC CIP-014 certification tier and embedded smart monitoring capability. Cost compression in standard distribution-class units intensifies as Asian imports compete on first cost. Industrial captive buyers exhibit highest price sensitivity; transmission companies prioritize lifecycle guarantees over unit economics.
Supply Chain Analysis
Export control regimes on advanced core steel laminations constrain flows from Japanese and South Korean specialty mills. Manufacturing draws from concentrated Asian feedstock for electrical steel, copper winding wire, and insulating paper. Single-source vulnerability in grain-oriented steel creates input cost volatility. Distribution runs through regional fabrication hubs with captive refurbishment capacity serving utility aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive moat built on regulatory entrenchment. FERC Order 2023 compliance deadlines and NERC reliability standards create switching costs that lock in incumbent positions for decades.
For Market Incumbents: Harden domestic extra-high-voltage testing infrastructure to extend lead-time advantages over import competition. Deepen backward integration into core steel supply chains to insulate margin pools from Asian mill pricing volatility. Invest in smart sensor R&D as California and New York utilities mandate predictive diagnostic capability in new specifications.
For New Entrants and Emerging Players: Establish a beachhead in Atlantic Canada offshore wind platform specifications where first-mover positioning remains open. Target dry-type transformer designs for urban substation replacement cycles in Manhattan and Toronto. Pursue joint development agreements with European offshore wind EPCs lacking North American manufacturing footprint.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic specialists with captive refurbishment networks and spare parts warehousing. Long-term viability rests on lifecycle contract recurring revenue rather than unit sales cyclicality. Monitor FERC efficiency tier updates as inflection indicator for next replacement wave timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Steel Supply | Captive sourcing from Japanese specialty mills insulates margin pools from tariff exposure. |
| Smart Sensor Platform Development | Embedded dissolved gas analysis meets California utility digitalization mandates. |
| Regional Service Hub Expansion | Texas and Ontario facilities capture lifecycle contract revenue from deferred greenfield capital. |
| Sealed-Tank Design Certification | EPA SF6 phase-down compliance opens procurement specifications for alternative insulation. |
| Offshore Wind Platform Partnership | Atlantic Canada lease rounds create first-mover positioning for dry-type specifications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across utility planning officers, transformer procurement managers at ERCOT and CAISO, EPC contractors, regional service hub directors, and aftermarket refurbishment technicians. Secondary validation drew from FERC Order 2023 filings, EIA transmission project databases, NERC reliability standard updates, and EPA SF6 emissions guidelines. Bottom-up unit demand estimates triangulated against top-down transmission investment forecasts.
Calibration against historical replacement cycles and interconnection queue data shaped the analytical framework across the analysis window. Segmentation dimensions modeled include voltage class, application context, cooling technology, and end-user specification authority. CAGRs derived from regression against transmission capital expenditure trajectories and renewable capacity addition schedules. Forecast inputs incorporated grain-oriented steel price indices and utility capital deferral propensity surveys.
Sensitivities concentrate around FERC efficiency tier acceleration and NERC CIP-014 physical security compliance timeline shifts. Forecasts reflect documented assumptions on interconnection queue clearance rates and data center load growth trajectories. Material shifts in federal infrastructure appropriations or Canadian provincial capital budgets would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transformers
Rectifier Transformers Market
Transformers
Electric Vehicle Charging Station Transformer Market
Transformers
High Frequency Transformer Market
Transformers
Latin America Transformer Market
Transformers
United States Large Power Transformer Market
Transformers
Green Power Transformers Market
Transformers
Liquid-Immersed Transformers Market
Transformers
Transformer Monitoring Systems (TMS) Market
Transformers
Amorphous Core Transformers Market
Transformers
Canada Transformer Market
Transformers
United States Transformer Market
Transformers
Traction Transformer Market
Transformers
Middle-East Smart Transformer Market
Transformers
Auto Transformer Rectifier Unit (ATRU) Market
Transformers
Transformer Steel Market
Transformers
Global Transformer Market