
 Magnetic Ballast Market | 2026-2036
Magnetic Ballast Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Ballast Market Insights
High-efficiency copper wire winding specifications is redrawing competitive priorities across the magnetic ballast landscape. Signify leverages vertical integration in lamp-ballast pairing to sustain pricing power in commercial retrofits. Tridonic anchors its position through specialized control gear integration for fluorescent systems. Keystone Technologies competes on manufacturing scale across North American distribution channels.
A magnetic ballast is an inductive device constructed from laminated steel cores and copper or aluminum windings that limits current flow in gas-discharge lamps through electromagnetic impedance, typically operating at line frequency with power factors between 0.5 and 0.9 depending on capacitor compensation. Its primary purpose remains stabilizing arc current in fluorescent and HID installations where electronic alternatives face cost or compatibility barriers. Electromagnetic ballasts occupy the largest installed base due to decades of legacy deployment in commercial facilities and government buildings. Fluorescent lighting applications retain dominant volume share though mercury vapor segments face accelerated phase-out pressure from efficiency mandates.
The US Department of Energy enforces minimum efficiency standards under federal appliance regulations while the EPA administers mercury-containing equipment disposal rules that shape replacement cycles and material handling obligations. European REACH restrictions on hazardous substances and RoHS directives limit certain insulation and coating chemistries in export-bound products. Stakeholders must monitor regulatory tightening on power factor requirements and hazardous material content as these standards increasingly determine market access eligibility across jurisdictions.
Market Dynamics
Legacy fluorescent and HID infrastructure across US commercial facilities sustains replacement demand for magnetic ballasts even as electronic alternatives dominate new installations. The US Department of Energy's appliance efficiency standards continue tightening minimum performance thresholds for core materials and winding specifications.
Growth Catalysts
- Educational Infrastructure Modernization:K-12 districts and university systems across the Midwestern United States prioritize electrical system upgrades in aging facilities, sustaining procurement volumes for compatible magnetic ballasts in fluorescent retrofits.
- Federal Efficiency Standards:The US Department of Energy's updated appliance efficiency regulations mandate improved core material grades, compelling manufacturers to upgrade product lines and creating replacement cycles for non-compliant installed base.
- Industrial Retrofit Cycles:Manufacturing facilities in Ohio, Michigan, and Indiana maintain active maintenance schedules for legacy high-bay HID systems where magnetic ballasts retain cost advantages over electronic conversions.
Market Restraints
- Copper and Steel Input Volatility:Laminated silicon steel core prices and copper winding costs fluctuate with commodity markets, compressing margin predictability for manufacturers dependent on these primary materials.
- Electronic Ballast Substitution:Solid-state electronic ballasts offer superior power factor correction and dimming capabilities, displacing magnetic alternatives in new construction and comprehensive renovation projects.
- Mercury Vapor Phase-Out Pressure:EPA regulations governing mercury-containing equipment disposal accelerate obsolescence timelines for mercury vapor lamp systems, eliminating a traditional magnetic ballast application segment.
Strategic Opportunities
- Rural Commercial Underpenetration:Smaller municipalities and agricultural processing facilities in secondary US markets maintain extensive fluorescent infrastructure with limited electronic conversion capital, preserving serviceable demand pockets.
- Control Gear Integration:Convergence of magnetic ballast designs with basic occupancy sensing and daylight harvesting modules creates upgrade pathways for facilities seeking incremental efficiency gains without full system replacement.
- Export-Compliant Product Lines:REACH and RoHS-aligned insulation and coating chemistries open European distribution channels for US manufacturers willing to reformulate product specifications for hazardous substance restrictions.
Industry Challenges
- Specialized Winding Technician Scarcity:Precision copper wire winding for high-efficiency specifications requires skilled labor pools that have contracted as domestic electrical component manufacturing employment has declined.
- Legacy System Integration Complexity:Facilities managers face compatibility verification burdens when specifying replacement ballasts for decades-old fluorescent fixtures with non-standard mounting configurations and electrical characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Ballast Market |
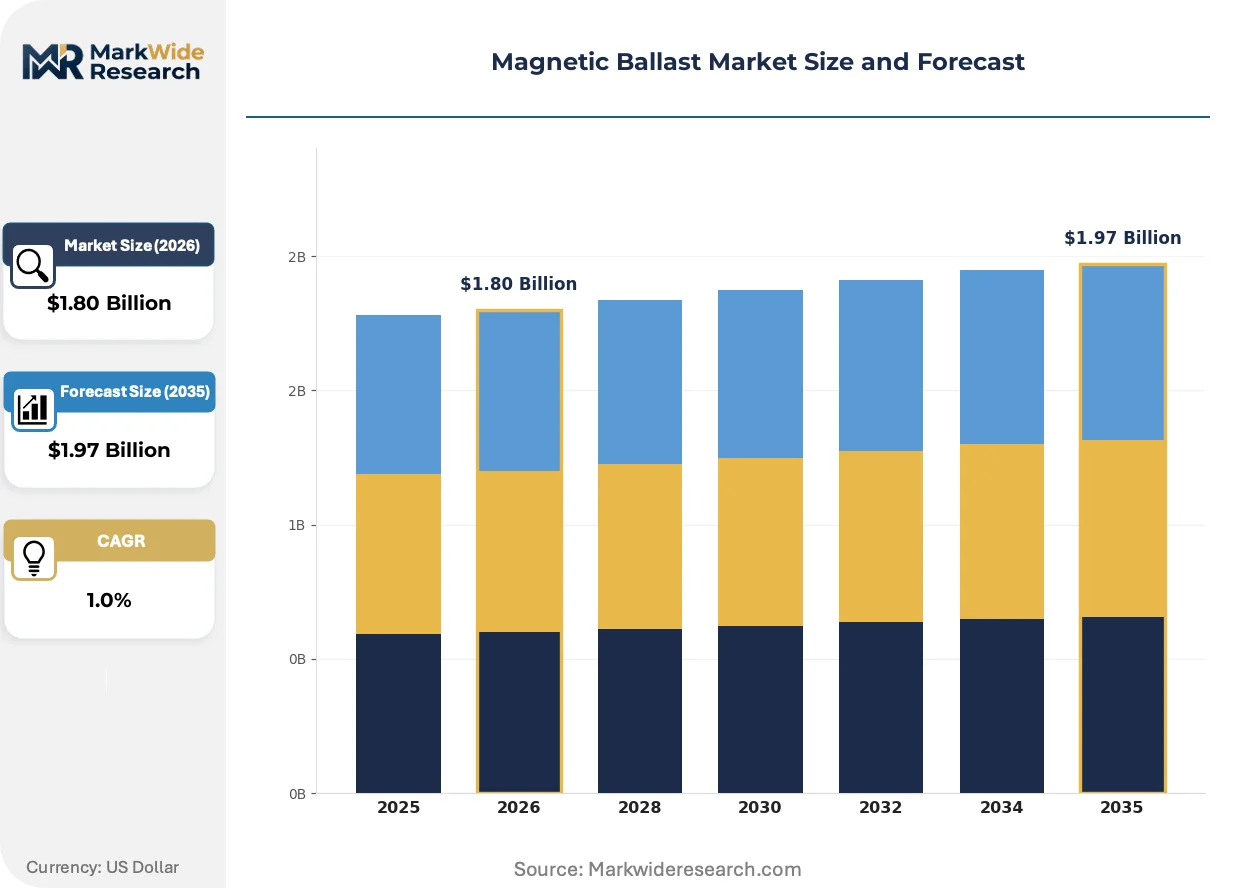
| Market Size in 2026 | $1.80 Billion |
| Market Size in 2035 | $1.97 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic, Ferroresonant, Auto Transformer, Capacitor-Starting, Reactance, Series Inductor Technology: Inductive, Capacitive, Magnetic Core, Copper Wire, Steel Lamination, Porcelain Insulation Application: Fluorescent Lighting, High-Intensity Discharge, Neon Lighting, Cold Cathode, Mercury Vapor, Metal Halide End User: Commercial Facilities, Educational Institutions, Manufacturing Plants, Government Buildings, Warehousing, Event Venues |
| Companies Covered | Signify, LEDVANCE, GE Lighting, Tridonic, Robertson, Helvar, Keystone Technologies, Universal Lighting Technologies, Industrias Sola Basic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Ballast Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are redefining magnetic ballast construction methodologies. Manufacturers navigate between performance optimization and hazardous substance compliance while serving a contracting but persistent installed base.
Amorphous metal core materials are displacing traditional grain-oriented silicon steel in premium magnetic ballast designs. Data centers and healthcare facilities with strict harmonic distortion requirements specify these cores for their superior magnetic properties and reduced core losses. The technology is displacing conventional laminated steel in applications where power quality justifies material cost premiums.
REACH restrictions on hazardous substances and RoHS directives limit certain insulation varnishes and potting compounds in export-bound products. European chemical regulations now prohibit specific brominated flame retardants and phthalate plasticizers previously standard in ballast construction. Manufacturers serving EU markets have reformulated encapsulation systems and thermal management materials to maintain market access eligibility.
Consolidated national distributor networks now dominate commercial lighting procurement, displacing the fragmented electrical wholesaler channel that historically served contractor and facility maintenance buyers. Independent reps and regional distributors lose share to WESCO, Graybar, and Rexel as buying power concentrates. This channel restructuring is most visible in large commercial retrofit projects across Texas, Florida, and California where national account pricing and integrated supply contracts predominate.
Magnetic Ballast Market Segmentation
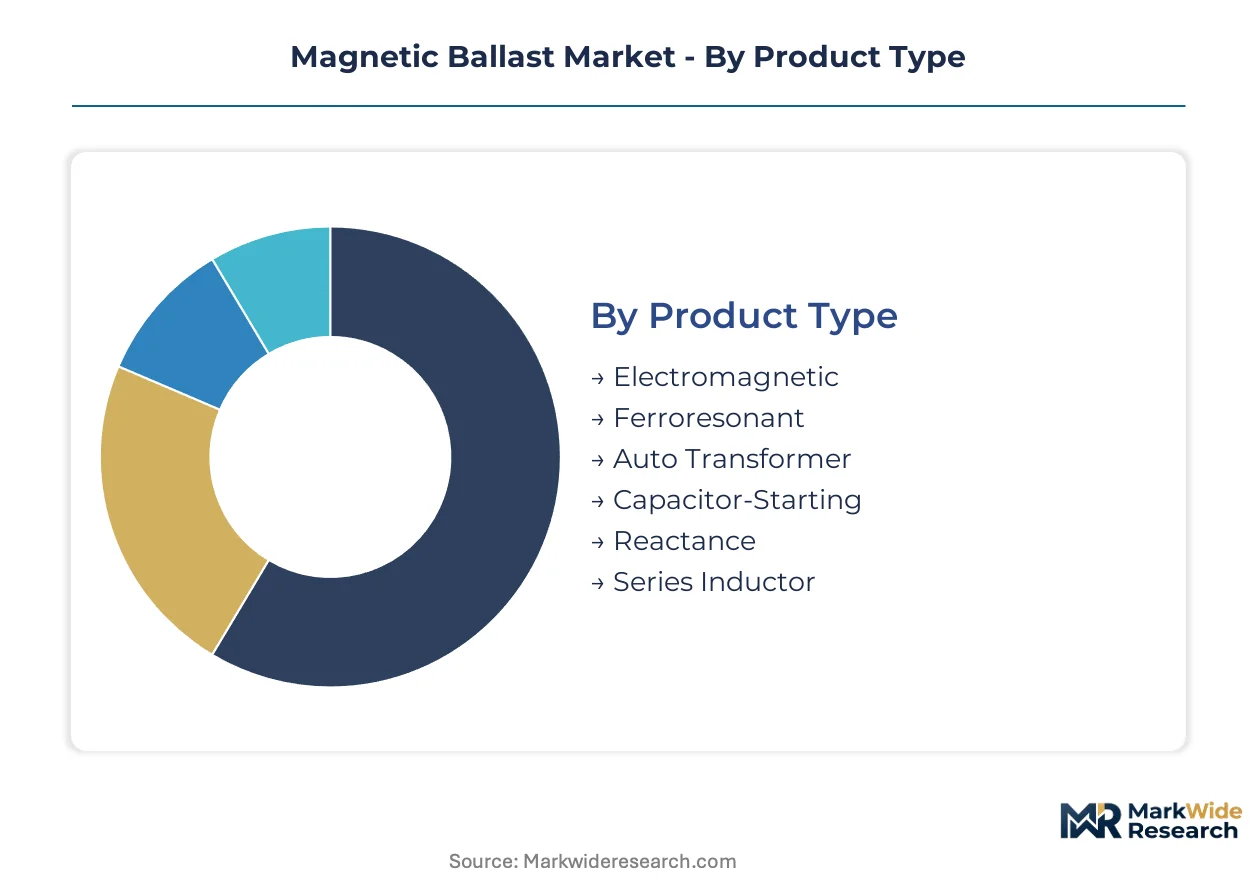
Magnetic ballast segmentation reveals how regulatory pressure and legacy infrastructure interact across product architectures. Each dimension carries distinct compliance burdens and replacement economics that shape procurement behavior in mature lighting markets.
Product Type:
EPA disposal rules and DOE efficiency standards create divergent compliance costs across electromagnetic, ferroresonant, and specialized transformer designs.
- Electromagnetic:Laminated silicon steel cores with copper windings constitute the dominant installed base. K-12 districts across Ohio and Michigan specify these units for fluorescent retrofits where fixture compatibility overrides efficiency gains from electronic alternatives. Federal efficiency mandates now require upgraded core grades, triggering replacement cycles in decades-old commercial installations.
- Ferroresonant:Saturating transformer designs deliver exceptional voltage regulation for mercury vapor and metal halide applications. Industrial facilities in Indiana maintain these systems for high-bay HID lighting where arc stability justifies higher copper and steel content. EPA mercury disposal regulations accelerate obsolescence timelines for this segment's traditional lamp pairings.
- Auto Transformer:Single-winding voltage step designs serve specialized neon and cold cathode installations.
- Capacitor-Starting:Auxiliary winding configurations assist lamp ignition in legacy fluorescent troffers.
- Reactance:Pure inductive impedance units occupy niche applications with minimal power factor correction requirements.
- Series Inductor:Simple two-terminal designs persist in lowest-cost replacement scenarios for obsolete fixture types.
Electromagnetic handles the majority of throughput; ferroresonant is the fastest mover on share.
Technology:
Material cost tiers separate premium specifications from commodity production, with copper wire and magnetic core grades commanding price premiums.
- Inductive:Electromagnetic impedance through wound coils remains the foundational operating principle. Grain-oriented silicon steel laminations with specified magnetic permeability dominate Midwestern industrial procurement for fluorescent and HID ballasts where line-frequency operation suffices.
- Capacitive:Power factor correction capacitors integrate with inductive cores to meet utility demand charge thresholds. Commercial retrofits across Texas and Florida specify these configurations to avoid reactive power penalties in large facilities with extensive lighting loads.
- Magnetic Core:Amorphous metal alloys displace traditional laminated steel in premium designs for data centers and healthcare facilities with strict harmonic distortion limits.
- Copper Wire:High-purity winding conductors differentiate efficiency grades under tightened DOE standards.
- Steel Lamination:Core material thickness and insulation coatings determine core loss performance.
- Porcelain Insulation:High-temperature terminal blocks serve industrial HID applications with elevated thermal stress.
Inductive technology anchors volume shipments; amorphous core magnetic specifications are expanding most quickly.
Application:
Mercury vapor phase-out pressure from EPA regulations fragments demand concentration across remaining gas-discharge technologies.
- Fluorescent Lighting:T8 and T12 lamp ballasts constitute the largest replacement volume. Educational institutions and government buildings across the Midwestern United States maintain extensive troffer infrastructure where magnetic ballasts offer plug-compatible retrofit economics against full LED conversions.
- High-Intensity Discharge:High-pressure sodium and metal halide systems in manufacturing plants and warehousing sustain procurement for robust electromagnetic designs. Ohio and Michigan industrial corridors specify these units for high-bay applications where lamp-ballast compatibility spans decades of fixture vintages.
- Neon Lighting:Cold cathode signage applications retain specialized transformer requirements.
- Cold Cathode:Compact fluorescent and specialty lamp formats use modified inductive designs.
- Mercury Vapor:EPA disposal regulations and efficiency mandates drive accelerated replacement with alternative HID technologies.
- Metal Halide:Ceramic arc tube systems specify ferroresonant and electromagnetic ballasts for sports and event venue lighting.
Fluorescent lighting carries the dominant replacement load; metal halide is gaining share fastest as mercury vapor retreats.
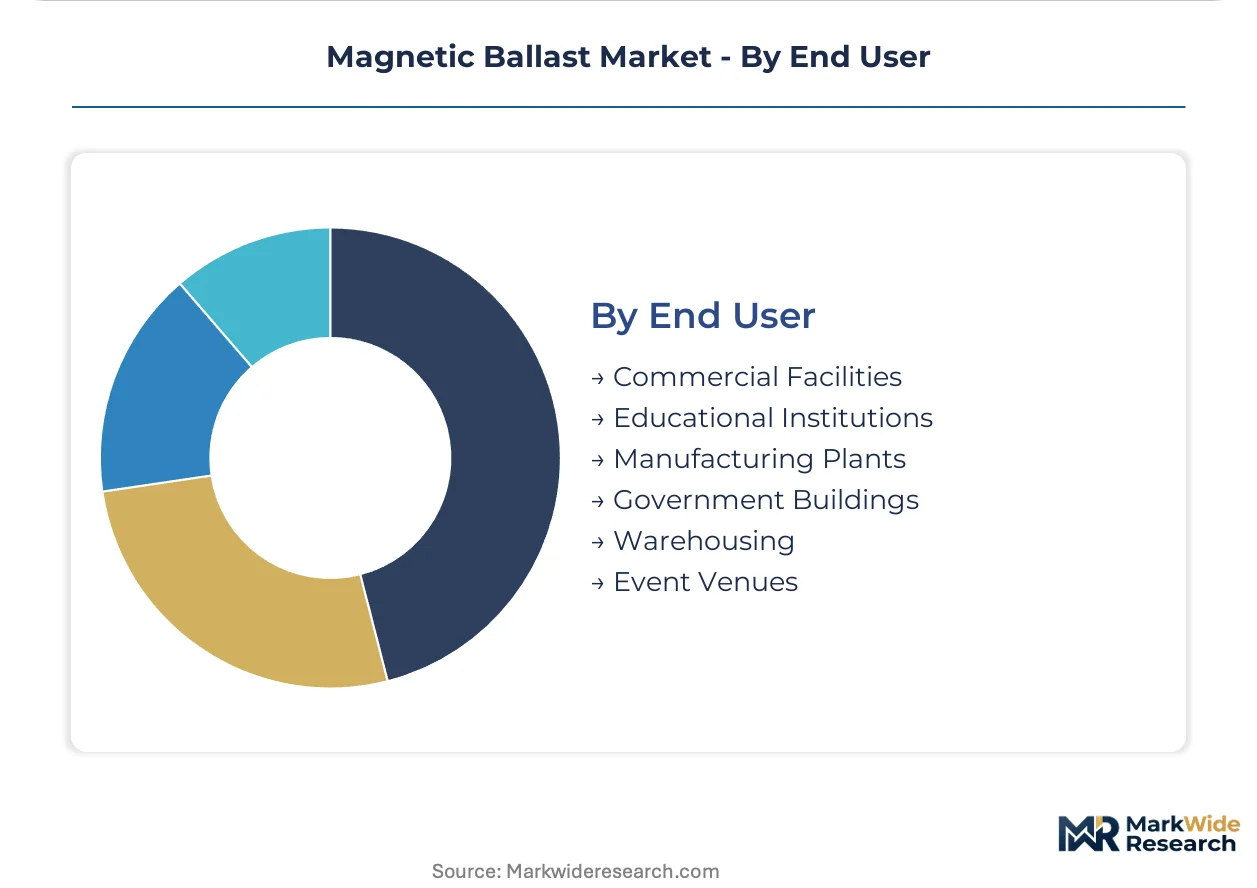
End User:
Facility ownership type determines capital allocation constraints and retrofit timing across replacement cycles.
- Commercial Facilities:Office buildings and retail centers balance operating cost reduction against tenant disruption. National distributor networks through WESCO and Graybar dominate procurement for multi-site retrofit programs where standardized specifications reduce maintenance complexity.
- Educational Institutions:K-12 districts and university systems prioritize electrical infrastructure modernization in aging facilities. Bond-funded capital programs across Indiana and Illinois sustain magnetic ballast procurement where fluorescent retrofits precede full LED system conversions.
- Manufacturing Plants:Industrial maintenance schedules in the Midwest preserve demand for HID ballast replacement.
- Government Buildings:Federal procurement guidelines and GSA schedules standardize efficiency requirements.
- Warehousing:High-bay fluorescent and sodium vapor installations in logistics facilities maintain electromagnetic ballast populations.
- Event Venues:Sports arenas and exhibition halls specify metal halide systems with specialized ferroresonant control gear.
Commercial facilities generate the highest procurement volume; educational institutions show the steepest expansion trajectory as modernization bonds deploy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Magnetic ballast manufacturing concentrates in industrial corridors with established electrical component ecosystems. Demand patterns diverge sharply between legacy infrastructure markets and jurisdictions with aggressive efficiency mandates.
United States
Midwestern industrial facilities in Ohio and Michigan sustain replacement demand for HID ballasts in high-bay applications. The US Department of Energy's appliance efficiency standards mandate upgraded core material grades for federal compliance. Educational institutions across Indiana and Illinois deploy bond-funded capital programs for fluorescent infrastructure modernization.
Germany
Industrial automation clusters in Bavaria and North Rhine-Westphalia maintain specialized transformer requirements for legacy manufacturing equipment. REACH restrictions on hazardous substances and RoHS directives limit insulation varnish formulations in export-bound products. Stuttgart-based electrical distributors serve Central European retrofit markets with reformulated ballast specifications.
China
Domestic infrastructure projects in the Yangtze River Delta preserve demand for cost-optimized electromagnetic designs in commercial construction. GB standards for lighting efficiency create compliance thresholds for local manufacturers. Shenzhen and Guangzhou export processing zones produce RoHS-aligned product lines for European distribution.
India
Educational infrastructure expansion in Maharashtra and Gujarat sustains procurement for fluorescent ballasts in institutional buildings. BIS certification requirements establish minimum efficiency thresholds for domestic market access. Tamil Nadu manufacturing corridors supply copper-wound inductive components to Southeast Asian retrofit markets.
Mexico
Maquiladora facilities in Nuevo León and the Bajío Region maintain legacy HID systems for industrial illumination. CEA electrical codes govern power factor requirements in commercial installations. Mexico City metropolitan area distributors channel replacement volumes for aging fluorescent infrastructure in government buildings.
Magnetic Ballast Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the magnetic ballast landscape. The vendor base spans vertically integrated lighting conglomerates, specialized control gear manufacturers, and regional scale producers. Three archetypes dominate: lamp-ballast pairing specialists leveraging backward integration into core materials; control gear integrators bundling sensing modules with electromagnetic designs; and distribution-scale fabricants competing on North American channel coverage. Consolidation pressure runs through M&A activity among electrical component portfolios and strategic partnerships between ballast producers and national distributor networks.
Among vertically integrated lighting groups, Signify and LEDVANCE occupy positions that exemplify lamp-ballast ecosystem control. Tridonic represents the control gear integration archetype, while Keystone Technologies anchors the manufacturing-scale competitive vector. These three players illustrate how competitive positioning stratifies between technology bundling, channel density, and captive supply chain economics.
| Leading Market Players |
|---|
| Signify |
| LEDVANCE |
| GE Lighting |
| Tridonic |
| Robertson |
| Helvar |
| Keystone Technologies |
| Universal Lighting Technologies |
| Industrias Sola Basic |
| Others |
Pricing and Supply Chain Analysis
Ninety-day raw material inventory cycles at laminated steel processors concentrate pricing leverage among integrated coil suppliers. DOE efficiency standards and copper commodity volatility feed directly into tiered cost structures that separate specification-grade from commodity replacement ballasts.
Pricing Analysis
The US Department of Energy's appliance efficiency standards dictates the pricing tier structure across magnetic ballast procurement. Three-tier pricing separates amorphous core premium specifications from standard grain-oriented silicon steel and economy-grade aluminum-wound alternatives. Price differentiation rests on core material certification grade and copper purity specifications under tightened winding standards. Cost compression in economy tiers is intensifying because aluminum substitution accelerates among price-sensitive educational procurement officers in Midwestern K-12 districts. Commercial facilities with GSA contract vehicles show lowest price sensitivity; rural agricultural processors exhibit highest sensitivity.
Supply Chain Analysis
China and India anchor electromagnetic core lamination and precision winding production for cost-optimized ballast lines. The supply chain draws from Australian silicon steel feedstock, Chilean copper cathode, and domestic US coil processing. Single-source vulnerability concentrates in grain-oriented electrical steel from a limited set of qualified mills. Distribution runs through consolidated national wholesaler networks with WESCO, Graybar, and Rexel controlling multi-site commercial retrofit procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ballast-lamp pairing ecosystems are shifting toward control-gear interoperability platforms that favor integrated suppliers over standalone component vendors. This platform economics inflection rewards vendors with captive sensing module development capabilities.
For Market Incumbents: Compound defensive positioning through backward integration into amorphous metal core supply and exclusive channel partnerships with national distributor networks. Electronic ballast substitution threatens replacement volume; secure long-term coil supply agreements with US steel mills to defend margin position against commodity volatility.
For New Entrants and Emerging Players: Differentiate on REACH-compliant insulation chemistry for European export qualification. Rural commercial underpenetration in secondary US agricultural markets offers lowest competitive density; target municipality maintenance contracts with reformulated RoHS-aligned product lines through regional electrical wholesaler relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a cash-extraction play because replacement demand concentrates in legacy infrastructure with declining new installation relevance. Acquisition candidates include specialized control gear integrators with sensing module capabilities. Monitor EPA mercury disposal enforcement intensity as phase-out acceleration signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Amorphous Core Material Integration | Captures premium specification demand from data centers with strict harmonic distortion limits. |
| REACH-Compliant Chemistry Reformulation | Opens European distribution channels previously closed to US manufacturers under RoHS restrictions. |
| National Distributor Network Partnership | Locks in multi-site commercial retrofit procurement through WESCO and Graybar integrated supply contracts. |
| Occupancy Sensing Module Bundling | Creates upgrade pathway for facilities seeking incremental efficiency without full LED conversion. |
| Copper Winding Technician Training Program | Addresses specialized labor scarcity constraining high-efficiency specification production capacity. |
Research Methodology
Desk research of trade customs data, electrical component SEC filings, and DOE regulatory dockets preceded structured interviews with ballast product managers, national distributor procurement directors, and facility maintenance engineers across Midwestern industrial corridors. Primary fieldwork with K-12 facilities directors and commercial lighting contractors validated replacement cycle assumptions. Secondary sources included copper and silicon steel commodity price indices, EPA mercury disposal enforcement records, and REACH regulatory amendment tracking. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Variance decomposition across product type, application technology, and end-user facility ownership shaped the analytical framework over the projection horizon. Modeled segmentation dimensions included electromagnetic versus ferroresonant architectures, fluorescent versus HID lamp pairings, and educational versus commercial versus industrial end-use categories. CAGRs were derived from replacement cycle timing, regulatory compliance deadline clustering, and commodity input cost trajectory assumptions. Core material efficiency grade adoption curves and distributor channel consolidation rates served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable DOE efficiency standard phase-in schedules and intact copper-steel price correlation assumptions; material deviation would warrant model refresh. Specific risks include accelerated mercury vapor phase-out enforcement, amorphous core material supply disruption, and distributor channel further consolidation. Recalibration cycles align with material shifts in federal appliance efficiency standard amendments and EPA hazardous waste disposal rulemakings.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Europe Electric Space Heaters Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Canada Electric Space Heater Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Bio-Based Transformer Oil Market
Electrical Power Equipment
Asia-Pacific Air-Insulated Switchgear Market
Electrical Power Equipment
Nuclear Cables Sales Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
Bucket Water Heater Market
Electrical Power Equipment
ESE Lightning Rod Market
Electrical Power Equipment
Alternating Current (AC) Electric Drives Market
Electrical Power Equipment
Unitary Heaters Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
Switching Residential Voltage Regulator Market