

Residential Air Insulated Power Distribution Component Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Air Insulated Power Distribution Component Market Insights
Utility-led microgrid developers and co-operative housing associations is redrawing procurement priorities for residential distribution infrastructure. ABB leverages its vacuum interruption portfolio to anchor premium contracts across European retrofit programs. Siemens sustains manufacturing scale advantages in electromechanical trip mechanisms for multi-unit dwellings. Schneider Electric differentiates through channel control in outdoor enclosure specifications for North American utilities.
Residential air insulated power distribution components rely on ambient air as the primary dielectric medium, with vacuum interruption technology achieving fault-current breaking capacities up to 50 kA in compact panelboard footprints. These systems isolate faults, meter consumption, and transform voltage levels for safe household delivery across single family homes through mixed-use buildings. Air circuit breakers dominate replacement cycles in aging indoor panelboards across European housing stocks, while metering equipment captures margin pools from smart-grid integration mandates. Distribution transformers face accelerating demand in underground vault installations within dense Asian apartment complexes.
The IEC 62271-100 standard shapes product certification requirements for vacuum interruption performance, while the EU F-Gas Regulation accelerates air-insulated alternatives to SF6-dependent equipment. The EPA and NHTSA influence U.S. supplier compliance through embodied energy disclosures and electrical safety frameworks for residential infrastructure. Stakeholders must monitor regulatory divergence between European eco-design mandates and emerging Asian efficiency labeling schemes when allocating R&D budgets across regional product platforms.
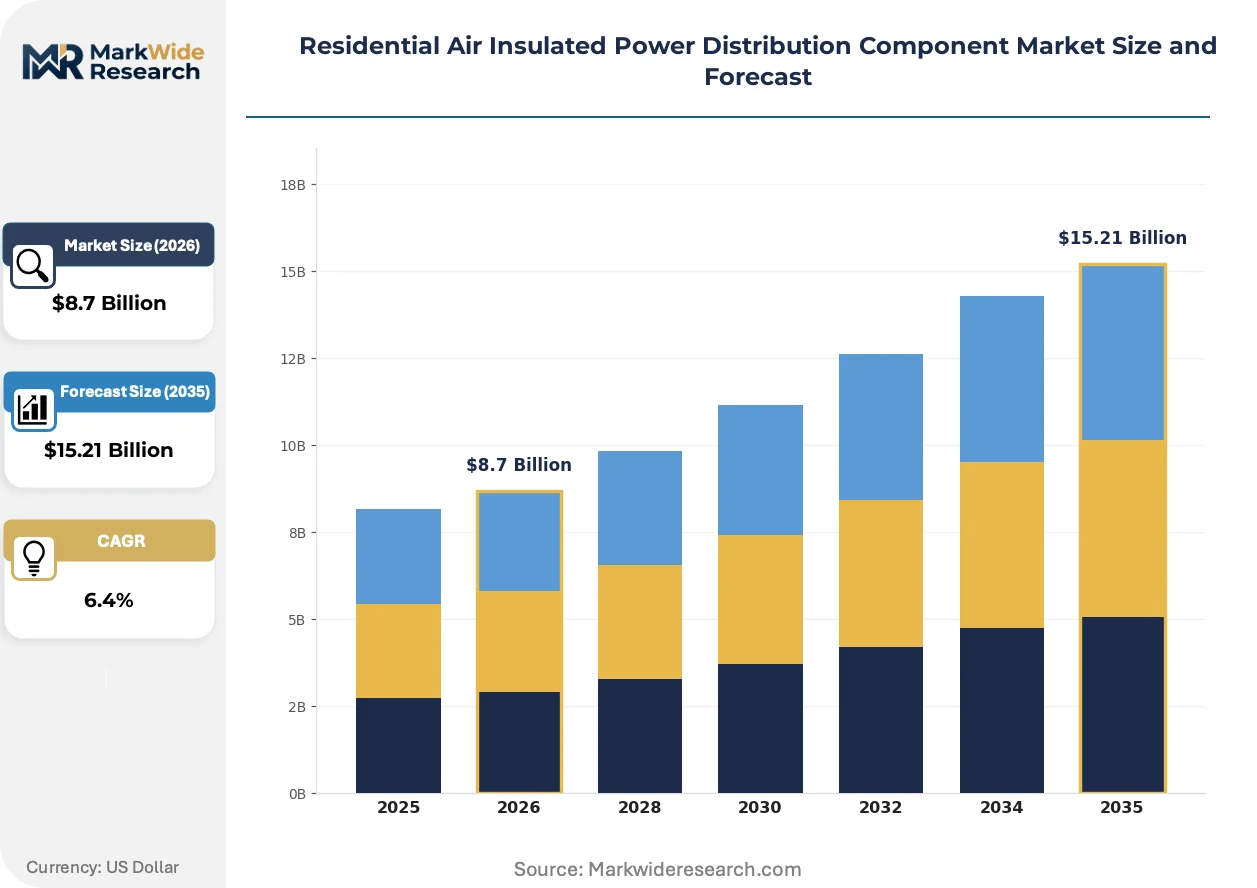
Market Dynamics
Vacuum interruption technology is compressing physical footprints while IEC 62271-100 certification requirements are elevating supplier qualification barriers across residential substation procurement.
Growth Catalysts
- Suburban electrification corridors:India, Germany, and the United States are accelerating air-insulated switchgear deployment in greenfield residential developments to serve expanding housing stocks.
- F-Gas Regulation displacement:The EU F-Gas Regulation is mandating SF6-free alternatives, redirecting utility capital toward air-insulated vacuum interruption systems for residential infrastructure.
- Smart-grid integration mandates:Metering equipment with embedded communication modules is capturing procurement priority as utilities modernize distribution networks for bidirectional power flows.
Market Restraints
- Copper and electrical steel volatility:Raw material price swings in transformer core laminations and conductor windings are compressing margin predictability for panelboard manufacturers.
- Testing facility concentration:IEC 62271-100 certification capacity clusters in Western European laboratories, creating bottlenecks for Asian suppliers seeking qualification.
- SF6 legacy asset inertia:Existing gas-insulated installations in European housing stocks face extended replacement cycles due to capital recovery timelines.
Strategic Opportunities
- Underground vault transformer demand:Dense Asian apartment complexes in Seoul, Tokyo, and Singapore are driving specification for compact, liquid-immersed distribution units with air-insulated terminations.
- Digital twin integration:Convergence of vacuum interruption hardware with IoT-enabled condition monitoring is opening predictive maintenance revenue streams for switchgear OEMs.
- Co-operative housing procurement aggregation:Bundled purchasing by German and Dutch housing associations is creating direct-to-installer channel bypass opportunities.
Industry Challenges
- Vacuum interrupter engineering scarcity:Specialized metallurgical expertise for contact material design remains concentrated among a limited pool of European and Japanese specialists.
- Legacy panelboard integration complexity:Retrofit installations in aging European housing stocks require custom mechanical adaptation kits, extending project timelines.
- Multi-standard certification burden:Suppliers serving both IEC and ANSI jurisdictions face duplicated type-testing costs for equivalent performance ratings.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Air Insulated Power Distribution Component Market Trends and Innovations
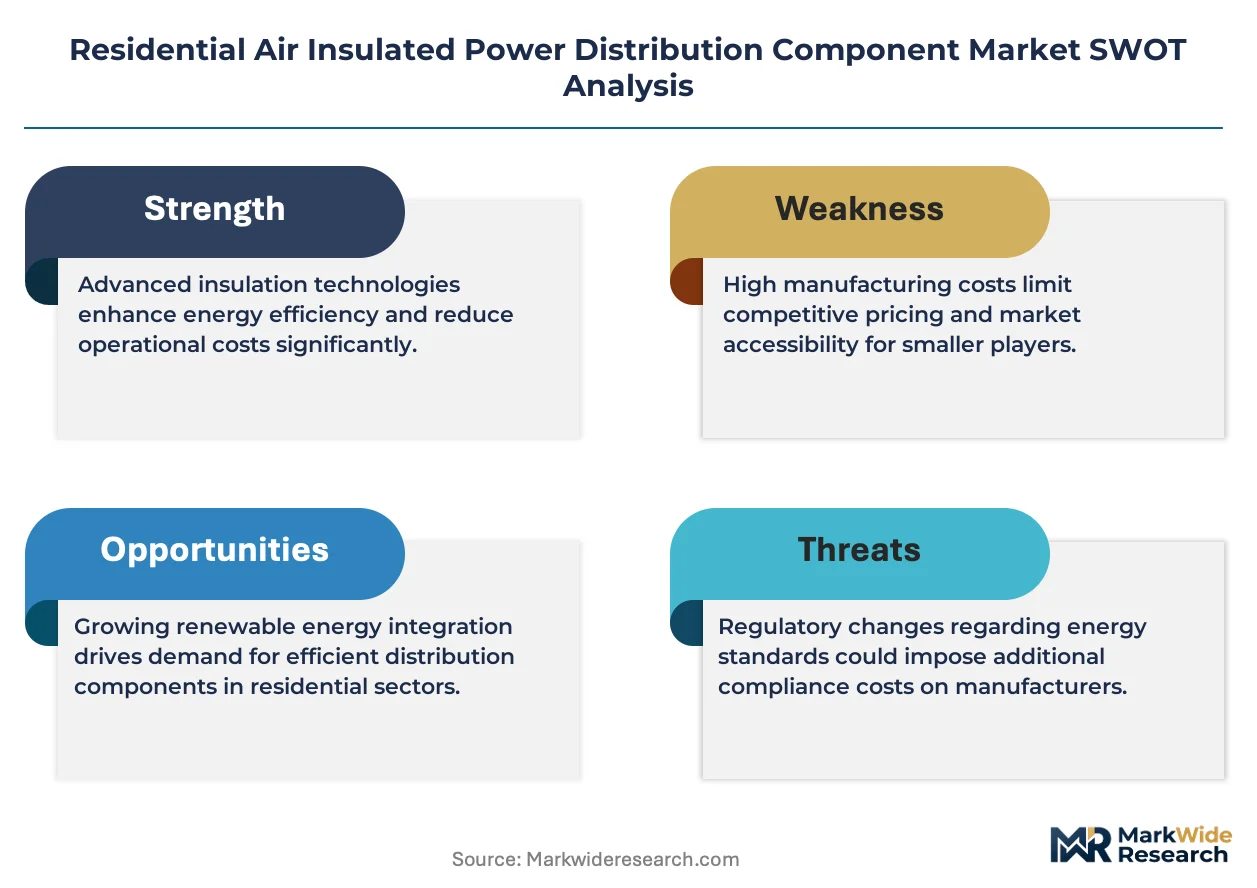
Three forces are restructuring residential distribution component supply: physical miniaturization of interruption technology, regulatory phase-out of fluorinated gases, and procurement consolidation by housing associations.
Vacuum interrupter assemblies are miniaturizing fault-current breaking capacity into panelboard footprints previously occupied by air-magnetic breakers. German and Austrian utilities are specifying these compact units for basement electrical rooms in multi-family dwellings. The technology is miniaturizing spatial requirements, enabling transformer-substation integration in dense urban sites.
The EU F-Gas Regulation is accelerating equipment replacement timelines by restricting SF6 maintenance and new installation. Air-insulated alternatives are capturing specification share in French and Italian utility tenders previously dominated by gas-insulated switchgear. Residential substation designers are responding with vacuum interruption architectures that eliminate sealed-pressure system dependencies.
Co-operative housing associations are consolidating procurement through framework agreements that bypass traditional electrical distributor channels. German Genossenschafts and Dutch woningcorporaties are negotiating direct supply relationships with switchgear manufacturers for standardized panelboard configurations. This concentration is most visible in North Rhine-Westphalia and Randstad urban regions.
Residential Air Insulated Power Distribution Component Market Segmentation
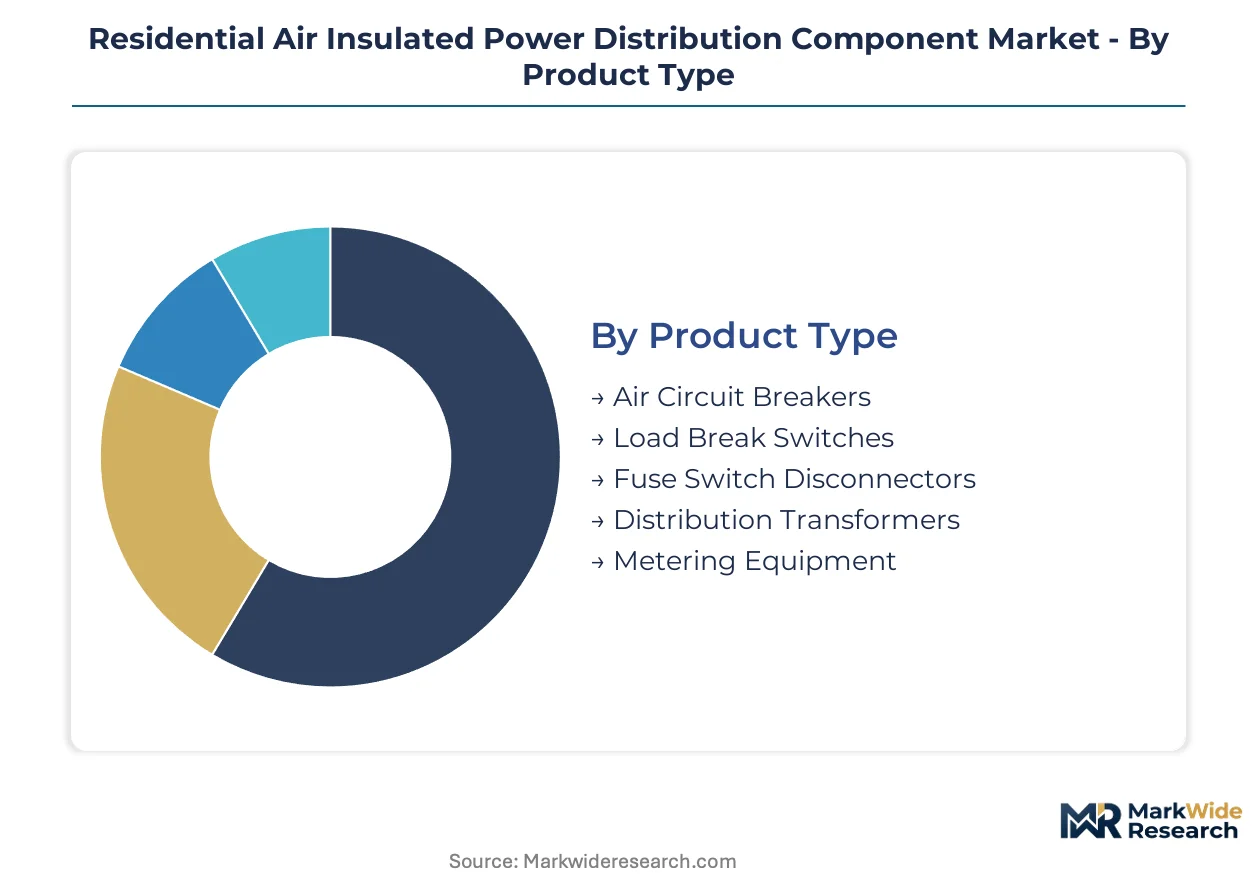
Margin pools in residential power distribution concentrate where fault-interruption performance intersects with regulatory compliance. Segment boundaries shift as IEC 62271-100 certification requirements reshape supplier qualification tiers across product categories.
Product Type:
Margin concentration follows replacement cycles in aging infrastructure and smart-grid integration mandates.
- Air Circuit Breakers:These units employ vacuum interruption technology to achieve fault-current breaking capacities up to 50 kA within compact panelboard footprints. Demand clusters in German and Austrian basement electrical rooms for multi-family dwellings, driven by F-Gas Regulation displacement of SF6-dependent alternatives.
- Distribution Transformers:Liquid-immersed units with air-insulated terminations serve underground vault installations in dense Asian apartment complexes. Seoul, Tokyo, and Singapore developers specify compact designs as urban land constraints intensify.
- Load Break Switches:These devices isolate circuits under normal load conditions in European retrofit programs.
- Fuse Switch Disconnectors:Simple overcurrent protection dominates cost-sensitive single-family installations in India.
- Metering Equipment:Embedded communication modules capture priority from utility modernization mandates for bidirectional power flows.
The dominant share belongs to Air Circuit Breakers, while Metering Equipment is gaining share fastest.
Technology:
Cost tier differentiation separates premium vacuum interruption from legacy electromechanical alternatives.
- Vacuum Interruption:Contact material design requires specialized metallurgical expertise concentrated among European and Japanese specialists. IEC 62271-100 testing protocols elevate supplier qualification barriers, compressing the qualified vendor pool.
- Electromechanical:Trip mechanisms sustain manufacturing scale advantages for multi-unit dwelling applications. Siemens leverages this technology for standardized panelboard configurations serving co-operative housing associations.
- Magnetic Latching:Low-power switching suits smart-grid communication integration in North American utilities.
- Thermal-magnetic:Cost-effective protection dominates replacement cycles in aging European housing stocks.
- Electronic Trip:Precise fault discrimination enables selective coordination in complex mixed-use buildings.
Premium positioning concentrates with Vacuum Interruption, though Electronic Trip is expanding most quickly in high-rise specifications.
Application:
Volume distribution tracks suburban electrification corridors across India, Germany, and the United States.
- Apartment Complexes:Dense Asian developments in Seoul and Singapore drive specification for compact transformer-substation integration. Underground vault installations maximize land efficiency in vertical residential construction.
- Single Family Homes:Greenfield suburban expansion in the United States and India accelerates air-insulated switchgear deployment for expanding housing stocks. Standardized panelboard configurations reduce installation complexity.
- Condominiums:Individual metering requirements multiply equipment counts per development.
- Townhouses:Shared infrastructure spreads capital costs across multiple units.
- Mixed-use Buildings:Diverse load profiles demand flexible protection coordination.
Apartment Complexes command the largest volume position, while Single Family Homes is climbing the fastest among application types.
Installation Environment:
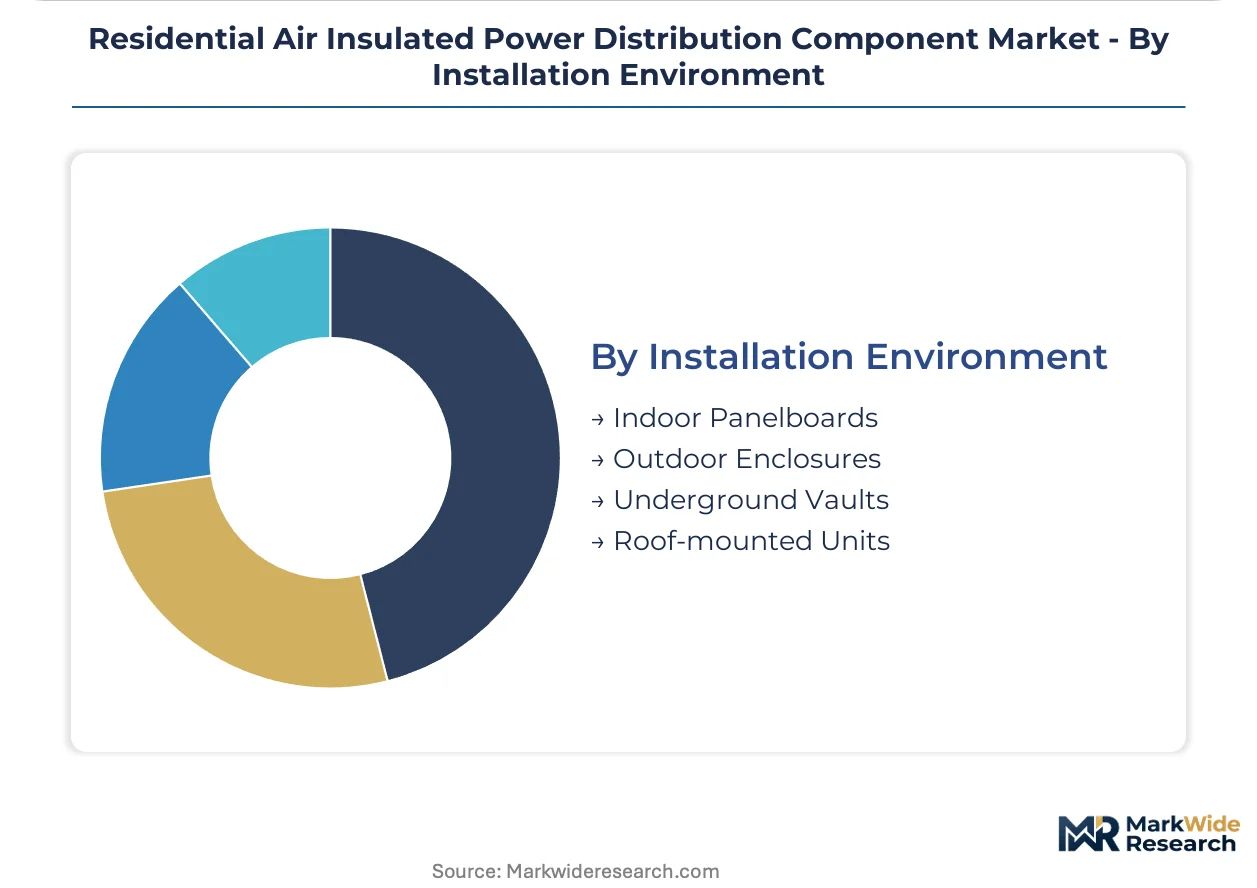
Supply concentration reflects regional building codes and climate exposure requirements.
- Indoor Panelboards:Air-magnetic breaker replacement cycles dominate aging European housing stocks. Custom mechanical adaptation kits extend project timelines for retrofit installations.
- Underground Vaults:Asian urban density necessitates compact liquid-immersed units with air-insulated terminations. Seoul and Tokyo developers prioritize space-efficient transformer designs.
- Outdoor Enclosures:North American utilities specify weather-resistant housings for suburban distribution.
- Roof-mounted Units:Limited deployment concentrates in flood-prone coastal regions.
Indoor Panelboards retains the dominant installation share, though Underground Vaults is showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The German-Dutch grid interconnect underwrites European procurement flows for vacuum interruption technology. India's Green Energy Corridors program is accelerating suburban electrification across expansion corridors. Japan's metropolitan power density drives specification for compact transformer-substation integration.
United States
Suburban greenfield developments in Texas and Florida are deploying air-insulated switchgear for expanding housing stocks. The EPA influences supplier compliance through embodied energy disclosure requirements for residential infrastructure. North Carolina's Research Triangle utilities specify outdoor enclosure configurations for suburban distribution networks.
Germany
F-Gas Regulation mandates are redirecting utility capital toward SF6-free vacuum interruption systems in multi-family dwellings. The EU Green Deal accelerates retrofit programs across aging European housing stocks. North Rhine-Westphalia's Genossenschafts consolidate procurement through direct framework agreements with switchgear manufacturers.
India
Green Energy Corridors infrastructure is electrifying suburban expansion corridors across Maharashtra and Karnataka. CEA technical standards govern distribution component specifications for residential substations. Mumbai and Bangalore developers specify standardized panelboard configurations for dense apartment complex construction.
Japan
Metropolitan land constraints in Tokyo and Osaka drive demand for compact transformer designs with air-insulated terminations. METI efficiency labeling schemes shape product certification requirements for residential distribution equipment. Yokohama's underground vault installations maximize space efficiency in vertical residential construction.
Singapore
Urban density mandates specify liquid-immersed distribution units for underground residential infrastructure. The country's national electrical safety regulator enforces stringent testing protocols for fault-current interruption performance. The Greater Southern Waterfront development integrates vacuum interruption technology into basement electrical room specifications.
Residential Air Insulated Power Distribution Component Market Competitive Landscape
Concentration sits with diversified electrical equipment conglomerates holding IEC 62271-100 certification capacity. The qualified vendor pool compresses around vacuum interrupter metallurgical expertise concentrated among European and Japanese specialists. Three archetypes dominate: integrated industrial conglomerates with manufacturing scale advantages, specialized switchgear fabricators with regional channel control, and utility-captive suppliers with direct procurement relationships. Competitive moves center on backward integration into contact material supply and strategic partnerships with co-operative housing associations.
Among diversified industrial conglomerates, ABB, Siemens, and Schneider Electric exemplify the certification-heavy tier where vacuum interruption portfolios anchor premium positioning. These entities occupy positions shaped by testing facility access and channel relationships with utility-led microgrid developers. Their geographic footprints reflect historical manufacturing concentrations in European and North American industrial basins.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| Schneider Electric |
| Eaton |
| General Electric |
| Hitachi Energy |
| Mitsubishi Electric |
| Larsen & Toubro |
| Lucy Group |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four week lead times for IEC 62271-100 certified vacuum interrupters concentrate pricing power among European and Japanese metallurgical specialists, while copper and electrical steel inventory cycles amplify margin volatility for panelboard manufacturers serving co-operative housing associations.
Pricing Analysis
Volume-discount tiering structures separate premium vacuum interruption systems from standard electromechanical alternatives and economy-grade thermal-magnetic units. Pricing stratifies across IEC 62271-100 certification grade, raw material volume commitments, and bundled after-sales service agreements. Cost compression in economy tiers is intensifying because Indian and Southeast Asian suppliers are scaling electromechanical production for single-family housing markets. Co-operative housing associations in Germany and the Netherlands exhibit lowest price sensitivity due to framework agreement consolidation, while independent electrical contractors in India's suburban corridors demonstrate highest sensitivity to per-unit panelboard costs.
Supply Chain Analysis
Inventory cycles for copper rod and grain-oriented electrical steel extend beyond twelve weeks, exposing transformer manufacturers to commodity price volatility between order placement and delivery. Manufacturing concentrates in Germany, China, and India, with vacuum interrupter metallurgy anchored in Japanese and Austrian specialist facilities. Supply chains draw from Chilean copper cathode, Ukrainian electrical steel, and rare-earth contact materials sourced through Chinese processing nodes. Single-source vulnerability sits with IEC 62271-100 testing capacity clustered in Western European laboratories. Distribution runs through utility-approved electrical distributors and direct framework agreements with co-operative housing associations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The residential air insulated power distribution component market is entering a cyclical recovery phase as F-Gas Regulation mandates across Europe force accelerated replacement of SF6-dependent infrastructure, creating sustained demand visibility for vacuum interruption suppliers.
For Market Incumbents: Consolidate backward integration into copper and electrical steel supply through long-term offtake agreements with Chilean and Ukrainian producers, insulating margin stability from raw material volatility. Acquire IEC 62271-100 testing capacity or secure exclusive partnerships with Western European certification laboratories to lock out Asian competitors facing qualification bottlenecks. For New Entrants and Emerging Players: Lead with digital twin-enabled condition monitoring bundles targeting North American utility microgrid developers seeking predictive maintenance capabilities for suburban distribution networks. Penetrate India's Green Energy Corridors through localized panelboard assembly partnerships with Maharashtra and Karnataka electrical contractors, bypassing established distributor channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core electrical equipment divisions lacking vacuum interruption certification portfolios. Long-term viability favors suppliers with captive contact material metallurgy and direct co-operative housing association relationships. Watch for inflection when IEC 62271-100 testing capacity expansion announcements surface from Asian laboratory investments.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62271-100 Certification Investment | Qualification barriers compress the vendor pool for European utility tenders. |
| Backward Integration into Copper Supply | Long-term Chilean offtake agreements stabilize transformer core lamination costs. |
| Digital Twin Platform Development | IoT-enabled condition monitoring opens predictive maintenance revenue at North American utilities. |
| Direct Framework Agreements | Bypassing distributors with German Genossenschafts improves margin capture and demand visibility. |
| Compact Transformer-Substation Integration | Underground vault specifications in Seoul and Tokyo maximize land efficiency premiums. |
Research Methodology
A spread of perspectives from utility procurement officers, co-operative housing association technical directors, switchgear OEM product managers, and IEC testing laboratory engineers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against CEA technical standards documentation, EU F-Gas Regulation implementation reports, METI efficiency labeling schemes, and customs trade data for copper and electrical steel flows. Bottom-up segment sizing triangulated against top-down macroeconomic drivers across the analysis window.
Segmentation dimensions modeled include product type, interruption technology, application environment, and installation configuration across suburban electrification corridors. CAGRs were derived from regression analysis of historical replacement cycles, regulatory mandate timelines, and housing stock expansion projections. Industry-specific forecast inputs incorporated F-Gas Regulation phase-out schedules and Green Energy Corridors infrastructure deployment patterns.
Forecasts assume regulatory continuity in EU F-Gas Regulation, Indian CEA standards, and Japanese METI labeling schemes; material policy shifts would require re-modeling of replacement cycle assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.