
 Busway-Bus Duct Market | 2026-2036
Busway-Bus Duct Market Size, Share, and Industry Trends Forecast 2026-2036
Busway-Bus Duct Market Analysis
The EU Green Deal's building efficiency mandates is shifting procurement criteria toward low-loss busway systems across European commercial construction. Eaton leverages its integrated electrical portfolio to dominate specification-driven projects in North American industrial corridors. Siemens anchors its position through IEC-certified modular designs that serve German automotive manufacturing complexes. Godrej and Boyce specializes in tropicalized plug-in busway variants for Indian infrastructure builds.
Busway and bus duct systems are enclosed power distribution assemblies that route electrical current through aluminum or copper conductors within grounded metal housings, typically rated from 800 to 5000 amperes for commercial and industrial applications. Their primary purpose replaces conventional cable and conduit runs with compact, ventilated pathways that simplify load reconfiguration and reduce installation footprint in space-constrained facilities. Concentrated busway occupies the mature high-current segment where margin pools depend on engineering services and custom tap configurations. Plug-in busway leads commercial building adoption because facility managers prioritize flexible load relocation without shutdowns. Data centers represent the fastest-growing application as hyperscale operators replace traditional PDUs with overhead busway to improve cooling aisle geometry and support liquid-cooled rack densities.
NFPA 70 National Electrical Code in the United States and IEC 61439-6 in Europe govern busway short-circuit withstand ratings, temperature rise limits, and enclosure integrity standards that manufacturers must certify before market access. China's GB 7251 series and India's BIS IS 8623 impose additional regional testing protocols for tropical humidity and pollution degree environments. Stakeholders must monitor evolving efficiency benchmarks from multiple jurisdictions to align product roadmaps with divergent certification timelines.
Market Dynamics
Data center rack densities exceeding 50kW per cabinet are forcing hyperscale operators to abandon traditional PDUs in favor of overhead busway architectures that preserve cooling aisle geometry and enable liquid-cooled server deployments.
Growth Catalysts
- EU Green Deal efficiency mandates:Building performance standards across European commercial construction are accelerating procurement of low-loss busway systems with copper-aluminum hybrid conductor designs.
- Utility-scale manufacturing parks in India:Industrial corridor developments require modular power distribution infrastructure that plug-in busway configurations deliver with minimal shutdown windows during facility reconfiguration.
- IEC 61439-6 certification harmonization:Standardized short-circuit withstand testing is reducing technical barriers for manufacturers seeking cross-border market access within European industrial zones.
Market Restraints
- Copper price volatility:Raw material cost swings compress margin pools for manufacturers locked into fixed-price engineering contracts for concentrated high-current installations.
- Regional certification fragmentation:Divergent testing protocols between China's GB 7251 series and India's BIS IS 8623 impose redundant compliance costs on multinational product portfolios.
- Busbar substitution in low-current segments:Cable management systems with integrated power distribution are capturing sub-800 ampere applications where installation flexibility outweighs busway density advantages.
Strategic Opportunities
- Tropicalized plug-in variants for Southeast Asian infrastructure:Humidity-resistant enclosure designs certified to pollution degree 3 environments address underserved commercial construction markets in Vietnam and Indonesia.
- Integration with digital twin platforms:Busway systems embedding IoT current monitoring and thermal sensors are enabling predictive maintenance contracts that extend manufacturer revenue streams beyond equipment sales.
- US Inflation Reduction Act manufacturing incentives:Domestic content requirements for federal facility upgrades are creating procurement preference windows for North American-assembled bus duct systems.
Industry Challenges
- Shortage of medium-voltage power distribution engineers:Specialized design expertise for 5kV-class busway tap configurations limits project execution capacity for EPC firms bidding hyperscale data center contracts.
- Legacy conduit infrastructure retrofit complexity:Facility managers face extended shutdown windows when replacing aging cable-and-conduit runs with busway in operational industrial plants.
- IEC versus NFPA 70 thermal rise standard misalignment:Temperature limit discrepancies between European and North American codes force manufacturers to maintain dual product variants for transatlantic projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Busway-Bus Duct Market |
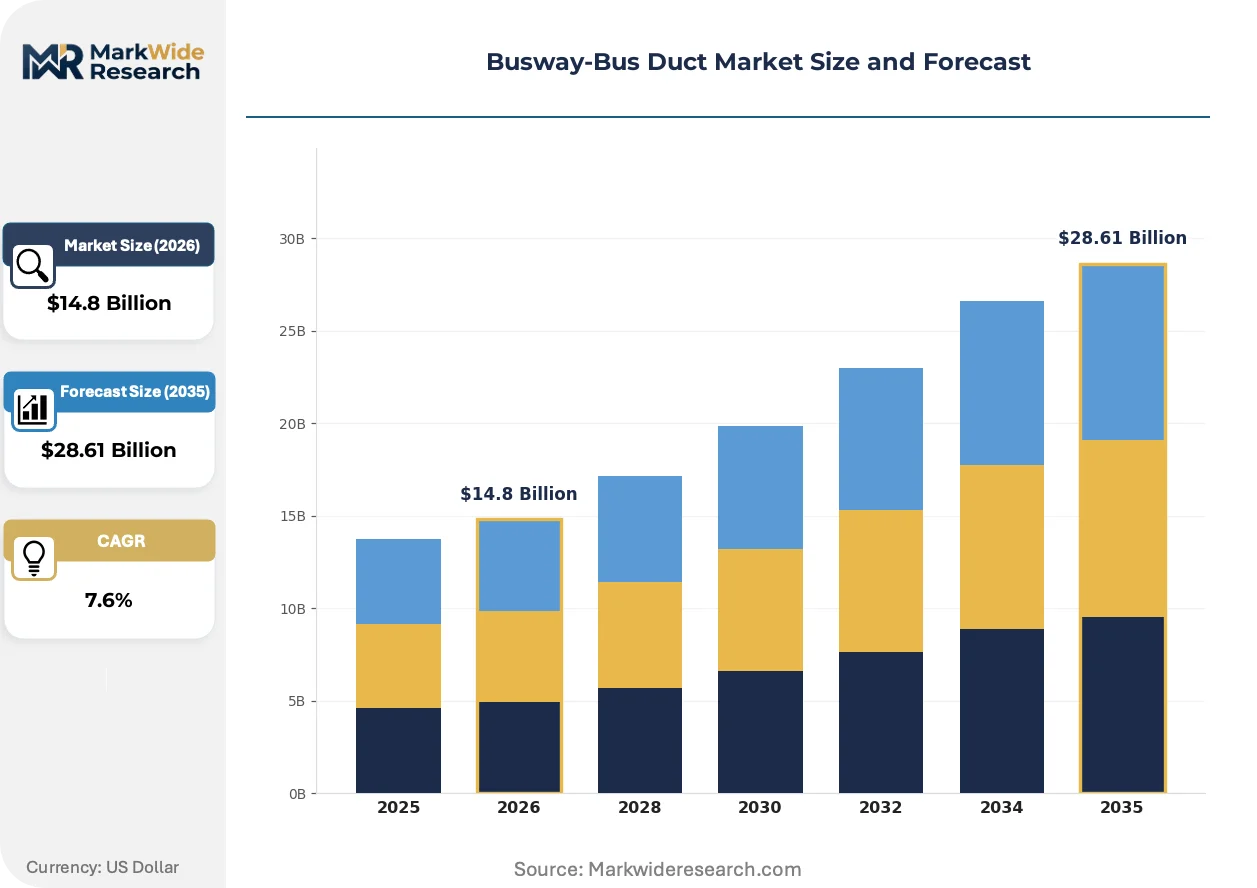
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Busway, Plug-In Busway, Modular Busway, Transportable Busway Application: Industrial Facilities, Commercial Buildings, Renewable Energy, Data Centers End User: Manufacturers, Contractors, Facility Managers, Utility Companies Installation Type: Indoor Installation, Outdoor Installation, Ceiling-Mounted, Wall-Mounted |
| Companies Covered | Eaton, Furukawa Electric, Siemens, Godrej and Boyce, Powell Industries, ABB, LS Cable and System, DBTS, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Busway-Bus Duct Market Emerging Trajectories
Busway architectures are converging with digital infrastructure layers, transforming power distribution from passive hardware into active grid-edge assets that enable real-time load optimization and predictive thermal management.
Copper-aluminum hybrid conductor technology is unifying cost efficiency with thermal performance in high-current commercial installations. Data center operators in Frankfurt and Singapore are specifying these composite designs for 3000-5000 ampere main runs where pure copper strains capital budgets. The technology is unifying procurement criteria across price-sensitive and performance-critical buyer segments that previously required separate product lines.
REACH substance restrictions on halogenated flame retardants are compelling enclosure manufacturers to reformulate insulating materials for European market access. Industrial consequences include extended material qualification timelines and higher compound costs for low-smoke zero-halogen alternatives. German automotive manufacturing complexes, bound by both REACH and facility insurance requirements, are driving specification adoption ahead of regulatory deadlines.
Facility managers are consolidating vendor relationships around integrated electrical infrastructure providers capable of delivering switchgear, busway, and digital monitoring through single-source contracts. Traditional busway specialists lacking panelboard or transformer portfolios are losing specification influence to full-line suppliers. This consolidation pattern is most visible in North American industrial corridor developments where EPC firms prioritize procurement simplicity over component-level optimization.
Busway-Bus Duct Market Segmentation
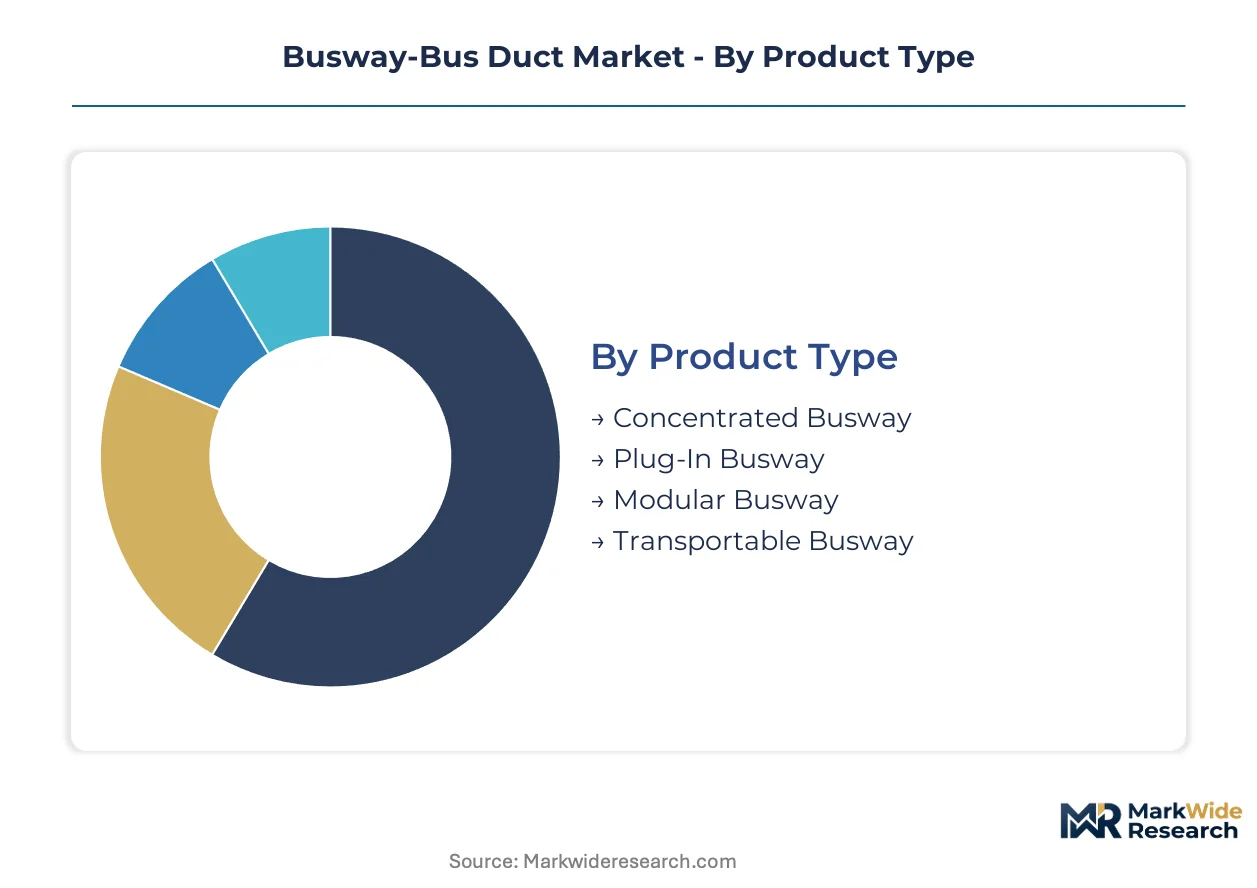
Busway-Bus Duct Market segmentation reveals distinct capital requirements across product architectures, with concentrated high-current systems demanding heavy engineering investment while plug-in variants prioritize inventory flexibility. Application-based splits expose divergent procurement cycles, from data center hyperscale tenders to industrial retrofit projects.
Product Type:
Concentrated busway systems require the heaviest upfront capital commitment due to custom tap engineering and site-specific structural calculations, while transportable variants minimize fixed asset exposure through standardized skid-mounted designs.
- Concentrated Busway:Engineered for 3000-5000 ampere main distribution runs with welded aluminum or copper conductors and bespoke tap box configurations. Demand concentrates in German automotive manufacturing complexes where continuous high-current reliability overrides capital intensity.
- Plug-In Busway:Modular tap-off designs enable live circuit reconfiguration without shutdowns, driving adoption across Indian utility-scale manufacturing parks requiring frequent production line rebalancing. IEC 61439-6 certification harmonization is reducing cross-border procurement friction for these systems.
- Modular Busway:Pre-fabricated sections with standardized joint connections reduce field installation labor for commercial building contractors in Southeast Asian humidity zones.
- Transportable Busway:Skid-mounted configurations serve temporary power needs at construction sites and event infrastructure where permanent installation is uneconomical.
Most installed capacity flows through concentrated busway in heavy industrial corridors. Expansion is steepest in plug-in variants serving modular facility architectures.
Application:
Volume concentration varies sharply by project scale, with data center deployments representing single-site megawatt procurement while commercial buildings fragment across numerous sub-1000 ampere installations.
- Industrial Facilities:Steel mills, petrochemical plants, and automotive assembly lines specify concentrated busway for motor control centers and heavy machinery feeds. Indian industrial corridor developments under the PLI scheme are accelerating procurement of tropicalized enclosure designs.
- Data Centers:Hyperscale operators in Frankfurt and Singapore are replacing traditional PDUs with overhead busway to preserve cooling aisle geometry and enable liquid-cooled rack densities exceeding 50kW per cabinet. This application is expanding most quickly across the analysis window.
- Commercial Buildings:Office towers and retail complexes favor plug-in busway for tenant improvement flexibility where load relocation occurs without electrical shutdowns.
- Renewable Energy:Solar and wind farm substations employ outdoor-rated bus duct for collector system aggregation where environmental sealing exceeds standard commercial specifications.
Industrial facilities retain the largest installed base. Data center applications are climbing the fastest as rack power densities force architectural reconsideration.
End User:
Procurement authority splits between capital-project owners and operational facility managers, with contractors serving as specification gatekeepers in design-build delivery models.
- Manufacturers:Industrial facility owners with in-house engineering teams specify concentrated busway for greenfield plant construction where lifecycle cost analysis favors capital-intensive distribution infrastructure.
- Facility Managers:Operational teams in existing commercial buildings prioritize plug-in busway for tenant reconfiguration agility and minimized shutdown windows during space rebalancing.
- Contractors:EPC firms consolidate vendor relationships around integrated electrical infrastructure providers capable of delivering switchgear, busway, and digital monitoring through single-source contracts.
- Utility Companies:Grid interconnection projects specify outdoor-rated bus duct for substation expansion where environmental sealing and pollution degree ratings exceed commercial building standards.
Contractors channel the majority of new specification decisions. Facility managers are gaining procurement influence fastest as operational expenditure frameworks displace capital-project silos.
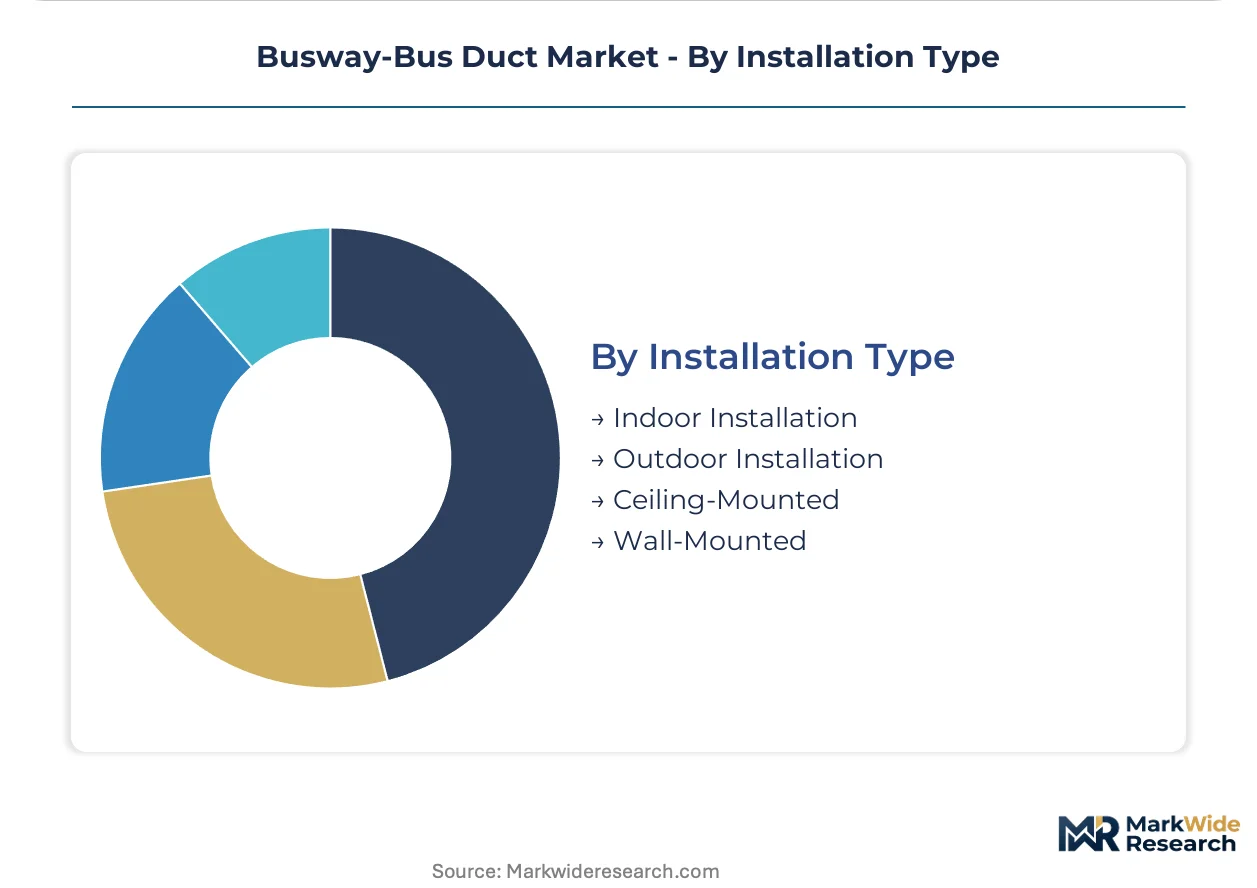
Installation Type:
Mounting configuration determines enclosure integrity requirements and labor specialization, with outdoor and ceiling-mounted variants commanding premium engineering margins over standard wall-mounted commercial installations.
- Indoor Installation:Climate-controlled environments allow standard IP54 enclosures with ventilation slots for thermal management in commercial building risers and industrial plant motor control centers.
- Outdoor Installation:IP65+ sealed housings with gasketed joints and corrosion-resistant coatings serve solar farm substations and petrochemical exposed environments where pollution degree 3 ratings are mandatory.
- Ceiling-Mounted:Overhead suspension systems preserve floor space in data center white rooms and clean manufacturing environments where aisle geometry directly impacts cooling efficiency.
- Wall-Mounted:Surface or recessed attachment simplifies retrofit installation in existing buildings where structural ceiling loading cannot support suspended distribution.
Indoor configurations dominate current installed capacity. Ceiling-mounted systems are gaining share fastest as data center operators optimize white room spatial economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized power distribution engineers concentrate in industrial corridors where data center and automotive investments are reshaping infrastructure procurement. Their expertise anchors regional competitive positioning as facilities demand higher-current busway configurations.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives overhead busway adoption for liquid-cooled rack densities. The Inflation Reduction Act's domestic content requirements create procurement preference windows for federal facility upgrades. Ashburn's data center cluster represents the densest concentration of 50kW-plus cabinet installations in North America.
Germany
Automotive manufacturing complexes in Bavaria and Baden-Württemberg specify concentrated busway for continuous high-current reliability. REACH substance restrictions on halogenated flame retardants compel enclosure material reformulation ahead of regulatory deadlines. Stuttgart's electric vehicle battery plants are accelerating copper-aluminum hybrid conductor procurement.
India
Utility-scale manufacturing parks under the PLI scheme require modular power distribution with minimal shutdown windows during reconfiguration. BIS IS 8623 testing protocols impose regional certification requirements distinct from IEC standards. Tamil Nadu's industrial corridor developments are driving tropicalized plug-in busway specification.
China
GB 7251 series standards govern short-circuit withstand ratings and temperature rise limits for commercial and industrial installations. Dual carbon goals are accelerating efficiency mandates in manufacturing facility construction. Yangtze River Delta data center clusters are adopting overhead busway architectures to optimize cooling aisle geometry.
Singapore
Tropical humidity and pollution degree 3 environments demand specialized enclosure designs for data center reliability. IEC 61439-6 certification harmonization reduces technical barriers for cross-border procurement. The city-state's hyperscale facilities are specifying composite conductor designs to balance capital budgets with thermal performance.
Busway-Bus Duct Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the busway market structure. Integrated electrical infrastructure providers dominate specification-driven projects through single-source contract capabilities. Three archetypes anchor competitive positioning: full-line suppliers with switchgear portfolios, specialized busway manufacturers with custom engineering expertise, and regional fabricators serving localized certification requirements. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms address engineer shortages and divergent thermal standards.
Among diversified industrial conglomerates, Siemens and ABB exemplify the integrated infrastructure archetype with broad electrical portfolios spanning switchgear through digital monitoring. Godrej and Boyce occupies a position within the regional specialization tier, with its corporate structure suggesting India-based manufacturing focus. These anchors illustrate how competitive positioning stratifies between specification influence through breadth versus targeted expertise in tropicalized or high-current configurations.
| Leading Market Players |
|---|
| Eaton |
| Furukawa Electric |
| Siemens |
| Godrej and Boyce |
| Powell Industries |
| ABB |
| LS Cable and System |
| DBTS |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
EU Green Deal efficiency mandates are shifting procurement criteria toward low-loss busway systems with copper-aluminum hybrid designs, forcing manufacturers to absorb higher material qualification costs while engineering services bundling preserves margin pools in concentrated high-current segments.
Pricing Analysis
Bundled engineering services versus unbundled equipment-only sales define the dominant pricing split across the market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with IEC 61439-6 and NFPA 70 compliance tiers commanding substantial premiums over regional-standard alternatives. Cost compression in standard-grade plug-in busway is intensifying because cable management systems are capturing sub-800 ampere applications. Facility managers in commercial buildings exhibit the highest price sensitivity, while data center operators prioritize thermal performance over capital outlay.
Supply Chain Analysis
Medium-voltage power distribution engineer shortages in Germany and India are constraining tap configuration capacity for 5kV-class installations. Manufacturing concentration centers on China, India, and Germany, with raw material supply drawing from Chilean copper cathode, Indonesian aluminum smelters, and specialty steel from Japanese mills. Single-source vulnerability around certified enclosure gaskets creates exposure to REACH substance restriction timelines. Distribution runs through EPC contractor consortia and integrated electrical infrastructure providers rather than component-level distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Busway-Bus Duct Market functions as a stable compounder anchored by data center infrastructure buildouts that sustain replacement cycles and specification upgrades across decade-long facility lifecycles.
For Market Incumbents: Lock in specification influence by deepening backward integration into copper-aluminum hybrid conductor casting and securing captive supply of low-smoke zero-halogen enclosure compounds ahead of REACH deadlines. Expand certification engineering teams in India to address BIS IS 8623 compliance bottlenecks that constrain project execution capacity. Cable management substitution in low-current segments threatens volume retention; counter with integrated digital monitoring bundles that extend revenue streams beyond hardware sales. For New Entrants and Emerging Players: Launch via tropicalized plug-in busway specialization for Vietnamese and Indonesian commercial construction markets where pollution degree 3 certification requirements exceed local manufacturing capability. Target data center ceiling-mounted installations in secondary markets where incumbent full-line suppliers prioritize hyperscale contracts. Partner with regional EPC firms lacking in-house electrical infrastructure design capacity to bypass specification gatekeeper barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized busway engineering firms possessing IEC-NFPA dual certification capabilities that serve transatlantic industrial corridor projects. Long-term viability rests on recurring revenue from predictive maintenance contracts enabled by IoT-embedded thermal monitoring rather than cyclical equipment replacement cycles. Watch for copper price volatility spikes as inflection indicators that compress margin pools and accelerate consolidation toward integrated infrastructure providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hybrid Conductor Casting | Captive copper-aluminum production secures margin control against LME price swings. |
| Dual Certification Investment (IEC 61439-6 + NFPA 70) | Unified product platforms reduce inventory duplication for transatlantic EPC contracts. |
| Predictive Maintenance Service Launch | IoT thermal monitoring contracts extend manufacturer revenue beyond equipment sales cycles. |
| Tropicalized Enclosure Development | Pollution degree 3 designs unlock Vietnamese and Indonesian commercial construction procurement. |
| Digital Twin Platform Integration | Real-time load optimization capabilities differentiate offerings in data center specification battles. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary research incorporated interviews with data center facility engineers, EPC contractor procurement leads, industrial plant maintenance directors, and busway manufacturer product managers. Secondary sources included IEC certification databases, NFPA code revision filings, BIS IS 8623 test protocols, and customs trade records for copper and aluminum conductor shipments. Bottom-up project pipeline analysis triangulated against top-down infrastructure investment forecasts.
Granularity-level modeling addressed product type, application, installation configuration, and end-user procurement authority across the projection horizon. Segmentation dimensions included concentrated versus plug-in versus modular busway architectures, data center versus industrial versus commercial building applications, and indoor versus outdoor versus ceiling-mounted installations. CAGRs were derived from weighted capacity expansion announcements and facility retrofit cycle analysis. Forecast inputs incorporated hyperscale data center power density trajectories and EU Green Deal implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price volatility extremes and divergent regional certification harmonization delays. Forecasts reflect documented assumptions regarding rack density adoption curves and efficiency mandate enforcement intensity. Material deviation in data center construction permitting velocity or REACH substance restriction acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Magnet Bearings Market
Electrical Power Equipment
Electric Substation Market
Electrical Power Equipment
Utility Equipment Market
Electrical Power Equipment
Smart Electric Heater Market
Electrical Power Equipment
Carbon Brush Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Frameless Brushless DC Motors Market
Electrical Power Equipment
HV Bushing Market
Electrical Power Equipment
Electrodialysis System Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
AV Power Conditioners Market
Electrical Power Equipment
Transformer Oil Testers Market
Electrical Power Equipment
High Voltage Ionising Air Gun Market
Electrical Power Equipment
Alternator Regulator Market
Electrical Power Equipment
Power Line Filters Market
Electrical Power Equipment
HVDC Converter Station Market