
 North America Air-Insulated Switchgear Market | 2026-2036
North America Air-Insulated Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
North America Air-Insulated Switchgear Market Insights
Modular switchgear configurations is realigning buyer choice across utility and industrial procurement channels. Eaton Corporation leverages its integrated power management portfolio to anchor large-scale infrastructure bids. Hitachi Energy Ltd specializes in digital monitoring overlays that differentiate its outdoor-rated assemblies. ABB Ltd dominates medium voltage retrofit channels through extensive North American service networks.
Air-insulated switchgear employs ambient air as the primary dielectric medium between live conductors and grounded enclosures, typically rated for voltages from 1 kV through 52 kV with busbar capacities up to 4000 A and short-circuit withstand ratings to 50 kA. These assemblies protect electrical distribution networks by isolating fault currents and enabling safe maintenance access in substations, industrial plants, and commercial facilities. Medium voltage switchgear leads installed value due to pervasive utility distribution deployment, while modular switchgear represents the fastest-expanding configuration category as site-constrained projects favor factory-integrated, skid-mounted delivery. Compact switchgear occupies premium margin pools in urban indoor applications where real estate costs and arc-flash containment requirements intensify.
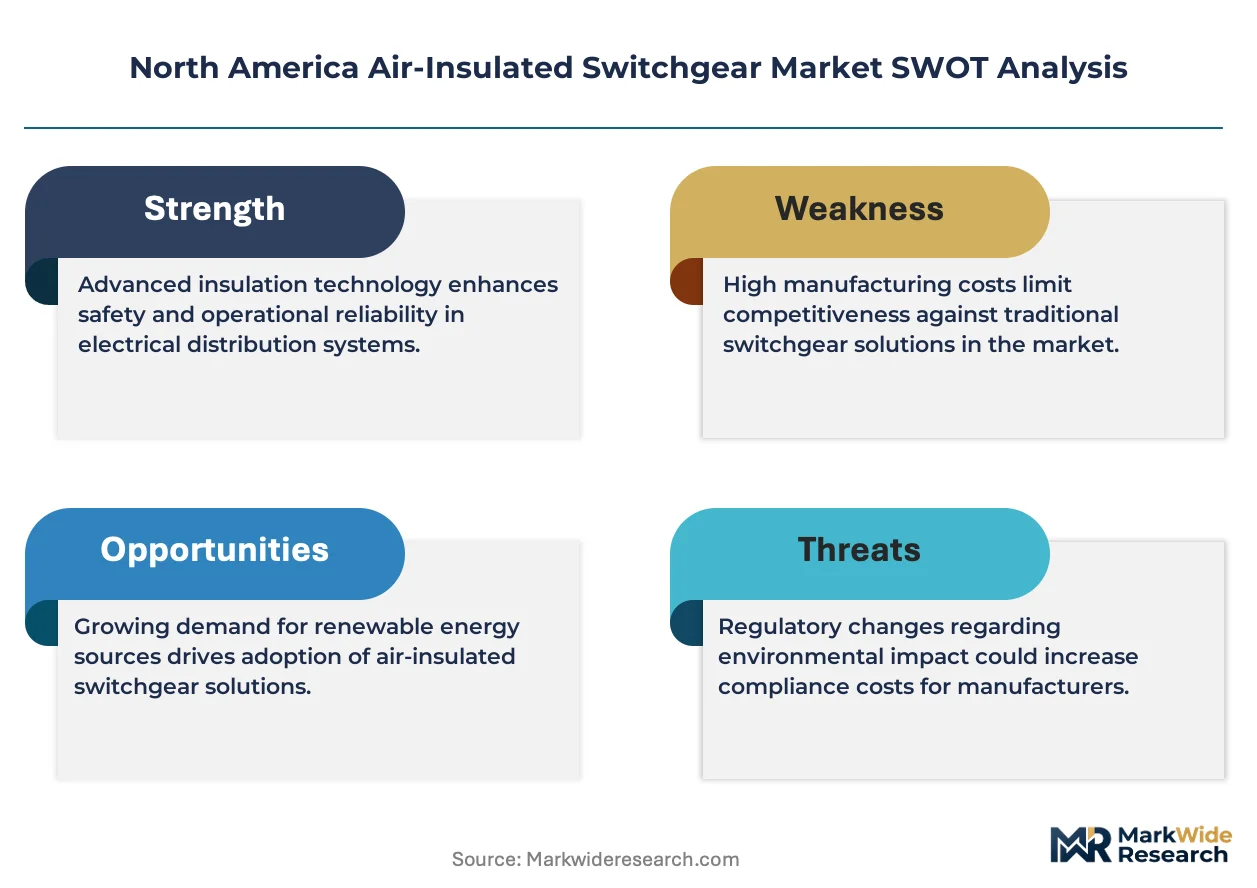
NERC reliability standards, IEEE C37 series design guidelines, and CSA C22.2 Canadian electrical codes collectively govern equipment qualification, seismic withstand, and arc-resistance testing across the North American footprint. These frameworks elevate engineering documentation burdens and third-party witness test requirements, effectively filtering out suppliers lacking accredited laboratory access or established field service presence. Stakeholders must monitor evolving EPA scrutiny of SF6 emissions from competing gas-insulated alternatives, as regulatory pressure on fluorinated gases could accelerate substitution toward air-insulated and hybrid vacuum-air technologies in utility specifications.
Market Dynamics
Utility-scale renewable interconnection across Texas, California, and PJM Interconnection states is forcing a procurement surge in outdoor-rated medium voltage assemblies, compressing delivery timelines and elevating arc-flash performance specifications under NERC reliability standards.
Growth Catalysts
- NERC reliability standards:Tightening arc-flash and seismic performance requirements for new substation installations are mandating equipment upgrades across utility distribution networks.
- Data center load growth:Hyperscale facility construction in Virginia, Texas, and Arizona is driving demand for robust medium voltage switchgear assemblies with high short-circuit withstand ratings.
- Grid modernization programs:State-level infrastructure investments are accelerating replacement cycles for aging air-insulated switchgear in urban substations and industrial corridors.
Market Restraints
- Copper and aluminum price volatility:Raw material cost swings for conductive busbar components compress manufacturer margins and complicate long-term project bidding.
- Accredited laboratory access concentration:Seismic and arc-resistance testing capabilities cluster with established North American service providers, filtering out smaller competitors lacking third-party witness test relationships.
- SF6 gas-insulated switchgear substitution threat:Competing gas-insulated technologies with smaller footprints threaten air-insulated solutions in space-constrained urban applications despite EPA fluorinated gas scrutiny.
Strategic Opportunities
- Modular factory-integrated delivery:Site-constrained renewable and data center projects favor skid-mounted switchgear configurations that reduce on-site assembly labor and commissioning time.
- Canadian provincial grid investments:Ontario and Alberta transmission expansion programs under CSA C22.2 codes create procurement channels for outdoor-rated medium voltage assemblies.
- Digital monitoring overlay convergence:Integration of sensor networks with air-insulated switchgear enables predictive maintenance contracts and remote diagnostics for utility asset managers.
Industry Challenges
- Arc-flash engineering expertise scarcity:Specialized protection coordination and incident energy calculation skills command premium compensation, constraining project staffing for EPC contractors.
- IEEE C37 series certification timelines:Extended third-party witness testing and documentation burdens delay product qualification for new market entrants lacking established laboratory partnerships.
- Legacy electromechanical relay integration:Retrofit projects face compatibility complications when merging modern microprocessor-based protection with existing substation control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Air-Insulated Switchgear Market |
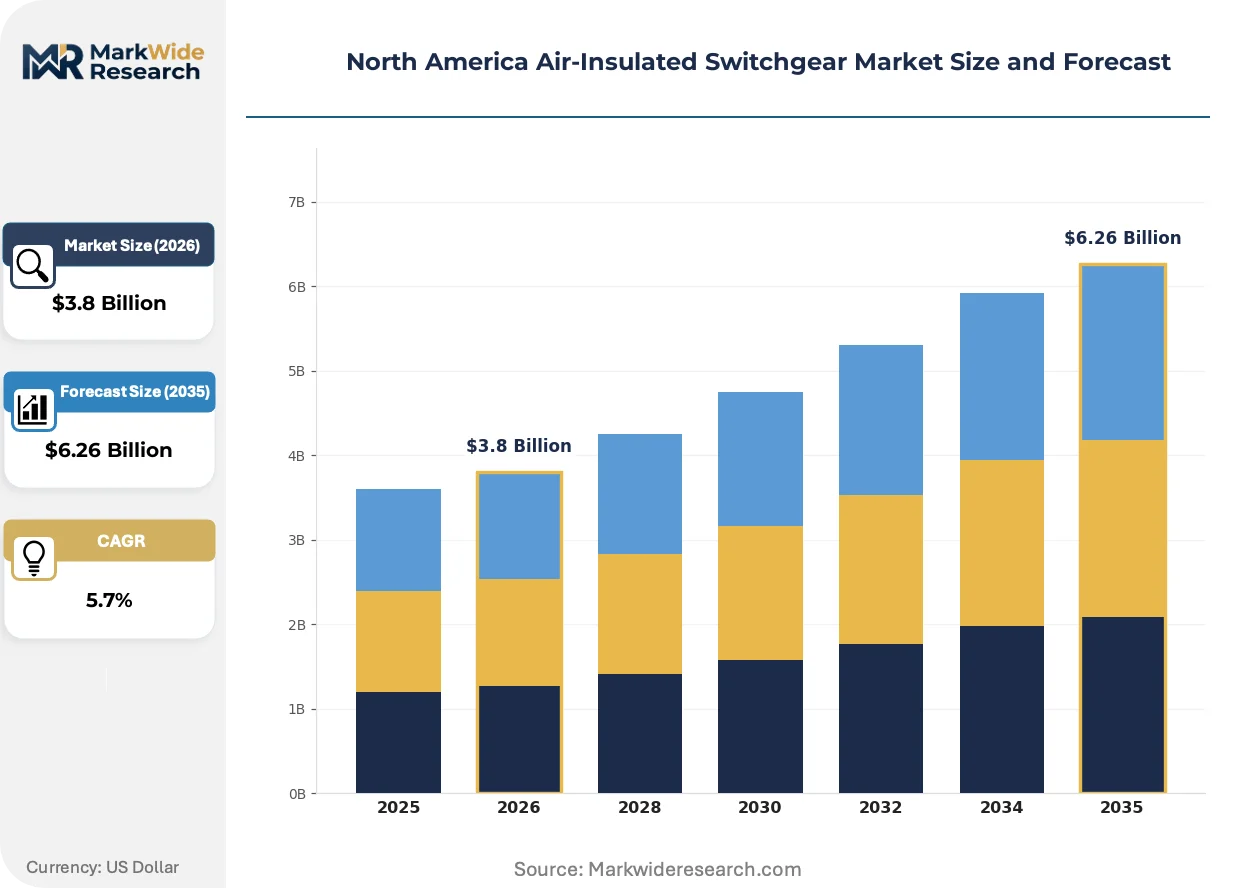
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Voltage, High Voltage, Compact Switchgear, Modular Switchgear End User: Industrial, Commercial, Utility, Renewable Energy Installation: Indoor, Outdoor, Retrofit, New Construction Technology: Vacuum Insulation, Air Insulation, SF6 Technology, Hybrid Solutions |
| Companies Covered | Eaton Corporation, Hitachi Energy Ltd, ABB Ltd, Hubbell Incorporated, Mitsubishi Electric Corporation, Siemens AG, General Electric Company, Powell Industries Inc, Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Air-Insulated Switchgear Market Trends and Innovations
Factory-integrated delivery models and digital sensor overlays are compressing project timelines while elevating performance verification standards across utility and industrial procurement channels.
Vacuum interrupter technology is modularizing medium voltage switchgear architectures by enabling compact, maintenance-free fault current interruption without oil or gas insulation. Renewable interconnection projects in Texas and California are specifying these assemblies for rapid deployment. The technology is modularizing procurement patterns by allowing utilities to order pre-tested, skid-mounted sections that slash on-site commissioning from weeks to days.
EPA scrutiny of SF6 emissions from gas-insulated alternatives is tightening under the agency's greenhouse gas reporting mandates and state-level fluorinated gas regulations. Industrial consequence includes specification shifts toward air-insulated and hybrid vacuum-air technologies in utility RFPs. Medium voltage retrofit channels across PJM Interconnection states are most affected, with asset managers now requiring SF6-free alternatives in environmental impact assessments.
Integrated power management procurement is consolidating vendor relationships as buyers seek single-source accountability for switchgear, protection relays, and energy monitoring. Industrial facilities and data center operators are displacing fragmented multi-vendor sourcing with bundled infrastructure packages. This consolidation is most visible in California and Virginia markets where EPC contractors face liquidated damages clauses for schedule overruns.
North America Air-Insulated Switchgear Market Segmentation
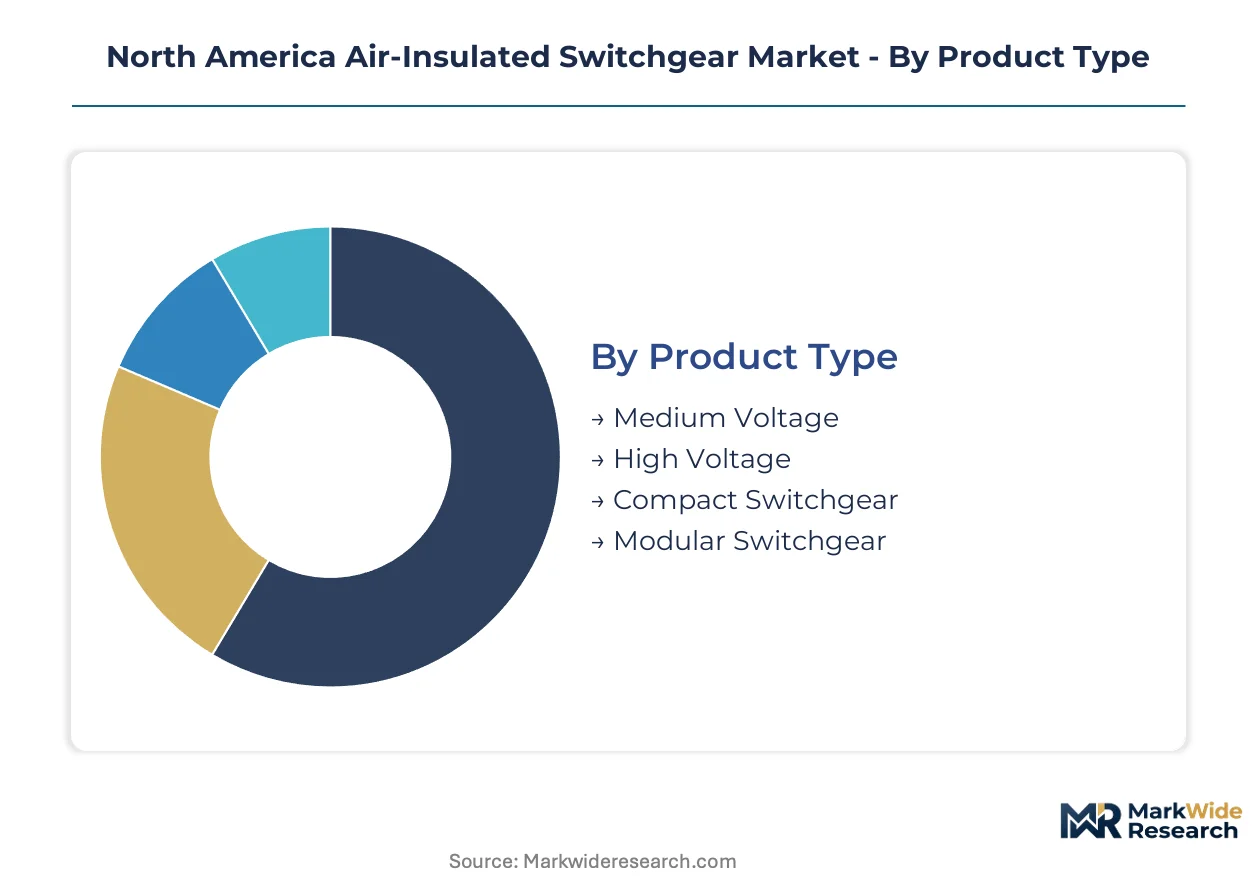
Segmentation reveals how procurement priorities diverge across voltage classes and installation contexts. Buyers in Texas and California weight outdoor ratings and arc-flash compliance differently than indoor urban operators in constrained substation footprints.
Product Type:
Upgrade cycles concentrate where NERC reliability standards force replacement of aging electromechanical assemblies with arc-resistant designs.
- Medium Voltage:Rated 1-52 kV with busbar capacities to 4000 A, these assemblies dominate utility distribution networks. Procurement concentrates in PJM Interconnection states where grid modernization programs accelerate replacement timelines for 1960s-era substations.
- Modular Switchgear:Factory-integrated, skid-mounted configurations compress on-site commissioning from weeks to days. Renewable interconnection projects across Texas and California specify these for rapid deployment where labor availability constrains construction schedules.
- High Voltage:Rated above 52 kV for transmission-level applications, these installations remain concentrated in Canadian provincial expansions under CSA C22.2 codes.
- Compact Switchgear:Space-optimized designs serve urban indoor applications where real estate costs and arc-flash containment requirements intensify.
Medium Voltage sits at the top of the volume ranking, with Modular Switchgear climbing the fastest.
End User:
Cost tier differentiation separates specification-heavy utility buyers from price-sensitive commercial operators.
- Utility:Distribution network operators mandate IEEE C37 series compliance and third-party witness testing. Procurement concentrates in ERCOT and PJM territories where NERC reliability standards tighten arc-flash and seismic performance requirements.
- Renewable Energy:Solar and wind interconnection projects demand outdoor-rated medium voltage assemblies with rapid delivery timelines. Texas and California lead procurement volume as independent power producers compete for transmission queue positions.
- Industrial:Manufacturing facilities and petrochemical complexes prioritize short-circuit withstand ratings and maintenance access protocols.
- Commercial:Data center operators in Virginia and Arizona drive demand for compact indoor configurations with integrated digital monitoring.
Utility captures the largest procurement volume, while Renewable Energy gains share fastest as interconnection backlogs clear.
Installation:
Application context determines whether buyers prioritize weatherproofing, seismic withstand, or spatial constraints.
- Outdoor:Weather-rated enclosures with corrosion-resistant finishes serve renewable and utility substation deployments. Texas and California specifications dominate procurement as these states absorb the majority of new renewable capacity additions.
- Retrofit:Legacy electromechanical relay integration challenges constrain project staffing for EPC contractors. PJM Interconnection states lead activity where 1970s-era air-insulated switchgear reaches end-of-design-life.
- Indoor:Arc-flash containment and footprint minimization drive specification in urban commercial and industrial facilities.
- New Construction:Greenfield data center and manufacturing projects favor factory-integrated delivery models with single-source accountability.
Outdoor installations lead procurement value, with Retrofit activity expanding most quickly as aging infrastructure replacement accelerates.
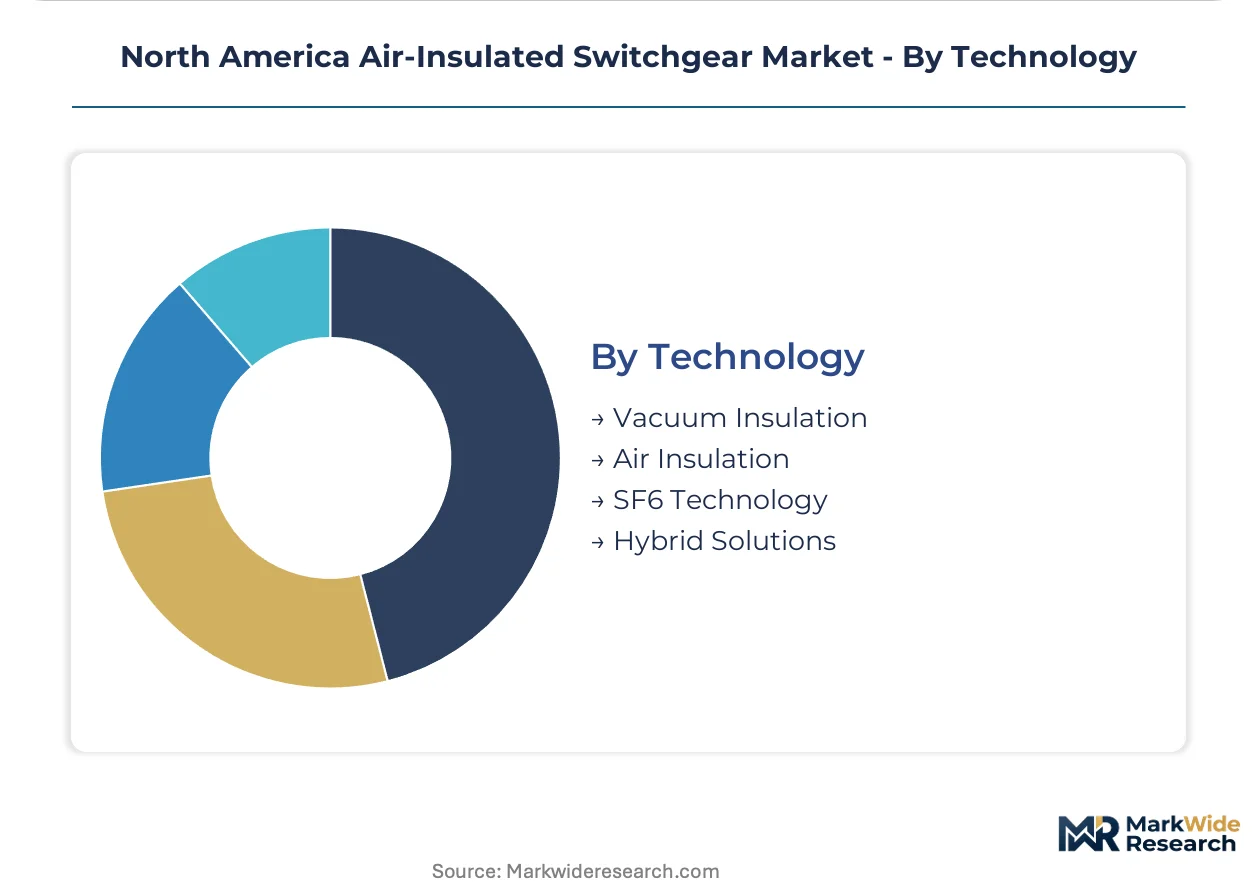
Technology:
Maturity curves separate established insulation methods from emerging hybrid architectures responding to regulatory pressure.
- Vacuum Insulation:Maintenance-free fault current interruption without oil or gas insulation enables compact, modular designs. Renewable developers in Texas and California specify these assemblies for rapid deployment and reduced lifecycle maintenance.
- Air Insulation:Ambient dielectric medium between live conductors and grounded enclosures remains the baseline for cost-sensitive utility procurement. IEEE C37 series guidelines govern qualification and testing protocols.
- SF6 Technology:Gas-insulated alternatives face EPA greenhouse gas reporting scrutiny and state-level fluorinated gas regulations. Utility RFPs increasingly require environmental impact assessments favoring SF6-free alternatives.
- Hybrid Solutions:Vacuum-air combinations merge compact footprints with regulatory compliance. Medium voltage retrofit channels across PJM states are most affected by specification shifts.
Air Insulation maintains the largest installed base, with Vacuum Insulation showing the steepest expansion trajectory as maintenance-free operation gains preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American air-insulated switchgear industry traces its commercial scale to post-war electrification programs that standardized outdoor medium voltage assemblies across utility networks. Federal infrastructure investments and state-level renewable mandates now drive procurement concentration in specific sub-regional corridors.
Texas
ERCOT interconnection backlogs and utility-scale solar deployment are compressing delivery timelines for outdoor-rated medium voltage assemblies. NERC reliability standards mandate arc-flash performance upgrades across transmission queue projects. The Permian Basin and West Texas solar corridors absorb the majority of new switchgear procurement as independent power producers compete for grid access.
California
CPUC grid modernization mandates and data center load growth in Silicon Valley are elevating specification requirements for seismic-resistant switchgear. Title 24 building codes and CEC energy efficiency standards tighten indoor arc-flash containment protocols. The Central Valley renewable belt and Bay Area hyperscale facilities represent the state's dual demand poles for medium voltage infrastructure.
PJM Interconnection States
Virginia data center construction and Pennsylvania-Ohio industrial corridor electrification are accelerating replacement cycles for 1970s-era substations. FERC Order 1920 transmission planning reforms incentivize standardization across multi-state procurement. Northern Virginia's Loudoun County and the Ohio River Valley manufacturing belt concentrate the region's switchgear demand.
Canada
Ontario and Alberta transmission expansion programs under CSA C22.2 electrical codes are creating procurement channels for outdoor-rated medium voltage assemblies. Federal clean electricity regulations and provincial grid investment frameworks mandate equipment upgrades. The Alberta oil sands electrification corridor and Ontario's nuclear refurbishment sites anchor Canadian demand concentration.
North America Air-Insulated Switchgear Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the arc-flash engineering and digital monitoring capability spectrum. The vendor base organizes into three tiers: integrated power management conglomerates with full infrastructure portfolios, specialized electrical equipment manufacturers with regional service density, and modular system integrators focused on factory-integrated delivery. Consolidation pressure is intensifying as buyers demand single-source accountability for protection relays, switchgear, and energy monitoring. Strategic moves center on backward integration into vacuum interrupter manufacturing and geographic expansion through accredited laboratory partnerships.
Within the integrated infrastructure tier, Eaton Corporation and ABB Ltd exemplify archetypes that bundle switchgear with adjacent power management technologies. Hitachi Energy Ltd occupies a position emphasizing digital monitoring overlays for outdoor-rated assemblies. Hubbell Incorporated and Powell Industries Inc represent North American specialists with concentrated utility relationships. Mitsubishi Electric Corporation, Siemens AG, General Electric Company, and Schneider Electric SE anchor the multinational electrical equipment segment with broad voltage-class coverage.
| Leading Market Players |
|---|
| Eaton Corporation |
| Hitachi Energy Ltd |
| ABB Ltd |
| Hubbell Incorporated |
| Mitsubishi Electric Corporation |
| Siemens AG |
| General Electric Company |
| Powell Industries Inc |
| Schneider Electric SE |
| Others |
Pricing and Supply Chain Analysis
Backward integration into vacuum interrupter manufacturing anchors supply security and pricing power for established North American switchgear producers, compressing cost structures for modular assemblies while elevating barriers for competitors lacking captive component sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates arc-resistant certified assemblies from baseline IEEE C37-compliant units and commodity retrofit configurations. Price differentiation hinges on seismic certification grade and after-sales service bundling. Cost compression in the economy tier intensifies as Chinese SF6-alternative imports pressure domestic manufacturers. Renewable energy developers exhibit the highest price sensitivity, while data center operators in Virginia and Arizona absorb premium pricing for integrated digital monitoring overlays.
Supply Chain Analysis
Freight cost volatility from Asian component sources is reshaping sourcing strategies as manufacturers regionalize vacuum interrupter procurement. Supply concentrates in the United States, Mexico, and Germany for final assembly, while copper busbar fabrication draws from Chilean and Peruvian mining output. Raw material dependencies span copper cathodes, aluminum extrusions, and epoxy resin insulators. Single-source vulnerability clusters with accredited seismic testing laboratories in California and Texas. Distribution runs through utility procurement departments, EPC contractor specifications, and industrial direct-buy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North American air-insulated switchgear market reads as a late-cycle quality story where NERC reliability standard upgrades are forcing specification premiums for arc-flash engineered assemblies.
For Market Incumbents: Cement laboratory accreditation partnerships in Texas and California to lock out competitors lacking IEEE C37 series witness test capabilities. Deepen backward integration into vacuum interrupter production to defend margin position against Chinese SF6-free import pressure. Prioritize digital monitoring overlay development as renewable interconnection projects mandate remote diagnostics. For New Entrants and Emerging Players: Enter via Canadian provincial grid investments under CSA C22.2 codes where incumbent service density remains thinner than in PJM Interconnection states. Target Ontario transmission expansion and Alberta oil sands electrification corridors with factory-integrated modular delivery. Lead with predictive maintenance software bundles to differentiate from hardware-focused incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where arc-flash engineering expertise scarcity constrains EPC contractor project staffing. The five-to-ten year viability window favors targets with established FERC Order 1920 transmission planning relationships and accredited seismic testing partnerships. Watch EPA fluorinated gas enforcement actions as the signal indicating accelerated substitution toward air-insulated and hybrid vacuum-air technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Interrupter Manufacturing | Captive component supply secures margin control against copper price volatility and import competition. |
| Accredited Laboratory Partnership Expansion | Seismic and arc-resistance testing access filters out competitors lacking third-party witness relationships. |
| Digital Monitoring Overlay Development | Predictive maintenance contracts create recurring revenue streams from utility asset managers. |
| Modular Factory-Integrated Delivery Scale-Up | Skid-mounted configurations compress commissioning timelines for site-constrained renewable projects. |
| SF6-Free Technology Certification Investment | EPA greenhouse gas scrutiny positions air-insulated alternatives for utility RFP specification shifts. |
Research Methodology
Multiple input streams — utility procurement officer interviews, EPC contractor specification reviews, and secondary regulatory filing analysis — were reconciled to construct demand estimates across the analysis window. Primary fieldwork engaged substation engineers, protection relay specialists, grid planning directors, and aftermarket service managers at equipment owners across ERCOT, PJM, and CAISO territories. Secondary validation drew from FERC interconnection queue data, NERC reliability standard dockets, EIA generation capacity reports, and IEEE C37 series technical committee proceedings. Bottom-up project pipeline aggregation and top-down utility capital expenditure triangulation cross-checked volume assumptions.
Historical deployment patterns were cross-referenced against panel input from equipment manufacturers and component suppliers to anchor growth trajectory assumptions. Segmentation modeling spanned voltage class, installation context, end-user archetype, and technology insulation method across the projection horizon. CAGRs were derived from equipment replacement cycle analysis and renewable interconnection backlog clearance rates. Forecast inputs incorporated NERC CIP compliance timeline shifts, copper futures curve movements, and data center load growth projections from hyperscaler facility announcements.
The model holds under stable NERC enforcement intensity and continued state-level renewable mandate progression; deviation in EPA SF6 regulatory stringency or FERC transmission cost allocation reforms would shift equipment substitution timelines and regional procurement concentration. Stakeholders should weight assumptions against their own operating context and project development pipeline exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Containerized Substation Market
Electrical Power Equipment
Gas Circuit Breaker Market
Electrical Power Equipment
Electric Submersible Pump Cable Market
Electrical Power Equipment
Magnet Bearings Market
Electrical Power Equipment
Power Strip Market
Electrical Power Equipment
Electrodialysis System Market
Electrical Power Equipment
Europe Gas Insulated Switchgear Market
Electrical Power Equipment
Alternating Current (AC) Electric Drives Market
Electrical Power Equipment
Europe Alternating Current (AC) Drive Market
Electrical Power Equipment
Global Hazardous Location Motor Starters Market
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
Overhead Aluminium Conductors Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
US Air Filter Market
Electrical Power Equipment
India Instrument Transformer Market
Electrical Power Equipment
Utility Equipment Market