
 Optical Current Transformer Market | 2026-2036
Optical Current Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Current Transformer Market Analytics
Single-source dependence on magnetic core suppliers is pivoting toward dual-source optical sensor strategies across major utilities. GE Grid Solutions leverages its high-voltage infrastructure heritage to anchor large-scale substation deployments. Siemens AG sustains R&D intensity in digital optical merging units for IEC 61850-compliant installations. ABB competes through integrated grid automation platforms that embed fiber-optic current sensing.
An optical current transformer measures electric current via the Faraday effect in optical fibers, achieving galvanic isolation with accuracy classes of 0.2S and bandwidth exceeding 100 kHz for protection-grade applications. The device eliminates magnetic saturation, serving critical roles in HVDC converter stations and compact gas-insulated switchgear. Fiber optic technology leads installed value due to proven immunity to electromagnetic interference in EHV corridors. Digital technology represents the fastest-expanding category as utilities demand sampled-value outputs for substation automation. Clamp-on configurations occupy niche margin pools in retrofit markets where busbar de-energization proves prohibitively expensive.
Grid operators in Germany navigate KBA-adjacent rail electrification standards while China's GB/T 20840 series governs optical instrument transformer certification. India's CEA mandates dynamic line rating systems that favor optical sensors for real-time thermal monitoring. Stakeholders must weigh fiber durability guarantees against solid-core optical designs as utility procurement shifts from component supply to performance-contracting frameworks.
Market Dynamics
Optical current transformer deployment is pivoting on IEC 61850 interoperability mandates that force utilities to retire analog merging units and adopt sampled-value digital architectures, compressing procurement cycles and redefining supplier qualification criteria.
Growth Catalysts
- GB/T 20840 certification:China's national standard for optical instrument transformers accelerates replacement of magnetic cores in ultra-high-voltage corridors, creating pull-through demand for fiber-optic sensing systems.
- Dynamic line rating mandates:India's CEA regulations require real-time thermal monitoring on transmission networks, positioning optical sensors as the only viable technology for continuous conductor temperature tracking without galvanic interference.
- HVDC converter station expansion:New interconnector projects across Asia-Pacific specify optical current transformers for protection-grade measurement in compact gas-insulated switchgear where magnetic saturation risks are unacceptable.
Market Restraints
- Fiber-optic cable cost volatility:Specialized polarization-maintaining fiber for Faraday-effect sensors concentrates production in limited manufacturing facilities, exposing project budgets to raw material price swings.
- Legacy workforce skill gaps:Utilities retain deep expertise in magnetic transformer maintenance while optical sensor calibration requires photonics-trained technicians that remain scarce in established grid operators.
- Proprietary digital protocols:Early optical CT installations deployed manufacturer-specific output formats that now create integration friction against IEC 61850-9-2LE sampled-value requirements.
Strategic Opportunities
- Retrofit clamp-on configurations:Busbar de-energization costs in aging substations create a niche for non-invasive optical sensors that install without primary circuit interruption.
- Rail electrification standards:Germany's KBA-adjacent specifications for interference-immune current measurement open a specialized vertical adjacent to traditional utility procurement.
- Performance contracting frameworks:Procurement teams are piloting availability-based payment models where sensor vendors guarantee measurement accuracy over 25-year asset lifecycles rather than selling hardware alone.
Industry Challenges
- IEC 61850 conformance testing delays:Third-party certification of optical merging units for sampled-value interoperability extends vendor qualification timelines by 12-18 months.
- Field fiber durability validation:Utilities demand accelerated aging data for optical cables in extreme temperature and vibration environments that manufacturers struggle to simulate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Current Transformer Market |
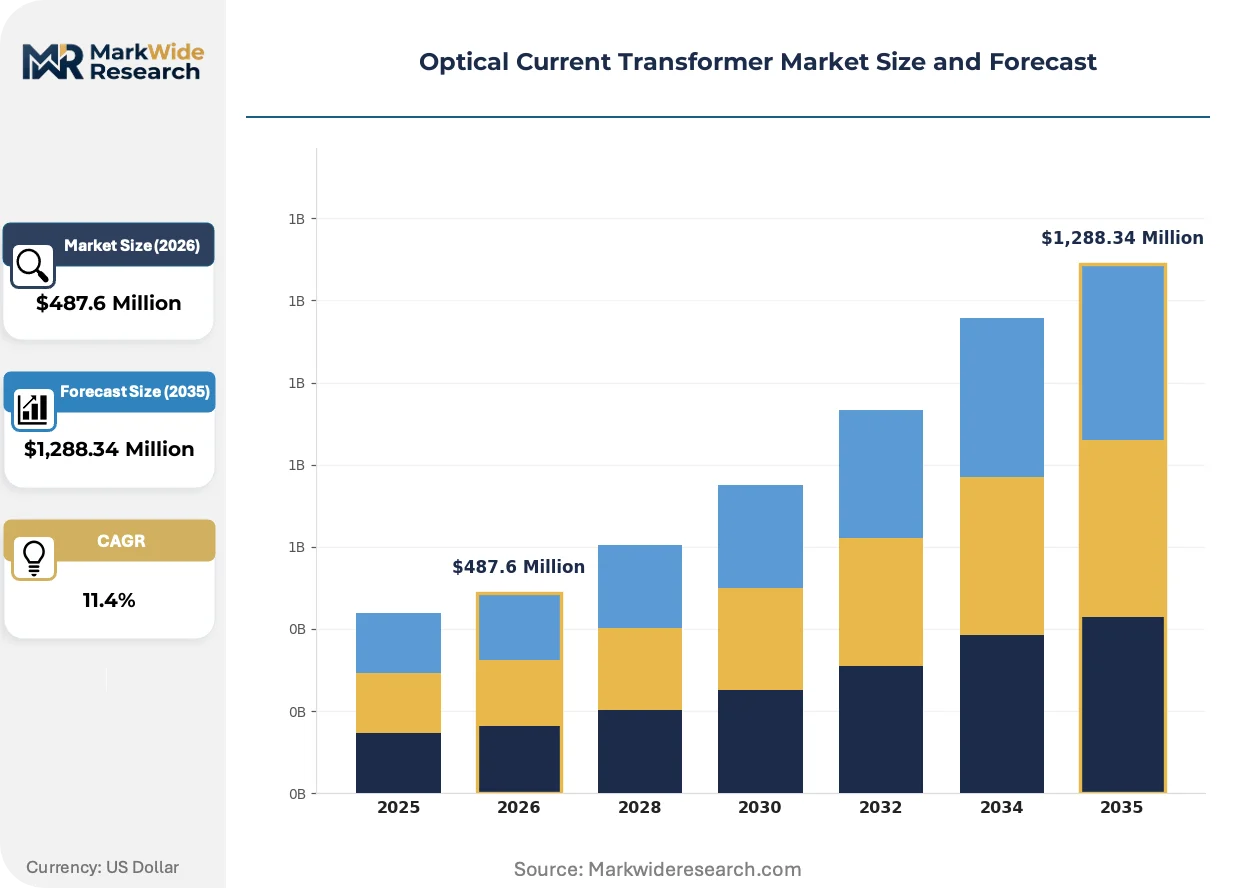
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Busbar, Ring, Split-Core, Clamp-On Technology: Fiber Optic, Digital, Analog, Hybrid Application: Power Monitoring, Grid Management, Renewable Energy, Industrial Automation End User: Utilities, Manufacturing, Oil & Gas, Transportation |
| Companies Covered | GE Grid Solutions, Siemens AG, ABB, Trench Group, NR Electric Co., Ltd., Arteche, Yangtze Optical Electronic Co., Ltd., Hitachi Energy Ltd., Profotech JSC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Current Transformer Market Evolving Landscape
Digital optical sensing is compressing the boundary between primary measurement and secondary protection systems, enabling architectures that embed intelligence directly at the sensing point rather than in remote merging units.
Photonic integrated circuits for Faraday rotation detection are rewriting the cost structure of optical current transformers. These chip-scale devices replace bulk optical components with silicon photonics platforms. HVDC converter station operators in China and India are qualifying pilot installations. The technology is compressing sensor head dimensions and enabling mass manufacturing economics previously unavailable to specialty fiber-optic assemblies.
Europe's F-Gas Regulation is accelerating scrutiny of sulfur hexafluoride insulation in gas-insulated switchgear, the primary installation environment for compact optical current transformers. The policy creates design pressure for SF6-free switchgear architectures that retain optical sensing compatibility. Manufacturers serving German and Nordic markets are prioritizing dry-air insulation designs that preserve fiber-optic current measurement pathways without fluorinated gas dependencies.
Utility procurement teams are consolidating vendor relationships from component sourcing to integrated substation automation platforms. Buyers now specify optical current transformers as subsystems within broader digital substation contracts rather than standalone equipment purchases. This pattern is most pronounced in China's State Grid procurement cycles and India's central transmission utility tenders, where single-source accountability for measurement accuracy, communication protocol compliance, and cyber security certification is becoming mandatory.
Optical Current Transformer Market Segmentation
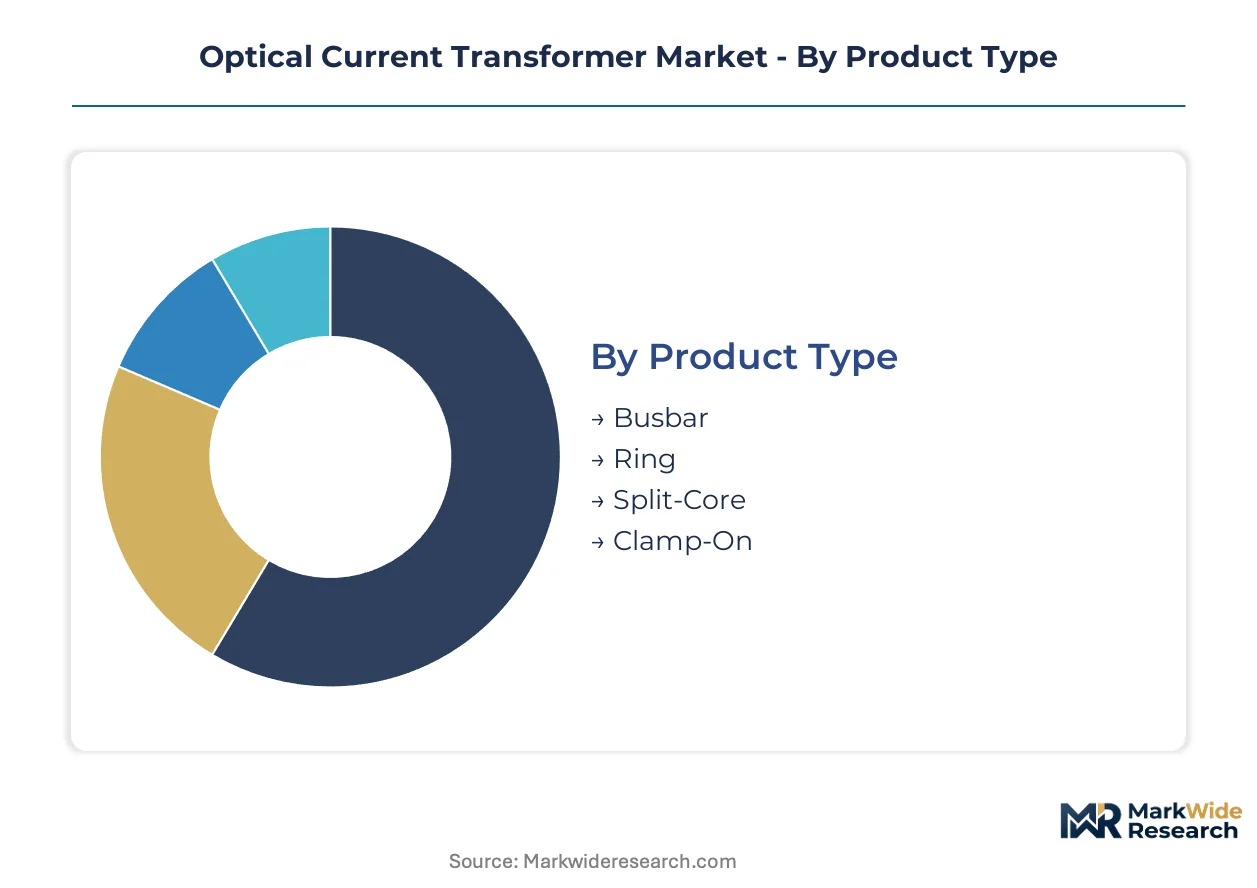
Optical current transformer procurement varies sharply by installation environment and measurement architecture. Segment boundaries determine fiber durability requirements, calibration protocols, and integration complexity with legacy substation infrastructure.
Product Type:
Busbar-mounted designs dominate volume procurement for new substation construction, while clamp-on variants command premium pricing in retrofit scenarios where circuit de-energization is prohibitively expensive.
- Busbar:These sensors integrate directly into primary conductor assemblies, achieving 0.2S accuracy class through polarization-maintaining fiber loops. Demand concentrates in China's ultra-high-voltage transmission corridors where compact gas-insulated switchgear requires minimal footprint current measurement without magnetic saturation risks.
- Clamp-On:Non-invasive configurations wrap around energized busbars or cables, eliminating primary circuit interruption. India's aging substation infrastructure drives adoption where de-energization costs exceed sensor procurement by factors of ten, particularly in congested urban distribution yards.
- Ring:Toroidal fiber-optic coils encircle primary conductors for high-precision metering applications in revenue-grade installations.
- Split-Core:Hinged optical assemblies enable post-installation deployment on existing infrastructure without conductor disassembly.
Mature deployment sits with busbar configurations in greenfield substations. Newer deployment is concentrated in clamp-on variants for brownfield grid modernization.
Technology:
Signal processing architecture determines interoperability with IEC 61850 substation automation systems and defines the boundary between component and subsystem procurement.
- Fiber Optic:Faraday-effect sensors using polarization-maintaining fiber achieve galvanic isolation with bandwidth exceeding 100 kHz for protection-grade applications. China's State Grid specifies these for HVDC converter stations where electromagnetic immunity is non-negotiable.
- Digital:Sampled-value output architectures with embedded merging units deliver IEC 61850-9-2LE compliance directly at the sensing point. India's central transmission utilities mandate these for new digital substation deployments to eliminate separate analog-to-digital conversion hardware.
- Analog:Conventional milliamp or volt outputs persist in legacy protection schemes requiring minimal integration engineering.
- Hybrid:Dual-output designs combine analog backup with digital primary channels for transitional substation architectures.
Hybrid configurations serve as bridge technology for utilities with mixed vintage protection systems. Digital technology is gaining share fastest as full substation automation becomes standard procurement.
Application:
Use case segmentation separates high-precision revenue metering from protection-grade fault detection and wide-area monitoring scenarios.
- Power Monitoring:Revenue-grade accuracy requirements drive fiber-optic sensor deployment at interconnection points and bulk power transfer locations. Germany's transmission system operators specify these for cross-border trading nodes under ENTSO-E harmonization guidelines.
- Grid Management:Dynamic line rating and real-time thermal monitoring applications favor optical sensors for continuous conductor temperature tracking without galvanic interference. India's CEA mandates these capabilities on congested transmission corridors.
- Renewable Energy:Offshore wind and solar inverter integration requires compact, interference-immune current measurement in harsh electromagnetic environments.
- Industrial Automation:High-current motor protection and arc flash mitigation in heavy manufacturing deploys optical isolation for personnel safety.
Established demand centers on power monitoring for wholesale electricity settlement. Renewable energy integration represents the steepest expansion trajectory as inverter-based generation proliferates.
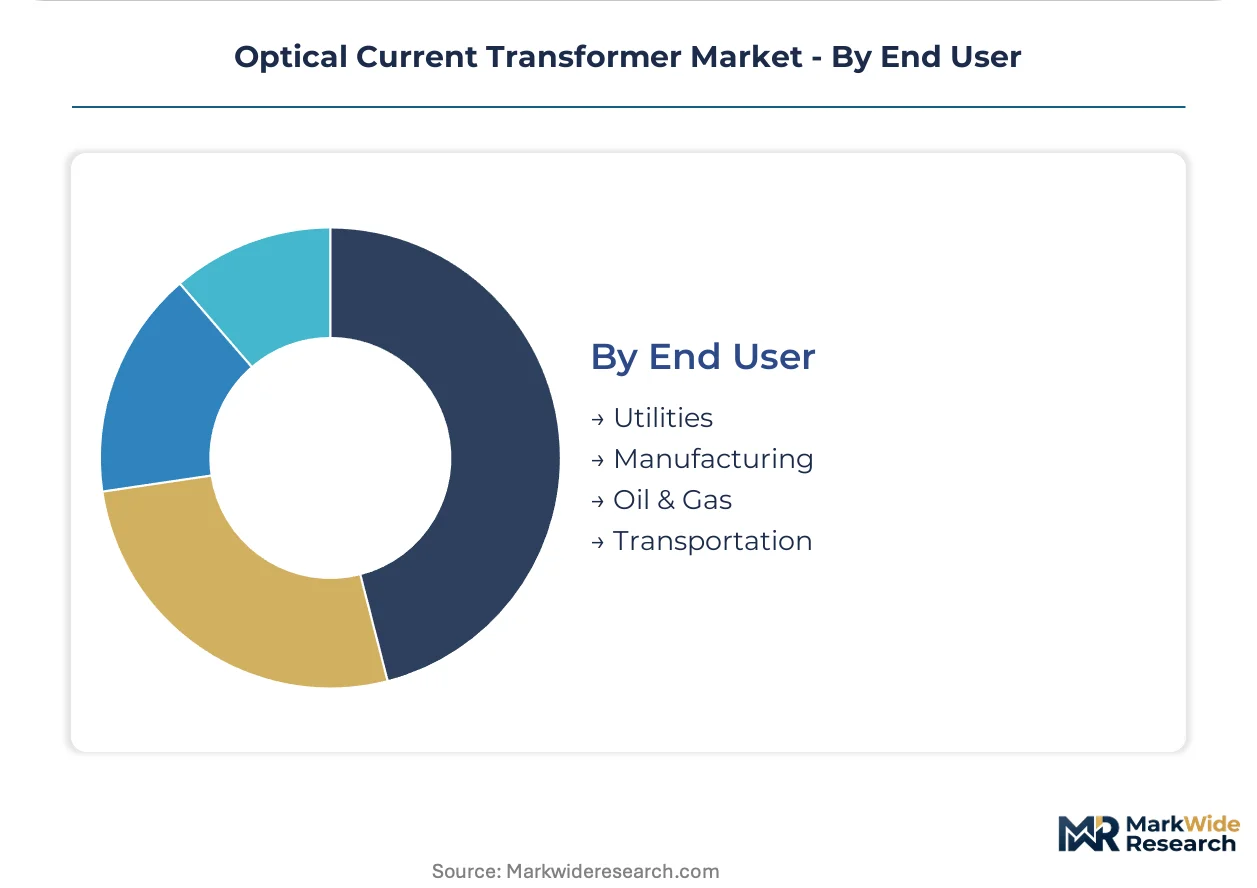
End User:
Procurement authority and technical specification depth vary dramatically between regulated utilities and industrial self-generation operators.
- Utilities:Centralized transmission and distribution operators drive standardization through framework agreements and multi-year supply contracts. China's State Grid and India's Power Grid Corporation specify optical current transformers as subsystems within integrated digital substation procurements.
- Manufacturing:Heavy industrial facilities with captive generation and high-voltage motor loads prioritize optical isolation for maintenance personnel safety in arc flash hazard zones.
- Oil & Gas:Offshore platforms and LNG terminals specify explosion-proof optical sensors for subsea cable monitoring and high-power pump protection.
- Transportation:Rail electrification systems under Germany's KBA-adjacent standards require interference-immune current measurement for catenary protection and traction substation monitoring.
Volume concentration remains with utility procurement. Transportation electrification is emerging as a specialized vertical with distinct certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's ultra-high-voltage transmission corridors and India's grid modernization zones concentrate procurement volume for optical current transformers. Germany's rail electrification standards and the United States' digital substation investments add specialized demand pockets.
China
State Grid Corporation drives replacement of magnetic cores in 1,100 kV corridors under GB/T 20840 certification requirements. The national standard accelerates fiber-optic sensing adoption for HVDC converter stations. Yangtze River Delta manufacturing clusters supply polarization-maintaining fiber assemblies to domestic transformer producers.
India
Power Grid Corporation mandates dynamic line rating systems across congested transmission networks per CEA regulations. Central transmission utilities specify sampled-value digital architectures for new substation deployments. Gujarat and Maharashtra host the primary installation activity for optical sensors in urban distribution yards.
Germany
KBA-adjacent rail electrification standards require interference-immune current measurement for catenary protection systems. The F-Gas Regulation pressures SF6-free switchgear designs that retain optical sensing compatibility. Bavaria and North Rhine-Westphalia concentrate traction substation modernization projects.
United States
FERC grid modernization incentives accelerate digital substation investments with IEC 61850 interoperability requirements. Utilities in Texas and California pilot performance-contracting frameworks for 25-year sensor accuracy guarantees. Southwest transmission corridors favor clamp-on configurations for retrofit scenarios.
Japan
METI energy efficiency directives promote compact gas-insulated switchgear with optical current measurement. Kansai and Chubu regional utilities specify Faraday-effect sensors for offshore wind interconnection projects. Osaka-based industrial clusters supply photonic components for domestic transformer assembly.
Optical Current Transformer Market Competitive Landscape
Strategic partnerships dominate the current landscape as component suppliers align with grid automation platforms. The market structure concentrates around integrated subsystem providers rather than standalone sensor vendors. Three archetypes define competitive positioning: high-voltage infrastructure heritage players, photonics specialists, and digital substation integrators. Technology licensing agreements and backward integration into fiber manufacturing represent the primary competitive vectors.
Among diversified electrical equipment manufacturers, GE Grid Solutions, Siemens AG, and ABB occupy positions anchored in high-voltage infrastructure heritage. These entities exemplify the integrated platform archetype where optical current transformers function as subsystems within broader digital substation contracts. NR Electric Co., Ltd. and Yangtze Optical Electronic Co., Ltd. represent the specialist tier with concentrated exposure to Asia-Pacific utility procurement cycles.
| Leading Market Players |
|---|
| GE Grid Solutions |
| Siemens AG |
| ABB |
| Trench Group |
| NR Electric Co., Ltd. |
| Arteche |
| Yangtze Optical Electronic Co., Ltd. |
| Hitachi Energy Ltd. |
| Profotech JSC |
| Others |
Value Network & Pricing Analysis
Utility procurement teams in China and India are consolidating vendor relationships into integrated digital substation contracts under IEC 61850 mandates, forcing component suppliers to absorb subsystem accountability costs and compressing hardware-only margins toward performance-guarantee pricing models.
Pricing Analysis
Volume procurement concentrates in busbar-mounted optical current transformers for greenfield substations, while clamp-on configurations capture premium margins in retrofit scenarios where de-energization costs dwarf sensor pricing. Three-tier pricing structure across IEC 61850-certified digital, hybrid transitional, and legacy analog outputs reflects certification investment differentiation. Cost compression in standard fiber-optic tiers is intensifying because polarization-maintaining fiber supply concentrates in limited manufacturing facilities. Distribution utilities exhibit highest price sensitivity due to framework agreement procurement, while HVDC converter station operators prioritize electromagnetic immunity over unit cost.
Supply Chain Analysis
Photonics-trained technician availability constrains manufacturing scale-up in Yangtze River Delta clusters and Osaka industrial zones where polarization-maintaining fiber assembly requires specialized labor pools. Supply concentrates in China for fiber-optic components, Germany for precision optical engineering, and Japan for photonic integrated circuit development. Raw material dependencies include polarization-maintaining fiber, Faraday-effect glass cores, and silicon photonics substrates. Single-source vulnerability in specialty fiber production exposes project timelines to capacity constraints. Distribution runs through direct utility framework agreements and EPC contractor specifications rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where IEC 61850 certification creates a 12-18 month qualification barrier that protects incumbents with approved merging units while excluding hardware-only vendors from digital substation procurement cycles.
For Market Incumbents: Acquire photonic integrated circuit design capabilities to compress sensor head dimensions and capture mass manufacturing economics before silicon photonics platforms commoditize Faraday rotation detection. Consolidate backward integration into polarization-maintaining fiber production to defend against raw material cost volatility from single-source suppliers. Prioritize embedded intelligence architectures that merge primary sensing with secondary protection functions, displacing separate merging unit vendors from utility specifications. For New Entrants and Emerging Players: Digital-channel route partnerships with substation automation platform vendors offer the fastest path to procurement visibility without direct utility qualification delays. Target India's aging urban distribution infrastructure where clamp-on retrofit demand outstrips qualified supplier capacity and de-energization costs justify premium positioning. Pursue rail electrification certification under Germany's KBA-adjacent standards as a specialized vertical with distinct procurement cycles and limited incumbent presence. For Investors and Strategic Acquirers: The window for entry favors photonics specialists with IEC 61850-9-2LE conformance testing already completed, as certification timelines extend vendor qualification beyond typical investment horizons. Long-term viability rests on subsystem integration capabilities rather than component supply, with digital substation automation platforms capturing procurement consolidation benefits. Monitor State Grid Corporation framework agreement awards as the primary signal for supplier share shifts in the highest-volume geography.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 61850 Conformance Certification | Third-party validation of sampled-value interoperability accelerates utility qualification timelines by 12-18 months. |
| Photonic Integrated Circuit Development | Silicon photonics platforms enable mass manufacturing economics for Faraday rotation detection chips. |
| Backward Integration into Fiber Manufacturing | In-house polarization-maintaining fiber production hedges raw material cost volatility from limited suppliers. |
| Performance Contracting Framework Pilot | Availability-based payment models shift vendor accountability from hardware delivery to 25-year accuracy guarantees. |
| Rail Electrification Certification Investment | KBA-adjacent standards compliance opens specialized vertical adjacent to traditional utility procurement. |
Research Methodology
Regulatory filings from IEC, CEA, and State Grid Corporation, trade data from customs authorities, and technical standards documentation formed the secondary backbone for market sizing and technology trend validation. Primary interviews with utility planning officers, substation automation engineers, EPC contractor procurement leads, and photonics R&D directors combined with bottom-up and top-down triangulation to cross-validate segmentation estimates and growth trajectory assumptions across the analysis window.
Historical trendline analysis of optical instrument transformer deployment patterns informed the projection framework, with CAGRs derived from utility capital expenditure trajectories and regulatory mandate implementation schedules. Segmentation dimensions modeled include product architecture, signal processing technology, application use case, and end-user procurement authority. Forecast inputs incorporated HVDC converter station buildout pipelines, digital substation automation adoption curves, and fiber-optic component manufacturing capacity expansion plans.
The model holds under continued IEC 61850 interoperability enforcement and stable specialty fiber supply; deviation in certification timeline delays or raw material cost spikes would shift volume assumptions. Forecasts reflect documented assumptions regarding utility procurement consolidation and technology substitution rates. Material deviation in regulatory implementation schedules or photonics manufacturing capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Global Electric Power Substation Automation Market
Electrical Power Equipment
Skid Mounted Unit Substations Market
Electrical Power Equipment
Canada Electric Space Heater Market
Electrical Power Equipment
Magnet Bearings Market
Electrical Power Equipment
Switching Residential Voltage Regulator Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
3rd Rail Current Collector Market
Electrical Power Equipment
North America Protective Relays Market
Electrical Power Equipment
AC Drives Market
Electrical Power Equipment
US Electric Towers and Poles Market
Electrical Power Equipment
Composite Insulators Market
Electrical Power Equipment
Global Air Insulated Switchgear Market
Electrical Power Equipment
Smart Electric Heater Market
Electrical Power Equipment
Global Surge Arrester Market
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
Low Voltage Protection Control Market