
 North America Gas Insulated Switchgear Market | 2026-2036
North America Gas Insulated Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gas Insulated Switchgear Market Outlook
The divergence between premium and commodity tiers in North American gas insulated switchgear is hardening around insulation integrity ratings and modular serviceability. Siemens Energy leverages captive manufacturing of cast resin bushings to command pricing power in high-reliability utility contracts. General Electric anchors its position through integrated digital monitoring platforms that reduce substation downtime. Powell Industries specializes in arc-resistant enclosures for petrochemical and heavy industrial sites.
Gas insulated switchgear encloses electrical conductors, circuit breakers, and disconnectors within sealed metal compartments pressurized with sulfur hexafluoride gas at densities typically exceeding 0.4 MPa to achieve dielectric strength far exceeding air-insulated alternatives. Its primary purpose centers on delivering compact, weather-independent switching and protection for high-voltage transmission substations, urban underground networks, and offshore platforms where footprint constraints or environmental exposure prohibit conventional open-air designs. Compact switchgear dominates unit shipments across metropolitan underground installations where real estate premiums restrict substation footprints. Medium voltage configurations absorb the largest share of replacement demand as aging urban infrastructure reaches end-of-design-life across northeastern US cities. Modular switchgear represents the fastest-expanding product category, driven by data center developers seeking phased capacity expansion without complete substation overhaul.
The Federal Energy Regulatory Commission and the EPA jointly shape market access through interconnection reliability mandates and phased restrictions on sulfur hexafluoride venting during maintenance and decommissioning. IEEE and NEMA standards govern dielectric testing protocols and seismic qualification requirements that differentiate approved suppliers from marginal entrants. Canadian Standards Association certification adds a parallel compliance layer for cross-border projects serving integrated US-Canada grid corridors. Stakeholders must monitor evolving state-level clean energy mandates that could accelerate replacement timelines beyond baseline depreciation schedules.
Market Dynamics
EPA sulfur hexafluoride emission restrictions are compressing replacement cycles across aging utility fleets while offshore wind interconnection mandates in Texas and California pull high-voltage compact installations into accelerated procurement timelines.
Growth Catalysts
- Offshore Wind Interconnection Mandates:State-level renewable portfolio standards in Massachusetts and New York require transmission upgrades that favor compact GIS configurations for coastal substations.
- FERC Order 2023:Interconnection queue reforms accelerate grid access timelines for data center loads exceeding 500 MW, prioritizing pre-certified switchgear vendors.
- Urban Underground Expansion:Metropolitan real estate constraints in Chicago and Toronto drive demand for footprint-minimal medium voltage installations replacing aging air-insulated assets.
Market Restraints
- Cast Resin Bushing Supply Concentration:North American manufacturing of high-voltage insulation components concentrates among three specialized foundries, creating lead time vulnerability for utility-scale contracts.
- SF6 Gas Price Volatility:Sulfur hexafluoride supply disruptions from European production curtailments under F-Gas Regulation have doubled refill costs for maintenance cycles.
- Seismic Qualification Barriers:IEEE 693 certification requirements for Pacific Coast installations exclude non-specialized fabricators from California and British Columbia utility tenders.
Strategic Opportunities
- Modular Phased Expansion:Data center developers in Northern Virginia and Phoenix seek containerized GIS blocks enabling 50 MW capacity increments without full substation rebuilds.
- SF6 Alternative Insulation:Fluoronitrile-based dielectric mediums qualify for EPA emission credits under emerging state clean energy mandates, opening retrofit markets.
- Digital Monitoring Convergence:Integration of dissolved gas analysis sensors with SCADA platforms creates recurring revenue streams for predictive maintenance contracts.
Industry Challenges
- High-Voltage Technician Scarcity:Specialized GIS commissioning expertise concentrates among retiring utility workforces, constraining deployment velocity for multi-site rollouts.
- Legacy Interoperability Complexity:Integration of IEC 61850-compliant digital controls with electromechanical protection schemes in older substations demands costly custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gas Insulated Switchgear Market |
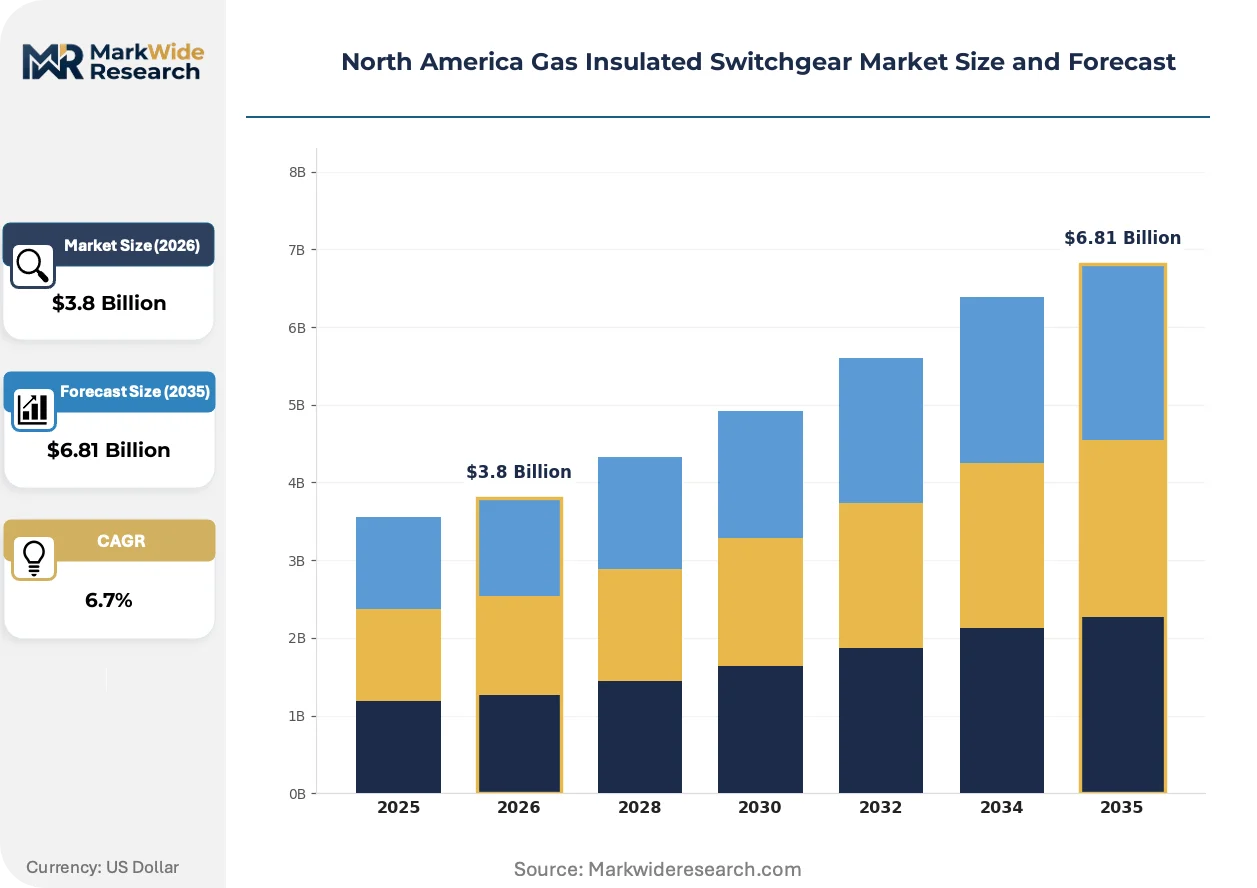
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid Switchgear, Compact Switchgear, Modular Switchgear, Standard Switchgear End User: Utilities, Industrial, Commercial, Renewable Energy Installation Type: Indoor, Outdoor, Mobile, Permanent Voltage Level: High Voltage, Medium Voltage, Extra High Voltage, Others |
| Companies Covered | Siemens Energy, General Electric, Schneider Electric, ABB, Eaton Corporation, Hitachi Energy, Mitsubishi Electric, Toshiba Energy Systems & Solutions Corporation, Powell Industries, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gas Insulated Switchgear Market Strategic Shifts
Three simultaneous vectors reshape competitive positioning: dielectric medium substitution, embedded intelligence integration, and procurement model compression toward lifecycle contracting.
Hybrid insulation systems combining SF6 with solid dielectric barriers are unifying reliability performance across temperature extremes. Arctic pipeline operators and desert solar farms adopt these configurations for ambient resilience. The technology is compressing the performance gap between premium cast-resin and commodity gas-insulated tiers, forcing mid-market suppliers toward feature differentiation.
EPA's phased restrictions on sulfur hexafluoride venting during maintenance operations impose recovery and recycling protocols. Equipment owners face decommissioning liability exposure that accelerates full replacement over component refurbishment. California utilities respond by specifying sealed-for-life designs with 40-year maintenance intervals in new procurement standards.
Lifecycle service contracting displaces transactional equipment sales for urban underground networks. Municipal utilities in Boston and Montreal bundle 25-year operation and maintenance commitments with initial capital purchases. This shift concentrates vendor selection criteria on regional service footprint density rather than unit cost alone.
North America Gas Insulated Switchgear Market Segmentation
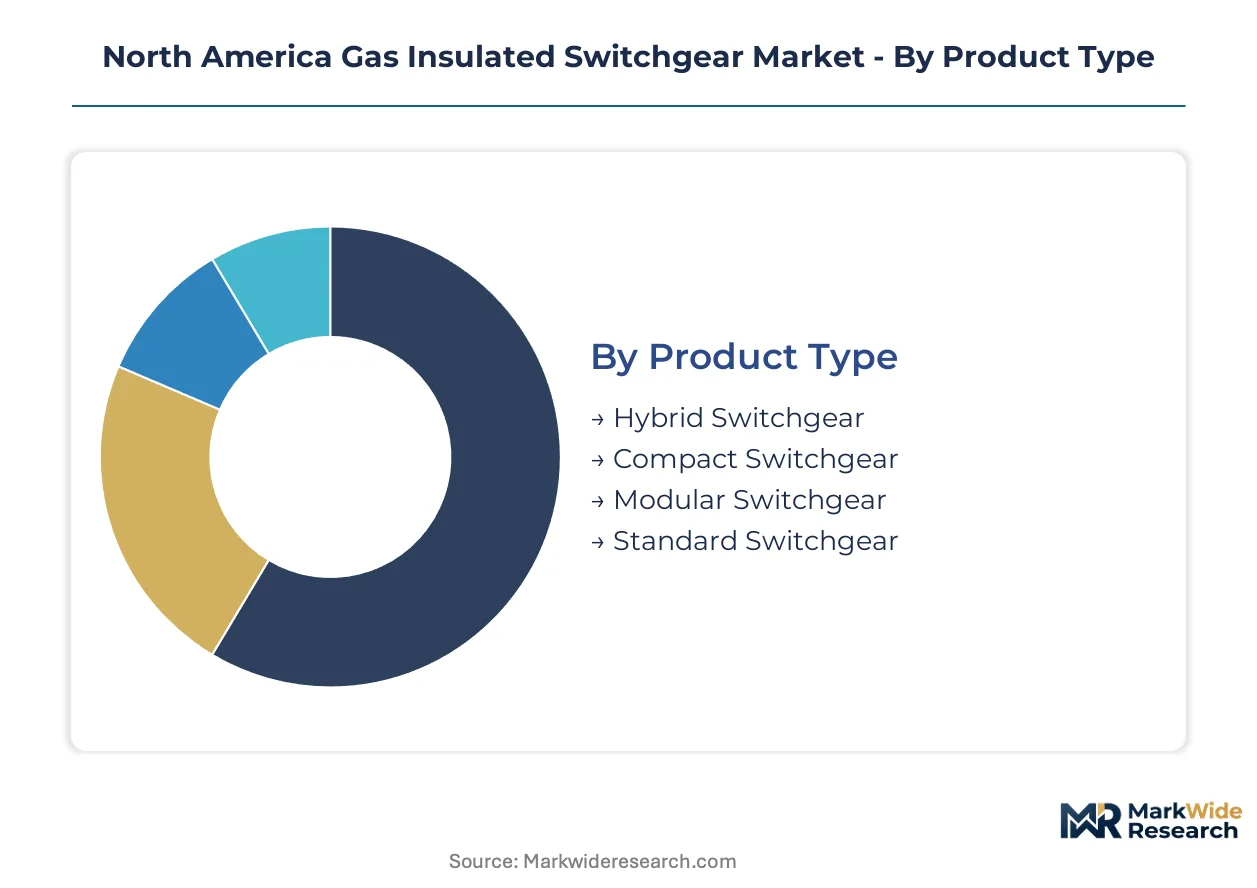
Gas insulated switchgear procurement across North America fragments sharply by footprint constraints, operational criticality, and voltage tier. Each segmentation axis carries distinct specification requirements that determine vendor qualification and pricing architecture.
Product Type:
Customization intensity varies from fully standardized utility catalog items to engineered-to-order modular blocks for phased data center expansions.
- Compact Switchgear:Sealed metal enclosures with fixed circuit breaker configurations minimize substation footprints for urban underground networks. Demand concentrates in Chicago and Toronto metropolitan utilities where real estate premiums restrict expansion options.
- Modular Switchgear:Containerized blocks enable 50 MW capacity increments without full substation rebuilds. Northern Virginia and Phoenix data center developers drive procurement volumes for this configuration.
- Hybrid Switchgear:Combines air-insulated bus sections with gas-insulated breaker compartments for intermediate footprint requirements.
- Standard Switchgear:Conventional aisle-based layouts serve greenfield transmission substations with minimal space constraints.
Most installed capacity flows through Compact Switchgear. Expansion is steepest in Modular Switchgear.
End User:
Procurement sophistication ranges from lifecycle-contracting municipal utilities to transaction-focused industrial maintenance teams.
- Utilities:Vertically integrated transmission operators specify sealed-for-life designs with 40-year maintenance intervals under California procurement standards. EPA sulfur hexafluoride emission restrictions accelerate replacement cycles across aging fleets in the northeastern United States.
- Renewable Energy:Offshore wind developers in Massachusetts and New York require coastal substation configurations that withstand salt spray and seismic loading. State renewable portfolio standards pull high-voltage compact installations into accelerated procurement timelines.
- Industrial:Petrochemical and heavy manufacturing sites demand arc-resistant enclosures for personnel protection.
- Commercial:Campus and healthcare facilities prioritize low-noise operation for urban siting approval.
Contract value concentrates with Utilities. Project velocity runs highest in Renewable Energy.
Installation Type:
Environmental exposure and relocation frequency determine enclosure sealing specifications and foundation requirements.
- Indoor:Climate-controlled substation buildings in dense urban cores eliminate weather-related dielectric degradation risks.
- Outdoor:Open-air installations with enhanced IP ratings serve transmission corridors and remote generation tie points.
- Mobile:Skid-mounted configurations support emergency restoration and temporary load serving during permanent facility construction.
- Permanent:Fixed concrete foundations anchor long-horizon infrastructure investments with 40-year depreciation schedules.
Foundation type splits evenly between Indoor and Outdoor. Deployment flexibility is expanding fastest in Mobile.
Voltage Level:
Dielectric design complexity and regulatory oversight intensity escalate with nominal voltage ratings.
- Medium Voltage:15-38 kV configurations absorb the largest share of replacement demand as aging urban infrastructure reaches end-of-design-life. Boston and Montreal municipal utilities bundle 25-year operation and maintenance commitments with capital purchases in this tier.
- High Voltage:72-145 kV installations dominate offshore wind interconnection projects in Texas and California. FERC interconnection queue reforms accelerate grid access timelines for data center loads exceeding 500 MW.
- Extra High Voltage:245-550 kV systems serve bulk power transmission corridors with minimal loss tolerance.
- Others:Specialty ratings for DC links and railway electrification occupy niche procurement channels.
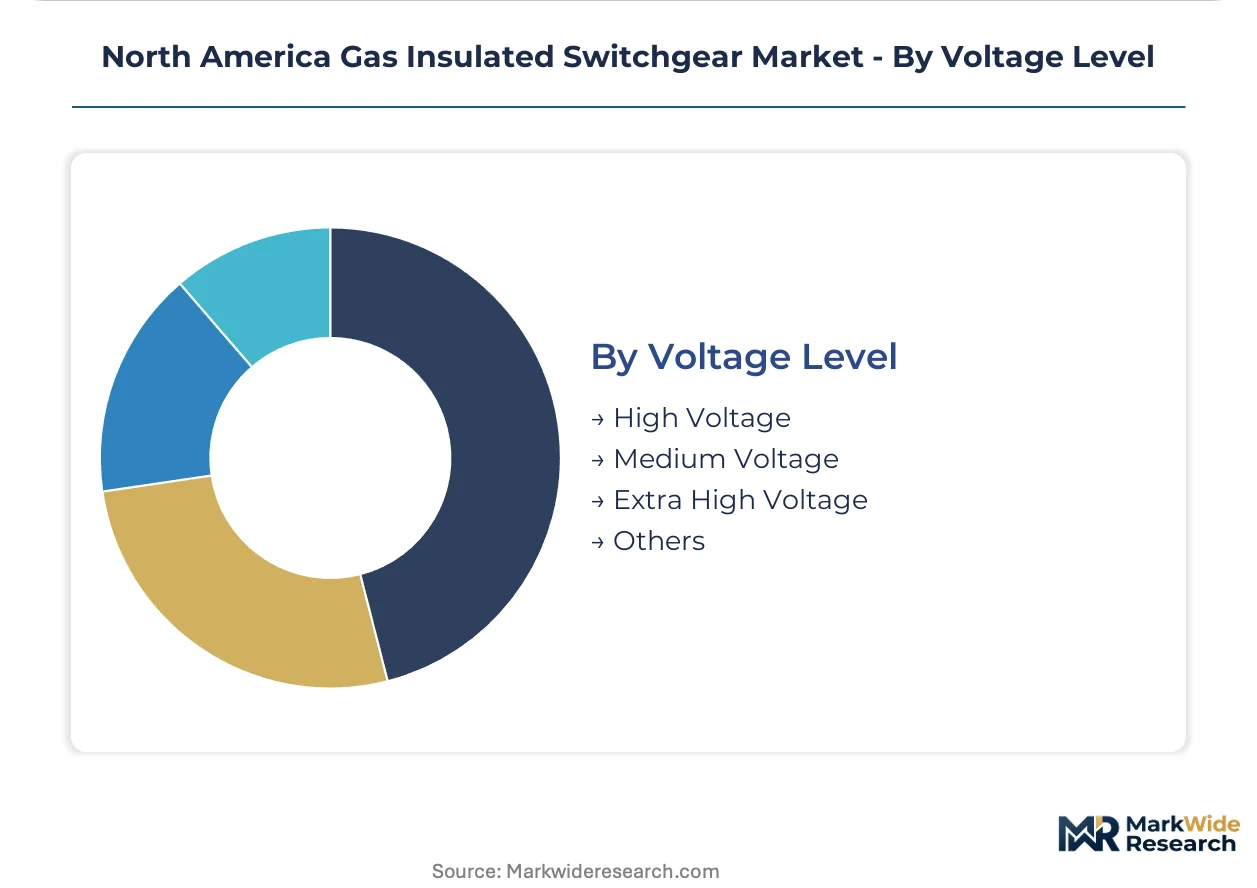
Unit shipment volume peaks in Medium Voltage. Capital intensity per bay climbs fastest in Extra High Voltage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized high-voltage technician pools concentrate in Houston, Chicago, and Toronto, anchoring commissioning capacity for utility-scale deployments across the continent.
United States
Texas and California utilities drive procurement volumes through offshore wind interconnection mandates and data center load growth exceeding 500 MW per site. The EPA's tightened sulfur hexafluoride emissions protocols compress replacement cycles for aging northeastern urban infrastructure. Metropolitan Chicago underground networks favor compact configurations where real estate premiums restrict substation footprints.
Canada
Cross-border grid corridors serving integrated US-Canada transmission require Canadian Standards Association certification as a parallel compliance layer. Provincial utilities in Ontario and Quebec specify sealed-for-life designs with extended maintenance intervals. Toronto municipal operators bundle 25-year operation and maintenance commitments with capital purchases for medium voltage urban installations.
Mexico
Industrial corridor electrification in Nuevo León and the Bajío Region pulls medium voltage switchgear into manufacturing hub expansions. The country's national energy regulator mandates seismic qualification for Pacific Coast installations. Mexico City metropolitan utilities prioritize low-noise configurations for dense urban siting approval.
North America Gas Insulated Switchgear Market Competitive Environment
Capital-heavy producers compete with asset-light designers across tiered qualification barriers. The vendor base stratifies around captive manufacturing of cast resin bushings versus outsourced component assembly. Three archetypes dominate: integrated digital platform providers, arc-resistant enclosure specialists, and modular containerized block fabricators. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure regional service footprint density.
Within the integrated platform tier, Siemens Energy and General Electric exemplify divergent approaches to lifecycle contracting. Powell Industries occupies a position among arc-resistant enclosure specialists serving heavy industrial site requirements. These three anchors illustrate how vendor selection criteria increasingly weight regional service presence over unit cost alone.
| Leading Market Players |
|---|
| Siemens Energy |
| General Electric |
| Schneider Electric |
| ABB |
| Eaton Corporation |
| Hitachi Energy |
| Mitsubishi Electric |
| Toshiba Energy Systems & Solutions Corporation |
| Powell Industries |
| Others |
Value Chain & Pricing Dynamics
Fluoronitrile-based dielectric medium qualification under emerging EPA emission credit protocols simultaneously compresses production costs for alternative insulation systems and concentrates manufacturing capability among suppliers with in-house gas handling infrastructure. This dual effect reshapes procurement economics across utility-scale contracts and data center lifecycle agreements.
Pricing Analysis
Lifecycle service bundling separates transaction-only equipment sales from 25-year operation and maintenance commitments in municipal utility procurement across Boston and Montreal. Price differentiation hinges on sealed-for-life design certification and regional service footprint density rather than unit manufacturing cost alone. Cost compression in commodity gas-insulated tiers intensifies because hybrid insulation systems unify reliability performance across temperature extremes. Data center developers in Northern Virginia exhibit lowest price sensitivity due to phased expansion requirements, while industrial maintenance teams in petrochemical corridors prioritize upfront capital minimization.
Supply Chain Analysis
Freight cost escalation for cast resin bushing shipments from European specialized foundries under F-Gas Regulation curtailments amplifies lead time vulnerability for North American utility-scale contracts. Geographic supply concentration centers on Germany, Japan, and the United States for high-voltage insulation components and sulfur hexafluoride gas reclamation equipment. Raw material dependencies encompass cast epoxy resins, aluminum alloy enclosures, and precision-machined copper conductors. Single-source vulnerability in high-voltage bushing manufacturing creates procurement risk for multi-site utility rollouts. Distribution runs through authorized regional service centers with EPA-certified gas handling capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American gas insulated switchgear constitutes a late-cycle quality story as California utilities mandate 40-year maintenance intervals and sealed-for-life designs in new procurement standards.
For Market Incumbents: Extend captive manufacturing of cast resin bushings to secure pricing power against commodity-tier competition from hybrid insulation entrants. Add EPA-certified gas reclamation capacity in Texas and California to defend regional service footprint density. Backward integration into precision-machined conductor production reduces exposure to copper price volatility. For New Entrants and Emerging Players: Launch via containerized modular block configurations targeting data center developers in Phoenix and Northern Virginia seeking 50 MW phased increments. Focus white-space capture on mobile skid-mounted configurations for emergency restoration contracts where incumbent service networks remain underdeveloped. Pursue Canadian Standards Association certification as parallel compliance entry point for cross-border grid corridor projects. For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists with EPA gas handling certification because utility procurement criteria increasingly weight maintenance footprint density over equipment unit cost. Long-term viability favors acquisition targets with sealed-for-life design portfolios and established municipal utility relationships. Monitor FERC interconnection queue processing velocity as inflection indicator for high-voltage compact installation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sealed-for-Life Design Certification | California procurement standards now mandate 40-year maintenance intervals for new utility installations. |
| EPA Gas Reclamation Capacity Expansion | Tightened sulfur hexafluoride venting restrictions create recurring revenue streams from recovery operations. |
| Modular Containerized Block Fabrication | Northern Virginia data center developers require 50 MW phased capacity without full substation rebuilds. |
| Canadian Standards Association Certification | Cross-border US-Canada grid corridors demand parallel compliance for integrated transmission projects. |
| Digital Monitoring Platform Integration | Dissolved gas analysis sensors with SCADA convergence enable predictive maintenance contract pricing. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, EPC contractors, data center infrastructure directors, and high-voltage commissioning technicians with secondary validation from FERC filings, EIA transmission project databases, EPA enforcement records, and IEEE standards documentation. Bottom-up unit shipment estimates triangulated against top-down capital expenditure forecasts across voltage tiers and end-use segments.
Segment-weighting approaches applied differential growth assumptions across compact, modular, hybrid, and standard switchgear configurations by installation type and voltage level. The analytical framework modeled procurement velocity across utilities, renewable energy developers, industrial sites, and commercial facilities throughout the projection horizon. CAGRs derived from regression analysis against interconnection queue depth, replacement cycle timing, and state-level clean energy mandate progression. Forecast inputs incorporated EPA regulatory phase-in schedules and FERC Order 2023 implementation timelines.
Several conditions sit outside the modeled scope, including potential sulfur hexafluoride import restrictions, seismic event frequency in Pacific Coast corridors, and acceleration of solid-state circuit breaker substitution. Forecasts reflect documented assumptions about technician workforce availability and foundry capacity expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
Europe Electric Radiators Market
Electrical Power Equipment
India Gas Insulated Switchgear Market
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
Overhead Aluminium Conductors Market
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
Electric Radiators Market
Electrical Power Equipment
Motor Generator Set Market
Electrical Power Equipment
Instant Water Heater Market
Electrical Power Equipment
Alternate Current (AC) Drives Market
Electrical Power Equipment
Solid Vacuum Reclosers Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
Gas Insulated Switchgears (GIS) Market
Electrical Power Equipment
Electric Submersible Pump Cable Market
Electrical Power Equipment
Global Switchgear Monitoring Market
Electrical Power Equipment
Industrial Power Supply Market