
 South America Air Insulated Switchgear Market | 2026-2036
South America Air Insulated Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
South America Air Insulated Switchgear Market Insights
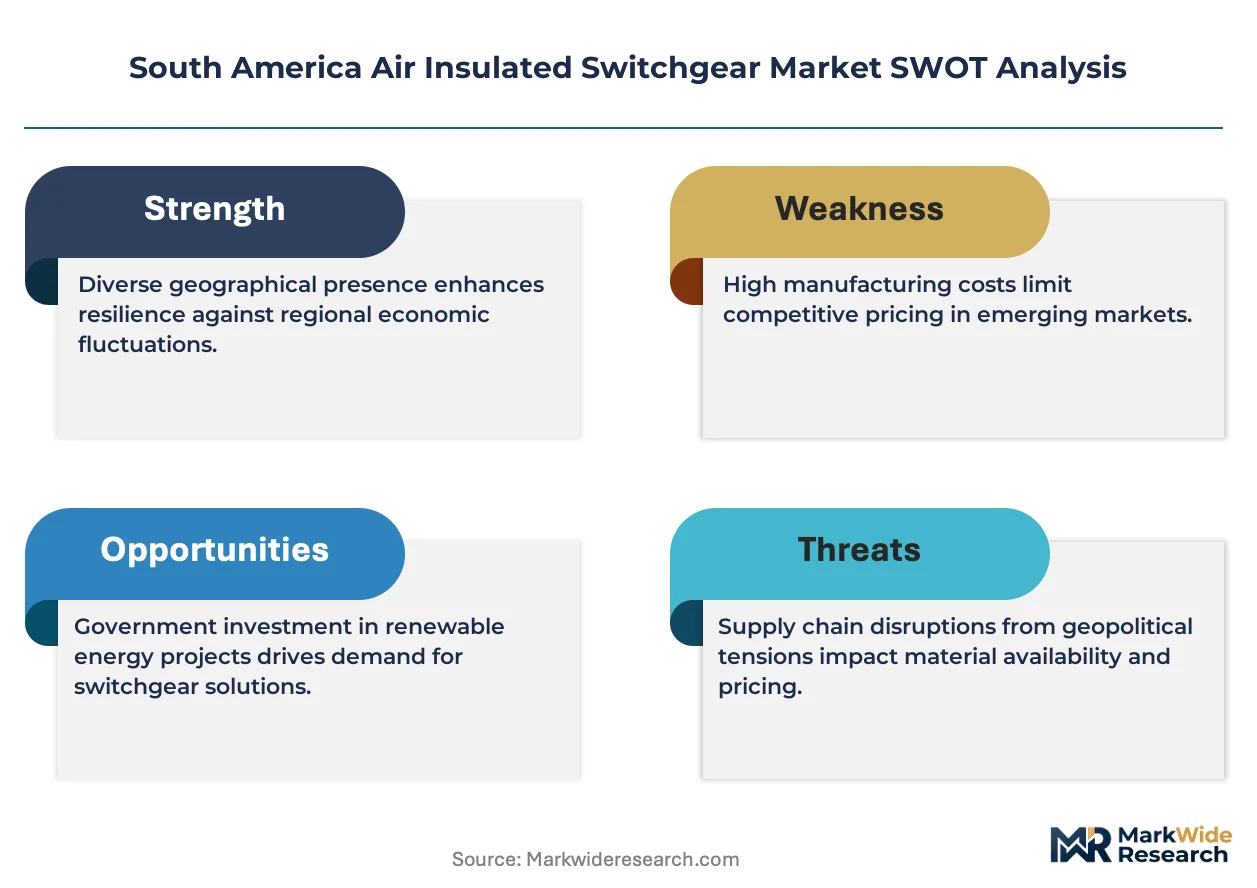
A shortage of certified high-voltage technicians is redrawing competitive dynamics across the South America Air Insulated Switchgear Market. Siemens AG leverages its regional training academies in Brazil to sustain a qualified installation workforce. ABB Ltd. anchors its position through backward integration into circuit breaker manufacturing. WEG competes aggressively on cost while dominating local supply chains for utility-scale projects.
Air insulated switchgear employs atmospheric air as the dielectric medium between live conductors and grounded enclosures, typically rated for voltages from 1 kV to 36 kV with metal-clad or metal-enclosed construction. The equipment isolates electrical faults, protects distribution networks, and enables safe maintenance access in substations and industrial facilities. Medium voltage assemblies command the largest revenue share due to their ubiquity in urban distribution networks across Brazil and Colombia. Renewable energy end users represent the fastest-expanding segment as wind farms in Argentina and solar parks in Chile require modular outdoor installations. Indoor configurations retain stable demand from commercial complexes in São Paulo and Santiago where space constraints favor compact switchgear lineups.
Brazil's national electric energy regulator ANEEL mandates periodic grid reliability audits that enforce IEC 62271-200 compliance for all new switchgear deployments. Argentina's Secretariat of Energy enforces IRAM standards that restrict market access to certified manufacturers. Chile's Superintendency of Electricity and Fuels imposes seismic resilience requirements that favor locally tested equipment. Stakeholders must monitor how evolving renewable interconnection codes across the Andean region reshape product certification timelines and procurement specifications.
Market Dynamics
ANEEL's grid reliability audits are compressing procurement cycles across Brazilian utilities, forcing distributors to hold larger certified inventory positions and reshaping working capital requirements throughout the regional supply chain.
Growth Catalysts
- ANEEL Reliability Mandates:Brazilian utilities must replace aging substation equipment under enforced IEC 62271-200 compliance deadlines, accelerating medium-voltage assembly orders.
- Argentina's RenovAr Auctions:Renewable energy tender mechanisms require air insulated switchgear for wind farm collector substations, creating dedicated procurement streams for modular outdoor configurations.
- Copper Mining Electrification:Chilean extraction operations in the Atacama region are upgrading power distribution infrastructure to support expanded processing capacity.
Market Restraints
- Certified Technician Scarcity:High-voltage installation and commissioning expertise concentrates in São Paulo and Santiago, limiting deployment velocity in secondary markets.
- Seismic Compliance Costs:Chile's Superintendency of Electricity and Fuels imposes localized testing requirements that extend certification timelines and raise non-recurring engineering expenses.
- SF6 Substitution Pressure:Environmental scrutiny of gas-insulated alternatives has not yet translated into proportional air insulated switchgear demand due to footprint and maintenance trade-offs.
Strategic Opportunities
- Colombian Grid Expansion:Rural electrification programs in Antioquia and Cundinamarca departments present untapped demand for cost-optimized medium-voltage distribution assemblies.
- Digitization Integration:Convergence of air insulated switchgear with IEC 61850-compliant monitoring systems enables predictive maintenance offerings that differentiate equipment suppliers.
- Peru Mining Corridor:Copper and gold extraction projects in the Andean foothills require robust outdoor switchgear resistant to altitude and contamination conditions.
Industry Challenges
- IRAM Certification Bottlenecks:Argentina's Secretariat of Energy restricts market access to locally tested manufacturers, creating six-to-nine month approval delays for new product introductions.
- Legacy Substation Integration:Urban utilities in Rio de Janeiro and Buenos Aires face complex retrofit requirements when interfacing new air insulated switchgear with decades-old protection relay schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Air Insulated Switchgear Market |
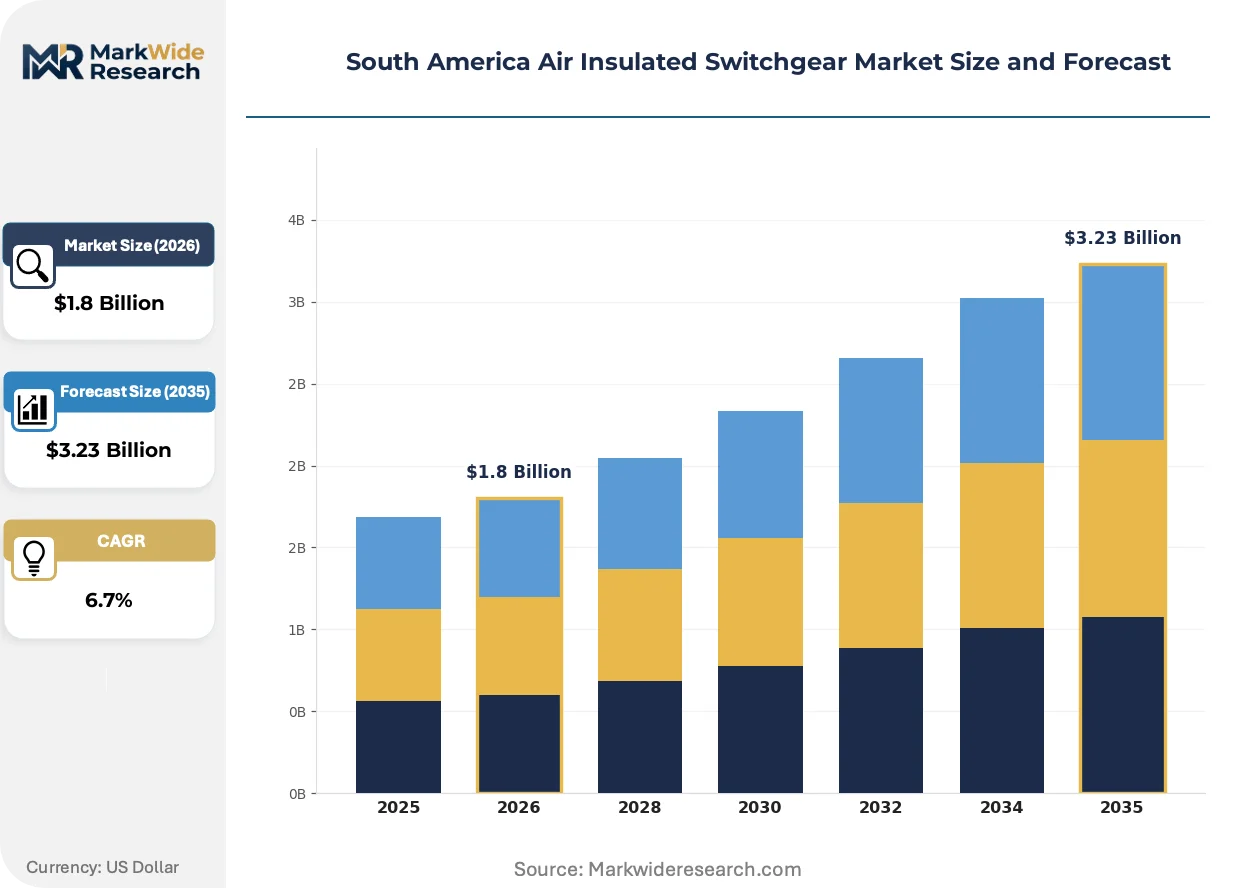
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Voltage, High Voltage, Low Voltage, Modular End User: Utilities, Industrial, Commercial, Renewable Energy Installation Type: Indoor, Outdoor, Substation, Portable Application: Power Distribution, Transmission, Renewable Integration, Smart Grid |
| Companies Covered | General Electric Company, ABB Ltd., Schneider Electric SE, Alstom SA, WEG, Siemens AG, Eaton Corporation, Crompton Greaves Ltd., Hitachi ABB Power Grids Ltd, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Air Insulated Switchgear Market Trends and Innovations
Equipment digitization and modular construction are reconfiguring how South American utilities specify and deploy air insulated switchgear across transmission and distribution networks.
Vacuum interrupter technology is displacing conventional air-break arc chutes in medium-voltage circuit breakers throughout Brazilian and Chilean installations. Mining operators and renewable developers favor vacuum mechanisms for reduced maintenance intervals and superior fault-current interruption capability. This transition is compressing demand for traditional arc-chamber spare parts while elevating supplier technical support requirements.
Argentina's IRAM 2470 standards revision is tightening short-circuit withstand requirements for metal-enclosed switchgear deployed in renewable interconnection projects. Manufacturers must redesign busbar configurations and enclosure bracing to meet elevated mechanical stress thresholds. Wind farm developers in Patagonia are responding by specifying type-tested assemblies from pre-qualified regional fabricators.
Utilities are consolidating procurement through framework agreements that bundle switchgear supply with multi-year maintenance and digital monitoring services. Distributors in São Paulo and Santiago are repositioning as lifecycle solution providers rather than transactional equipment vendors. This behavioral shift is most pronounced among Eletrobras subsidiaries and Colombian transmission operators seeking operational expenditure predictability.
South America Air Insulated Switchgear Market Segmentation
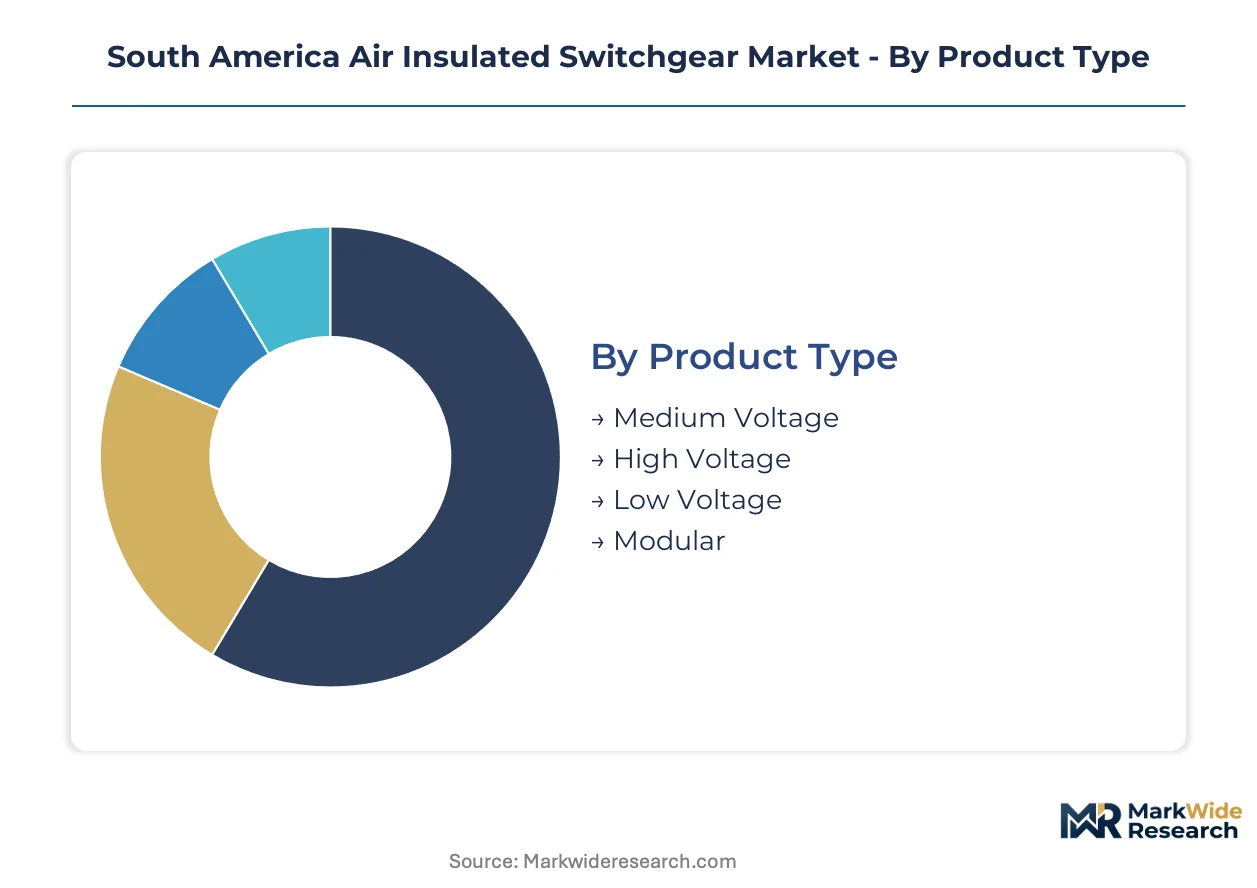
Segmentation in the South America Air Insulated Switchgear Market reveals how voltage ratings, end-use requirements, and installation environments dictate procurement specifications across Brazilian utilities, Chilean mining operations, and Argentine renewable projects. Understanding these divisions exposes where technical differentiation commands premium positioning versus where cost-optimized assemblies dominate.
Product Type:
Margin pools concentrate in medium-voltage assemblies where ANEEL-mandated grid reliability upgrades sustain pricing power, while high-voltage configurations face certification barriers that limit supplier participation.
- Medium Voltage:Metal-clad and metal-enclosed constructions rated 1 kV to 36 kV isolate faults in urban distribution networks. Brazilian utilities in São Paulo and Rio de Janeiro drive procurement volume through enforced IEC 62271-200 compliance deadlines for substation replacements.
- High Voltage:Atmospheric air dielectric systems above 36 kV require specialized seismic certification under Chile's Superintendency of Electricity and Fuels standards. Northern Chilean copper mining electrification projects in the Atacama region concentrate demand for these robust outdoor configurations.
- Low Voltage:Compact assemblies serve commercial building electrical rooms in Santiago and Buenos Aires where space constraints favor standardized panel designs.
- Modular:Factory-assembled skid-mounted units accelerate deployment timelines for Argentine wind farm collector substations under RenovAr auction schedules.
Medium Voltage holds installed capacity. Modular is rotating up the share rankings.
End User:
Customer type determines whether procurement flows through multi-year framework agreements with lifecycle service bundles or transactional spot purchases for discrete projects.
- Utilities:State-owned and private distribution companies in Brazil, Colombia, and Chile negotiate consolidated supply contracts that bundle switchgear with digital monitoring and predictive maintenance services.
- Industrial:Copper extraction operations and mineral processing facilities in Chile's Atacama and Peru's Andean foothills demand outdoor-rated equipment resistant to altitude contamination and seismic stress.
- Commercial:High-rise developments and shopping complexes in São Paulo and Santiago specify compact indoor lineups where footprint constraints override raw cost considerations.
- Renewable Energy:Wind developers in Argentine Patagonia and solar park operators in Chile's Atacama Desert require modular outdoor installations with rapid commissioning capabilities to meet interconnection deadlines.
Utilities anchor procurement volume. Renewable Energy is gaining share fastest.
Installation Type:
Physical deployment environment shapes enclosure specifications, seismic bracing requirements, and maintenance access design across the region's diverse terrain and climate zones.
- Indoor:Metal-enclosed switchgear lineups in commercial complexes and urban substations prioritize compact footprints and personnel safety interlocks. São Paulo's dense electrical infrastructure drives specification density for these configurations.
- Outdoor:Weather-resistant enclosures with corrosion-resistant finishes serve remote mining sites and renewable collector substations where building structures are economically impractical.
- Substation:Integrated bay configurations for utility-scale transformation and switching operations dominate Brazilian transmission expansion programs.
- Portable:Trailer-mounted or skid-based temporary installations support construction-phase electrification and emergency restoration across Colombia's rural grid expansion zones.
Outdoor configurations hold installed capacity. Portable is rotating up the share rankings.
Application:
Use case specificity determines whether assemblies emphasize fault interruption speed, distribution automation compatibility, or renewable interconnection flexibility.
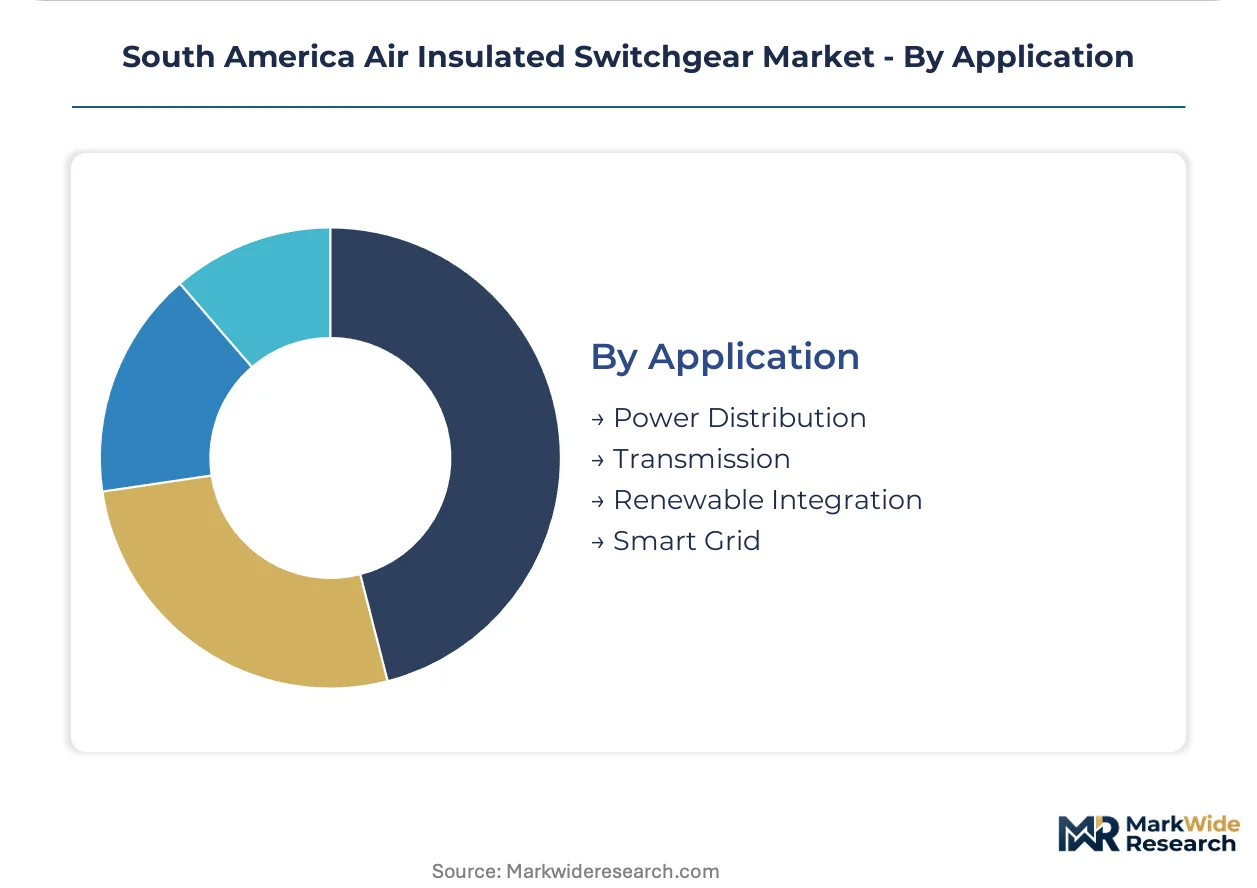
- Power Distribution:Ring-main units and feeder circuits manage load segmentation across Brazilian urban distribution networks. ANEEL reliability audits enforce periodic replacement cycles that sustain equipment demand.
- Transmission:High-capacity switching bays interface with regional transmission networks in Colombia and Chile where voltage stability requirements dictate specialized breaker specifications.
- Renewable Integration:Collector substation assemblies aggregate generation from dispersed wind turbines and solar inverters. Argentine IRAM 2470 standards revisions tighten short-circuit withstand requirements for these installations.
- Smart Grid:IEC 61850-compliant switchgear with embedded monitoring sensors enables predictive maintenance and remote fault location for utilities pursuing operational expenditure predictability.
Power Distribution holds installed capacity. Smart Grid is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANEEL, Brazil's national electric energy regulator, mandates IEC 62271-200 compliance for all new switchgear deployments through enforced grid reliability audits. This regulatory anchor compresses procurement cycles across South America's largest market while reshaping inventory requirements throughout the regional supply chain.
Brazil
São Paulo and Rio de Janeiro utilities drive medium-voltage assembly orders through substation replacement programs. ANEEL's reliability mandates enforce periodic equipment audits that accelerate procurement from certified distributors. Eletrobras subsidiaries consolidate purchasing through framework agreements bundling switchgear with digital monitoring services.
Chile
Copper mining electrification in the Atacama region concentrates demand for high-voltage outdoor configurations. The Superintendency of Electricity and Fuels imposes seismic resilience requirements that favor locally tested equipment. Northern extraction operations upgrade power distribution infrastructure to support expanded processing capacity.
Argentina
RenovAr auction mechanisms require air insulated switchgear for wind farm collector substations across Patagonia. The Secretariat of Energy enforces IRAM standards that restrict market access to certified manufacturers. Wind developers specify type-tested assemblies from pre-qualified regional fabricators to meet interconnection deadlines.
Colombia
Rural electrification programs in Antioquia and Cundinamarca departments present demand for cost-optimized medium-voltage distribution assemblies. Transmission operators pursue operational expenditure predictability through consolidated supply contracts. Secondary markets face deployment velocity constraints from technician scarcity concentrated in Bogotá.
Peru
Copper and gold extraction projects in the Andean foothills require robust outdoor switchgear resistant to altitude and contamination conditions. Mining corridors concentrate procurement for weather-resistant enclosures with corrosion-resistant finishes. Remote site electrification favors modular skid-mounted units over permanent building structures.
South America Air Insulated Switchgear Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the South America Air Insulated Switchgear Market. The vendor base organizes into three tiers: multinational industrial conglomerates with integrated manufacturing footprints, regional specialists dominating local supply chains, and mid-scale fabricators competing on price for standardized assemblies. Strategic moves center on backward integration into circuit breaker production and digitization service bundling.
Among European-based industrial conglomerates, ABB Ltd., Siemens AG, and Schneider Electric SE exemplify the technology-forward archetype. These companies anchor their positioning through regional training academies and lifecycle solution portfolios. WEG represents the Brazil-based regional specialist model, competing aggressively on cost while capturing utility-scale procurement through dominant local supply chain relationships.
| Leading Market Players |
|---|
| General Electric Company |
| ABB Ltd. |
| Schneider Electric SE |
| Alstom SA |
| WEG |
| Siemens AG |
| Eaton Corporation |
| Crompton Greaves Ltd. |
| Hitachi ABB Power Grids Ltd |
| Others |
Pricing and Supply Chain Analysis
Long-term framework agreements bundling switchgear supply with multi-year maintenance services lock in both supply access and price visibility for Brazilian utilities navigating ANEEL-mandated replacement cycles. These contracts compress working capital volatility while elevating switching costs for buyers seeking alternative suppliers.
Pricing Analysis
Brazilian metropolitan utilities pay 15-25% premiums over Andean counterparts for medium-voltage assemblies due to ANEEL certification requirements and concentrated technician availability. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates Eletrobras subsidiaries from private distributors and secondary market resellers. Cost compression in the economy tier is intensifying because Argentine IRAM bottlenecks strand imported inventory. Industrial mining operators in Chile's Atacama region exhibit lowest price sensitivity due to project finance structures that embed equipment costs within capital expenditure envelopes.
Supply Chain Analysis
Vacuum interrupter manufacturing concentrates in Germany, Japan, and Brazil, creating single-source vulnerability for regional switchgear assemblers dependent on imported arc-quenching mechanisms. Copper busbar fabrication and sheet metal enclosure production draw from Chilean mining output and Brazilian steel mills respectively. Tariff exposure runs through Mercosur external border adjustments affecting Argentine import flows. Distribution runs through São Paulo-based distributors holding certified inventory positions for ANEEL-compliant rapid deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gas-insulated switchgear substitution pressure demands defensive positioning from air insulated incumbents, as environmental scrutiny of SF6 emissions creates technology-switch risk despite footprint trade-offs.
For Market Incumbents: Secure backward integration into vacuum interrupter production to decouple from German and Japanese component dependencies. Anchor digitization service bundles with IEC 61850-compliant monitoring to elevate switching costs against SF6 alternative vendors targeting renewable interconnection projects. For New Entrants and Emerging Players: Anchor in Colombia's rural electrification corridors where technician scarcity has slowed incumbent deployment velocity. Target Antioquia and Cundinamarca departments with skid-mounted modular assemblies bypassing complex urban retrofit requirements. Lead with cost-optimized medium-voltage lineups undercutting framework agreement pricing. For Investors and Strategic Acquirers: Regional fabricators with pre-qualified IRAM and ANEEL certification pipelines represent acquisition targets with embedded regulatory moats. Long-term viability hinges on digitization integration capabilities across the projection horizon. Monitor RenovAr auction award velocity as inflection indicator for Argentine demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Interrupter Production | Captive supply of arc-quenching mechanisms insulates margins from German and Japanese component pricing. |
| IEC 61850-Compliant Monitoring Platform Launch | Predictive maintenance bundling differentiates offerings for Eletrobras subsidiaries seeking opex predictability. |
| Seismic Certification Investment | Chile Superintendency compliance unlocks high-voltage mining electrification procurement in Atacama region. |
| Modular Skid-Mounted Assembly Expansion | Factory pre-assembly accelerates Argentine wind farm commissioning under RenovAr interconnection deadlines. |
| Regional Training Academy Establishment | Certified technician pipelines address scarcity constraints compressing deployment velocity in secondary markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ANEEL regulatory filings, IEC standards documentation, and utility procurement databases through structured interviews with substation engineering directors, distributor inventory managers, and mining project electrification leads. Bottom-up assembly demand estimates triangulate against top-down grid investment forecasts from national regulator capital expenditure disclosures.
Segmentation dimensions modeled span voltage rating tiers, end-user archetypes, installation environment types, and application categories across the projection horizon. CAGRs derive from equipment replacement cycle analysis, renewable interconnection queue trajectories, and mining electrification project pipelines. Forecast inputs incorporate ANEEL audit enforcement intensity and IRAM certification timeline assumptions.
Decision-makers should treat outputs as directional under sustained ANEEL compliance enforcement and RenovAr auction continuity; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as SF6 regulatory pressure and seismic standard revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Middle East and Africa Hazardous Location Motor Starters Market
Electrical Power Equipment
Low Voltage Protection Control Market
Electrical Power Equipment
MV Protection Relay Market
Electrical Power Equipment
Gas Water Heater Market
Electrical Power Equipment
Immersion Heater Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
Asia Pacific Gas Insulated Switchgear Market
Electrical Power Equipment
Magnetic Ballast Market
Electrical Power Equipment
Power Strip Market
Electrical Power Equipment
Battery Charger Market
Electrical Power Equipment
North America Surge Arresters Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Global Lightning Arrester Market
Electrical Power Equipment
Bucket Water Heater Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
Global Electric Power Substation Automation Market