
 Europe Electric Vehicle Solid State Battery Market | 2026-2036
Europe Electric Vehicle Solid State Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle Solid State Battery Market Analytics
Luxury passenger vehicle electrification is decoupling from conventional lithium-ion supply chains as European OEMs prioritize energy density targets above 400 Wh/kg. Blue Solutions anchors France's polymer solid-state segment through its Bolloré Group manufacturing heritage. Robert Bosch GmbH leverages Stuttgart-based R&D infrastructure to sustain German automotive supplier relationships. Samsung SDI Co., Ltd. competes from Korean headquarters while extending European pilot production capabilities.
Europe Electric Vehicle Solid State Batteries replace flammable liquid electrolytes with ceramic, glass, or sulfide ionic conductors to eliminate thermal runaway while enabling lithium metal anodes. Cell manufacturing requires dry-room environments below -40°C dew point and precision thin-film deposition for ceramic electrolyte layers. Polymer solid-state configurations currently occupy established production lines for early commercial deployment. Large-format technology leads capital allocation as automakers demand pack-level integration above 100 kWh. Fleet operator applications represent the fastest-growing end-user channel as logistics companies seek extended-range commercial vehicles with reduced fire risk profiles.
The EU Green Deal, F-Gas Regulation, and CE marking under the EU Battery Directive collectively mandate carbon footprint disclosure and recycled content thresholds that reshape cell chemistry selection. ECHA's REACH framework restricts sulfide electrolyte precursor imports, forcing European producers toward localized material refining. Stakeholders must monitor solid-state pilot line yield rates and OEM qualification timelines to calibrate capacity commitments against polymer-to-ceramic technology transitions.
Market Dynamics
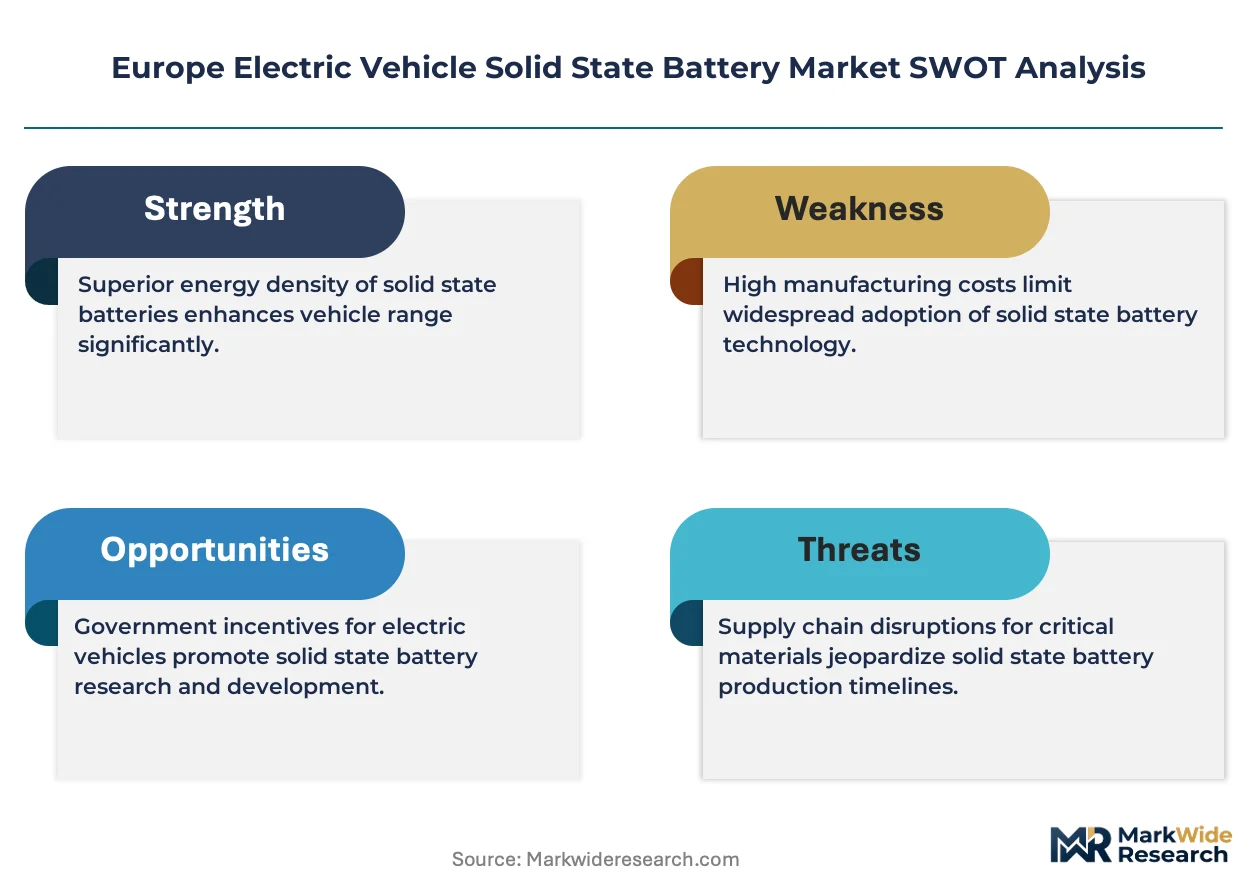
EU Green Deal carbon mandates and F-Gas Regulation phase-down schedules are forcing European OEMs to abandon liquid electrolyte chemistries before solid-state manufacturing readiness matures, creating a supply-demand timing mismatch that concentrates investment in polymer interim solutions.
Growth Catalysts
- EU Battery Directive recycled content thresholds:Mandates for recovered lithium and cobalt are accelerating closed-loop supply chain investments that favor solid-state architectures with simpler material separation.
- German automotive manufacturing clusters:Stuttgart and Munich production ecosystems are anchoring pilot line qualification programs for premium passenger vehicle platforms.
- Sulfide electrolyte energy density potential:Ceramic ionic conductors enable lithium metal anodes that push cell-level targets beyond 400 Wh/kg, satisfying range requirements for electric luxury sedans.
Market Restraints
- Capital intensity of dry-room infrastructure:Dew point requirements below -40°C demand specialized HVAC and contamination control systems that inflate gigafactory construction costs.
- ECHA REACH restrictions on sulfide precursors:Import limitations for lithium sulfide and phosphorus sulfide compounds are constraining European producers to localized refining capacity that remains underdeveloped.
- Polymer electrolyte performance ceiling:Room-temperature ionic conductivity limitations in polyethylene oxide matrices are capping early commercial deployments to low-C-rate applications.
Strategic Opportunities
- French battery gigafactory expansion:Verkor and Automotive Cells Company facilities in Dunkirk and Douai are creating anchor demand for regional solid-state cell supply.
- Fleet operator extended-range commercial vehicles:Logistics companies operating cross-border EU routes are specifying reduced fire risk profiles that favor solid-state thermal stability.
- CE marking pathway convergence:Harmonized safety certification standards under the EU Battery Directive are reducing duplicate testing burdens for multi-market product launches.
Industry Challenges
- Thin-film deposition technician scarcity:Precision ceramic layer manufacturing requires specialized vacuum coating expertise that European labor markets currently undersupply.
- OEM qualification timeline compression:Automotive validation cycles spanning 24-36 months are misaligned with investor expectations for near-term revenue realization.
- Pack-level integration complexity:Large-format solid-state cells demand redesigned thermal management architectures that disrupt existing module assembly workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle Solid State Battery Market |
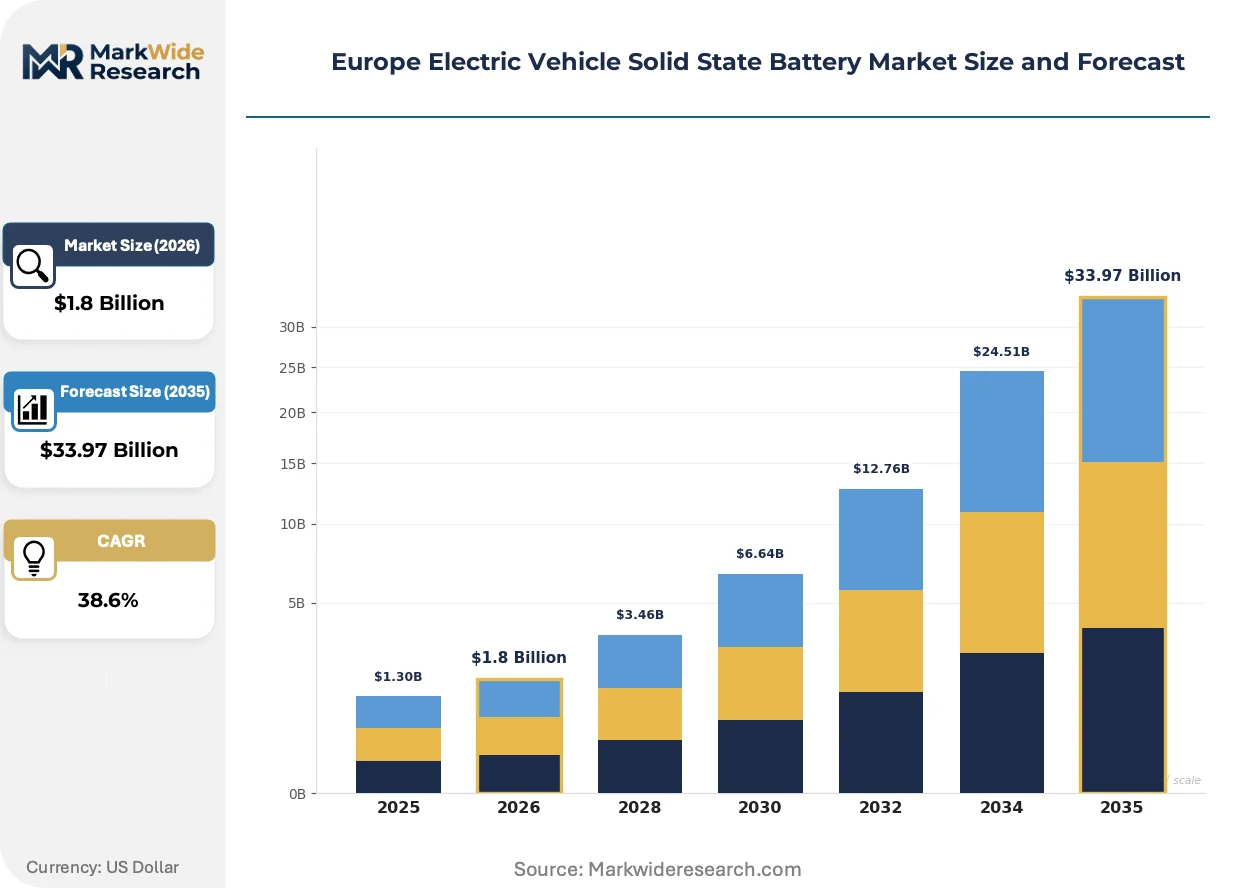
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $33.97 Billion |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Metal, Polymer, Hybrid, Others Technology: Non-volatile, Thin-film, Microbattery, Large-format End User: OEMs, Fleet Operators, Aftermarket Providers, Ride-sharing Services Application: Passenger Vehicles, Commercial Vehicles, Buses, Two-wheelers |
| Companies Covered | Blue Solutions, Basquevolt, Ilika, SOLiTHOR, ProLogium Europe, Robert Bosch GmbH, Samsung SDI Co., Ltd., LG Chem Ltd., Solid Power, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle Solid State Battery Market Evolving Landscape
Manufacturing process innovation is outpacing materials science breakthroughs in European solid-state battery development, with dry electrode coating and precision lamination techniques currently absorbing more capital than next-generation electrolyte formulations.
Sulfide-based ceramic electrolytes are absorbing the majority of French and German R&D allocation as automakers prioritize ionic conductivity metrics over polymer flexibility. Premium passenger vehicle OEMs in Stuttgart and Munich are integrating these materials into A-sample prototype packs for 2027 platform launches. The technology is absorbing engineering resources previously directed toward silicon-anode liquid cell optimization, compressing conventional lithium-ion improvement timelines.
EU F-Gas Regulation phase-down schedules are mandating alternative thermal management chemistries in battery production facilities. Industrial refrigeration suppliers are retrofitting European gigafactories with CO2-based cooling systems to maintain dry-room specifications. Cell manufacturers in Germany's Baden-Württemberg region are most exposed, accelerating capital deployment into climate-controlled infrastructure ahead of 2030 compliance deadlines.
Logistics fleet operators are consolidating procurement decisions at the European level rather than national subsidiaries, centralizing solid-state battery supplier selection criteria. This concentration is displacing fragmented national tendering processes that previously favored incumbent liquid-cell relationships. The shift is most visible in German and Dutch long-haul trucking corridors where total cost of ownership calculations now incorporate fire risk insurance differentials.
Europe Electric Vehicle Solid State Battery Market Segmentation
Solid-state battery deployment in Europe fragments across chemistry choices, manufacturing scales, and customer procurement patterns. Each segmentation dimension carries distinct capital requirements and regulatory exposure that reshape competitive positioning.
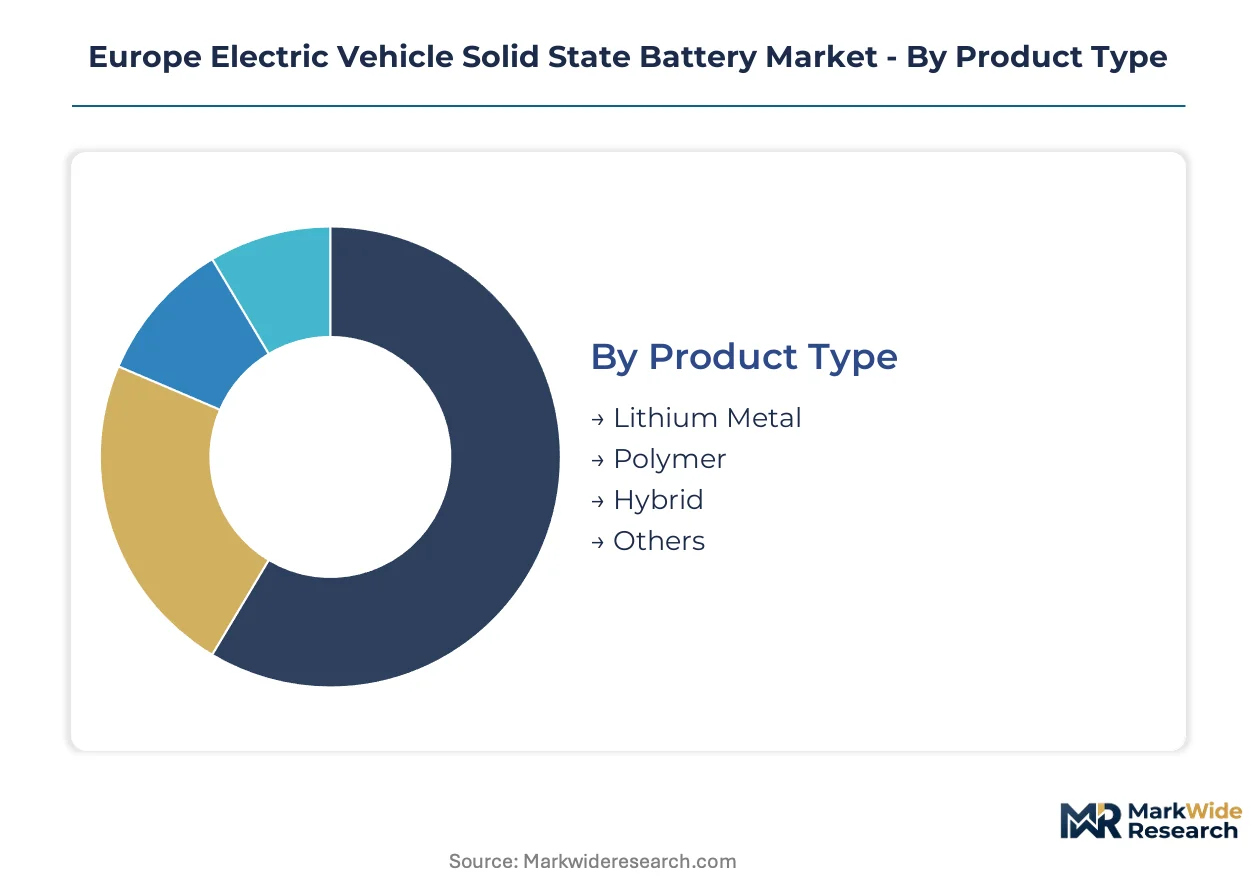
Product Type:
Capital intensity varies sharply across electrolyte architectures, with ceramic processing demanding dry-room infrastructure that polymer configurations avoid.
- Lithium Metal:Anode architecture pairs ceramic or sulfide electrolytes with pure lithium foil to achieve energy density above 400 Wh/kg. German premium OEMs in Stuttgart are prioritizing this chemistry for flagship sedan platforms where range specifications dominate procurement criteria.
- Polymer:Polyethylene oxide matrices operate at moderate temperatures with established roll-to-roll manufacturing equipment. Blue Solutions in France leverages this lower-capital pathway for early commercial deployment while ceramic supply chains mature.
- Hybrid:Composite electrolytes combine polymer mechanical flexibility with ceramic ionic conductivity in layered architectures.
- Others:Emerging glass-ceramic and halide formulations occupy pre-pilot research stages.
Most installed capacity flows through Polymer. Expansion is steepest in Lithium Metal.
Technology:
Manufacturing scale determines which technology platforms attract European gigafactory investment, with large-format cells commanding module-level integration resources.
- Large-format:Prismatic cells exceeding 100 Ah enable direct pack integration without module assembly, reducing connection complexity and thermal management overhead. French Automotive Cells Company and Verkor facilities in Dunkirk are specifying this format for commercial vehicle contracts.
- Thin-film:Vacuum-deposited ceramic layers below 50 micrometers achieve dense packing in constrained spaces. Robert Bosch GmbH pilots this approach for premium passenger vehicle prototypes where volumetric efficiency outweighs cost sensitivity.
- Non-volatile:Solid electrolyte architectures eliminate flammable components entirely, satisfying EU Battery Directive safety certification pathways.
- Microbattery:Sub-watt-hour cells target auxiliary power and sensor applications in vehicle electrical architectures.
Production volume concentrates in Large-format. Thin-film is gaining share fastest among technology platforms.
End User:
Procurement consolidation patterns separate fleet-level tenders from fragmented aftermarket channels, reshaping supplier relationship structures.
- Fleet Operators:Logistics companies operating German-Dutch long-haul corridors are centralizing European procurement decisions to leverage fire risk insurance differentials in total cost calculations. Reduced thermal runaway profiles in solid-state architectures translate directly to premium reductions at fleet scale.
- OEMs:Stuttgart and Munich automotive manufacturers qualify cell suppliers through 24-36 month validation cycles, locking in capacity commitments ahead of platform launches.
- Aftermarket Providers:Independent service networks target replacement battery demand as first-generation European EVs age out of warranty coverage.
- Ride-sharing Services:Urban mobility platforms prioritize rapid charging compatibility and cycle life durability over absolute energy density.
Contract value concentrates with OEMs. Fleet Operators are expanding most quickly as procurement centralization accelerates.
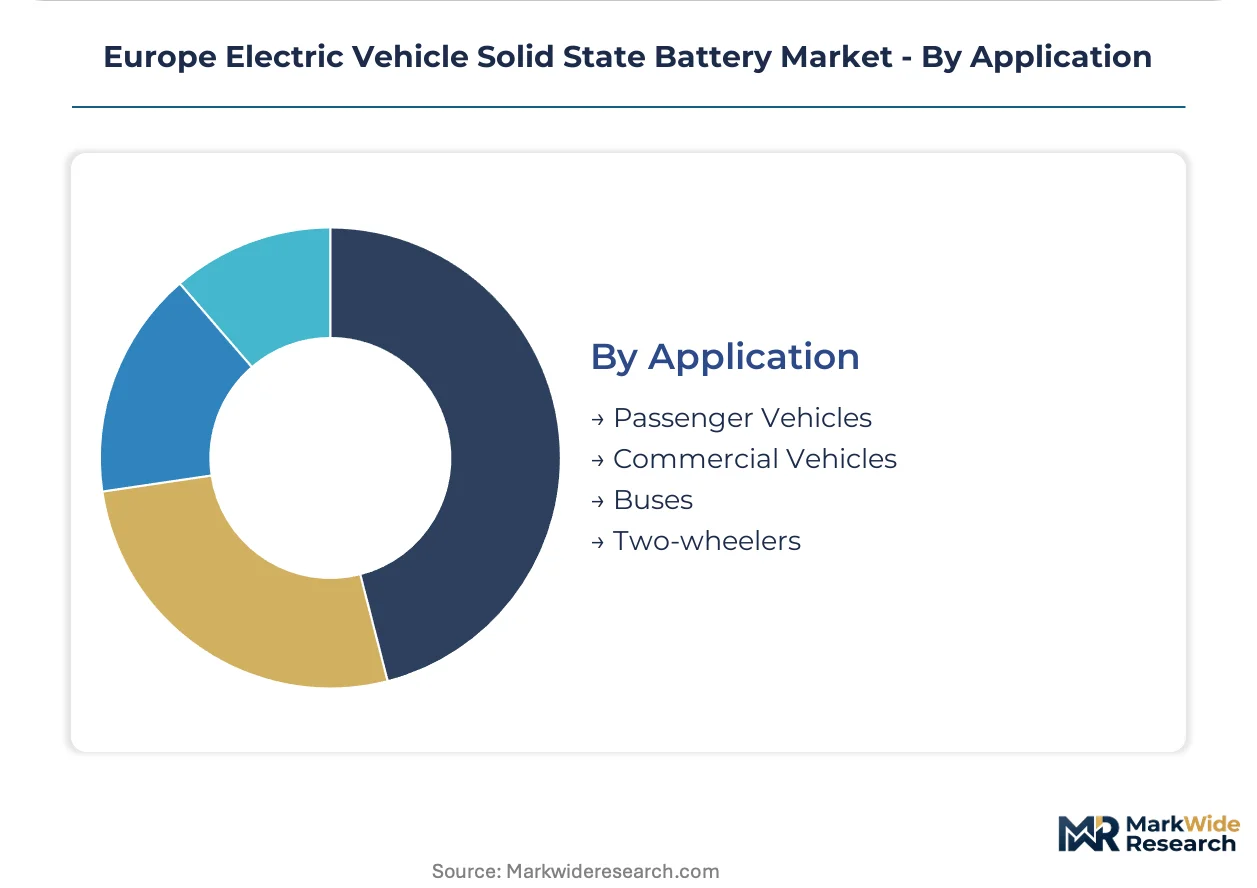
Application:
Vehicle class determines pack size requirements and thermal management complexity, with commercial platforms demanding the highest absolute capacity.
- Commercial Vehicles:Heavy-duty trucks and vans require pack-level integration above 100 kWh for cross-border EU route completion. Fleet operators specify solid-state configurations to minimize downtime from thermal management derating in summer corridor conditions.
- Passenger Vehicles:Premium sedans and SUVs in the German luxury segment prioritize energy density for range parity with combustion equivalents. OEM qualification programs are concentrating R&D resources on this application.
- Buses:Municipal transit authorities specify standardized pack formats for depot-based charging infrastructure.
- Two-wheelers:Electric motorcycles and scooters represent lower absolute demand but faster replacement cycles.
Revenue concentration sits with Passenger Vehicles. Commercial Vehicles are climbing the fastest as logistics electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production is migrating toward jurisdictions where dry-room energy costs and REACH compliance burdens create arbitrage opportunities for solid-state cell manufacturers. The EU Green Deal's carbon border adjustments are redrawing facility location decisions across the continent.
Germany
Baden-Württemberg's automotive supplier ecosystem anchors pilot line investments from Robert Bosch GmbH and Samsung SDI Co., Ltd. The KBA's type-approval protocols for novel battery chemistries compress validation timelines for Stuttgart-based OEMs. Munich manufacturing clusters are absorbing sulfide electrolyte R&D talent from liquid-cell optimization programs.
France
Dunkirk and Douai gigafactory corridors concentrate demand from Automotive Cells Company and Verkor for large-format solid-state supply. ANSM oversight of industrial chemical safety intersects with EU Battery Directive CE marking pathways. Blue Solutions leverages Bolloré Group polymer manufacturing heritage in Brittany for early commercial deployment.
United Kingdom
Oxfordshire and Midlands battery research facilities attract Ilika's thin-film expertise for microbattery applications. The UK's post-Brexit chemicals regulatory framework diverges from ECHA REACH schedules, creating precursor import complexity. Warwick Manufacturing Group anchors university-industry partnerships for solid-state technician training pipelines.
Netherlands
Eindhoven's high-tech systems corridor hosts SOLiTHOR's R&D operations for maritime and aviation solid-state applications. Dutch long-haul logistics operators centralize European procurement decisions at Rotterdam headquarters, favoring fire-risk-reduced cell architectures. The country's grid interconnection capacity supports energy-intensive dry-room facility operations.
Spain
Basquevolt anchors the Basque Country's emerging battery materials cluster with regional government co-investment structures. Spanish automotive component suppliers in Catalonia are retooling for solid-state pack integration workflows. The country's renewable energy surplus positions dry-room facilities for carbon footprint compliance under EU Green Deal thresholds.
Europe Electric Vehicle Solid State Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with polymer electrolyte incumbents holding established production relationships while sulfide-ceramic developers compete on qualification timelines. The market exhibits tiered concentration: integrated automotive suppliers control premium passenger vehicle channels, independent cell developers serve fleet operator tenders, and materials specialists capture precursor supply positions. Two strategic archetypes dominate—vertically integrated chemistry-to-cell producers and modular technology licensors. Competitive moves concentrate on pilot line yield improvement and OEM validation cycle acceleration.
Within the European headquarters tier, Blue Solutions and Basquevolt occupy positions representing polymer and sulfide-ceramic pathways respectively. Robert Bosch GmbH anchors German automotive supplier relationships through Stuttgart-based R&D infrastructure. Samsung SDI Co., Ltd. exemplifies the Asia-headquartered, Europe-extended model, competing from Korean headquarters while building continental pilot capabilities. Ilika represents the UK-based thin-film specialization archetype, distinct from large-format prismatic developers.
| Leading Market Players |
|---|
| Blue Solutions |
| Basquevolt |
| Ilika |
| SOLiTHOR |
| ProLogium Europe |
| Robert Bosch GmbH |
| Samsung SDI Co., Ltd. |
| LG Chem Ltd. |
| Solid Power, Inc. |
| Others |
Value Network & Pricing Analysis
Captive sulfide precursor refining in France and Germany anchors both supply security and pricing power for European solid-state cell producers facing ECHA REACH import restrictions. This backward integration choice insulates qualified suppliers from spot-market volatility while forcing higher capital commitments that transmit into OEM contract premiums.
Pricing Analysis
Distributor margins in the polymer electrolyte segment compress under pressure from Blue Solutions' direct-to-OEM volume contracts. Pricing stratifies across ceramic qualification grade, with sulfide-based cells commanding premium positioning against polyethylene oxide alternatives. Cost compression in the polymer tier intensifies because Korean competitors extend European pilot capabilities without local dry-room overhead. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership procurement models, while premium passenger vehicle OEMs prioritize energy density over unit economics.
Supply Chain Analysis
Lithium sulfide feedstock rests on German and French localized refining capacity that remains underdeveloped relative to pilot line demand. Ceramic electrolyte manufacturing draws from South Korean and Japanese specialty chemical producers for precision deposition equipment. Single-source vulnerability concentrates in thin-film vacuum coating systems where European labor markets undersupply qualified technicians. Distribution runs through Stuttgart and Munich automotive supplier clusters for OEM qualification, with Dunkirk and Douai gigafactories anchoring fleet operator direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon border adjustments compound demand for solid-state architectures as liquid electrolyte imports face escalating compliance costs. This regulatory compounding accelerates OEM abandonment of conventional lithium-ion supply chains before solid-state manufacturing readiness matures.
For Market Incumbents: Cement sulfide electrolyte qualification timelines ahead of Korean competitor European pilot scale-up. Prioritize captive refining capacity in Baden-Württemberg to defend against ECHA REACH restriction escalation. Lock fleet operator procurement consolidation through fire-risk insurance partnership structures.
For New Entrants and Emerging Players: Logistics fleet operators represent the most penetrable channel given centralized Rotterdam procurement decisions and unmet demand for extended-range commercial vehicles. Target thin-film technician training partnerships with Warwick Manufacturing Group to bypass labor scarcity constraints. Lead with thermal stability certification to differentiate from polymer interim solutions.
For Investors and Strategic Acquirers: Roll-up economics work for sulfide-ceramic technology licensors because OEM qualification cycles create sticky multi-year revenue visibility. Five-to-ten-year viability hinges on dry-room yield rate improvement rather than materials science breakthrough. Watch pilot line defect rate trends as the inflection signal for capacity commitment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Dry-Room Infrastructure Expansion | Baden-Württemberg facilities secure F-Gas Regulation compliance ahead of 2030 deadlines. |
| Sulfide Precursor Backward Integration | French and German refining capacity reduces ECHA REACH import dependency exposure. |
| OEM Platform Qualification Partnership | Stuttgart and Munich automotive clusters compress 24-36 month validation timelines. |
| Fleet Operator Insurance Integration | Rotterdam-based logistics procurement leverages fire-risk premium differentials. |
| Thin-Film Technician Training Pipeline | Warwick Manufacturing Group addresses European vacuum coating expertise scarcity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with solid-state cell engineering directors, OEM platform procurement managers, fleet operator sustainability leads, and ECHA regulatory affairs specialists against secondary validation. Sources included EU Battery Directive CE marking databases, ECHA REACH restriction filings, automotive production registration data, and gigafactory construction permit records. Bottom-up cell manufacturing capacity estimates triangulated against top-down OEM platform electrification targets.
Segment-weighting applied chemistry type, manufacturing format, and end-user procurement consolidation patterns across the projection horizon. Vehicle class, energy density tier, and regional production cluster dimensions shaped volume allocation. CAGRs derived from installation base expansion curves calibrated to OEM qualification timeline data and dry-room infrastructure deployment schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sulfide electrolyte yield breakthroughs and ECHA REACH restriction enforcement intensity. Assumptions reflect documented pilot line performance and regulatory filing trajectories. A small set of triggers—OEM A-sample pack acceptance rates, fleet operator insurance differential crystallization, and thin-film technician graduation volumes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
Electric Vehicle Battery Coolant Market
EV Batteries
Asia Pacific Electric Vehicle Battery Manufacturing Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Materials Market
EV Batteries
Germany Electric Vehicle Battery Manufacturing Market
EV Batteries
China Electric Vehicle Battery Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Market
EV Batteries
India EV Battery Pack Market
EV Batteries
Automotive Rechargeable Battery Market
EV Batteries
Electronic Vehicle (EV) Cells Market
EV Batteries
Auto Storage Battery Market
EV Batteries
ASEAN Countries Electric Vehicle Battery Manufacturing Market
EV Batteries
Europe Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Europe LFP Battery Pack Market
EV Batteries
Middle East and Africa Electric Vehicle Battery Manufacturing Market