
 Global Aerospace Adhesives and Sealants Market | 2026-2036
Global Aerospace Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerospace Adhesives and Sealants Market Intelligence
Demand from commercial aircraft OEMs for cabin interior applications is consolidating around materials offering superior fire, smoke, and toxicity (FST) performance. Henkel AG & Co KGaA leverages its extensive portfolio to serve diverse airframe bonding needs across multiple aircraft programs. Solvay specializes in high-performance structural adhesives for composite-intensive platforms. 3M sustains a strong market position through its broad product lines for both structural and non-structural uses.
Aerospace adhesives and sealants are specialized polymer-based formulations designed to bond and seal aircraft components. These materials must withstand extreme temperature fluctuations, high stress, and exposure to aviation fluids. Epoxy-based products dominate structural airframe bonding applications due to their high strength-to-weight ratio. Silicone and polyurethane sealants are critical for fuel systems and cabin interiors, valued for their flexibility and environmental resistance.
Product qualification is governed by standards from the US Federal Aviation Administration (FAA) and compliance with chemical regulations like the EU's REACH. These frameworks mandate rigorous testing for flammability and mechanical performance, influencing material selection. Future material development will center on creating sustainable, lower-VOC formulations that meet evolving environmental mandates without compromising safety and performance.
Market Dynamics
The aerospace adhesives and sealants market is fundamentally shaped by the airframe manufacturing sector's transition to lightweight composite materials. This shift away from traditional metallic structures necessitates advanced bonding formulations that can join dissimilar materials while contributing to overall weight reduction and fuel efficiency goals.
Growth Catalysts
- Advanced Composite Adoption:The increasing use of carbon fiber reinforced plastics (CFRP) in new aircraft platforms like the Airbus A350 and Boeing 787 directly stimulates demand for high-performance epoxy-based structural adhesives.
- Space Sector Expansion:A rising tempo in satellite constellation deployment and commercial launch services creates a dedicated market for adhesives and sealants qualified for the extreme thermal cycles and vacuum of space.
- Domestic Manufacturing Initiatives:Government policies in nations such as India and China aimed at building sovereign aerospace production capabilities are expanding the geographic footprint of demand beyond established North American and European hubs.
Market Restraints
- Raw Material Price Volatility:The cost structure for many adhesives is directly exposed to fluctuations in petrochemical-derived inputs, such as epoxy resins and polyurethane precursors, creating margin pressure for manufacturers.
- Stringent Qualification Cycles:New product introduction is constrained by the lengthy and expensive testing and certification processes mandated by aviation authorities like the FAA and EASA, which can take years to complete.
- Technical Performance Ceilings:Current material science faces limitations in developing adhesives that simultaneously meet the extreme high-temperature and mechanical stress requirements for emerging hypersonic and reusable space vehicle applications.
Strategic Opportunities
- Urban Air Mobility (UAM):The development of electric vertical takeoff and landing (eVTOL) aircraft for urban transport presents a new, high-volume application for lightweight structural adhesives and sealants.
- Sustainable Formulations:The EU's REACH framework creates a significant commercial opportunity for manufacturers to develop and market next-generation, low-VOC and chrome-free formulations that meet stricter environmental and health standards.
- MRO Market in Emerging Regions:Expanding aircraft fleets in the Middle East and Southeast Asia drive growth in the maintenance, repair, and overhaul (MRO) segment, opening new channels for qualified sealant and repair adhesive sales.
Industry Challenges
- Regulatory Divergence:Managing product portfolios becomes complex due to differing chemical control regulations, such as the EU's REACH and the US EPA's TSCA, which can require separate formulations for different markets.
- Limited Material Shelf Life:Many high-performance adhesives and sealants have restricted working lives and require refrigerated storage, posing significant logistical challenges and increasing the risk of material waste across the supply chain.
- Specialized Application Skills Gap:A shortage of technicians trained in the meticulous surface preparation, mixing, and application techniques required for structural bonding can lead to improper application and potential bond-line failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerospace Adhesives and Sealants Market |
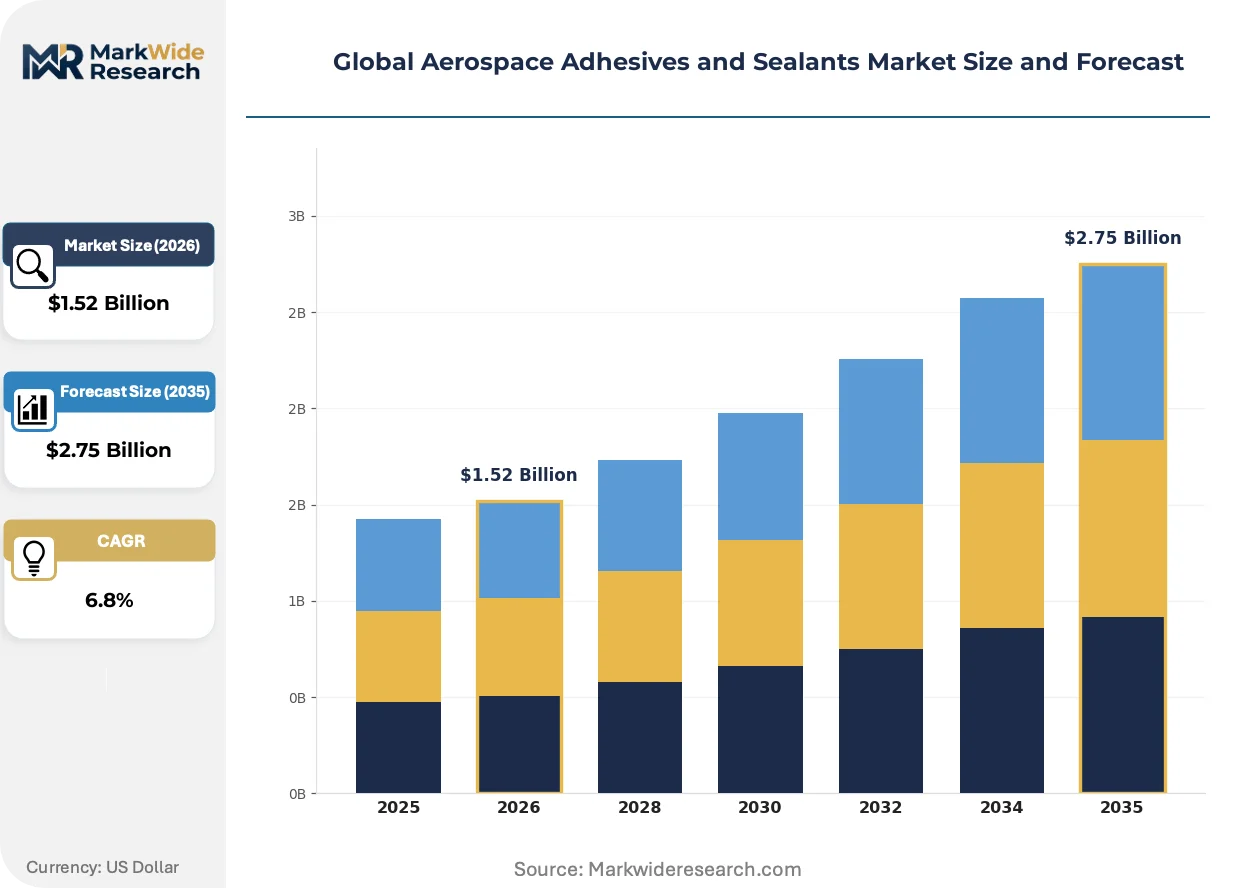
| Market Size in 2026 | $1.52 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Silicone, Polyurethane, Anaerobic, Cyanoacrylate Technology: Thermosetting, Thermoplastic, Structural, Non-Structural, Solvent-Based, Water-Based Application: Airframe Bonding, Engine Assembly, Cabin Interiors, Landing Gear, Electrical Components, Fuel Systems End User: Commercial Aircraft OEMs, Defense Contractors, Spacecraft Manufacturers, Maintenance Repair Organizations, Drone Producers |
| Companies Covered | Huntsman International LLC, Arkema, Henkel AG & Co KGaA, Solvay, Illinois Tool Works Inc, 3M, H B Fuller Company, Master Bond Inc, PPG Industries Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerospace Adhesives and Sealants Market Strategic Shifts & Innovations
Material innovation is driven by the dual imperatives of enhancing performance for next-generation aircraft and spacecraft while simultaneously complying with an increasingly stringent global environmental regulatory landscape. This dynamic pushes development towards multifunctional and sustainable solutions.
Multi-material adhesives are specifically formulated to create durable bonds between dissimilar substrates, such as composites and metals like aluminum or titanium. Airframe and component designers are increasingly specifying these products to optimize weight and performance in hybrid structures. This adhesive technology is converging with advanced digital simulation software, enabling engineers to accurately model and predict bond-line performance under stress before committing to physical manufacturing.
European chemical regulations, particularly the REACH framework, are actively phasing out certain substances of very high concern (SVHC) traditionally used in aerospace formulations. This directly impacts materials containing hexavalent chromium, a common corrosion inhibitor in primers and sealants. The MRO sector is most affected by this shift, accelerating the adoption of chrome-free alternatives to maintain compliance and ensure uninterrupted access to the European market.
A notable shift in buying behavior is occurring as aircraft OEMs move from procuring simple material inputs to demanding integrated solutions. This trend disrupts the role of traditional distributors, as procurement teams now favor suppliers that can provide a complete package of qualified adhesives, compatible surface preparation agents, and automated dispensing equipment. This demand for bundled systems is most pronounced within the high-volume aerospace manufacturing clusters located in the United States and France.
Global Aerospace Adhesives and Sealants Market Segmentation
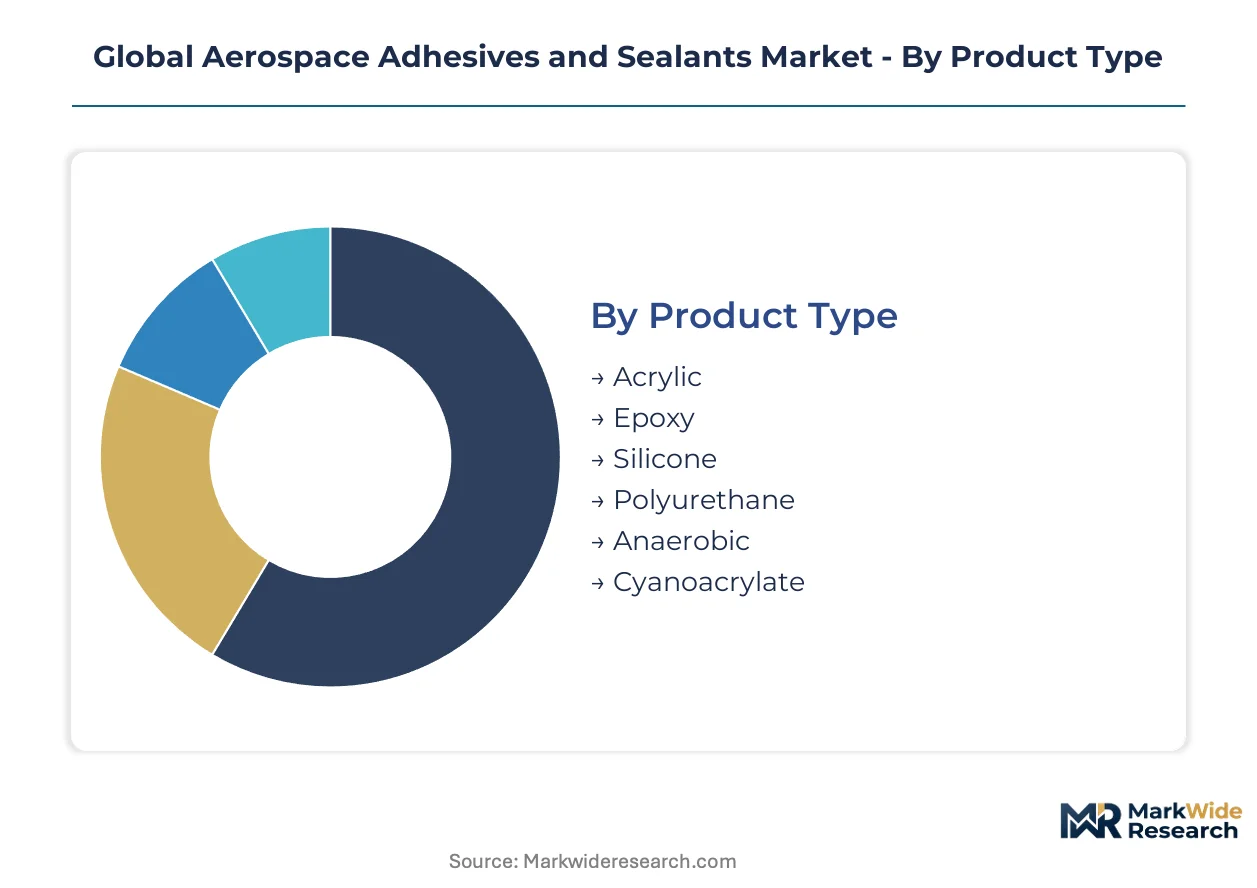
The global aerospace adhesives and sealants market is segmented to reflect the diverse technical requirements and operational contexts within aviation and space. Each segment addresses specific performance criteria, from extreme temperature resistance in engine components to fire safety in cabin interiors, driving specialized material development.
Product Type:
The capital intensity associated with manufacturing aerospace-grade adhesives varies significantly across different chemical formulations.
- Epoxy:These thermosetting polymers offer exceptional strength-to-weight ratios and high chemical resistance, making them indispensable for structural bonding applications. Demand concentrates in airframe manufacturing for advanced composite structures, where their robust mechanical properties are critical.
- Silicone:Known for superior flexibility, high-temperature stability, and environmental sealing capabilities, silicone formulations are crucial for fuel systems and cabin interior sealing. Their demand is particularly strong in MRO operations across Europe and the United States for repair and overhaul.
- Acrylic:Acrylic adhesives provide rapid curing times and strong bonds for non-structural applications, particularly in interior assembly.
- Polyurethane:These versatile polymers offer good flexibility and adhesion to various substrates, finding use in sealing and bonding applications where vibration dampening is required.
- Anaerobic:Anaerobic adhesives cure in the absence of oxygen, primarily used for threadlocking and retaining cylindrical assemblies in engine components.
- Cyanoacrylate:Often referred to as "super glues," cyanoacrylates provide fast, strong bonds for small, non-structural repairs and component assembly.
Most installed capacity flows through Epoxy formulations. Expansion is steepest in Silicone products.
Technology:
The application requirements fundamentally dictate the underlying adhesive technology, influencing material selection and processing methods.
- Structural:Structural adhesives are engineered to transfer significant loads between bonded parts, directly contributing to the integrity and safety of aircraft structures. Their use is paramount in airframe assembly for both metallic and composite components.
- Thermosetting:These polymer systems undergo an irreversible chemical reaction during curing, forming a rigid, cross-linked network that offers high thermal and chemical resistance. Thermosetting adhesives dominate high-performance applications in engine and airframe construction.
- Thermoplastic:Thermoplastic adhesives can be repeatedly softened by heating and hardened by cooling, allowing for reworkability and ease of processing.
- Non-Structural:Non-structural adhesives provide bonding for interior components, insulation, and sealing where load-bearing capacity is not the primary requirement.
- Solvent-Based:These formulations use organic solvents to carry adhesive solids, offering good adhesion and flexibility but facing increasing regulatory scrutiny due to VOC emissions.
- Water-Based:Water-based adhesives utilize water as a carrier, providing a more environmentally friendly alternative with lower VOCs, gaining traction in cabin interior applications.
Structural adhesive technologies command the largest market share. Water-Based formulations are gaining momentum due to environmental mandates.
Application:
Customer type and their specific operational needs drive demand for adhesives and sealants across various aircraft components.
- Airframe Bonding:This application involves joining primary and secondary airframe structures, increasingly utilizing advanced composites and requiring high-strength, fatigue-resistant adhesives. Demand is concentrated among commercial aircraft OEMs in the United States and France.
- Cabin Interiors:Adhesives and sealants for cabin interiors must meet stringent fire, smoke, and toxicity (FST) regulations while providing aesthetic and functional bonding for panels, seating, and galleys. European aircraft manufacturers prioritize these FST-compliant materials.
- Engine Assembly:High-temperature resistant adhesives and sealants are critical for bonding and sealing components within aircraft engines, enduring extreme thermal and mechanical stresses.
- Landing Gear:Adhesives and sealants in landing gear applications require robust performance against high impact, corrosion, and hydraulic fluids.
- Electrical Components:These materials provide insulation, encapsulation, and bonding for sensitive electronic systems, protecting them from environmental factors.
- Fuel Systems:Fuel-resistant sealants are essential for preventing leaks and ensuring the integrity of aircraft fuel tanks and lines.
Airframe Bonding represents the largest application segment. Cabin Interiors applications are experiencing rapid expansion.
End User:
The volume requirements and certification pathways define the market dynamics for adhesives and sealants across different end-user segments.
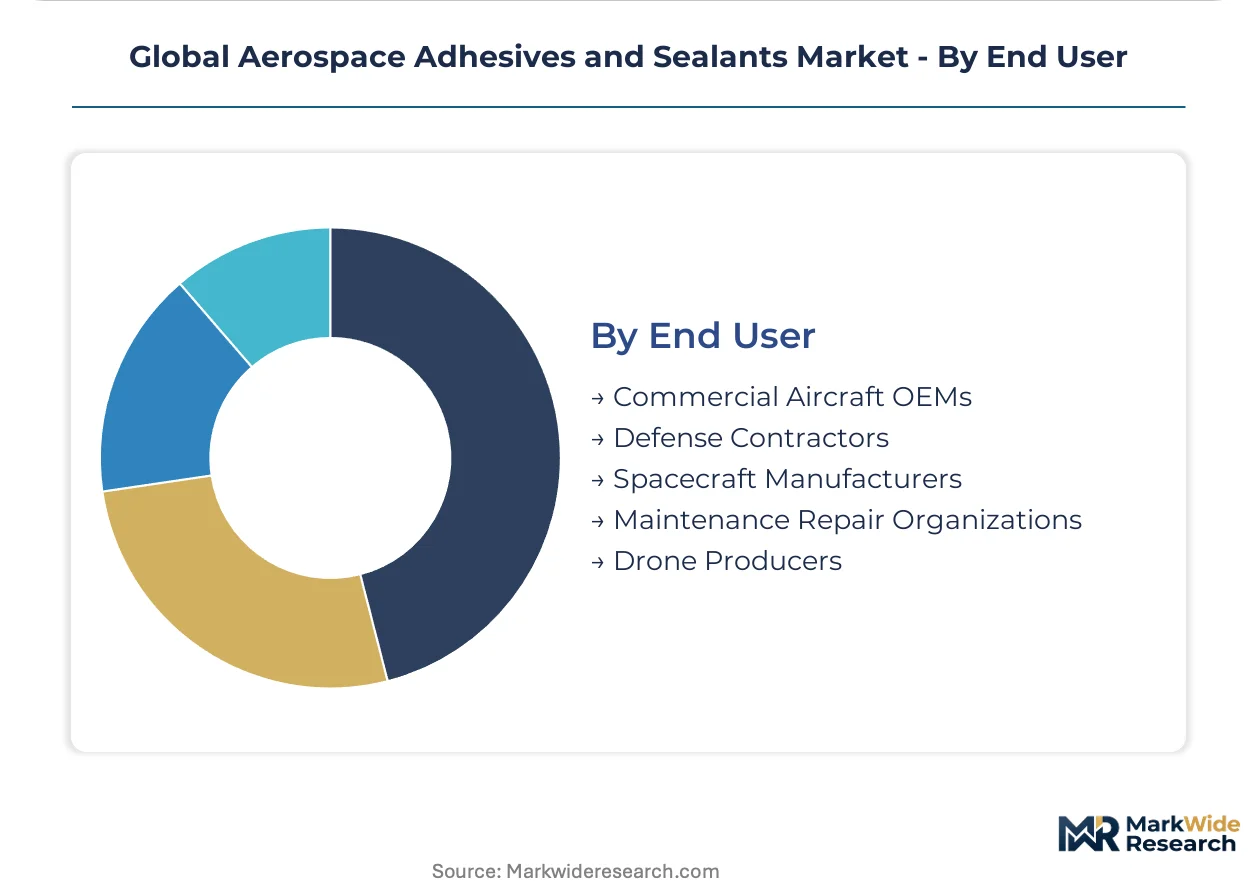
- Commercial Aircraft OEMs:These manufacturers require high volumes of qualified adhesives and sealants for the production of new passenger and cargo aircraft, driving innovation in efficient application methods. Airbus and Boeing represent major procurement hubs for these materials.
- Spacecraft Manufacturers:This segment demands highly specialized adhesives and sealants capable of withstanding extreme thermal cycles, vacuum, and radiation for satellite and launch vehicle construction. Companies like SpaceX and Blue Origin are significant consumers.
- Defense Contractors:Defense programs require adhesives and sealants that meet rigorous military specifications for performance in extreme operational environments and stealth applications.
- Maintenance Repair Organizations:MROs utilize a diverse range of adhesives and sealants for aircraft repair, overhaul, and modifications, focusing on products with long shelf lives and ease of application.
- Drone Producers:The emerging drone market requires lightweight, durable bonding solutions for both commercial and military unmanned aerial vehicles.
Commercial Aircraft OEMs account for the largest volume of adhesive and sealant consumption. The Spacecraft Manufacturers segment exhibits significant growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between major aerospace manufacturing regions creates a compliance cost gap, influencing where production capacity for adhesives and sealants is established or expanded. Differences in chemical regulations and certification pathways necessitate tailored product formulations and market strategies for suppliers.
United States
Demand for aerospace adhesives and sealants in the United States is driven by robust commercial aircraft production and expanding space sector activities. The US Federal Aviation Administration (FAA) sets stringent qualification standards for all materials used in aircraft construction. Key aerospace manufacturing hubs in Washington State and California concentrate significant demand for high-performance bonding solutions.
France
France remains a central hub for aerospace manufacturing, particularly for commercial aircraft OEMs like Airbus, which demands high volumes of specialized adhesives. Compliance with the European Union's REACH framework dictates material selection and formulation, particularly for chrome-free alternatives. The Toulouse region anchors significant airframe assembly operations and related supply chain activity.
China
China's aerospace market is expanding through government policies aimed at building sovereign production capabilities, fostering domestic demand for advanced materials. Chinese GB standards regulate the performance and safety of aerospace adhesives and sealants. Industrial clusters in Xi'an and Shanghai are rapidly developing capabilities for aircraft and component manufacturing.
India
India's aerospace sector is experiencing growth due to domestic manufacturing initiatives and an expanding MRO market. The country's Bureau of Indian Standards (BIS) oversees material quality and performance for local aerospace applications. Bengaluru, with its strong presence of Hindustan Aeronautics Limited (HAL) and defense research, serves as a significant aerospace hub.
Germany
Germany plays a vital role in the European aerospace supply chain, contributing specialized components and advanced material development for aircraft. The European Union Aviation Safety Agency (EASA) certification process is critical for market access and product acceptance. Major aerospace engineering and manufacturing facilities in Hamburg and Munich drive demand for high-performance adhesives.
Global Aerospace Adhesives and Sealants Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting the varied technical requirements and procurement models within aerospace. The market structure includes diversified material conglomerates, niche high-performance adhesive providers, and application-specific sealant manufacturers. Portfolio diversification and strategic partnerships represent dominant competitive moves among these players.
On the diversified portfolio vector, Henkel AG & Co KGaA and 3M exemplify broad market coverage, serving multiple aerospace applications with extensive product lines. Solvay, a European-based company, represents a focus on high-performance structural solutions, particularly for composite-intensive platforms. These companies anchor market segments through their established product ranges and global distribution networks.
| Leading Market Players |
|---|
| Huntsman International LLC |
| Arkema |
| Henkel AG & Co KGaA |
| Solvay |
| Illinois Tool Works Inc |
| 3M |
| H B Fuller Company |
| Master Bond Inc |
| PPG Industries Inc |
| Others |
Cost & Logistics Intelligence
Technicians trained in specialized application techniques in North America and Europe drive labor-cost differentials, influencing pricing-tier spreads for performance-critical aerospace adhesives. This specialized workforce ensures precise material handling and application, commanding premium rates for structural bonding solutions.
Pricing Analysis
Distributor margins reflect the value-added services necessary for product qualification and technical support within the aerospace adhesives market. The dominant pricing model for large-volume OEM contracts is long-term, contract-based offtake, while MRO operations typically engage in per-unit transactional pricing. Price differentiation stems from the stringent FAA and EASA certification levels and the volume scale of procurement. Pricing softness reflects raw material price volatility, particularly for petrochemical-derived inputs. The MRO segment exhibits the highest price sensitivity, whereas commercial aircraft OEMs prioritize performance over cost.
Supply Chain Analysis
Skilled labor availability in key manufacturing hubs like the United States, France, and Germany fundamentally shapes the aerospace adhesives supply chain. Geographic supply concentration for high-performance formulations centers in these nations, driven by established aerospace clusters. The industry relies heavily on specialized epoxy resins and polyurethane precursors as critical raw materials. Single-source vulnerability for certain high-performance chemical inputs represents a structural supply chain risk. Downstream distribution runs primarily direct-to-OEM for new aircraft production and through specialized distributor networks for MRO operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global aerospace adhesives and sealants market represents a late-cycle quality story, driven by the demand-shift toward premium specifications for lightweight composite airframe bonding. This transition emphasizes material performance over initial cost, favoring advanced formulations.
For Market Incumbents: Acquire specialized formulation expertise through strategic mergers and acquisitions to consolidate advanced material portfolios. Invest in advanced FST-compliant material research and development to address evolving cabin interior safety standards. This strategy mitigates the threat of technical performance ceilings for emerging hypersonic applications. Focus on certification investment for next-generation multi-material bonding solutions.
For New Entrants and Emerging Players: Enter via niche applications like Urban Air Mobility (UAM), which presents a high-volume opportunity for lightweight structural adhesives. Target the MRO market in emerging regions such as Southeast Asia and the Middle East, where expanding aircraft fleets create demand for maintenance solutions. A strong go-to-market angle involves partnering with local MROs to introduce chrome-free alternative sealants compliant with European regulations.
For Investors and Strategic Acquirers: Diversified material conglomerates are the most active acquirers in this space, seeking to expand their high-performance chemical portfolios. The long-term viability of this market is anchored in sustained demand from global aerospace production cycles and MRO activity over the next decade. Acquisition targets should include niche high-performance adhesive providers specializing in composite bonding or FST-compliant materials. Accelerated UAM platform certification serves as a key signal to watch for market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Supports increasing production schedules for advanced composite aircraft platforms. |
| Green Manufacturing Transition | Addresses evolving environmental mandates and reduces VOC emissions in new formulations. |
| Product Launch: FST-Compliant Adhesives | Meets stringent fire, smoke, and toxicity standards for cabin interior applications. |
| Strategic Partnership with OEMs | Facilitates integrated solutions and secures preferred supplier status for new aircraft programs. |
| Certification Investment for New Materials | Ensures compliance with FAA and EASA standards, enabling market access for innovative products. |
Research Approach
Multiple input streams — primary interviews, industry association reports, and regulatory body publications — were reconciled to construct a comprehensive market view. This involved engaging aerospace engineers, procurement managers at OEMs, MRO technical leads, and chemical R&D directors. Secondary validation drew from FAA certification documents, EASA guidelines, EU REACH reports, and company 10-K filings, employing both bottom-up and top-down triangulation approaches.
Historical market performance was cross-referenced with expert panel input to project future trends across the analysis window. The analytical framework incorporated segmentation dimensions such as product type, technology, application, end user, and regional regulatory frameworks. Compound annual growth rates were derived from projected aircraft production schedules and material consumption trends. Key industry-specific forecast inputs included new aircraft platform delivery forecasts and satellite launch manifests.
Inputs from public financial disclosures and regulatory databases were available through the study window; gaps in granular MRO spending data and emerging UAM market adoption rates introduce uncertainty bands. Forecasts reflect assumptions concerning technological advancements and regulatory stability. Material deviation in geopolitical shifts affecting trade or sudden changes in aerospace production targets warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Aerospace Titanium Market
Aerospace and Aircraft Materials
Aramid Honeycomb Market
Aerospace and Aircraft Materials
Radiation Shielding Market
Aerospace and Aircraft Materials
India Aerospace Coating Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Russia Space Electronics Market
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market