
 Aircraft Soft Goods Market | 2026-2036
Aircraft Soft Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Soft Goods Market Analysis
Modular seat cover bundling is rebalancing procurement economics for aftermarket buyers. Lantal Textile AG leverages its European manufacturing footprint to sustain long-term supply agreements with flag carriers. Botany Weaving Mill Ltd anchors its position through specialized weaving capabilities for aviation-grade fabrics. Spectra Interior Products differentiates via vertical control over dyeing and finishing processes that meet stringent burn-test protocols.
Aircraft soft goods encompass textiles, leathers, and synthetic materials engineered for cabin interiors, including seat covers, curtains, upholstery, and pillows, typically manufactured to meet 12-second vertical burn tests and smoke density thresholds under FAR 25.853 and EASA CS-25 standards. Their primary purpose is passenger comfort, cabin aesthetics, and regulatory-compliant fire safety in commercial and private aircraft environments. Seat covers and upholstery command the largest share of material spend due to replacement cycles tied to airframe heavy checks, while leather and advanced synthetic materials capture expanding share as carriers prioritize premium cabin differentiation and reduced maintenance intervals. Military aviation represents a concentrated but slower-growing demand pool governed by distinct procurement frameworks and durability specifications.
The FAA enforces flammability standards under 14 CFR 25.853 that mandate specific burn lengths and extinguishment times for all cabin materials, directly shaping R&D priorities and supplier qualification timelines. EASA's CS-25 harmonizes with FAA requirements while adding supplemental certification demands for European-registered operators, creating dual-compliance costs for global suppliers. REACH restrictions on chemical flame retardants and the EU Green Deal's circular economy mandates are forcing material reformulation toward halogen-free alternatives. Stakeholders must monitor evolving flammability test methodologies and sustainability-linked procurement criteria that will determine supplier viability across the next replacement cycle.
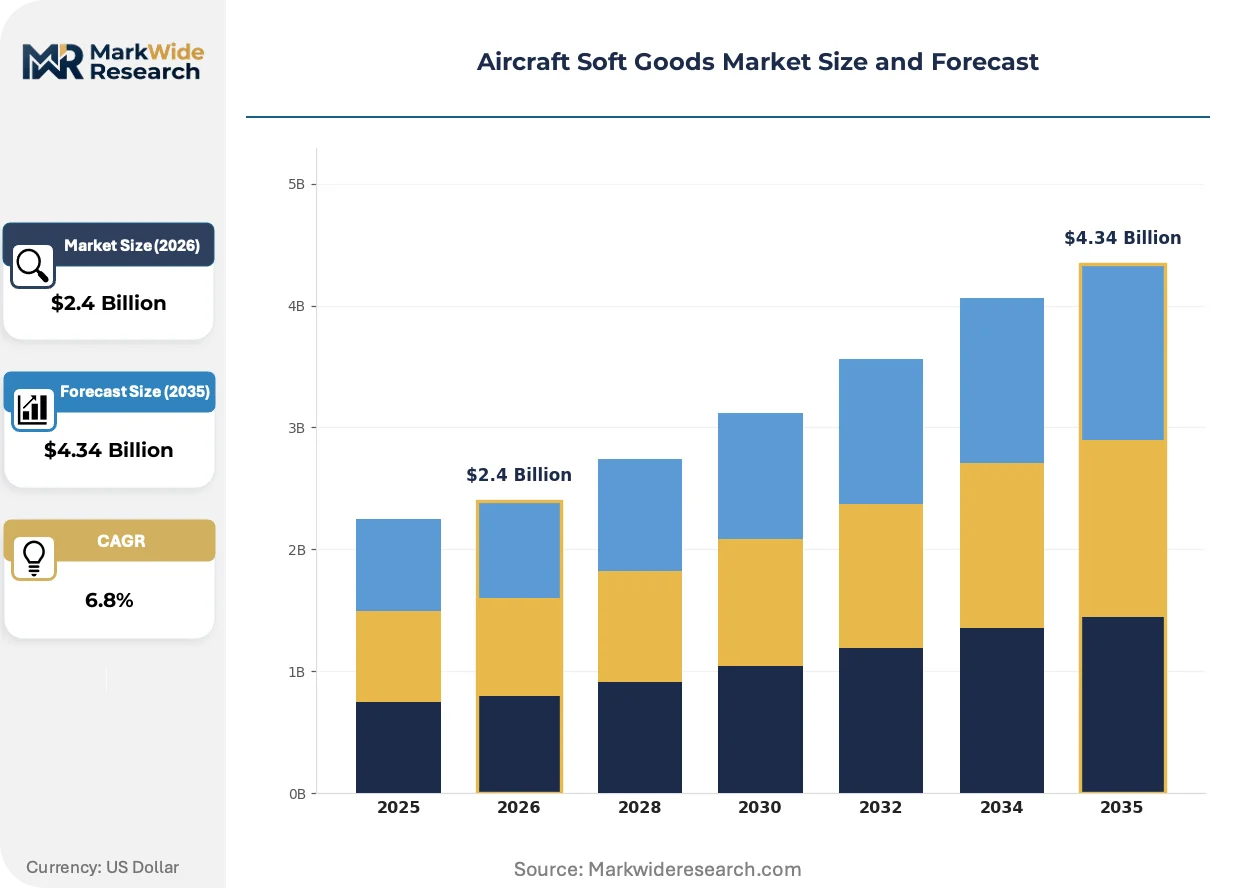
Market Dynamics
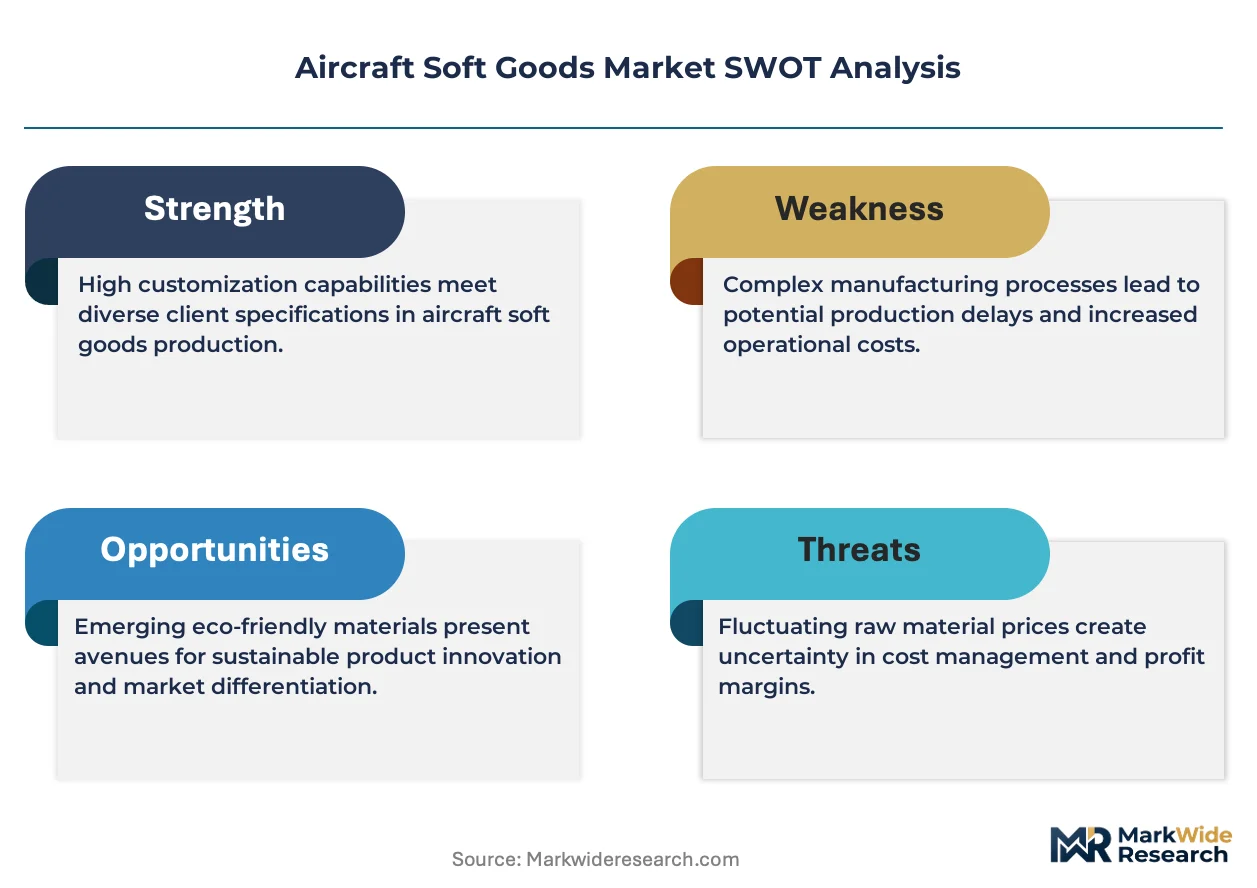
FAA's updated flammability standards under 14 CFR 25.853 are compressing supplier qualification timelines while forcing material reformulation investments that favor vertically integrated producers with captive testing facilities.
Growth Catalysts
- Narrow-body fleet expansion:Major US carriers are accelerating cabin retrofit programs to extend airframe service life, generating replacement demand for seat covers and upholstery tied to heavy check intervals.
- REACH chemical restrictions:ECHA's evolving flame-retardant regulations are creating first-mover advantage for suppliers with halogen-free material portfolios already certified to EASA CS-25 standards.
- Synthetic leather advancement:Polyurethane and silicone-based alternatives are capturing share from traditional hides by offering reduced maintenance intervals and consistent burn-test performance.
Market Restraints
- Petrochemical input volatility:Polyester and nylon feedstock costs fluctuate with crude oil indices, compressing margins for converters without long-term resin supply agreements.
- Specialized weaving concentration:Aviation-grade fabric production clusters in Western European mills, creating geographic supply risk for North American airlines seeking dual-source strategies.
- Dual certification burden:Suppliers must maintain parallel FAA and EASA testing protocols, adding fixed compliance costs that disadvantage smaller regional competitors.
Strategic Opportunities
- Indian MRO hub development:IndiGo and Air India's fleet expansion is creating aftermarket soft goods demand that local suppliers are positioned to capture under the country's PLI scheme incentives.
- Circular economy mandates:The EU Green Deal's textile recycling requirements are opening market space for suppliers with closed-loop material recovery capabilities and biodegradable fiber portfolios.
- Digital textile printing convergence:Inkjet deposition technology combined with flame-retardant chemistry is enabling rapid customization cycles for airline livery refreshes without minimum order constraints.
Industry Challenges
- Burn-test engineering talent scarcity:Qualified technicians capable of interpreting FAR 25.853 vertical test results and troubleshooting material failures command premium compensation in a shallow labor pool.
- Legacy seat frame incompatibility:New synthetic materials often require attachment hardware modifications that complicate retrofit installations on older Boeing 737NG and Airbus A320ceo airframes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Soft Goods Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seat Covers, Curtains, Upholstery, Pillows Material: Polyester, Nylon, Cotton, Leather End User: Commercial Airlines, Private Jets, Cargo Services, Military Aviation Manufacturing Stage: Raw Material, Pre-Production, Production, Post-Production |
| Companies Covered | Anker Technology (UK) Ltd, Tapis Corp, Spectra Interior Products, RAMM Aerospace, Mohawk Carpet, LLC, Lantal Textile AG, Botany Weaving Mill Ltd, E-Leather Ltd, Fellfab Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Soft Goods Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to reshape competitive positioning around certification speed and sustainable formulation capabilities rather than scale alone.
Silicone-coated fabrics are integrating into premium cabin segments as carriers seek alternatives to traditional leather that withstand accelerated cleaning protocols without surface degradation. Singapore Airlines and Emirates have adopted these materials for first-class suites, compressing replacement cycles from five years to three while maintaining aesthetic standards. The technology is integrating fire-resistant properties directly into polymer substrates rather than relying on topical treatments that degrade through laundering.
EASA's CS-25 harmonization with FAA 14 CFR 25.853 is tightening smoke density thresholds for cabin materials, forcing reformulation of legacy polyester blends that previously met extinguishment time requirements alone. European-registered operators face supplemental certification demands for thermoplastic polyurethane applications, extending supplier qualification timelines by 12-18 months. Narrow-body retrofit programs in Germany and France are experiencing procurement delays as airlines await revised material approvals.
Airline procurement departments are consolidating soft goods purchasing under fleet-wide framework agreements that bundle seat covers, curtains, and carpets by aircraft type rather than material category. Low-cost carriers in the US Southwest and Southeast Asia are driving this consolidation, displacing spot-buy arrangements with multi-year contracts tied to guaranteed unit pricing. The shift is most visible in narrow-body programs where standardized cabins reduce customization complexity and enable volume leverage.
Aircraft Soft Goods Market Segmentation
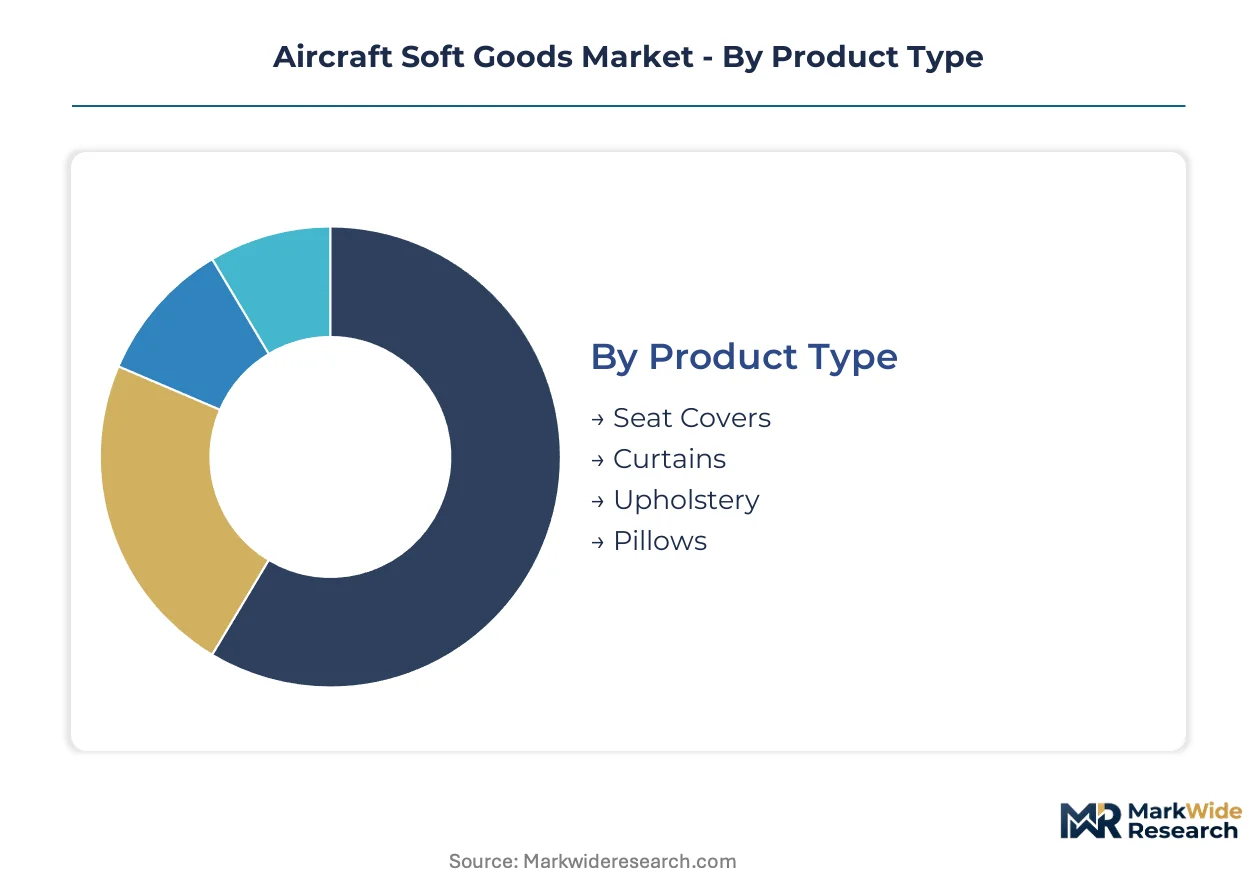
Procurement patterns in aircraft soft goods diverge sharply across product categories and end-use applications. Material specifications, replacement cycles, and regulatory compliance requirements create distinct commercial dynamics within each segment boundary.
Product Type:
Airlines prioritize replacement economics and burn-test certification speed when selecting cabin textile categories.
- Seat Covers:Engineered from multilayer constructions combining fire-blocking substrates with aesthetic face fabrics. Demand concentrates in narrow-body retrofit programs at US carriers, where heavy check intervals drive predictable replacement schedules.
- Upholstery:Wall panels, headrests, and decorative elements requiring complex three-dimensional forming capabilities. Premium cabin differentiation at Emirates and Singapore Airlines accelerates demand for silicone-coated alternatives with accelerated cleaning protocols.
- Curtains:Galley and cabin dividers manufactured to stringent smoke density thresholds under EASA CS-25. Volume clusters in European flag carriers refreshing legacy wide-body interiors.
- Pillows:Disposable comfort items with shorter replacement cycles. Low-cost carriers in Southeast Asia drive procurement consolidation under fleet-wide framework agreements.
Volume sits with Seat Covers; growth tilts toward Upholstery.
Material:
Feedstock selection hinges on flammability performance, maintenance intervals, and petrochemical input cost exposure.
- Polyester:Dominant aviation textile substrate woven to precise denier specifications for abrasion resistance. REACH restrictions on halogenated flame retardants are forcing reformulation investments at Western European mills.
- Leather:Traditional hides face displacement from synthetic alternatives offering consistent burn-test results. Premium cabin segments at Gulf carriers sustain residual demand for authentic materials.
- Nylon:High-tenacity yarns for high-wear applications including crew seating and cargo restraint systems. Nylon feedstock volatility compresses margins for converters without long-term resin agreements.
- Cotton:Limited aviation applications restricted by natural fiber flammability challenges. Specialized treatments enable niche use in private jet interiors where regulatory pathways differ.
Polyester captures the largest installed base; polyurethane and silicone synthetics are climbing the fastest.
End User:
Procurement frameworks and durability specifications diverge fundamentally across operator categories.
- Commercial Airlines:Fleet-wide standardization drives volume concentration. US major carriers anchor replacement demand through narrow-body retrofit programs extending airframe service life.
- Private Jets:Customization requirements and shorter production runs characterize demand. Completion centers in Wichita and Savannah source bespoke materials with expedited certification timelines.
- Cargo Services:Durability specifications prioritize abrasion resistance over passenger comfort. Freighter conversion programs at Amazon Air and DHL generate steady demand for utilitarian seat covers and restraint systems.
- Military Aviation:Distinct procurement frameworks governed by MIL-SPEC durability requirements. Slower growth reflects extended platform lifecycles and concentrated supplier relationships.
Commercial Airlines dominate procurement volume; Private Jets show the steepest expansion trajectory as fractional ownership models proliferate.
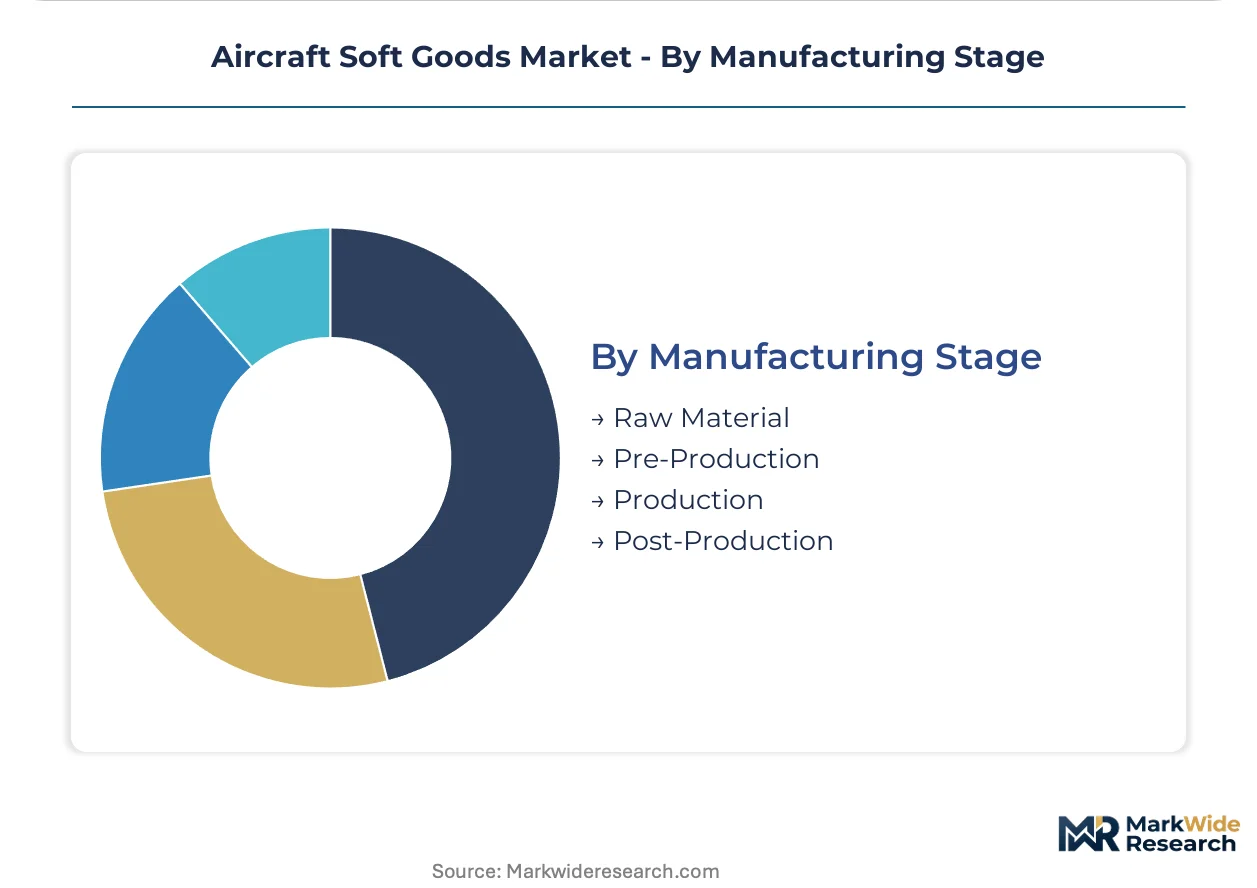
Manufacturing Stage:
Vertical control over testing and finishing capabilities determines supplier qualification success.
- Raw Material:Polymer resin and fiber production concentrates with petrochemical majors. Long-term supply agreements insulate qualified aviation textile producers from crude oil index volatility.
- Pre-Production:Yarn spinning and fabric weaving require specialized equipment for aviation-grade specifications. Western European mills retain concentration in high-tenacity nylon and aramid blends.
- Production:Cutting, sewing, and assembly operations are migrating toward Indian MRO hubs under PLI scheme incentives. IndiGo and Air India fleet expansion supports local supplier development.
- Post-Production:Dyeing, finishing, and burn-test certification represent critical bottlenecks. Suppliers with captive testing facilities compress qualification timelines under FAA 14 CFR 25.853 protocols.
Production-stage assembly commands employment concentration; post-production finishing captures margin premium through certification speed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special Economic Zones in Gujarat and Maharashtra are concentrating textile finishing capacity under India's PLI scheme incentives. These zones attract aviation-grade fabric producers seeking cost-advantaged post-production capabilities. Regional demand patterns diverge sharply based on fleet age, regulatory stringency, and MRO infrastructure maturity.
United States
Major carriers operate the world's largest narrow-body installed base requiring soft goods replacement cycles. FAA's 14 CFR 25.853 flammability standards compress supplier qualification timelines for domestic retrofit programs. Wichita and Savannah completion centers anchor private jet demand with expedited certification requirements.
Germany
Lufthansa Group's fleet standardization drives volume concentration in seat cover and upholstery procurement. EASA's CS-25 supplemental certification demands for thermoplastic polyurethane applications extend qualification timelines. Hamburg and Munich MRO clusters experience procurement delays awaiting revised material approvals.
India
IndiGo and Air India's fleet expansion creates aftermarket demand that local suppliers capture under PLI scheme incentives. BIS alignment with EASA standards accelerates domestic certification pathways for aviation textiles. Bengaluru and Hyderabad production facilities are migrating cutting and sewing operations from European mills.
United Arab Emirates
Emirates and Etihad premium cabin differentiation sustains demand for silicone-coated fabric alternatives. Dubai's aviation free zone infrastructure supports rapid customs clearance for imported aviation-grade materials. Sharjah MRO facilities are developing regional burn-test certification capabilities.
United Kingdom
British Airways' narrow-body retrofit programs generate predictable replacement schedules tied to heavy check intervals. ECHA REACH restrictions on halogenated flame retardants force reformulation investments at remaining domestic mills. Manchester and Glasgow textile producers are pivoting toward halogen-free material portfolios.
Aircraft Soft Goods Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material formulation and certification speed dimensions. The supplier base organizes into three tiers: vertically integrated European mills with captive testing facilities, regional converters dependent on third-party certification, and emerging Asian assemblers leveraging cost-advantaged production. Two dominant competitive moves are reshaping positioning: backward integration into polymer substrate production and strategic partnerships with airlines for fleet-wide framework agreements.
Among European-based textile specialists, Lantal Textile AG and Botany Weaving Mill Ltd exemplify the integrated mill archetype with specialized weaving capabilities for aviation-grade specifications. Spectra Interior Products occupies a position representing vertical control over dyeing and finishing processes. These three anchors illustrate how certification speed and sustainable formulation capabilities are displacing scale alone as competitive differentiators.
| Leading Market Players |
|---|
| Anker Technology (UK) Ltd |
| Tapis Corp |
| Spectra Interior Products |
| RAMM Aerospace |
| Mohawk Carpet, LLC |
| Lantal Textile AG |
| Botany Weaving Mill Ltd |
| E-Leather Ltd |
| Fellfab Limited |
| Others |
Supply Flow & Price Mechanics
Qualified burn-test engineering talent concentrated in Western European mills commands premium compensation that widens pricing spreads between certified premium tiers and uncertified economy alternatives. Labor-cost differentials between these specialized technicians and assembly workers in emerging production hubs directly feed into three-tier pricing stratification across aviation textile procurement.
Pricing Analysis
Short lead-time premiums compress standard pricing by fifteen to twenty percent for spot inventory held by distributors with captive testing facilities. The dominant model runs through contract-based long-term offtake agreements bundling seat covers, curtains, and upholstery by aircraft type, with price differentiation resting on certification speed and burn-test documentation completeness. Cost compression in standard-grade polyester segments is intensifying because REACH-mandated reformulation investments favor larger suppliers with captive chemistry labs. Low-cost carriers operating narrow-body fleets exhibit highest price sensitivity, while Gulf carriers prioritizing premium cabin differentiation show lowest sensitivity to unit pricing.
Supply Chain Analysis
Workforce availability for specialized weaving and finishing skills concentrates in Germany, the United Kingdom, and Italy, constraining capacity expansion despite demand growth in North America and Asia-Pacific. Raw material dependencies draw from petrochemical resin suppliers in the United States and Middle East, with aramid fiber production anchored in DuPont's American and European facilities. Single-source vulnerability sits with Western European mills controlling aviation-grade nylon and aramid blending capabilities. Distribution runs through airline procurement departments consolidating purchases under fleet-wide framework agreements, with MRO hubs in India and the UAE developing regional finishing capacity to shorten logistics loops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around certification speed and sustainable formulation capabilities as dual-compliance burdens under FAA and EASA protocols force smaller regional competitors toward exit. The analysis frames this as a consolidation play justified by fixed compliance costs that disproportionately disadvantage non-integrated suppliers.
For Market Incumbents: Hedge against REACH chemical restriction acceleration by accelerating halogen-free material portfolio certification before ECHA mandates tighten. Secure backward integration into polymer substrate production to insulate margin position from petrochemical feedstock volatility. Capture fleet-wide framework agreements with US major carriers retrofitting narrow-body fleets, locking out emerging Asian assemblers before PLI scheme incentives mature domestic Indian supply.
For New Entrants and Emerging Players: Enter via digital textile printing convergence for rapid customization cycles serving low-cost carriers refreshing livery without minimum order constraints. Target Indian MRO hub development where IndiGo and Air India fleet expansion outpaces local supplier certification capacity. Pursue go-to-market angles emphasizing closed-loop material recovery capabilities aligned with EU Green Deal circular economy mandates.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated European mills with captive burn-test facilities and established EASA CS-25 certification track records. Long-term viability over the next replacement cycle hinges on qualification speed advantages that compound through airline procurement consolidation. Watch for EASA smoke density threshold tightening as the inflection indicator that separates reformulation-capable suppliers from stranded legacy inventory holders.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Substrates | Captive resin supply insulates margins from crude oil index volatility. |
| Halogen-Free Material Certification | REACH compliance creates first-mover advantage in European airline procurement. |
| Fleet-Wide Framework Agreements | Multi-year contracts with US carriers displace spot-buy arrangements and lock volume. |
| Digital Textile Printing Deployment | Inkjet flame-retardant deposition enables rapid livery customization without minimum orders. |
| Indian MRO Hub Capacity Buildout | PLI scheme incentives support local assembly migration from European mills. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs that combined with primary interviews across airline procurement directors, MRO facility managers, aviation textile plant engineers, and FAA certification specialists. FAA 14 CFR 25.853 documentation, EASA CS-25 submission databases, and EU REACH chemical restriction updates provided regulatory trajectory inputs. Bottom-up triangulation across individual airline fleet retrofit schedules and top-down reconciliation against petrochemical feedstock demand models validated volume estimates.
Granularity-level modeling disaggregated projections across product type, material substrate, end-user category, and manufacturing stage through the analysis window. CAGRs derived from weighted average replacement cycle frequencies tied to heavy check intervals and fleet age distributions. Synthetic leather adoption curves and REACH-mandated reformulation timelines served as industry-specific forecast inputs shaping material mix projections.
Revisions become necessary when EASA smoke density thresholds tighten beyond current CS-25 harmonization, when Indian BIS certification alignment accelerates domestic supplier qualification, or when petrochemical input volatility disrupts long-term resin supply agreements. Material deviation in these named triggers warrants pause and re-evaluation of supplier viability rankings and regional demand concentration assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace 3D Printing Consumables Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Aerospace High-Performance Alloys Market
Aerospace and Aircraft Materials
Global Composite Materials Aluminum Alloys Aerospace Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Aerospace Forging Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Radiation Shielding Market
Aerospace and Aircraft Materials
Aerospace Foam Market
Aerospace and Aircraft Materials
Ablative Coatings Market