
 Aircraft Braking System Market | 2026-2036
Aircraft Braking System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Braking System Market Intelligence
Electro-mechanical actuation is rewriting the architecture of landing gear control, displacing legacy hydraulic routing with distributed motor-driven braking. Safran Landing Systems leverages its integrated landing gear-to-brake design pipeline to capture OEM specification authority on new programs. Honeywell International Inc. anchors aftermarket revenue through proprietary brake monitoring electronics that lock in recurring service contracts. Collins Aerospace competes on thermal management patents that extend carbon disc life cycles under high-energy rejected takeoff conditions.
An aircraft braking system converts kinetic energy into thermal energy through friction interfaces, typically comprising rotors, stators, actuators, and anti-skid control units rated for temperatures exceeding 1,500°C during emergency stops. Its primary purpose is to ensure safe deceleration within runway length constraints while preventing tire blowout or structural damage. Carbon brakes dominate long-haul commercial platforms where weight reduction justifies premium pricing, while electro-mechanical brakes represent the fastest-growing technology segment as electric aircraft architectures eliminate hydraulic infrastructure. Retrofitting activity lags OEM installation in volume but generates superior margins as operators face airworthiness directive compliance deadlines.
FAA Part 25 airworthiness standards and EASA CS-25 certification frameworks mandate specific stopping distance performance across contaminated runway scenarios, directly shaping brake sizing requirements for new type certificates. The EU Green Deal emissions trajectory and ICAO carbon offset mechanisms are pressuring operators to adopt lighter brake systems that reduce fuel burn per flight cycle. Stakeholders must monitor how electric system reliability data accumulates under commercial airline duty cycles before committing fleet-wide hydraulic elimination strategies.
Market Dynamics
Electro-mechanical actuation is collapsing the hydraulic infrastructure that has dominated aircraft braking architecture since the 1960s, forcing suppliers to reconfigure production footprints and certification pathways around distributed motor control systems.
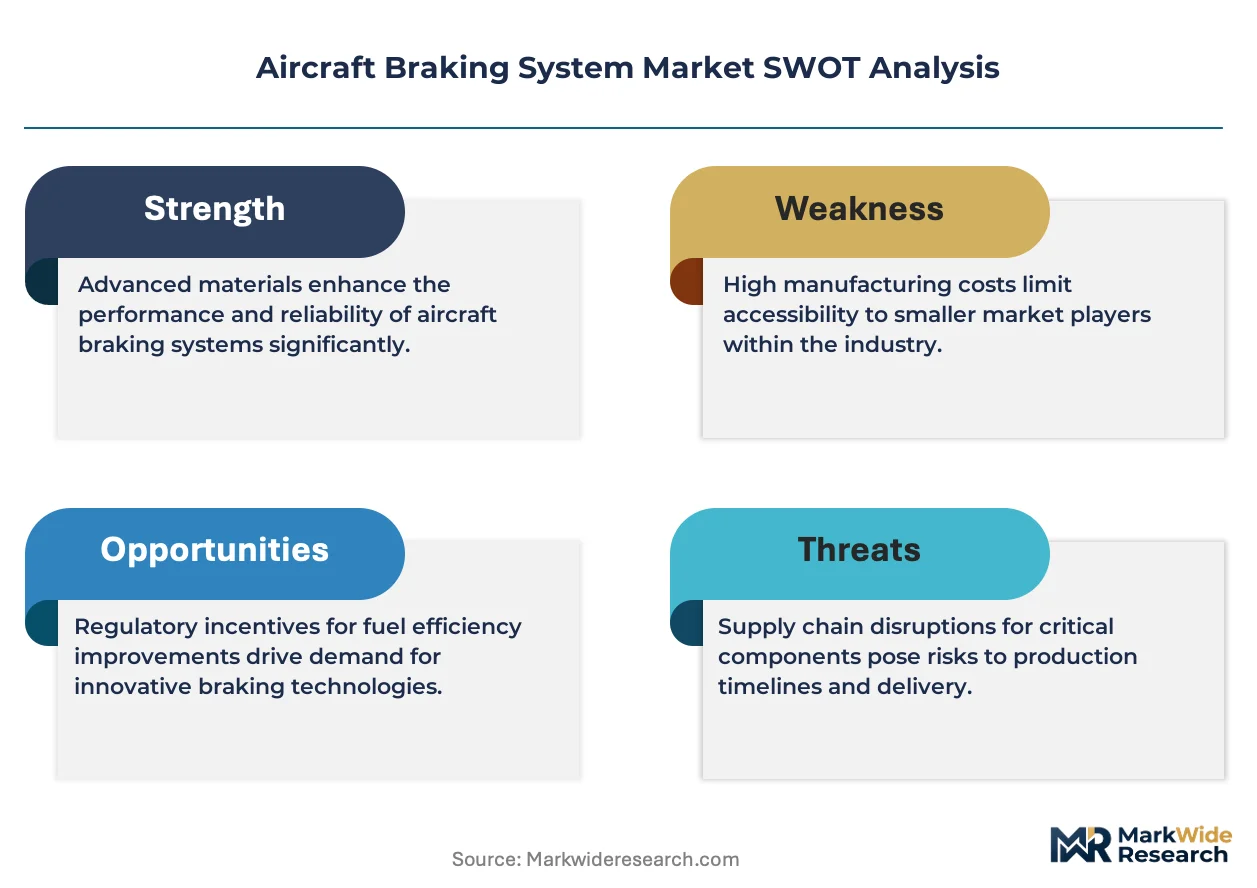
Growth Catalysts
- FAA Part 25 Certification:Airworthiness standards for rejected takeoff stopping distances are tightening thermal performance thresholds, expanding carbon brake specifications on new narrow-body programs.
- EU Green Deal:Emissions reduction mandates are pressuring fleet operators toward lighter brake systems that reduce fuel burn per flight cycle.
- Carbon brake thermal management:High-energy absorption capabilities above 1,500°C are displacing steel brakes on long-haul commercial platforms where weight reduction justifies premium positioning.
Market Restraints
- Raw material concentration:Carbon-carbon composite precursor supply concentrates among specialized Japanese and US chemical suppliers, exposing brake manufacturers to acrylonitrile price volatility.
- Certification timeline friction:EASA CS-25 validation cycles for new electro-mechanical architectures extend development programs by 18-24 months versus legacy hydraulic approvals.
- Technical limitation:Electric actuator reliability data under commercial airline duty cycles remains insufficient for fleet-wide hydraulic elimination commitments.
Strategic Opportunities
- Urban air mobility:Electric vertical takeoff platforms require entirely new brake architectures sized for distributed propulsion and frequent stop-start cycles.
- India defense modernization:Indigenous fighter programs are creating specification authority for domestic brake suppliers previously locked out of military procurement.
- ICAO carbon offset mechanisms:Compliance credit frameworks are incentivizing brake weight reduction as a measurable emissions abatement pathway.
Industry Challenges
- Electro-mechanical systems engineering:Talent scarcity in motor control firmware and high-temperature electronics is constraining supplier engineering bandwidth.
- Legacy fleet integration:Hydraulic-to-electric retrofit pathways require airworthiness directive compliance without disrupting operator maintenance schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Braking System Market |
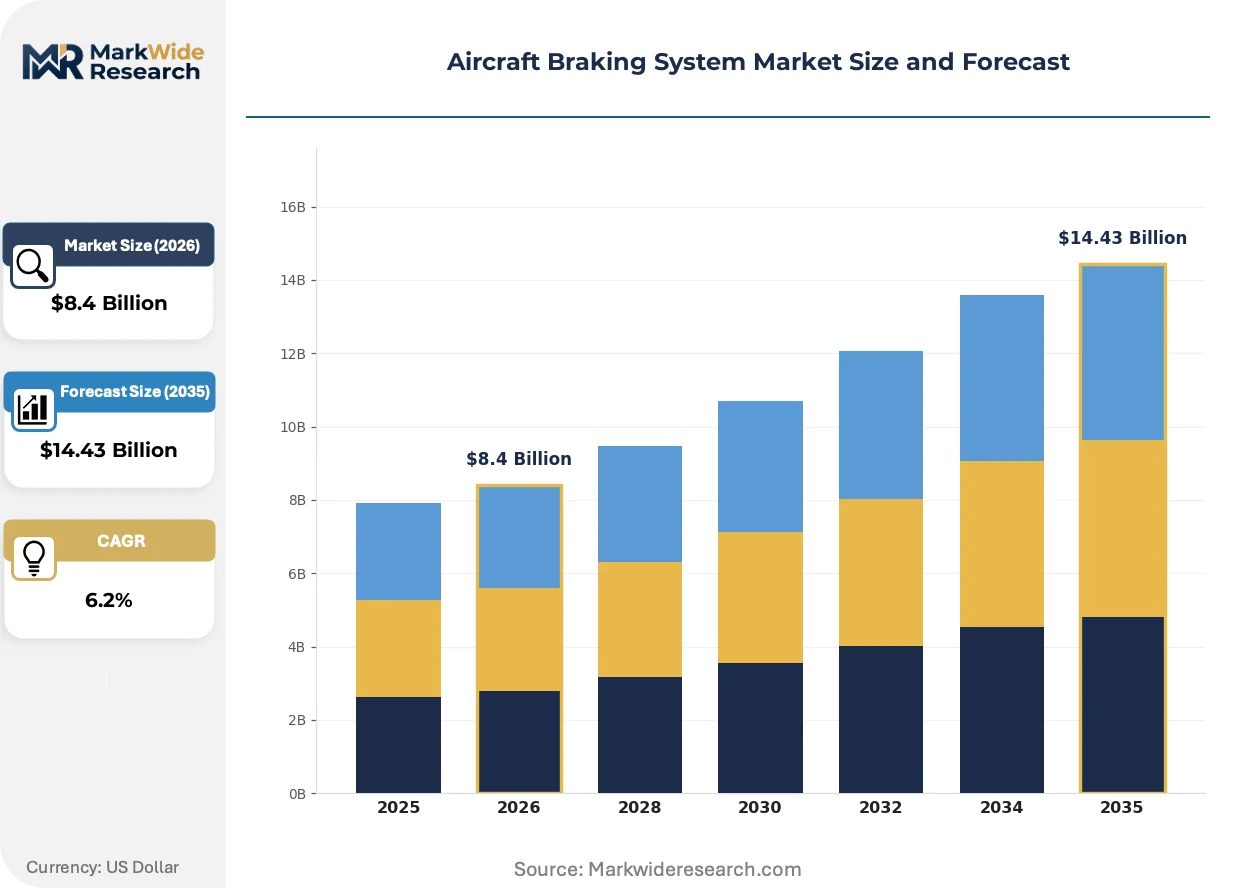
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Brakes, Drum Brakes, Electro-Mechanical Brakes, Carbon Brakes End User: Commercial Aviation, Military Aviation, Cargo Operations, Private Jets Technology: Hydraulic Systems, Pneumatic Systems, Electric Systems, Hybrid Systems Installation: Retrofitting, OEM Installation, Maintenance Repair Overhaul, Aftermarket |
| Companies Covered | Honeywell International Inc., Safran Landing Systems, Collins Aerospace, Parker-Hannifin Corporation, Crane Aerospace & Electronics, AAR Corporation, Lufthansa Technik AG, Meggitt PLC, Beringer Aero, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Braking System Market Strategic Shifts & Innovations
Brake system architecture is fragmenting along electric-hybrid boundaries as OEMs place divergent bets on hydraulic elimination timelines. Suppliers must now maintain dual certification pipelines while accumulating operational data on unproven actuation modes.
Electro-mechanical braking is collapsing the centralized hydraulic distribution model that has governed landing gear control for six decades. Narrow-body OEMs are embedding motor-driven actuators in new type certificates, eliminating miles of routed tubing and valve assemblies. This compression is enabling distributed computing architectures where brake control migrates to landing gear-mounted electronics rather than centralized avionics bays.
EASA CS-25 amendments on thermal energy absorption are mandating revised carbon disc density specifications for contaminated runway scenarios. Brake manufacturers must retest existing designs under wet and icy surface protocols previously exempt from certification. Long-haul operators in Northern Europe are accelerating fleet upgrades to meet these revised stopping distance guarantees.
Airline procurement departments are unbundling brake monitoring electronics from hardware supply contracts, creating separate vendor relationships for predictive maintenance software. Low-cost carriers are driving this disintermediation, seeking direct data platform access rather than OEM-mediated service agreements. This restructuring is most advanced in the United States, where Southwest and Allegiant have established independent brake health monitoring contracts.
Aircraft Braking System Market Segmentation
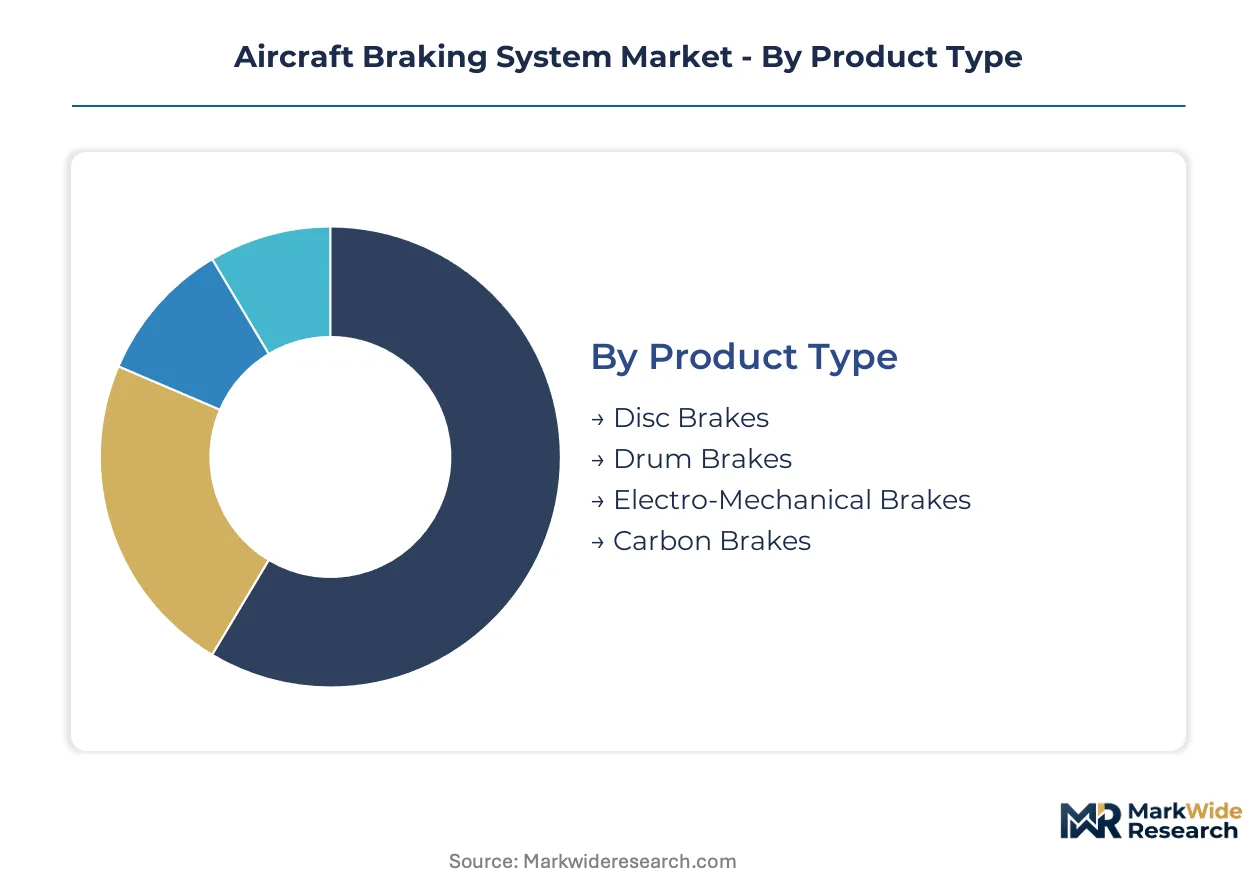
Brake system procurement splits across divergent performance specifications and regulatory compliance pathways. Each segmentation dimension captures distinct buyer priorities: weight-critical operators favor carbon over steel, while fleet renewal timelines separate OEM installation from aftermarket retrofit economics.
Product Type:
Use-case spectrum spans legacy friction materials through electric actuation architectures, with thermal performance and weight trade-offs defining specification authority.
- Carbon Brakes:Carbon-carbon composite discs absorb thermal loads exceeding 1,500°C during rejected takeoff scenarios. Long-haul carriers operating from high-altitude airports in the United States and Switzerland specify these for weight reduction that compounds fuel savings across flight cycles.
- Electro-Mechanical Brakes:Motor-driven actuation eliminates hydraulic distribution infrastructure entirely. Narrow-body OEM programs in France and Germany are embedding these architectures as electric aircraft propulsion systems mature.
- Disc Brakes:Multi-rotor configurations with steel or composite stators dominate regional aviation fleets where acquisition cost outweighs weight penalties.
- Drum Brakes:Enclosed friction assemblies persist in light aircraft and certain military trainer platforms requiring simplified maintenance protocols.
Established volume favors carbon brakes; emerging adoption favors electro-mechanical brakes.
End User:
Customer-type concentration determines contract structure, with commercial airlines driving volume and military procurement anchoring margin through technical specification complexity.
- Commercial Aviation:Scheduled carriers operate under FAA Part 25 and EASA CS-25 stopping distance mandates that dictate brake sizing for contaminated runways. Fleet operators in Germany and the United Kingdom are accelerating carbon brake retrofits to meet revised wet-surface certification protocols.
- Military Aviation:Fighter and transport programs require anti-skid systems rated for unprepared landing surfaces. Indigenous procurement in India is creating specification pathways for domestic suppliers previously excluded from defense contracts.
- Cargo Operations:Express freight carriers prioritize brake durability under high-cycle, short-haul duty profiles with frequent landing events.
- Private Jets:Business aviation operators balance weight reduction against customization requirements and lower utilization rates.
Commercial aviation commands procurement scale; military programs sustain engineering premium pricing.
Technology:
Architecture maturity curves separate proven hydraulic infrastructure from electric system reliability accumulation timelines.
- Hydraulic Systems:Centralized fluid distribution through routed tubing and valve manifolds has governed landing gear control for six decades. Legacy fleets in the United States and Brazil retain this architecture for parts commonality across mixed-generation operations.
- Electric Systems:Distributed motor control eliminates fluid leaks and reduces maintenance intervals. EASA validation cycles for these architectures extend development programs by 18-24 months versus legacy approvals.
- Pneumatic Systems:Compressed air actuation persists in certain regional aircraft where system simplicity outweighs precision control requirements.
- Hybrid Systems:Electric-hydraulic combinations bridge reliability demonstration gaps during fleet transition periods.
Hydraulic systems anchor installed base; electric architectures are climbing the fastest.
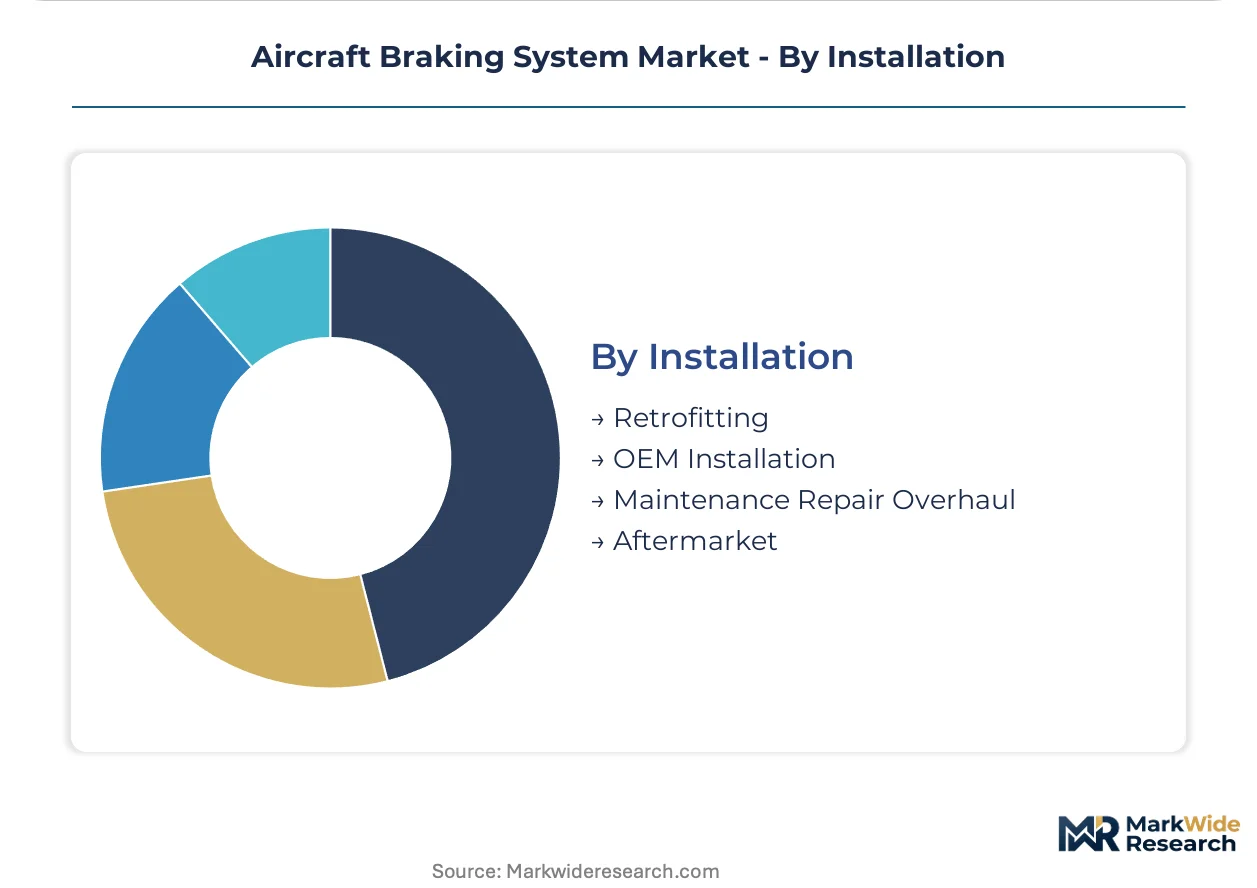
Installation:
Channel economics separate high-volume OEM line-fit from aftermarket margin structures driven by airworthiness directive compliance deadlines.
- OEM Installation:Brake systems specified at type certificate award lock in supplier relationships for production runs. Final assembly lines in the United States and France concentrate procurement authority with integrated landing gear-to-brake design pipelines.
- Aftermarket:Replacement demand generates superior margins as operators face mandatory compliance windows. Independent brake health monitoring contracts at Southwest and Allegiant in the United States are disintermediating OEM service agreements.
- Retrofitting:Hydraulic-to-carbon or hydraulic-to-electric conversions require certification without disrupting operator maintenance schedules.
- Maintenance Repair Overhaul:MRO hubs in the United States perform thermal performance restoration and disc reconditioning for life cycle extension.
OEM installation captures specification authority; aftermarket channels sustain margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision brake actuation components to French and US final assembly lines, anchoring transatlantic supply chains for next-generation narrow-body programs.
United States
Boeing final assembly lines in Washington and South Carolina drive OEM brake procurement volumes, while Southwest Airlines and Allegiant operate independent brake health monitoring contracts that disintermediate traditional service agreements. FAA Part 25 certification requirements for rejected takeoff stopping distances are tightening thermal performance thresholds. Dallas-Fort Worth and Atlanta anchor major MRO hubs performing thermal restoration and disc reconditioning for life cycle extension.
Germany
Airbus Hamburg and Bremen final assembly lines concentrate specification authority for electro-mechanical brake architectures on new narrow-body programs. EASA CS-25 amendments on thermal energy absorption mandate revised carbon disc density specifications for contaminated runway scenarios. Munich and Stuttgart host specialized engineering clusters developing motor control firmware for distributed braking systems.
France
Safran Landing Systems leverages integrated landing gear-to-brake design pipelines to capture OEM specification authority on new programs. EU Green Deal emissions reduction mandates pressure fleet operators toward lighter brake systems that reduce fuel burn per flight cycle. Toulouse and Bordeaux anchor carbon-carbon composite manufacturing clusters serving long-haul commercial platforms.
India
Indigenous fighter programs under the defense modernization initiative create specification pathways for domestic brake suppliers previously excluded from military procurement. BIS certification frameworks for aerospace components are aligning with EASA technical standards to facilitate export qualification. Bangalore and Hyderabad host emerging engineering centers developing anti-skid systems for unprepared landing surfaces.
United Kingdom
British Airways and easyJet accelerate carbon brake retrofits to meet revised EASA wet-surface certification protocols for contaminated runway scenarios. CAA alignment with EASA CS-25 amendments streamlines dual certification pathways for suppliers serving European and domestic operators. Bristol and Derby maintain legacy aerospace manufacturing clusters transitioning from hydraulic to electro-mechanical system integration.
Aircraft Braking System Market Key Industry Players
On the supply side, the industry is consolidating around integrated landing gear-to-brake design pipelines that capture specification authority at type certificate award. Tiered competitive dynamics separate OEM-captive suppliers with full system integration capabilities from independent component specialists serving aftermarket channels. Two strategic archetypes dominate: vertically integrated aerostructures conglomerates controlling end-to-end thermal management patents, and specialized brake monitoring electronics providers locking in recurring service contracts. Dominant competitive moves include strategic partnerships for electric actuator reliability data accumulation and geographic expansion into India defense procurement.
Within the integrated systems tier, Safran Landing Systems and Collins Aerospace exemplify the vertically integrated model spanning landing gear through brake control. Honeywell International Inc. occupies a distinct position anchoring aftermarket revenue through proprietary electronics that sustain recurring service relationships. These three corporations represent the full spectrum of competitive positioning from OEM specification authority through aftermarket data platform control.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Safran Landing Systems |
| Collins Aerospace |
| Parker-Hannifin Corporation |
| Crane Aerospace & Electronics |
| AAR Corporation |
| Lufthansa Technik AG |
| Meggitt PLC |
| Beringer Aero |
| Others |
Cost & Logistics Intelligence
Undercapacity in Japanese carbon-carbon composite precursor production is elevating raw material premiums and compressing brake manufacturer margins, while simultaneously accelerating supplier consolidation around long-term offtake contracts with tier-one OEMs.
Pricing Analysis
The technology-generation pricing gap separates legacy steel brake assemblies from carbon-carbon composite systems and emerging electro-mechanical architectures. Three-tier pricing structure across premium carbon, standard steel, and economy refurbished tiers dominates procurement, with FAA Part 25 certification grade and fleet volume scale as primary differentiation drivers. Cost compression in steel brake tiers is intensifying because low-cost regional carriers are extending replacement intervals. Cargo operators exhibit highest price sensitivity due to high-cycle duty profiles, while long-haul flag carriers prioritize thermal performance over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for brake electronics and motor control components. Manufacturing concentrates in France, Germany, and the United States for final assembly, while carbon fiber precursor supply draws from Japan and specialized US chemical suppliers. Acrylonitrile price volatility and single-source vulnerability for high-temperature composite matrices constrain supplier flexibility. Distribution runs through OEM-captive channels for new aircraft and independent MRO hubs for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft braking system market sits at a platform-economics inflection where brake health monitoring data platforms are decoupling from hardware supply, creating interoperability standards battles between OEM-captive and independent service providers.
For Market Incumbents: Entrench specification authority by deepening backward integration into carbon-carbon composite manufacturing and capturing type certificate award timing on next-generation narrow-body programs. Lock in recurring revenue through proprietary brake monitoring electronics that resist disintermediation by low-cost carrier procurement departments. Prioritize certification investment in EASA CS-25 amendments to defend against emerging electro-mechanical entrants.
For New Entrants and Emerging Players: Urban air mobility platforms in Germany and France represent the most penetrable entry point for entirely new brake architectures sized for distributed propulsion and frequent stop-start cycles. India's indigenous fighter programs under defense modernization create specification pathways for domestic suppliers previously excluded from military procurement. Lead with predictive maintenance software partnerships rather than hardware specification challenges.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electro-mechanical brake development programs due to extended EASA validation cycles and firmware engineering talent scarcity. Target acquisition archetypes include specialized motor control electronics firms and high-temperature sensor developers with existing FAA engagement. Monitor electric actuator reliability data accumulation under commercial airline duty cycles as the critical inflection signal for fleet-wide hydraulic elimination timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon-Carbon Composite Manufacturing | Captures precursor supply margin and insulates against Japanese supplier concentration risk. |
| Electro-Mechanical Brake Certification Investment | Positions suppliers for EASA CS-25 validation leadership as hydraulic elimination accelerates. |
| Independent Brake Health Monitoring Platform Launch | Disintermediates OEM service agreements at Southwest and Allegiant, creating recurring SaaS revenue. |
| Urban Air Mobility Brake Architecture Development | Establishes specification authority on electric vertical takeoff platforms before standards crystallize. |
| India Defense Procurement Partnership | Unlocks indigenous fighter program specifications previously closed to foreign brake suppliers. |
Research Approach
A standing panel of landing gear procurement directors, MRO operations managers, FAA certification engineers, and airline fleet planners provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FAA Part 25 airworthiness directives, EASA CS-25 certification frameworks, OEM production forecasts, and carbon composite trade flow data. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Scenario-bracketing framed the projection horizon across conservative, baseline, and accelerated electro-mechanical adoption pathways. Segmentation dimensions modeled include brake technology type, end-user category, installation channel, and regional regulatory cluster. CAGRs derived from fitted growth curves against historical fleet renewal patterns and new aircraft delivery schedules. Forecast inputs incorporated brake replacement cycle extension trends and carbon offset incentive elasticity under EU Green Deal mechanisms.
Macroeconomic conditions sit as an overlay; deviation in jet fuel price trajectories, interest rate environments affecting aircraft financing, or trade policy shifts affecting carbon precursor tariffs would shift the trajectory. Forecasts reflect documented assumptions about electric system reliability maturation and certification timeline compression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Aviation Airbags Market
Aircraft Safety Systems
Commercial Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
Aircraft Survival Equipment Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Aircraft Fire Protection Systems Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
Aircraft Survivability Equipment Market
Aircraft Safety Systems
Airborne Lightning Detection System Market
Aircraft Safety Systems
Helicopter Emergency Flotation System Market
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
Aircraft Evacuation Slide Market