
 Aerographene Market | 2026-2036
Aerographene Market Size, Share, and Industry Trends Forecast 2026-2036
Aerographene Market Analysis
Ultra-lightweight grade specifications is rotating toward the center of procurement decisions in the aerographene space. Dow leverages captive carbon precursor supply to sustain cost discipline across North American production. Evonik Industries AG anchors European qualification pipelines for aerospace-grade material. Aspen Aerogels differentiates through thermal conductivity thresholds that meet defense contractor specifications.
Aerographene denotes a three-dimensional graphene architecture with a density below 3 mg per cubic centimeter and specific surface area exceeding 3000 square meters per gram, synthesized through hydrothermal reduction and supercritical drying to deliver electrical conductivity and thermal insulation in extreme environments. Graphene aerogel dominates current volume owing to its established production protocols, while composite materials capture expanding share as automotive OEMs integrate multifunctional substrates into battery enclosures. Energy storage applications lead absolute demand, though lightweight structures in satellite platforms represent the fastest qualification pathway.
The EPA governs volatile organic compound emissions during sol-gel processing, while OSHA mandates exposure limits for graphene nanoparticles in manufacturing facilities; REACH compliance in Europe adds substance registration burdens that reshape supplier eligibility. China's GB standards and MIIT directives on new material industrialization establish parallel certification tracks for import market access. Stakeholders must track evolving toxicity classifications under OECD testing guidelines and align capital deployment with whichever regulatory jurisdiction achieves harmonized standards first.
Market Dynamics
Aerospace thermal management specifications are compressing qualification timelines and forcing producers to demonstrate simultaneous electrical conductivity and thermal insulation performance under vacuum conditions.
Growth Catalysts
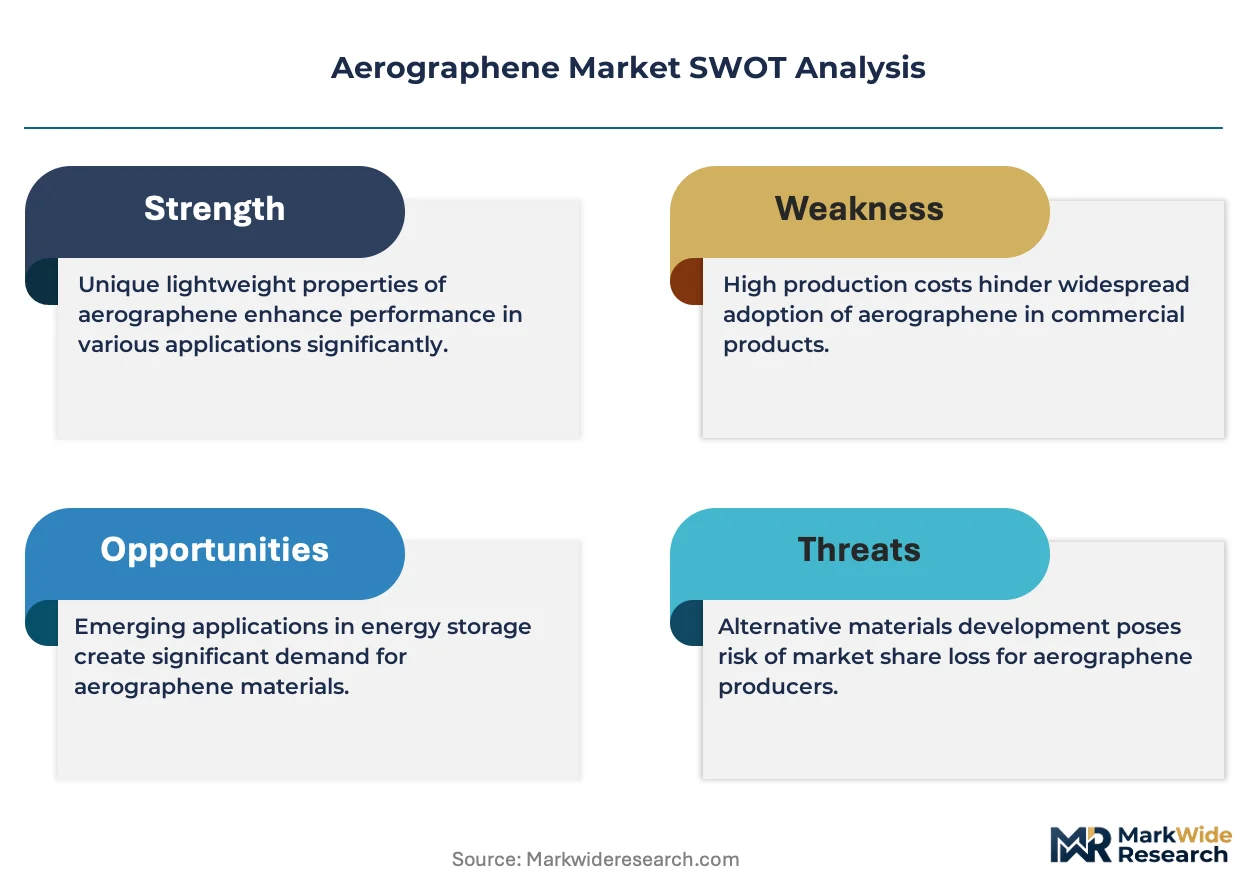
- REACH substance registration:ECHA's evolving chemical safety dossiers are filtering out non-compliant suppliers, concentrating procurement among qualified European producers.
- Satellite platform lightweighting:Defense contractors are mandating aerographene substrates for payload enclosures to maximize orbital capacity per launch.
- Hydrothermal reduction scale-up:Continuous-flow synthesis methods are cutting batch-to-batch variability and accelerating aerospace qualification pipelines.
Market Restraints
- Supercritical drying energy intensity:CO₂ solvent recovery systems consume 40-60% of production energy, anchoring cost floors regardless of precursor economics.
- Carbon precursor supply concentration:High-purity graphene oxide feedstock production clusters in China's Shandong and Jiangsu provinces, creating single-source vulnerability.
- Silica aerogel substitution:Established silica formulations with lower thermal conductivity thresholds compete in non-conductive insulation applications.
Strategic Opportunities
- India's PLI scheme for advanced materials:Domestic production incentives are opening import-substitution pathways for battery enclosure manufacturers.
- Automotive battery multifunctional substrates:OEMs are specifying aerographene composites that combine thermal runaway containment with electromagnetic shielding in single layers.
- ISO/TC 229 nanotechnology standardization:Harmonized measurement protocols for specific surface area and density are reducing cross-border certification duplication costs.
Industry Challenges
- Supercritical drying technician scarcity:Operators capable of maintaining CO₂ phase boundaries across 100+ liter vessels command premium wages and limit capacity expansion.
- OECD TG 412/413 inhalation toxicity data gaps:Sub-chronic studies on graphene nanoparticle exposure are pending, freezing workplace exposure limit harmonization.
- Legacy aerospace qualification inertia:Prime contractors require 18-36 month flight heritage demonstration before designating aerographene as approved material.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerographene Market |
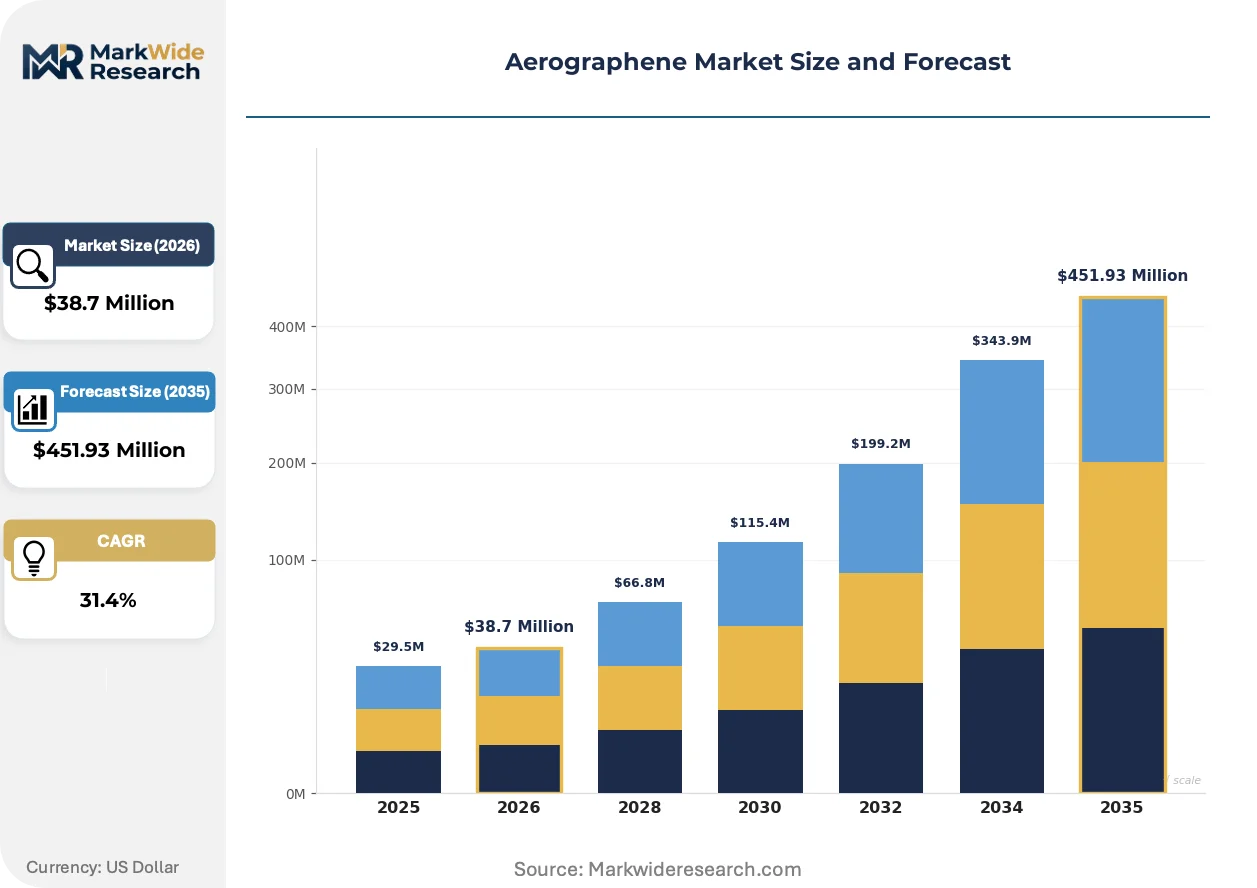
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $451.93 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphene Aerogel, Composite Materials, Coatings, Insulation Application: Energy Storage, Thermal Insulation, Sensors, Lightweight Structures End User: Aerospace, Automotive, Electronics, Construction Distribution Channel: Direct Sales, Online Retail, Distributors, B2B Sales |
| Companies Covered | Dow, Cabot Corporation, Aerograph Technologies Inc., Aspen Aerogels, American Elements, SGL Carbon SE, BASF SE, NGK Spark Plug, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerographene Market Emerging Trajectories
Continuous manufacturing architectures are replacing batch sol-gel processing, compressing cycle times and enabling real-time quality monitoring that was previously impossible.
Template-assisted chemical vapor deposition is displacing hydrothermal reduction for ultra-high-purity grades. Satellite manufacturers are adopting CVD-synthesized aerographene for mission-critical thermal straps. This displacement is compressing the performance gap between laboratory specimens and production-scale material, forcing incumbent hydrothermal producers to demonstrate cost advantages at equivalent purity levels.
China's MIIT directives on new material industrialization are mandating domestic substitution timelines for import-dependent aerospace supply chains. The regulations require tier-1 suppliers to certify alternative material sources within five-year windows. Battery enclosure manufacturers in Ningbo and Shenzhen are accelerating local aerographene qualification to maintain defense contractor eligibility.
Defense procurement offices are unbundling material qualification from system integration contracts, creating direct purchasing relationships with substrate producers. Tier-2 suppliers previously captive to prime contractors are establishing standalone aerospace certification portfolios. This pattern is most visible in Germany's industrial corridor, where specialty chemical clusters are building direct sales channels to satellite platform integrators.
Aerographene Market Segmentation
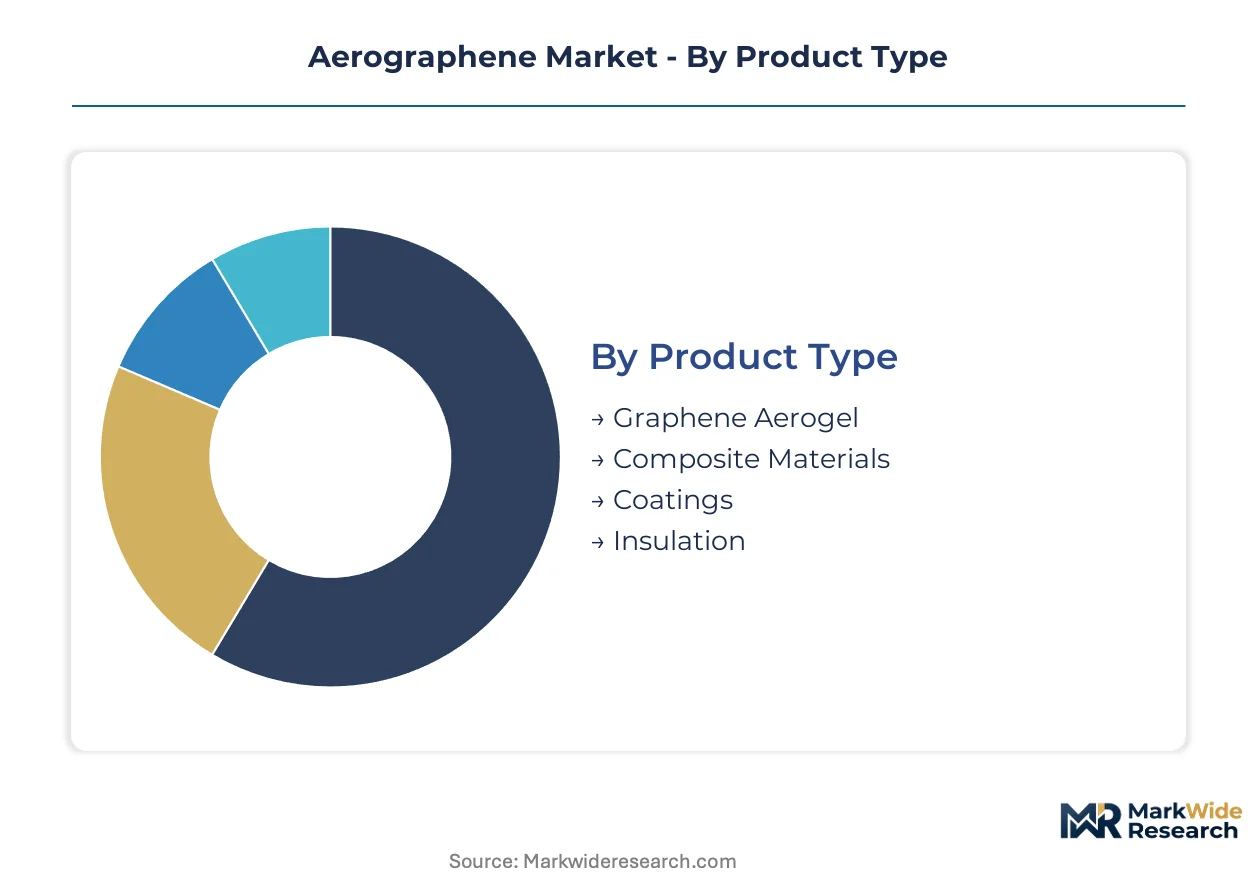
Aerographene procurement patterns diverge sharply across product grades and end-use specifications. Aerospace contractors demand traceable batch documentation that commodity channels cannot satisfy, while automotive buyers prioritize volume scalability over pedigree.
Product Type:
Domestic production concentrates graphene aerogel and composite materials in Germany's Ruhr Valley and China's Jiangsu corridor, whereas coatings and insulation flow through export-oriented distributors in Singapore and Rotterdam.
- Graphene Aerogel:Pure carbon architecture synthesized via hydrothermal reduction achieves density below 3 mg per cubic centimeter. Demand clusters in satellite thermal management systems where defense contractors mandate vacuum-qualified substrates with demonstrated flight heritage.
- Composite Materials:Multifunctional substrates integrating aerographene with polymer matrices deliver combined electromagnetic shielding and thermal runaway containment. Automotive OEMs in Stuttgart and Shanghai are specifying these for battery enclosure applications.
- Coatings:Thin-film formulations applied through spray deposition serve electronics manufacturers seeking localized thermal dissipation on circuit boards.
- Insulation:Bulk forms compete against silica aerogel in non-conductive applications where electrical properties remain secondary.
Graphene aerogel commands the established base. The steepest expansion runs through composite materials.
Application:
Cost tiering separates mission-critical aerospace qualifications from price-sensitive construction retrofit projects.
- Energy Storage:Electrode architectures leverage specific surface area exceeding 3000 square meters per gram to enhance ion transport kinetics. China's Ningbo battery cluster is absorbing production volumes for next-generation cell designs.
- Thermal Insulation:Extreme-environment performance under vacuum conditions drives qualification for satellite platform integrators. ECHA's REACH substance registration filters out non-compliant suppliers from European procurement pools.
- Sensors:Piezoresistive response to mechanical strain enables structural health monitoring in civil infrastructure.
- Lightweight Structures:Payload enclosure applications maximize orbital capacity per launch, with defense contractors mandating 18-36 month flight heritage demonstration before designating approved material status.
Energy storage anchors current volume. Lightweight structures are climbing the fastest as launch economics tighten.
End User:
Customer type determines certification burden and contract structure, with aerospace requiring standalone material qualification and automotive accepting system-level integration.
- Aerospace:Prime contractors unbundle material qualification from system integration, creating direct purchasing relationships with substrate producers. Germany's specialty chemical clusters are building standalone certification portfolios for satellite platform integrators.
- Automotive:OEM specifications for battery enclosures combine thermal runaway containment with electromagnetic shielding in single-layer substrates. India's PLI scheme for advanced materials is opening import-substitution pathways for domestic manufacturers.
- Electronics:Miniaturization trends drive demand for localized thermal management on high-density circuit boards.
- Construction:Building retrofit applications compete on installed cost against conventional insulation systems.
Aerospace dominates qualification pipelines. Automotive represents the volume unlock as cell architecture standardizes.
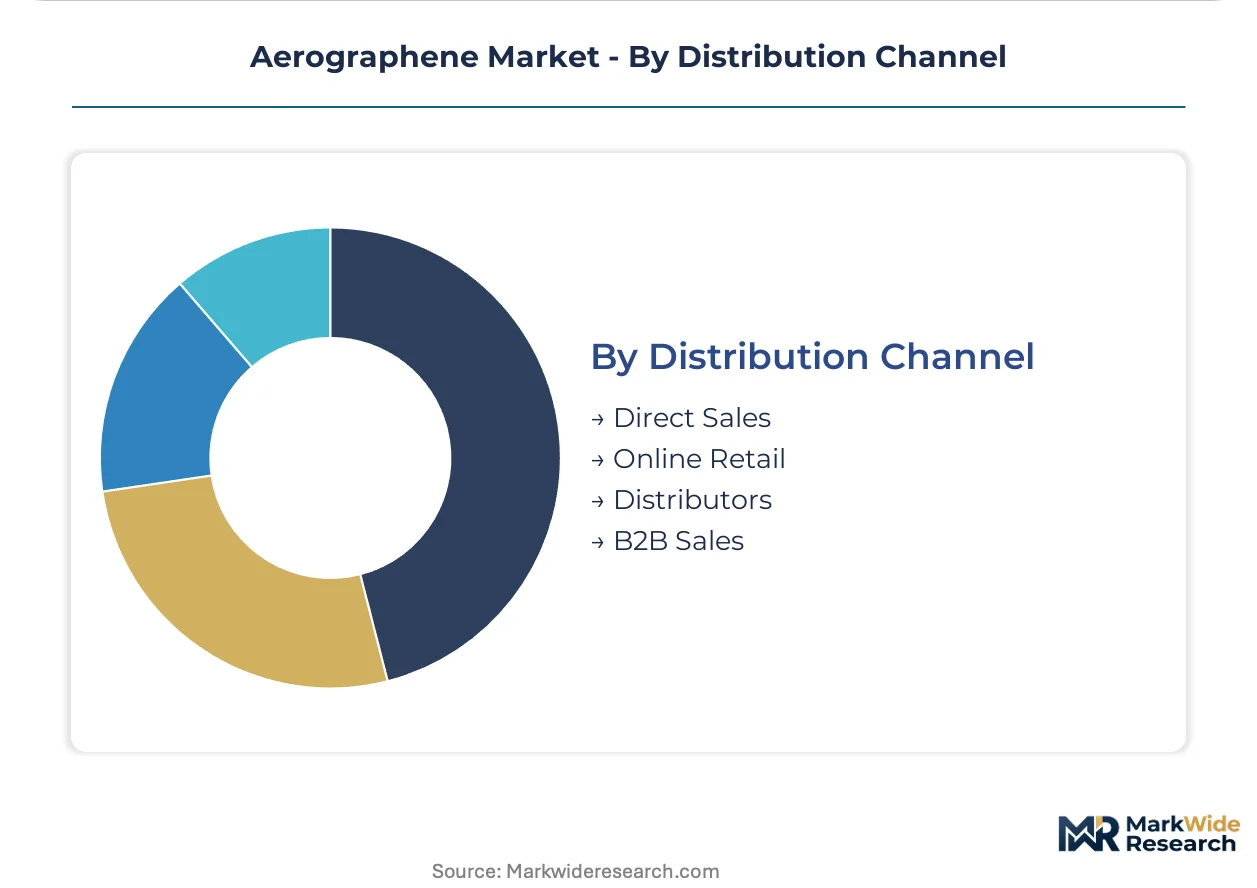
Distribution Channel:
Margin structures vary from captive direct sales with aerospace primes to fragmented online retail serving research laboratories.
- Direct Sales:Long-term supply agreements with tier-1 aerospace and automotive manufacturers include embedded technical service and joint qualification support.
- Online Retail:Small-batch procurement for research institutions and pilot-scale testing, with limited traceability documentation.
- Distributors:Regional stocking points in Rotterdam and Singapore buffer lead times for mid-volume electronics manufacturers.
- B2B Sales:Project-based contracting for construction and industrial applications with specification-driven sourcing.
Direct sales capture the premium tier. Distributors are gaining share fastest as electronics demand fragments geographically.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity graphene oxide feedstock production clusters in China's Shandong and Jiangsu provinces, creating single-source vulnerability that shapes procurement security calculations across downstream markets. Germany's Ruhr Valley specialty chemical infrastructure anchors European qualification pipelines, while US defense procurement offices unbundle material certification from system integration contracts.
China
MIIT directives on new material industrialization mandate domestic substitution timelines for import-dependent aerospace supply chains. The NMPA standards for advanced materials establish parallel certification tracks for import market access. Battery enclosure manufacturers in Ningbo and Shenzhen accelerate local aerographene qualification to maintain defense contractor eligibility.
Germany
ECHA's REACH substance registration filters out non-compliant suppliers from European procurement pools. The EU's REACH framework on chemical safety adds substance registration burdens that reshape supplier eligibility. Specialty chemical clusters in the Ruhr Valley build direct sales channels to satellite platform integrators.
United States
Defense contractors mandate aerographene substrates for payload enclosures to maximize orbital capacity per launch. The EPA governs volatile organic compound emissions during sol-gel processing, while OSHA mandates exposure limits for graphene nanoparticles in manufacturing facilities. Prime contractors require 18-36 month flight heritage demonstration before designating aerographene as approved material.
India
The PLI scheme for advanced materials opens import-substitution pathways for battery enclosure manufacturers. BIS standards for nanomaterials establish domestic certification requirements that parallel international protocols. Domestic production incentives concentrate new capacity in Gujarat and Maharashtra industrial corridors.
Japan
METI industrial policy prioritizes lightweight materials for satellite platform applications under national space development programs. JIS standards for carbon nanomaterials provide harmonized measurement protocols that reduce cross-border certification duplication costs. Kansai region chemical producers integrate aerographene qualification into existing aerospace supplier networks.
Aerographene Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with hydrothermal reduction specialists competing against continuous-flow synthesis innovators for aerospace qualification contracts. The vendor base spans diversified chemical conglomerates, dedicated aerogel producers, and carbon materials specialists, creating tiered competitive dynamics. Three archetypes dominate: captive carbon precursor producers leveraging upstream integration, specialty chemical firms anchoring European qualification pipelines, and dedicated aerogel manufacturers differentiating through thermal conductivity thresholds. Capacity expansion and strategic partnerships represent the dominant competitive moves, as producers seek to secure aerospace flight heritage and automotive OEM qualification simultaneously.
Among diversified chemical conglomerates, Dow and BASF SE occupy positions that exemplify captive supply chain advantages, while Evonik Industries AG anchors the European specialty chemical tier with dedicated aerogel expertise. Aspen Aerogels represents the pure-play aerogel specialist archetype, with SGL Carbon SE sitting within the carbon materials fabricator tier that supplies precursor feedstock downstream.
| Leading Market Players |
|---|
| Dow |
| Cabot Corporation |
| Aerograph Technologies Inc. |
| Aspen Aerogels |
| American Elements |
| SGL Carbon SE |
| BASF SE |
| NGK Spark Plug |
| Evonik Industries AG |
| Others |
Supply Flow & Price Mechanics
Template-assisted chemical vapor deposition displacing hydrothermal reduction simultaneously redraws supply geography toward Germany's Ruhr Valley specialty chemical clusters and compresses pricing economics for incumbent batch producers facing purity-equivalence demands from satellite platform integrators.
Pricing Analysis
REACH substance registration dictates the pricing tier structure across European procurement pools. Three-tier pricing structure across aerospace-qualified, industrial-grade, and research-laboratory levels separates traceable batch documentation from commodity channels. Cost compression in industrial-grade material is intensifying because silica aerogel substitutes compete on thermal conductivity thresholds. Automotive OEMs exhibit highest price sensitivity due to volume scale requirements, while defense contractors accept premium tiers for demonstrated flight heritage.
Supply Chain Analysis
Supercritical drying technician scarcity creates a chokepoint that constrains capacity expansion regardless of precursor availability. High-purity graphene oxide feedstock production clusters in China's Shandong and Jiangsu provinces, with carbon precursor supply drawing from SGL Carbon SE's European fabrication network. Single-source vulnerability in Asian feedstock anchors structural risk. Distribution runs through direct sales channels for aerospace primes and regional stocking points in Rotterdam for mid-volume electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aerospace procurement cycles are recovering from qualification timeline compression, with defense contractor unbundling of material certification from system integration contracts creating direct purchasing relationships that favor substrate producers with standalone aerospace portfolios.
For Market Incumbents: Shield established qualification pipelines by accelerating continuous-flow synthesis scale-up before CVD-synthesized aerographene achieves cost parity. Deepen backward integration into captive carbon precursor supply to mitigate Shandong-Jiangsu concentration risk. Prioritize joint qualification support embedded in long-term supply agreements with tier-1 aerospace manufacturers. For New Entrants and Emerging Players: India's PLI scheme for advanced materials certification fast-track offers the most penetrable entry pathway for battery enclosure manufacturers seeking import-substitution positioning. Target Gujarat and Maharashtra industrial corridors where domestic production incentives concentrate new capacity. Pursue automotive OEM qualification through multifunctional substrate specifications combining thermal runaway containment with electromagnetic shielding. For Investors and Strategic Acquirers: The market sits at a pre-harmonization phase that favors specialty chemical firms with established European qualification pipelines and direct sales channels to satellite platform integrators. Long-term viability hinges on securing aerospace flight heritage before ISO/TC 229 nanotechnology standardization reduces cross-border certification duplication costs. Watch ECHA's evolving chemical safety dossiers as the inflection signal for supplier concentration acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous-Flow Synthesis Scale-Up | Batch-to-batch variability reduction accelerates aerospace qualification timelines for hydrothermal producers. |
| Backward Integration into Carbon Precursor Supply | Dow's captive graphene oxide feedstock anchors cost discipline against Chinese supply concentration. |
| Aerospace Flight Heritage Demonstration | Eighteen-to-thirty-six month orbital performance documentation unlocks prime contractor approved material status. |
| Joint Venture with Satellite Platform Integrator | Direct purchasing relationships bypass tier-2 supplier captivity in Germany's Ruhr Valley cluster. |
| ISO/TC 229 Standardization Alignment | Harmonized specific surface area measurement protocols reduce certification duplication across EU-US-China jurisdictions. |
Methodological Framework
Operator-level perspectives from supercritical drying technicians, aerospace procurement officers at prime contractors, automotive OEM platform engineers, and specialty chemical R&D directors anchored the qualitative base. Primary interviews combined with secondary validation drawing from ECHA REACH substance registration databases, MIIT new material industrialization directives, SEC filings of diversified chemical conglomerates, and OECD TG 412/413 inhalation toxicity study protocols. Bottom-up capacity estimates triangulated against top-down demand projections from satellite launch manifests and battery enclosure production forecasts.
Sensitivity analysis tested forecast robustness across the projection horizon against variable supercritical drying energy intensity assumptions and carbon precursor supply disruption scenarios. Segmentation modeling incorporated product grade tier, end-use application, customer type certification burden, and regional regulatory cluster dimensions. CAGRs derived from slope-intercept fitting of historical qualification pipeline data and projected adoption curves in energy storage and lightweight structures. Industry-specific inputs included defense contractor flight heritage demonstration timelines and automotive cell architecture standardization trajectories.
Underlying assumptions cover REACH compliance maintenance, MIIT domestic substitution timeline adherence, and OECD toxicity classification finalization, with deviation risk concentrated in supercritical drying technician wage inflation and graphene oxide feedstock export restriction scenarios. Practitioners should keep alternative scenarios live as ECHA chemical safety dossier evolution and ISO/TC 229 harmonization progress unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Advanced Materials for Flying Cars Market
Aerospace and Aircraft Materials
Aircraft Coatings Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Radome Market
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Aerogel Blanket Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Aerospace Foam Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Thermal Spray Coating Market
Aerospace and Aircraft Materials
Global Flame Retardant for Aerospace Plastics Market
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market