
 Fiberglass for Aerospace Market | 2026-2036
Fiberglass for Aerospace Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass for Aerospace Market Analysis
The EU Green Deal's emissions reduction mandates for aviation is realigning procurement criteria across European airframe programs. Owens Corning leverages its North American manufacturing scale to supply certified E-glass formulations for primary structures. China Jushi Co., Ltd. anchors its position through backward integration into raw material processing, controlling silica and boron supply chains. AGY Holding specializes in high-performance S-2 glass fibers for military engine components, differentiating through elevated temperature resistance.
Fiberglass for aerospace comprises engineered glass fiber reinforcements manufactured from silica-alumina-boron compositions, typically achieving tensile strengths of 3,400-4,800 MPa depending on alkali content and sizing chemistry. These fibers serve primarily as structural reinforcements in polymer matrix composites, reducing airframe weight by 15-25% compared to aluminum alloys while maintaining damage tolerance. Continuous Fiber dominates current procurement volumes for automated fiber placement in wing skin fabrication, while Roving commands premium positioning in filament-wound engine nacelle components. Interior Components represents the fastest-growing application segment as cabin fire-smoke-toxicity regulations tighten and airlines retrofit existing fleets.
FAA certification standards under 14 CFR Part 25, EASA CS-25 airworthiness codes, and China's CAAC CCAR-25 framework collectively dictate flammability, smoke density, and structural durability requirements for fiberglass-reinforced components. REACH restrictions on boron compounds and the EU F-Gas Regulation are forcing reformulation of traditional E-glass chemistries toward boron-free alternatives. Stakeholders must monitor evolving OEM qualification timelines and pre-position alternative chemistries before regulatory deadlines eliminate incumbent formulations from new type certification programs.
Market Dynamics
OEM airframe programs are consolidating composite procurement around automated fiber placement systems, forcing fiberglass suppliers to certify continuous fiber formats for wing skin fabrication at scale. This manufacturing pivot is compressing qualification timelines and elevating material traceability requirements across the supply base.
Growth Catalysts
- EASA CS-25 Amendment 25-147:Tightened flammability standards for cabin interiors are mandating fiberglass-reinforced thermoset panels in retrofit programs across European narrowbody fleets.
- Automated fiber placement:Wing manufacturers in Germany and the United States are qualifying continuous E-glass formats for primary structure automation, displacing hand layup methods.
- Engine nacelle expansion:Next-generation turbofan programs are driving filament-wound fiberglass demand for acoustic liner substrates and thrust reverser cascades.
Market Restraints
- Boron supply concentration:E-glass formulations depend on boron sourced from limited mining operations in Turkey and the United States, exposing processors to input volatility and export restriction risk.
- Carbon fiber substitution:Primary wing spars and fuselage barrels in widebody programs are transitioning to carbon fiber composites, constraining fiberglass to secondary structures and interiors.
- REACH boron compound restrictions:ECHA classification of boric acid and borates as reproductive toxicants is forcing costly reformulation of traditional E-glass chemistries ahead of sunset dates.
Strategic Opportunities
- Urban air mobility airframes:Electric vertical takeoff and landing manufacturers in the United States and Germany are specifying S-2 glass for rotor blade impact resistance at reduced weight thresholds.
- CAAC CCAR-25 harmonization:China's alignment with FAA and EASA flammability standards is opening qualification pathways for certified fiberglass suppliers in COMAC C919 and CR929 programs.
- Interior retrofit cycles:Post-pandemic cabin reconfiguration programs are accelerating demand for fiberglass-reinforced sidewall panels and overhead bin structures with enhanced fire-smoke-toxicity ratings.
Industry Challenges
- Composite technician scarcity:Automated fiber placement and filament winding operations require specialized programming and material handling skills that outpace vocational training output in aerospace manufacturing clusters.
- OEM qualification timelines:Boeing and Airbus material approval processes extend 18-36 months for new fiberglass formulations, freezing supplier switching and delaying revenue recognition for certified alternatives.
- Legacy fleet integration:Fiberglass components for aging aircraft must meet original type certificate specifications while sourcing base materials that original suppliers no longer manufacture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass for Aerospace Market |
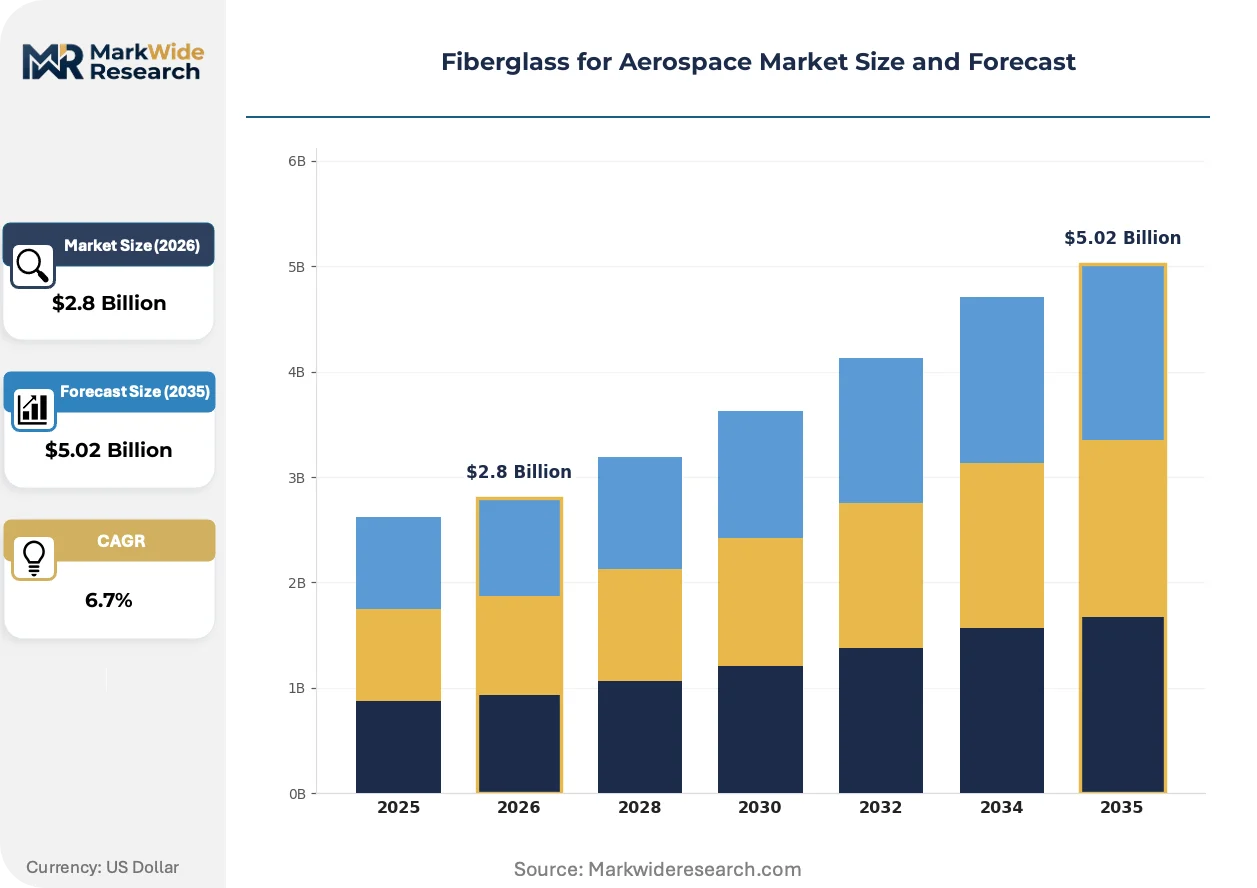
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Fiber, Glass Wool, Roving, Batts Application: Airframe, Engine Components, Wing Structures, Interior Components Manufacturing Stage: Raw Material Processing, Component Fabrication, Final Assembly, Quality Control End User: Commercial Aviation, Military Aviation, Spacecraft Manufacturing, Repair & Maintenance |
| Companies Covered | Owens Corning, China Jushi Co., Ltd., Johns Manville, Saint-Gobain Vetrotex, 3B Fibreglass, Chongqing Polycomp International Corp., AGY Holding, PPG Industries, Hexcel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass for Aerospace Market Emerging Trajectories
Boron-free glass chemistries are advancing through qualification pipelines as regulatory deadlines approach, while digital thread technologies are embedding material traceability from fiber formation through final component inspection. These shifts are redefining supplier capability requirements.
S-2 glass fiber formulations are unifying high-temperature engine component requirements with structural airframe applications through improved silica-alumina ratios and advanced sizing chemistries. Military engine manufacturers are qualifying these fibers for exhaust fairings and augmentor liners. Commercial OEMs are adopting S-2 glass for hot-zone proximity structures, compressing the traditional performance gap between E-glass and carbon fiber alternatives in temperature-critical zones.
The EU F-Gas Regulation is phasing down hydrofluorocarbon blowing agents used in fiberglass-reinforced foam core production for sandwich panels. European interior component manufacturers are reformulating with water-blown and hydrocarbon alternatives. German and French Tier 1 suppliers are absorbing qualification costs for new core materials to maintain EASA certification continuity under amended CS-25 Appendix F test protocols.
Airline procurement organizations are consolidating fiberglass component sourcing through airframe OEM direct buy agreements rather than aftermarket distributor channels. This channel compression eliminates intermediate inventory positions and forces suppliers to hold consignment stock at final assembly lines. The United States and China exhibit the most pronounced consolidation, with Boeing, Airbus, and COMAC exerting greater pricing leverage through volume commitment structures.
Fiberglass for Aerospace Market Segmentation
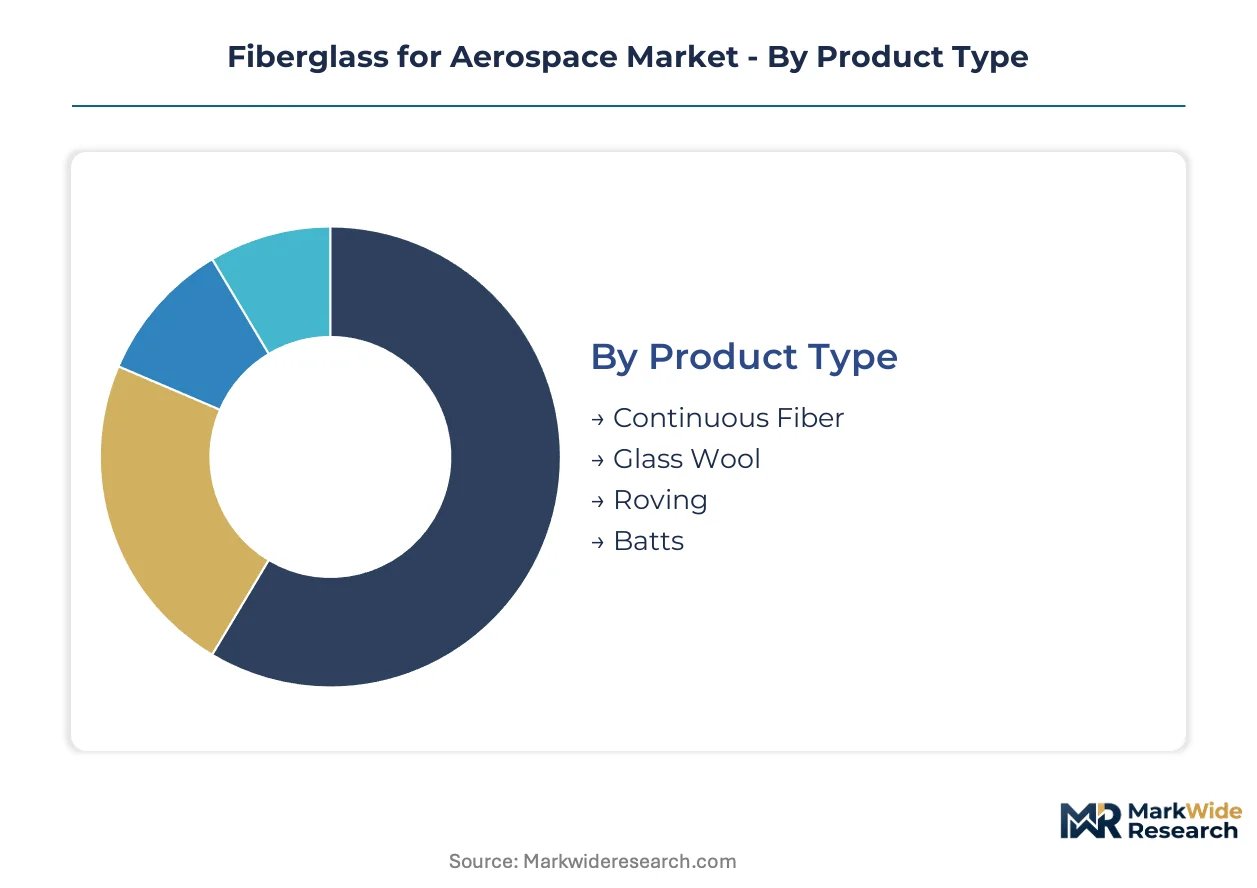
Segmentation in aerospace fiberglass tracks how material formats, application requirements, and certification stages fragment procurement specifications across OEM and aftermarket channels. Each dimension shapes supplier qualification timelines and pricing structures differently.
Product Type:
Continuous Fiber commands volume procurement for automated manufacturing lines, while Roving captures premium positioning in specialized winding applications.
- Continuous Fiber:Long, unidirectional glass filaments designed for automated fiber placement systems in wing skin fabrication. Boeing and Airbus narrowbody programs in the United States and Germany specify continuous E-glass formats for primary structure automation, displacing hand layup methods and compressing cycle times.
- Roving:Bundled glass strands assembled for filament winding and pultrusion processes. Next-generation turbofan engine nacelle programs specify roving for acoustic liner substrates and thrust reverser cascades, where precise fiber orientation controls acoustic damping performance.
- Glass Wool:Discontinuous fiber mats used primarily for thermal and acoustic insulation in aircraft interiors. Cabin retrofit programs specify glass wool for firewall blankets and duct insulation meeting FAA 14 CFR Part 25 flammability standards.
- Batts:Pre-formed insulation blankets cut to dimensional specifications for fuselage cavity filling. Regional jet manufacturers specify batts for sidewall and crown insulation in secondary structure zones.
Mature deployment sits with Continuous Fiber. Newer deployment is concentrated in Roving as engine nacelle programs expand filament-wound component specifications.
Application:
Structural applications anchor material qualification investments, while interior retrofits drive fastest-expanding demand cycles.
- Airframe:Primary and secondary structural reinforcements in fuselage panels, floor beams, and bulkheads. E-glass composites reduce airframe weight by 15-25% compared to aluminum alloys while maintaining damage tolerance for commercial narrowbody programs.
- Interior Components:Sidewall panels, overhead bins, galley structures, and lavatory modules requiring fire-smoke-toxicity compliance. EASA CS-25 Amendment 25-147 tightened flammability standards, mandating fiberglass-reinforced thermoset panels in European narrowbody fleet retrofit programs.
- Wing Structures:Skin panels, spar caps, and rib reinforcements in fixed-wing aircraft. Automated fiber placement systems in Germany and the United States qualify continuous fiber formats for wing fabrication at scale.
- Engine Components:Exhaust fairings, augmentor liners, and nacelle structures in proximity to hot zones. S-2 glass fibers with elevated temperature resistance serve military engine manufacturers for components exceeding E-glass thermal limits.
Structural applications concentrate procurement volume. Interior Components climb the fastest as post-pandemic cabin reconfiguration accelerates demand for fire-rated sidewall and overhead structures.
Manufacturing Stage:
Upstream processing controls material traceability, while downstream stages dictate certification liability distribution.
- Raw Material Processing:Silica-alumina-boron batch formulation, melting, and fiber formation with sizing chemistry application. China Jushi Co., Ltd. anchors position through backward integration into silica and boron supply chains, controlling input volatility.
- Component Fabrication:Prepreg manufacturing, filament winding, and automated fiber placement of semi-finished composite forms. German Tier 1 suppliers absorb qualification costs for new core materials to maintain EASA certification continuity under amended CS-25 protocols.
- Final Assembly:Integration of fiberglass-reinforced components into airframe structures at OEM facilities. Boeing, Airbus, and COMAC exert pricing leverage through direct buy agreements and volume commitment structures.
- Quality Control:Non-destructive testing, material traceability verification, and airworthiness documentation. Digital thread technologies embed traceability from fiber formation through final component inspection.
Component Fabrication captures margin concentration. Quality Control is gaining investment priority as OEM qualification timelines extend and traceability requirements tighten.
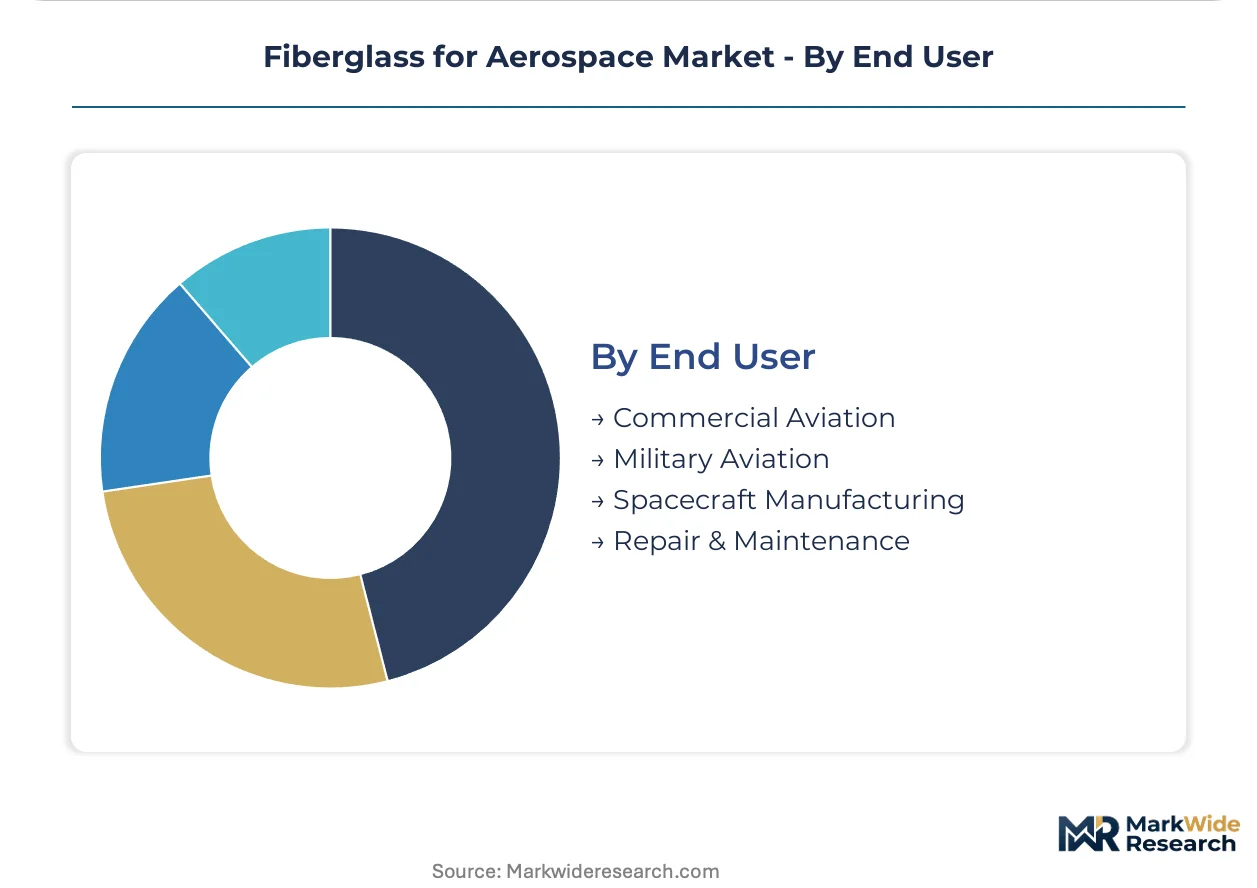
End User:
Commercial aviation drives procurement scale, while military and space applications specify performance premiums.
- Commercial Aviation:OEM airframe programs and fleet retrofit demand from passenger and cargo operators. FAA and EASA airworthiness directives for reduced-emission aircraft tighten material performance requirements across Boeing and Airbus supply chains.
- Military Aviation:Fighter, transport, and rotorcraft programs with specialized survivability and signature requirements. AGY Holding supplies S-2 glass fibers for military engine components, differentiating through elevated temperature resistance.
- Spacecraft Manufacturing:Launch vehicle structures and satellite components requiring extreme thermal cycling durability. Limited procurement volumes concentrate with specialized composite shops serving NASA and ESA contractor networks.
- Repair & Maintenance:Aftermarket component replacement and damage repair for aging fleets. Legacy fleet integration challenges arise as original base materials cease manufacture while type certificate specifications remain fixed.
Commercial Aviation anchors procurement volume. Military Aviation concentrates premium-grade S-2 glass demand for high-temperature engine proximity structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle anchors North American aerospace fiberglass demand through Boeing's final assembly lines for 737 MAX and 777X programs. The Puget Sound cluster concentrates automated fiber placement capacity for wing skin fabrication. FAA 14 CFR Part 25 certification timelines drive supplier co-location around Everett and Renton facilities.
United States
Boeing's 737 MAX and 777X production lines in Washington and South Carolina consume continuous E-glass formats for primary wing structures. FAA airworthiness directives for reduced-emission aircraft tighten material traceability requirements across the supply base. The Wichita, Kansas aerostructure cluster hosts Tier 1 suppliers qualifying fiberglass prepregs for automated fiber placement systems.
Germany
Airbus Hamburg and Toulouse-bound component flows drive filament-wound fiberglass demand for engine nacelle programs. EASA CS-25 Amendment 25-147 mandates upgraded fire-smoke-toxicity ratings for cabin interior retrofits across European narrowbody fleets. The Bavarian aerospace corridor around Munich concentrates S-2 glass qualification activity for military engine proximity structures.
China
COMAC C919 and CR929 programs in Shanghai and Xian generate procurement scale for certified E-glass formulations in primary airframe applications. CAAC CCAR-25 harmonization with FAA and EASA standards opens qualification pathways for international suppliers. The Yangtze River Delta cluster around Jiaxing hosts backward-integrated fiberglass producers controlling silica and boron supply chains.
France
Airbus Toulouse final assembly lines anchor fiberglass demand for A320neo and A350 programs across wing and fuselage applications. The EU F-Gas Regulation forces reformulation of foam core materials in sandwich panels for interior components. The Toulouse-Blagnac aerocluster hosts Tier 1 suppliers absorbing qualification costs for boron-free glass chemistries ahead of REACH sunset dates.
United Kingdom
Rolls-Royce engine programs in Derby and Bristol specify S-2 glass fibers for exhaust fairings and augmentor liners requiring elevated temperature resistance. UK Export Finance supports composite supplier qualification for military aerospace contracts. The South West England aerospace cluster around Bristol concentrates digital thread implementation for material traceability from fiber formation through component inspection.
Fiberglass for Aerospace Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and performance grade. The vendor base stratifies between E-glass commodity suppliers and S-2 glass specialists capturing temperature-critical premiums. Three archetypes dominate: backward-integrated raw material processors, automated manufacturing format specialists, and high-performance fiber niche players. Capacity expansion and qualification timeline acceleration represent the dominant competitive moves as OEM consolidation compresses supplier switching windows.
Among North American material suppliers, Owens Corning occupies a position exemplifying scale-driven E-glass certification for primary structures. China Jushi Co., Ltd. anchors the backward-integrated archetype through captive control of silica and boron inputs. AGY Holding represents the high-performance specialist tier, with its portfolio sitting within temperature-resistant fiber applications for military and commercial engine proximity zones.
| Leading Market Players |
|---|
| Owens Corning |
| China Jushi Co., Ltd. |
| Johns Manville |
| Saint-Gobain Vetrotex |
| 3B Fibreglass |
| Chongqing Polycomp International Corp. |
| AGY Holding |
| PPG Industries |
| Hexcel |
| Others |
Supply Flow & Price Mechanics
Composite technician scarcity in the Puget Sound cluster and Bavarian aerospace corridor widens labor-cost differentials between automated fiber placement specialists and hand layup operators, compressing margin spreads across premium-certified and standard-grade fiberglass tiers.
Pricing Analysis
Certified airframe qualification outcomes anchor value-based pricing, with continuous fiber formats commanding premiums tied to FAA and EASA material approval cycles. Pricing stratifies across S-2 glass temperature-resistance tiers, E-glass primary structure grades, and commodity roving for interior applications. Cost compression in E-glass formulations is intensifying because REACH boron restrictions force reformulation investments ahead of sunset dates. Aftermarket repair and maintenance channels exhibit highest price sensitivity due to legacy fleet budget constraints, while military engine programs show lowest sensitivity given survivability specifications.
Supply Chain Analysis
Domestic-content mandates in China's COMAC programs and U.S. Buy American provisions for military aerospace are reshaping sourcing patterns toward qualified local suppliers. Raw material processing concentrates in China, the United States, and Turkey, with boron compound supply anchored in Turkish mining operations and U.S. desert deposits. Borate supply vulnerability from export restriction risk and ECHA regulatory reclassification threatens E-glass chemistry continuity. Distribution runs through direct buy agreements with Boeing, Airbus, and COMAC final assembly lines, eliminating traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fiberglass for aerospace market functions as a vertical-integration race, with silica-boron supply chain control and automated manufacturing format certification serving as the decisive levers separating margin capture from commodity positioning.
For Market Incumbents: Hedge against carbon fiber substitution in primary wing structures by accelerating S-2 glass qualification for engine proximity zones and hot-zone airframe applications. Deepen backward integration into boron-free glass chemistry R&D ahead of REACH enforcement timelines. Lock in multi-year volume commitments with COMAC and emerging urban air mobility manufacturers to defend position against Chinese state-backed producers. For New Entrants and Emerging Players: Capture white-space in boron-free E-glass formulations serving European retrofit programs under EASA CS-25 Amendment 25-147. Target interior component Tier 1 suppliers in Germany and France absorbing qualification costs for foam core reformulation. Lead with digital thread traceability capabilities to compress OEM approval timelines for new market entrants. For Investors and Strategic Acquirers: Re-rating potential sits with backward-integrated specialty glass producers given CAAC-FAA-EASA harmonization opening Chinese qualification pathways. Long-term viability favors suppliers controlling captive boron or silica inputs with demonstrated military temperature-resistance certification. Monitor urban air mobility airframe program announcements as inflection signal for S-2 glass demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Boron-Free Glass Chemistry Qualification | REACH compliance ahead of sunset dates preserves EASA certification continuity for European suppliers. |
| Automated Fiber Placement Format Certification | Boeing and Airbus narrowbody programs specify continuous E-glass for wing skin fabrication at scale. |
| Backward Integration into Silica-Boron Supply | China Jushi's captive raw material control insulates margin against Turkish borate export volatility. |
| Digital Thread Traceability Implementation | FAA 14 CFR Part 25 material documentation requirements compress supplier switching windows. |
| Urban Air Mobility Partnership Development | eVTOL rotor blade specifications in the United States and Germany specify S-2 glass impact resistance. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this fiberglass for aerospace market assessment. Primary interviews with composite manufacturing engineers, Tier 1 supplier procurement directors, FAA certification specialists, and military aerospace program managers combined with bottom-up and top-down triangulation. Secondary validation drew from EASA CS-25 amendment documentation, FAA airworthiness directive databases, REACH substance restriction timelines, and customs import records for boron compound flows.
Data-stream reconciliation across production volume estimates, OEM procurement disclosures, and material qualification timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, application category, manufacturing stage, and end-user archetype. CAGRs were derived from regression analysis against airframe delivery forecasts and retrofit cycle acceleration. Industry-specific inputs encompassed automated fiber placement adoption curves and EASA flammability standard amendment implementation rates.
The model holds under stable regulatory harmonization between FAA, EASA, and CAAC frameworks; deviation in boron compound restriction timelines or COMAC program delays would shift volume trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Global Aerospace Adhesives and Sealants Market
Aerospace and Aircraft Materials
Titanium Sponge for Aerospace and Defense Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Aerospace Foam Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Ablative Coatings Market
Aerospace and Aircraft Materials
Commercial Aircraft Honeycomb Core Market
Aerospace and Aircraft Materials
Magnesium Beryllium Alloy Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market
Aerospace and Aircraft Materials
Aviation Coatings Market
Aerospace and Aircraft Materials
Aerospace High-Performance Alloys Market
Aerospace and Aircraft Materials
Aerospace Cold Forgings Market