
 Global Military Aerospace Coatings Market | 2026-2036
Global Military Aerospace Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military Aerospace Coatings Market Intelligence
Direct sales channels between coating manufacturers and national defense agencies is rewriting the role of traditional distributors. PPG Industries leverages its extensive R&D infrastructure to secure long-term government contracts for advanced materials. Akzo Nobel specializes in chromate-free primers and topcoats, aligning with stringent environmental standards. Sherwin-Williams competes by offering a broad portfolio of qualified products that meet various military specifications, securing its position within the maintenance, repair, and overhaul supply chain.
Military aerospace coatings are advanced material systems applied to the exterior and interior of military aircraft. These formulations provide critical protection against corrosion, abrasion, and chemical exposure, often incorporating pigments for camouflage or low-observability characteristics. Their primary function is to extend aircraft service life and enhance mission survivability. Polyurethane topcoats command a significant share due to their durability and chemical resistance, while demand for advanced anti-corrosion primers is a key growth area.
Product formulation is heavily governed by environmental regulations. The U.S. Environmental Protection Agency (EPA) and Europe's ECHA under the REACH framework impose strict controls on volatile organic compounds (VOCs) and hexavalent chromium. These rules mandate the development of safer, more sustainable alternatives like water-based and high-solids coatings. Navigating the complex matrix of performance specifications and evolving chemical regulations is the central challenge for material suppliers.
Market Dynamics
The market's core dynamic is the direct conflict between escalating military performance specifications for survivability and the global regulatory mandate to eliminate hazardous materials like hexavalent chromium. This tension dictates material science priorities and reshapes the competitive landscape for suppliers.
Growth Catalysts
- UAV Fleet Expansion:The proliferation of Unmanned Aerial Vehicles for surveillance and combat roles requires specialized, lightweight coatings with unique thermal and low-observability signatures, creating a distinct new demand stream.
- Aircraft Modernization Programs:Government initiatives in the United States and allied nations to extend the service life of aging fleets, such as heavy-lift transports and fighter jets, drive consistent demand for high-performance anti-corrosion and repair coatings.
- Advanced Primer Systems:Development of chromate-free primers that offer corrosion resistance comparable to legacy systems is unlocking new refurbishment and MRO contracts, as operators comply with stricter environmental health and safety standards.
Market Restraints
- Raw Material Volatility:Price and availability fluctuations for key inputs like titanium dioxide, specialty polymers, and rare earth elements used in low-observable coatings create margin pressure and supply chain instability for manufacturers.
- Stringent Qualification Timelines:The extensive and costly process for testing and certifying new coating systems against military specifications can take years, creating a significant barrier to entry and slowing the adoption of innovative materials.
- Low-Observability Maintenance Complexity:The specialized materials and application techniques required to repair stealth coatings without compromising their radar-absorbent properties are extremely expensive and limit repairs to highly secure depot facilities.
Strategic Opportunities
- Functional Coating Integration:Incorporating properties like self-healing, de-icing, or embedded sensing into coating layers offers a path to higher-value, differentiated products that enhance aircraft operational availability and reduce maintenance burdens.
- Asia-Pacific Defense Growth:Rising defense budgets and indigenous aerospace manufacturing programs in countries like India, South Korea, and Japan present underpenetrated markets for qualified coating suppliers able to navigate local procurement requirements.
- Sustainable Formulation Leadership:Companies that establish a technology lead in high-performance, water-based, or high-solids polyurethane and epoxy systems compliant with both EPA and ECHA rules can capture share from slower-moving competitors.
Industry Challenges
- Navigating Regulatory Divergence:Formulating a single product that meets the distinct and evolving chemical regulations of both the U.S. EPA and Europe's REACH framework is a major technical and compliance hurdle for global suppliers.
- Application Specialist Scarcity:A shortage of technicians trained in the precise surface preparation and application of advanced multi-layer coating systems, particularly for in-field repairs, creates bottlenecks in MRO workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military Aerospace Coatings Market |
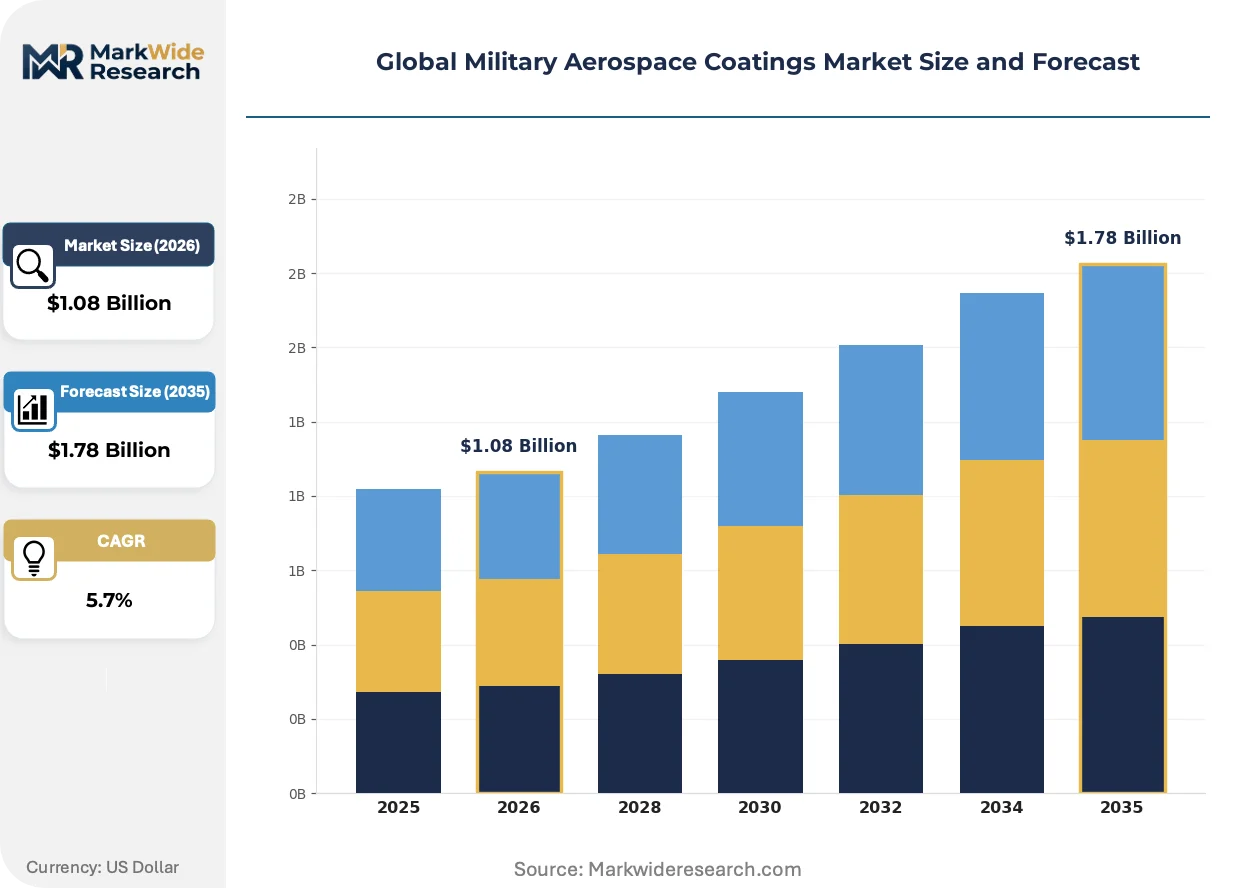
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.78 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primer, Topcoat, Anti-Corrosion, Thermal Barrier, Decorative, Sealant Technology: Solvent-Based, Water-Based, Powder Coating, Fluoropolymer, Epoxy, Polyurethane Application: Fighter Jets, Helicopters, UAVs, Bombers, Transport Aircraft, Reconnaissance Aircraft End User: Defense Contractors, Aircraft Maintenance Providers, Government Agencies, Special Forces |
| Companies Covered | BASF, Hentzen Coatings, Akzo Nobel, Argosy International, BryCoat, PPG Industries, Henkel, Mankiewicz Coatings, Sherwin-Williams, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military Aerospace Coatings Market Strategic Shifts & Innovations
Material science innovation is responding to a dual mandate for enhanced mission survivability and environmental sustainability. This pressure accelerates the development of multifunctional coatings that perform beyond basic protection, altering how airframes are maintained over their lifecycle.
Smart coating systems incorporate chemical or physical taggants to monitor for corrosion, impacts, or chemical agent exposure. Defense maintenance, repair, and overhaul (MRO) organizations are beginning to evaluate these systems to enable condition-based maintenance schedules rather than fixed-interval inspections. This technology is digitizing the process of airframe health monitoring, linking the physical state of the coating directly to platform lifecycle management software.
Europe's REACH regulation continues to expand its list of restricted substances, directly impacting legacy formulations used on long-service-life platforms. The industrial consequence is a forced requalification cycle for coatings on aircraft operated by NATO members and other European air forces. The primer and pretreatment segment is most affected, compelling a transition to chromate-free alternatives that must prove performance equivalence.
Direct engagement between coating specialists and national defense agencies for R&D and supply contracts is altering the market structure. This collaborative model often bypasses traditional tiered distributors, particularly for advanced systems like stealth or anti-icing coatings. The trend is most visible within large-scale United States Department of Defense aviation programs, where material solutions are co-developed with the prime airframe contractor.
Global Military Aerospace Coatings Market Segmentation
Understanding the distinct requirements of military aerospace coatings across various segments is critical for suppliers to align product development and market strategies. This granular analysis reveals where innovation cycles are shortest, demanding rapid adaptation, versus segments characterized by longer qualification timelines and established material specifications.
Product Type:
The turnover rate for coating products varies significantly, with some formulations requiring frequent updates due to evolving threats or environmental mandates, while others maintain long-standing specifications.
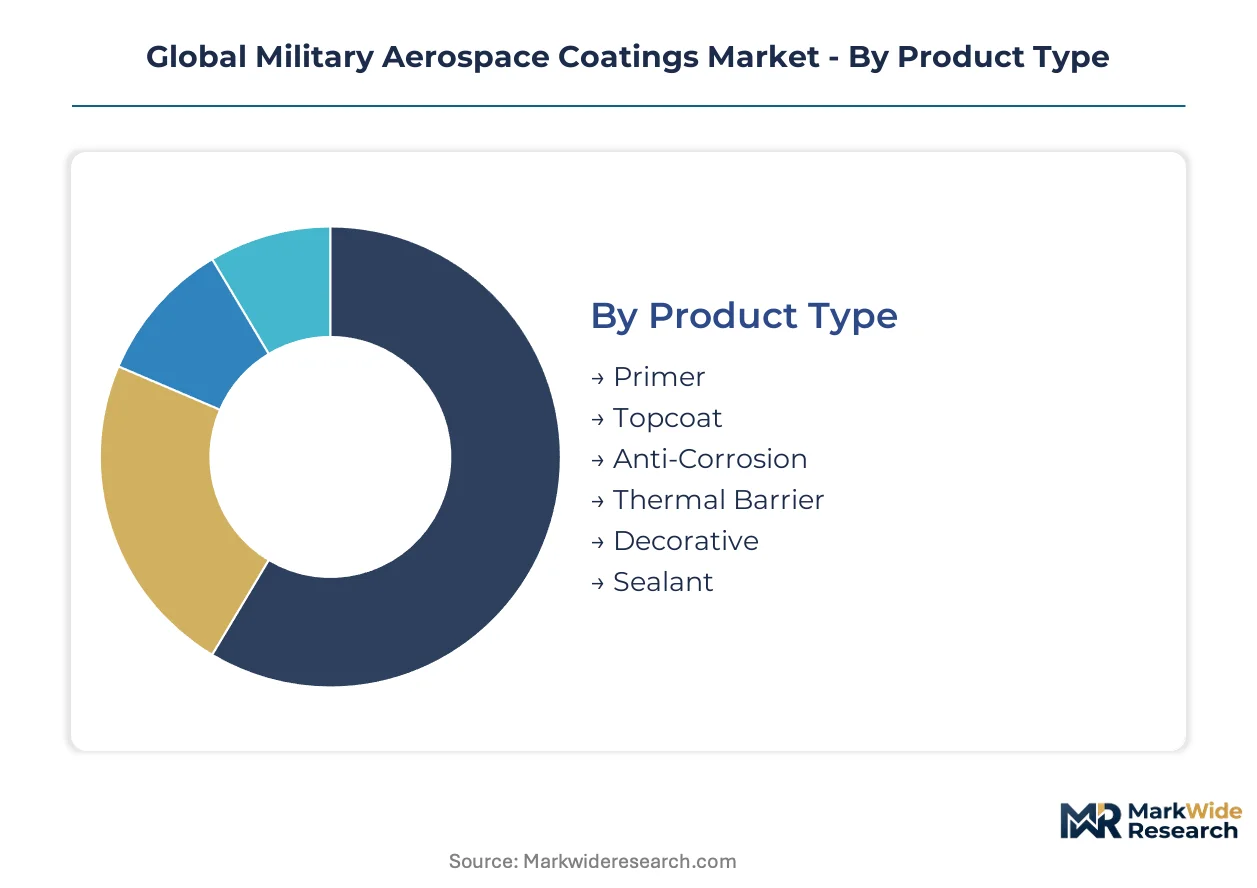
- Primer:These base layers provide essential adhesion and corrosion protection to the substrate, forming the foundation for subsequent coating layers. Demand for advanced chromate-free primers is driven by stringent environmental regulations from the U.S. Environmental Protection Agency and Europe's ECHA, necessitating continuous reformulation.
- Topcoat:Applied as the outermost layer, topcoats deliver critical protection against abrasion, chemical exposure, and UV radiation, often incorporating camouflage or low-observability characteristics. Polyurethane topcoats command significant market share due to their superior durability and chemical resistance, particularly for high-performance aircraft.
- Anti-Corrosion:Specialized coatings designed to prevent metal degradation, extending the service life of military aircraft components.
- Thermal Barrier:Formulations engineered to protect aircraft parts from extreme heat generated by engine operation or high-speed flight.
- Decorative:Coatings primarily used for aesthetic purposes or non-critical interior surfaces, adhering to less stringent performance criteria.
- Sealant:Materials used to fill gaps and prevent fluid ingress, crucial for maintaining structural integrity and aerodynamic efficiency.
Primer anchors the volume base while Anti-Corrosion gains share at the steepest rate.
Technology:
Different coating technologies present varying cost structures and performance envelopes, influencing their adoption across military aircraft platforms and maintenance cycles.
- Polyurethane:This technology offers excellent durability, chemical resistance, and flexibility, making it a preferred choice for high-performance topcoats on military aircraft. Demand for polyurethane systems is robust across fighter jets and transport aircraft due to their long service life.
- Water-Based:These environmentally compliant formulations reduce volatile organic compound emissions, aligning with global regulatory pressures from the U.S. Environmental Protection Agency and ECHA. Water-based coatings are gaining traction in MRO applications and for new aircraft programs seeking sustainable alternatives.
- Solvent-Based:Traditional formulations offering strong performance characteristics, though facing increasing regulatory scrutiny due to high VOC content.
- Powder Coating:An environmentally friendly application method that uses electrostatically charged dry powder, ideal for components requiring durable finishes.
- Fluoropolymer:Known for exceptional chemical resistance and low friction properties, used in specific applications requiring extreme environmental protection.
- Epoxy:Provides excellent adhesion and corrosion resistance, frequently used as a robust primer or intermediate coating layer.
Polyurethane represents a large installed base while Water-Based technology is expanding most quickly.
Application:
The specific operational demands and mission profiles of different aircraft types dictate unique coating requirements, from stealth properties to extreme durability.
- UAVs:Unmanned Aerial Vehicles require specialized, lightweight coatings with unique thermal management and low-observability signatures due to their diverse surveillance and combat roles. The expansion of UAV fleets globally drives significant demand for these advanced material systems.
- Fighter Jets:These aircraft demand high-performance coatings that withstand extreme speeds, temperatures, and G-forces, often incorporating stealth capabilities and advanced camouflage. Modernization programs for existing fighter fleets in the United States and allied nations sustain consistent demand.
- Helicopters:Coatings for helicopters must endure severe vibration, abrasion, and diverse environmental conditions, providing robust protection for rotors and airframes.
- Bombers:Large strategic aircraft require durable coatings that offer long-range protection against environmental factors and potential radar signature management.
- Transport Aircraft:These heavy-lift platforms need highly durable and corrosion-resistant coatings to ensure extended service life and operational reliability.
- Reconnaissance Aircraft:Specialized platforms demanding coatings that enhance stealth, reduce thermal signatures, and protect sensitive onboard equipment.
Fighter Jets form a substantial segment while UAVs are climbing the fastest.
End User:
The procurement and application of military aerospace coatings are channeled through distinct end-user categories, each with specific purchasing processes and material needs.
- Defense Contractors:These prime manufacturers and system integrators procure vast quantities of coatings for new aircraft production and major overhaul programs. Direct engagement with coating specialists is common for R&D and supply contracts, particularly within large United States Department of Defense programs.
- Government Agencies:National defense agencies often procure coatings directly for their own maintenance, repair, and overhaul facilities, setting specific performance and environmental standards. The United States military operates extensive depot facilities requiring specialized coating materials.
- Aircraft Maintenance Providers:Third-party companies specializing in MRO services require a broad portfolio of qualified coatings that meet various military specifications for fleet upkeep.
- Special Forces:These units may require highly specialized, mission-specific coatings for smaller fleets or unique operational requirements, often prioritizing rapid deployment and stealth.
Defense Contractors represent a primary demand driver while Government Agencies are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Environmental Protection Agency (EPA) heavily influences product development in the global military aerospace coatings market, particularly for low-VOC formulations. Procurement remains heavily concentrated in the United States, driven by extensive military aviation programs and modernization initiatives. This demand profile shapes material science priorities worldwide.
United States
The United States drives significant demand for military aerospace coatings through its extensive aviation programs and ongoing aircraft modernization initiatives. Strict EPA regulations necessitate continuous innovation in low-VOC and chromate-free formulations. Wichita, Kansas, remains a pivotal hub for aerospace manufacturing and MRO, generating consistent demand for advanced repair coatings.
France
France sustains demand through its robust indigenous aerospace manufacturing base, including active fighter jet programs. ECHA regulations under the REACH framework mandate the adoption of sustainable, chromate-free primer systems. Toulouse, a primary European aerospace hub, concentrates on advanced material integration and testing for next-generation military platforms.
Germany
Germany contributes to demand through ongoing aircraft modernization programs and extensive MRO activities for NATO member fleets. ECHA regulations under REACH significantly influence material selection, pushing for safer, high-performance alternatives. Hamburg's prominent aerospace cluster focuses on MRO and specialized coating applications for transport and mission aircraft.
Japan
Japan's indigenous defense production capabilities and ongoing fighter jet development programs create specialized demand for military aerospace coatings. METI actively supports research into advanced materials, including functional coatings, for defense applications. Nagoya, a significant aerospace manufacturing region, integrates advanced coating technologies into its fighter and transport aircraft production lines.
India
India's rising defense budgets and expanding indigenous aerospace manufacturing programs open new avenues for military aerospace coatings. BIS standards increasingly guide material specifications for defense procurement, emphasizing performance and local compliance. Bengaluru, a prominent aerospace and defense hub, focuses on MRO services and local production of specialized coating systems.
Global Military Aerospace Coatings Market Key Industry Players
Large-scale material science conglomerates and specialized coating manufacturers split the market for military aerospace coatings. The industry structure increasingly favors direct engagement between suppliers and national defense agencies, rewriting the role of traditional distributors. Strategic partnerships and extensive R&D investments are crucial for securing long-term government contracts and meeting stringent military specifications. Companies also prioritize portfolio diversification to address evolving environmental regulations and complex performance demands, including low-observability characteristics.
Within the established tier of global coating providers, PPG Industries exemplifies a strategy leveraging extensive R&D infrastructure to secure long-term government contracts for advanced materials. Akzo Nobel occupies a position as a specialist in chromate-free primers and topcoats, aligning with stringent environmental standards like Europe's REACH framework. Sherwin-Williams anchors its presence by offering a broad portfolio of qualified products, meeting diverse military specifications within the maintenance, repair, and overhaul supply chain. These entities collectively represent the market's dual mandate for enhanced mission survivability and environmental sustainability, shaping material science priorities.
| Leading Market Players |
|---|
| BASF |
| Hentzen Coatings |
| Akzo Nobel |
| Argosy International |
| BryCoat |
| PPG Industries |
| Henkel |
| Mankiewicz Coatings |
| Sherwin-Williams |
| Others |
Cost & Logistics Intelligence
Raw material volatility for key inputs like titanium dioxide and specialty polymers directly impacts where margin pools sit across the military aerospace coatings supply chain. This volatility strains profitability for manufacturers, who often operate under long-term government contracts with fixed pricing structures. The specialized nature of advanced materials for low-observability characteristics further concentrates upstream supply, influencing downstream costs for defense contractors.
Pricing Analysis
Pricing for military aerospace coatings varies significantly between regions, reflecting procurement scale and regulatory overhead. The dominant pricing model is contract-based long-term offtake, particularly for advanced systems. Price differentiation stems from stringent military specification certification levels and the degree of customization required for functional coatings. Pricing pressure originates from the escalating costs of raw materials, particularly for specialized polymers. Defense agencies exhibit the lowest price sensitivity when performance and mission readiness are paramount, while MRO providers show greater sensitivity for standard maintenance products.
Supply Chain Analysis
Specialized coating manufacturers like PPG Industries and Akzo Nobel hold significant production capacity for military aerospace coatings, often engaging in direct supply to national defense agencies. The supply chain draws from critical raw materials including titanium dioxide, specialty polymers, and rare earth elements, with significant processing concentrated in countries like the United States, Germany, and Japan. A key structural risk is raw material volatility, which creates instability for manufacturers. Distribution runs through both direct channels to defense contractors for new aircraft and specialized distributors for maintenance, repair, and overhaul operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global military aerospace coatings market represents an early-cycle expansion story, driven by the proliferation of UAV fleets and ongoing aircraft modernization programs. This market offers substantial opportunities for innovation and strategic positioning.
For Market Incumbents:
Harden existing market positions by deepening R&D investments into sustainable, chromate-free formulations that meet evolving environmental regulations like REACH. Secure long-term government contracts through co-development initiatives with prime airframe contractors, mitigating the threat of new entrants with niche solutions. Invest in advanced certification processes for functional coatings to maintain a competitive edge against regulatory divergence. This strategy ensures continued access to critical defense programs.
For New Entrants and Emerging Players:
Pursue white-space opportunities in the Asia-Pacific defense sector, leveraging rising defense budgets and indigenous aerospace manufacturing programs in countries like India. Target the specialized UAV coatings segment, focusing on lightweight materials with unique thermal and low-observability signatures. The most penetrable segment lies in advanced anti-corrosion primers, where innovation in chromate-free alternatives can capture share. A key go-to-market angle involves establishing a technology lead in high-performance water-based or high-solids polyurethane systems.
For Investors and Strategic Acquirers:
Capital is best deployed toward specialized material science firms with proprietary sustainable coating technologies or functional coating expertise. The long-term viability of this market is robust, anchored by continuous military modernization and the essential need for aircraft protection and survivability. Acquisition targets should possess strong R&D pipelines and established relationships with defense prime contractors. Quarterly review of defense spending and technology qualification milestones is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| R&D in Sustainable Formulations | Addresses ECHA and EPA mandates, securing future market access for coating manufacturers. |
| Direct Defense Agency Engagement | Bypasses traditional distributors, fostering co-development of advanced materials with national defense agencies. |
| Asia-Pacific Market Entry | Captures demand from rising defense budgets and indigenous aerospace programs in countries like India. |
| Functional Coating Development | Integrates self-healing or sensing properties, enhancing aircraft operational availability for military end-users. |
| Advanced Primer Qualification | Unlocks new MRO contracts by providing chromate-free alternatives that meet stringent performance specifications. |
Research Approach
Initial hypotheses were tested against primary input from R&D directors at coating manufacturers, procurement officers from defense agencies, MRO facility managers, and aerospace engineers, and refined through iterative feedback. This approach combined in-depth primary interviews with rigorous secondary validation. Secondary data sources included military specifications documents, environmental regulatory reports from the U.S. Environmental Protection Agency and ECHA, aerospace industry publications, and relevant company financial filings, ensuring comprehensive bottom-up and top-down triangulation.
Demand-supply-balance modeling informed the analytical framework across the analysis window, projecting market evolution based on historical trends and future outlooks. Segmentation dimensions modeled included product type, technology, application (UAVs, Fighter Jets), end-user (Defense Contractors, Government Agencies), and geographic region. Compound annual growth rates were derived from a synthesis of market drivers, restraints, and strategic opportunities. Key industry-specific forecast inputs included defense budget allocations and aircraft modernization program schedules.
Sensitivities concentrate around geopolitical events, raw material price shocks, and unforeseen regulatory changes, reflecting assumptions documented in the forecast. Quarterly review of defense spending and technology qualification milestones is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Radiation Shielding Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Aerospace Sealants Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Aluminum Beryllium Market
Aerospace and Aircraft Materials
Aerospace Foam Market
Aerospace and Aircraft Materials
Aerospace Forging Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market
Aerospace and Aircraft Materials
Titanium Sponge for Aerospace and Defense Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Global Composite Materials Aluminum Alloys Aerospace Market
Aerospace and Aircraft Materials
Thermal Spray Coating Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market
Aerospace and Aircraft Materials
Aircraft Coatings Market