
 Aircraft Carbon Brake Disc Market | 2026-2036
Aircraft Carbon Brake Disc Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Carbon Brake Disc Market Analysis
Capital-intensity divergence between in-house carbon-carbon composite production and outsourced preform sourcing is bifurcating competitive tiers. SGL Carbon leverages captive carbon fiber and pyrolysis capacity to sustain margin control across the value chain. Honeywell anchors its position through R&D intensity in thermal management architectures for next-generation brake systems. Safran Landing Systems dominates European OEM channels while competing on airframe integration depth.
Aircraft carbon brake discs are friction components manufactured from carbon-carbon composites, typically produced through chemical vapor infiltration of carbon fiber preforms followed by high-temperature densification cycles to achieve densities exceeding 1.75 g/cm³ for repeated energy absorption exceeding 100 MJ/kg during landing and rejected takeoff events. Civil aviation applications command the largest installed base, though military aviation programs are shifting toward lightweight disc configurations to extend range and payload capacity. Two-piece disc architectures lead commercial retrofits due to field-replaceable rotor-stator modularity, while heavy-duty variants occupy narrowbody and widebody new-build programs where cycle life requirements exceed ten thousand landings.
FAA Part 25 airworthiness standards, EASA CS-25 certification requirements, and China's CAAC CCAR-25 rules collectively govern brake energy rating, wear indicator calibration, and thermal overload thresholds for type-certified installations. REACH chemical restrictions in Europe and evolving EPA emissions scrutiny at U.S. manufacturing facilities are reshaping binder chemistry and pyrolysis byproduct handling protocols. Stakeholders must monitor regulatory divergence between FAA-EASA harmonization efforts and China's accelerating domestic certification autonomy to anticipate qualification cost trajectories and aftermarket access conditions.
Market Dynamics
Carbon-carbon composite densification cycles are compressing qualification timelines for new brake disc entrants, forcing suppliers to choose between captive pyrolysis capacity or outsourced preform dependency. This technical bottleneck is redrawing competitive tiers across the landing systems value chain.
Growth Catalysts
- FAA Part 25 Energy Rating Mandates:Stringent thermal absorption thresholds for rejected takeoff scenarios are accelerating steel-to-carbon retrofits across narrowbody fleets operating high-cycle routes.
- Commercial Air Transport Expansion:Low-cost carriers in Southeast Asia and the Middle East are prioritizing brake weight reduction to extend payload-range economics on trunk routes.
- Chemical Vapor Infiltration Maturation:Process automation in densification cycles is shortening production lead times for two-piece disc architectures serving the aftermarket.
Market Restraints
- Acrylonitrile Precursor Cost Volatility:PAN-based carbon fiber feedstock prices fluctuate with petrochemical indices, compressing margins for preform suppliers lacking backward integration into fiber production.
- European REACH Compliance Burden:Binder chemistry restrictions on phenolic resin systems are forcing reformulation of preform matrices, extending qualification timelines for new material submissions.
- Technical Limitation in Thermal Shock Resistance:Carbon-carbon composites exhibit microcracking under extreme thermal gradients during emergency braking events, limiting cycle life in heavy-duty widebody applications.
Strategic Opportunities
- India Defense Aviation Modernization:Indigenous combat aircraft programs are specifying lightweight brake configurations, creating first-mover advantage for suppliers establishing local technical partnerships.
- EASA CS-25 Certification Harmonization:Convergence with FAA testing protocols is reducing duplicate qualification costs for dual-certification brake systems targeting transatlantic operators.
- Sensor-Integrated Brake Health Monitoring:Convergence of embedded thermocouple arrays with predictive maintenance software is enabling performance-based service contracts for fleet operators.
Industry Challenges
- Pyrolysis Technician Scarcity:Specialized furnace operators capable of managing high-temperature densification cycles command premium wages, constraining capacity expansion at mid-tier suppliers.
- Type Certificate Amendment Timelines:FAA and EASA coordination delays for brake energy rating revisions extend product launch windows by 18-24 months for modified disc geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Carbon Brake Disc Market |
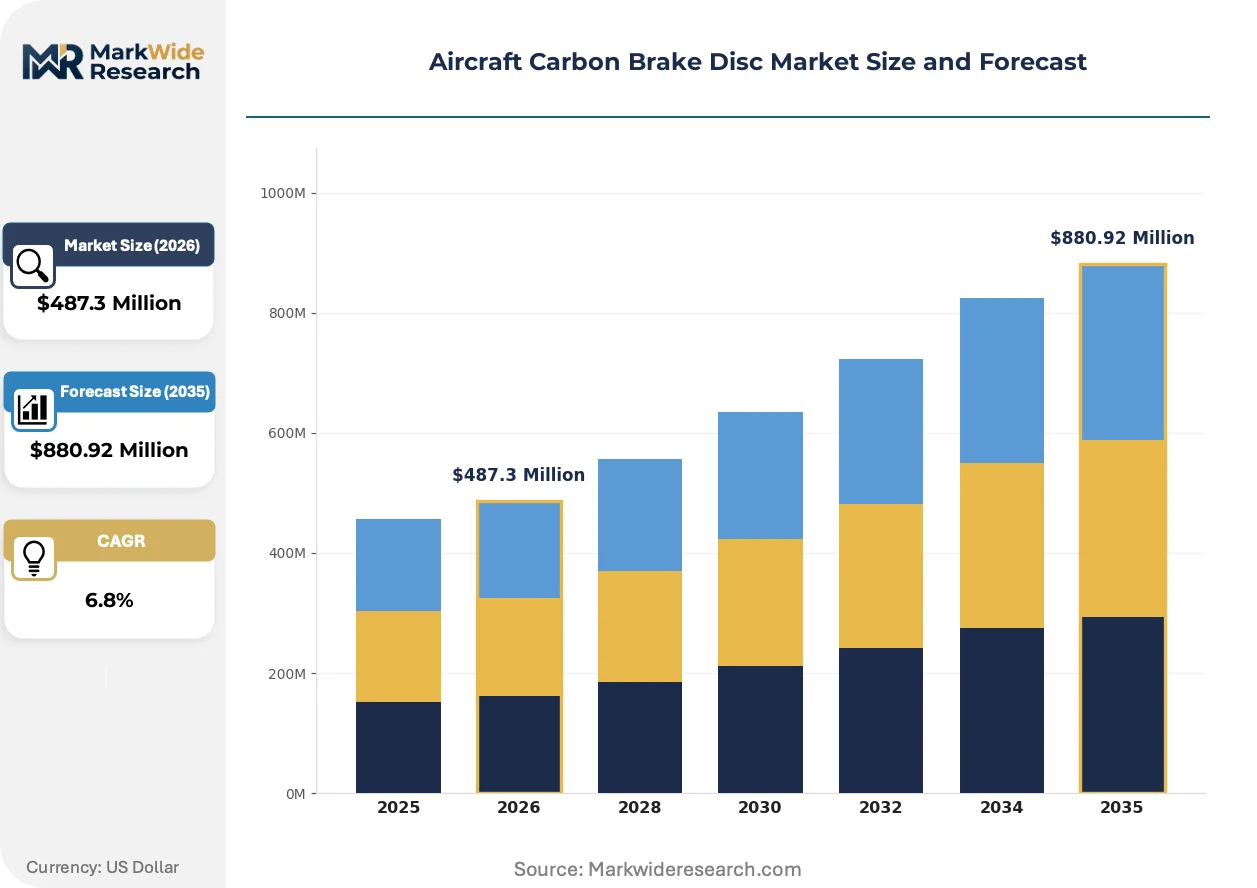
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-piece Disc, One-piece Disc, Lightweight Disc, Heavy-duty Disc Application: Civil Aviation, Military Aviation, Commercial Air Transport, Business Jets End User: Aerospace OEMs, Aviation Maintenance Providers, Airlines, Repair Shops Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | SGL Carbon, Honeywell, Safran Landing Systems, Hunan Boyun New Materials, Lantai Aviation Equipment, Collins Aerospace, CFC Carbon, AVIC Xi'an Aviation Brake, Meggitt PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Carbon Brake Disc Market Emerging Trajectories
Thermal management architectures are displacing legacy friction material specifications as the primary axis of supplier competition. This shift is elevating systems integration capabilities above standalone disc manufacturing scale.
3D-woven carbon fiber preforms are replacing traditional laminated layups in next-generation brake disc cores. Tier-one landing system integrators are adopting these architectures for widebody new-build programs where energy absorption requirements exceed 120 MJ/kg. The technology is bifurcating the supplier base between textile engineering specialists and legacy machining houses unable to bridge the composites competency gap.
REACH chemical restrictions in Europe are mandating phenolic resin binder substitutions with reduced formaldehyde emissions during pyrolysis. Brake disc manufacturers serving EASA-certified installations must reformulate preform matrices and revalidate thermal mechanical properties under revised ECHA substance evaluation protocols. Suppliers with European manufacturing footprints are absorbing higher compliance costs than competitors with Asia-Pacific production bases.
Fleet operators are consolidating brake procurement under long-term performance agreements rather than transactional disc replacement. Low-cost carriers in the Middle East are bundling rotor-stator sets with MRO shop visits, compressing supplier margins but securing multi-year volume commitments. This behavior is most visible among operators with centralized fleet management functions based in Dubai and Singapore.
Aircraft Carbon Brake Disc Market Segmentation
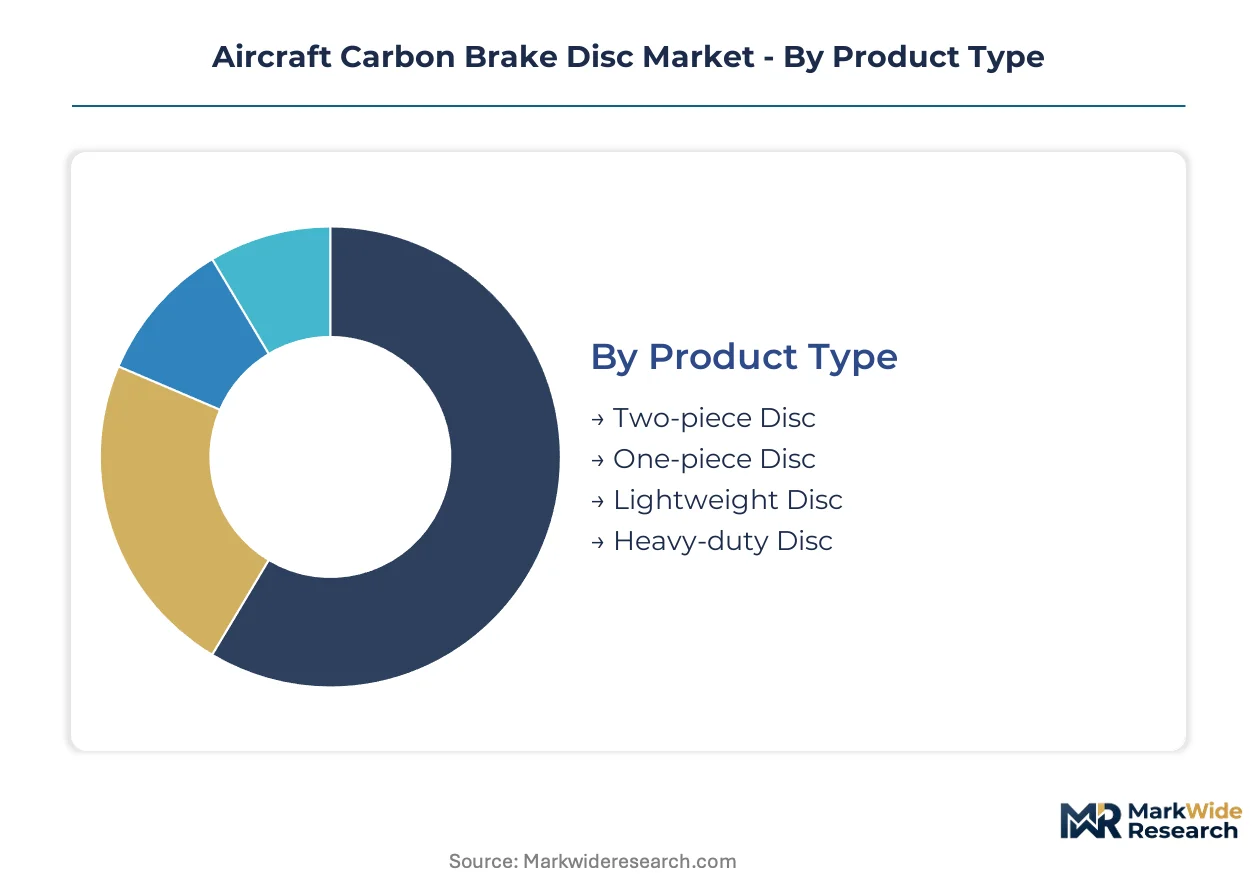
Aircraft carbon brake disc segmentation reveals how technical specifications, operational intensity, and procurement channels fragment demand across the landing systems value chain. Each dimension carries distinct qualification burdens and margin profiles that shape supplier positioning strategies.
Product Type:
Substitution pressure from alternative friction materials and emerging ceramic matrix composites concentrates most acutely on legacy disc architectures with shorter cycle life ratings.
- Two-piece Disc:Modular rotor-stator configurations enable field replacement of worn friction surfaces without full disc removal. Commercial air transport operators in the United States prioritize these architectures for high-cycle narrowbody fleets where turnaround time constraints dominate maintenance economics.
- Heavy-duty Disc:Monolithic densified carbon-carbon structures withstand energy absorption exceeding 120 MJ/kg during rejected takeoff events. Widebody new-build programs in France specify these variants where ten-thousand-landing cycle life requirements exceed retrofit economics.
- One-piece Disc:Integrated hub-and-friction-ring designs persist in regional jet applications with moderate energy ratings.
- Lightweight Disc:Reduced-mass configurations serve military range-extension programs and business jet weight-critical installations.
Heavy-duty Disc retains volume leadership; Lightweight Disc holds the steepest expansion curve.
Application:
Cost tier differentiation separates capital-intensive new-build specifications from aftermarket retrofit economics across aviation end-uses.
- Commercial Air Transport:Scheduled operators with centralized fleet management functions drive consolidated procurement of certified brake systems under long-term performance agreements. Low-cost carriers in the Middle East bundle rotor-stator replacement with MRO shop visits, compressing unit margins while securing multi-year volume commitments.
- Civil Aviation:General aviation and regional operators exhibit fragmented demand with lower energy rating requirements and extended replacement intervals. China's expanding domestic airline network anchors procurement growth for civil-certified configurations meeting CAAC CCAR-25 standards.
- Military Aviation:Combat aircraft modernization programs in India specify indigenous brake configurations with reduced observability signatures.
- Business Jets:Fractional ownership fleets prioritize weight reduction over cycle life in brake specification.
Commercial Air Transport commands procurement scale; Military Aviation climbs the fastest as defense modernization accelerates.
End User:
Customer type determines whether procurement flows through OEM-integrated channels or fragmented aftermarket intermediaries.
- Aerospace OEMs:Airframe manufacturers specify brake systems during type certification, locking in supplier relationships through program life cycles. Safran Landing Systems and Honeywell anchor European and North American OEM channels respectively through airframe integration depth and thermal management R&D.
- Airlines:Fleet operators with in-house engineering capabilities conduct direct technical negotiations with disc manufacturers for performance-based service contracts. Sensor-integrated health monitoring enables predictive maintenance agreements that shift supplier revenue toward recurring service streams.
- Aviation Maintenance Providers:Third-party MRO shops in Singapore and Dubai consolidate brake procurement for operator clients without captive technical capabilities.
- Repair Shops:Independent facilities handle lower-volume disc refurbishment and emergency replacement for non-fleet operators.
Aerospace OEMs retain specification authority; Airlines gain procurement influence fastest through fleet consolidation.
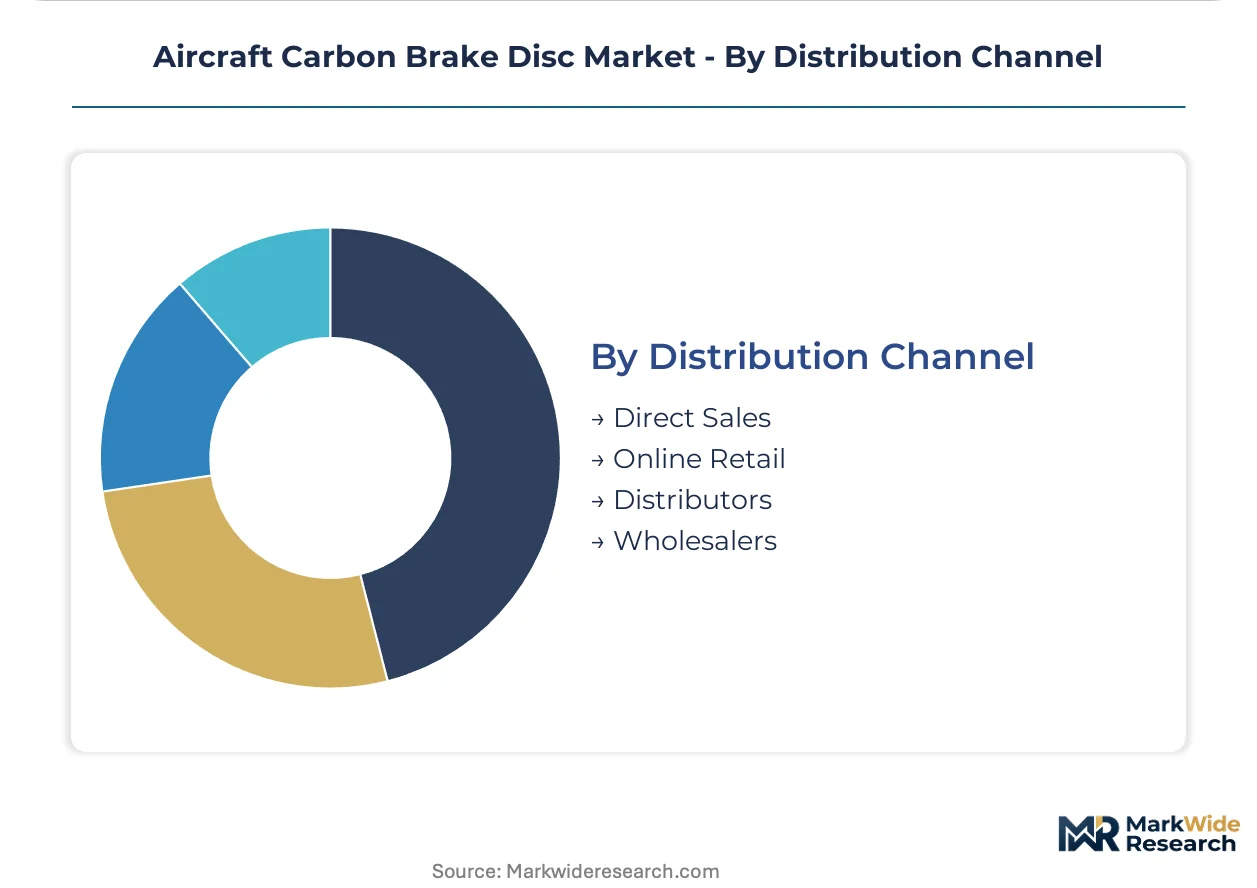
Distribution Channel:
Supply concentration in certified brake logistics favors direct manufacturer-operator relationships over intermediaries with limited technical qualification capabilities.
- Direct Sales:Landing system manufacturers maintain technical field service teams supporting brake installation, bedding-in protocols, and warranty claim resolution. FAA Part 25 and EASA CS-25 certification requirements for traceability and installation records reinforce direct channel dominance for type-certified discs.
- Distributors:Authorized intermediaries stock fast-moving two-piece disc configurations for scheduled maintenance windows. REACH chemical compliance documentation requirements in Europe filter distributor participation to entities with regulatory affairs capabilities.
- Wholesalers:Volume aggregators serve secondary markets with extended lead time tolerance and lower technical service expectations.
- Online Retail:Digital channels capture limited non-certified consumable demand from general aviation segments with minimal regulatory oversight.
Direct Sales retains channel leadership; Distributors expand fastest as fleet standardization concentrates procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with French and American suppliers commanding OEM specification authority, while Chinese manufacturers undercut on aftermarket volume through state-backed capacity expansion. This asymmetry reshapes procurement patterns across operator fleets and MRO networks.
United States
FAA Part 25 certification timelines and rejected takeoff energy mandates drive steel-to-carbon retrofit demand among narrowbody operators. EPA emissions scrutiny at pyrolysis facilities tightens binder chemistry compliance. The Wichita-Miami corridor anchors landing system manufacturing and Southeast MRO hub concentration.
France
EASA CS-25 harmonization with FAA protocols reduces dual-qualification costs for transatlantic brake suppliers. REACH restrictions on phenolic resin systems force preform matrix reformulation. The Toulouse-Paris aerospace cluster dominates widebody new-build specification channels through airframe integration partnerships.
China
CAAC CCAR-25 domestic certification autonomy accelerates indigenous brake program qualification timelines. State-directed carbon fiber capacity expansion under dual carbon goals feeds preform supply security. Xi'an and Chengdu anchor military aviation brake development for combat aircraft modernization programs.
Germany
ECHA substance evaluation protocols extend qualification timelines for European-manufactured preform matrices. Automotive carbon-carbon technology transfer supports aviation brake composite densification capabilities. The Bavaria-Baden-Württemberg corridor hosts specialized pyrolysis equipment suppliers serving tier-one landing system integrators.
India
Defense aviation modernization programs specify lightweight brake configurations for indigenous combat aircraft. BIS standards alignment with EASA testing protocols facilitates import substitution strategies. Bangalore-Hyderabad technical partnerships create first-mover positioning for brake system qualification on domestic platforms.
Aircraft Carbon Brake Disc Market Vendor Landscape
Concentration sits with integrated carbon-carbon composite manufacturers and airframe-anchored landing system specialists. The supplier base stratifies between captive fiber-to-disc producers and outsourced preform-dependent assemblers. Three archetypes dominate: vertically integrated material science conglomerates, airframe-integrated braking system OEMs, and emerging national champions with state-backed capacity. Competitive moves center on pyrolysis capacity expansion and sensor-integrated health monitoring partnerships.
Among integrated material specialists, SGL Carbon exemplifies captive carbon fiber and pyrolysis control across the value chain. Honeywell occupies a position anchoring North American OEM channels through thermal management architecture development. Safran Landing Systems represents the airframe-integrated tier dominating European specification authority. Hunan Boyun New Materials and AVIC Xi'an Aviation Brake sit within the emerging national champion archetype serving domestic certification pathways.
| Leading Market Players |
|---|
| SGL Carbon |
| Honeywell |
| Safran Landing Systems |
| Hunan Boyun New Materials |
| Lantai Aviation Equipment |
| Collins Aerospace |
| CFC Carbon |
| AVIC Xi'an Aviation Brake |
| Meggitt PLC |
| Others |
Supply Flow & Price Mechanics
FAA Part 25 airworthiness certification gates both supplier qualification and price differentiation simultaneously, as only densified carbon-carbon composites meeting thermal absorption thresholds command configured-to-order premiums while uncertified preform suppliers compete on spot pricing for non-aviation applications.
Pricing Analysis
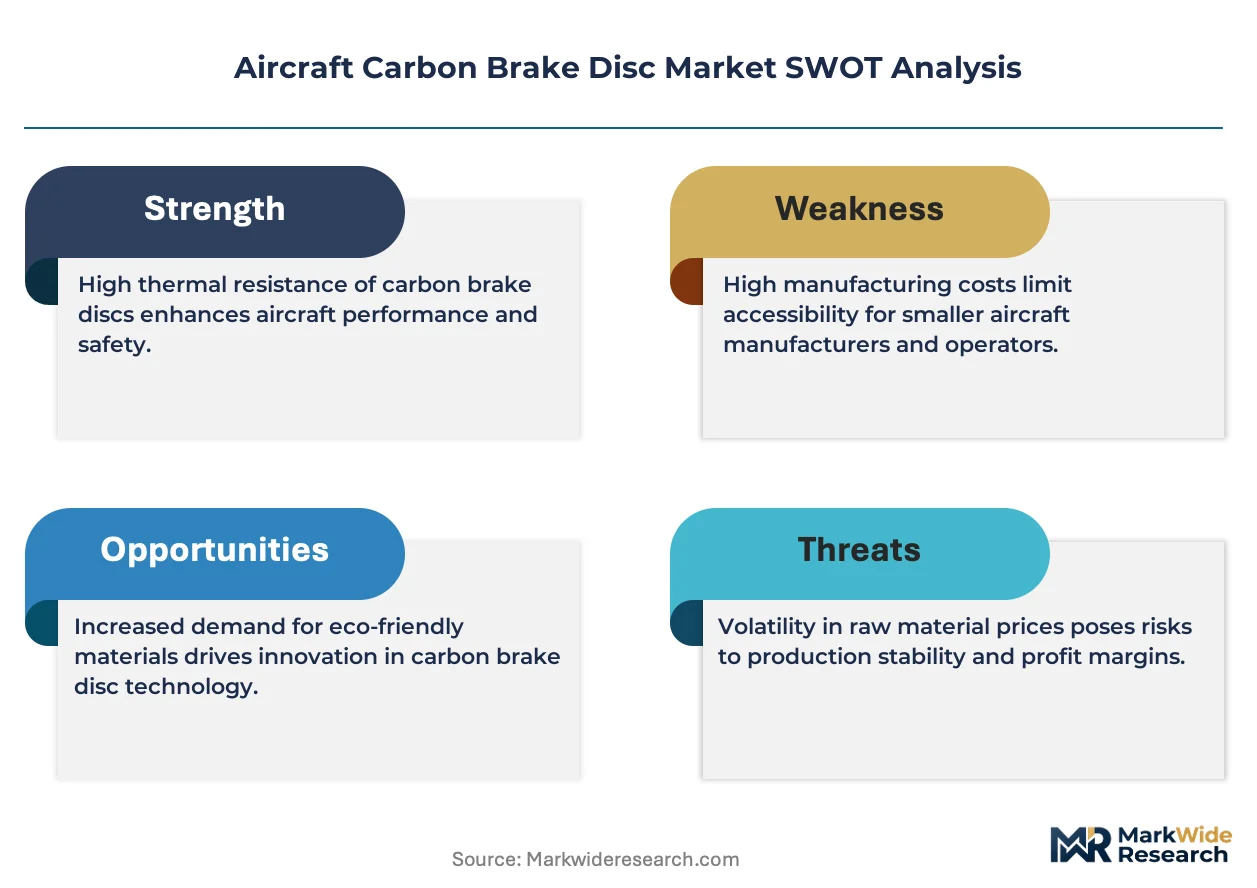
Configured-to-order pricing for heavy-duty discs serving widebody new-build programs commands substantial premiums over standard two-piece retrofit configurations. Price differentiation rests on EASA CS-25 certification tier and pyrolysis cycle count, with OEM-integrated suppliers capturing margin through thermal management architecture bundling. Cost compression in the aftermarket tier is intensifying because low-cost carriers are consolidating procurement under multi-year performance agreements. Airlines with centralized fleet management functions exhibit lowest price sensitivity, while independent MRO shops in secondary markets face acute margin pressure.
Supply Chain Analysis
France and the United States anchor carbon-carbon composite densification capacity, with China's state-backed carbon fiber expansion feeding preform supply security for domestic brake programs. Raw material dependencies center on PAN-based carbon fiber precursor, phenolic resin binder systems, and specialized pyrolysis furnace equipment. Single-source vulnerability concentrates in acrylonitrile precursor supply, where petrochemical index fluctuations transmit directly to preform costs. Distribution runs through direct manufacturer-operator channels for type-certified discs, with authorized distributors serving scheduled maintenance windows for standardized configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against ceramic matrix composite brake architectures, where incumbent carbon-carbon suppliers must navigate emerging lightweight alternatives threatening cycle-life advantages in next-generation combat aircraft programs.
For Market Incumbents: Shield program life cycle revenue by deepening captive pyrolysis capacity before REACH binder chemistry restrictions force preform matrix reformulation. Anchor OEM specification authority through sensor-integrated brake health monitoring partnerships that shift operator procurement toward performance-based service contracts. Prioritize thermal management R&D investment to maintain energy absorption leadership against ceramic matrix substitute threats.
For New Entrants and Emerging Players: EASA-FAA harmonization fast-tracks dual-certification pathways for brake systems targeting transatlantic operators, reducing duplicate qualification cost barriers. Exploit white-space in India's defense aviation modernization by establishing technical partnerships with Bangalore-Hyderabad aerospace clusters for indigenous combat aircraft brake qualification. Penetrate through aftermarket two-piece disc architectures where field-replaceable modularity lowers initial certification burden.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core carbon-carbon composite assets serving automotive or industrial applications. Long-term viability hinges on pyrolysis capacity scarcity and certification backlog duration across the analysis window. Monitor EASA substance evaluation protocol acceleration as inflection indicator for European manufacturing footprint repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Pyrolysis Capacity Expansion | Captive densification cycles reduce preform dependency and margin leakage to outsourced suppliers. |
| Sensor-Integrated Health Monitoring Partnership | Honeywell and Safran anchor predictive maintenance revenue streams through embedded thermocouple arrays. |
| REACH-Compliant Binder Reformulation | ECHA substance evaluation protocols force phenolic resin substitutions with extended requalification timelines. |
| Defense Aviation Localization Joint Venture | India's BIS standards alignment creates import substitution pathways for indigenous brake qualification. |
| CAAC CCAR-25 Certification Autonomy Investment | China's state-directed carbon fiber capacity supports domestic brake program independence from FAA-EASA pathways. |
Methodological Framework
Desk research of FAA airworthiness directives, EASA certification databases, and carbon fiber trade flow data preceded structured interviews with landing system procurement directors, pyrolysis furnace operators, airline fleet managers, and MRO shop technical leads. Primary fieldwork validated secondary findings through bottom-up triangulation against top-down production capacity estimates across the value chain.
Variance decomposition across product type, application intensity, and end-user procurement channel shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by energy rating tier and certification pathway. Forecast inputs incorporated chemical vapor infiltration automation rates and REACH compliance cost absorption assumptions.
Underlying assumptions cover continued FAA-EASA harmonization momentum and acrylonitrile precursor price stability, with deviation risk concentrated in CAAC unilateral certification acceleration and defense program budget reallocation. Recalibration cycles align with material shifts in pyrolysis equipment capacity commissioning and ECHA substance evaluation protocol finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aviation Carbon Fiber Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Titanium Market
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Advanced Materials for Flying Cars Market
Aerospace and Aircraft Materials
Aluminum Titanate Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Aerogel Blanket Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Europe Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Global Aerospace and Defense Elastomers Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market