
 Aramid Honeycomb Market | 2026-2036
Aramid Honeycomb Market Size, Share, and Industry Trends Forecast 2026-2036
Aramid Honeycomb Market Intelligence
Multi-source aramid fiber procurement is restructuring supply economics for honeycomb core manufacturers. Hexcel Corporation leverages captive resin formulation capabilities to secure margin pools in aerospace-qualified material streams. Teijin Limited anchors Japanese supply through integrated para-aramid fiber production from polymer to finished core. DuPont de Nemours, Inc. dominates Kevlar honeycomb positioning via decades of fiber brand equity and specification lock-in across military airframe programs.
Aramid honeycomb consists of hexagonal cell structures manufactured from aramid fiber sheets bonded with phenolic resin, yielding density ranges from 32 to 192 kg per cubic meter and compressive strengths up to 10 MPa depending on cell geometry. Nomex honeycomb leads commercial aerospace interiors due to fire-smoke-toxicity compliance and decades of qualification data, while Kevlar honeycomb occupies ballistic and structural applications demanding higher shear modulus. Phenolic honeycomb competes on cost in marine and industrial panels where extreme temperature exposure remains limited.
FAA Part 25 airworthiness standards and EASA CS-25 certification frameworks mandate flammability resistance and structural burn-through thresholds that only meta-aramid cores consistently satisfy. REACH chemical registration in Europe and EPA emissions oversight in the United States constrain phenolic resin formulations and solvent-based adhesive processes. Stakeholders must monitor evolving OEM sustainability scorecards and recycled content mandates that threaten to displace conventional thermoset bonding chemistries before next-generation bio-based alternatives achieve qualification.
Market Dynamics
Airframers are consolidating supplier bases around qualified aramid honeycomb producers capable of certifying to FAA Part 25 and EASA CS-25 flammability thresholds, compressing vendor pools and locking in specification-controlled material streams.
Growth Catalysts
- FAA Part 25 Amendment 25-116:Mandates enhanced burn-through resistance for cabin interior panels, forcing retrofit programs and new-build aerospace demand toward meta-aramid cores with established qualification data.
- Commercial aerospace interiors:Airbus and Boeing production rate recoveries are pulling Nomex honeycomb volumes for sidewalls, ceilings, and galleys where fire-smoke-toxicity compliance is non-negotiable.
- German chemical cluster concentration:Specialty phenolic resin formulators near Cologne and Leverkusen anchor European supply chains, reducing lead times for aerospace-qualified adhesive systems.
Market Restraints
- Para-aramid fiber oligopoly:DuPont and Teijin control upstream Kevlar and Twaron supply, exposing honeycomb manufacturers to input cost volatility and allocation rationing during capacity constraints.
- REACH chemical registration:ECHA oversight of phenolic resin precursors and formaldehyde emissions is constraining formulation flexibility and extending reformulation timelines for European producers.
- Thermoplastic composite substitution:PEI and PPS honeycomb cores are penetrating lower-temperature aerospace applications where fire performance requirements are less stringent.
Strategic Opportunities
- Urban air mobility airframes:eVTOL manufacturers in Germany and the United States are specifying aramid honeycomb for battery enclosure protection and structural floors where crashworthiness and weight reduction converge.
- EU Green Deal sustainable aviation fuels pathway:Parallel OEM sustainability scorecards are creating early-mover advantage for honeycomb producers developing bio-based phenolic resin alternatives.
- Rail interior refurbishment:EN 45545-2 fire safety standards for European passenger trains are opening specification windows for meta-aramid cores previously confined to aerospace.
Industry Challenges
- Aerospace certification timeline compression:FAA and EASA material qualification protocols require 18-36 months for new core densities or resin formulations, freezing product development cycles.
- Adhesive process engineering talent scarcity:Specialized expertise in phenolic resin impregnation and node-bonding automation is concentrating at legacy producers, constraining new entrant scale-up.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aramid Honeycomb Market |
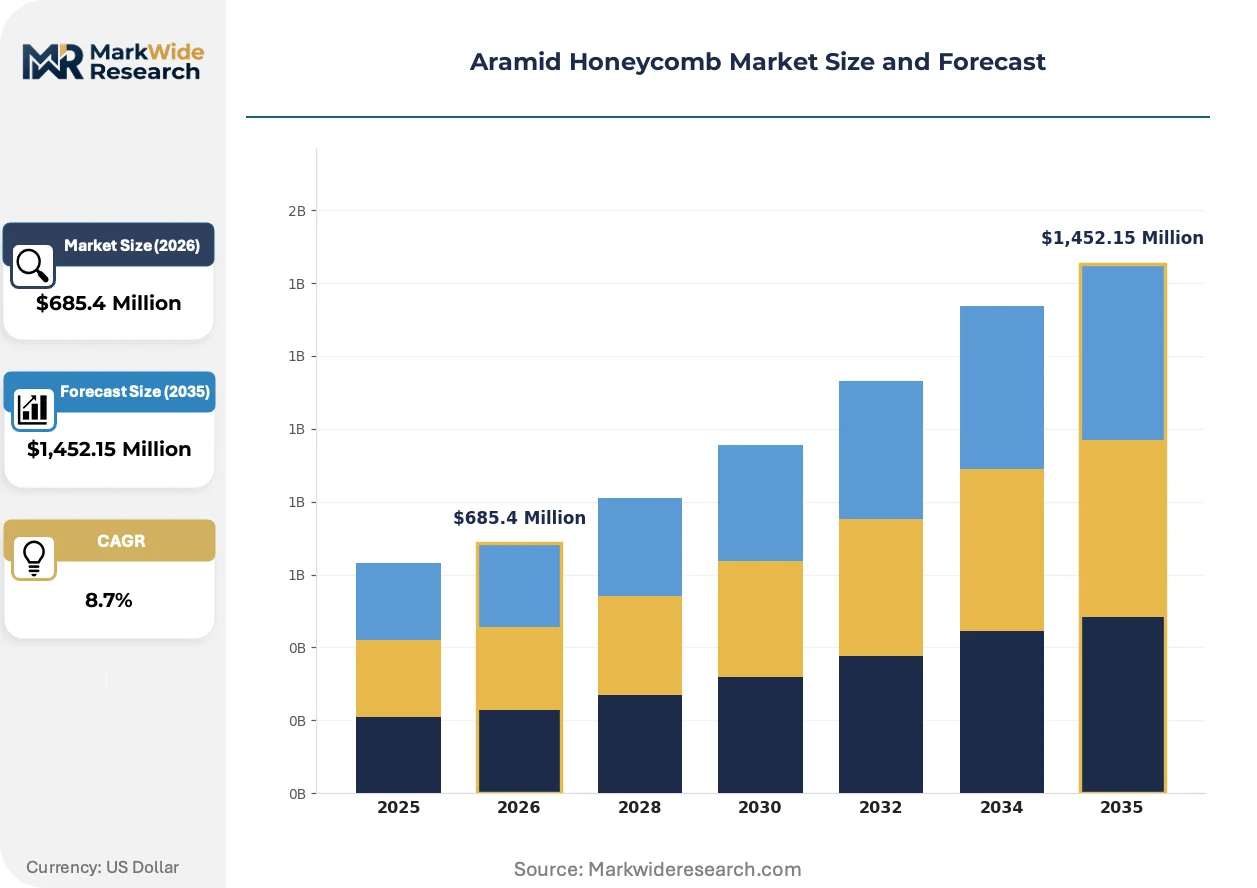
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nomex Honeycomb, Kevlar Honeycomb, Phenolic Honeycomb, Fiberglass Honeycomb, Aluminum Honeycomb Application: Aerospace Composites, Automotive Interiors, Marine Structures, Wind Turbine Blades, Sports Equipment, Industrial Panels End User: Aircraft Manufacturers, Vehicle Assemblers, Shipbuilders, Renewable Energy Firms, Sporting Goods Producers Form: Sheet, Block, Roll, Customized Shapes |
| Companies Covered | The Gill Corporation, AVIC Composite Corporation Ltd., Hexcel Corporation, Teijin Limited, Toray Industries, Inc., Plascore, Inc., Showa Aircraft Industry Co., Ltd., DuPont de Nemours, Inc., Euro-Composites S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aramid Honeycomb Market Strategic Shifts & Innovations
Digital manufacturing and sustainability mandates are restructuring how aramid honeycomb is specified, produced, and qualified across aerospace and adjacent transportation sectors.
Thermoplastic film adhesives are overtaking traditional phenolic resin bonding in select aerospace applications. These systems enable faster cure cycles and reduced volatile organic compound emissions. Tier 1 suppliers in Germany and the United States are piloting automated layup lines around these materials. The shift is compressing qualification timelines for secondary structure applications while pressuring legacy thermoset processors to retool.
REACH authorization requirements for formaldehyde-releasing substances are tightening phenolic resin formulation spaces in Europe. ECHA's 2023-2027 substance evaluation roadmap is forcing reformulation investments across adhesive suppliers. German honeycomb producers with captive resin synthesis capabilities are internalizing compliance costs, while smaller converters face outsourcing penalties or market exit.
Airframer consolidation of approved vendor lists is concentrating procurement authority at Boeing, Airbus, and emerging eVTOL primes. Long-term material purchase agreements now span 5-7 years with price-adjustment clauses tied to resin input indices. This behavior is most visible in Germany and the United States, where supplier reduction programs have halved qualified core vendors since 2019.
Aramid Honeycomb Market Segmentation
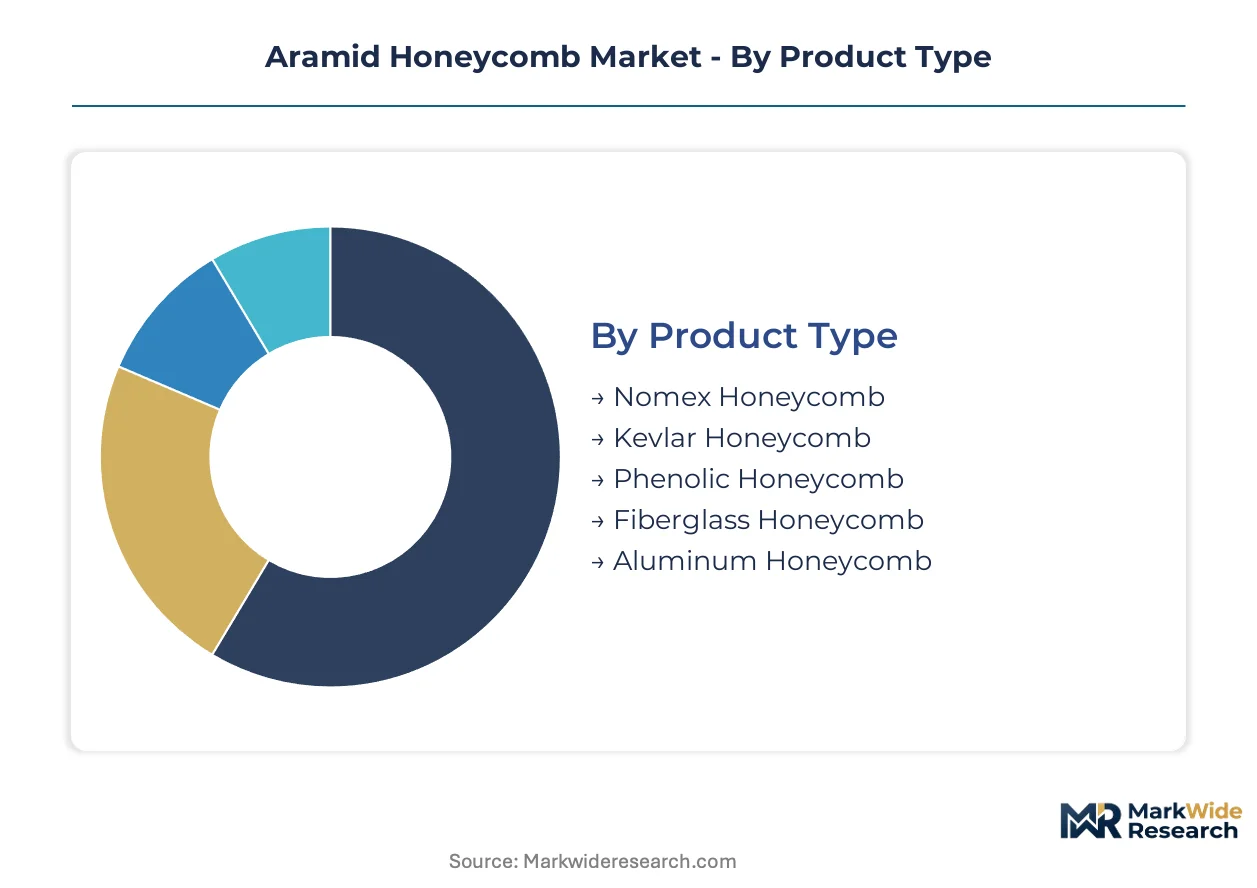
Aramid honeycomb markets fragment across material chemistry, integration depth, and end-use performance requirements. Each segmentation axis reveals distinct margin pools, qualification barriers, and supply chain configurations that determine competitive positioning.
Product Type:
Integration depth varies sharply across chemistries, with some grades functioning as standalone structural elements and others requiring lamination into composite sandwich panels.
- Nomex Honeycomb:Meta-aramid fiber construction bonded with phenolic resin delivers density ranges from 32 to 192 kg/m³. Aerospace interior demand concentrates at Airbus and Boeing tier suppliers in Germany and the United States, where FAA Part 25 and EASA CS-25 flammability thresholds are non-negotiable.
- Kevlar Honeycomb:Para-aramid fiber yields higher shear modulus and ballistic resistance than meta-aramid alternatives. Military airframe programs and eVTOL battery enclosures in the United States drive specification lock-in, though DuPont fiber allocation constraints create supply volatility.
- Phenolic Honeycomb:Cost-optimized phenolic resin systems serve marine and industrial panels where temperature exposure remains moderate. Shipbuilders in Germany and industrial panel converters favor this grade for non-structural bulkheads.
- Fiberglass Honeycomb:E-glass or S-glass fiber construction offers intermediate stiffness-to-weight at reduced raw material cost. Wind turbine blade manufacturers in Germany specify this grade for non-critical core sections.
- Aluminum Honeycomb:Metallic cell structures provide maximum compressive strength and thermal conductivity. Aircraft flooring and energy absorption systems in the United States retain this legacy specification despite weight penalties versus aramid alternatives.
Nomex honeycomb leads volumes today; Kevlar honeycomb is gaining share fastest in emerging mobility applications.
Application:
Cost tier stratification separates qualification-intensive aerospace programs from price-sensitive industrial volumes.
- Aerospace Composites:Sidewalls, ceilings, galleys, and structural floors require burn-through resistance certification. Airbus production rate recoveries in Germany and Boeing supplier consolidation in the United States anchor premium pricing.
- Automotive Interiors:Headliners, package trays, and load floors exploit aramid honeycomb for acoustic damping and weight reduction. German luxury vehicle assemblers specify Nomex grades for electric vehicle battery protection systems.
- Marine Structures:Hull cores, bulkheads, and deck panels in recreational and commercial vessels. German shipbuilders near Hamburg and Bremen favor phenolic honeycomb for cost-competitive superyacht construction.
- Wind Turbine Blades:Spar caps and shear webs integrate honeycomb cores for stiffness-to-weight optimization. Renewable energy firms in Germany specify fiberglass and phenolic grades for blade lengths exceeding 80 meters.
- Sports Equipment:Racing shells, skis, and protective gear exploit tailored density gradients. Sporting goods producers in the United States and Germany drive customized shape demand.
- Industrial Panels:Cleanroom partitions, elevator cabs, and architectural facades. German industrial panel converters purchase sheet and block forms for standardized dimensions.
Aerospace composites command the highest margin tier; automotive interiors are expanding most quickly as electrification accelerates lightweighting mandates.
End User:
Customer concentration patterns determine contract structure, with OEM direct procurement squeezing converter margins.
- Aircraft Manufacturers:Boeing, Airbus, and emerging eVTOL primes consolidate approved vendor lists around qualified core producers. Long-term agreements span 5-7 years with resin input price adjustment clauses.
- Vehicle Assemblers:German premium automotive OEMs and United States electric vehicle startups specify honeycomb for battery enclosure crashworthiness. Sustainability scorecards increasingly influence supplier selection.
- Shipbuilders:German and United States marine constructors balance fire safety certification against cost targets. EN 45545-2 compliance is opening specification windows previously confined to aerospace.
- Renewable Energy Firms:Wind turbine OEMs in Germany purchase fiberglass and phenolic honeycomb for blade manufacturing. Volume contracts favor block and roll forms for automated layup integration.
- Sporting Goods Producers:Specialized manufacturers in the United States and Germany demand customized shapes with rapid prototyping turnaround. Smaller lot sizes sustain premium pricing versus industrial volumes.
Aircraft manufacturers concentrate procurement authority; renewable energy firms are climbing the fastest as offshore wind scale-up accelerates blade length requirements.
Form:
Supply chain configuration varies by form factor, with standardized sheet and roll products supporting scale economies and customized shapes capturing value-added fabrication.
- Sheet:Planar panels in standard thicknesses from 3 to 50 millimeters. Aerospace tier suppliers in Germany and the United States machine sheets to final dimensions for interior panel assemblies.
- Block:Thick sections for deep sandwich structures and energy absorption systems. Wind turbine blade manufacturers in Germany purchase blocks for spar cap integration.
- Roll:Continuous honeycomb for automated cutting and contouring operations. Automotive and industrial panel converters favor rolls for high-volume production efficiency.
- Customized Shapes:CNC-machined or thermoformed cores matching complex mold geometries. Sporting goods and eVTOL airframe producers in the United States and Germany specify tailored forms for structural optimization.
Sheet forms dominate volume throughput; customized shapes are gaining share fastest as eVTOL and advanced mobility applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cologne-Leverkusen chemical corridor anchors European aramid honeycomb production through specialty phenolic resin formulators and Airbus tier suppliers. United States aerospace clusters concentrate procurement authority among consolidated vendor pools. Asian para-aramid fiber capacity is reshaping upstream supply economics for core manufacturers worldwide.
United States
Boeing supplier consolidation and eVTOL battery enclosure programs drive specification demand for Kevlar honeycomb. FAA Part 25 Amendment 25-116 mandates enhanced burn-through resistance, forcing retrofit procurement toward qualified meta-aramid cores. Wichita and Seattle aerospace clusters host tier suppliers machining customized shapes for structural floor assemblies.
Germany
Airbus production rate recoveries pull Nomex honeycomb volumes for sidewalls, ceilings, and galley systems. REACH chemical registration constrains phenolic resin formulation flexibility, extending reformulation timelines for adhesive suppliers. The Cologne-Leverkusen specialty chemical cluster reduces lead times for aerospace-qualified resin systems serving European airframers.
Japan
Integrated para-aramid fiber production from polymer to finished core anchors domestic supply security. METI industrial standards and aerospace certification protocols maintain qualification barriers for imported honeycomb products. Nagoya and Tokyo manufacturing belts concentrate automated node-bonding expertise for commercial aviation programs.
China
Wind turbine blade scale-up and rail interior refurbishment create specification windows for fiberglass and phenolic honeycomb alternatives. GB standards and MIIT industrial policy guide domestic composite core development toward import substitution. Yangtze River Delta manufacturing hubs integrate honeycomb cores into renewable energy and transportation equipment supply chains.
Aramid Honeycomb Market Key Industry Players
Global majors compete with regional champions across qualification-intensive aerospace supply chains. The vendor base stratifies between fiber-integrated producers and downstream converters dependent on external resin supply. Three archetypes dominate: captive fiber-to-core integrators, aerospace-qualified specialty converters, and cost-optimized industrial panel suppliers. Consolidation through long-term material purchase agreements and supplier reduction programs is compressing vendor pools around certified producers.
Among fiber-integrated producers, Hexcel Corporation, Teijin Limited, and DuPont de Nemours, Inc. occupy positions where upstream aramid supply confers procurement leverage. These companies exemplify the qualification lock-in archetype through decades of specification data across military and commercial airframe programs. Downstream, AVIC Composite Corporation Ltd. and Euro-Composites S.A. represent regional champions serving geographically concentrated aerospace clusters with proximity-based logistics advantages.
| Leading Market Players |
|---|
| The Gill Corporation |
| AVIC Composite Corporation Ltd. |
| Hexcel Corporation |
| Teijin Limited |
| Toray Industries, Inc. |
| Plascore, Inc. |
| Showa Aircraft Industry Co., Ltd. |
| DuPont de Nemours, Inc. |
| Euro-Composites S.A. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists in Germany anchor aerospace-grade honeycomb production, translating generational expertise in phenolic resin chemistry into pricing discipline that resists commoditization pressure from industrial panel converters. This ownership structure concentrates supply-side bargaining power while locking in long-term offtake agreements with Airbus tier suppliers.
Pricing Analysis
Input-cost pass-through from para-aramid fiber oligopolists DuPont and Teijin governs contract structures across qualified aerospace streams. Three-tier pricing structure across aerospace-certified, industrial-grade, and marine-optimized levels separates specification-intensive Nomex cores from cost-driven phenolic alternatives. Cost compression in industrial segments is intensifying because fiberglass honeycomb substitutes erode volume leverage. Automotive battery enclosure buyers exhibit highest price sensitivity, while military airframe programs remain least elastic due to qualification lock-in.
Supply Chain Analysis
Single-source vulnerability sits with DuPont's Kevlar fiber allocation for ballistic-grade honeycomb, exposing downstream converters to rationing during capacity constraints. Geographic concentration centers on Germany, the United States, and Japan, where aerospace certification infrastructure and resin formulation expertise co-locate. Raw material dependencies draw from para-aramid polymer supply, phenolic resin precursors, and formaldehyde-based adhesive systems. Tariff exposure on aramid fiber imports threatens margin stability for European converters. Distribution runs through direct long-term agreements with Boeing, Airbus, and emerging eVTOL primes, bypassing spot-market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA Part 25 Amendment 25-116 functions as a regulatory compounder, mandating enhanced burn-through resistance that retrofits existing fleets and locks in meta-aramid core demand across new-build programs.
For Market Incumbents: Lock in specification-controlled supply relationships through captive resin synthesis investments near Cologne and Leverkusen, insulating margin pools from REACH-driven reformulation penalties. Deepen backward integration into phenolic precursor supply to neutralize ECHA authorization risks for formaldehyde-releasing substances. For New Entrants and Emerging Players: Launch via automated thermoplastic film adhesive lines serving secondary aerospace structures, exploiting faster cure cycles to compress qualification timelines against legacy thermoset processors. Target rail interior refurbishment under EN 45545-2 standards as the most penetrable specification window, leveraging fire-performance parity with aerospace grades at reduced certification burden. For Investors and Strategic Acquirers: Valuations sit cheapest among regional industrial panel converters lacking aerospace qualification data, presenting consolidation platforms for capability accretion. Long-term viability hinges on bio-based phenolic resin alternatives achieving OEM sustainability scorecard compliance. Watch for eVTOL battery enclosure program awards as the inflection signal validating Kevlar honeycomb share expansion beyond legacy military applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenolic Resin Synthesis | German producers internalize REACH compliance costs while securing formulation control for aerospace-qualified adhesives. |
| Thermoplastic Film Adhesive Line Deployment | Tier 1 suppliers in Germany and the United States pilot automated layup systems reducing VOC emissions and cure cycle duration. |
| Long-term Material Purchase Agreement Extension | Airbus and Boeing consolidate vendor pools around 5-7 year contracts with resin input price adjustment clauses. |
| Joint Venture for Bio-based Phenolic Development | EU Green Deal scorecards create early-mover advantage for honeycomb producers qualifying sustainable resin alternatives. |
| Geographic Expansion into eVTOL Battery Enclosure Supply | Urban air mobility primes in Germany and the United States specify aramid honeycomb for crashworthiness and weight reduction. |
Research Approach
Coverage spans Germany, the United States, Japan, and China, with primary inputs from each region combining interviews with aerospace procurement directors, phenolic resin formulators, composite tier supplier plant managers, and eVTOL airframe engineers. Secondary validation draws from FAA airworthiness directives, EASA certification databases, ECHA substance evaluation roadmaps, and customs trade flow records. Bottom-up volume modeling triangulates against top-down aerospace production rate forecasts.
Granularity-level framing segments the market by fiber chemistry, integration depth, end-use performance tier, and form factor, with regional production hub dynamics layered across each dimension. CAGRs derive from production rate recovery trajectories at Airbus and Boeing, eVTOL program ramp assumptions, and rail refurbishment cycle timing. Industry-specific inputs include phenolic resin price indices and para-aramid fiber allocation patterns from DuPont and Teijin disclosures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under REACH authorization delays or thermoplastic substitution acceleration in lower-temperature aerospace applications. Forecasts reflect documented assumptions regarding OEM sustainability scorecard evolution and bio-based resin qualification timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Magnesium Beryllium Alloy Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Aviation Titanium Alloy Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Aerospace Fiber Optics Market
Aerospace and Aircraft Materials
Aerospace Radome Market
Aerospace and Aircraft Materials
Thermal Spray Coating Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Aerographene Market