
 Aviation Maintenance Repair and Overhaul MRO Software Market | 2026-2036
Aviation Maintenance Repair and Overhaul MRO Software Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Maintenance Repair and Overhaul MRO Software Market Analysis
Asset-light leasing and power-by-the-hour financing is rewriting competitive dynamics in aviation MRO software procurement. IBS Software leverages cloud-native architecture to serve lessors seeking real-time visibility across distributed fleets. Oracle Corporation anchors enterprise-grade maintenance planning for global carriers with complex multi-fleet operations. Ramco Systems specializes in mobile-first work order execution for regional operators with limited IT infrastructure.
Aviation Maintenance Repair and Overhaul MRO Software encompasses digital platforms that schedule, track, and document aircraft maintenance activities, typically integrating with airworthiness databases, parts traceability systems, and labor certification records to ensure regulatory compliance and minimize aircraft on ground time. Cloud-Based deployment is capturing the fastest expansion as operators abandon capital-intensive on-premise infrastructure for subscription models that scale with fleet size. Compliance Tracking commands premium pricing due to the complexity of harmonizing FAA, EASA, and CAAC airworthiness standards across international operations. Fleet Management retains the largest installed base among legacy carriers with heterogeneous aircraft portfolios requiring unified scheduling.
FAA airworthiness directives and EASA Part-145 maintenance organization approvals shape software functionality requirements, with both regulators mandating auditable digital records that legacy paper systems cannot satisfy. The EU AI Act introduces emerging compliance obligations for predictive maintenance algorithms used in European-registered aircraft, creating new certification pathways for AI-enabled MRO platforms. Stakeholders must evaluate whether their current software stacks can absorb blockchain-based parts provenance tracking as supply chain transparency standards tighten across major aviation authorities.
Market Dynamics
Cloud migration is compressing deployment cycles as operators abandon multi-year on-premise implementations for modular SaaS architectures that scale with fleet fluctuations. This shift is redistributing bargaining power from traditional enterprise vendors toward specialized cloud-native providers.
Growth Catalysts
- FAA Airworthiness Directive Digitization:The FAA's mandate for auditable electronic records is forcing paper-based MRO operations toward compliant software platforms. Legacy carriers with mixed fleets face the steepest compliance cliffs.
- Predictive Maintenance Algorithms:Machine learning models trained on flight data analytics are reducing unplanned downtime for commercial airlines. These systems integrate directly with inventory and scheduling modules.
- Power-by-the-Hour Financing:Leasing structures that transfer operational risk to lessors are creating demand for real-time fleet visibility tools. Asset-light operators require granular maintenance cost attribution across distributed aircraft portfolios.
Market Restraints
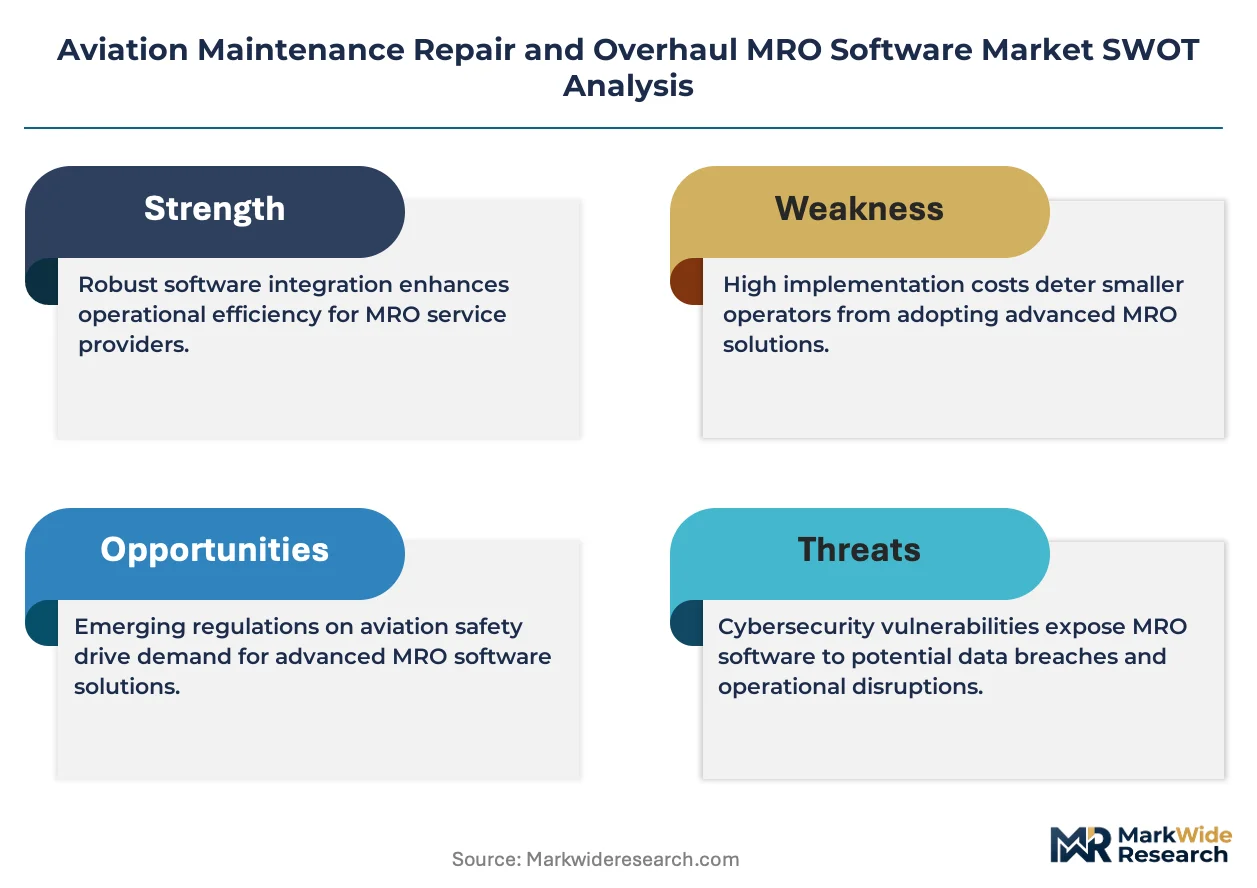
- Legacy System Integration Costs:Heterogeneous IT environments at established carriers create prohibitive data migration expenses. Custom API development for proprietary maintenance databases consumes implementation budgets.
- Specialized Labor Scarcity:Shortages of aviation software engineers with airworthiness regulation expertise are extending deployment timelines. Certification requirements for safety-critical code limit talent pools.
- Input Cost Volatility:Cloud infrastructure pricing fluctuations affect SaaS provider margins. Data storage costs for decades-long airworthiness record retention are compressing subscription pricing flexibility.
Strategic Opportunities
- Blockchain Parts Provenance:Distributed ledger technology is enabling tamper-proof traceability for high-value components. Regulatory pressure from EASA and FAA on counterfeit parts is accelerating pilot programs.
- Regional Operator Mobile-First Platforms:Underpenetrated markets in Southeast Asia and Latin America lack IT infrastructure for heavy client-server deployments. Lightweight mobile work order systems address this gap.
- EU AI Act Certification Pathways:The emerging regulatory framework for AI-enabled maintenance predictions creates first-mover advantages for compliant platforms. European-registered aircraft operators will require certified algorithmic decision support.
Industry Challenges
- Airworthiness Engineer Shortage:The gap between retiring certification specialists and trained replacements is widening. Software vendors must embed regulatory expertise directly into automated compliance modules.
- Multi-Authority Harmonization:Simultaneous compliance with FAA, EASA, and CAAC standards requires complex rule-engine architectures. Divergent record-keeping formats create audit preparation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Maintenance Repair and Overhaul MRO Software Market |
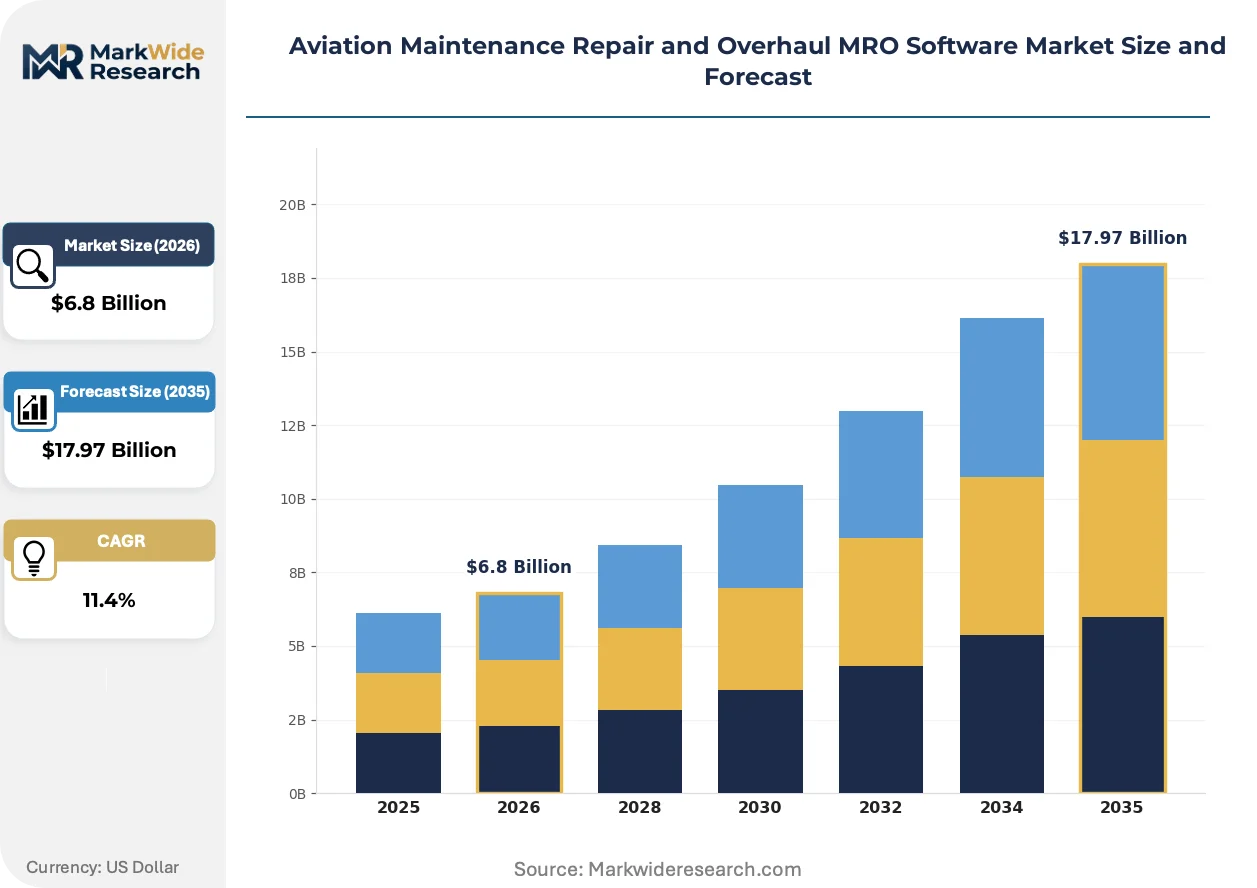
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Work Order Management, Inventory Management, Fleet Management, Compliance Tracking Deployment: On-Premise, Cloud-Based, Hybrid, Mobile End User: Airlines, Maintenance Repair Stations, Original Equipment Manufacturers, Defense Operators Technology: Artificial Intelligence, Internet of Things, Big Data Analytics, Blockchain |
| Companies Covered | IBS Software, Lufthansa Technik AG, Ramco Systems, Oracle Corporation, General Electric Company, IFS AB, Flatirons Solutions, SAP SE, Swiss Aviation Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Maintenance Repair and Overhaul MRO Software Market Emerging Trajectories
Digital thread architectures are unifying previously siloed maintenance data streams, creating continuous feedback loops between flight operations, hangar execution, and supply chain planning. This convergence is compressing decision cycles and enabling condition-based interventions.
Digital twin technology is digitizing physical aircraft systems into real-time virtual replicas that mirror component degradation. Major carriers with heterogeneous Boeing and Airbus fleets are deploying these models to simulate maintenance scenarios before aircraft enter hangars. The technology is digitizing traditional calendar-based inspection schedules into usage-driven maintenance events.
EASA Part-145 maintenance organization approval requirements are tightening documentation standards for third-party repair stations. The regulation now mandates electronic signature capture and immutable audit trails that paper-based systems cannot satisfy. European MRO providers are accelerating platform upgrades to avoid approval suspensions during regulatory inspections.
Airline procurement departments are consolidating vendor relationships around integrated platform suites rather than point solutions for scheduling, inventory, and compliance. This concentration is displacing specialized best-of-breed tools in favor of unified data models. North American network carriers with complex hub-and-spoke operations are driving this consolidation most aggressively.
Aviation Maintenance Repair and Overhaul MRO Software Market Segmentation
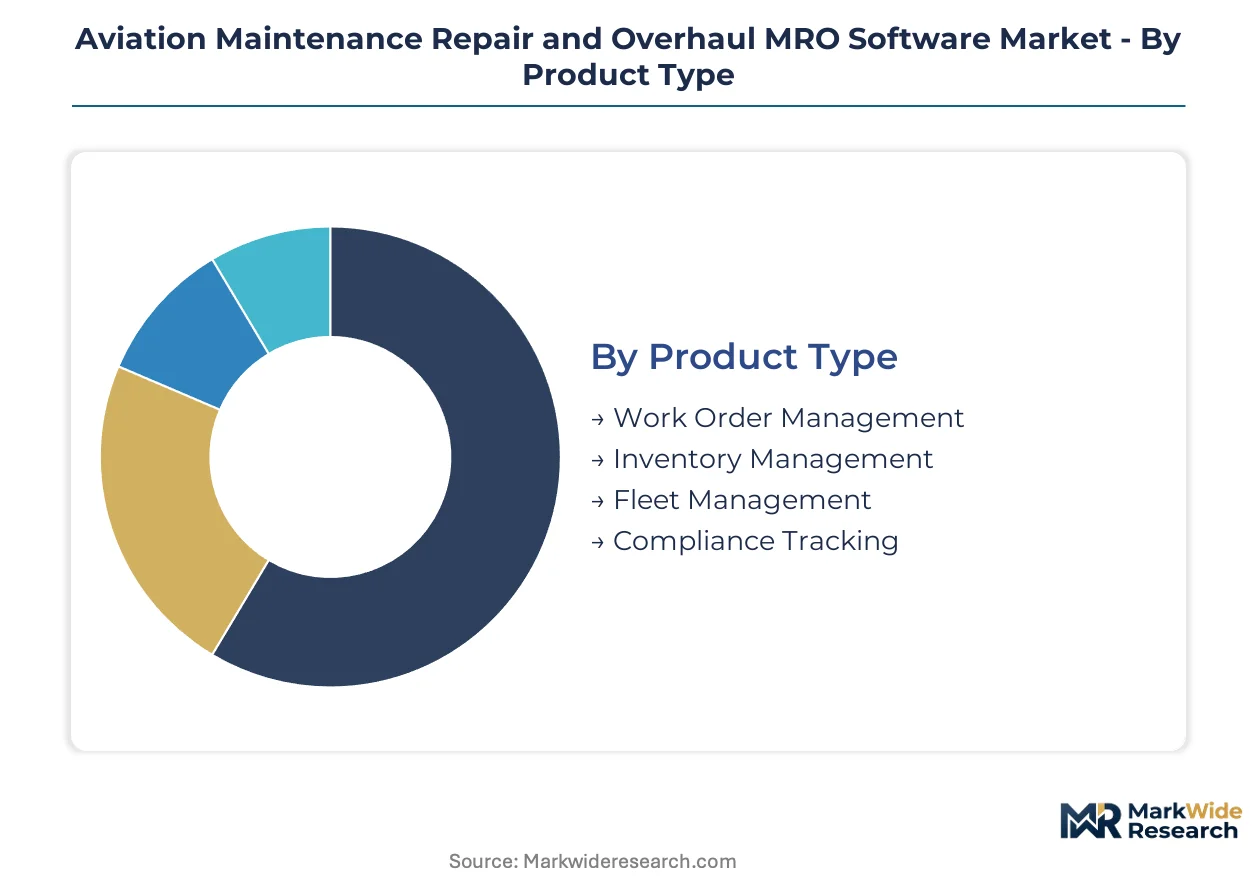
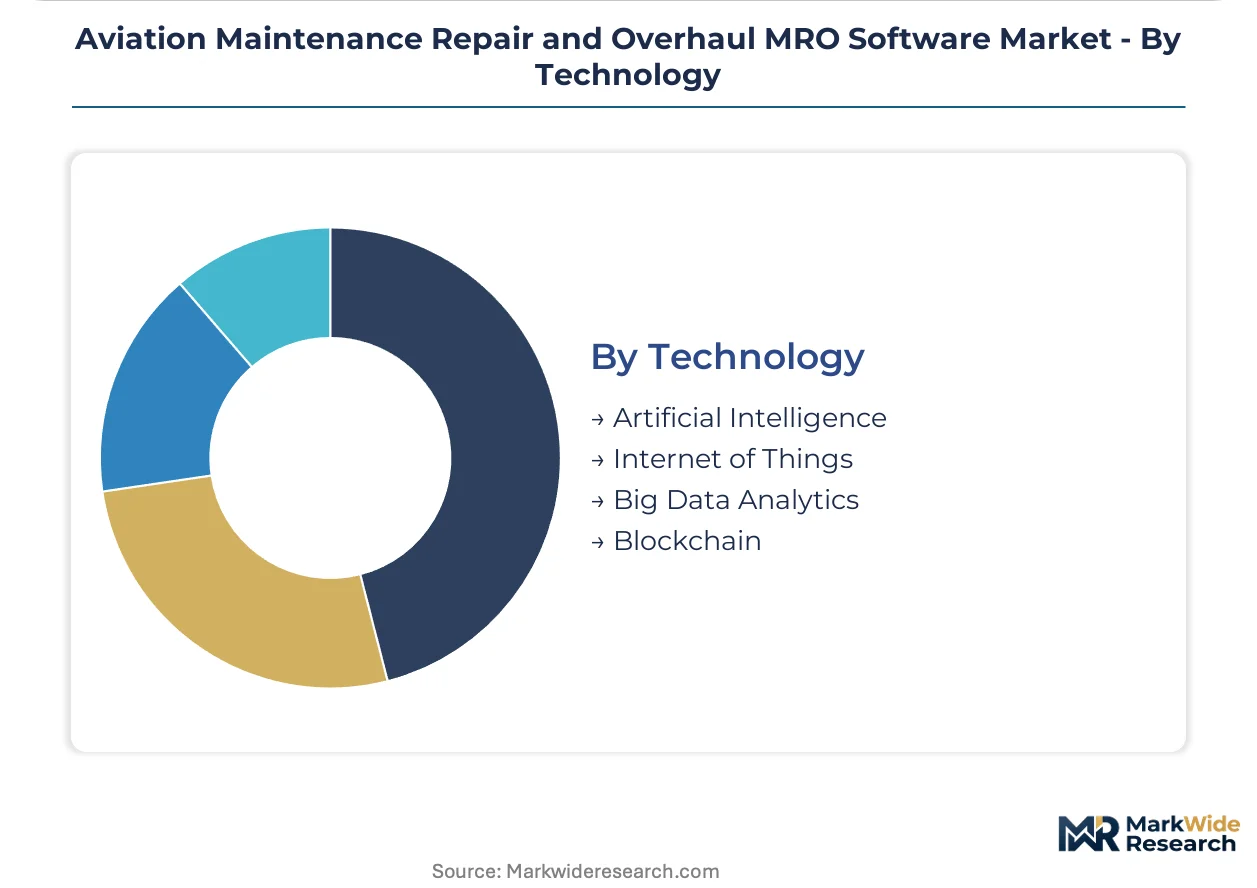
Segmentation in aviation MRO software reveals how procurement priorities diverge between capital-constrained regional operators and complex fleet managers. Deployment choices and technology adoption patterns directly determine vendor selection criteria and implementation timelines across the value chain.
Product Type:
Application focus varies sharply between operators prioritizing operational efficiency versus those facing immediate regulatory pressure.
- Work Order Management:Digital platforms coordinate labor scheduling, task assignment, and hangar resource allocation through real-time dashboards. Regional MRO stations in the United States deploy these systems to compress turnaround times and maximize bay utilization rates.
- Inventory Management:Modules track parts availability, rotable pooling, and procurement workflows across distributed supply chains. Airlines with aging fleets concentrate demand here as parts obsolescence risks escalate maintenance delays.
- Compliance Tracking:Automated audit trails harmonize FAA airworthiness directives with EASA Part-145 documentation requirements.
- Fleet Management:Unified scheduling interfaces consolidate heterogeneous aircraft portfolios under single operational views.
Fleet Management holds installed capacity. Compliance Tracking is rotating up the share rankings.
Deployment:
Cost tier positioning determines accessibility for different operator scales and IT maturity levels.
- Cloud-Based:Subscription architectures eliminate capital expenditure barriers and scale compute resources with fleet fluctuations. Asset-light lessors across North American and European markets drive concentration here as power-by-the-hour financing demands real-time visibility without infrastructure ownership.
- Mobile:Lightweight applications enable work order execution on hangar floors without fixed workstation dependency. Southeast Asian regional operators with limited IT infrastructure represent the fastest-expanding demand pocket for these platforms.
- On-Premise:Legacy client-server installations persist at defense operators with stringent data sovereignty requirements.
- Hybrid:Split architectures maintain sensitive compliance data locally while pushing analytics workloads to cloud environments.
On-Premise retains legacy commitments. Cloud-Based is climbing the fastest.
End User:
Customer type dictates functional requirements from predictive algorithms to audit-ready documentation.
- Airlines:Network carriers with hub-and-spoke operations demand integrated suites spanning scheduling, inventory, and compliance. These operators prioritize condition-based maintenance to minimize aircraft on ground time across high-utilization fleets.
- Maintenance Repair Stations:Third-party providers serving multiple airline contracts require flexible platforms supporting disparate regulatory standards and customer-specific reporting formats. EASA Part-145 approval maintenance drives technology refresh cycles here.
- Original Equipment Manufacturers:Boeing and Airbus leverage MRO software to manage warranty programs and technical documentation distribution.
- Defense Operators:Military fleets impose classified data handling requirements and specialized airworthiness protocols.
Airlines anchor procurement volume. Maintenance Repair Stations are gaining share fastest.
Technology:
Maturity gradients separate experimental deployments from production-scale implementations.
- Artificial Intelligence:Machine learning models trained on flight data analytics predict component degradation before failure. Commercial airlines with extensive sensor data archives concentrate adoption here as unplanned downtime costs justify algorithm development investment.
- Internet of Things:Sensor networks stream real-time health monitoring from engines, avionics, and structural components. Connected fleet programs at major carriers drive deployment as hardware costs decline and connectivity standards stabilize.
- Big Data Analytics:Historical maintenance record mining identifies failure patterns across aircraft populations.
- Blockchain:Distributed ledger pilots address parts provenance tracking amid regulatory pressure on counterfeit components.
Big Data Analytics holds production deployment. Artificial Intelligence is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where major carrier fleets demand predictive maintenance platforms at scale, while European operators absorb compliance premiums from EASA digitization mandates.
United States
Legacy carrier fleets and asset-light lessors drive demand for cloud-native platforms with real-time visibility. FAA airworthiness directive digitization pressures paper-based MRO operations toward compliant software. Dallas-Fort Worth and Chicago O'Hare hub concentrations anchor procurement volume for integrated fleet management suites.
Germany
Lufthansa Technik's engineering heritage shapes regional preference for precision maintenance planning tools. EASA Part-145 documentation standards mandate electronic signature capture and immutable audit trails. Hamburg's MRO cluster accelerates platform upgrades to avoid approval suspensions during regulatory inspections.
United Kingdom
Heathrow-centric network carriers prioritize condition-based maintenance to minimize aircraft on ground time. The Civil Aviation Authority aligns with EASA standards while maintaining distinct record-keeping protocols. London Gatwick's third-party repair stations drive demand for flexible multi-authority compliance modules.
India
Regional operators with limited IT infrastructure favor mobile-first work order execution platforms. DGCA digitization initiatives lag EASA and FAA timelines, creating implementation windows for lightweight deployments. Bangalore's aviation software development cluster supplies engineering talent for cloud-native architecture builds.
Singapore
Changi-based MRO hubs serving Asia-Pacific transit traffic require multi-fleet scheduling across heterogeneous aircraft portfolios. CAAS harmonization with EASA standards simplifies compliance for European-registered aircraft maintenance. Seletar Aerospace Park concentrates third-party repair station demand for inventory management and parts traceability systems.
Aviation Maintenance Repair and Overhaul MRO Software Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in compliance tracking and mobile execution modules. The vendor base stratifies across three tiers: enterprise suite providers anchoring major carrier contracts, cloud-native challengers capturing lessor and regional operator segments, and legacy on-premise vendors defending defense operator relationships. Two competitive moves dominate: vertical integration into adjacent fleet analytics and strategic partnerships with sensor hardware manufacturers for IoT-enabled maintenance pipelines.
Within the cloud-native challenger tier, IBS Software and Ramco Systems exemplify architecture-first positioning against incumbent enterprise stacks. Oracle Corporation anchors the enterprise-grade maintenance planning segment for global carriers with complex multi-fleet operations. These three occupy positions across the deployment spectrum from subscription SaaS to hybrid cloud environments.
| Leading Market Players |
|---|
| IBS Software |
| Lufthansa Technik AG |
| Ramco Systems |
| Oracle Corporation |
| General Electric Company |
| IFS AB |
| Flatirons Solutions |
| SAP SE |
| Swiss Aviation Software |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure concentration in the United States and Western Europe anchors margin pools with SaaS providers serving asset-light lessors, while downstream pricing power fragments across regional operators with heterogeneous IT maturity.
Pricing Analysis
The customization-premium spread separates configured enterprise deployments from standardized SaaS tiers. Subscription-based pricing dominates, with differentiation driven by compliance certification level and fleet integration complexity. Cost compression in the mid-market tier intensifies as cloud-native challengers undercut legacy on-premise vendors. Regional operators with limited capital budgets exhibit highest price sensitivity, while global carriers with multi-fleet operations absorb premium configurations.
Supply Chain Analysis
Extended payment terms from major carriers concentrate working capital pressure on specialized aviation software engineering pools in India and Eastern Europe. Development talent draws from Bangalore's aviation software cluster and Poland's technical universities. Single-source vulnerability sits with scarce airworthiness regulation expertise. Distribution runs through direct enterprise sales teams for major carriers and channel partners for regional operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as airline procurement departments consolidate around integrated platform suites, displacing fragmented point-solution vendors.
For Market Incumbents: Build regulatory data moats by embedding automated FAA, EASA, and CAAC compliance modules directly into core platforms. Acquire specialized mobile-first execution providers serving Southeast Asian regional operators before cloud-native challengers scale. The threat of AI-enabled predictive maintenance algorithms from venture-backed entrants demands rapid certification investment in EU AI Act pathways. For New Entrants and Emerging Players: Establish a beachhead in mobile-first work order execution for underpenetrated Latin American and Southeast Asian markets lacking IT infrastructure for heavy client-server deployments. Target third-party maintenance repair stations facing EASA Part-145 documentation upgrades. A channel partnership model with regional aviation hardware distributors accelerates footprint without direct enterprise sales investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed cloud-native challengers possessing scalable architectures but limited compliance certification depth. Long-term viability hinges on regulatory moat construction over algorithmic differentiation. Monitor EU AI Act implementation timelines as inflection indicator for certified platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies fleet management, compliance tracking, and inventory modules for hub-and-spoke carriers. |
| EU AI Act Certification | Creates first-mover advantage for predictive maintenance algorithms on European-registered aircraft. |
| Strategic Partnership | Links sensor hardware manufacturers to IoT-enabled maintenance pipelines for connected fleet programs. |
| Acquisition of Specialist Firm | Absorbs mobile-first execution capabilities for regional operators with limited IT infrastructure. |
| Geographic Expansion | Establishes local compliance engineering presence for EASA Part-145 and CAAC harmonization requirements. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airline fleet managers, MRO station directors, aviation software engineers, lessor asset managers, and regulatory compliance officers. Secondary validation drew from FAA airworthiness directive databases, EASA Part-145 approval registries, SEC filings of publicly traded software vendors, and cloud infrastructure capex disclosures. Bottom-up deployment estimates across fleet sizes and top-down vendor revenue analysis were triangulated for segmentation calibration.
Calibration against historical adoption curves and regulatory implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, fleet size tier, compliance complexity, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating power-by-the-hour financing penetration and predictive maintenance algorithm adoption rates.
Stress conditions across cloud infrastructure pricing volatility, airworthiness engineer supply constraints, and multi-authority regulatory divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about digitization mandate timelines and SaaS migration velocity. Macroeconomic contraction, accelerated regulatory fragmentation, or breakthrough AI certification pathways would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Africa Aircraft Windshield Wiper and Washer System Market
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Autoclave Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Training Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Colombia Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Disassembly Dismantling and Recycling Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
US Aerospace Components MRO Market
Aircraft Maintenance and MRO Solutions
Aerospace and Defense MRO Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Engine MRO Market