
 Aerospace and Defense Composites Market | 2026-2036
Aerospace and Defense Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace and Defense Composites Market Insights
Software-defined predictive maintenance contracts for composite airframe health monitoring is decoupling material sales from long-term revenue capture. Hexcel Corporation leverages captive prepreg manufacturing to anchor its position in military fighter programs. Toray Industries, Inc. sustains technology leadership through vertical control of carbon fiber precursor supply. Syensqo SA differentiates via specialized thermoplastic composite formulations for next-generation engine nacelles.
Aerospace and defense composites are fiber-reinforced polymer systems combining carbon, glass, or aramid reinforcements with thermoset or thermoplastic matrices, typically cured under autoclave pressure at 180°C to achieve specific strength-to-weight ratios exceeding 200 MPa/(g/cm³) for primary structural applications. CFRP dominates primary airframe applications where specific stiffness requirements govern material selection, while thermoplastic composites represent the fastest-expanding manufacturing stage category due to weldability and recyclability advantages in high-rate production environments. GFRP retains cost-sensitive positions in interior panels and secondary structures where electromagnetic transparency or damage tolerance priorities override weight minimization.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements mandate extensive damage tolerance and fatigue testing protocols that extend qualification timelines and concentrate supplier relationships with established testing capabilities. EPA National Emission Standards for Hazardous Air Pollutants and REACH substance restrictions constrain resin chemistry options and drive reformulation investments across European and North American supply chains. Stakeholders must monitor evolving military airworthiness requirements from the US DoD and NATO certification bodies as next-generation platforms accelerate composite content targets without established long-term performance databases.
Market Dynamics
Military airframe procurement is compressing qualification timelines for thermoplastic composites while FAA and EASA tighten material traceability mandates. Suppliers face simultaneous pressure to accelerate production rates and expand certified supplier networks.
Growth Catalysts
- Next-generation fighter programs:US DoD and NATO procurement offices are mandating composite content targets above 50% airframe weight, creating locked-in demand for qualified prepreg suppliers.
- REACH substance restrictions:ECHA-driven reformulation of epoxy resin chemistry is accelerating adoption of bio-based alternatives in European aerospace manufacturing clusters.
- Thermoplastic weldability:Out-of-autoclave processing is absorbing capital investment from German and French Tier 1 suppliers seeking high-rate production for narrowbody programs.
Market Restraints
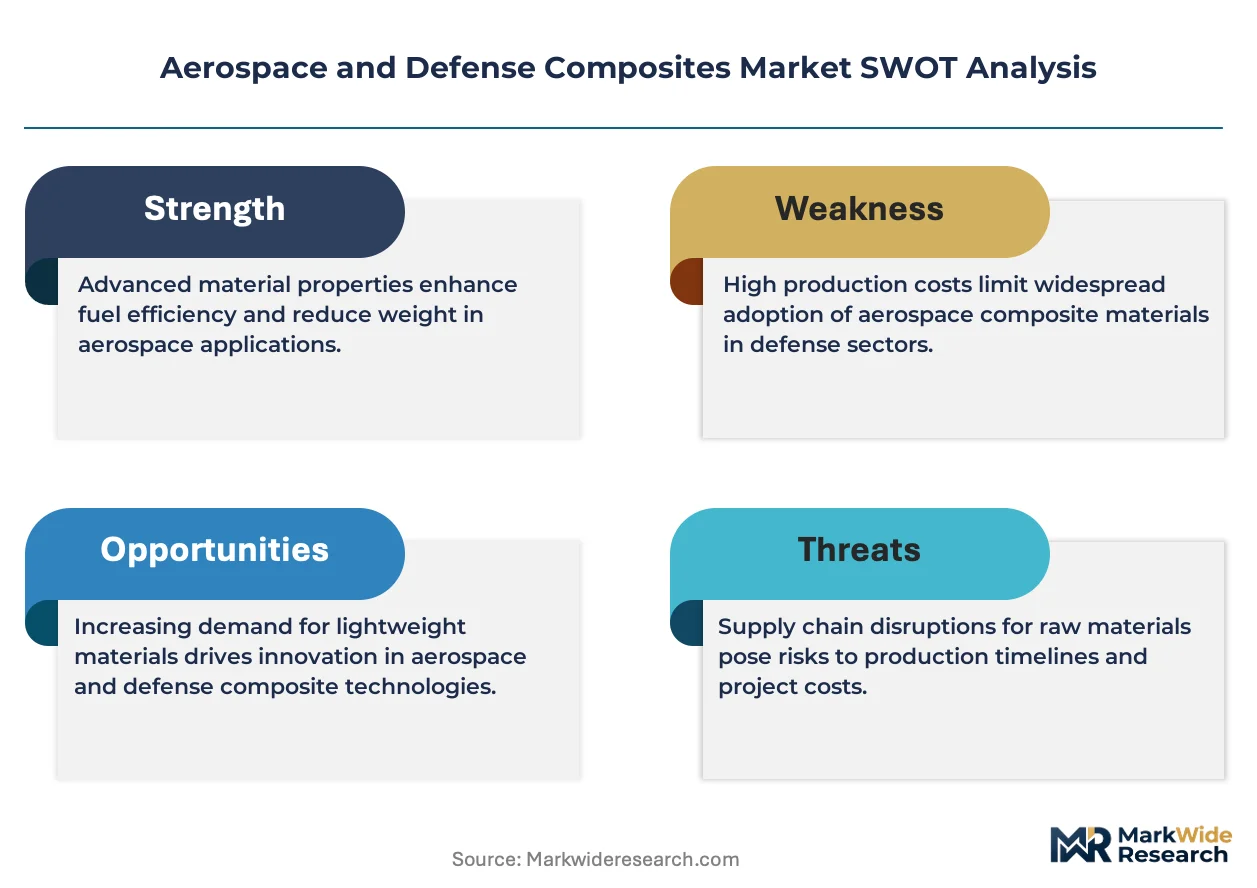
- Acrylonitrile cost volatility:Carbon fiber precursor supply concentrates among Japanese and Chinese petrochemical producers, exposing margins to feedstock price swings.
- FAA Part 25 damage tolerance protocols:Fatigue testing requirements extend qualification timelines to 18-24 months, freezing out new entrants lacking established testing infrastructure.
- Aluminum-lithium substitution:Arconic and Constellium are advancing third-generation Al-Li alloys for wing skins, reclaiming applications where composite repair complexity outweighs weight savings.
Strategic Opportunities
- Urban air mobility platforms:eVTOL manufacturers in California and Bavaria are sourcing thermoplastic fuselage panels without legacy airframe qualification baggage.
- US DoD software-defined maintenance:Predictive health monitoring contracts are decoupling material sales from long-term revenue capture for established suppliers.
- India defense industrial corridor:Tamil Nadu and Uttar Pradesh manufacturing zones offer tariff-advantaged positions for composite component fabrication serving Southeast Asian MRO demand.
Industry Challenges
- Autoclave operator scarcity:Specialized technician training programs at Wichita State and Cranfield University cannot match retirement rates in North American and European manufacturing bases.
- Legacy fleet retrofit integration:Boeing 737 and Airbus A320 MRO networks face structural repair certification gaps when bonding composite patches to aging aluminum substrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace and Defense Composites Market |
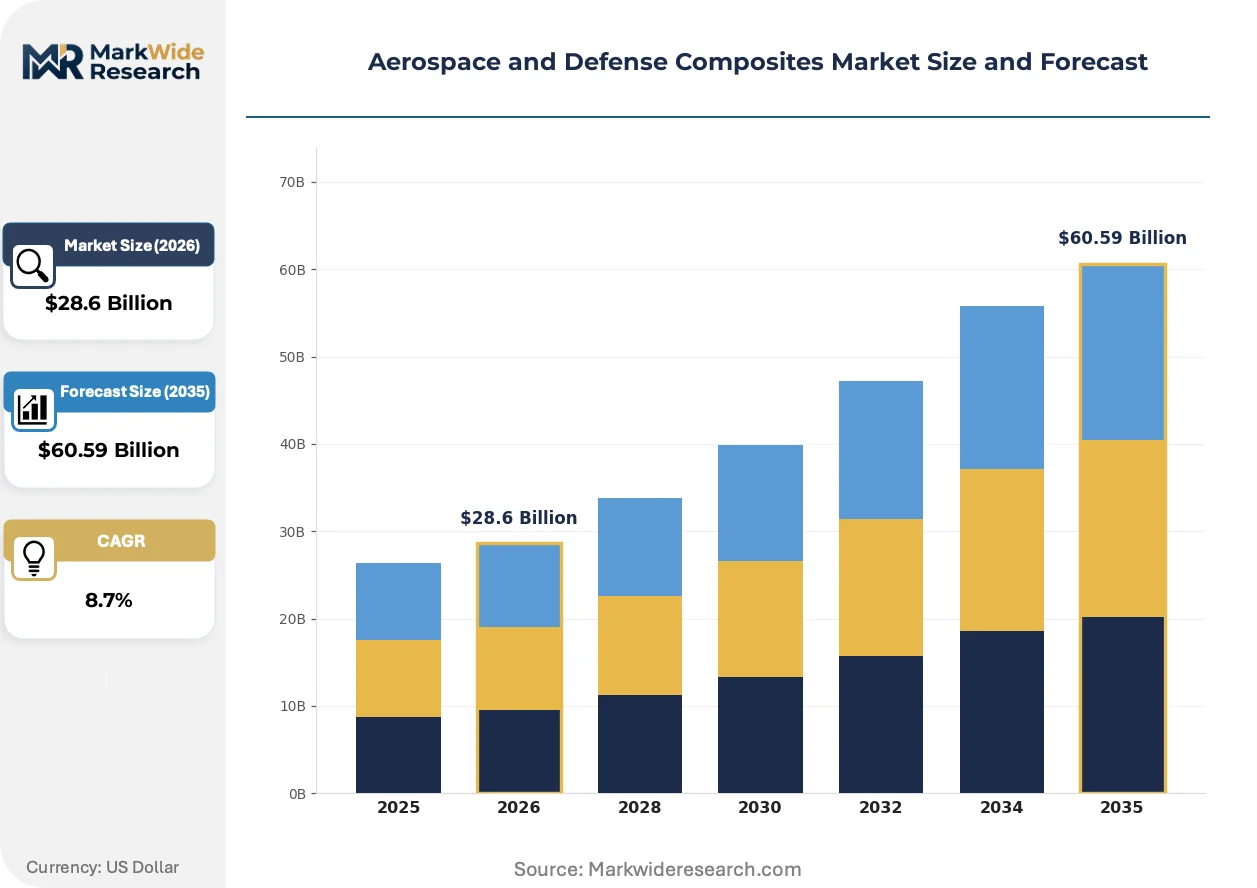
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CFRP, GFRP, Aramid, Thermoplastic Composites Application: Airframes, Components, Interiors, Military Equipment End User: Commercial Aviation, Military Aviation, Defense Contractors, Aerospace OEMs Manufacturing Stage: Prepregs, Infusion, Layup, 3D Printing |
| Companies Covered | Hexcel Corporation, Syensqo SA, Toray Industries, Inc., DuPont de Nemours, Inc., Honeywell International Inc., Mitsubishi Chemical Group Corporation, Teijin Limited, SGL Carbon, Owens Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace and Defense Composites Market Trends and Innovations
Manufacturing process evolution is compressing cycle times while regulatory chemistry constraints and defense procurement model shifts are rewriting supplier economics. Material qualification protocols lag behind processing advances.
Automated fiber placement with in-situ consolidation is absorbing development resources from Toray and Hexcel as they race to eliminate autoclave bottlenecks. Defense prime contractors in Texas and Bavaria are piloting these systems for fighter wing production. The technology is absorbing capital that previously flowed to incremental prepreg formulation improvements.
EPA National Emission Standards for Hazardous Air Pollutants are forcing reformulation of bisphenol-A based epoxy systems across US Gulf Coast resin manufacturing. Formulators in Louisiana and Texas are shifting to dicyclopentadiene and lignin-derived alternatives. Small airframe subcontractors without in-house environmental compliance teams are consolidating procurement through Tier 1 distributors.
Performance-based logistics contracts are fragmenting traditional material-supply relationships. US Air Force and Navy sustainment offices now contract for flight-hour availability rather than spare parts delivery. Composite repair depots in Georgia and Arizona are absorbing inventory risk previously held by OEMs, compressing working capital cycles for specialist MRO providers.
Aerospace and Defense Composites Market Segmentation
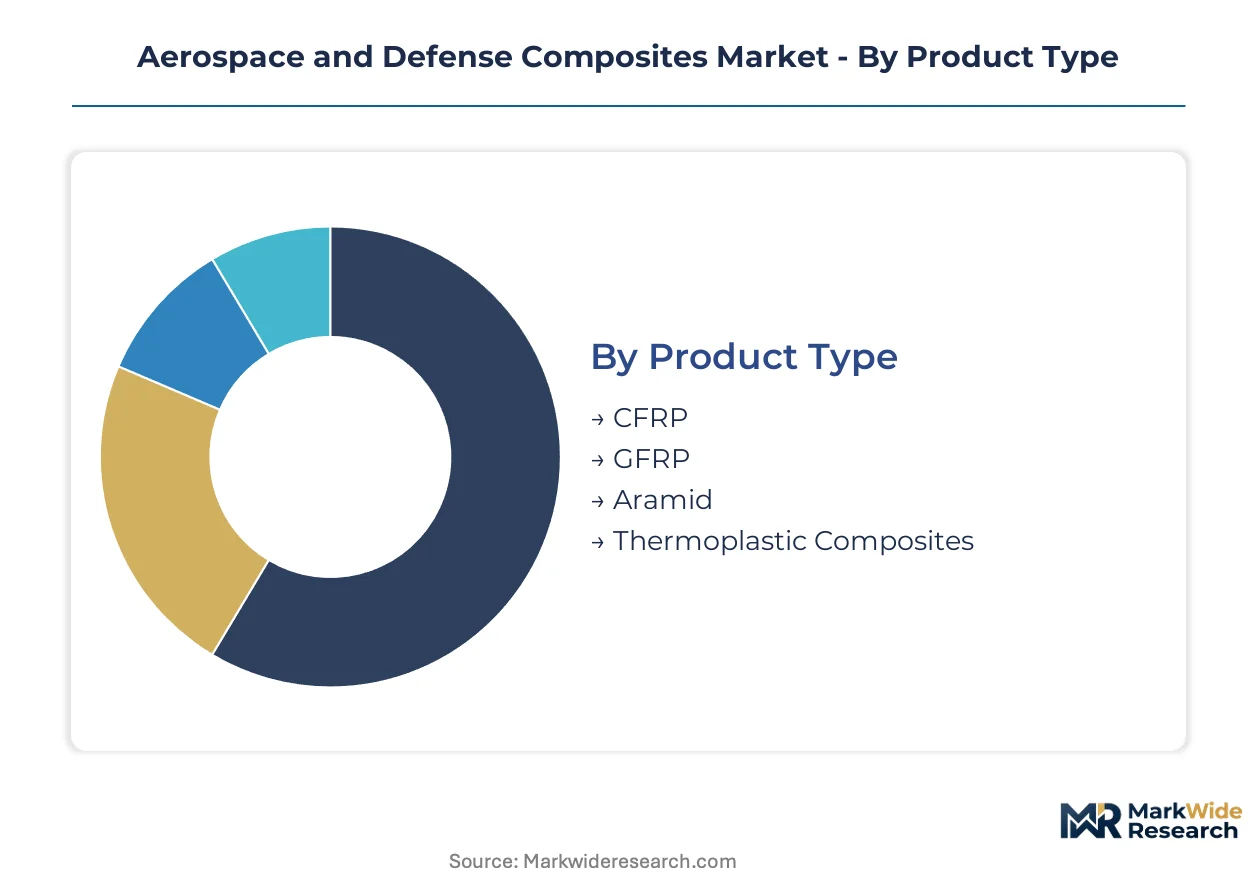
Segmentation reveals how material specifications, certification requirements, and manufacturing economics partition this market. Each dimension exposes distinct margin structures and supplier positioning strategies that shape procurement decisions across defense and commercial programs.
Product Type:
Carbon fiber reinforced polymer commands premium pricing while glass fiber alternatives serve cost-constrained applications. Aramid and thermoplastic formulations occupy specialized niches with divergent growth trajectories.
- CFRP:Carbon fiber reinforced polymer systems achieve specific strength ratios exceeding 200 MPa/(g/cm³) through autoclave curing at 180°C. Primary structural applications in US fighter programs and German aerospace clusters drive locked-in demand from qualified prepreg suppliers.
- Thermoplastic Composites:Weldable thermoplastic matrices enable out-of-autoclave processing with recyclability advantages. Bavarian and French Tier 1 suppliers are absorbing capital investment for high-rate narrowbody production.
- GFRP:Glass fiber systems retain electromagnetic transparency for radar-transparent applications and damage-tolerant secondary structures where weight minimization is secondary to cost control.
- Aramid:Kevlar-based composites provide ballistic protection and vibration damping in military rotorcraft and armor applications with specialized resin compatibility requirements.
Today's leader: CFRP. Tomorrow's challenger: Thermoplastic Composites.
Application:
Structural loads and regulatory scrutiny vary dramatically across airframe integration depth. Primary structures face FAA Part 25 damage tolerance mandates while interior applications navigate flammability standards.
- Airframes:Wing skins, fuselage barrels, and empennage structures carry primary flight loads. US DoD next-generation fighter mandates above 50% composite airframe weight concentrate procurement among established prepreg suppliers with fatigue testing infrastructure.
- Components:Control surfaces, engine nacelles, and landing gear doors balance weight savings against repair accessibility. Specialized thermoplastic formulations from Syensqo SA target next-generation engine integration.
- Interiors:Cabin panels, galleys, and lavatory modules prioritize flammability resistance and acoustic dampening over structural performance. GFRP dominates this cost-sensitive segment.
- Military Equipment:Armor plates, radomes, and unmanned vehicle structures combine ballistic protection with electromagnetic signature management. Aramid-carbon hybrids serve fragmentation-resistant applications.
Structural certification barriers protect incumbent positions in airframes. Component applications offer the steepest expansion trajectory for alternative material systems.
End User:
Procurement models diverge between performance-based logistics contracts and traditional material supply agreements. Defense sustainment offices now contract for flight-hour availability rather than spare parts delivery.
- Commercial Aviation:Boeing and Airbus production rates drive volume demand for qualified prepreg systems. MRO networks face structural repair certification gaps when bonding composite patches to aging aluminum substrates.
- Military Aviation:US Air Force and Navy sustainment offices decouple material sales from long-term revenue through predictive health monitoring contracts. Composite repair depots in Georgia and Arizona absorb inventory risk previously held by OEMs.
- Defense Contractors:Prime contractors in Texas and Bavaria pilot automated fiber placement with in-situ consolidation for fighter wing production. Capital flows to processing technology rather than incremental formulation improvements.
- Aerospace OEMs:Tier 1 integrators consolidate procurement through distributors to manage EPA National Emission Standards for Hazardous Air Pollutants compliance without in-house environmental teams.
Military procurement innovation is reshaping supplier economics. Commercial aviation volume sustains manufacturing scale.
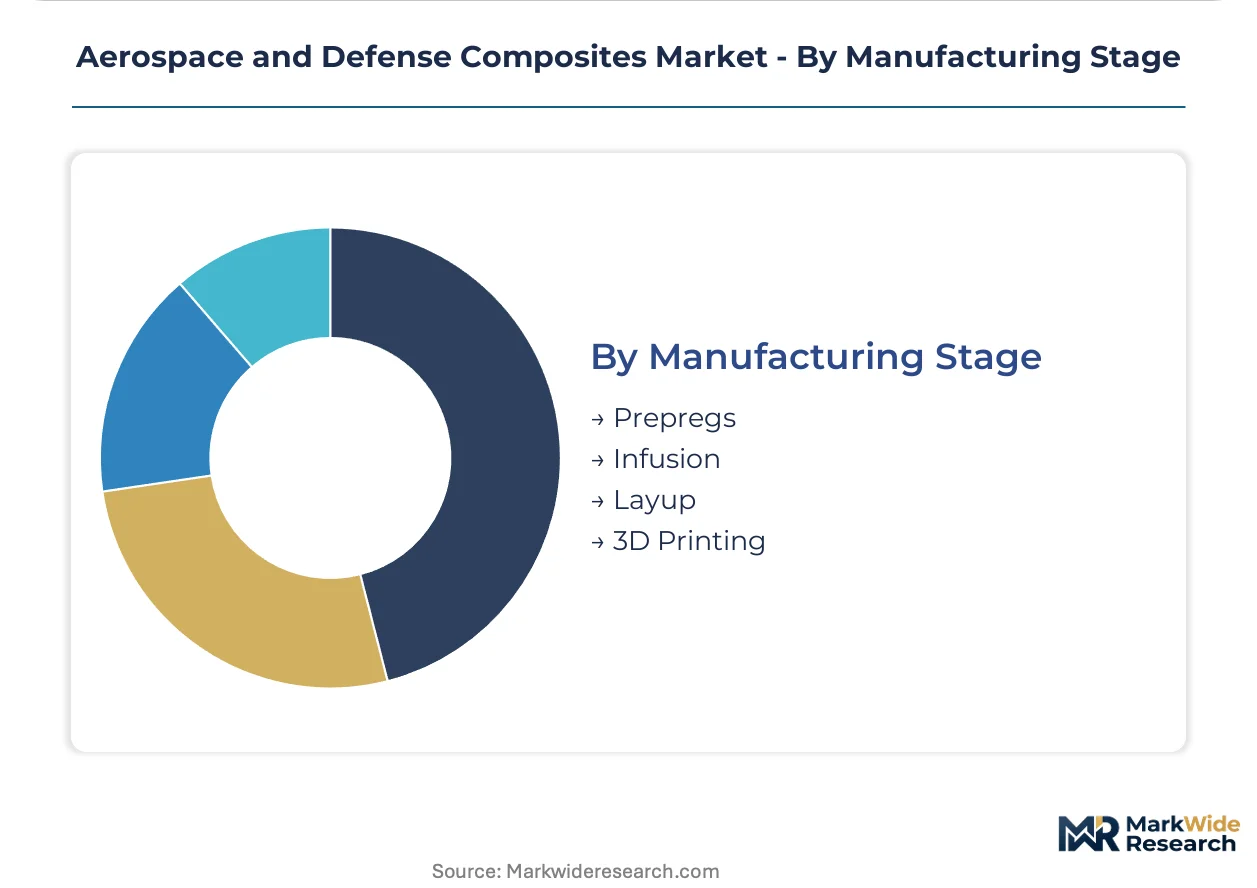
Manufacturing Stage:
Process selection determines capital intensity, cycle time, and qualification pathway. Established autoclave methods face displacement from out-of-autoclave alternatives.
- Prepregs:Resin-impregnated fiber systems cure under autoclave pressure with 18-24 month FAA qualification timelines. Hexcel Corporation leverages captive prepreg manufacturing to anchor military fighter program positions.
- Infusion:Resin transfer molding and vacuum-assisted processes reduce capital requirements for large structures. EASA design approval standards tighten material traceability mandates across European manufacturing clusters.
- Layup:Manual and automated fiber placement remain dominant for complex geometries. Wichita State and Cranfield University training programs cannot match retirement rates for specialized autoclave technicians.
- 3D Printing:Additive manufacturing of continuous fiber composites enables topology-optimized brackets and ducting. eVTOL manufacturers in California source thermoplastic fuselage panels without legacy airframe qualification baggage.
Prepreg qualification infrastructure defends incumbent margins. Thermoplastic 3D printing gains share fastest in emerging mobility platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States defense industrial base generates heavier composite demand per airframe than German commercial aviation clusters, yet both markets face converging pressure from FAA and EASA material traceability mandates.
United States
Next-generation fighter programs from Lockheed Martin and Northrop Grumman mandate composite airframe content above 50%, locking in prepreg demand for qualified suppliers. FAA Part 25 damage tolerance protocols extend qualification timelines to 18-24 months, concentrating procurement among established testing infrastructure holders. Defense prime contractors in Texas and Georgia pilot automated fiber placement systems for fighter wing production.
Germany
Airbus Hamburg and Premium Aerotec drive thermoplastic composite adoption for narrowbody fuselage sections seeking out-of-autoclave cycle time reductions. EASA CS-25 certification requirements tighten material traceability across Bavarian and Hamburg manufacturing zones. Munich-area Tier 1 suppliers absorb capital investment for high-rate automated fiber placement lines serving A320 family production ramps.
France
Safran and Dassault Aviation anchor composite demand for engine nacelles and Rafale fighter structures respectively. REACH substance restrictions from ECHA force reformulation of bisphenol-A epoxy systems across French resin manufacturing. Toulouse and Bordeaux aerospace clusters specialize in thermoplastic welding processes for next-generation engine integration.
Japan
Toray Industries and Mitsubishi Chemical Group control carbon fiber precursor supply chains serving both domestic and export aerospace demand. METI industrial policy supports advanced materials R&D through public-private partnerships. Nagoya and Tokyo manufacturing bases concentrate on PAN-based precursor production for military and commercial airframe qualification.
India
Tamil Nadu and Uttar Pradesh defense industrial corridors attract composite component fabrication for Southeast Asian MRO demand. DGFT tariff structures favor localized production serving Indian Air Force Tejas and AMCA programs. Bengaluru and Hyderabad clusters develop indigenous prepreg capabilities under offset arrangements with foreign OEMs.
Aerospace and Defense Composites Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with qualified prepreg suppliers commanding premium positions in military fighter programs while commoditized fabricators compete on cycle time for commercial interiors. The market structure concentrates around three to five vertically integrated carbon fiber producers and a fragmented tier of regional laminators. Strategic archetypes include captive precursor manufacturers, autoclave-dependent qualification holders, and thermoplastic welding specialists. Dominant competitive moves involve backward integration into precursor supply and strategic partnerships with defense primes for predictive maintenance contracts.
Among established qualification holders, Hexcel Corporation and Toray Industries, Inc. exemplify the captive manufacturing archetype through in-house prepreg and precursor control. Syensqo SA occupies a differentiated position within thermoplastic composite formulations. These three entities anchor the supplier landscape across US and European defense procurement channels.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Syensqo SA |
| Toray Industries, Inc. |
| DuPont de Nemours, Inc. |
| Honeywell International Inc. |
| Mitsubishi Chemical Group Corporation |
| Teijin Limited |
| SGL Carbon |
| Owens Corning |
| Others |
Pricing and Supply Chain Analysis
US DoD next-generation fighter mandates for above 50% composite airframe weight are forcing prepreg suppliers to absorb extended FAA Part 25 qualification timelines while defending margins against aluminum-lithium substitution threats. This demand-side pressure concentrates procurement among established testing infrastructure holders and compresses pricing flexibility for new material formulations.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for carbon fiber precursor supply as Toray Industries and Mitsubishi Chemical Group expand PAN-based production. Three-tier pricing structure across aerospace-qualified, industrial-grade, and emerging mobility tiers reflects FAA certification investment recovery timelines. Cost compression in thermoplastic formulations is intensifying because Bavarian Tier 1 suppliers absorb capital for out-of-autoclave welding systems. Commercial aviation OEMs exhibit highest price sensitivity due to production rate volatility, while defense primes accept premium positioning for locked-in supply security.
Supply Chain Analysis
Dual-sourcing requirements from US Air Force and Navy sustainment offices mandate qualified backup suppliers for critical prepreg systems, fragmenting procurement across Hexcel Corporation and secondary qualification holders. Geographic supply concentration centers on the United States, Japan, and Germany for carbon fiber precursor, epoxy resin formulation, and automated fiber placement equipment respectively. Raw material dependencies rest on acrylonitrile feedstock from Japanese and Chinese petrochemical producers, bisphenol-A alternatives from Louisiana formulators, and specialized thermoplastic polymers from European chemical clusters. Single-source vulnerability concentrates in Japanese PAN precursor production. Distribution runs through Tier 1 integrators consolidating procurement to manage EPA National Emission Standards compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Tamil Nadu and Uttar Pradesh manufacturing zones offer tariff-advantaged positions against established US and European supply bases, exploiting India's DGFT structures and lower autoclave operator labor costs.
For Market Incumbents: Acquire predictive health monitoring software capabilities to capture flight-hour availability contracts decoupling material sales from long-term revenue. Anchor military fighter program positions through captive prepreg manufacturing while expanding thermoplastic welding expertise to defend against aluminum-lithium substitution in wing skin applications. Threats concentrate in third-generation Al-Li alloys from Arconic and Constellium reclaiming structural applications. For New Entrants and Emerging Players: Launch via direct supply relationships with California and Bavarian eVTOL manufacturers sourcing thermoplastic fuselage panels without legacy airframe qualification baggage. Target urban air mobility platforms and Indian defense industrial corridor fabrication for Southeast Asian MRO demand. Penetrate through specialized thermoplastic composite formulations for next-generation engine nacelles where Syensqo SA has established differentiation. For Investors and Strategic Acquirers: Asymmetric upside sits with thermoplastic welding specialists and automated fiber placement technology providers serving high-rate narrowbody production ramps. Long-term viability over the next decade hinges on qualification infrastructure moats and software-defined maintenance contract capture. Signal to monitor: FAA and EASA material traceability mandate enforcement accelerating supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Toray Industries controls carbon fiber quality through captive PAN production serving military qualification. |
| Automated Fiber Placement Deployment | Defense primes in Texas eliminate autoclave bottlenecks through in-situ consolidation systems. |
| Thermoplastic Welding Process Development | Safran and Airbus Hamburg reduce cycle times for A320 family fuselage sections. |
| Predictive Maintenance Platform Launch | US Air Force contracts for flight-hour availability shift inventory risk to repair depots. |
| India Defense Industrial Corridor Expansion | Tamil Nadu zones attract composite fabrication under offset arrangements with foreign OEMs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with prepreg manufacturing directors, defense procurement officers at US DoD and NATO offices, FAA certification engineers, and Tier 1 supplier procurement leads with secondary validation from FAA Part 25 airworthiness filings, EASA CS-25 design approval records, EPA National Emission Standards enforcement data, and customs trade flows for carbon fiber precursor. Bottom-up segment sizing and top-down market reconciliation anchored value estimates.
Segment-weighting across product type, application depth, end-user procurement model, and manufacturing stage informed volume and value outputs throughout the forecast period. Analytical framework modeled CFRP, thermoplastic composites, GFRP, and aramid systems separately with divergent growth assumptions. CAGRs derived from production rate projections for Boeing and Airbus narrowbody programs, US DoD fighter procurement timelines, and eVTOL manufacturer order pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under military airworthiness requirement shifts from US DoD and NATO certification bodies without established long-term performance databases. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aircraft AFP and ATL Composites Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Stealth Coating Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Aerospace Composite Ducting Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Aerospace 3D Printing Consumables Market
Aerospace and Aircraft Materials
Composites in United States Defense Market
Aerospace and Aircraft Materials
Electromagnetic and Radio Frequency Interference Coating Market
Aerospace and Aircraft Materials
Aerospace and Defense Materials Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market