
 Aerospace Fasteners Market | 2026-2036
Aerospace Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Fasteners Market Intelligence
The EU Green Deal is recalibrating material selection across European aerospace supply chains. LISI Aerospace leverages titanium alloy expertise to dominate European narrow-body programs. Howmet Aerospace anchors North American rotorcraft demand through specialized superalloy fastener production. Precision Castparts Corp sustains foundry-to-finish vertical integration that controls critical heat-treatment specifications for engine-grade hardware.
Aerospace fasteners are mechanical joining devices engineered to shear strengths exceeding 1,100 MPa, manufactured through cold-heading, thread-rolling, and precision heat-treatment processes to maintain clamp loads under cyclic aerodynamic loading. Their primary function is structural integrity assurance across airframes, engines, and control surfaces subjected to extreme thermal and pressure differentials. Titanium alloys command premium positioning in commercial aviation applications where weight reduction translates directly to fuel burn savings. Steel alloys retain mature volume leadership in military aviation where cost tolerance for extreme-temperature engine exposure remains highest. Rotorcraft applications represent a concentrated margin pool given lower production volumes but exacting dynamic-load certification requirements.
FAA airworthiness standards, EASA CS-25 certification protocols, and ISO 9001/AS9100 quality frameworks collectively govern material traceability, lot testing, and supplier qualification timelines. These regulatory layers extend product development cycles and elevate barriers for uncertified entrants attempting aftermarket penetration. Stakeholders must monitor evolving sustainable aviation fuel compatibility requirements that may introduce new galvanic corrosion risks between dissimilar material interfaces.
Market Dynamics
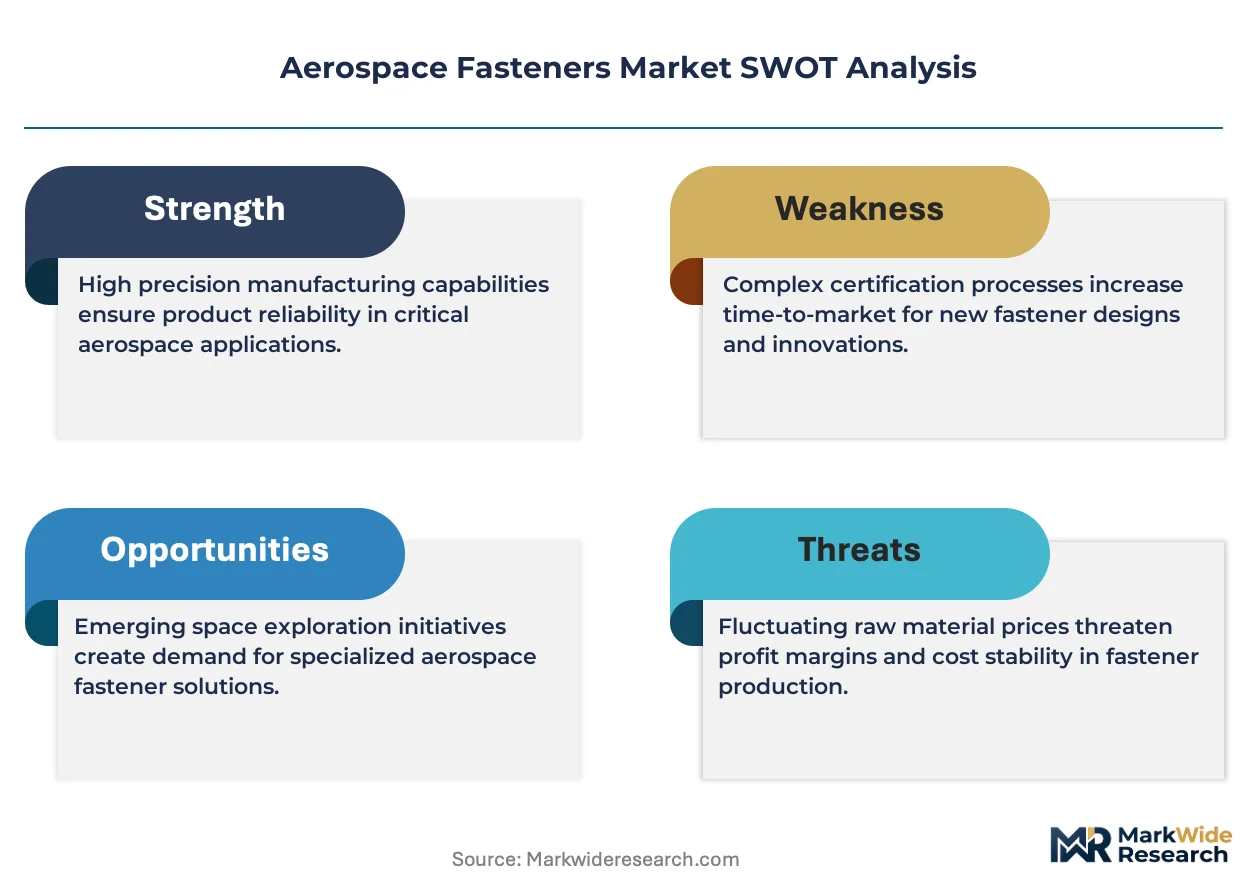
Commercial aviation procurement teams are consolidating fastener suppliers to secure titanium alloy volumes as narrow-body production rates climb toward sixty aircraft monthly. This concentration pressure is reshaping qualification timelines and forging long-term offtake agreements that lock out secondary vendors.
Growth Catalysts
- FAA Airworthiness Directives:Fatigue-resistant joining mandates for aging fleet retrofits are accelerating replacement cycles for legacy steel hardware across US-registered aircraft.
- Superalloy Fastener Adoption:Rotorcraft manufacturers are specifying nickel-based superalloys for dynamic-load zones, opening premium-margin demand pools beyond commercial aviation.
- China Final Assembly Expansion:COMAC C919 production ramp at Shanghai Pudong is localizing fastener procurement requirements and qualifying domestic heat-treatment facilities.
Market Restraints
- Titanium Sponge Volatility:Russian and Ukrainian feedstock disruptions have compressed spot availability for aerospace-grade titanium sponge, inflating raw material carrying costs.
- European Supplier Concentration:EASA-certified fastener production clusters heavily in France and Italy, creating single-source vulnerability for A320 family programs.
- Additive Manufacturing Substitution:Directed energy deposition of titanium lattice structures is displacing mechanical fastening in non-critical brackets and ducting.
Strategic Opportunities
- India MRO Expansion:Bangalore and Hyderabad maintenance clusters are qualifying AS9100 suppliers for indigenous narrow-body support, bypassing import dependency.
- Sustainable Aviation Fuel Compatibility:Biofuel aromatic content variations are driving galvanic corrosion testing protocols that favor coated titanium over bare steel interfaces.
- Digital Thread Integration:Blockchain-enabled material traceability is converging with automated optical inspection to compress lot-release documentation from weeks to days.
Industry Challenges
- Heat-Treatment Talent Scarcity:Specialized furnace operators capable of maintaining AMS 2750 pyrometry compliance are retiring faster than vocational programs can replenish.
- AS9100 Certification Timelines:New entrant qualification cycles now extend eighteen to twenty-four months, freezing working capital and delaying revenue recognition.
- Legacy System Integration:ERP migration from paper-based traveler systems to digital twins is disrupting shop-floor traceability during parallel operation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Fasteners Market |
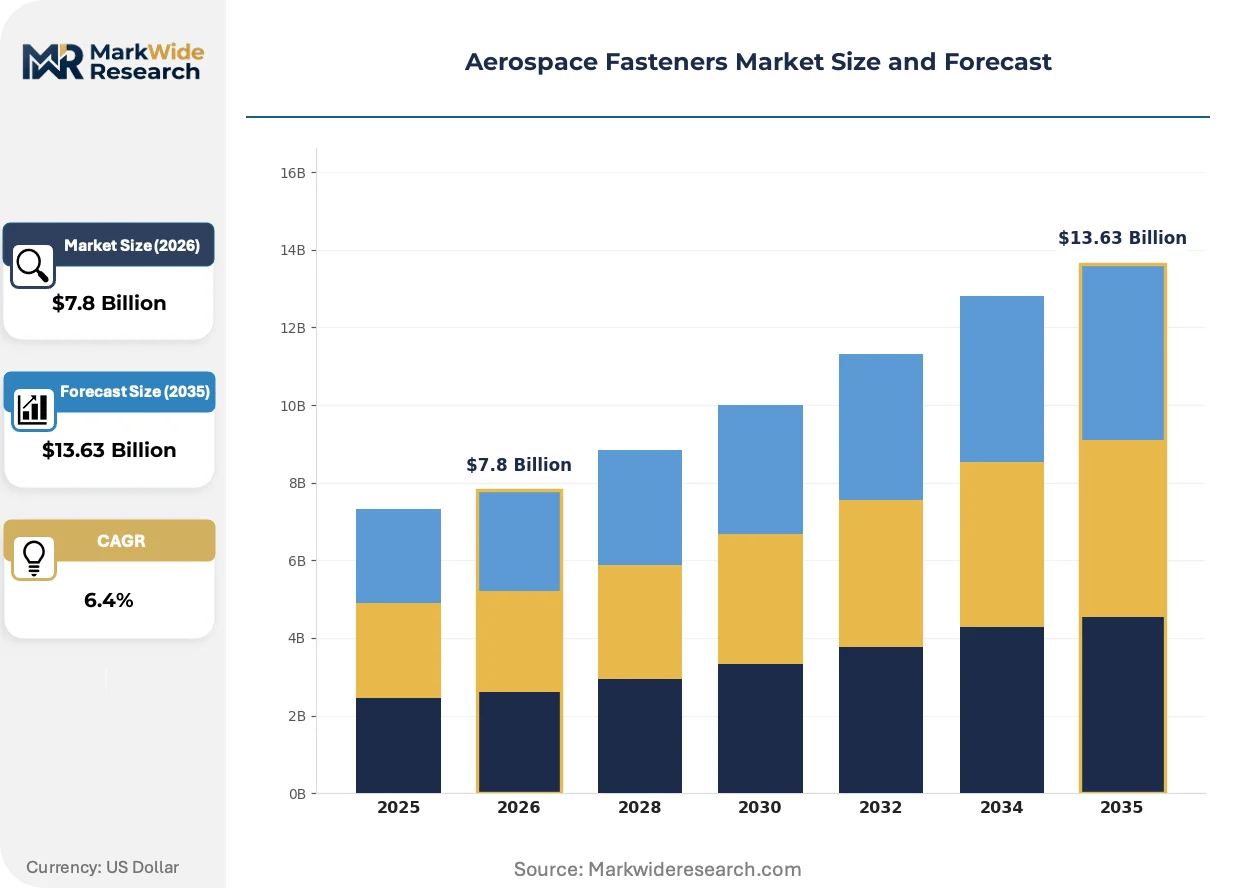
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rivets, Bolts, Screws, Washers, Nuts Material: Aluminum Alloys, Titanium Alloys, Steel Alloys, Composites, Nickel Alloys Application: Commercial Aviation, Military Aviation, Spacecraft, Rotorcraft End User: Aircraft OEMs, Maintenance Facilities, Aftermarket Suppliers, Component Manufacturers |
| Companies Covered | Stanley Black & Decker, B&B Specialties, LISI Aerospace, National Aerospace Fasteners Corporation, TriMas Corporation, Howmet Aerospace, Alcoa Fastening Systems, Wurth Group, Precision Castparts Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Fasteners Market Strategic Shifts & Innovations
Digital manufacturing protocols and sustainable material specifications are converging to redefine fastener value chains. These shifts are compressing development cycles while elevating documentation burdens.
Cold-formed titanium alloy fasteners are expanding into wing-to-fuselage attachment points previously reserved for machined steel. Boeing and Airbus procurement teams are qualifying these components for A350 and 787 programs to capture weight savings. This expansion is compressing the addressable market for legacy steel hardware in primary structure applications.
EASA CS-25 certification amendments now mandate digital thread documentation for all fatigue-critical fasteners entering European-registered aircraft. The regulation forces suppliers to retrofit legacy quality systems with blockchain-enabled traceability. Engine-grade hardware manufacturers face the steepest compliance costs, with some diverting investment from capacity expansion to IT infrastructure.
Airline technical procurement teams are unbundling fastener sourcing from airframe OEM kit agreements, establishing direct relationships with tier-two specialists. This disintermediation concentrates volume with AS9100-certified suppliers capable of lot-size flexibility. The pattern is most visible in North American low-cost carrier fleets, where maintenance control centers negotiate spot contracts for AOG support.
Aerospace Fasteners Market Segmentation
Fastener segmentation in aerospace tracks divergent technical requirements across airframe structures, propulsion systems, and mission profiles. Procurement patterns split sharply between fuel-efficiency-driven commercial programs and durability-focused military specifications.
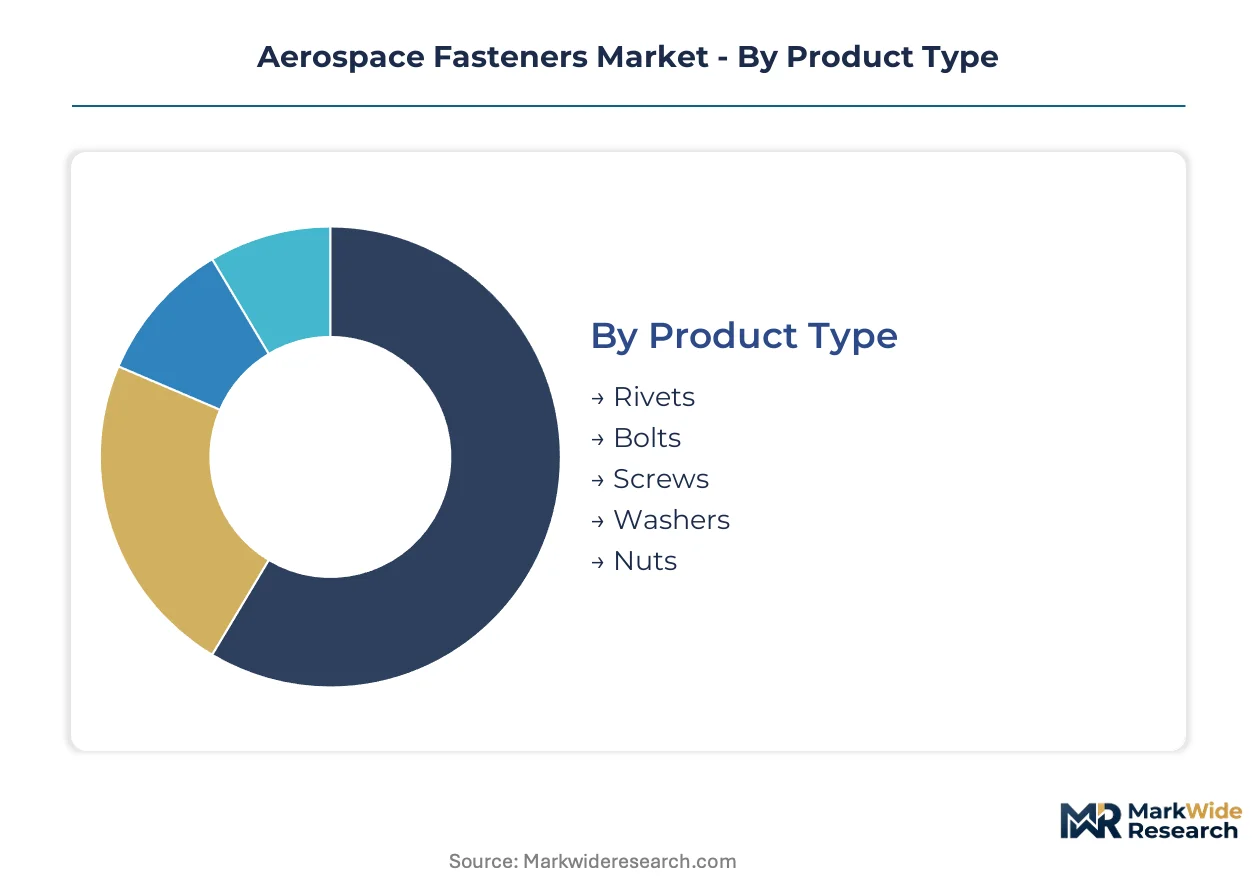
Product Type:
Buyers differentiate by installation method, load-bearing geometry, and field-serviceability requirements.
- Rivets:Permanent mechanical fasteners installed through cold-working processes that create interference-fit joints. Airbus A350 wing panel assembly consumes substantial volumes of titanium blind rivets at its Hamburg and Toulouse facilities.
- Bolts:Removable high-strength threaded fasteners engineered to preload specifications exceeding 75% of yield strength. Boeing 787 fuselage barrel sections specify titanium alloy bolts for longitudinal splice joints to minimize parasitic weight.
- Screws:Self-tapping or machine-threaded fasteners for non-structural panels and interior hardware.
- Washers:Load-distribution components preventing galling under bolt heads in aluminum-titanium interfaces.
- Nuts:Threaded retention elements including self-locking variants for vibration-critical engine mounts.
Volume sits with rivets; growth tilts toward bolts.
Material:
Material selection follows a weight-versus-temperature tradeoff curve unique to each aircraft zone.
- Titanium Alloys:Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr grades deliver strength-to-weight ratios roughly 40% superior to steel. Narrow-body OEMs in the United States and France are locking in multi-year offtake agreements for aerospace-grade sponge to secure Ti-6Al-4V bolt production.
- Steel Alloys:A286 and MP35N superalloys retain mechanical properties beyond 650°C in turbine engine hot sections. Military engine programs specify these alloys for combustor and afterburner attachment hardware where cost tolerance exceeds commercial thresholds.
- Aluminum Alloys:2024-T4 and 7075-T6 grades serve secondary structure applications with moderate thermal exposure.
- Nickel Alloys:Inconel 718 and Waspaloy fasteners secure exhaust nozzle assemblies and thrust reverser linkages.
- Composites:Carbon-fiber reinforced polymer fasteners address electromagnetic interference concerns in radar-proximate installations.
Steel alloys dominate current volume; titanium alloys are gaining share fastest.
Application:
Application segmentation reflects fundamentally different certification cycles and procurement consolidation patterns.
- Commercial Aviation:Single-aisle and wide-body aircraft programs with FAA/EASA type certificates driving standardization. Final assembly lines in Renton, Everett, Toulouse, and Tianjin consume threaded fasteners at rates scaling with sixty-aircraft monthly production targets.
- Military Aviation:Fighter and bomber platforms with MIL-STD-810 environmental qualification requirements. Lockheed Martin F-35 production at Fort Worth and Cameri specifies corrosion-resistant steel hardware for carrier-based operations.
- Rotorcraft:Dynamic-load certification under CS-29 or FAR Part 29 mandates fatigue-resistant joining for main rotor hubs and transmission mounts.
- Spacecraft:Outgassing-controlled fasteners for satellite bus structures and launch vehicle payload adapters.
Commercial aviation commands the steepest expansion trajectory; military aviation retains the most stable procurement baselines.
End User:
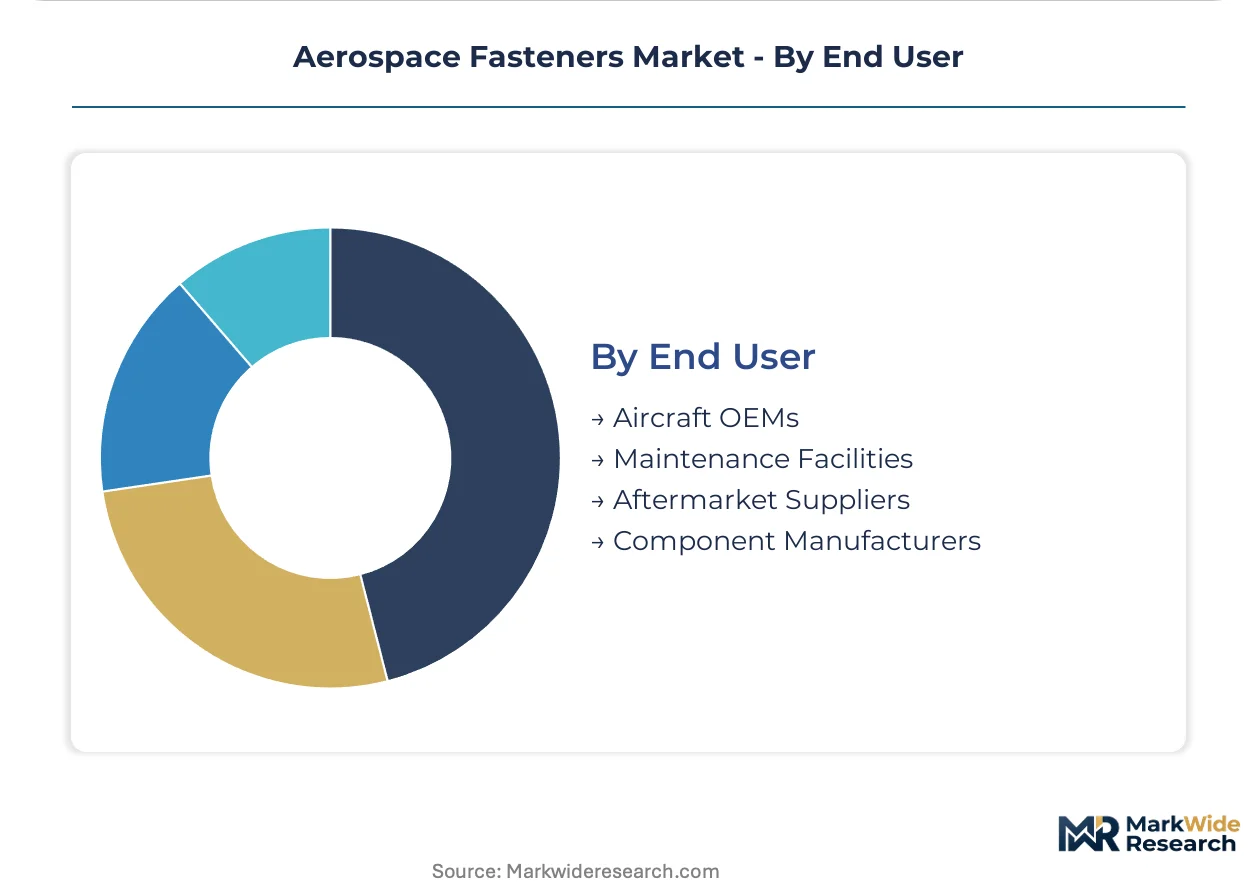
End-user categories separate design-authority holders from maintenance execution and spare-part distribution functions.
- Aircraft OEMs:Boeing, Airbus, and COMAC engineering teams specify fastener grades during structural design, embedding procurement into airframe kit agreements.
- Maintenance Facilities:AS9110-certified MRO stations in Singapore, Dubai, and Indianapolis hold buffer inventories for AOG events.
- Component Manufacturers:Tier-two suppliers producing control surfaces, landing gear, and engine nacelles procure fasteners under delegated production authority.
- Aftermarket Suppliers:PMA-certified distributors serving aging fleet retrofit demand outside OEM channel structures.
OEMs control specification authority; aftermarket suppliers are expanding most quickly as fleet age profiles deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fastener production concentrates in nations hosting final assembly lines, while consumption spreads across MRO hubs and tier-two manufacturing clusters. The United States, France, China, Germany, and Japan anchor this geography through divergent regulatory and supply-chain configurations.
United States
Boeing's Renton and Everett facilities drive titanium bolt procurement for 737 and 787 programs. FAA airworthiness directives mandate fatigue-resistant retrofits across aging narrow-body fleets. Wichita's aerostructure cluster qualifies specialty fastener suppliers for defense rotorcraft programs.
France
Airbus Toulouse and Hamburg final assembly lines source titanium blind rivets through EASA-certified supply chains. The EU Green Deal recalibrates material selection toward lightweight alloys. The Haute-Savoie region hosts precision cold-heading operations serving A320 family production.
China
COMAC C919 production ramp at Shanghai Pudong localizes fastener procurement and heat-treatment qualification. MIIT standards govern domestic aerospace-grade titanium sponge allocation. Xi'an's aviation industrial base develops indigenous superalloy fastener capabilities for engine programs.
Germany
Airbus Hamburg fuselage assembly consumes substantial threaded fastener volumes for A350 programs. KBA certification protocols align with EASA CS-25 fatigue requirements. Bavaria's precision engineering corridor supplies cold-formed components to European OEM kit agreements.
Japan
Mitsubishi Heavy Industries and Subaru coordinate fastener specifications for Boeing 787 wing production. METI industrial standards enforce material traceability through digital thread documentation. Nagoya's aerospace cluster maintains specialty heat-treatment capacity for engine-grade hardware.
Aerospace Fasteners Market Key Industry Players
The competitive structure tilts toward vertically integrated specialists with captive metallurgical capabilities. Three to five dominant players control titanium alloy supply chains through long-term offtake agreements with sponge producers. Two strategic archetypes prevail: foundry-integrated manufacturers commanding heat-treatment specifications, and precision cold-heading specialists serving narrow-body OEM kit agreements. Consolidation pressure manifests through M&A targeting AS9100-certified facilities and strategic partnerships locking titanium volumes.
Within the foundry-integrated tier, Precision Castparts Corp and Howmet Aerospace exemplify upstream control over critical specifications. LISI Aerospace occupies a position among European specialists leveraging titanium alloy expertise for narrow-body programs. These anchors represent divergent geographic and capability configurations rather than interchangeable competitors.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| B&B Specialties |
| LISI Aerospace |
| National Aerospace Fasteners Corporation |
| TriMas Corporation |
| Howmet Aerospace |
| Alcoa Fastening Systems |
| Wurth Group |
| Precision Castparts Corp |
| Others |
Cost & Logistics Intelligence
Captive metallurgical integration among foundry-integrated manufacturers anchors both supply security and premium pricing power across aerospace fastener tiers. Boeing and Airbus procurement teams negotiate long-term offtake agreements that lock titanium alloy volumes, compressing spot-market participation and elevating contract-based pricing structures.
Pricing Analysis
Margin tightening in engine-grade hardware reflects AMS 2750 pyrometry compliance costs and heat-treatment talent scarcity. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-certified suppliers from PMA distributors and uncertified imports. Price differentiation hinges on certification grade and volume scale, with narrow-body OEM kit agreements commanding least sensitivity while aftermarket spot buyers face steepest pressure.
Supply Chain Analysis
Aerospace-grade titanium sponge supply rests on Russian and Ukrainian feedstock corridors now disrupted by geopolitical compression. Cold-heading equipment and precision furnace capacity concentrate in France, Italy, and the United States. Single-source vulnerability for A320 family programs creates structural risk. Distribution runs through EASA-certified tier-one suppliers into OEM kit agreements and AS9110-certified MRO buffer inventories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold-formed titanium alloys are displacing machined steel in primary wing-to-fuselage attachments, compressing legacy hardware addressable markets and forcing qualification investments.
For Market Incumbents: To counter additive manufacturing substitution in non-critical brackets, deepen backward integration into aerospace-grade titanium sponge offtake and accelerate digital thread infrastructure for EASA CS-25 compliance. Lock multi-year narrow-body contracts before COMAC C919 localizes procurement. For New Entrants and Emerging Players: Begin with India MRO qualification in Bangalore and Hyderabad maintenance clusters, bypassing eighteen-month AS9100 certification timelines through partnership with incumbent heat-treatment facilities. Target sustainable aviation fuel compatibility testing protocols as entry wedge. For Investors and Strategic Acquirers: Exit pathways concentrate in foundry-integrated specialists with captive AMS 2750 furnace capacity and existing Boeing or Airbus kit agreement relationships. Long-term viability favors targets with digital thread documentation already operational. Watch COMAC C919 production rate acceleration as inflection signal for China supply chain localization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sponge | Secures raw material allocation against Russian and Ukrainian supply disruption. |
| Digital Thread Infrastructure Deployment | Compresses EASA CS-25 lot-release documentation from weeks to days. |
| AS9100 Certification Acceleration | Unlocks narrow-body OEM kit agreement eligibility for tier-two specialists. |
| India MRO Partnership Formation | Bypasses import dependency through indigenous narrow-body support qualification. |
| Sustainable Aviation Fuel Compatibility Testing | Captures galvanic corrosion protocol demand favoring coated titanium interfaces. |
Research Approach
Independent corroboration across fastener procurement executives at Boeing and Airbus, heat-treatment furnace operators in Haute-Savoie and Wichita, and EASA certification auditors underwrites the qualitative findings. Primary interviews with tier-two supplier engineering directors and MRO inventory planners combined with secondary validation from FAA airworthiness directive filings, EASA CS-25 amendment records, and customs trade data. Bottom-up fastener volume modeling and top-down aerospace production rate triangulation anchored segment allocations.
Comparable-period anchoring to historical narrow-body and wide-body delivery schedules established the forecast window baseline. The analysis models product type, material grade, application, and end-user dimensions across the projection horizon. CAGRs derived from production rate scaling, fleet age profile replacement cycles, and titanium alloy adoption curve penetration. Forecast inputs include COMAC C919 ramp velocity and sustainable aviation fuel aromatic content regulatory evolution.
Underlying measurement precision varies by segment; commercial aviation carries tighter precision than military rotorcraft given production transparency. Forecasts reflect assumptions on titanium sponge supply normalization and heat-treatment capacity expansion. A small set of triggers warrants ongoing watch: COMAC localization acceleration, additive manufacturing substitution rates, and EU Green Deal material specification amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
India Aerospace Coating Market
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Aerospace Fluoropolymers Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Global Aerospace and Defense Elastomers Market
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Aviation Titanium Alloy Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market