
 India Aerospace Coating Market | 2026-2036
India Aerospace Coating Market Size, Share, and Industry Trends Forecast 2026-2036
India Aerospace Coating Market Insights
A capital-intensity divergence between integrated multinationals and domestic specialists is reorganizing competitive dynamics in the India Aerospace Coating Market. PPG Industries, Inc. leverages its global formulation libraries to serve HAL and DRDO tier-1 suppliers from Indian blending facilities. High Performance Composites and Coatings Pvt. Ltd. anchors its position through proximity to Bengaluru's defense aerospace corridor. Akzo Nobel N.V. competes by sustaining certified supply relationships with Airbus and Boeing offset manufacturing partners in India.
India aerospace coatings comprise polymeric and ceramic formulations engineered to withstand thermal cycling, UV degradation, and aerodynamic erosion while meeting strict weight and outgassing parameters for flight-critical surfaces. These coatings protect aluminum, titanium, and composite substrates across exterior skins, engine nacelles, and avionics housings in both fixed-wing and rotary platforms. Exterior coatings dominate current procurement volumes as India's commercial fleet expansion and military retrofits accelerate repaint cycles. Thermal spray technology captures expanding share for engine component restoration, while powder coating remains concentrated in non-flight hardware and ground support equipment.
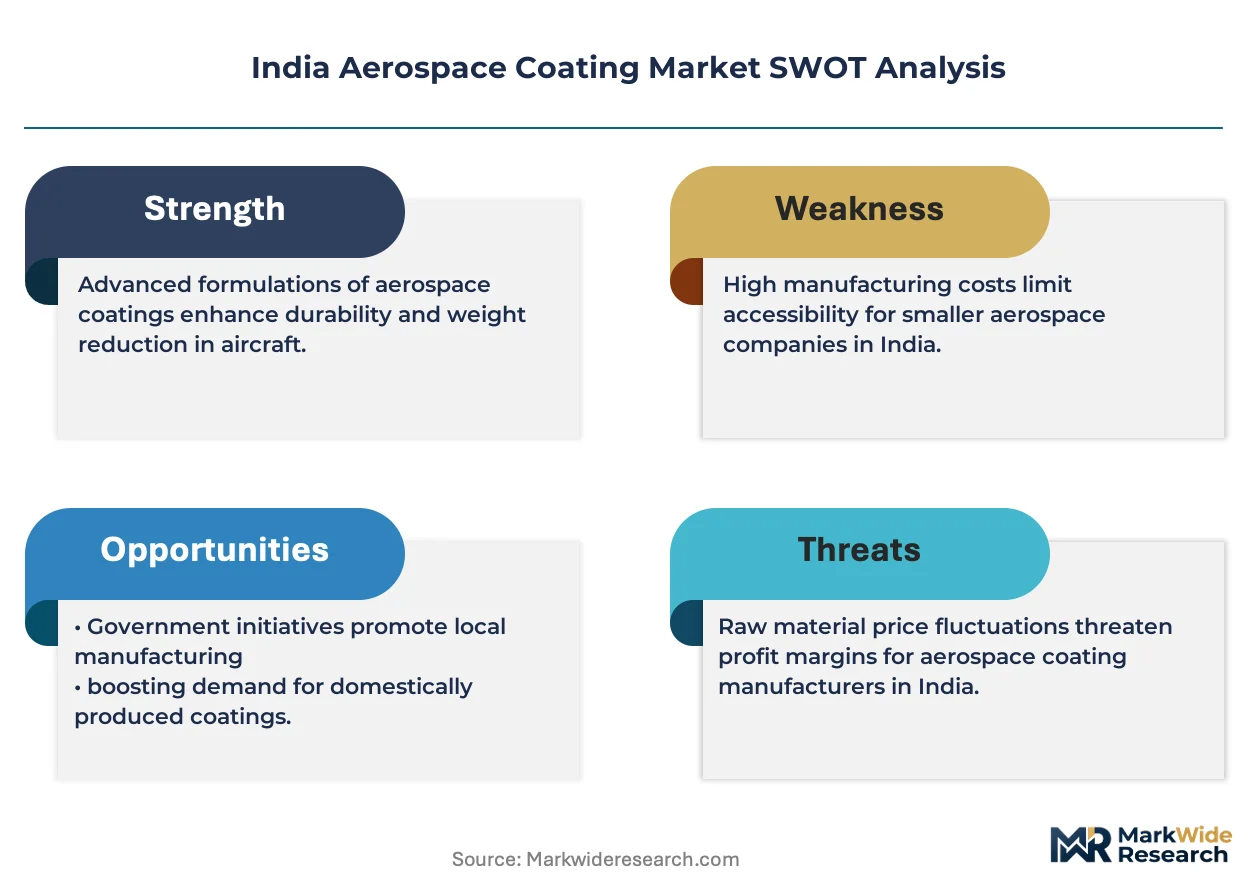
BIS standards for aerospace materials, CDSCO oversight on coating chemistries with biocidal properties, and DGFT import licensing for dual-use formulations collectively shape product registration and local sourcing obligations. The Ministry of Defence's negative import lists and PLI scheme incentives are redirecting coating procurement toward domestic-qualified suppliers. Stakeholders must monitor qualification timelines for new indigenous platforms and align certification investments with the specific airworthiness requirements of DRDO, HAL, and private defense manufacturing entrants.
Market Dynamics
The Ministry of Defence's negative import lists are forcing coating procurement toward domestic-qualified suppliers, compressing qualification timelines for DRDO and HAL platforms while redirecting supply relationships away from established import channels.
Growth Catalysts
- PLI Scheme Incentives:The Production Linked Incentive scheme for specialty chemicals subsidizes capital expenditure on aerospace-grade blending facilities, accelerating domestic formulation capacity.
- Military Fleet Modernization:Indigenization mandates under the Ministry of Defence's capital acquisition procedures are expanding repaint and original coating demand for Tejas, AMCA, and Prachand programs.
- Thermal Spray Technology:Cold spray and high-velocity oxy-fuel systems for engine component restoration are penetrating MRO operations at HAL's Koraput and Bengaluru complexes.
Market Restraints
- Import Dependency for Resins:Epoxy and polyurethane precursor supply concentrates in Chinese and German chemical manufacturers, exposing formulators to freight cost volatility and currency fluctuation.
- BIS Certification Friction:Bureau of Indian Standards aerospace material approvals require 18-24 month validation cycles, delaying product commercialization for new domestic entrants.
- Chromate Conversion Substitution:Hexavalent chromium pretreatments face phase-out pressure under REACH-aligned import scrutiny, forcing reformulation investment before qualified alternatives achieve scale.
Strategic Opportunities
- Drone Platform Surge:Unmanned aerial system manufacturing for defense and agricultural surveillance is creating coating demand for lightweight composite airframes outside traditional fixed-wing specifications.
- Private Defense Manufacturing:New entrants under the Defence Acquisition Procedure 2020 require qualified coating suppliers for offset manufacturing partnerships with Airbus and Boeing tier-1 vendors.
- Green Chemistry Transition:Waterborne and high-solids formulations aligned with DGFT sustainability notifications can capture preference in public sector tenders with environmental compliance weighting.
Industry Challenges
- NADCAP Audit Burden:Aerospace coating applicators must maintain National Aerospace and Defense Contractors Accreditation Program certification for chemical processing, requiring specialized metallurgical laboratory investment and trained inspection personnel.
- Formulation-Species Matching:Each indigenous platform—LCA Mk2, TEDBF, IMRH—demands substrate-specific qualification cycles that fragment production runs and compress batch economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Aerospace Coating Market |
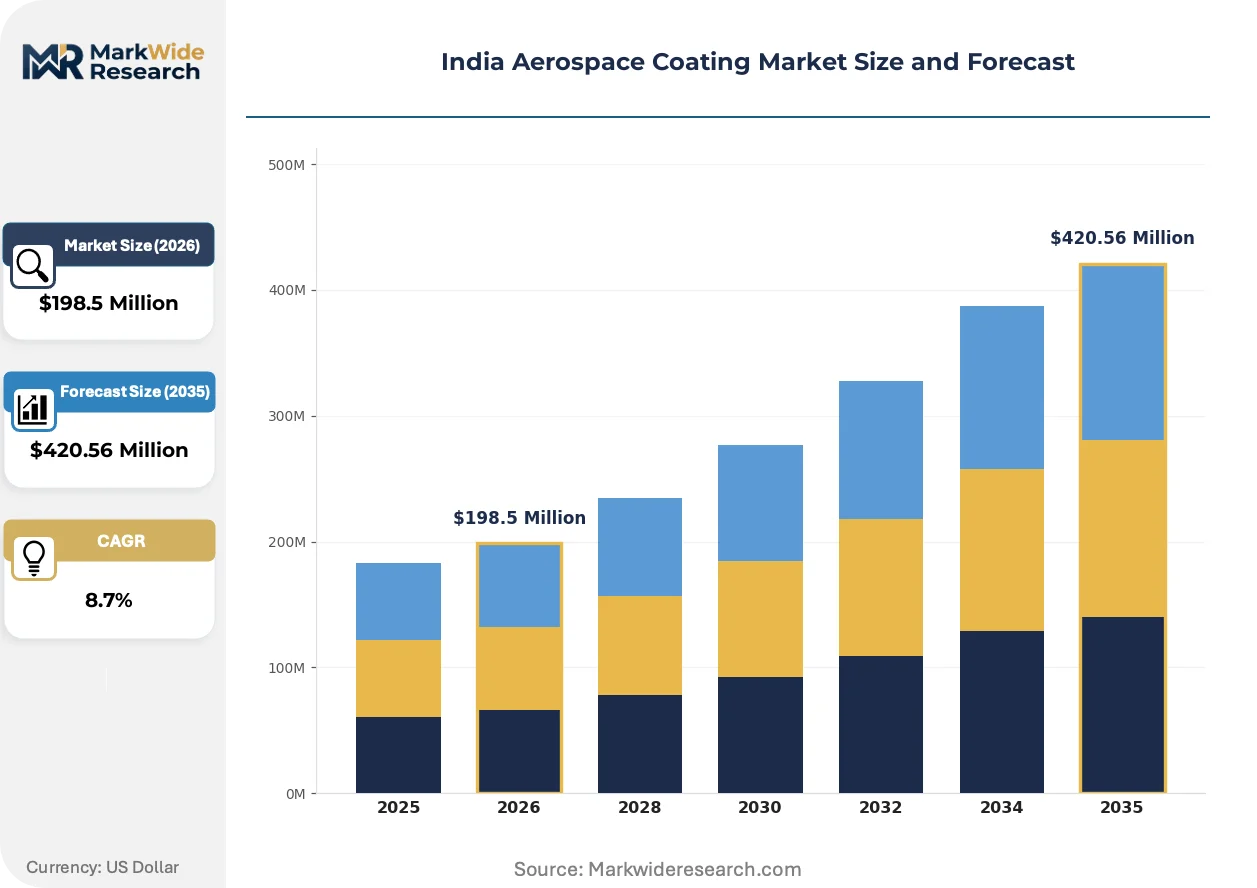
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $420.56 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Exterior Coatings, Interior Coatings, Component Coatings, Specialty Coatings Application: Commercial Aircraft, Military Aircraft, Helicopters, Spacecraft End User: Aerospace Manufacturers, Maintenance Repair Overhaul (MRO), Defense Contractors, Airlines Technology: Electrostatic Spray, Powder Coating, Liquid Coating, Thermal Spray |
| Companies Covered | PPG Industries, Inc., Akzo Nobel N.V., The Sherwin-Williams Company, BASF SE, Henkel AG & Co. KGaA, Hentzen Coatings, Inc., Mankiewicz Gebr. & Co., IHI Ionbond AG, High Performance Composites and Coatings Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Aerospace Coating Market Trends and Innovations
Coating technology trajectories in Indian aerospace are diverging between legacy solvent-borne systems and advanced functional layers, with regulatory pressure and platform-specific performance requirements fragmenting standardization efforts.
Ceramic matrix composite coatings for hypersonic leading edges and engine hot sections are fragmenting the traditional polymeric dominance in exterior protection. DRDO's Hypersonic Technology Demonstrator Vehicle and associated programs are pulling demand toward alumina-zirconia and yttria-stabilized zirconia thermal barrier formulations. Domestic plasma spray capability at IISc Bengaluru and GTRE is enabling in-house qualification, reducing reliance on foreign MRO providers for engine restoration.
BIS notification of aerospace material standards under the Compulsory Registration Scheme is tightening heavy metals and VOC thresholds for imported formulations. CDSCO oversight of biocidal additives in anti-fouling primers is adding registration layers for marine-crossover products. Formulators are responding by segregating India-specific SKUs with simplified chemistries to accelerate compliance clearance.
HAL and private defense OEMs are consolidating vendor lists around qualified applicators with captive laboratory testing, displacing spot-market coating procurement. Approved vendor status now requires demonstration of spectrographic analysis, salt spray testing, and pull-off adhesion verification. This concentration is most visible in the Nagpur-Pune corridor, where integrated MRO facilities are absorbing previously distributed surface treatment functions.
India Aerospace Coating Market Segmentation
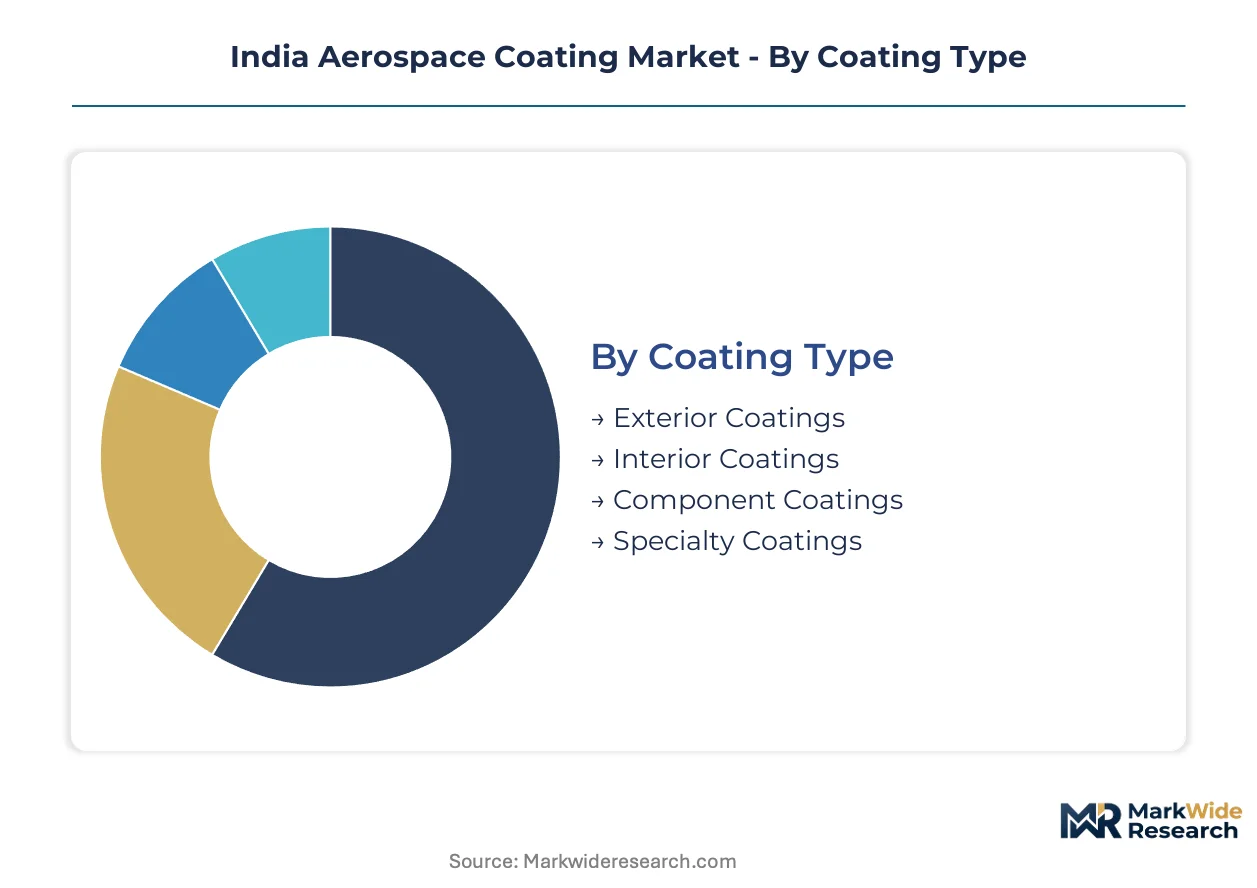
Coating specifications diverge sharply across India's aerospace value chain, with BIS certification requirements and platform-specific airworthiness mandates fragmenting procurement into technically distinct supply channels. Each segment carries unique qualification burdens that reshape vendor economics and customer relationships.
Coating Type:
BIS aerospace material standards apply differential VOC and heavy metals thresholds across coating chemistries, forcing formulators to maintain India-specific SKUs with simplified compositions.
- Exterior Coatings:Polyurethane and fluoropolymer formulations engineered for UV degradation resistance, aerodynamic erosion protection, and thermal cycling endurance on aluminum and composite skins. Demand concentrates at HAL's Bengaluru and Koraput facilities for Tejas and Prachand repaint cycles, with Maharashtra's MRO cluster absorbing commercial fleet maintenance volumes. BIS notification timelines for new exterior chemistries extend qualification cycles for reformulated chromate-free primers.
- Component Coatings:Epoxy and ceramic formulations protecting engine nacelles, landing gear, and avionics housings from corrosion and heat exposure. DRDO's Hypersonic Technology Demonstrator Vehicle program is pulling demand toward alumina-zirconia thermal barrier layers at GTRE and IISc Bengaluru plasma spray facilities.
- Interior Coatings:Low-outgassing polymeric systems for cabin surfaces, galleys, and lavatories meeting fire-smoke-toxicity standards. Airlines operating from Delhi and Mumbai hubs drive specification adherence for retrofit programs.
- Specialty Coatings:Radar-absorbent and infrared-suppressive formulations for military platform signature management. Defense procurement under negative import lists restricts qualified supplier pools to DRDO-cleared domestic blenders.
Established volume favors Exterior Coatings; emerging adoption favors Component Coatings.
Application:
Platform-specific substrate demands fragment coating specifications across India's indigenous manufacturing programs.
- Commercial Aircraft:Polymeric exterior and interior systems for aluminum airframes operated by domestic carriers. Airbus and Boeing offset manufacturing partnerships in Maharashtra concentrate specification authority with tier-1 vendors.
- Military Aircraft:Multi-layer coating stacks for Tejas, AMCA, and TEDBF programs combining corrosion protection with signature management. HAL's indigenization mandates compress qualification timelines for new domestic suppliers.
- Helicopters:Rotary-wing specific erosion-resistant leading edge coatings and anti-fouling treatments. IMRH program development at HAL's Bengaluru complex drives formulation testing for composite rotor blade protection.
- Spacecraft:Thermal control and atomic oxygen-resistant coatings for satellite bus structures and launch vehicle stages. ISRO's vendor qualification protocols impose extended validation cycles on domestic formulators.
Defense procurement volumes dominate current coating demand; commercial fleet expansion offers steepest expansion trajectory.
End User:
Customer type determines certification depth and supply relationship structure across India's aerospace coating procurement.
- Aerospace Manufacturers:Original equipment coating application for HAL, private defense OEMs, and tier-1 suppliers to Airbus-Boeing offset programs. PLI scheme subsidies for specialty chemicals accelerate capital deployment at domestic blending facilities.
- Maintenance Repair Overhaul (MRO):Repaint and component restoration services concentrated in Maharashtra's Nagpur-Pune corridor. NADCAP certification requirements for chemical processing elevate barrier to entry for applicator facilities.
- Defense Contractors:Coating procurement for DRDO laboratories and private sector partners under Defence Acquisition Procedure 2020 offset obligations. Negative import lists redirect sourcing toward BIS-qualified domestic formulators.
- Airlines:Fleet maintenance and livery repaint contracts specifying OEM-approved coating systems. Indigo and Air India procurement frameworks favor suppliers with captive laboratory testing capabilities.
Manufacturer relationships capture premium pricing; MRO channels gain share through fleet expansion.
Technology:
Application method selection trades capital intensity against performance requirements and substrate compatibility.
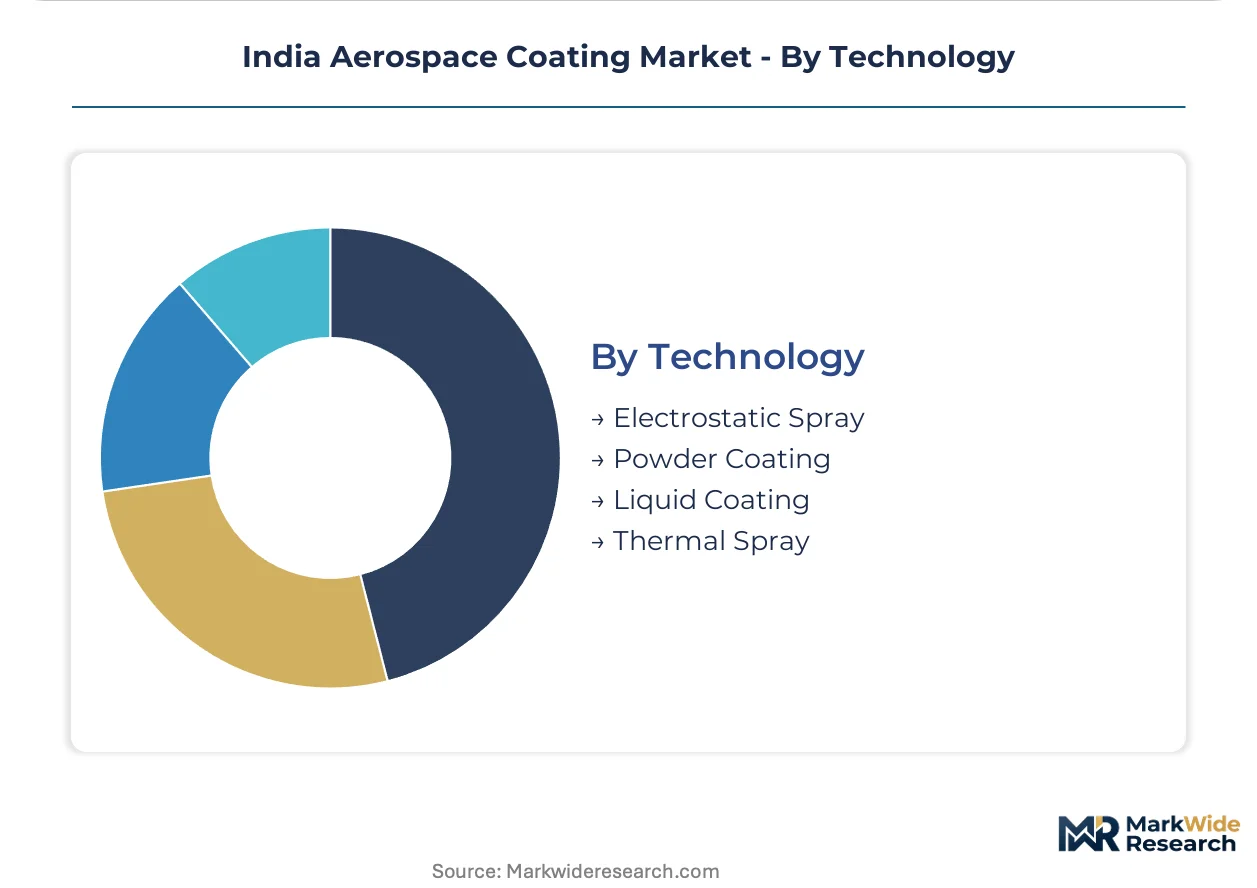
- Thermal Spray:Plasma spray and high-velocity oxy-fuel deposition of ceramic and metallic coatings for engine hot section restoration. HAL's Koraput and Bengaluru complexes are absorbing previously foreign-sourced MRO capacity for turbine blade repair.
- Liquid Coating:Solvent-borne and waterborne spray application for exterior skins and large structural components. BIS VOC thresholds are accelerating reformulation investment toward high-solids and waterborne alternatives.
- Electrostatic Spray:Charged particle deposition for uniform film build on complex geometries. Precision component manufacturers in Bengaluru's defense corridor favor this method for avionics housing finishing.
- Powder Coating:Thermoset polymer application for non-flight hardware, ground support equipment, and interior fixtures. Lower regulatory burden attracts smaller domestic applicators serving tier-2 and tier-3 suppliers.
Capital-intensive thermal spray claims engine MRO value; liquid coating retains structural application dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Indian aerospace coatings diverge sharply between defense-centric southern corridors and commercial aviation hubs in the west, with each geography driving distinct specification demands and procurement channels.
Maharashtra
Maharashtra's Nagpur-Pune aerospace corridor concentrates India's commercial MRO coating demand through integrated facilities serving Airbus and Boeing offset manufacturing. The state's PLI scheme subsidies for specialty chemicals accelerate capital deployment at domestic blending operations. Mumbai's airline headquarters drive specification authority for fleet repaint contracts, favoring suppliers with captive laboratory testing capabilities.
Karnataka
Karnataka anchors defense aerospace coating procurement through HAL's Bengaluru complex and DRDO laboratories developing indigenous platforms. BIS certification requirements for aerospace materials impose 18-24 month validation cycles on new domestic entrants. The state's plasma spray capability at IISc Bengaluru and GTRE enables in-house engine component restoration, reducing foreign MRO dependency.
Telangana
Telangana's emerging defense manufacturing ecosystem under the Defence Acquisition Procedure 2020 creates coating demand for private sector offset partnerships. The state's industrial policy incentives attract tier-1 suppliers seeking proximity to DRDO research facilities. Hyderabad's aerospace park concentrates precision component manufacturers requiring electrostatic spray application for avionics housings.
Gujarat
Gujarat's chemical manufacturing base supplies epoxy and polyurethane precursors to domestic formulators, though import dependency on Chinese and German resin suppliers persists. The state's port infrastructure facilitates DGFT-licensed import of dual-use coating formulations. Mundra and Hazira industrial zones host ground support equipment manufacturers utilizing powder coating for non-flight hardware.
Tamil Nadu
Tamil Nadu's aerospace component manufacturing cluster around Chennai serves both commercial and defense supply chains with differentiated coating specifications. CDSCO oversight of biocidal additives in anti-fouling primers adds registration layers for marine-crossover products. Sriperumbudur's electronics manufacturing corridor generates demand for low-outgassing interior coatings meeting fire-smoke-toxicity standards.
India Aerospace Coating Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with global multinationals leveraging formulation libraries against domestic players competing on proximity and qualification speed. The market structure reflects capital-intensity divergence between integrated blending facilities and application-focused service providers. Three archetypes dominate: global coating majors with certified supply relationships, domestic specialists anchored to defense corridors, and regional applicators serving tier-2 manufacturing. Competitive moves concentrate on qualification timeline compression and captive laboratory investment to secure approved vendor status.
Among global coating majors, PPG Industries, Inc. and Akzo Nobel N.V. occupy positions exemplifying the integrated multinational archetype, serving HAL and DRDO tier-1 suppliers through established certification frameworks. High Performance Composites and Coatings Pvt. Ltd. represents the domestic specialist tier, anchoring competitive positioning through proximity to Bengaluru's defense aerospace corridor and alignment with Ministry of Defence indigenization mandates.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| The Sherwin-Williams Company |
| BASF SE |
| Henkel AG & Co. KGaA |
| Hentzen Coatings, Inc. |
| Mankiewicz Gebr. & Co. |
| IHI Ionbond AG |
| High Performance Composites and Coatings Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at HAL's Bengaluru and Koraput blending facilities shapes both supply concentration and price floors for domestic aerospace coatings. The Ministry of Defence's negative import lists compress qualification timelines while redirecting procurement toward BIS-certified domestic formulators, tightening vendor pools and elevating entry barriers.
Pricing Analysis
After-sales service contracts and MRO repaint cycles drive lifetime value for qualified coating suppliers. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and captive laboratory capability. Cost compression in standard-grade exterior coatings intensifies because BIS notification timelines extend validation cycles for chromate-free reformulations. Airlines and tier-2 component manufacturers exhibit highest price sensitivity; defense contractors under indigenization mandates accept premium pricing for DRDO-cleared domestic blenders.
Supply Chain Analysis
Inventory lead times for epoxy and polyurethane precursors stretch 12-16 weeks due to concentration in Chinese and German chemical manufacturers. Domestic formulators draw from imported resin supply while maintaining India-specific SKUs with simplified chemistries to accelerate BIS compliance clearance. Single-source vulnerability concentrates in specialty ceramic feedstocks for thermal barrier formulations. Distribution runs through approved vendor lists at HAL, DRDO laboratories, and integrated MRO facilities in Maharashtra's Nagpur-Pune corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery tied to military fleet modernization under the Ministry of Defence's capital acquisition procedures. The indigenization push for Tejas, AMCA, and Prachand programs creates recurring coating demand through original application and repaint cycles.
For Market Incumbents: Shield formulation libraries against margin erosion by securing NADCAP certification for captive metallurgical laboratories. Deepen backward integration into epoxy and polyurethane precursor supply through partnerships with Gujarat's chemical manufacturing base. Chromate conversion substitution pressure under REACH-aligned import scrutiny threatens incumbent reformulation investment timelines. For New Entrants and Emerging Players: Anchor in drone platform coating demand outside traditional fixed-wing specifications, where unmanned aerial system manufacturing for defense and agricultural surveillance creates white-space opportunity. Target private defense manufacturing entrants under Defence Acquisition Procedure 2020 offset obligations. Accelerate BIS qualification through simplified waterborne formulations aligned with DGFT sustainability notifications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated applicators with captive laboratory testing and approved vendor status at HAL. Five-to-ten year viability favors domestic specialists with demonstrated DRDO platform qualification. Monitor PLI scheme subsidy disbursement timelines as inflection indicator for domestic formulation capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Gujarat chemical manufacturers reduce import dependency for epoxy and polyurethane precursors. |
| NADCAP Certification Investment | Specialized metallurgical laboratories secure approved vendor status at HAL MRO complexes. |
| Green Chemistry Transition | Waterborne formulations capture preference in DGFT-weighted public sector tenders. |
| Drone Platform Qualification | Lightweight composite airframe coatings address defense and agricultural surveillance demand. |
| Thermal Spray Capability Buildout | Plasma spray facilities at IISc Bengaluru and GTRE reduce foreign engine MRO dependency. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of BIS aerospace material notifications, DGFT import licensing records, and Ministry of Defence procurement disclosures. Primary interviews engaged coating formulators, HAL procurement officers, DRDO laboratory directors, and MRO facility managers across Maharashtra and Karnataka. Secondary validation drew from CDSCO biocidal additive registrations, PLI scheme administrative data, and customs records for dual-use formulation imports. Bottom-up demand modeling triangulated against top-down capacity assessments at domestic blending facilities.
Segmentation dimensions modeled include coating type, application platform, end-user category, and technology method across the analysis window. CAGRs derived from platform-specific procurement timelines for indigenous aircraft programs and commercial fleet expansion assumptions. Industry-specific inputs incorporated BIS certification cycle durations, NADCAP audit frequency requirements, and thermal spray technology penetration rates at HAL complexes.
Decision-makers should treat outputs as directional under assumptions of sustained Ministry of Defence indigenization policy and stable BIS regulatory frameworks; material deviation in PLI scheme continuity or REACH-aligned import restrictions would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Magnesium Beryllium Alloy Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Aerospace Titanium Market
Aerospace and Aircraft Materials
Global Aerospace Insulation Market
Aerospace and Aircraft Materials
Supersonic Wind Tunnel Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Global Composite Materials Aluminum Alloys Aerospace Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Europe Advanced Aerospace Coatings Market
Aerospace and Aircraft Materials
Aerospace Fluoropolymers Market
Aerospace and Aircraft Materials
Radiation Shielding Market