
 Commercial Aircraft Materials Market | 2026-2036
Commercial Aircraft Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Materials Market Outlook
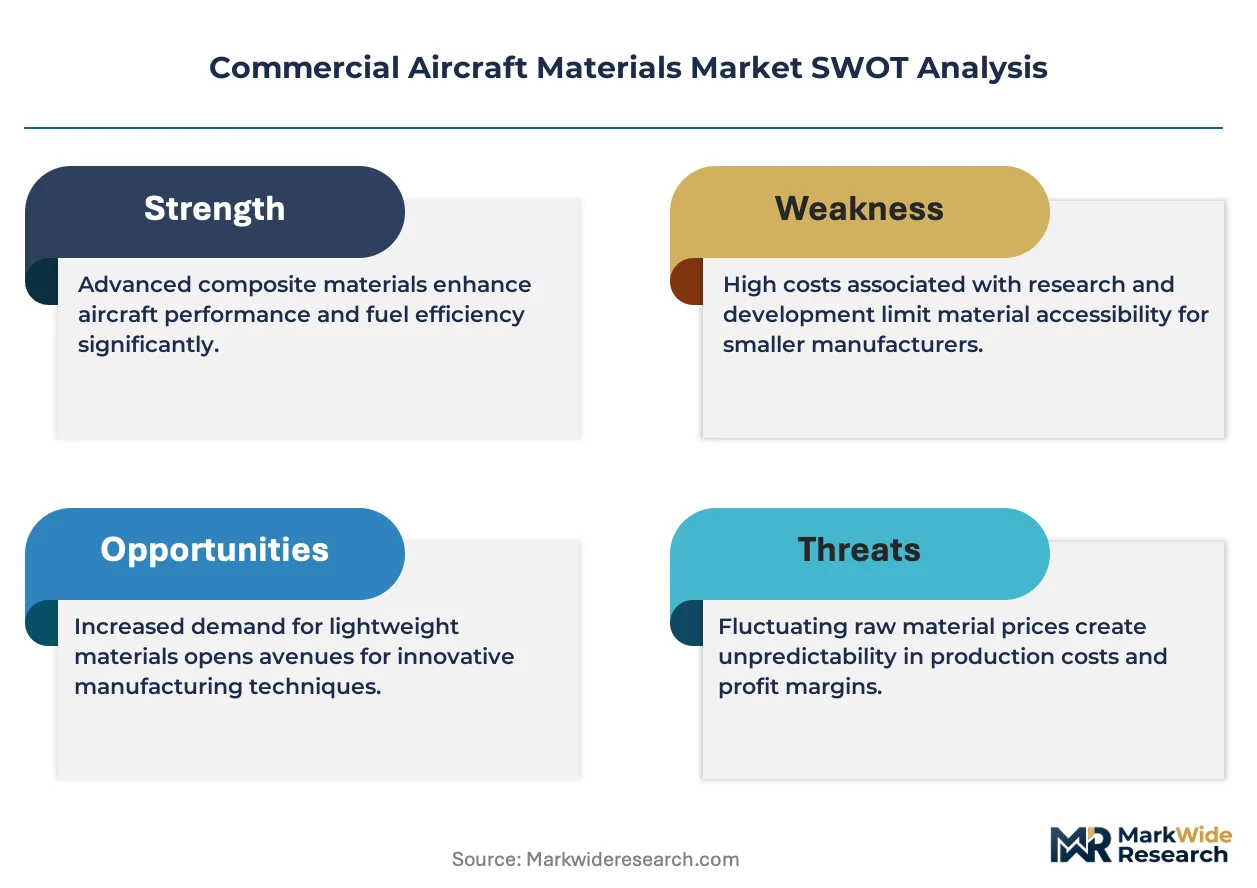
EU Green Deal aviation targets is hardening demand for lightweight, low-carbon-footprint materials across European supply chains. Hexcel Corporation leverages its carbon fiber prepreg leadership to sustain positions in next-generation wing programs. Toray Industries anchors Japanese-to-European material flows through dedicated aerospace resin capacity. Solvay S.A. differentiates via thermoplastic composite formulations that compete with traditional thermoset dominance in fuselage applications.
Commercial aircraft materials encompass engineered metals, polymers, and ceramic-matrix systems specified by tensile strength-to-weight ratios, fatigue resistance thresholds, and flame-smoke-toxicity compliance metrics, serving the structural and propulsion needs of fixed-wing passenger and cargo platforms. Aluminum alloys retain volume leadership in single-aisle airframes due to established forming infrastructure and repair protocols, while carbon fiber reinforced polymers represent the fastest-expanding category as OEMs redesign wings and empennage for fuel efficiency gains. Titanium alloys command concentrated margin pools in engine rotating components and landing gear forgings where heat resistance and specific strength justify premium positioning against steel alternatives.
FAA airworthiness directives and EASA certification specifications govern material qualification timelines, with AS9100 quality management mandates filtering market access for Tier-2 and Tier-3 suppliers seeking OEM approval. REACH chemical registration in Europe and evolving EPA emissions benchmarks in the United States are reshaping resin chemistry roadmaps and recycling obligations for composite waste streams. Stakeholders must monitor regulatory divergence between jurisdictions and pre-position qualification data packages before platform design freeze gates.
Market Dynamics
Fuel efficiency mandates from FAA and EASA are compressing material qualification timelines, forcing OEMs to pre-certify composites and titanium alloys before platform design freezes lock specifications.
Growth Catalysts
- EU Green Deal aviation targets:Binding carbon reduction deadlines are accelerating lightweight material substitution in European narrow-body programs. REACH chemical registration is tightening resin chemistry roadmaps.
- Titanium alloys:Heat resistance and specific strength advantages are expanding procurement in engine rotating components and landing gear forgings against steel alternatives.
- United States:Domestic OEM supply chains and defense aerospace clusters in Washington and Texas are anchoring composite and titanium consumption volumes.
Market Restraints
- Carbon fiber feedstock concentration:Precursor supply chains cluster in Japan and the United States, exposing Tier-2 suppliers to input cost volatility and allocation constraints.
- AS9100 certification barriers:Quality management mandates filter market access for Tier-2 and Tier-3 suppliers seeking Boeing and Airbus approval, extending qualification timelines.
- Aluminum alloy substitution resistance:Established forming infrastructure and repair protocols in single-aisle airframes slow carbon fiber reinforced polymer penetration in fuselage applications.
Strategic Opportunities
- India:PLI scheme incentives for aerospace manufacturing are drawing material suppliers to establish local prepreg and titanium processing capacity.
- Thermoplastic composites:Solvay S.A. formulations are competing with thermoset dominance in fuselage applications, enabling faster cycle times and weldability.
- Recycling infrastructure:Evolving EPA emissions benchmarks and REACH obligations are creating service revenue streams for composite waste stream recovery and resin chemistry redesign.
Industry Challenges
- Fatigue modeling expertise:Shortages of engineers proficient in composite damage tolerance analysis are delaying certification submissions to FAA and EASA.
- Autoclave capacity constraints:Capital intensity of out-of-autoclave and press-forming equipment upgrades is straining mid-tier suppliers during narrow-body production ramp.
- Platform design freeze synchronization:Material qualification data packages must pre-position before Boeing and Airbus lock specifications, compressing R&D-to-production handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Materials Market |
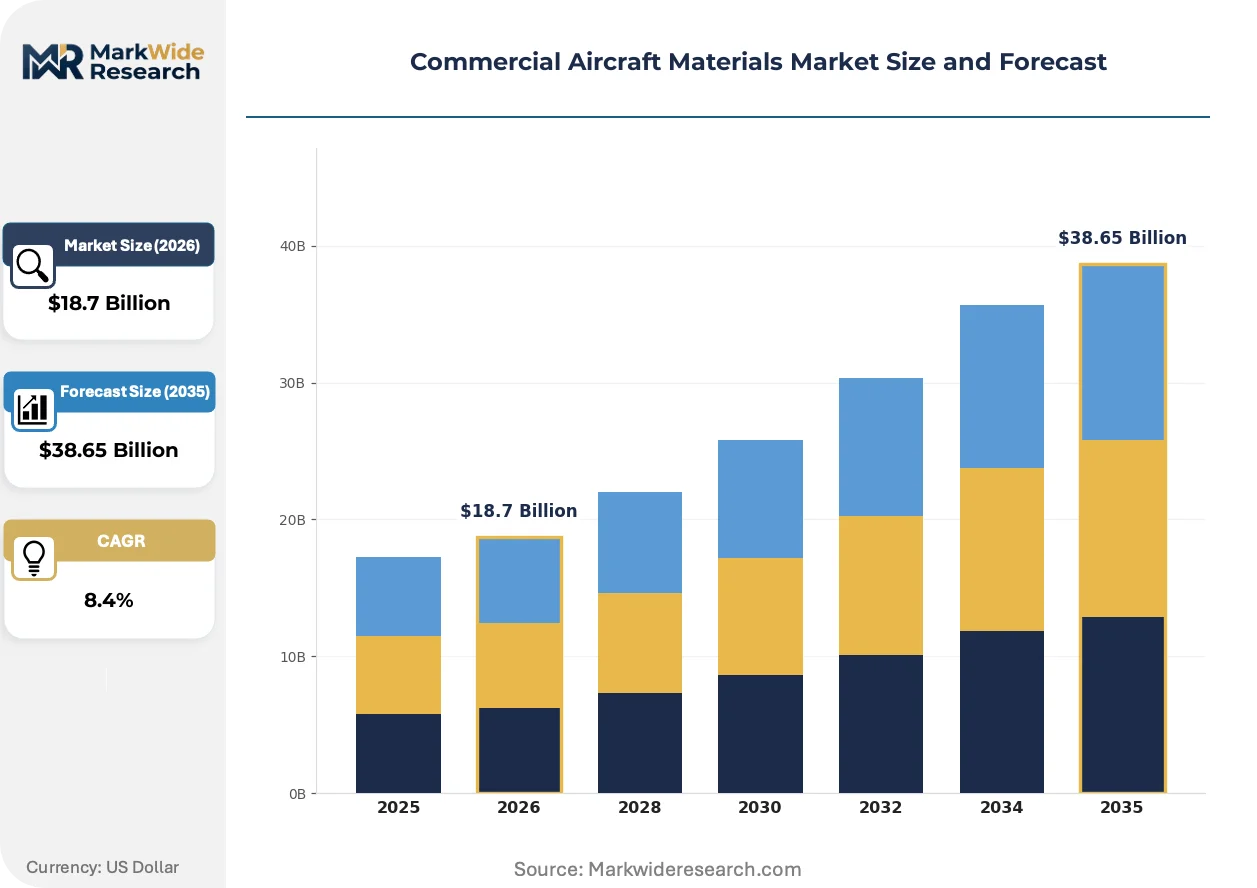
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Composite, Steel, Titanium Application: Airframe, Wing, Fuselage, Engine End User: OEMs, MRO, Airlines, Tier-1 Suppliers Certification: FAA, EASA, AS9100, ISO 9001 |
| Companies Covered | Hexcel Corporation, Toray Industries, Inc., Solvay S.A., Constellium SE, Arconic Corporation, Teijin Limited, Alcoa Corporation, VSMPO-AVISMA Corporation, DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Materials Market Strategic Shifts
Material science roadmaps are converging on thermoplastic formulations and out-of-autoclave processing to break cost and cycle-time barriers that have constrained composite penetration.
Thermoplastic composite formulations are consolidating their position in next-generation wing and fuselage programs. Airbus A350 and Boeing 787 successor platforms are specifying PEEK and PPS matrices for damage tolerance and weldability advantages. This consolidation is compressing the supplier base around resin systems capable of meeting flame-smoke-toxicity compliance without autoclave curing.
REACH chemical registration in Europe is forcing reformulation of epoxy resin systems and hardeners. ECHA substance of very high concern listings are disqualifying legacy bisphenol and amine chemistries from new platform qualifications. European Tier-1 suppliers are responding with bio-based precursor development and closed-loop recycling partnerships to secure feedstock continuity.
Airline fleet planners are compressing material specification cycles by bundling long-term procurement with MRO service agreements. Lessors and flag carriers are shifting from spot purchasing to performance-based material supply contracts covering airframe life cycles. This pattern is most visible in United States and Middle East markets where lessor concentration drives standardization across operator fleets.
Commercial Aircraft Materials Market Segmentation
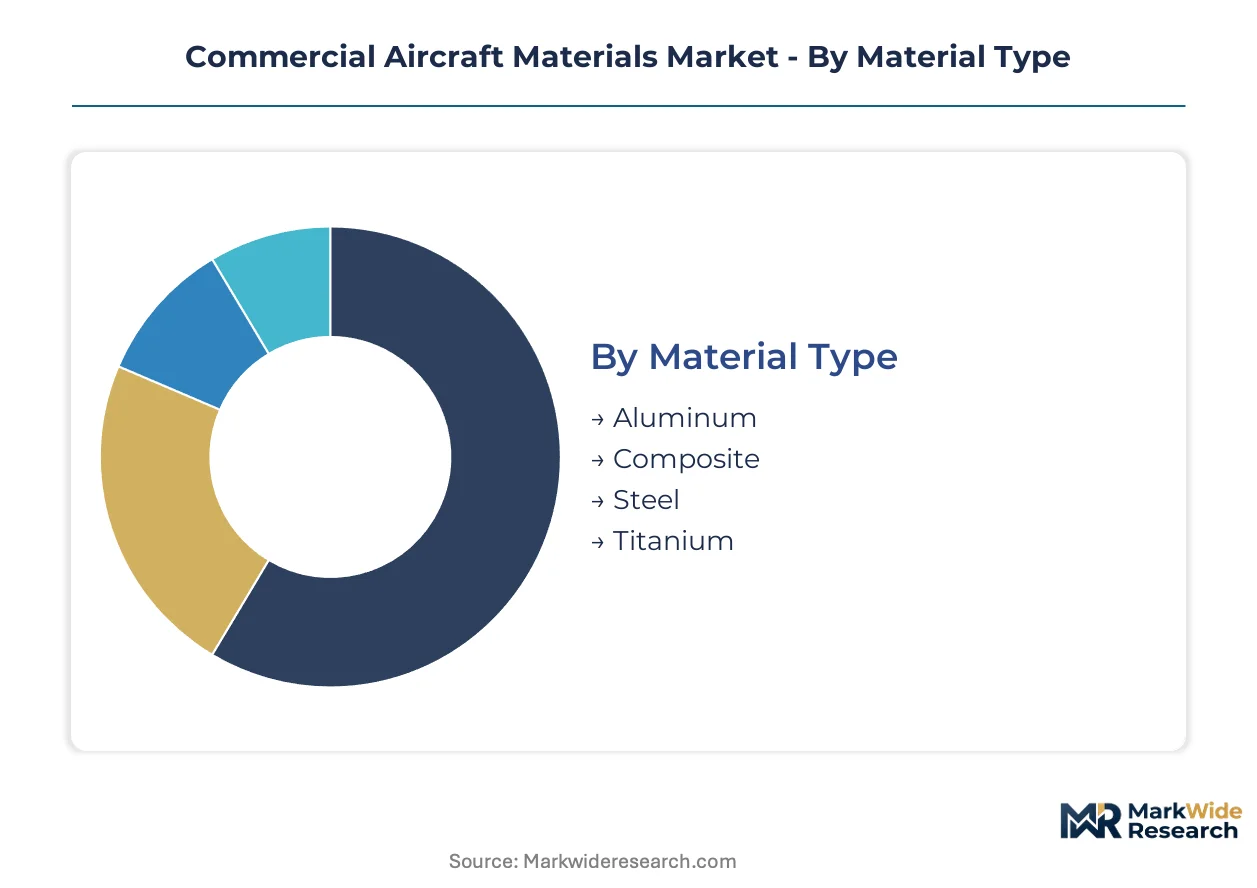
Material selection in commercial aviation follows platform-specific load paths and regulatory qualification timelines. Segmentation reveals where procurement budgets concentrate across structural applications and which certification pathways govern supplier access.
Material Type:
Replacement cycles for aging narrow-body fleets are accelerating demand for lighter, more durable alloys and polymers that reduce fuel burn across operational lifespans.
- Aluminum:Established 2xxx and 7xxx series alloys dominate single-aisle fuselage skins and stringers due to mature forming infrastructure and repair protocols. Boeing 737 MAX and Airbus A320neo programs in the United States and France sustain volume procurement despite composite encroachment on wings.
- Composite:Carbon fiber reinforced polymers specified for wing boxes and empennage structures deliver specific strength advantages that justify qualification costs. Airbus A350 and Boeing 787 successor platforms in Washington state and Toulouse are expanding thermoset and thermoplastic resin procurement.
- Steel:High-strength alloys retain positions in landing gear forgings and engine fasteners where fatigue resistance thresholds exceed aluminum capabilities.
- Titanium:Ti-6Al-4V and Ti-5Al-5V-5Mo-3Cr grades command concentrated procurement for engine rotating components and critical structural joints in Texas and Ohio defense aerospace clusters.
Aluminum sits at the top of the volume ranking, with composite climbing the fastest.
Application:
Cost tier differentiation separates high-investment primary structures from replaceable secondary assemblies across OEM supply chains.
- Airframe:Longerons, frames, and bulkheads integrate multi-material architectures balancing weight reduction against damage tolerance requirements. FAA certification specifications for 25-year design life govern material qualification data packages.
- Wing:Spar caps, ribs, and skin panels represent the most aggressive composite penetration as fuel efficiency mandates drive aspect ratio increases. EASA CS-25 airworthiness standards for flutter and gust response constrain material selection freedom.
- Fuselage:Pressure vessel structures in single-aisle programs retain aluminum dominance due to established lightning strike protection and repair procedures.
- Engine:Hot section components and fan cases specify superalloys and titanium matrix composites where creep resistance and thermal fatigue thresholds dominate selection criteria.
Airframe absorbs the largest procurement dollar pool, with wing applications gaining share fastest.
End User:
Customer type determines contract structure, with OEMs locking long-term supply agreements while MRO operators drive spot market volatility for replacement materials.
- OEMs:Boeing and Airbus specify qualified material lists that freeze supplier bases years before first flight, compressing Tier-2 qualification timelines for composite prepreg and titanium billet.
- MRO:Maintenance providers in Atlanta and Singapore source certified replacement materials under AS9110 quality systems, with demand spiking during scheduled heavy checks.
- Airlines:Delta, United, and Lufthansa negotiate direct material supply contracts for in-house engineering modifications and damage repairs.
- Tier-1 Suppliers:Spirit AeroSystems and GKN Aerospace aggregate material procurement across multiple OEM programs, leveraging volume for price positioning on aluminum sheet and carbon fiber.
OEMs command the dominant procurement volume, with MRO expanding most quickly as fleet ages deepen.
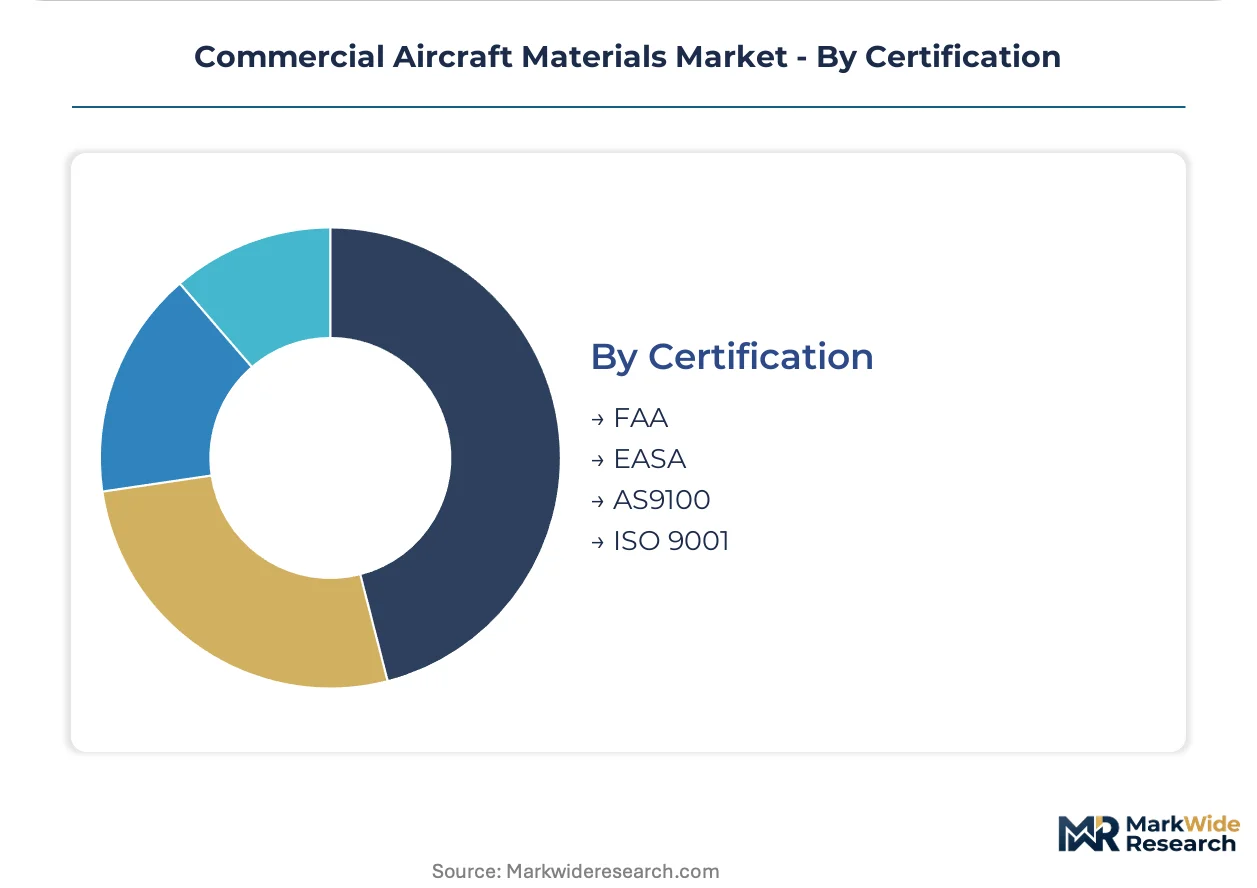
Certification:
Margin structure correlates directly with regulatory barrier height, with AS9100 and platform-specific approvals filtering supplier participation.
- FAA:Airworthiness directives and material qualification protocols under 14 CFR Part 25 govern all materials for United States-registered aircraft and Boeing production.
- EASA:Certification specifications and continued airworthiness requirements under CS-25 apply to Airbus production and European operator fleets.
- AS9100:Aerospace quality management mandates filter market access for Tier-2 and Tier-3 suppliers seeking OEM approval.
- ISO 9001:Baseline quality systems support non-flight-critical component supply and raw material processing stages.
FAA and EASA specifications represent the highest barrier tier, with AS9100 adoption spreading fastest among mid-tier processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled aerospace engineers and composite technicians concentrate in Washington state, Toulouse, and Nagoya, anchoring the industry's geographic footprint. These talent pools sustain OEM final assembly lines and Tier-1 material processing operations. Certification expertise and defense procurement further reinforce these clusters.
United States
Boeing's 737 MAX and 787 programs in Everett and Charleston drive titanium and carbon fiber procurement. FAA airworthiness directives under 14 CFR Part 25 govern material qualification timelines. Washington state's Puget Sound region hosts Hexcel Corporation prepreg facilities serving next-generation wing programs.
France
Airbus A320neo and A350 production in Toulouse accelerates demand for thermoplastic composites. EASA CS-25 certification specifications constrain material selection freedom for European-registered aircraft. The Occitanie region's aerospace valley clusters Solvay S.A. resin formulation expertise with OEM engineering centers.
Japan
Toray Industries anchors carbon fiber precursor supply chains for Boeing and Airbus programs. METI industrial policy supports aerospace material R&D through technology partnerships. Nagoya's Chubu region concentrates PAN-based precursor manufacturing with dedicated aerospace resin capacity.
United Kingdom
GKN Aerospace and Spirit AeroSystems operations in Bristol and Prestwick aggregate multi-program material procurement. UK REACH implementation post-Brexit maintains chemical registration alignment with ECHA standards. The Midlands aerospace cluster specializes in titanium forging and engine component supply.
India
PLI scheme incentives for aerospace manufacturing draw material suppliers to establish local prepreg capacity. DGFT export promotion frameworks support titanium processing investments in Gujarat and Karnataka. Hyderabad's defense aerospace cluster anchors composite and specialty alloy consumption for regional MRO expansion.
Commercial Aircraft Materials Market Competitive Environment
Capital-heavy producers compete with asset-light designers across distinct competitive tiers. Integrated resin-to-prepreg operators command premium positioning against specialized fiber or chemical suppliers. Three archetypes dominate: full-stack composite system houses, metals-focused forging and rolling specialists, and diversified chemical conglomerates with aerospace divisions. Consolidation pressure manifests through strategic partnerships for recycling infrastructure and capacity expansion in thermoplastic formulations.
Among carbon fiber system suppliers, Hexcel Corporation and Toray Industries occupy positions at opposite ends of geographic specialization. Solvay S.A. exemplifies the diversified chemical archetype competing in thermoplastic matrices. These three anchors represent distinct strategic postures: North American OEM-captive supply, Asian precursor dominance, and European resin formulation leadership.
| Leading Market Players |
|---|
| Hexcel Corporation |
| Toray Industries, Inc. |
| Solvay S.A. |
| Constellium SE |
| Arconic Corporation |
| Teijin Limited |
| Alcoa Corporation |
| VSMPO-AVISMA Corporation |
| DuPont de Nemours Inc. |
| Others |
Value Chain & Pricing Dynamics
AS9100 certification ladders bifurcate material suppliers into qualified Tier-1 incumbents and excluded commodity processors, concentrating pricing power with Hexcel Corporation and Toray Industries while compressing margins for unqualified aluminum sheet distributors. This tier divergence manifests in long-term offtake contracts for Boeing and Airbus programs versus spot-market volatility for MRO replacement materials, with supply chain configurations mirroring this split through captive prepreg facilities in Washington state and Japan versus fragmented toll-processing networks in India and Southeast Asia.
Pricing Analysis
Bundled performance-based contracts covering airframe life cycles now dominate OEM procurement, while unbundled spot purchasing persists for MRO operators during heavy check spikes. Price differentiation rests on FAA/EASA certification tier and volume scale, with AS9100-qualified suppliers commanding premiums against ISO 9001 processors. Cost compression in aluminum fuselage materials is intensifying because established forming infrastructure slows composite substitution. Tier-1 suppliers exhibit lowest price sensitivity due to design freeze synchronization requirements, while Tier-3 processors face acute margin pressure from feedstock allocation constraints.
Supply Chain Analysis
Reverse-logistics flows for carbon fiber scrap and titanium machining chips are creating secondary feedstock streams that reshape raw material economics. Geographic concentration centers on Japan for PAN-based precursors, the United States for aerospace resin systems, and Russia for titanium sponge. Raw material dependencies include acrylonitrile monomer, epoxy hardeners subject to REACH restrictions, and aerospace-grade titanium billet. Single-source vulnerability in Japanese precursor supply exposes Tier-2 suppliers to allocation rationing during narrow-body production ramps. Distribution runs through Spirit AeroSystems and GKN Aerospace as program-aggregating intermediaries between resin formulators and OEM assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as airline fleet planners bundle procurement with MRO service agreements, shifting demand toward premium thermoplastic composites and qualified titanium grades that reduce through-life fuel burn and maintenance costs.
For Market Incumbents: Lock in backward integration into carbon fiber precursor manufacturing to defend against Japanese supply allocation constraints. Secure AS9100D certification renewals ahead of Boeing 787 successor platform design freezes. Add press-forming capacity in Texas and Washington state to capture thermoplastic composite substitution away from autoclave-dependent competitors.
For New Entrants and Emerging Players: Enter via India's PLI scheme incentives for aerospace manufacturing, establishing local prepreg capacity to serve Hyderabad's defense aerospace cluster. Target MRO replacement materials as the most penetrable segment, where AS9110 quality requirements are less stringent than OEM qualification timelines. Pursue direct airline contracts with Delta and United for in-house engineering modifications, bypassing Tier-1 supplier intermediation.
For Investors and Strategic Acquirers: Consolidation pressure builds where REACH chemical registration disqualifies legacy resin formulators lacking bio-based precursor development capabilities. Five-to-ten year viability favors integrated resin-to-prepreg operators over specialized fiber or chemical suppliers. Acquisition target archetype: mid-tier thermoplastic composite specialists with EASA CS-25 qualification data packages. Monitor ECHA substance of very high concern listings as the inflection signal for forced reformulation cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Thermoplastic Composite Capacity Expansion | Solvay S.A. formulations enable faster cycle times without autoclave curing for Airbus A350 successor wings. |
| Backward Integration into Precursor Manufacturing | Toray Industries' PAN-based supply chains reduce allocation risk for Boeing 787 and 737 MAX programs. |
| AS9100D Certification Investment | Quality management mandates filter Tier-2 supplier access to Boeing and Airbus qualified material lists. |
| Recycling Infrastructure Partnership | Closed-loop carbon fiber recovery addresses EPA emissions benchmarks and REACH waste stream obligations. |
| Long-term Supply Agreement with Tier-1 Aggregators | Spirit AeroSystems bundles multi-program procurement for price positioning on aluminum and carbon fiber. |
Study Parameters
Multiple input streams — primary interviews with material procurement directors at Boeing and Airbus, technical discussions with Hexcel Corporation and Toray Industries R&D heads, and regulatory consultations with FAA certification engineers — were reconciled against secondary validation from EASA CS-25 specifications, EPA emissions benchmarks, and SEC 10-K filings from Constellium SE and Arconic Corporation. Bottom-up build-ups from platform-specific material specifications were cross-checked against top-down aerospace production forecasts. Triangulation across these sources anchored segmentation by material type, application, and certification tier.
Historical shipment data from United States, French, and Japanese aerospace clusters were cross-referenced against panel input from Tier-1 supplier procurement teams to construct demand projections across the analysis window. Segmentation dimensions modeled include material grade tier, platform application, end-user contract structure, and regional regulatory cluster. CAGRs were derived from slope analysis of qualification timeline compression and narrow-body fleet replacement cycles. Industry-specific forecast inputs encompassed Boeing 737 MAX and Airbus A320neo production ramp schedules, plus thermoplastic composite penetration rates in wing programs.
Inputs from FAA airworthiness directives and EASA certification specifications were available through the study window; gaps in proprietary OEM qualified material list data introduce uncertainty bands around supplier market share estimates. Forecasts reflect documented assumptions regarding REACH chemical registration timelines and PLI scheme incentive continuity in India. Practitioners should monitor ECHA substance of very high concern listings, Boeing 787 successor platform design freeze dates, and Japanese precursor allocation announcements for early signals of forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Aerospace Plastics Market
Aerospace and Aircraft Materials
Aerospace Materials Market
Aerospace and Aircraft Materials
Aeroengine Composites Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Global Military Aerospace Coatings Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Aerospace Additive Manufacturing Market
Aerospace and Aircraft Materials
Electromagnetic and Radio Frequency Interference Coating Market
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
3D Printing for Aerospace Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Europe Advanced Aerospace Coatings Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Radiation Shielding Market