
 North America Fuel Cell UAV Market | 2026-2036
North America Fuel Cell UAV Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fuel Cell UAV Market Insights
Canada is rewriting its clean-technology manufacturing map through federal hydrogen strategy investments that target unmanned aerial systems. Ballard Power Systems leverages its Vancouver engineering base to sustain proton-exchange-membrane stack development for defense contractors. Plug Power anchors North American hydrogen logistics by controlling liquefaction and refueling infrastructure that extends UAV sortie durations.
A fuel cell UAV converts chemical energy from hydrogen, methanol, or ammonia into electrical power through electrochemical reaction, yielding water vapor exhaust and enabling flight endurance of four to twelve hours depending on stack power density and tank configuration. The platform serves military reconnaissance, pipeline inspection, and precision agriculture where combustion engines create acoustic or thermal signatures and batteries impose weight-payload tradeoffs. Hydrogen fuel type dominates procurement budgets because it delivers the highest gravimetric energy density among available chemistries, though methanol reformer systems occupy niche roles in logistics-constrained theaters. Tactical UAV size brackets capture the fastest-growing segment as defense agencies prioritize medium-altitude platforms with multi-sensor payloads over micro-systems with limited range.
The FAA's Part 107 waiver process and emerging type-certification pathways for hydrogen-powered aircraft shape market access timelines for commercial operators. Transport Canada's evolving Remotely Piloted Aircraft Systems regulations parallel these developments, creating a dual-jurisdiction compliance landscape for cross-border service providers. Stakeholders must monitor hydrogen infrastructure build-out rates and military procurement schedule shifts to align capacity investments with actual demand pull.
Market Dynamics
The FAA's evolving Part 107 waiver framework for beyond-visual-line-of-sight operations is compressing commercial clearance timelines and redrawing competitive boundaries between defense contractors and commercial operators across the United States and Canada.
Growth Catalysts
- Beyond-Visual-Line-of-Sight Waivers:The FAA's Part 107 framework accelerates commercial deployment timelines for hydrogen-powered surveillance platforms in Texas energy corridors and California aerospace clusters.
- Canada Federal Hydrogen Strategy:Ottawa's clean-technology manufacturing investments channel capital into unmanned aerial systems development, anchoring proton-exchange-membrane stack production in Vancouver engineering bases.
- Multi-Sensor Payload Integration:Defense agencies prioritize medium-altitude tactical platforms with electro-optical, infrared, and signals-intelligence packages over range-limited micro-systems.
Market Restraints
- Liquid Hydrogen Infrastructure Gaps:Limited liquefaction and refueling station density in rural inspection corridors forces operators to truck fuel from Texas Gulf Coast production hubs, inflating logistics costs.
- Proton-Exchange-Membrane Stack Concentration:Vancouver and California engineering clusters dominate membrane electrode assembly production, creating geographic supply vulnerability for eastern defense contractors.
- Methanol Reformer Efficiency Ceiling:Reformate purification requirements impose 15-20% energy penalty versus direct hydrogen feed, constraining mission duration in logistics-constrained theaters where methanol is preferred.
Strategic Opportunities
- Canadian Arctic Surveillance:Transport Canada's Remotely Piloted Aircraft Systems regulations create first-mover advantage for hydrogen-powered platforms operating in extreme cold where battery performance degrades.
- Agricultural Multispectral Imaging:Precision agriculture operators in California Central Valley seek acoustic-signature-free crop monitoring alternatives to combustion-engine drones for pest and irrigation mapping.
- Pipeline Integrity Management Mandates:PHMSA inspection interval requirements for interstate natural gas transmission lines pull sustained demand for extended-endurance aerial platforms in Permian Basin and Appalachian corridors.
Industry Challenges
- Hydrogen Safety Certification Bottlenecks:FAA type-certification pathways for hydrogen-powered aircraft lack precedent, forcing manufacturers to navigate case-by-case special class approvals with unpredictable timeline variance.
- Cross-Border Regulatory Friction:Service providers operating between United States and Canada face dual compliance burdens under divergent FAA Part 107 and Transport Canada RPAS frameworks, complicating fleet standardization.
- Electrolyzer Technician Scarcity:Hydrogen fueling infrastructure deployment outpaces training pipeline for certified maintenance personnel, constraining operational scale-up in remote inspection corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fuel Cell UAV Market |
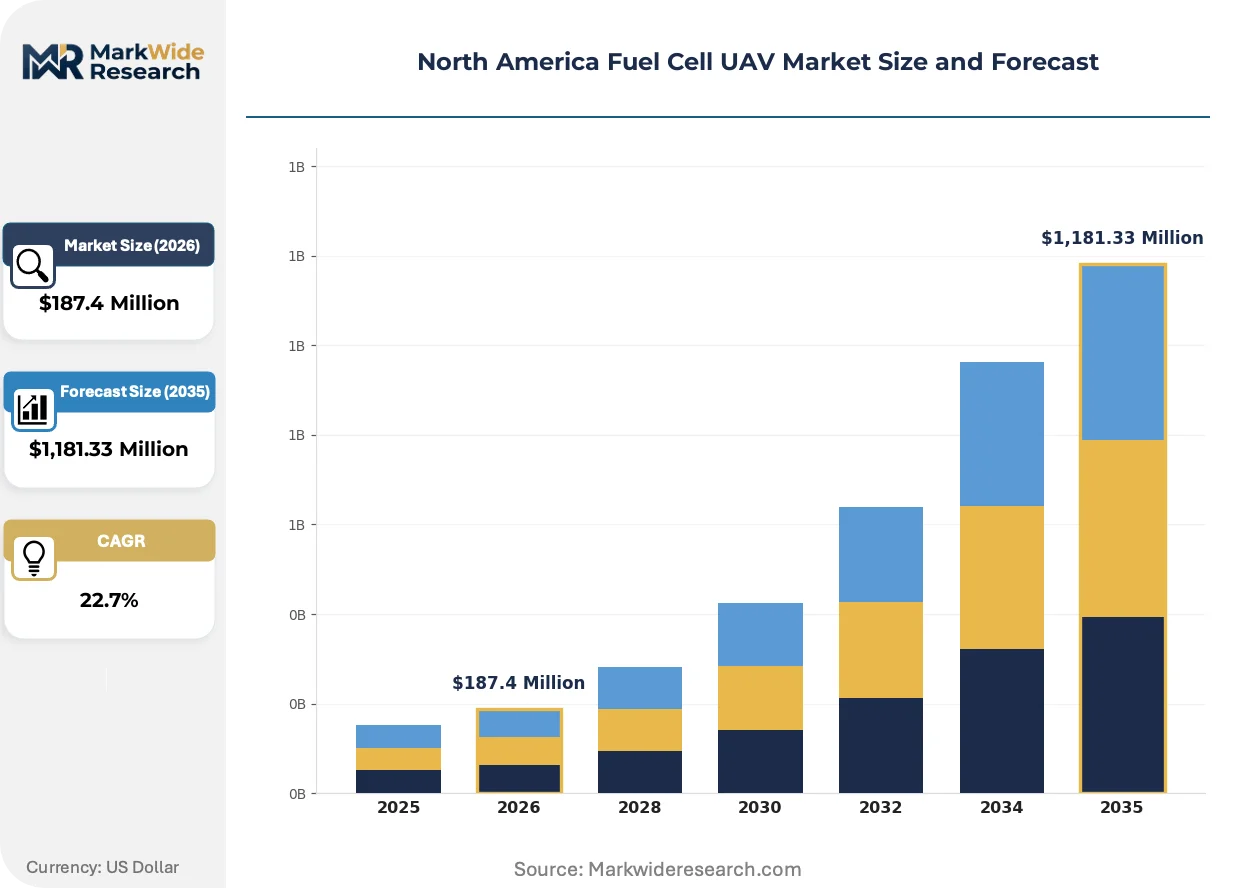
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Hydrogen, Methanol, Ammonia, Natural Gas UAV Size: Micro, Mini, Tactical, Large End User: Aerospace, Agriculture, Military, Research Application: Surveillance, Delivery, Mapping, Inspection |
| Companies Covered | Intelligent Energy, Honeywell Aerospace, Ballard Power Systems, Plug Power, AeroVironment, Inc., General Atomics, Textron Inc., Northrop Grumman Corporation, Boeing, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fuel Cell UAV Market Trends and Innovations
Solid-state hydrogen storage materials are compressing tank mass fractions and extending mission profiles, while regulatory harmonization efforts between Washington and Ottawa reshape cross-border service economics.
Metal hydride storage systems are collapsing the gravimetric efficiency gap between compressed gas and liquid hydrogen configurations. Defense contractors in California and Texas are piloting titanium-iron alloy beds that absorb hydrogen at moderate pressure, eliminating cryogenic handling requirements. This storage architecture is collapsing logistics constraints for forward-deployed military units that lack liquid hydrogen infrastructure.
The FAA's emerging type-certification pathway for hydrogen-powered aircraft under Special Class regulations is forcing manufacturers to adopt standardized tank and fuel-cell module interfaces. Transport Canada is paralleling this development through RPAS safety assurance framework updates. Medium-altitude tactical platforms bear the heaviest compliance burden, driving consolidation of stack suppliers around common form factors.
Energy majors in Texas and Alberta are unbundling hydrogen fueling from drone operations, selling kilograms at fixed-price contracts rather than bundled flight-hour rates. Pipeline inspection contractors now source fuel independently from liquefaction hubs in Houston and Edmonton, compressing operator margins but expanding fleet deployment flexibility. This procurement decoupling is most visible in Permian Basin methane monitoring contracts where fuel cost transparency has become a bidding requirement.
North America Fuel Cell UAV Market Segmentation
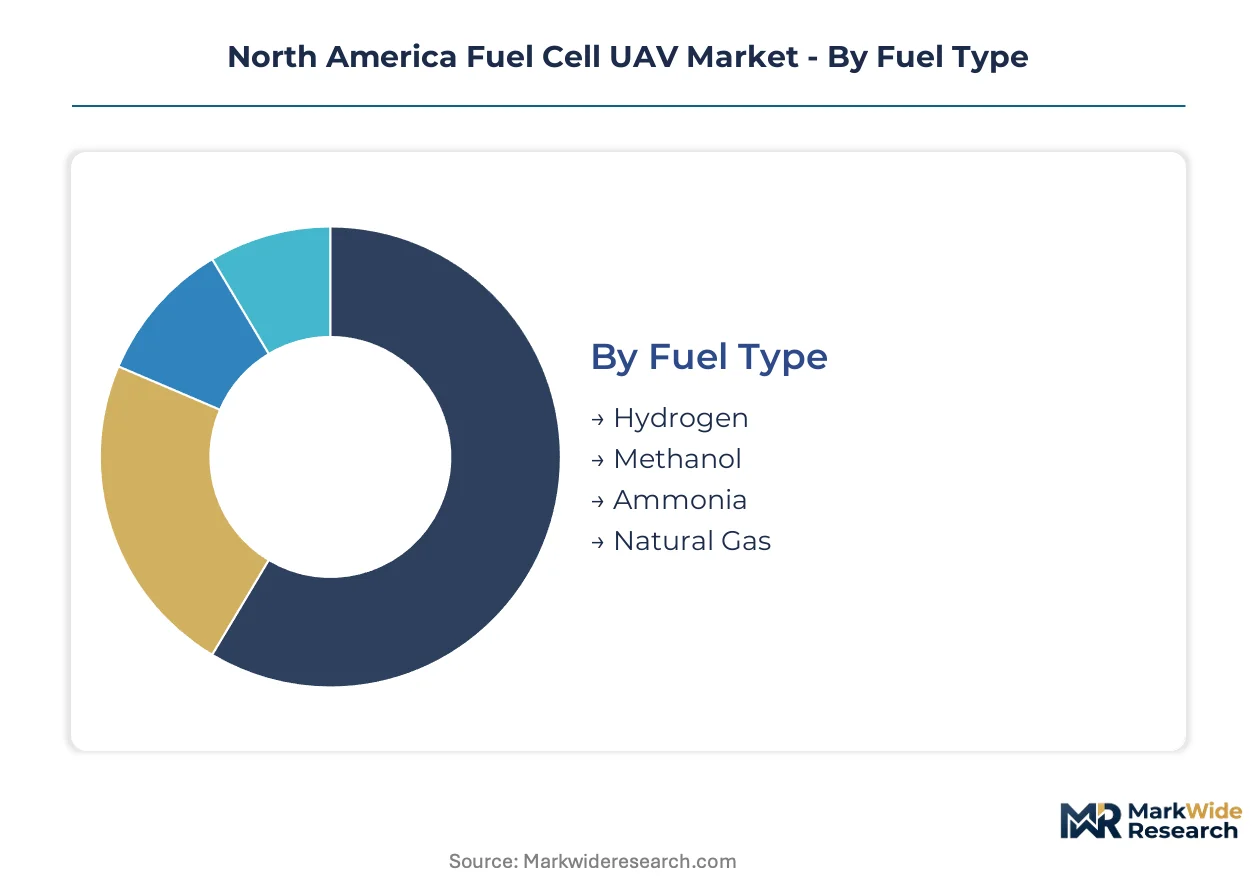
Fuel cell UAV procurement patterns diverge sharply across hydrogen logistics maturity, platform payload requirements, and regulatory clearance timelines. Understanding segment-level demand drivers enables manufacturers to align stack development roadmaps with actual deployment economics rather than speculative capability targets.
Fuel Type:
Compressed hydrogen cycles through procurement budgets fastest as defense agencies validate tank configurations, while methanol reformer systems linger in extended pilot phases due to efficiency penalties.
- Hydrogen:Direct-feed proton-exchange-membrane systems deliver gravimetric energy density of 33.3 kWh/kg, enabling four-to-twelve-hour endurance brackets. Procurement concentrates in California aerospace corridors and Texas Permian Basin inspection contracts where liquefaction infrastructure anchors supply certainty.
- Methanol:Onboard reformer architectures eliminate cryogenic handling but impose 15-20% energy conversion losses. Demand clusters in logistics-constrained military theaters where liquid fuel transport trumps hydrogen infrastructure availability.
- Ammonia:Cracking systems remain pre-commercial across North American defense and energy sectors, constrained by reactor mass penalties and unproven field reliability.
- Natural Gas:Reformer-fed solid-oxide configurations occupy niche stationary testing roles, lacking the power-to-weight ratios required for flight-weight platforms.
Hydrogen anchors the volume base while methanol gains share at the steepest rate in forward-deployed military procurement.
UAV Size:
Cost tier stratification separates payload-capable platforms from sensor-limited micro-systems, with procurement budgets scaling non-linearly across weight brackets.
- Tactical:Medium-altitude platforms spanning 55-1,320 pounds maximum takeoff weight carry multi-sensor electro-optical, infrared, and signals-intelligence payloads. Defense agencies in the United States prioritize this bracket for border surveillance and maritime patrol missions exceeding battery endurance limits.
- Large:Heavy platforms above 1,320 pounds integrate liquid hydrogen cryogenic tanks for 24-plus-hour endurance. Demand pulls from Arctic surveillance programs under Transport Canada where extreme cold degrades lithium-ion performance.
- Mini:Sub-55-pound platforms serve agricultural multispectral imaging in California Central Valley where acoustic signature suppression matters more than multi-hour endurance.
- Micro:Sub-4.4-pound platforms remain battery-dominated, with fuel cell integration costs exceeding mission value for 30-minute flight profiles.
Tactical platforms command the dominant procurement share while large systems climb the fastest in extreme-climate defense applications.
End User:
Customer type determines specification rigidity, with military contracts demanding hardened interfaces and agricultural buyers prioritizing cost-per-acre economics.
- Military:Extended-range reconnaissance and signals-intelligence missions drive stack durability requirements under MIL-STD-810 environmental stress protocols. Procurement schedules align with FAA Part 107 waiver milestones for beyond-visual-line-of-sight operations.
- Agriculture:Precision crop monitoring in California and Texas seeks acoustic-signature-free alternatives to combustion-engine drones for pest detection and irrigation mapping.
- Aerospace:Research institutions and commercial operators test hydrogen certification pathways under FAA Special Class regulations, absorbing timeline uncertainty for first-mover positioning.
- Research:University and national laboratory programs validate metal hydride storage architectures and solid-state hydrogen materials, bridging basic science toward fieldable systems.
Military contracts anchor the revenue base while agriculture expands most quickly as fuel cost transparency becomes standard in California Central Valley bidding.
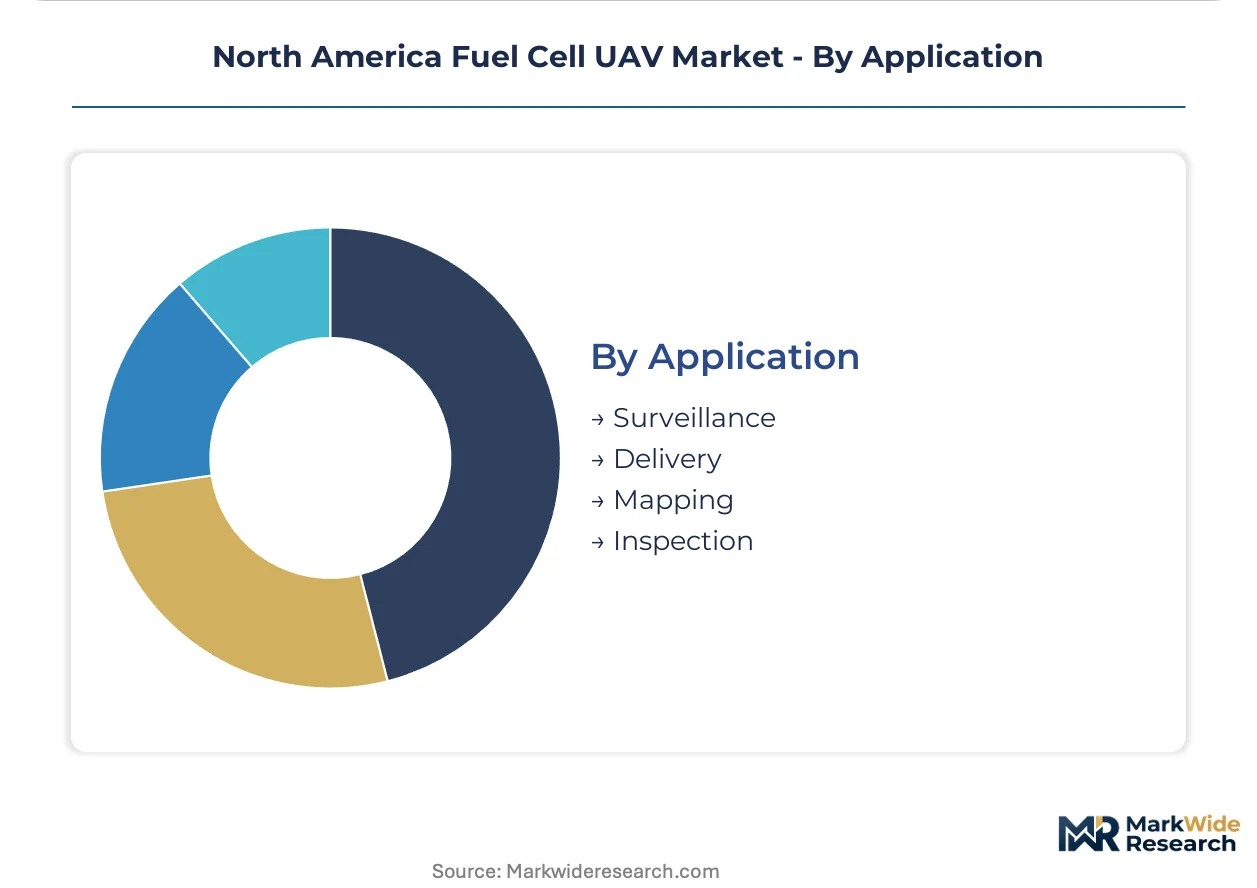
Application:
Volume concentration tracks infrastructure proximity, with pipeline corridors pulling sustained demand and delivery networks awaiting regulatory clarity.
- Surveillance:Border patrol and maritime domain awareness missions require 8-plus-hour endurance brackets that batteries cannot satisfy. PHMSA inspection interval mandates for interstate natural gas transmission lines sustain aerial platform demand in Appalachian and Permian corridors.
- Inspection:Energy sector methane monitoring and electrical transmission line assessment contracts specify hydrogen fueling independence from bundled flight-hour rates, compressing operator margins while expanding fleet flexibility.
- Mapping:Topographic and multispectral survey missions in Canadian Arctic regions leverage fuel cell cold-weather reliability where battery capacity collapses below -20°C.
- Delivery:Last-mile logistics applications remain constrained by FAA type-certification bottlenecks for hydrogen-powered aircraft, with commercial timelines trailing surveillance and inspection deployments by several years.
Surveillance and inspection together anchor procurement volume while delivery applications face the steepest regulatory headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA's Part 107 waiver framework for beyond-visual-line-of-sight operations anchors procurement momentum across the United States, while Transport Canada's evolving RPAS regulations create parallel compliance pathways for cross-border operators.
United States
Defense procurement programs and energy-sector inspection contracts drive hydrogen-powered platform demand. The FAA's Special Class type-certification pathway for hydrogen aircraft compresses timeline uncertainty for manufacturers seeking commercial clearance. California's aerospace corridor and Texas Permian Basin anchor stack development and liquefaction infrastructure deployment.
Canada
Federal hydrogen strategy investments channel capital into unmanned aerial systems manufacturing and proton-exchange-membrane stack production. Transport Canada's RPAS safety assurance framework updates parallel FAA developments, creating first-mover advantage for Arctic surveillance applications. Vancouver engineering bases sustain membrane electrode assembly development for defense contractors.
Mexico
Energy infrastructure monitoring along pipeline corridors creates emerging demand for extended-endurance aerial platforms. The country's national aviation regulator advances remotely piloted aircraft integration frameworks that reference FAA and Transport Canada precedents. Northern border states concentrate pilot programs for methane detection and transmission line assessment.
North America Fuel Cell UAV Market Competitive Landscape
Capability concentration sits with defense-integrated primes; scale advantage sits with hydrogen infrastructure specialists. The vendor base stratifies across three tiers: aerospace conglomerates with military certification authority, fuel cell stack developers with membrane electrode assembly expertise, and energy majors controlling liquefaction and refueling logistics. Dominant competitive moves include strategic partnerships between stack suppliers and airframe integrators, plus geographic expansion of hydrogen fueling networks to match inspection contract corridors.
Within the fuel cell stack developer tier, Ballard Power Systems and Plug Power exemplify divergent strategic positions. Ballard anchors proton-exchange-membrane development from its Vancouver engineering base, serving defense contractors requiring hardened stack configurations. Plug Power occupies the infrastructure-control position, managing liquefaction and refueling station deployment that extends UAV sortie durations across Texas and California corridors. Intelligent Energy represents the European-origin specialist archetype competing in North American defense procurement cycles.
| Leading Market Players |
|---|
| Intelligent Energy |
| Honeywell Aerospace |
| Ballard Power Systems |
| Plug Power |
| AeroVironment, Inc. |
| General Atomics |
| Textron Inc. |
| Northrop Grumman Corporation |
| Boeing |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Vancouver and California membrane electrode assembly production compresses pricing tier spreads while forcing eastern defense contractors into premium logistics arrangements for proton-exchange-membrane stacks. This geographic chokepoint simultaneously inflates standard-tier procurement costs and accelerates backward integration investments among prime contractors seeking supply security.
Pricing Analysis
Texas Permian Basin contractors pay 15-25% premiums over California aerospace cluster pricing for equivalent hydrogen fuel cell UAV configurations due to liquefaction hub distance and trucking logistics. Three-tier pricing structure across defense-certified, commercial-grade, and pilot-program tiers separates hardened MIL-STD-810 configurations from agricultural multispectral platforms. Pricing pressure stems from energy majors unbundling fuel sales from flight-hour contracts, exposing operator margins to spot hydrogen volatility. Agricultural buyers in California Central Valley exhibit highest price sensitivity, while defense agencies prioritize certification compliance over unit economics.
Supply Chain Analysis
Liquid hydrogen feedstock draws from Texas Gulf Coast production hubs and Edmonton liquefaction facilities, with reformer-grade methanol sourcing from Louisiana chemical corridor and Alberta petrochemical complexes. Membrane electrode assemblies rest on platinum group metal catalysts from South African and Russian mining operations, while titanium-iron alloy hydride beds feed from Japanese and German specialty metallurgy. Tariff exposure on catalyst materials threatens stack cost stability. Distribution runs through defense prime contractor integration channels for military procurement, with commercial operators sourcing directly from Ballard and Plug Power regional service centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Fuel Cell UAV Market sits at a regulatory-inflection disruption where FAA Part 107 waiver expansion and Transport Canada RPAS harmonization are compressing commercial deployment timelines against hydrogen infrastructure build-out rates.
For Market Incumbents: Build certification moats through early FAA Special Class type-certification submissions for medium-altitude tactical platforms, locking in precedent advantage before pathway standardization erodes differentiation. Anchor membrane electrode assembly capacity in eastern North American engineering bases to offset Vancouver supply concentration risk. Pursue backward integration into metal hydride storage bed production to capture titanium-iron alloy efficiency gains and collapse cryogenic logistics dependencies for forward-deployed military units. For New Entrants and Emerging Players: Pursue Canadian Arctic surveillance white space where Transport Canada RPAS framework evolution creates first-mover windows before incumbent defense primes reorient capacity. Target agricultural multispectral imaging in California Central Valley where acoustic-signature sensitivity and fuel cost transparency requirements favor new entrant pricing disruption. Establish fixed-price hydrogen supply partnerships with Alberta and Texas energy majors as beachhead go-to-market anchor, decoupling fuel procurement from bundled operator margins. For Investors and Strategic Acquirers: The market sits at a infrastructure-buildout phase that favors hydrogen logistics specialists with liquefaction and refueling station control over pure-stack developers. Long-term viability hinges on regulatory harmonization completion between FAA and Transport Canada frameworks enabling cross-border fleet standardization. Watch FAA Part 107 waiver approval velocity as inflection signal; acceleration beyond current timelines indicates demand pull sufficient to justify capacity expansion commitments, while stagnation suggests infrastructure bottlenecks constraining addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrode Assembly Capacity Expansion | Eastern North American engineering base development reduces Vancouver supply concentration vulnerability for defense contractors. |
| Metal Hydride Storage Bed Pilot Programs | Titanium-iron alloy field validation collapses cryogenic handling requirements for forward-deployed military units. |
| FAA Special Class Type-Certification Submission | Early pathway engagement locks precedent advantage before hydrogen aircraft standardization erodes certification differentiation. |
| Fixed-Price Hydrogen Supply Contracting | Energy major unbundling of fuel sales from flight-hour rates expands fleet deployment flexibility for commercial operators. |
| Cross-Border Regulatory Harmonization Engagement | FAA-Transport Canada framework alignment enables fleet standardization for service providers operating between United States and Canada. |
Research Methodology
A standing panel of fuel cell stack engineering directors, defense procurement program managers, FAA certification specialists, and hydrogen infrastructure planners provided ongoing calibration across the study period. Primary interviews with UAV system integrators, liquefaction facility operators, and agricultural drone service providers combined with secondary validation from FAA docket filings, Transport Canada RPAS regulatory notices, EIA hydrogen production data, and defense budget justification documents. Bottom-up stack shipment tracking and top-down procurement budget analysis enabled triangulation across independent estimation approaches.
Scenario-bracketing around FAA Part 107 waiver velocity, hydrogen infrastructure build-out rates, and defense procurement schedule shifts anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include fuel type chemistry, UAV size bracket, end-user contract structure, and application mission profile. CAGRs derived from logistic curve fitting to technology adoption patterns, with inputs from electrolyzer capacity expansion timelines and military unmanned systems budget trajectories.
Macroeconomic conditions sit as an overlay; deviation in hydrogen production cost curves, platinum group metal commodity volatility, or defense appropriations prioritization would shift the trajectory. Forecasts reflect documented assumptions on regulatory harmonization timing and infrastructure deployment rates. Cross-checking against PHMSA pipeline inspection contract awards and FAA waiver approval databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Latin America Small UAV Market
UAV
Global Electric Drone Market
UAV
UAV Payload and Subsystems Market
UAV
Auto-Follow Drone Market
UAV
Bubble Drone Market
UAV
Electric Glider Market
UAV
North America Small UAV Market
UAV
Toy Drones Market
UAV
Tethered Drones Market
UAV
Unmanned Combat Aerial Vehicle Market
UAV
GCC Drone Pilot Training Market
UAV
Global Smartphone Controlled Drone Market
UAV
Military UAV Sensor Market
UAV
Global Drone Light Shows Market
UAV
Stratospheric Flying Drone Market
UAV
UAV Lidar Market