
 Global Aerospace Adhesives Market | 2026-2036
Global Aerospace Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aerospace Adhesives Market Foresight
The buyer base for aerospace adhesives is broadening beyond traditional commercial OEMs as urban air mobility startups, satellite constellation builders, and regional MRO networks enter procurement channels. 3M Company leverages its film-adhesive portfolio to dominate bonding solutions for composite-intensive airframes. Henkel AG & Co. KGaA sustains European supply relationships through REACH-compliant epoxy systems certified for primary structural applications.
Aerospace adhesives are engineered bonding agents formulated to withstand extreme thermal cycling, vibration, and aerodynamic loading while maintaining structural integrity across aluminum, titanium, and carbon-fiber-reinforced polymer substrates. Epoxy formulations deliver the highest shear strength for primary structural joints, while silicone variants occupy sealing and thermal-protection roles where flexibility under temperature extremes matters. Pressure-sensitive technology leads in interior assembly and temporary fixturing, whereas UV-cure systems are gaining traction in satellite manufacturing for rapid, low-heat bonding of sensitive electronic modules.
FAA airworthiness directives and EASA certification standards govern adhesive qualification for flight-critical applications, forcing suppliers to maintain extensive test documentation and batch-traceability protocols. EPA VOC regulations and REACH substance restrictions in Europe are reshaping formulation chemistry, pushing R&D investment toward solvent-free and bio-based curing systems. Stakeholders must monitor how emerging supersonic and hydrogen-powered aircraft programs redefine thermal and permeability requirements for bonded joints.
Market Dynamics
Composite-intensive airframe architectures are forcing adhesive suppliers to reformulate for multi-material bonding across aluminum, titanium, and carbon-fiber substrates simultaneously. FAA and EASA certification protocols for primary structural joints now demand batch-traceability systems that extend from raw resin through cured assembly.
Growth Catalysts
- REACH substance restrictions:ECHA mandates on high-VOC formulations are accelerating solvent-free epoxy development for European OEM supply chains.
- Urban air mobility:eVTOL manufacturers require rapid-cure systems for prototype iteration cycles far shorter than traditional aerospace programs.
- Film adhesive technology:Out-of-autoclave processing is enabling thinner bondlines and reduced scrap rates in wing skin fabrication.
Market Restraints
- Raw petrochemical volatility:Epoxy resin and amine hardener feedstock costs fluctuate with benzene and propylene pricing, compressing formulation margins unpredictably.
- Supplier concentration in specialty polymers:A handful of German and Japanese chemical houses control high-purity bisphenol-F and cycloaliphatic amine supply.
- Thermal limitation of organic adhesives:Supersonic and hypersonic airframe sections exceeding 180°C operational limits require metallic joining or ceramic alternatives.
Strategic Opportunities
- India defense procurement:Indigenous fighter and helicopter programs under the Ministry of Defence's Make in India initiative create qualified-supplier entry points for structural adhesive vendors.
- Bio-based curing systems:USDA BioPreferred and EU Green Deal procurement incentives favor epoxies derived from lignin and plant-based polyols.
- Satellite constellation manufacturing:UV-cure acrylics are penetrating solar panel and antenna bonding for LEO spacecraft production lines.
Industry Challenges
- Adhesive bonding technician certification:FAA-approved training programs for structural bonding specialists face 18-24 month qualification timelines, constraining MRO capacity expansion.
- Legacy fleet compatibility:New low-VOC formulations must demonstrate equivalent performance to chromated legacy products on aging aluminum airframes without full requalification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aerospace Adhesives Market |
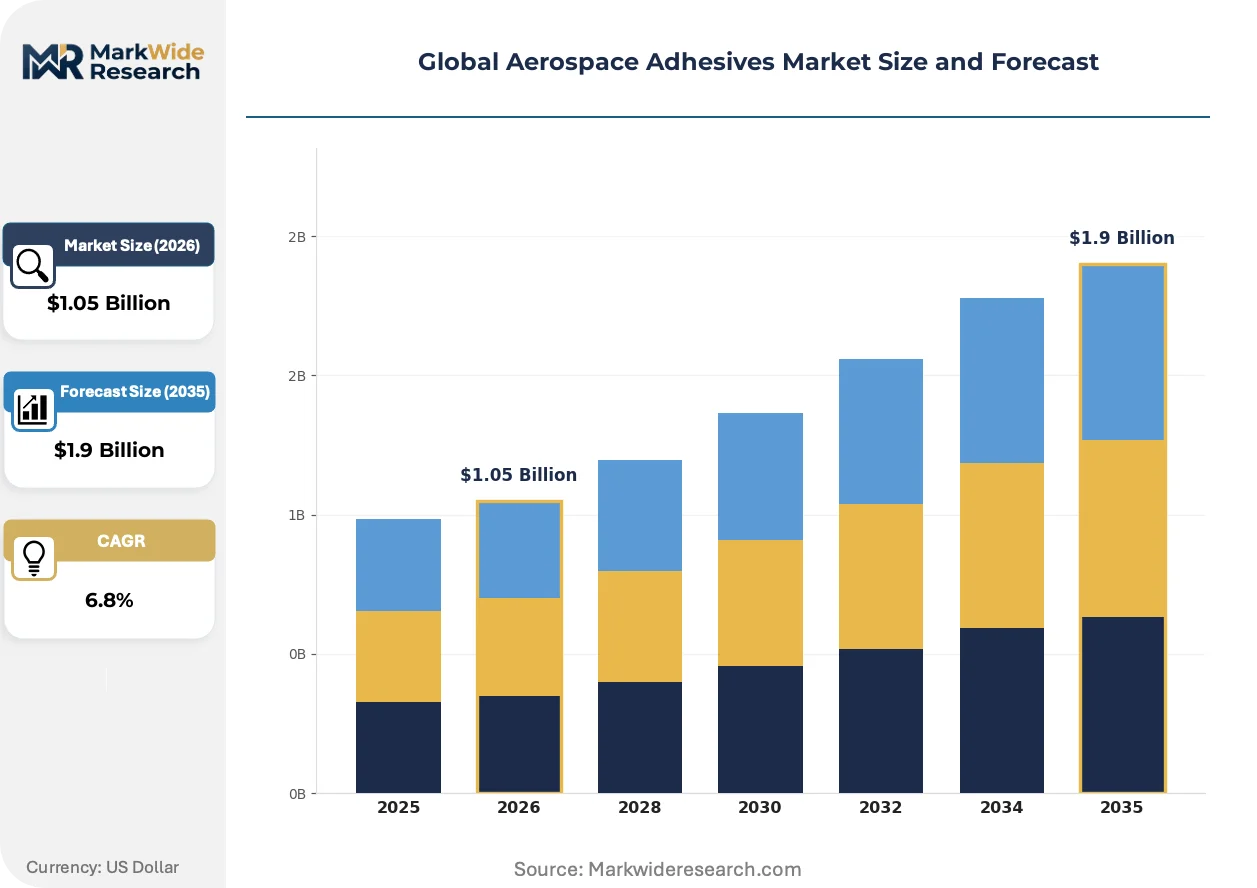
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.9 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Silicone, Polyurethane, Anaerobic Technology: Curing, Pressure Sensitive, Hot Melt, Structural, UV Cure Application: Composite Bonding, Metal Bonding, Sealing, Insulation, Electrical Assembly End User: Aircraft Manufacturers, Aircraft Maintenance Providers, Defense Contractors, Spacecraft Assemblers |
| Companies Covered | 3M Company, Henkel AG & Co. KGaA, H.B. Fuller Company, PPG Industries Inc., Arkema S.A., Hexcel Corporation, Huntsman Corporation, Illinois Tool Works Inc., Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aerospace Adhesives Market Shifts & Advancements
Adhesive technology is converging around multi-functional formulations that simultaneously address structural, thermal, and electromagnetic requirements. Suppliers are integrating sensing capabilities and self-healing chemistries into bondline architectures.
Hybrid epoxy-silicone systems are unifying structural load-bearing with vibration damping and thermal cycling resilience in a single bondline layer. Satellite manufacturers and eVTOL airframe builders are adopting these formulations to reduce part count and assembly steps. This convergence is compressing the traditional separation between primary structure and environmental sealing functions.
EASA's updated CS-25 certification memoranda on bonded repairs are mandating digital twin documentation for adhesive joints in primary structure. Airframe OEMs must now submit finite-element models predicting bondline stress distribution under limit load conditions. European MRO networks are responding by investing in ultrasonic inspection automation and blockchain-based batch records.
Airlines and lessors are unbundling adhesive procurement from airframe purchase agreements, creating direct supplier relationships for MRO consumables. This disintermediation concentrates volume with technical distributors capable of just-in-time formulation mixing and frozen-film logistics. North American cargo operators and Middle East-based lessors are most aggressive in pursuing these arrangements.
Global Aerospace Adhesives Market Segmentation
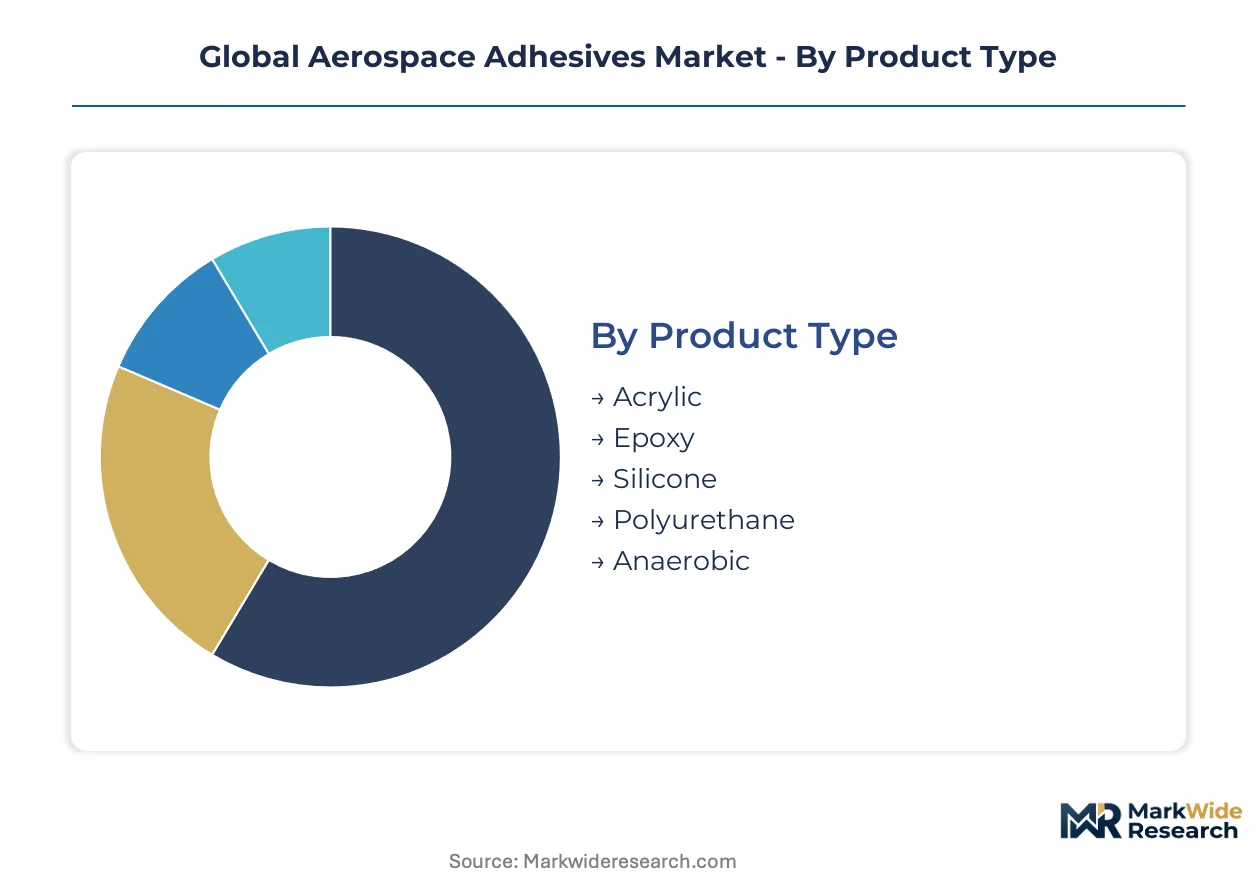
Segmentation in aerospace adhesives reveals distinct capital requirements, certification barriers, and customer concentration patterns across chemistry families and application methods. Understanding these divides allows suppliers to align R&D portfolios with segments where qualification investments yield durable revenue streams.
Product Type:
Epoxy and silicone formulations demand the heaviest upfront capital in resin synthesis infrastructure and FAA/EASA batch-traceability systems, while acrylic and polyurethane lines require less specialized curing equipment.
- Epoxy:Two-part thermosetting systems built from bisphenol-A or bisphenol-F resins deliver the highest shear strength for primary structural joints in wing boxes and fuselage barrels. Aircraft manufacturers in the United States concentrate procurement here for composite-intensive airframes, though REACH substance restrictions on amine hardeners are forcing reformulation investments.
- Silicone:Elastomeric formulations maintain flexibility across temperature extremes from -55°C to 230°C, serving sealing and thermal-protection roles in engine nacelles and avionics bays. Demand concentrates with defense contractors seeking MIL-SPEC compliance for fighter jet environmental sealing.
- Acrylic:Rapid-cure methacrylate systems penetrate MRO channels for quick structural repairs on aging aluminum fleets without full requalification cycles.
- Polyurethane:Tough, abrasion-resistant bondlines find niche application in interior panel assembly and cargo floor bonding where impact resistance matters.
- Anaerobic:Threadlocking and retaining compounds secure fasteners in fuel systems and hydraulic manifolds where vibration loosening risks catastrophic failure.
Epoxy absorbs the bulk of installed capacity; acrylic is expanding most quickly as MRO networks seek faster-cure alternatives.
Technology:
Structural and film-adhesive technologies command premium pricing tiers tied to airworthiness certification depth, while pressure-sensitive and hot-melt formats serve lower-margin interior applications with shorter qualification cycles.
- Structural:Load-bearing formulations certified for primary joints must demonstrate fatigue life exceeding 10^6 cycles under ASTM D1002 protocols. Aircraft manufacturers in Germany and Japan specify these for out-of-autoclave wing skin processing.
- Curing:Heat-activated systems dominate legacy metal bonding where oven processing remains economical; demand concentrates in regional MRO facilities with established thermal infrastructure.
- Pressure Sensitive:Tackified films enable rapid interior assembly of cabin panels and insulation blankets without clamping fixtures.
- Hot Melt:Thermoplastic formulations serve temporary fixturing and non-structural gasketing where reversibility aids disassembly.
- UV Cure:Acrylic photopolymers penetrate spacecraft assemblers in California and Texas for solar panel bonding where low-heat curing protects temperature-sensitive electronics.
Structural technology captures the steepest pricing premiums; UV cure is gaining share fastest among satellite constellation manufacturers.
Application:
Composite bonding and metal bonding applications require the most intensive technician certification and inspection protocols, whereas sealing and insulation segments tolerate more automated dispensing with lower skill barriers.
- Composite Bonding:Multi-material joining across carbon-fiber, aluminum, and titanium substrates demands surface preparation protocols including plasma treatment and peel-ply removal. Aircraft manufacturers in France and Italy drive specification tightening as new airframe programs adopt hybrid material stacks.
- Metal Bonding:Chromate-free epoxy alternatives must match legacy performance on 2024-T3 and 7075-T6 alloys without full requalification, concentrating demand among MRO networks serving aging narrowbody fleets.
- Sealing:Fuel tank and pressure vessel sealing applications favor polysulfide and silicone formulations with long-term fuel resistance.
- Insulation:Thermal and acoustic barrier adhesives bond multi-layer insulation blankets in engine cowlings and cabin sidewalls.
- Electrical Assembly:Conductive and dielectric adhesives secure avionics modules and antenna assemblies where electromagnetic interference control is critical.
Composite bonding commands the largest qualified-supplier footprint; electrical assembly is climbing the fastest as satellite electronics density increases.
End User:
Aircraft manufacturers and defense contractors impose the most stringent batch-traceability and documentation requirements, while maintenance providers and spacecraft assemblers offer faster qualification paths with smaller minimum volume commitments.
- Aircraft Manufacturers:Boeing and Airbus specification control locks in approved suppliers for multi-year platform lifecycles, with qualification costs exceeding $2 million per adhesive grade. REACH and EU Green Deal mandates are accelerating solvent-free formulation shifts in European supply chains.
- Defense Contractors:Lockheed Martin and BAE Systems procurement embeds MIL-PRF and DEF STAN standards requiring domestic sourcing percentages and ITAR compliance.
- Aircraft Maintenance Providers:Lufthansa Technik and ST Engineering operations consume frozen-film adhesives for bonded repairs, with EASA CS-25 updates mandating digital twin documentation for primary structure work.
- Spacecraft Assemblers:SpaceX and Blue Origin production lines specify UV-cure and rapid-cure systems for prototype iteration cycles measured in weeks rather than years.
Aircraft manufacturers absorb the bulk of qualified-supplier capacity; spacecraft assemblers are expanding procurement fastest as launch cadence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for aerospace adhesives concentrates in the United States, where defense procurement and commercial backlog expansion are driving volume. European REACH mandates and the EU Green Deal are accelerating solvent-free formulation shifts. Asian supply chains are emerging as qualified alternatives for composite-intensive airframe programs.
United States
Boeing's commercial backlog and Lockheed Martin's defense contracts absorb the majority of structural adhesive procurement. FAA airworthiness directives govern batch-traceability protocols for primary structural joints. Wichita, Kansas and Seattle, Washington anchor composite wing fabrication clusters where out-of-autoclave processing demands film-adhesive precision.
Germany
Airbus Hamburg and Premium AEROTEC operations specify REACH-compliant epoxy systems for A320 family fuselage barrels. ECHA substance restrictions on high-VOC amine hardeners are forcing reformulation investments across Bavarian chemical suppliers. Munich and Augsburg host specialized resin synthesis facilities serving Tier 1 aerostructures.
France
Safran and Dassault Aviation procurement concentrates on silicone formulations for engine nacelle sealing and fighter jet environmental protection. EASA CS-25 certification memoranda mandate digital twin documentation for bonded repairs. Toulouse and Bordeaux clusters specialize in multi-material bonding for hybrid aluminum-composite airframes.
Japan
Mitsubishi Heavy Industries and Kawasaki Heavy Industries specify JIS-certified structural adhesives for regional jet programs and defense platforms. METI industrial standards align with FAA fatigue-life protocols for primary joints. Nagoya and Komaki host automated dispensing equipment manufacturing for precision bondline control.
India
Hindustan Aeronautics Limited and Tata Advanced Systems are qualifying indigenous suppliers under the Ministry of Defence's Make in India initiative. BIS certification requirements for aerospace materials are converging with MIL-PRF standards for fighter and helicopter programs. Bangalore and Hyderabad clusters are developing MRO capabilities for bonded repair documentation.
Global Aerospace Adhesives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue satellite constellation and urban air mobility channels where qualification cycles compress from years to months. The vendor base stratifies across three tiers: diversified chemical conglomerates with film-adhesive portfolios, specialized epoxy formulators with EASA primary-structure certification, and regional distributors mixing just-in-time formulations for MRO networks. Competitive moves center on backward integration into high-purity bisphenol-F resin supply and partnerships with out-of-autoclave equipment manufacturers.
Within the diversified chemical tier, 3M Company and Henkel AG & Co. KGaA exemplify suppliers with REACH-compliant systems certified for composite-intensive airframes. H.B. Fuller Company represents the mid-tier specialist archetype, occupying a position between global conglomerates and regional distributors. These anchors illustrate how qualification depth and formulation breadth determine platform access across Boeing, Airbus, and emerging eVTOL procurement channels.
| Leading Market Players |
|---|
| 3M Company |
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| PPG Industries Inc. |
| Arkema S.A. |
| Hexcel Corporation |
| Huntsman Corporation |
| Illinois Tool Works Inc. |
| Solvay |
| Others |
Supply & Pricing Matrix
Certified structural bonding technician concentrations in Wichita, Kansas and Seattle, Washington anchor labor-cost differentials that widen pricing-tier spreads between qualified primary-structure suppliers and regional MRO formulators.
Pricing Analysis
High-volume frozen-film epoxy contracts for Boeing and Airbus wing-skin programs absorb margin compression from amine hardener feedstock volatility, while low-volume UV-cure acrylic batches for satellite assemblers sustain premium pricing through rapid-cure technical differentiation. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified primary-structure grades from EASA-compliant MRO repair formulations and uncertified interior-assembly hot-melts. Price differentiation hinges on batch-traceability documentation depth and out-of-autoclave processing compatibility. Regional MRO networks in Germany and Japan exhibit highest price sensitivity due to REACH reformulation cost pass-throughs, whereas defense contractors tolerate premium pricing for ITAR-compliant domestic sourcing.
Supply Chain Analysis
FAA and EASA qualification gating restricts approved resin synthesis to Bavarian chemical houses, Japanese specialty polymer producers, and US Gulf Coast petrochemical complexes, creating supply concentration that amplifies benzene and propylene price transmission effects. Raw material dependencies center on high-purity bisphenol-F from German suppliers, cycloaliphatic amine hardeners from Japanese chemical houses, and epoxy resin precursors from US propylene derivatives. Single-source vulnerability in aerospace-grade amine supply chains intensifies margin risk when ECHA substance restrictions trigger reformulation cycles. Distribution runs through technical distributors capable of just-in-time frozen-film logistics and blockchain batch documentation for MRO networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance restrictions and FAA certification cost inflation are forcing sub-scale formulators toward exit or acquisition, consolidating qualified-supplier lists around backward-integrated resin producers.
For Market Incumbents: Deepen captive supply of high-purity bisphenol-F through partnerships with German chemical houses or in-house resin synthesis investments, insulating margin structures from petrochemical volatility while accelerating solvent-free formulation pipelines to preempt ECHA restriction expansions. Lock in multi-year frozen-film logistics contracts with technical distributors serving disintermediated airline procurement channels. For New Entrants and Emerging Players: E-commerce-enabled technical distribution platforms offer lowest-friction entry points for satellite constellation assemblers and urban air mobility prototype shops seeking rapid-cure acrylics with compressed qualification cycles. Target spacecraft manufacturing clusters in California and Texas with UV-cure formulations bypassing traditional FAA primary-structure certification timelines. Lead with digital batch-traceability documentation to satisfy emerging EASA digital twin mandates. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap epoxy formulators possessing EASA primary-structure certification but lacking backward integration, given REACH-driven consolidation pressure on independent resin buyers. Long-term viability hinges on qualification moats widening as FAA and EASA harmonize bonded repair documentation standards. Watch for EASA CS-25 memoranda enforcement intensity as the inflection signal separating qualified-supplier premium capture from commodity margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol-F Resin Supply | Captive feedstock secures margin stability against benzene volatility and REACH restriction cascades. |
| Out-of-Autoclave Equipment Partnership | Film-adhesive precision alignment with Boeing and Airbus composite wing fabrication clusters accelerates platform access. |
| Solvent-Free Epoxy Formulation Launch | ECHA-compliant systems unlock European OEM procurement channels ahead of substance restriction deadlines. |
| Digital Twin Documentation Platform | Blockchain-based batch records satisfy EASA CS-25 mandates for bonded repair traceability in primary structure. |
| Satellite Constellation Supply Agreement | UV-cure acrylic volume commitments with SpaceX and Blue Origin production lines capture fastest-growing end-use segment. |
Research Methodology
Multi-period observation of Boeing and Airbus specification control releases, EASA certification memoranda updates, and REACH substance restriction timelines anchored the trend analysis, supplemented by interviews with adhesive formulator R&D directors, Tier 1 aerostructure procurement leads, FAA-approved bonding technician training program administrators, and technical distributor logistics managers. Secondary validation drew from ECHA regulatory filings, FAA airworthiness directives, SEC 10-K disclosures from diversified chemical conglomerates, and customs trade data on epoxy resin and amine hardener imports. Bottom-up volume estimates from individual platform adhesive content specifications were triangulated against top-down aerospace production forecasts.
Segment-weighting across product type, technology, application, and end-user dimensions shaped the analytical framework, with chemistry-family splits calibrated to resin synthesis capacity utilization and certification depth tiers. CAGRs were derived from regression analysis of historical procurement volumes against airframe delivery backlogs and defense program award cycles, incorporating satellite constellation launch cadence and urban air mobility prototype build rates as emerging demand variables across the projection horizon.
Inputs from ECHA substance restriction consultations and FAA bonding technician certification databases were available through the study window; gaps in proprietary formulation cost structures and long-term Boeing-Airbus supplier contract terms introduce uncertainty bands around margin compression estimates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Global Aerospace and Defense Elastomers Market
Aerospace and Aircraft Materials
Titanium Sponge for Aerospace and Defense Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Aerospace Foam Market
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Aviation Carbon Fiber Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Stealth Coating Market
Aerospace and Aircraft Materials
Aramid Honeycomb Market
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Russia Space Electronics Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Advanced Materials for Flying Cars Market
Aerospace and Aircraft Materials
Aerospace Titanium Market