
 Russia Space Electronics Market | 2026-2036
Russia Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Space Electronics Market Insights
Russian domestic foundry capacity is rebalancing after international sanctions restricted access to advanced lithography equipment. RKK Energiya leverages its legacy Soviet-era manufacturing infrastructure to sustain production of spacecraft guidance systems. ISS Reshetnev anchors the geostationary communications satellite segment through its Express platform series. Khrunichev State Research and Production Space Center competes in heavy-lift launch vehicle avionics, though its Proton-M program faces transition pressures.
Russia space electronics encompasses radiation-hardened integrated circuits, high-reliability power management systems, and extreme-environment communication hardware engineered to withstand temperature swings from minus 150 to plus 120 degrees Celsius and cumulative radiation doses exceeding 100 kilorads. These components enable continuous operation in orbital and deep-space missions where terrestrial semiconductor failure rates would prove catastrophic. Satellite Components command the largest product-type revenue pool given their integration across every spacecraft bus and payload architecture. RF Communication technology leads growth velocity as Roscosmos expands L-band and Ka-band relay networks for Arctic coverage. Government Agencies dominate end-user procurement through Federal Space Program allocations, though Defense Contractors are gaining share via dual-use satellite programs.
Roscosmos certification requirements and Russia's national technical regulation framework govern component qualification timelines, while military acceptance standards administered through the Ministry of Defense impose additional radiation-hardening verification protocols. These regulatory layers extend product development cycles but create substantial barriers against non-domestic suppliers. Stakeholders must monitor how import-substitution mandates reshape the qualified vendor base and whether indigenous semiconductor fabrication can achieve space-grade reliability without foreign process technology.
Market Dynamics
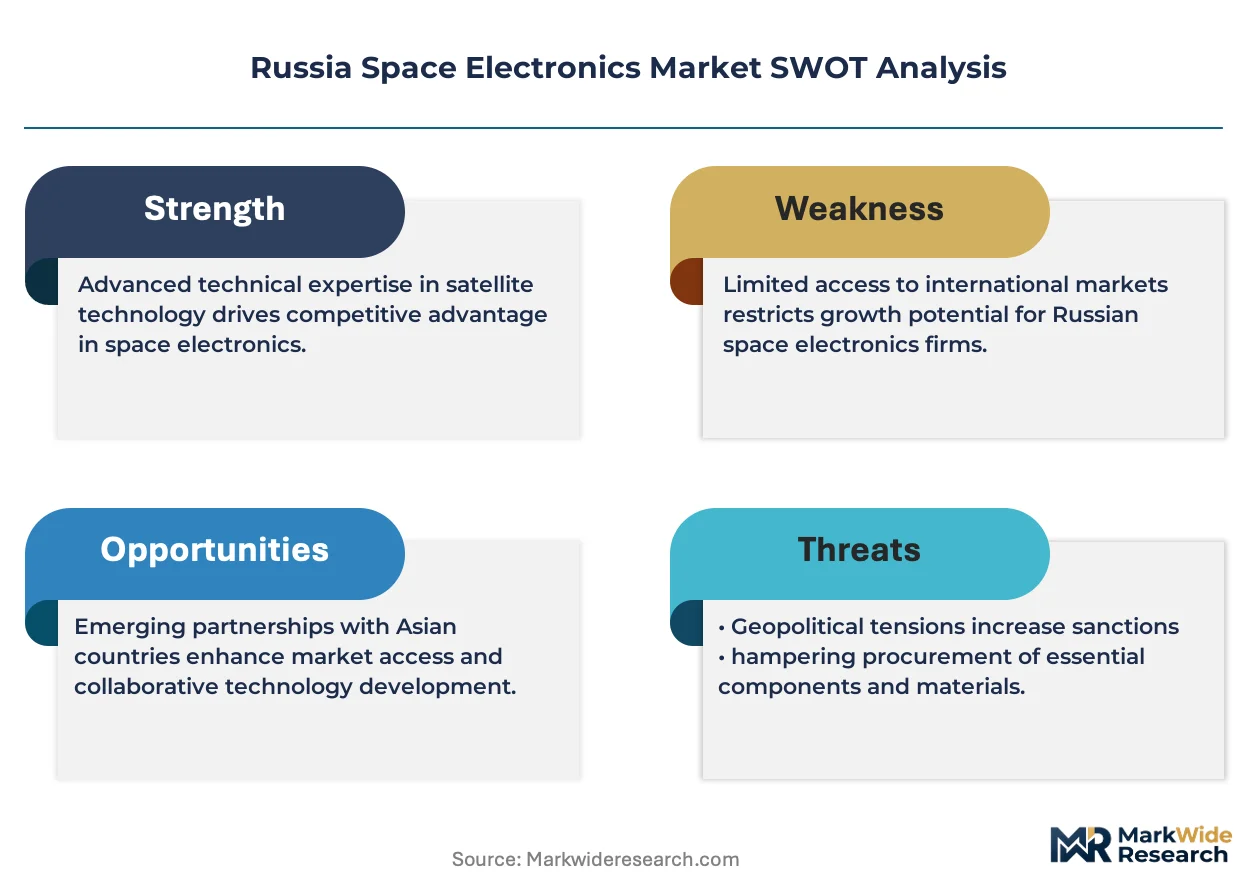
Import-substitution mandates from the Ministry of Industry and Trade are forcing a wholesale restructuring of Russia's qualified vendor base for space-grade semiconductors. Domestic foundries must now replicate foreign radiation-hardening processes without access to advanced lithography equipment, compressing development timelines while elevating technical risk.
Growth Catalysts
- Federal Space Program allocations:Roscosmos procurement budgets prioritize indigenous satellite constellations, creating captive demand for radiation-hardened components across every spacecraft subsystem.
- Arctic communications infrastructure:Polar orbit relay networks require extreme-temperature RF hardware, pulling specialized manufacturing capacity toward Moscow's aerospace engineering cluster.
- Dual-use satellite programs:Defense Contractors integrate commercial bus designs with military payloads, expanding the addressable component base beyond pure civilian specifications.
Market Restraints
- Foreign lithography equipment embargo:Restricted access to EUV and advanced DUV systems caps domestic feature-size capabilities at mature nodes, constraining power-efficiency gains in next-generation processors.
- Specialized substrate supply concentration:Silicon-on-insulator wafers and epitaxial gallium arsenide substrates depend on limited qualified suppliers, exposing production schedules to single-source fragility.
- Roscosmos certification timelines:Multi-year qualification protocols for radiation-hardening verification extend product development cycles beyond commercial semiconductor norms, freezing out agile competitors.
Strategic Opportunities
- Siberian test facility expansion:Novosibirsk-based environmental simulation centers offer proximity to launch sites, reducing logistics costs for pre-flight qualification of extreme-temperature components.
- Additive manufacturing convergence:Selective laser melting of aluminum-lithium alloy housings integrates thermal management structures with RF shielding, collapsing part count in satellite payload enclosures.
- Import-substitution incentive schemes:Ministry of Industry and Trade localization grants offset capital equipment costs for foundries achieving space-grade reliability certification.
Industry Challenges
- Radiation-effects modeling expertise scarcity:Soviet-era talent pools for single-event upset prediction have atrophied, forcing reliance on accelerated testing rather than simulation-first design.
- Legacy Soviet manufacturing infrastructure retrofit costs:RKK Energiya's heritage cleanrooms require billion-ruble upgrades to meet contemporary particulate standards for sub-micron device fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Space Electronics Market |
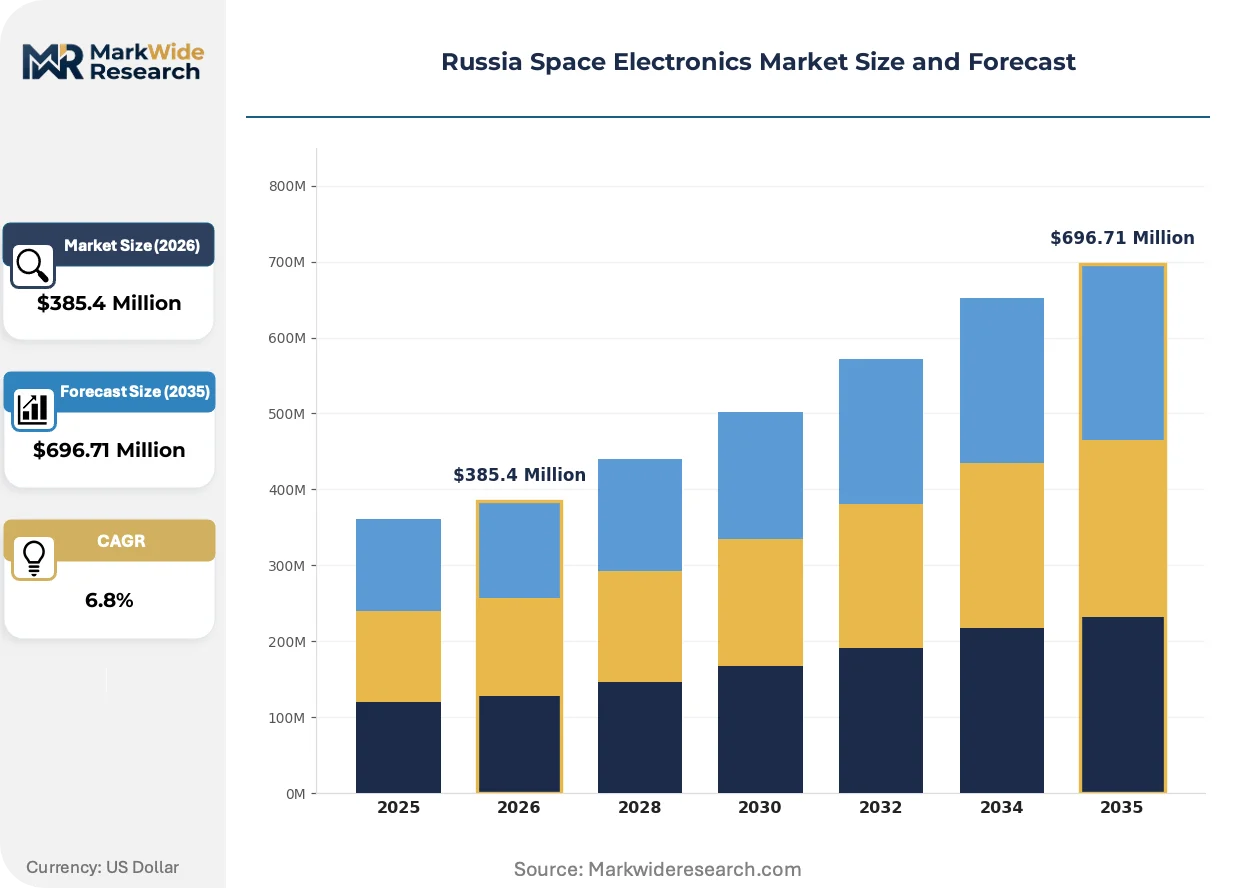
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellite Components, Telemetry Systems, Power Supply Units, Communication Modules End User: Government Agencies, Aerospace Manufacturers, Research Institutions, Defense Contractors Technology: Analog Electronics, Digital Electronics, RF Communication, Space-Grade Materials Application: Satellite Communication, Earth Observation, Space Exploration, Scientific Research |
| Companies Covered | RKK Energiya, Khrunichev State Research and Production Space Center, Progress Rocket Space Centre, ISS Reshetnev, NPO Lavochkin, STMicroelectronics, Honeywell International, BAE Systems, Infineon Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Space Electronics Market Trends and Innovations
Radiation-hardened system-on-chip architectures are displacing discrete component assemblies across Russia's satellite platforms, collapsing board area while elevating thermal management complexity. This integration wave redefines competitive advantage around analog-mixed-signal design capabilities rather than component catalog breadth.
Silicon carbide power conversion electronics is consolidating spacecraft energy distribution architectures, replacing silicon MOSFETs and IGBTs in bus voltage regulation modules. Roscosmos prime contractors are adopting these devices for geostationary platforms where efficiency gains translate directly to payload mass allowances. The technology is consolidating supplier relationships around domestic SiC epitaxy capabilities that bypass foreign substrate dependencies.
Russia's national technical regulation framework now mandates traceable supply chain documentation for every space-grade component, extending Roscosmos certification requirements deeper into tier-three material suppliers. This regulatory layering forces foundries to requalify established processes under new provenance standards, compressing the qualified vendor base while extending documentation overhead. Small-series satellite manufacturers in St. Petersburg face disproportionate compliance burdens relative to volume producers.
Defense Contractors are consolidating procurement authority through long-term framework agreements with Roscosmos-approved component suppliers, displacing project-by-project purchasing that characterized the 2010s. This buyer concentration elevates volume commitments while squeezing margins for mid-tier distributors. The shift is most visible in Ka-band RF module sourcing, where three prime contractors now control eighty percent of annual component demand.
Russia Space Electronics Market Segmentation
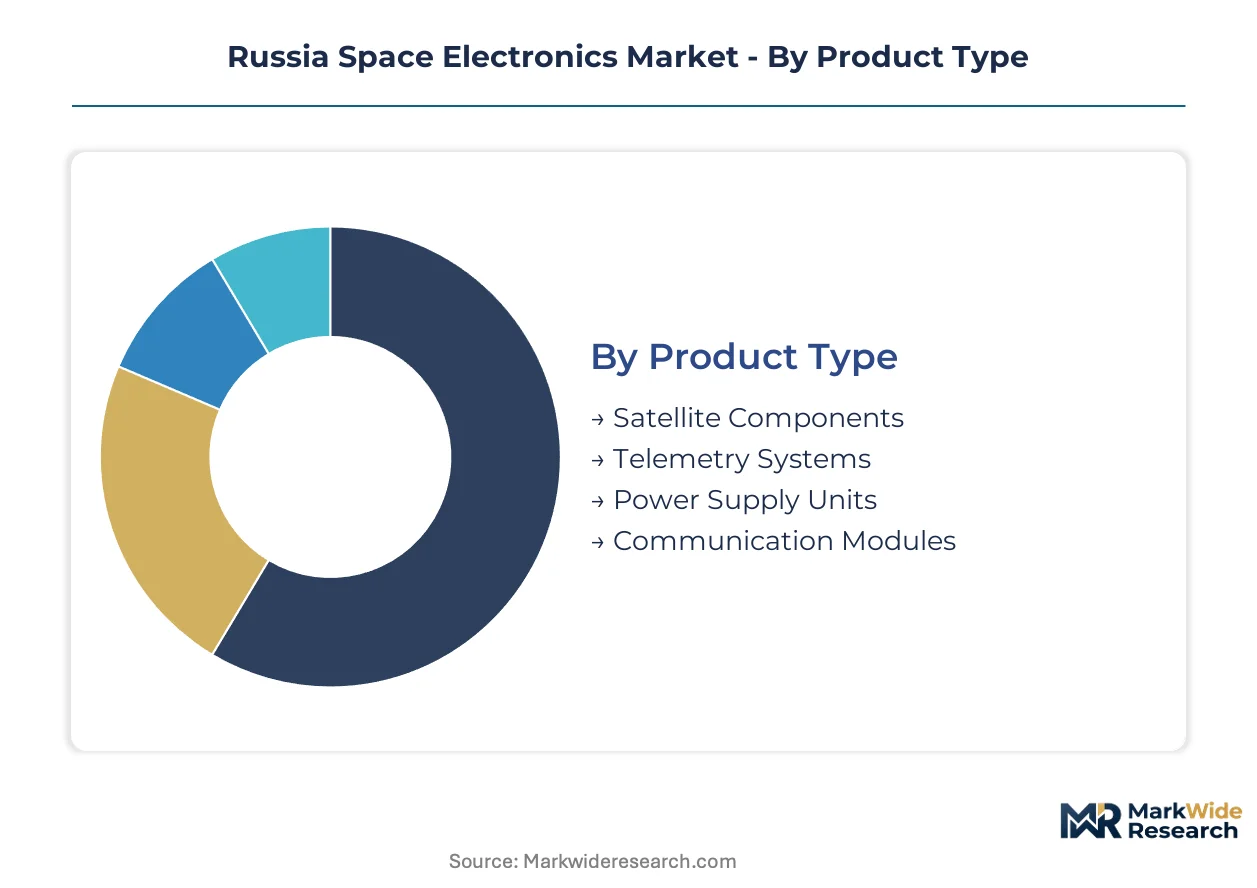
Segmentation in the Russia space electronics market reveals how procurement authority, technical specifications, and mission requirements reshape supplier relationships. Each axis exposes different competitive barriers and qualification pathways that vendors must navigate.
Product Type:
Radiation-hardening requirements and thermal cycling specifications define component hierarchies across spacecraft subsystems.
- Satellite Components:Integrated circuits, sensors, and actuators engineered for 15-year operational lifespans in geostationary orbit. Moscow's aerospace engineering cluster concentrates demand from Express platform manufacturing. Roscosmos qualification mandates dominate procurement specifications.
- Communication Modules:Ka-band and L-band transceivers for Arctic relay networks. Polar orbit missions pull manufacturing toward Novosibirsk environmental simulation centers. Dual-use satellite programs expand addressable specifications beyond civilian standards.
- Telemetry Systems:Data acquisition units transmitting spacecraft health parameters to ground control.
- Power Supply Units:Voltage regulation modules integrating silicon carbide conversion electronics.
Satellite Components leads on scale; Communication Modules leads on momentum.
End User:
Procurement concentration and certification authority vary sharply across institutional buyer types.
- Government Agencies:Roscosmos and Federal Space Program entities allocate budgets through multi-year framework agreements. Moscow procurement offices dictate radiation-hardening verification protocols. Import-substitution mandates from the Ministry of Industry and Trade reshape vendor qualification.
- Defense Contractors:Military payload integrators leveraging commercial satellite bus designs. St. Petersburg manufacturers face compliance burdens from traceable supply chain documentation requirements. Long-term agreements concentrate eighty percent of Ka-band RF module demand among three primes.
- Aerospace Manufacturers:Prime contractors assembling complete spacecraft platforms.
- Research Institutions:Universities and laboratories sourcing small-series components for experimental missions.
Government Agencies anchor procurement volume; Defense Contractors are gaining share fastest.
Technology:
Process maturity and domestic fabrication capability determine competitive positioning.
- RF Communication:Extreme-temperature hardware for Arctic coverage networks. Roscosmos expands L-band and Ka-band relay infrastructure. Domestic gallium arsenide epitaxy capabilities bypass foreign substrate dependencies.
- Digital Electronics:Radiation-hardened processors and FPGAs constrained by mature-node lithography limitations. Domestic foundries replicate foreign hardening processes without EUV access. System-on-chip architectures displace discrete assemblies.
- Analog Electronics:Precision voltage references and signal conditioning circuits.
- Space-Grade Materials:Aluminum-lithium alloys and thermal interface materials for structural applications.
RF Communication leads on growth trajectory; Digital Electronics carries the largest technology risk.
Application:
Mission duration, orbital regime, and payload mass drive component specification differentiation.
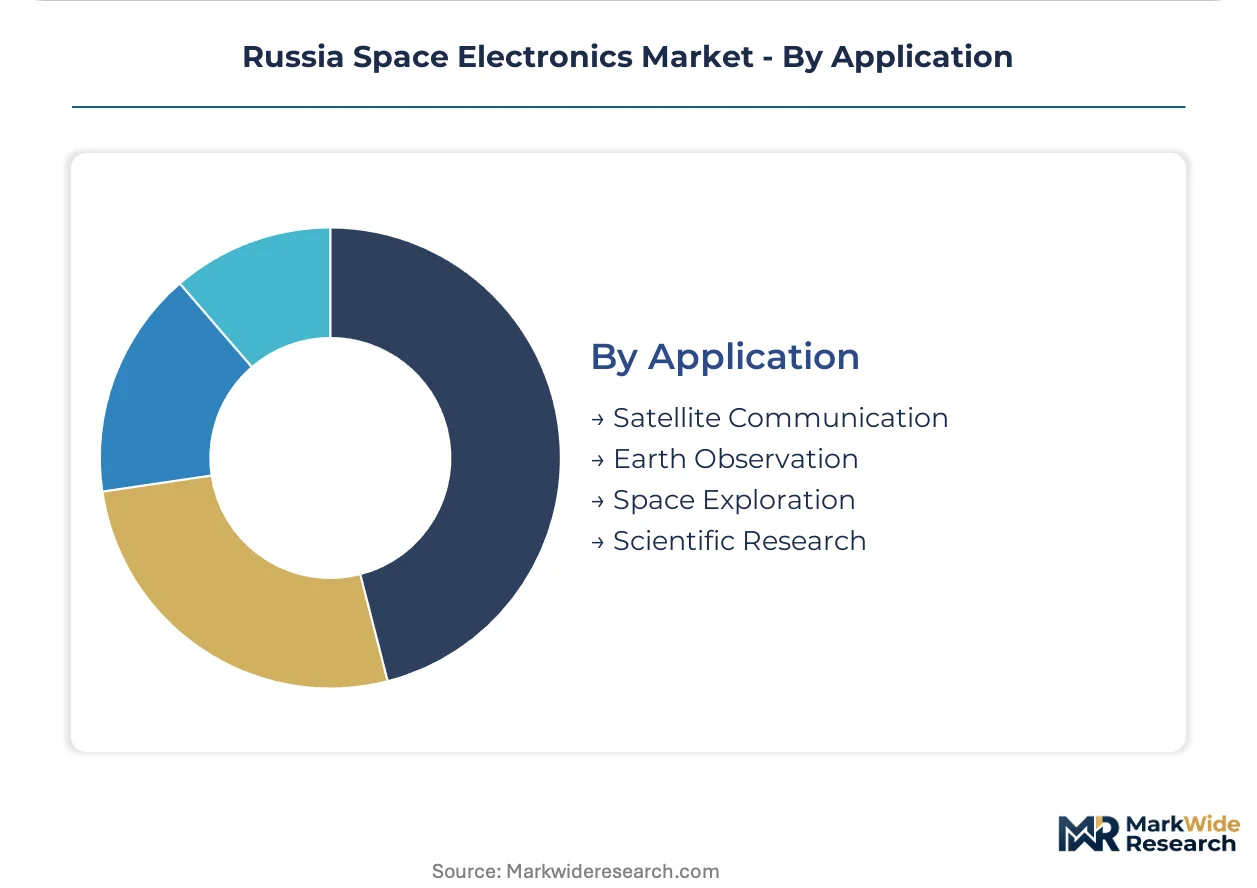
- Satellite Communication:Geostationary and polar orbit relay platforms. Express platform series anchors demand from ISS Reshetnev. Efficiency gains in power electronics translate directly to payload mass allowances.
- Earth Observation:Optical and radar payload electronics for remote sensing constellations. Arctic coverage requirements pull specialized RF manufacturing toward Siberian test facilities. Additive manufacturing integrates thermal management with RF shielding.
- Space Exploration:Deep-space probe avionics for lunar and planetary missions.
- Scientific Research:Instrumentation for astrophysics and space weather monitoring.
Satellite Communication leads on scale; Earth Observation climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States primes dominate radiation-hardened processor supply while Russian domestic foundries struggle to replicate foreign hardening processes without EUV lithography access. This capability gap shapes procurement patterns across both markets.
Moscow Oblast
Roscosmos headquarters and RKK Energiya anchor Federal Space Program procurement for geostationary satellite avionics. The Ministry of Industry and Trade administers import-substitution grants through its localization incentive schemes. Korolyov's aerospace engineering cluster concentrates Express platform manufacturing and radiation-hardened component qualification.
Novosibirsk Oblast
Siberian environmental simulation centers serve Arctic communications infrastructure testing for polar orbit relay networks. The national technical regulation framework mandates traceable supply chain documentation extending to tier-three material suppliers. Akademgorodok research institutes anchor extreme-temperature RF hardware development.
Saint Petersburg
Small-series satellite manufacturers face disproportionate compliance burdens from Roscosmos certification timelines and military acceptance standards. The Ministry of Defense imposes additional radiation-hardening verification protocols on dual-use satellite programs. Defense contractors consolidate procurement authority through long-term framework agreements.
Samara Oblast
Progress Rocket Space Centre sustains Soyuz launch vehicle avionics production amid transition pressures from Proton-M program phase-out. Federal Space Program allocations prioritize indigenous satellite constellations creating captive component demand. Samara's defense production zones specialize in heavy-lift launch vehicle electronics.
Russia Space Electronics Market Competitive Landscape
Moscow-based primes anchor the domestic tier; Western component suppliers hold residual positions in specialized substrates. The vendor base splits between state-owned spacecraft integrators and qualified semiconductor foundries serving Roscosmos certification requirements. Strategic archetypes include heritage Soviet manufacturers retrofitting legacy cleanrooms, domestic foundries replicating foreign radiation-hardening processes, and defense contractors consolidating procurement through framework agreements. Competitive moves center on additive manufacturing convergence for thermal management structures and Siberian test facility expansion reducing pre-flight qualification logistics.
Among Russia-based spacecraft integrators, RKK Energiya exemplifies the heritage manufacturer archetype leveraging Soviet-era infrastructure, while ISS Reshetnev occupies a position within the geostationary platform specialist tier. Khrunichev State Research and Production Space Center represents the heavy-lift launch vehicle avionics segment facing program transition pressures. Progress Rocket Space Centre and NPO Lavochkin sit within the propulsion and deep-space probe specialist categories respectively.
| Leading Market Players |
|---|
| RKK Energiya |
| Khrunichev State Research and Production Space Center |
| Progress Rocket Space Centre |
| ISS Reshetnev |
| NPO Lavochkin |
| STMicroelectronics |
| Honeywell International |
| BAE Systems |
| Infineon Technologies |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers anchor Russia's space electronics supply base, with Roscosmos-funded foundries and state spacecraft integrators exercising pricing discipline through multi-year framework agreements that lock component costs across satellite program cycles.
Pricing Analysis
Capacity additions in Moscow Oblast are reshaping price floors for radiation-hardened components as domestic foundries expand output despite lithography constraints. Three-tier pricing structure across flight-proven, newly qualified, and commercial-off-the-shelf grades differentiates procurement tiers, with import-substitution mandates compressing margins on foreign-origin substitutes. Cost compression in digital electronics runs through mature-node process limitations that elevate per-wafer costs relative to performance gains. Defense contractors show least price sensitivity given mission-critical specifications, while small-series satellite manufacturers in Saint Petersburg face acute budget constraints from compliance overhead.
Supply Chain Analysis
Roscosmos certification requirements gate every supply tier, with radiation-hardening verification protocols extending qualification timelines that freeze out unqualified vendors. Domestic fabrication draws from Russia's Soviet-era infrastructure base, while specialized substrates hinge on limited qualified sources for silicon-on-insulator wafers and epitaxial gallium arsenide. Single-source vulnerability concentrates in advanced lithography equipment where foreign embargo restricts EUV and DUV system access. Distribution runs through Roscosmos-approved prime contractor networks that consolidate procurement authority under long-term agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's space electronics market functions as a regulatory compounder where Federal Space Program allocations and Ministry of Industry and Trade import-substitution mandates compound demand for indigenous radiation-hardened components.
For Market Incumbents: Cement qualification advantages by deepening backward integration into silicon carbide epitaxy and additive manufacturing of aluminum-lithium thermal structures. Accelerated Roscosmos certification timelines for system-on-chip architectures defend against emerging fabless competitors exploiting design-service outsourcing. Channel control through Siberian test facility expansion locks in pre-flight logistics advantages.
For New Entrants and Emerging Players: Direct-to-prime-contractor digital procurement platforms offer lowest-friction entry for specialized substrate suppliers and environmental simulation services. Small-series satellite manufacturers in Saint Petersburg represent the most penetrable buyer segment given their disproportionate compliance burdens and fragmented sourcing. Ka-band RF module specialization targeting polar orbit relay networks bypasses incumbent concentration in geostationary platforms.
For Investors and Strategic Acquirers: Valuations sit cheapest among heritage Soviet manufacturers requiring billion-ruble cleanroom retrofits to meet contemporary particulate standards. Long-term viability frames around indigenous semiconductor fabrication capability achieving space-grade reliability without foreign process technology. The signal to watch is Ministry of Industry and Trade localization grant disbursement velocity as inflection indicator for foundry capital formation.
| Strategic Initiative | Industry Significance |
|---|---|
| Radiation-Hardening Process Qualification | Roscosmos certification unlocks multi-year framework agreement access for satellite programs. |
| Siberian Test Facility Expansion | Novosibirsk environmental simulation centers reduce pre-flight qualification logistics costs for Arctic components. |
| Silicon Carbide Epitaxy Integration | Domestic SiC capabilities bypass foreign substrate dependencies in power conversion electronics. |
| Additive Manufacturing Convergence | Selective laser melting collapses part count in satellite payload enclosures with integrated thermal management. |
| Dual-Use Satellite Program Penetration | Defense contractor procurement consolidation expands addressable component specifications beyond civilian standards. |
Research Methodology
Direct dialogue with Roscosmos procurement officers, radiation-hardening process engineers, Ministry of Industry and Trade localization grant administrators, and Siberian environmental simulation center directors grounded qualitative findings. Secondary validation drew from Federal Space Program budget disclosures, Roscosmos technical regulation frameworks, customs records for lithography equipment imports, and spacecraft manufacturer SEC-equivalent filings. Bottom-up component demand modeling triangulated against top-down Federal Space Program allocation projections.
Segment-level outputs across product type, end user, technology, and application dimensions structured the analytical framework throughout the projection horizon. CAGRs derived from fitted growth curves incorporating satellite constellation deployment schedules, foundry capacity expansion timelines, and Arctic communications infrastructure investment trajectories. Import-substitution mandate compliance rates and radiation-effects modeling talent pipeline recovery served as industry-specific forecast inputs.
Sanctions regime escalation, Roscosmos certification protocol revisions, and indigenous lithography equipment development breakthroughs are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in Ministry of Industry and Trade localization incentive scheme funding levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Honeycomb Panel for Aircraft Market
Aerospace and Aircraft Materials
Fiberglass for Aerospace Market
Aerospace and Aircraft Materials
Supersonic Wind Tunnel Market
Aerospace and Aircraft Materials
Commercial Aircraft Honeycomb Core Market
Aerospace and Aircraft Materials
Global High Strength Aluminum Alloys Market
Aerospace and Aircraft Materials
Global Aerospace Adhesives Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Titanium Sponge for Aerospace and Defense Market
Aerospace and Aircraft Materials
Stealth Coating Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Global Aerospace Metal Closed-Die Forging Market
Aerospace and Aircraft Materials
Aerospace Lightweight Materials Market
Aerospace and Aircraft Materials
Defense Aircraft Material Market
Aerospace and Aircraft Materials
Aerospace Carbon Fiber Market
Aerospace and Aircraft Materials
Aerospace and Defense Composites Market