
 Aircraft Cabin Interiors Market | 2026-2036
Aircraft Cabin Interiors Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Cabin Interiors Market Intelligence
A preference for multi-sourcing key cabin components from specialized suppliers is hardening across the aerospace industry, allowing airframers to access targeted innovation. Collins Aerospace leverages its extensive portfolio in seating and integrated lighting systems. Safran differentiates through its complete cabin solutions, including lavatories and overhead bins. RECARO Aircraft Seating specializes in ergonomic and lightweight passenger seats for various airline classes.
Aircraft cabin interiors encompass all fixtures and furnishings inside the passenger cabin, engineered to meet stringent flammability standards like the FAA's FAR 25.853. These components primarily exist to ensure passenger safety and comfort while reflecting an airline's brand identity. Seating represents the largest component category by value, driven by frequent premium cabin upgrades. The commercial airlines segment commands the market, while demand for lightweight composite materials is displacing traditional metals to improve overall aircraft fuel efficiency.
The market operates under strict oversight from aviation authorities like the U.S. Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA). These bodies enforce rigorous type certification for all cabin components, governing material flammability, structural integrity, and occupant safety. Suppliers must now balance the conflicting demands of cost reduction, weight optimization, and enhanced passenger personalization to secure long-term contracts with major airframers and airlines.
Market Dynamics
The primary force shaping the market is the intense pressure on airlines to reduce fuel burn through weight optimization, while simultaneously investing in cabin personalization to compete for high-yield passengers. This creates a direct demand for advanced, lightweight materials.
Growth Catalysts
- Lightweight Composites:The use of carbon fiber in seats and monuments reduces aircraft weight, addressing airline mandates for improved fuel efficiency.
- Premium Cabin Retrofits:A consistent upgrade cycle for first and business class by major airlines drives demand for high-value seating and fixtures.
- Environmental Policy:European regulations promoting lighter aircraft create a tailwind for suppliers of weight-optimized components, stimulating material innovation.
Market Restraints
- Material Cost Volatility:Unstable pricing for aerospace-grade carbon fiber impacts component manufacturer margins due to a concentrated supply base.
- Stringent Certification:Lengthy and costly certification from the FAA and EASA for new components stifles innovation and delays market entry.
- Supplier Concentration:Dependence on a few subsystem suppliers in European aerospace clusters creates bottlenecks and limits negotiating leverage for airframers.
Strategic Opportunities
- Cabin MRO in Asia:Expanding maintenance services in India and Southeast Asia creates local demand for retrofit parts to support growing airline fleets.
- Smart Cabin Integration:Integrating IoT sensors for predictive maintenance on seats and galleys offers new recurring revenue from data-driven services.
- Modular Cabin Systems:Developing reconfigurable layouts allows airlines to adjust seating class-counts between flights, maximizing revenue on specific routes.
Industry Challenges
- Specialized Labor Shortages:A scarcity of technicians skilled in composite material repair and smart cabin avionics integration hinders maintenance efficiency and drives up labor costs for airlines and MROs.
- Supply Chain Compliance:Managing and certifying supply chains to meet diverging sustainability and material traceability requirements from regulators like EASA is increasingly complex and costly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Cabin Interiors Market |
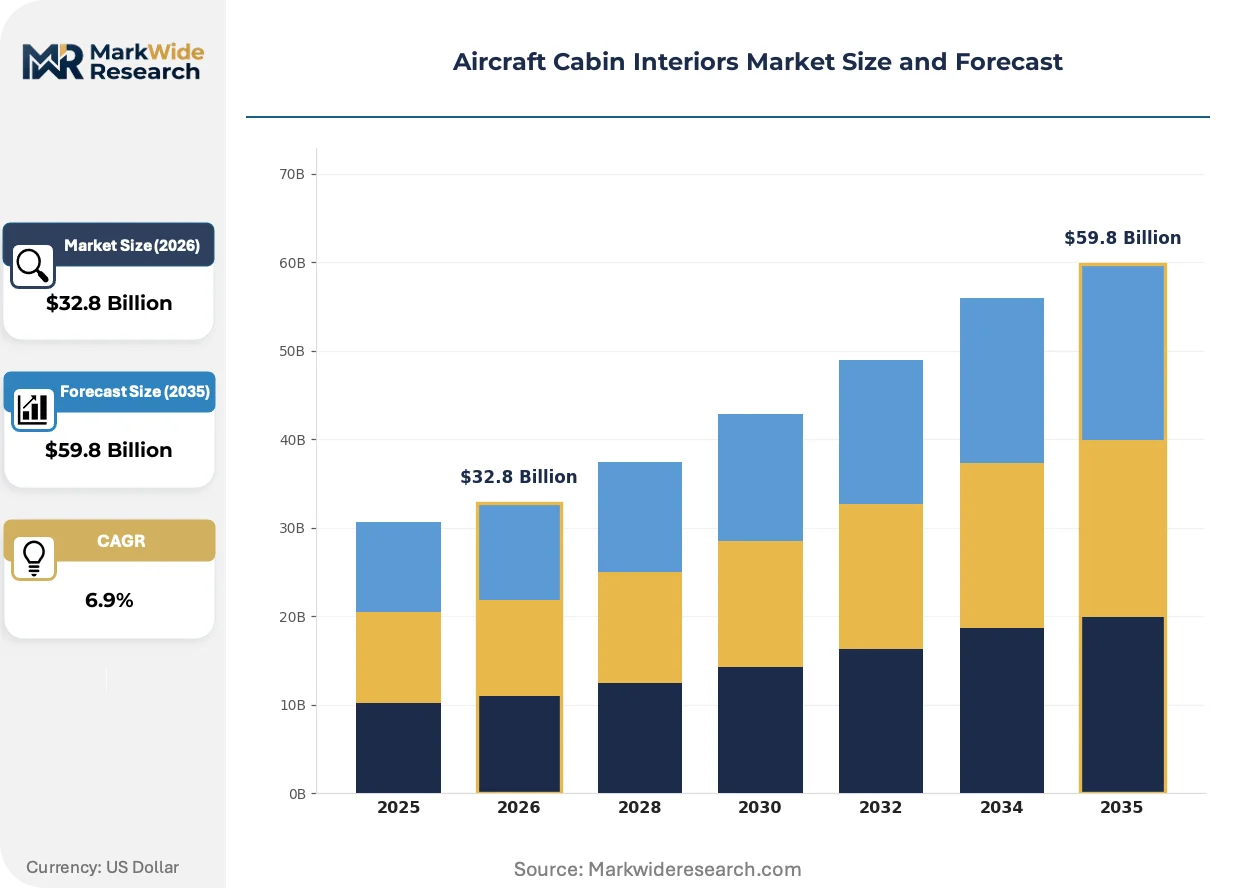
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $59.8 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Seating, Lighting, Overhead Bins, Lavatories Material: Fabric, Leather, Composite, Metals End User: Commercial Airlines, Private Aviation, Military, Charter Services Design Type: Modular, Custom, Ergonomic, Standardized |
| Companies Covered | Collins Aerospace, Safran, Panasonic Avionics Corporation, Honeywell International Inc., JAMCO Corporation, Diehl Aviation, Astronics Corporation, RECARO Aircraft Seating, Aviointeriors S.p.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Cabin Interiors Market Strategic Shifts & Innovations
Digitalization and advanced material science are converging to redefine both passenger experience and operational economics within the aircraft cabin. This shift forces suppliers to innovate beyond traditional component manufacturing toward integrated, data-enabled systems.
Additive manufacturing enables on-demand production of complex, lightweight non-structural cabin parts like brackets and trim pieces. Airlines and MRO providers are adopting this technology to reduce spare part inventories and shorten aircraft-on-ground time. This capability is decentralizing part manufacturing from large, centralized facilities to localized maintenance hubs worldwide.
Heightened focus on cabin air quality and hygiene is driving new standards for filtration and antimicrobial surfaces. This trend compels suppliers to integrate advanced air purification systems and touchless features into lavatories and galleys. The commercial airline segment is most affected, now specifying these features in new aircraft and retrofit orders.
Airlines are shifting procurement from one-time transactional purchases to long-term service agreements for major components like seats. This model bundles the initial product with ongoing maintenance, spares, and upgrade paths, replacing traditional capital expenditure cycles. The trend is most visible among large network carriers in Europe and North America seeking to manage total ownership costs.
Aircraft Cabin Interiors Market Segmentation
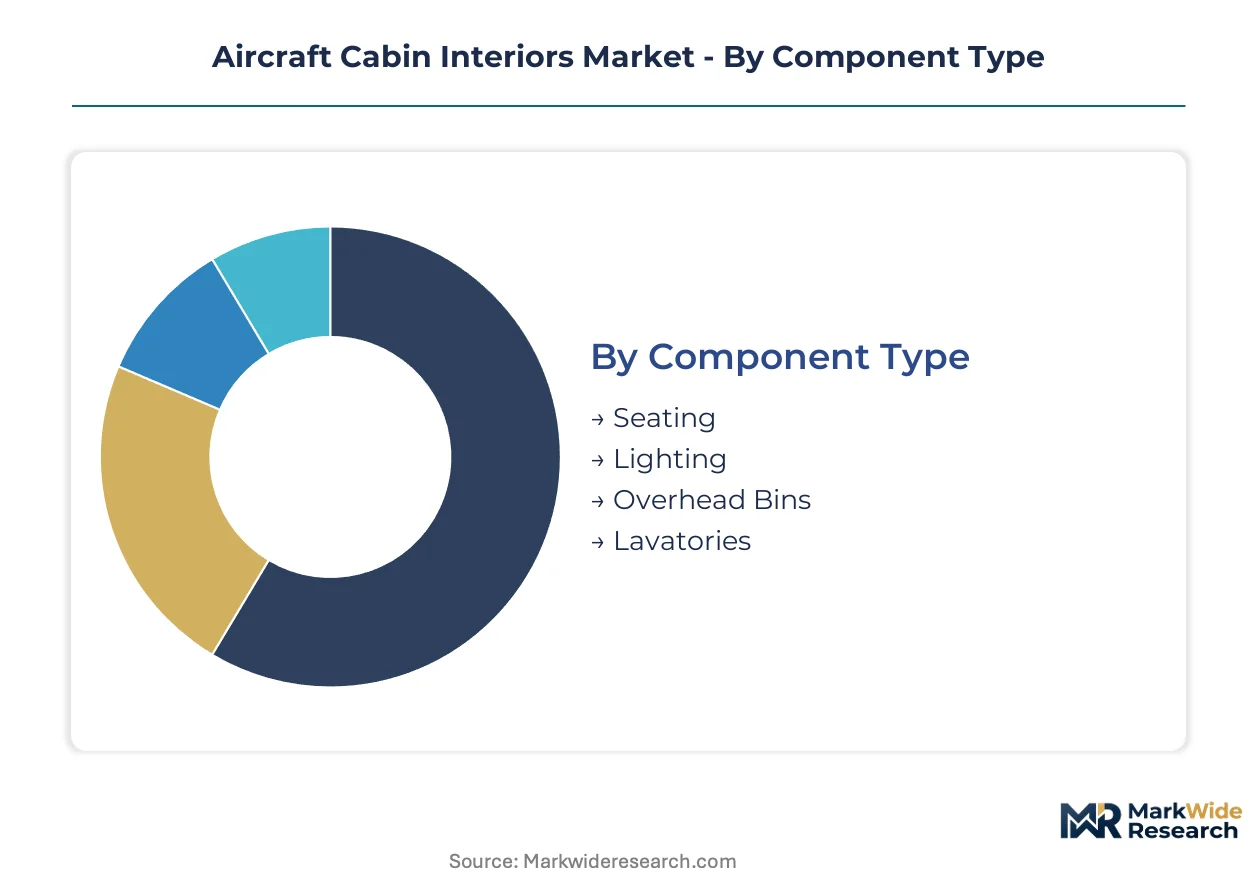
The aircraft cabin interiors market segments reflect the diverse requirements for safety, comfort, and operational efficiency across different aviation sectors. Understanding these distinct segments helps suppliers tailor solutions that meet specific regulatory demands and customer preferences.
Component Type:
Certification mandates from aviation authorities like the U.S. Federal Aviation Administration (FAA) and the European Union Aviation Safety Agency (EASA) heavily influence the component type segment, requiring rigorous testing for flammability and structural integrity.
- Seating:Aircraft seating comprises the primary passenger interface, engineered for comfort, safety, and weight efficiency. Demand concentrates within commercial airlines for premium cabin retrofits, driven by competition for high-yield passengers.
- Lavatories:Lavatories are self-contained modules integrating plumbing, waste management, and antimicrobial surfaces, subject to strict health and safety standards. Demand is rising from commercial airlines specifying enhanced hygiene features in new aircraft and retrofit orders.
- Lighting:Cabin lighting systems, including LED and mood lighting, enhance passenger experience and guide emergency egress.
- Overhead Bins:Overhead bins provide secure stowage for carry-on luggage, designed for lightweight construction and structural integrity.
Leading the category by volume: Seating. Growing fastest: Lavatories, driven by hygiene mandates.
Material:
Material selection for aircraft cabin interiors prioritizes a balance of performance characteristics, including weight, durability, and flammability resistance, directly impacting fuel efficiency and safety compliance.
- Composite:Composite materials, primarily carbon fiber, offer superior strength-to-weight ratios for components like seat frames and monuments. Demand is strongest from commercial airlines seeking significant fuel efficiency gains through weight optimization.
- Metals:Metals, including aluminum alloys, provide structural integrity for critical components and are used for traditional cabin fixtures. Their application is gradually being displaced by lighter composites in non-structural elements.
- Fabric:Fabric upholstery offers cost-effective and versatile design options for economy class seating.
- Leather:Leather provides a premium aesthetic and enhanced durability for business and first-class cabin environments.
Composite materials are gaining significant share due to their weight reduction benefits, while traditional metals maintain a presence in structural applications.
End User:
Each end-user segment presents distinct procurement priorities and operational demands for cabin interior solutions, ranging from high-volume commercial operations to specialized military requirements.
- Commercial Airlines:Commercial airlines represent the largest end-user segment, driven by new aircraft deliveries and extensive cabin retrofit cycles. Their demand centers on cost-efficiency, durability, and passenger comfort for high-volume operations.
- Private Aviation:Private aviation clients seek highly customized and luxurious cabin interiors, emphasizing bespoke design and premium material integration. This segment prioritizes personalization and advanced technological features.
- Military:Military applications require rugged and functional cabin interiors, focused on durability and mission-specific configurations.
- Charter Services:Charter services balance operational flexibility with passenger comfort, often opting for reconfigurable or premium-economy style layouts.
Commercial airlines dominate the market volume, while private aviation drives innovation in customization and luxury features.
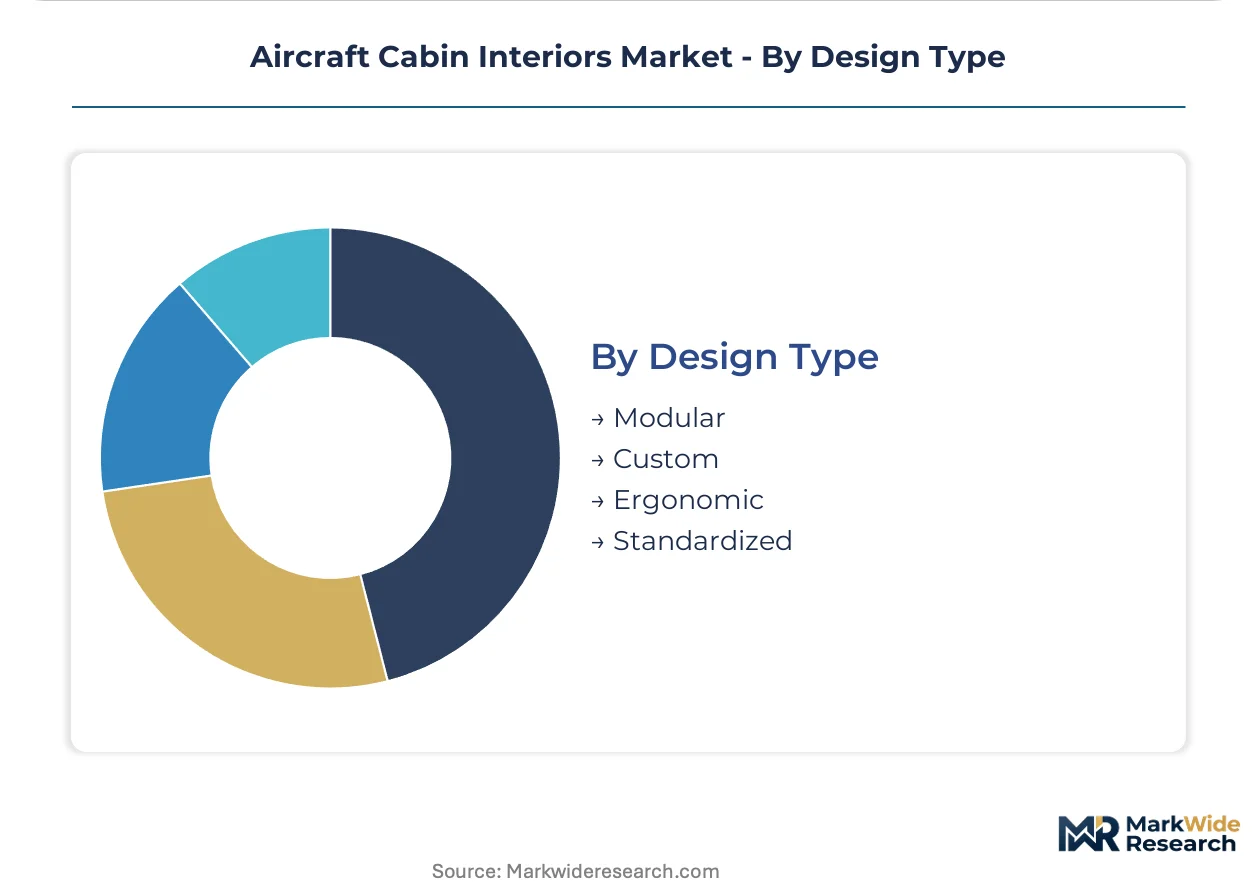
Design Type:
Design types are evolving to meet conflicting demands for operational flexibility, passenger personalization, and rapid reconfigurability within the cabin, responding to airline revenue strategies and passenger expectations.
- Modular:Modular cabin systems allow airlines to reconfigure layouts quickly, adjusting seating class-counts between flights to optimize revenue. This design type is increasingly adopted by major network carriers in Europe and North America.
- Custom:Custom designs provide unique branding and high-end aesthetics, favored by private aviation and premium commercial airline cabins. These designs often integrate advanced materials and personalized features.
- Ergonomic:Ergonomic designs prioritize passenger comfort and well-being through optimized seat contours and support features.
- Standardized:Standardized designs offer cost-effectiveness and ease of maintenance, commonly used in economy class and high-volume commercial operations.
Modular designs are gaining traction for their revenue optimization capabilities, while custom designs continue to define the premium segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for aircraft cabin interiors concentrates in regions with established aerospace manufacturing and significant commercial airline operations. These areas drive both new aircraft deliveries and extensive retrofit cycles. The focus on fuel efficiency and passenger experience shapes procurement decisions across these markets.
United States
New aircraft deliveries and premium cabin upgrades fuel demand for advanced seating and integrated systems in the United States. The FAA's FAR 25.853 mandates stringent flammability standards for all cabin components. Seattle's aerospace cluster, alongside Wichita, Kansas, drives innovation in seating and integrated systems for major airframers.
France
Commercial airlines in France fuel demand for advanced cabin solutions, particularly in lightweight materials and smart cabin integration. The European Union Aviation Safety Agency (EASA) enforces rigorous type certification for all cabin components. Toulouse, a major aerospace hub, sees significant design and manufacturing activity for cabin elements like lavatories and overhead bins.
Germany
German airlines prioritize weight optimization and enhanced passenger personalization, stimulating demand for ergonomic seating and modular systems. EASA regulations promoting lighter aircraft create a tailwind for suppliers of weight-optimized components. Hamburg's aerospace sector focuses on developing advanced composite materials for cabin interiors, improving fuel efficiency.
Japan
Japanese commercial carriers seek durable and aesthetically pleasing cabin interiors for their growing fleets and regional routes. JIS standards guide material specifications and manufacturing processes for aerospace components, ensuring high quality. Clusters around Nagoya and Tokyo support specialized suppliers focusing on integrated lighting systems and advanced galley modules.
Aircraft Cabin Interiors Market Key Industry Players
Strategic partnerships and technology licensing dominate the current landscape as airframers seek targeted innovation and specialized component suppliers. The market structure is tiered, with large system integrators providing complete cabin solutions and smaller firms specializing in specific components. Global integrators often leverage extensive portfolios, while specialized manufacturers focus on ergonomic seating or advanced material applications. Portfolio diversification and geographic expansion represent other significant competitive moves among market participants.
Specialists in integrated cabin solutions include Collins Aerospace, which exemplifies extensive portfolio strength in seating and lighting systems. Safran occupies a position as a provider of complete cabin solutions, spanning lavatories and overhead bins. RECARO Aircraft Seating represents a specialized manufacturer focusing on ergonomic and lightweight passenger seats across various airline classes. These companies anchor different segments of the value chain, from broad system integration to highly specialized component manufacturing, reflecting the industry's multi-sourcing preference.
| Leading Market Players |
|---|
| Collins Aerospace |
| Safran |
| Panasonic Avionics Corporation |
| Honeywell International Inc. |
| JAMCO Corporation |
| Diehl Aviation |
| Astronics Corporation |
| RECARO Aircraft Seating |
| Aviointeriors S.p.A |
Cost & Logistics Intelligence
Specialized technicians skilled in composite material repair concentrated in established aerospace clusters create labor-cost differentials influencing pricing tiers for complex cabin components.
Pricing Analysis
Warranty and service agreements often bundle initial product purchases with ongoing maintenance, shifting procurement from transactional capital expenditure to long-term service agreements. This model prevails for major components like seats, differentiating pricing based on customization level for premium cabins and stringent FAA/EASA certification requirements. Cost compression in economy class seating stems from high-volume orders, influencing price points. Commercial airlines demonstrate high price sensitivity for standardized components, while private aviation clients prioritize bespoke features over cost.
Supply Chain Analysis
Reverse logistics for cabin components, including refurbishment and remanufacturing of seats and lavatories, is gaining importance for sustainability and cost management. Manufacturing concentrates in the United States, France, and Germany, forming established aerospace clusters. Carbon fiber, aluminum alloys, and specialized fire-retardant resins are critical inputs for cabin interiors. Commodity price volatility for aerospace-grade carbon fiber creates a structural supply chain risk, with distribution primarily running through direct contracts between component manufacturers and airframers or airlines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Aircraft Cabin Interiors market presents a cost-of-compliance story, where strict FAA FAR 25.853 flammability standards create a barrier-to-entry moat for compliant players.
For Market Incumbents: Deepen strategic partnerships with major airframers and airlines to secure long-term service agreements for integrated cabin solutions. Invest in advanced R&D for next-generation lightweight composite materials to counter the threat of new entrants with superior material science. Accelerate certification investments for new components to maintain a competitive edge and navigate stringent regulatory oversight from bodies like EASA.
For New Entrants and Emerging Players: Additive manufacturing technology offers a technology-first wedge for producing complex, lightweight non-structural cabin parts like brackets and trim pieces. Target the expanding Maintenance, Repair, and Overhaul (MRO) market in Asia, specifically India and Southeast Asia, for retrofit parts. Focus on smart cabin integration solutions for regional carriers, leveraging localized production to reduce spare part inventories and aircraft-on-ground time.
For Investors and Strategic Acquirers: The window for entry favors patient investors seeking long-term value creation through consolidation within specialized component manufacturing over the next decade. Target vertically integrated mid-cap specialists with strong intellectual property in ergonomic seating or advanced composite materials. The signal to watch is an uptick in M&A activity among these niche players, indicating market maturation and opportunity for strategic roll-ups.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Composite Manufacturing Capacity | Reduces material cost volatility for carbon fiber, improving margin stability for component manufacturers. |
| Develop Modular Cabin Systems | Allows airlines to quickly reconfigure layouts, maximizing revenue on specific routes for major network carriers. |
| Invest in Smart Cabin IoT Integration | Creates new recurring revenue streams from predictive maintenance data for seats and galleys. |
| Acquire Specialized MRO Providers in Asia | Captures growing demand for retrofit parts and maintenance services in India and Southeast Asia. |
| Enhance Antimicrobial Surface Technologies | Addresses heightened focus on cabin air quality and hygiene, meeting new commercial airline specifications. |
Research Approach
Multi-period observation of new aircraft deliveries and cabin retrofit cycles anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with airframe engineers, airline procurement officers, MRO specialists, and material scientists. Secondary data sources included FAA and EASA certification databases, IATA traffic reports, and company annual reports. A bottom-up and top-down triangulation approach validated market sizing and growth projections.
The segment-weighting approach informed the quantitative model, disaggregating the market by component type, material, end user, and design type. This framework projected market evolution across the analysis window, incorporating regional regulatory compliance as a key dimension. Compound annual growth rates were calculated based on historical trends and future outlooks. Key forecast inputs included airline fleet expansion plans and advancements in composite material innovation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme fuel price volatility or global health crises. Forecasts reflect assumptions regarding economic stability and technological adoption, where significant supply chain disruptions or new regulatory mandates could necessitate revisions. Material deviation in certification timelines or air travel demand warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aircraft Seat Upholstery Market
Aircraft Cabin Interior
Aerospace Floor Panels Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Global Composites in the Aerospace Interior Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Asia-Pacific Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aerospace Interior Adhesive Market
Aircraft Cabin Interior
Cabin Interior Composites Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Seating Market
Aircraft Cabin Interior
Aircraft Floor Panels Market
Aircraft Cabin Interior
Aviation Carpet Market
Aircraft Cabin Interior
Global Commercial Aviation Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market