
 Aerospace Additive Manufacturing Market | 2026-2036
Aerospace Additive Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Additive Manufacturing Market Analysis
Aftermarket service revenue from legacy component replacement is narrowing as airlines qualify printed spare parts for direct installation. GE Additive leverages its vertical position across powder supply and machine architecture to capture value from engine component production. EOS GmbH dominates industrial metal laser sintering systems for flight-certified titanium structures. Stratasys Ltd. specializes in polymer tooling and cabin interior fixtures where FAA flammability standards apply.
Aerospace additive manufacturing produces metallic, polymer, and composite components through layer-by-layer deposition guided by digital CAD models, achieving near-net-shape geometries with buy-to-fly ratios below three-to-one in titanium alloys. Selective Laser Sintering of nickel superalloys anchors engine component production where thermal management properties exceed cast equivalents. Fused Deposition Modeling occupies non-structural polymer applications including ducting and brackets where weight reduction drives fuel efficiency. Electron Beam Melting competes for dense titanium structural elements in satellite and launch vehicle frames where porosity thresholds fall below one percent.
FAA certification protocols under 14 CFR Part 21 govern airworthiness approval of additively manufactured structural elements, while EASA's AMC 20-42 establishes comparable European qualification pathways for metal powder bed fusion. The EU AI Act and CSRD disclosure rules are reshaping documentation requirements for automated build monitoring and supply chain emissions tracking. Stakeholders must weigh capital allocation between machine capacity expansion and qualification engineering as regulatory convergence across FAA and EASA frameworks determines market access velocity.
Market Dynamics
FAA and EASA certification pathway convergence is compressing qualification timelines for flight-critical printed components, forcing capital reallocation between machine capacity expansion and regulatory engineering resources.
Growth Catalysts
- Defense Aviation Procurement:United States military programs are qualifying printed titanium structural elements for combat aircraft under accelerated airworthiness protocols. Flight-critical component adoption is expanding beyond prototyping into serial production.
- CSRD Disclosure Mandates:European sustainability reporting rules are requiring automated build monitoring and emissions documentation across aerospace supply chains. Metal powder bed fusion operations are investing in real-time process traceability systems.
- Titanium Buy-to-Fly Ratios:Near-net-shape geometries are reducing material waste in engine bracket and satellite frame production. Powder bed fusion is displacing machined-from-solid legacy methods in weight-critical applications.
Market Restraints
- Nickel Superalloy Powder Supply:Gas atomization capacity constraints are creating input cost volatility for engine component producers. Inconel 718 and 625 powder specifications face limited qualified supplier bases.
- Electron Beam Melting Equipment Concentration:Dense titanium structural printing for satellite frames depends on a narrow geography of system manufacturers. Beam control and vacuum chamber maintenance expertise concentrates in Northern European industrial clusters.
- FAA Part 21 Certification Friction:Structural element airworthiness approval requires extensive mechanical testing and statistical process control documentation. Small and mid-tier suppliers lack resources to navigate qualification timelines independently.
Strategic Opportunities
- India Defense Manufacturing Corridors:Tamil Nadu and Karnataka aerospace clusters are attracting metal additive capacity for indigenous fighter and helicopter programs. PLI scheme incentives are offsetting initial qualification engineering costs.
- Digital Twin Integration:Convergence of in-situ process monitoring with predictive maintenance platforms is enabling outcome-based spare part supply contracts. Airlines are piloting printed component lifecycle tracking from build to retirement.
- Polymer Cabin Interior Applications:Fused Deposition Modeling is penetrating non-structural ducting and bracket markets where FAA flammability standards previously blocked polymer adoption. Weight reduction targets are forcing specification reviews.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Thermal and residual stress modeling for laser powder bed fusion requires specialized computational mechanics expertise. Universities are struggling to produce graduates with combined materials science and process simulation skills.
- Post-Processing Capital Intensity:Hot isostatic pressing, CNC finishing, and surface treatment equipment require substantial fixed investment beyond printer acquisition. Build-to-finish workflow integration is straining balance sheets.
- IP Fragmentation Across Process Parameters:Proprietary laser scan strategies and support structure designs are creating licensing complexity between machine OEMs and contract manufacturers. Patent thickets are slowing technology transfer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Additive Manufacturing Market |
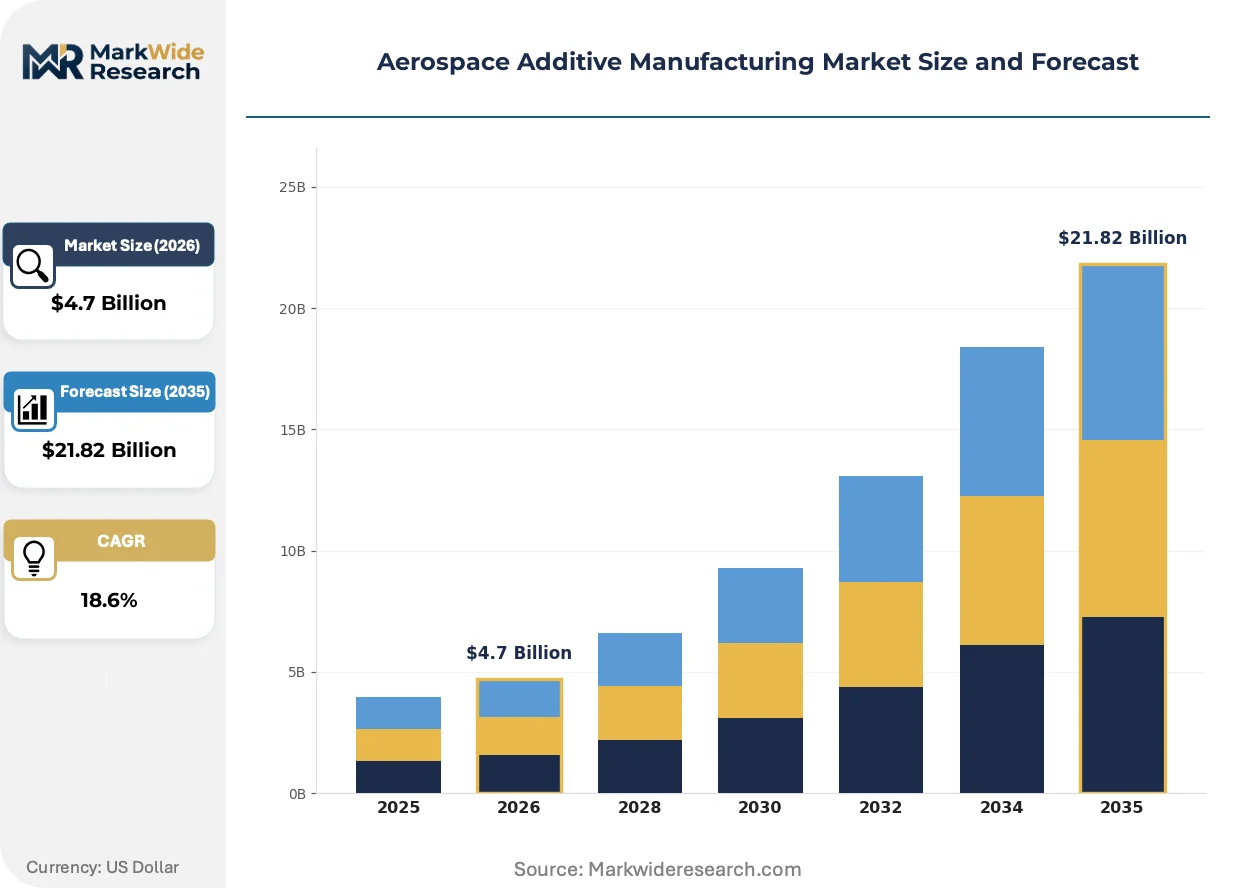
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Components, Polymer Parts, Composite Materials, Prototype Models Technology: Selectively Laser Sintering, Fused Deposition Modeling, Electron Beam Melting, Binder Jetting Application: Structural Parts, Engine Components, Interior Fittings, Spare Parts End User: OEMs, Tier-1 Suppliers, Maintenance Providers, Research Institutions |
| Companies Covered | 3D Systems Corporation, GE Additive, Stratasys Ltd., EOS GmbH, Airbus SE, Materialise, SLM Solutions Group AG, Norsk Titanium AS, Velo3D, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Additive Manufacturing Market Emerging Trajectories
Process automation and regulatory digitization are converging to reshape how flight-certified components move from design to installation.
Directed Energy Deposition is migrating from repair and remanufacturing applications into full-rate production of large titanium aerostructures. Space launch vehicle manufacturers are adopting wire-fed systems for fuel tank domes and interstage skirts. Build volumes exceeding two meters are compressing lead times for traditionally forged components.
EASA's AMC 20-42 framework is establishing equivalence with FAA pathways for metal powder bed fusion qualification. European engine OEMs are consolidating certification documentation across dual-jurisdiction programs. German and French aerospace clusters are investing in shared qualification testing facilities to amortize regulatory compliance costs.
Airline technical procurement teams are consolidating vendor bases around suppliers with integrated design-to-certification capabilities. Legacy tiered sourcing structures separating design houses, printers, and finishers are compressing into single-accountability contracts. North American and Middle Eastern carriers are piloting direct digital spare part procurement platforms that bypass traditional distribution channels.
Aerospace Additive Manufacturing Market Segmentation
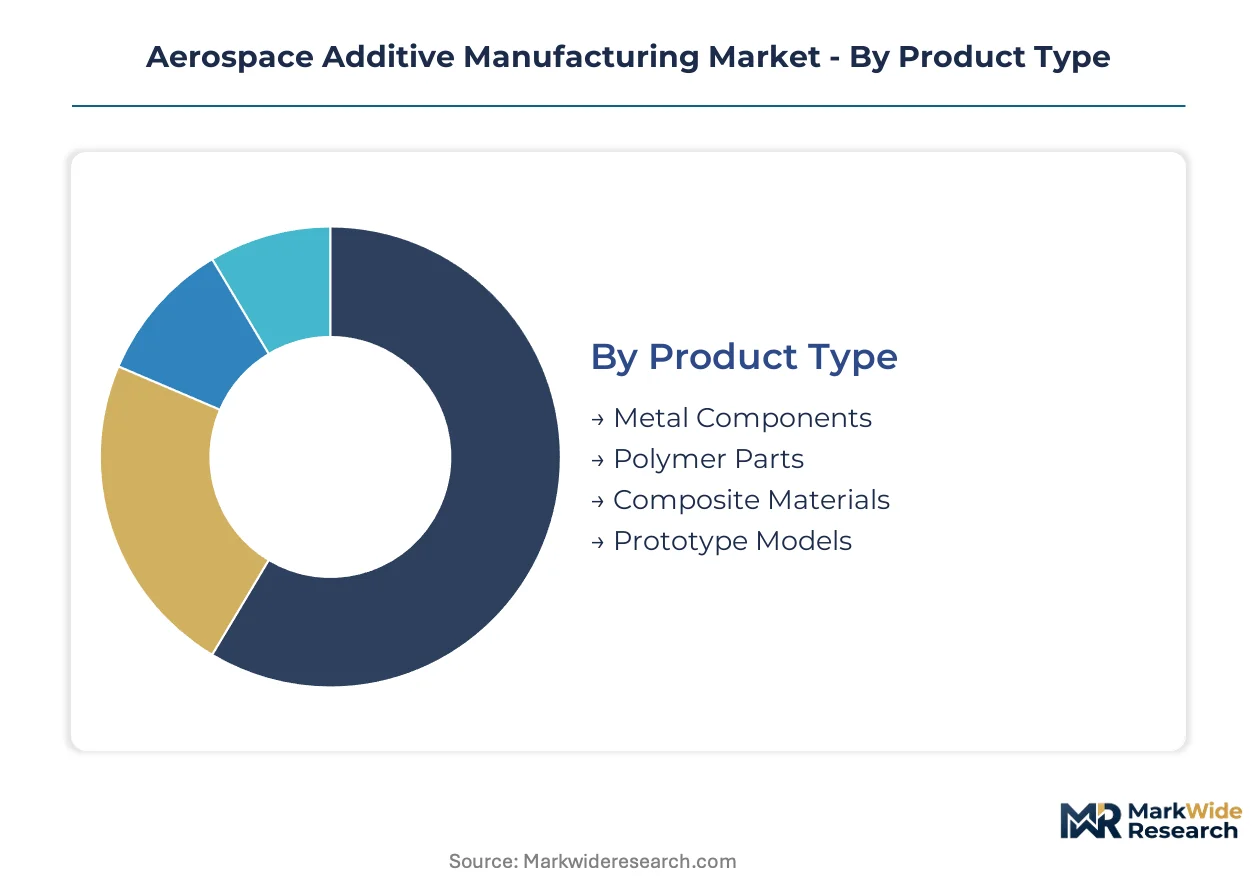
Segmentation in aerospace additive manufacturing reveals how material constraints, certification pathways, and production economics partition value capture across the value chain. Each dimension—product, technology, application, and buyer type—carries distinct margin profiles and qualification burdens that reshape supplier positioning.
Product Type:
Mature structural metals coexist with emerging polymer and composite categories as certification frameworks mature.
- Metal Components:Titanium and nickel superalloy parts dominate flight-critical applications through powder bed fusion. Engine brackets and satellite frames in Germany's Munich cluster absorb the bulk of industrial laser sintering capacity as FAA Part 21 pathways stabilize.
- Polymer Parts:PEEK and ULTEM formulations penetrate cabin interiors where FAA flammability standards have eased. Ducting and non-structural brackets for weight reduction programs concentrate in French aerospace supply chains around Toulouse.
- Composite Materials:Continuous fiber-reinforced deposition occupies repair and remanufacturing niches.
- Prototype Models:Rapid validation parts serve design iteration cycles with minimal certification overhead.
Metal Components retain volume leadership; Polymer Parts hold the steepest expansion curve.
Technology:
Cost tiers separate capital-intensive metal systems from accessible polymer platforms.
- Selectively Laser Sintering:Powder bed fusion of titanium and Inconel anchors certified production with buy-to-fly ratios below three-to-one. EOS GmbH systems in Hamburg process flight-critical nickel superalloys for engine OEMs facing CSRD emissions documentation mandates.
- Fused Deposition Modeling:Extrusion-based polymer printing scales rapidly for interior fixtures. Stratasys equipment dominates cabin bracket production where thermoplastic mechanical properties satisfy non-structural load requirements.
- Electron Beam Melting:Vacuum-based titanium processing serves satellite frame manufacturers demanding porosity thresholds under one percent.
- Binder Jetting:Emerging metal shaping technology targets medium-complexity structural elements without thermal distortion risks.
Selectively Laser Sintering commands the premium tier; Fused Deposition Modeling scales most quickly.
Application:
Customer type fragmentation splits the market between serialized production and aftermarket service.
- Structural Parts:Titanium brackets and satellite frames require full FAA airworthiness certification with extensive mechanical testing. Launch vehicle manufacturers in the United States qualify dense components through statistical process control documentation.
- Engine Components:Nickel superalloy turbine blades and combustor liners demand thermal management properties exceeding cast equivalents. GE Additive's vertical integration across powder supply and machine architecture captures value here.
- Interior Fittings:Polymer ducting and trim panels face lighter regulatory burdens.
- Spare Parts:Digital inventory models disrupt legacy distribution for aging fleet support.
Structural Parts absorb the heaviest qualification investment; Spare Parts gain share fastest through digital warehousing.
End User:
Supply concentration clusters around integrated design-to-certification capabilities versus fragmented service providers.
- OEMs:Airbus SE and Boeing internalize metal printing for proprietary airframe designs with captive qualification engineering. Direct production control insulates against tiered supplier IP fragmentation.
- Tier-1 Suppliers:Specialized contract manufacturers aggregate build capacity across multiple airframe programs. Post-processing capital intensity for hot isostatic pressing and CNC finishing strains balance sheets.
- Maintenance Providers:Airlines pilot printed spare part procurement bypassing traditional distribution.
- Research Institutions:Universities struggle to produce graduates with combined materials science and multiphysics simulation expertise.
OEMs retain margin control; Tier-1 Suppliers face the steepest capital reallocation pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense aviation programs in the United States consume flight-critical titanium structures at volumes unmatched elsewhere, while Germany's industrial clusters specialize in nickel superalloy engine components and India's emerging corridors prioritize qualification engineering for indigenous platforms.
United States
Combat aircraft modernization and space launch vehicle production drive titanium structural element demand. FAA Part 21 certification protocols govern airworthiness approval timelines. Defense manufacturing concentrates in California's aerospace corridor and Texas launch facilities.
Germany
Engine OEM procurement and satellite frame production anchor nickel superalloy powder bed fusion capacity. EASA's AMC 20-42 framework streamlines European qualification pathways. Munich and Hamburg industrial clusters host EOS GmbH and Airbus SE metal printing operations.
France
Turbine blade remanufacturing and cabin interior polymer applications sustain dual technology demand. REACH chemical safety regulations shape powder handling compliance. Toulouse aerospace supply chains specialize in PEEK ducting and non-structural brackets.
India
Indigenous fighter and helicopter programs accelerate metal additive adoption through defense procurement mandates. PLI scheme incentives offset initial qualification engineering investments. Tamil Nadu and Karnataka aerospace clusters attract build capacity for flight-critical components.
United Kingdom
Space sector launch vehicle frames and satellite structures demand dense titanium with sub-one-percent porosity thresholds. UK Space Agency funding supports process qualification for commercial space manufacturing. Greater London and Southwest England clusters concentrate electron beam melting expertise.
Aerospace Additive Manufacturing Market Vendor Landscape
Capability concentration sits with integrated design-to-certification specialists; scale advantage sits with diversified industrial conglomerates. The vendor base separates into three tiers: machine OEMs controlling powder bed fusion architecture, contract manufacturers aggregating build capacity, and aerospace primes internalizing production for proprietary designs. Strategic moves center on captive powder supply integration and shared qualification facility investments to amortize regulatory compliance costs.
Within the machine architecture tier, EOS GmbH and SLM Solutions Group AG exemplify European laser sintering specialization, while GE Additive represents diversified industrial conglomerate verticalization across powder supply and qualification engineering. Norsk Titanium AS anchors Nordic electron beam melting capability for dense structural applications.
| Leading Market Players |
|---|
| 3D Systems Corporation |
| GE Additive |
| Stratasys Ltd. |
| EOS GmbH |
| Airbus SE |
| Materialise |
| SLM Solutions Group AG |
| Norsk Titanium AS |
| Velo3D |
| Others |
Supply Flow & Price Mechanics
Gas atomization capacity in Germany and the United States concentrates nickel superalloy powder supply for flight-critical components, anchoring margin capture with engine OEMs and Tier-1 suppliers who internalize build-to-finish workflows. Powder bed fusion machine architecture controlled by EOS GmbH and SLM Solutions Group AG creates tiered access to qualified production, with pricing power flowing to holders of FAA Part 21 certification documentation.
Pricing Analysis
Long-term offtake agreements dominate nickel superalloy powder procurement as engine OEMs lock in gas atomization capacity from qualified suppliers. Price differentiation rests on certification grade—FAA Part 21 versus non-flight-critical tiers—and volume scale for serial production programs. Cost compression in polymer cabin interior components is intensifying as Fused Deposition Modeling equipment depreciates across Stratasys Ltd. installed bases. Airlines represent the most price-sensitive buyers for spare parts, while defense procurement programs absorb premium pricing for titanium structural elements with full traceability documentation.
Supply Chain Analysis
Contract manufacturing concentration sits with German Tier-1 suppliers around Munich and Hamburg, where EOS GmbH and Airbus SE anchor industrial-scale metal printing operations. Raw material dependencies center on titanium sponge from Ukraine and Kazakhstan, nickel powder from Russia and Canada, and polymer feedstock from Saudi Arabia and the United States. Single-source vulnerability in electron beam melting vacuum chamber systems creates chokepoint risk for satellite frame producers. Distribution runs through direct digital procurement platforms that bypass traditional aerospace parts distributors for printed spare components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as defense aviation procurement accelerates flight-critical component adoption beyond prototyping into serial production.
For Market Incumbents: Entrench qualification engineering capabilities as the primary defensive moat against emerging contract manufacturers in India and Southeast Asia. Deepen backward integration into gas atomized powder supply to offset Inconel 718 input cost volatility. Expand shared testing facility investments across German and French aerospace clusters to amortize EASA AMC 20-42 compliance burdens. For New Entrants and Emerging Players: Build out digital twin integration capabilities for outcome-based spare part supply contracts with Middle Eastern and North American carriers. Target polymer cabin interior applications as the most penetrable segment where FAA flammability standard revisions have eased regulatory barriers. Pursue qualification engineering partnerships with established machine OEMs to accelerate FAA Part 21 pathway navigation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturers holding stranded post-processing capacity for hot isostatic pressing and CNC finishing. The five-to-ten year viability window favors acquisition of design-to-certification specialists with integrated build-finish-test workflows. Monitor FAA-EASA regulatory convergence velocity as the critical inflection signal for market access velocity and valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Powder Supply Integration | GE Additive's upstream control over gas atomization capacity insulates engine component margins from nickel superalloy input volatility. |
| Shared Qualification Facility Investment | German aerospace clusters amortize EASA AMC 20-42 compliance costs across Airbus SE and engine OEM certification programs. |
| Digital Twin Platform Deployment | Airlines piloting printed component lifecycle tracking from build to retirement enable outcome-based spare part procurement contracts. |
| Polymer Flammability Certification | Stratasys Ltd. penetrates cabin interior markets as FAA revises flammability standards for PEEK and ULTEM formulations. |
| India Defense Manufacturing Corridor Entry | PLI scheme incentives in Tamil Nadu offset qualification engineering costs for indigenous fighter and helicopter programs. |
Methodological Framework
A standing panel of additive manufacturing engineering directors, FAA certification specialists, airline technical procurement managers, and defense program supply officers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with machine OEM product strategists and contract manufacturing operations heads with secondary validation against EASA AMC 20-42 documentation, FAA Part 21 guidance materials, and CSRD disclosure rule filings. Bottom-up build-ups of installed machine bases and powder consumption volumes triangulated against top-down aerospace production forecasts.
Scenario-bracketing around defense procurement acceleration and regulatory pathway convergence shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology platform, application category, and end-user archetype, with additional granularity on certification tier and geographic production cluster. CAGRs derived from elasticity-adjusted demand curves incorporating titanium buy-to-fly ratio improvements and polymer weight reduction program adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indian defense manufacturing corridors or accelerated FAA-EASA harmonization would shift outcomes beyond modeled ranges. Quarterly review of defense procurement award flows, nickel superalloy powder spot pricing, and EASA AMC 20-42 implementation guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerographite Market
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Aerospace Fluoropolymers Market
Aerospace and Aircraft Materials
Commercial Aerospace 3D Printing Market
Aerospace and Aircraft Materials
Additive Manufactured Pressure Vessel Proof and Burst Test Rigs Market
Aerospace and Aircraft Materials
Aircraft Soft Goods Market
Aerospace and Aircraft Materials
Aerospace Composites Market
Aerospace and Aircraft Materials
Global Anti-Icing Coating Market
Aerospace and Aircraft Materials
Out-of-Autoclave Composite Skin Panels for Regional and Business Jets Market
Aerospace and Aircraft Materials
Aerospace and Defense Metal Stamping Market
Aerospace and Aircraft Materials
Global Aerospace Insulation Market
Aerospace and Aircraft Materials
Aerospace High-Performance Alloys Market
Aerospace and Aircraft Materials
Global Aerospace Titanium Machining Market
Aerospace and Aircraft Materials
Russia Space Electronics Market
Aerospace and Aircraft Materials
Commercial Aircraft Materials Market
Aerospace and Aircraft Materials
Aerospace Ceramic Matrix Composites Market