
 Glass Syringe Market | 2026-2036
Glass Syringe Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Syringe Market Intelligence
ISO 11040-4 qualification for prefilled glass syringes is reorganizing supplier eligibility across pharmaceutical packaging tiers. Gerresheimer AG leverages integrated borosilicate glass tube-to-syringe manufacturing to control quality continuity. SCHOTT Pharma anchors its position through proprietary FIOLAX glass chemistry optimized for parenteral drug stability. Nipro Corporation competes via differentiated coating technologies that reduce protein adsorption on glass surfaces.
Glass syringes consist of precision-formed borosilicate glass barrels with matched plunger systems, typically manufactured through controlled thermal forming and siliconization processes to achieve break-resistance below 2% and extractable limits meeting pharmacopeial standards. Their primary purpose centers on delivering sterile injectable therapies while eliminating drug-container interaction risks inherent in polymer alternatives. Luer Lock Syringes command structural priority in biologics administration where connection security prevents medication errors, while Safety Syringes represent the fastest-expanding segment as needlestick prevention mandates proliferate across healthcare settings. Home Healthcare emerges as a concentrated margin pool where patient self-administration protocols demand intuitive glass syringe designs with integrated safety mechanisms.
FDA device master file requirements and EMA's Medical Device Regulation (MDR) classification for prefilled syringes are elevating documentation burdens and clinical evidence thresholds for market access. ISO 11040 series standards and USP <661.1> glass extractables testing collectively define the technical compliance perimeter that determines supplier qualification status. Stakeholders must monitor evolving pharmacopeial glass delamination guidance and assess whether in-house siliconization capabilities or outsourced coating partnerships better align with accelerating biologics pipeline demands.
Market Dynamics
ISO 11040-4 qualification requirements are restructuring supplier eligibility across pharmaceutical packaging tiers, forcing manufacturers to consolidate quality documentation and siliconization capabilities under unified control.
Growth Catalysts
- Biologics pipeline expansion:Monoclonal antibody and cell therapy developers are mandating prefilled glass syringes to eliminate drug-container interaction risks that polymer alternatives cannot address.
- FDA device master file tightening:Updated documentation standards for glass primary packaging are accelerating supplier consolidation toward integrated borosilicate tube-to-syringe manufacturers.
- German production clustering:Specialized glass formation expertise concentrates in the Rhine-Main region, anchoring supply security for European biopharma fill-finish operations.
Market Restraints
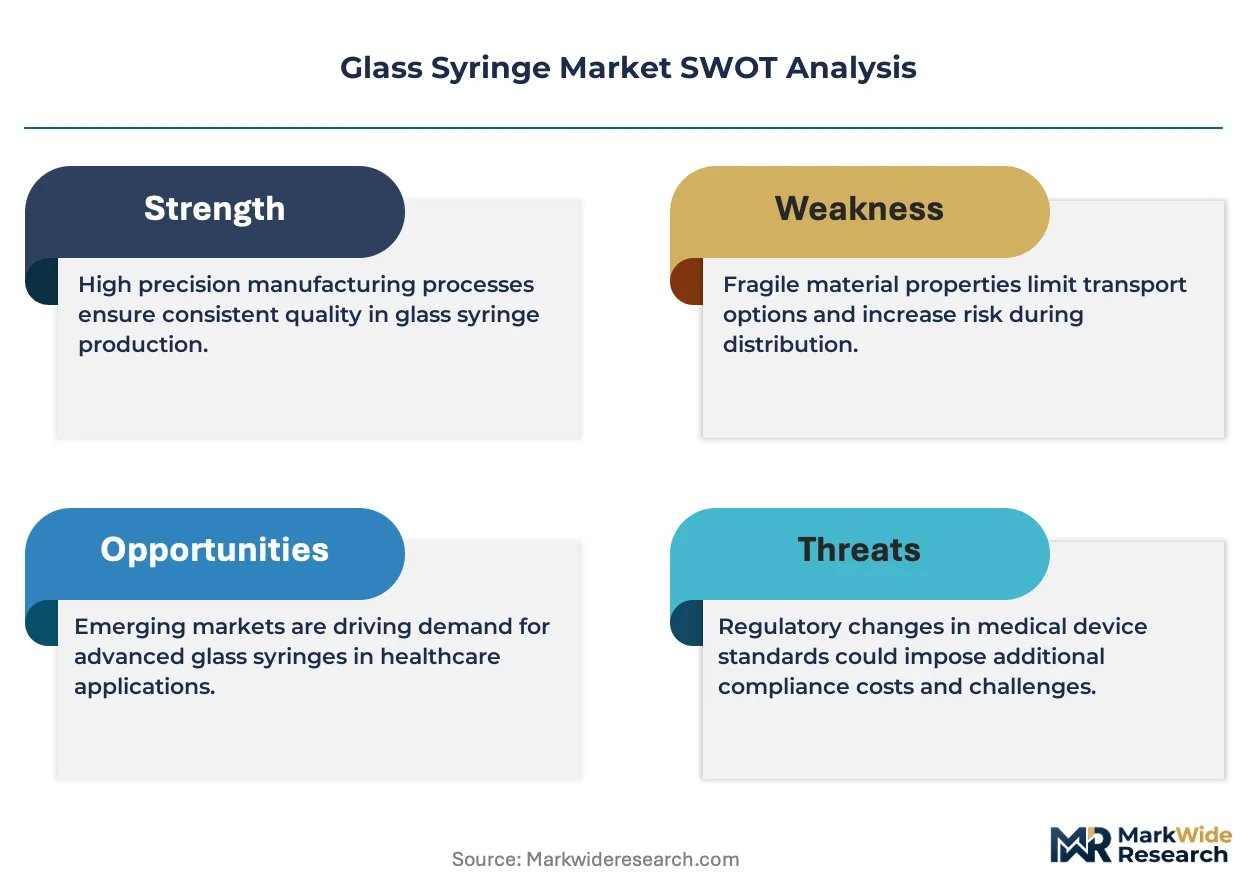
- Borosilicate glass supply concentration:FIOLAX and equivalent pharmaceutical-grade tubing production remains captive to three specialized melt facilities worldwide.
- Siliconization cost volatility:Medical-grade silicone oil prices fluctuate with semiconductor feedstock markets, compressing margin on coated syringe variants.
- Polymer substitution pressure:Cyclic olefin polymer syringes are capturing volume in non-biologic generics where protein stability concerns do not apply.
Strategic Opportunities
- Home healthcare self-administration:Rheumatology and endocrinology patients require intuitive glass syringe designs with integrated needlestick prevention for subcutaneous injection protocols.
- EMA MDR classification alignment:Prefilled syringe device reclassification creates first-mover advantage for suppliers with established notified body relationships.
- Coating technology convergence:Plasma-deposited barrier layers combined with traditional siliconization are opening pH-sensitive biologic formulations previously incompatible with glass.
Industry Challenges
- Pharmacopeial glass delamination expertise:Analytical chemists capable of predictive glass stability modeling remain scarce relative to accelerated biologics pipeline timelines.
- ISO 11040-4 certification timelines:Notified body backlogs extend qualification cycles to 18-24 months, delaying new supplier market entry.
- Legacy fill-finish line retrofit complexity:Automated inspection systems designed for polymer syringes require vision algorithm retraining for glass optical properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Syringe Market |
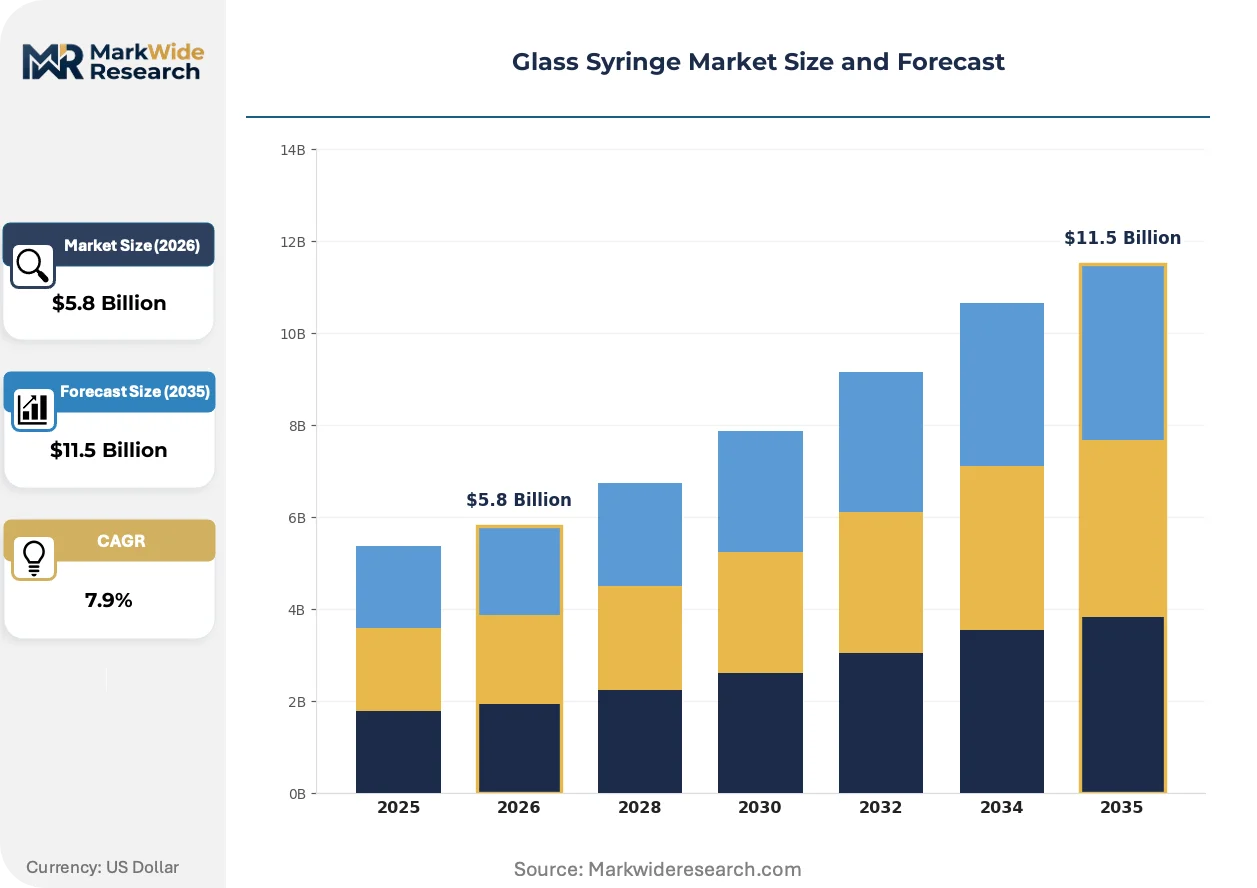
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Syringes, Luer Lock Syringes, Safety Syringes, Specialty Syringes End User: Hospitals, Clinics, Diagnostic Labs, Home Healthcare Application: Vaccination, Anesthesia, Blood Sampling, Fluid Administration Packaging Type: Sterile Packs, Bulk Packs, Display Boxes, Cartons |
| Companies Covered | Gerresheimer AG, Nipro Corporation, Stevanato Group, SCHOTT Pharma, BD, Terumo Corporation, GROUPE GUILLIN, Ampulla Ltd., Ompi srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Syringe Market Strategic Shifts & Innovations
Glass syringe manufacturing is experiencing fundamental process reorganization as quality standards tighten and end-use applications diversify beyond traditional hospital settings.
Siliconization is decomposing from a commodity coating step into a precision-controlled drug-container interface engineering discipline. Biologics manufacturers now specify silicone oil distribution profiles by therapeutic protein class. This specification depth is decomposing the supplier base into integrated coating-capable manufacturers versus tube-only merchants unable to meet documentation burdens.
EMA's Medical Device Regulation reclassification of prefilled syringes as Class III devices is elevating clinical evidence requirements for market authorization. German and French notified bodies are processing submission backlogs extending qualification timelines. High-value biologics developers are responding by locking in dual-source supply agreements with established MDR-compliant manufacturers.
Hospital procurement departments are consolidating purchasing through specialized pharmaceutical distributors rather than direct manufacturer relationships. This channel compression is most visible in German and Swiss acute care networks, where group purchasing organizations now negotiate multi-year prefilled syringe supply contracts with integrated safety feature specifications.
Glass Syringe Market Segmentation
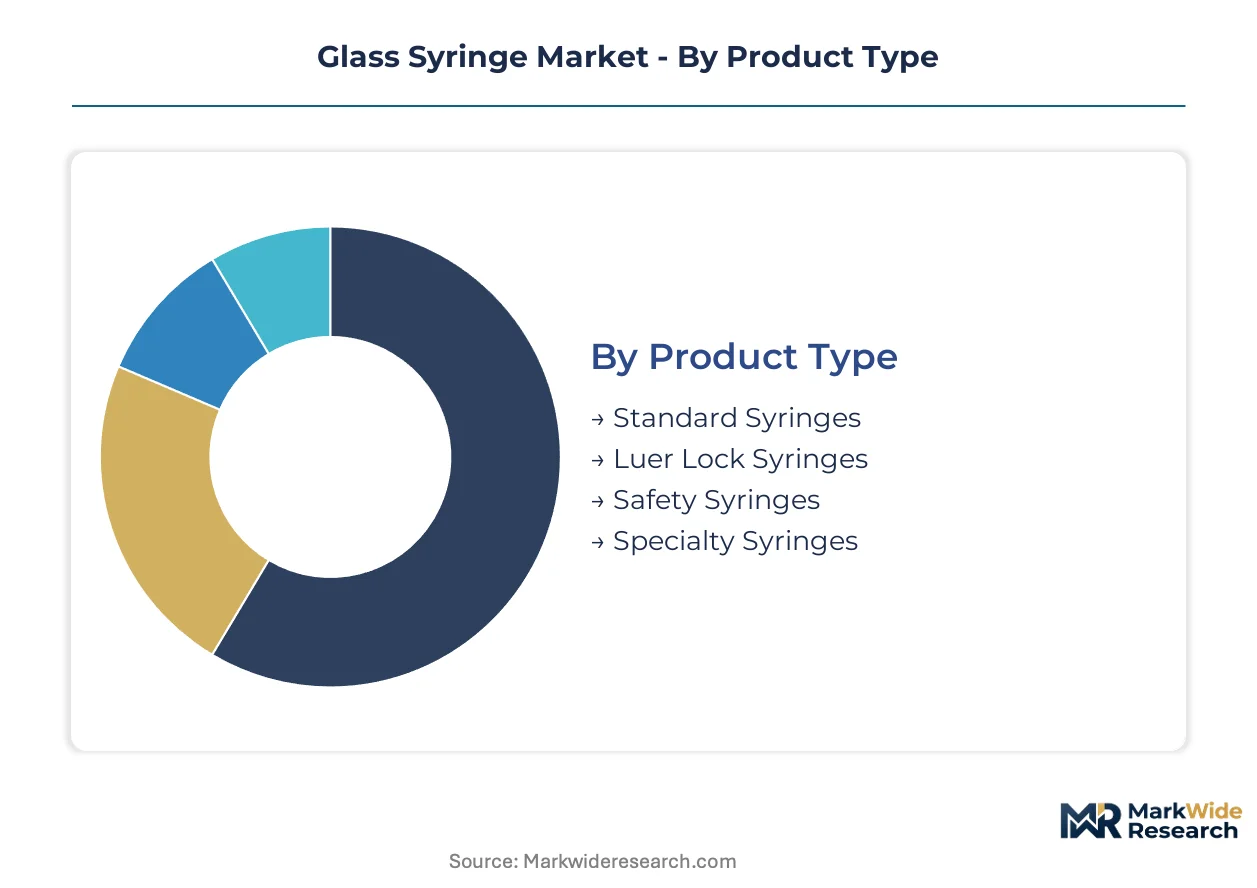
Glass syringe segmentation reflects divergent technical requirements across clinical settings and regulatory exposure levels. Product architecture, end-user protocols, and packaging integrity standards each create distinct margin architectures that suppliers must navigate simultaneously.
Product Type:
Margins concentrate in connection-security and needlestick-prevention variants where liability exposure and clinical protocol rigor intersect.
- Luer Lock Syringes:Threaded hub connections prevent accidental disengagement during high-pressure biologics administration. Oncology and rheumatology infusion centers in Germany and Switzerland specify ISO 594-2 compliant Luer Lock configurations for monoclonal antibody delivery, where medication error liability drives premium positioning.
- Safety Syringes:Integrated needle retraction or shielding mechanisms activate post-injection to prevent healthcare worker needlestick injuries. US OSHA Bloodborne Pathogens Standard compliance mandates are accelerating hospital conversion, with retractable designs gaining preference over sliding shields in acute care settings.
- Standard Syringes:Slip-tip configurations serve cost-sensitive diagnostic and research applications where connection security requirements remain minimal.
- Specialty Syringes:Prefilled formats with staked needles or dual-chamber designs address lyophilized drug reconstitution and fixed-dose vaccines.
Luer Lock Syringes hold installed capacity. Safety Syringes are rotating up the share rankings.
End User:
Channel economics vary sharply between institutional procurement scale and patient-directed consumption patterns.
- Home Healthcare:Self-administration of diabetes, multiple sclerosis, and growth hormone therapies demands intuitive designs with integrated needlestick prevention. FDA combination product regulations and EMA MDR classification apply to prefilled formats, elevating documentation burdens that favor established suppliers with notified body relationships.
- Hospitals:Acute care networks in Germany and Switzerland consolidate purchasing through group purchasing organizations, negotiating multi-year contracts with safety feature specifications and siliconization quality guarantees.
- Clinics:Outpatient settings balance cost containment with occupational safety compliance, often selecting passive safety mechanisms over active retraction for budget predictability.
- Diagnostic Labs:Blood collection and specimen handling prioritize volume throughput and sterility assurance over advanced safety engineering.
Hospitals anchor volume concentration. Home Healthcare is climbing the fastest as biologics self-administration protocols proliferate.
Application:
Different use cases impose distinct extractables limits, siliconization profiles, and compatibility testing requirements.
- Vaccination:Mass immunization programs require high-volume, single-dose formats with staked needles and fixed dosing. WHO prequalification standards and national immunization program tenders in India and Brazil drive specification harmonization.
- Anesthesia:Glass syringes for propofol and neuromuscular blockers demand lipid compatibility and low protein binding surfaces. USP <661.1> extractables testing and US FDA device master file documentation support regulatory submission packages.
- Blood Sampling:Vacuum tube compatibility and precise volume graduation markings serve clinical laboratory workflows.
- Fluid Administration:Irrigation and enteral feeding applications tolerate broader material specifications than parenteral drug delivery.
Vaccination commands the largest unit volumes. Anesthesia is expanding most quickly as ambulatory surgical center utilization rises.
Packaging Type:
Packaging configuration directly determines shelf-life validation requirements and distribution channel access.
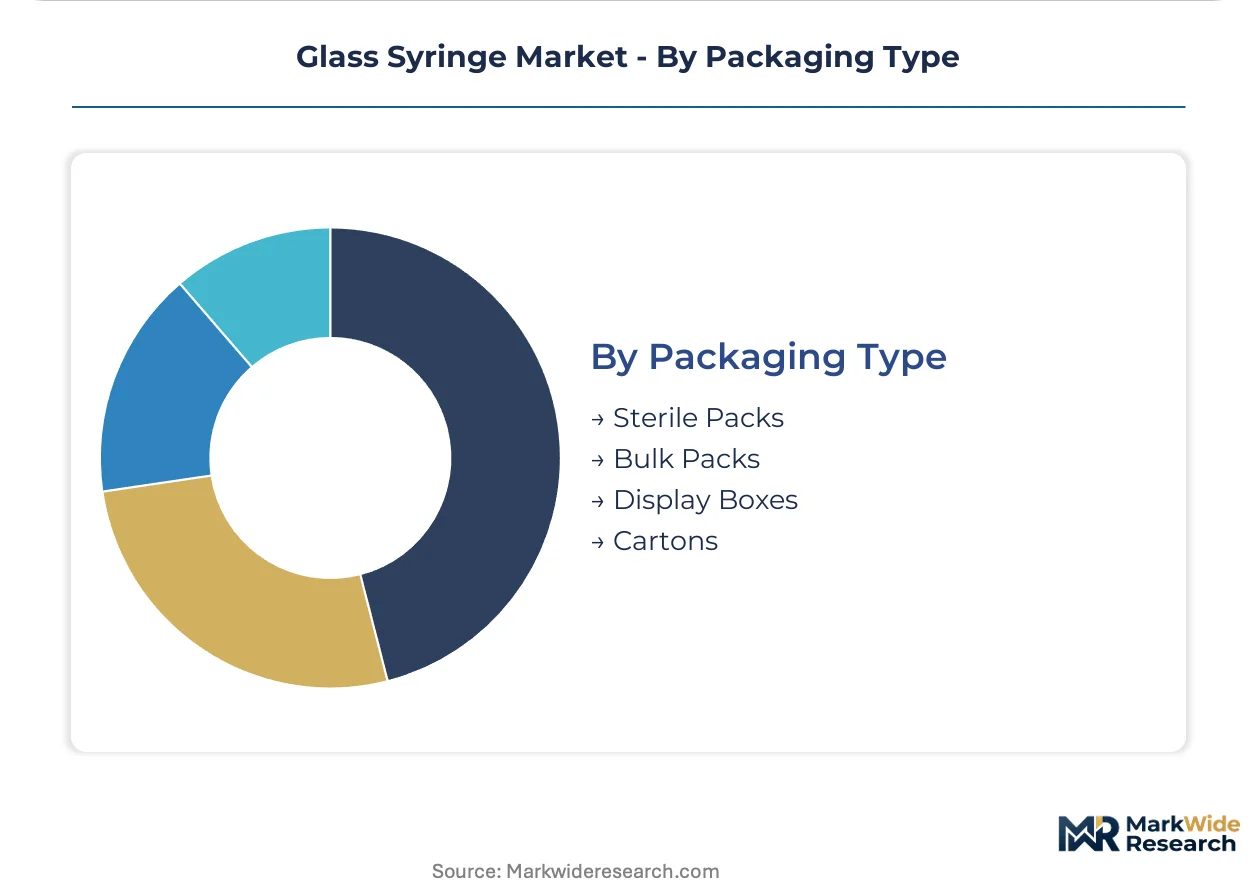
- Sterile Packs:Individual blister or peel-pouch configurations maintain sterility assurance through terminal sterilization and barrier validation. EMA Annex 1 manufacturing guidelines and FDA sterile drug product requirements govern validation protocols.
- Bulk Packs:Multi-unit configurations serve institutional customers with in-house sterilization capabilities or immediate consumption patterns.
- Display Boxes:Retail-oriented packaging supports pharmacy and home healthcare channel presentation requirements.
- Cartons:Intermediate configurations balance shipping efficiency with point-of-use accessibility for mid-scale clinical operations.
Sterile Packs dominate biologics and vaccine applications. Bulk Packs are gaining share fastest in generics manufacturing and research supply channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA device master file tightening and EMA MDR reclassification are redirecting prefilled syringe procurement toward jurisdictions with established notified body infrastructure. Germany, the United States, Switzerland, Japan, and India each concentrate distinct supply chain functions.
Germany
Biologics fill-finish operations in the Rhine-Main region consume specialized borosilicate glass tubing from Wertheim and Mitterteich melt facilities. EMA MDR Class III device classification mandates clinical evidence packages that favor incumbent suppliers with BfArM relationships. Gerresheimer AG and SCHOTT Pharma anchor integrated tube-to-syringe manufacturing clusters in Hesse and Bavaria.
United States
Monoclonal antibody developers in Massachusetts and California specify prefilled glass syringes for subcutaneous oncology and immunology portfolios. FDA updated device master file requirements are compressing supplier qualification timelines to 12-18 months. BD and Terumo Corporation maintain fill-finish partnerships with Boston-Cambridge biotech corridors.
Switzerland
Swissmedic's alignment with EMA MDR implementation creates regulatory continuity for Basel-Zurich biopharma manufacturing networks. Roche and Novartis contract manufacturing organizations specify FIOLAX-compatible glass for parenteral biologics stability. The Lake Geneva region concentrates sterile packaging validation expertise serving European and US markets simultaneously.
Japan
PMDA's pharmaceutical and medical device combined review pathway accommodates prefilled syringe submissions for rheumatology and endocrinology self-administration therapies. Terumo Corporation and Nipro Corporation supply domestic diabetes and growth hormone markets from Kanto and Kansai production bases. METI's medical device industry support programs subsidize siliconization process automation.
India
CDSCO's medical device rules implementation is elevating documentation standards for imported glass primary packaging used in domestic biologics manufacturing. Serum Institute of India and Bharat Biotech tender WHO-prequalified prefilled syringes for national immunization programs. Gujarat and Maharashtra states are emerging as fill-finish contract manufacturing destinations for export-oriented vaccine production.
Glass Syringe Market Key Industry Players
Player mix skews toward integrated borosilicate glass manufacturers with captive tube supply and notified body relationships. The supplier base concentrates across three tiers: pharmaceutical-grade glass specialists with melt-to-syringe integration, fill-finish service providers with device assembly capabilities, and regional distributors with sterilization partnerships. Strategic moves center on M&A for siliconization technology access and capacity expansion for biologics pipeline commitments.
Within the integrated manufacturing tier, Gerresheimer AG and SCHOTT Pharma exemplify archetypes of tube-to-syringe quality continuity. Nipro Corporation occupies a differentiated position through surface coating specialization. These three anchors demonstrate how regulatory documentation burdens favor suppliers with unified control over borosilicate chemistry, forming, and drug-contact surface engineering.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Nipro Corporation |
| Stevanato Group |
| SCHOTT Pharma |
| BD |
| Terumo Corporation |
| GROUPE GUILLIN |
| Ampulla Ltd. |
| Ompi srl |
| Others |
Cost & Logistics Intelligence
Long-term offtake contracts between biologics manufacturers and German glass tubing suppliers lock in both FIOLAX supply access and price visibility across multi-year fill-finish commitments. These arrangements insulate pharmaceutical customers from medical-grade silicone oil volatility while embedding ISO 11040-4 qualification costs into negotiated unit economics.
Pricing Analysis
Certification level creates the primary spread between ISO 11040-4 qualified suppliers and standard-grade merchants. Three-tier pricing structure across MDR-compliant, FDA master-filed, and unqualified tiers reflects notified body investment amortization. Cost compression in standard-grade segments is intensifying because polymer substitution captures non-biologic generic volume. Diagnostic labs and research institutions exhibit highest price sensitivity, while monoclonal antibody developers prioritize qualification over unit cost.
Supply Chain Analysis
Inventory buffers at Rhine-Main fill-finish facilities now extend to 90-120 days given borosilicate glass supply concentration. Melt-to-syringe integration in Germany, Switzerland, and Japan draws from semiconductor-grade silicone oil feedstocks. Single-source vulnerability at FIOLAX-equivalent tubing facilities represents the dominant structural risk. Distribution runs through specialized pharmaceutical distributors rather than direct manufacturer relationships in German and Swiss acute care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as EMA MDR reclassification bifurcates qualified and non-qualified supplier tiers. Home healthcare self-administration protocols are spawning demand for intuitive safety-engineered designs that incumbent glass specialists underserve.
For Market Incumbents: Fortify backward integration into medical-grade silicone oil supply through long-term offtake agreements with semiconductor chemical suppliers. Lock in dual-source MDR certification with German and French notified bodies before submission backlogs extend further. Polymer substitution in non-biologic segments threatens volume retention in standard-grade tiers. For New Entrants and Emerging Players: ISO 11040-4 fast-track partnerships with established notified bodies offer the most viable entry path for regional fill-finish specialists. Target Indian and Brazilian vaccine manufacturing corridors where WHO prequalification standards create qualification shortcuts absent in EMA jurisdictions. Plasma-deposited barrier coating technologies provide differentiation for pH-sensitive biologics incompatible with standard siliconization. For Investors and Strategic Acquirers: Surface coating specialists with proprietary protein-adsorption reduction technologies represent the most defensible acquisition archetype in a consolidating supplier base. Long-term viability hinges on exposure to biologics pipeline depth rather than commoditized diagnostic volume. Watch for FDA device master file submission acceleration as signal that qualification timelines are compressing toward 12-month cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11040-4 Certification Fast-Track | MDR Class III reclassification creates 18-24 month qualification backlogs at German notified bodies. |
| Backward Integration into Borosilicate Tubing | Captive FIOLAX-equivalent melt capacity eliminates single-source dependency for syringe manufacturers. |
| Plasma-Deposited Barrier Coating Development | pH-sensitive biologic formulations previously incompatible with glass now become addressable. |
| Home Healthcare Safety Mechanism Integration | Patient self-administration protocols in rheumatology and endocrinology demand intuitive needlestick prevention. |
| Indian WHO-Prequalification Tender Positioning | National immunization programs in India and Brazil specify harmonized standards bypassing EMA documentation burdens. |
Research Approach
A standing panel of biologics manufacturing executives, regulatory affairs leads at German notified bodies, hospital GPO contracts managers, and pharmaceutical packaging procurement directors provided ongoing calibration against secondary validation. FDA device master file databases, EMA MDR submission records, ISO certification registries, and USP extractables testing protocols supplied triangulation anchors. Bottom-up volume modeling across product tiers reconciled with top-down pharmaceutical packaging expenditure estimates.
Consistency checks against external benchmarks validated projection outputs across the modeling period. Segmentation dimensions included connection security configuration, end-user channel, therapeutic application, and regional regulatory cluster. CAGRs derived from unit volume trajectory analysis incorporating biologics pipeline expansion rates and polymer substitution elasticity. Forecast inputs captured siliconization cost volatility and notified body qualification timeline fluctuations.
Decision-makers should treat outputs as directional under assumptions of sustained EMA MDR enforcement and stable borosilicate glass melt capacity; material deviation in regulatory implementation pace or feedstock supply disruption would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Micro Injection Molding Medical Devices Market
Medical Devices
Non-Invasive Intracranial Pressure Monitoring Device Market
Medical Devices
Canada Ultrasound Devices Market
Medical Devices
Bone Densitometer Devices Market
Medical Devices
Intraoperative Sensor Market
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
Ventricular Restoration Systems Market
Medical Devices
Spinal Thoracolumbar Implants Market
Medical Devices
Global Surgical Robotics Market
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Upper Limb Prosthetics Market
Medical Devices
Blood Warmer Devices/Sample Warmer Market
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Double-Lumen Biliary Catheters Market