
 Global Micro Injection Molding Medical Devices Market | 2026-2036
Global Micro Injection Molding Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Micro Injection Molding Medical Devices Market Foresight
Polyether ether ketone is realigning cost structures as it displaces metal alloys in orthopedic micro-implants and surgical fixtures. Spectrum Plastics Group leverages captive toolmaking to compress development cycles for drug delivery devices. SMC Ltd. anchors its position through cleanroom manufacturing scale across North American and European facilities. Accumold specializes in two-shot micro-molding for diagnostic consumables requiring dissimilar material bonding.
Micro injection molding medical devices refers to the precision fabrication of components with shot weights below one gram and tolerances reaching ±0.01 millimeters, typically executed in ISO Class 7 or 8 cleanrooms using hardened steel molds with multi-cavity layouts. The process serves primarily to manufacture disposable and implantable instruments where geometric fidelity directly determines clinical performance. Catheters and drug delivery systems command the deepest margin pools due to polymer formulation complexity and sterilization validation requirements. Diagnostic devices represent the fastest-expanding application cluster as point-of-care testing platforms proliferate. Multi-shot molding technology is displacing cold runner systems in high-volume programs where cycle time reduction justifies capital intensity.
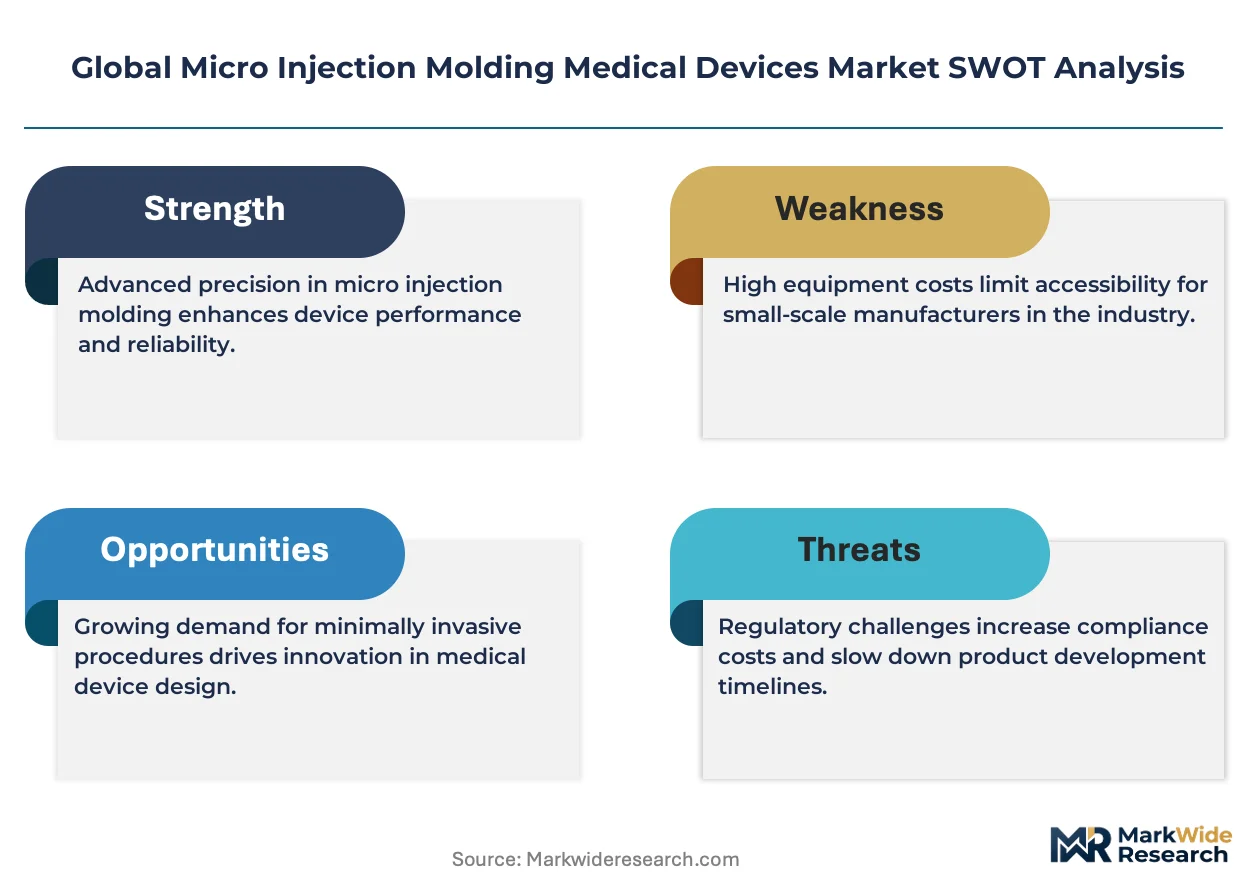
FDA 21 CFR Part 820 quality system regulations and the EU Medical Device Regulation impose design control and post-market surveillance obligations that filter out undercapitalized entrants. ISO 13485 certification functions as a baseline credential for supplier qualification by original equipment manufacturers across Japan, the United States, and Switzerland. Stakeholders must monitor how the EU AI Act's risk classification framework applies to software-integrated diagnostic devices containing micro-molded sensor housings.
Market Dynamics
Polyether ether ketone displacement of metal alloys is compressing orthopedic implant cost structures while FDA biocompatibility guidance tightens compliance thresholds for polymer suppliers serving minimally invasive surgery suites.
Growth Catalysts
- EU Medical Device Regulation:Post-market surveillance obligations are filtering out undercapitalized molders and consolidating procurement around ISO 13485-certified suppliers with validated sterilization protocols.
- Point-of-care diagnostic platforms:Disposable micro-molded consumables for rapid testing are expanding cavity utilization rates at contract manufacturers serving clinical laboratory networks.
- Multi-shot micro-molding:Two-shot bonding of dissimilar polymers is displacing cold runner assemblies in high-volume drug delivery programs where cycle time reduction justifies tooling capital.
Market Restraints
- Tooling capital intensity:Hardened steel multi-cavity molds for ±0.01mm tolerance components require 18-24 month amortization periods that strain mid-tier contract manufacturers.
- German supply concentration:The Stuttgart-Freiburg medical technology corridor concentrates procurement of catheter micro-components, creating geographic vulnerability to regional logistics disruptions.
- Metal alloy substitution limits:Titanium and cobalt-chrome retain structural dominance in load-bearing orthopedic applications where PEEK creep resistance remains insufficient.
Strategic Opportunities
- Japan's PMDA pathway:Streamlined approval for micro-molded diagnostic housings creates first-mover advantage for manufacturers with existing FDA 510(k) clearances.
- Software-integrated sensor housings:The EU AI Act's risk classification framework for diagnostic devices containing embedded electronics opens specialized molding niches requiring electromagnetic shielding integration.
- Cleanroom-as-a-service models:Third-party validated ISO Class 7 capacity in Switzerland and Singapore allows asset-light entry for polymer compounders seeking medical qualification.
Industry Challenges
- Biocompatibility validation timelines:ISO 10993 cytotoxicity and sensitization testing for new polymer grades extends development cycles by 8-14 months.
- Micro-tooling craftsmanship scarcity:Mold fabrication for sub-gram shot weights requires specialized EDM and polishing competencies concentrated among aging technician cohorts in Germany and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Micro Injection Molding Medical Devices Market |
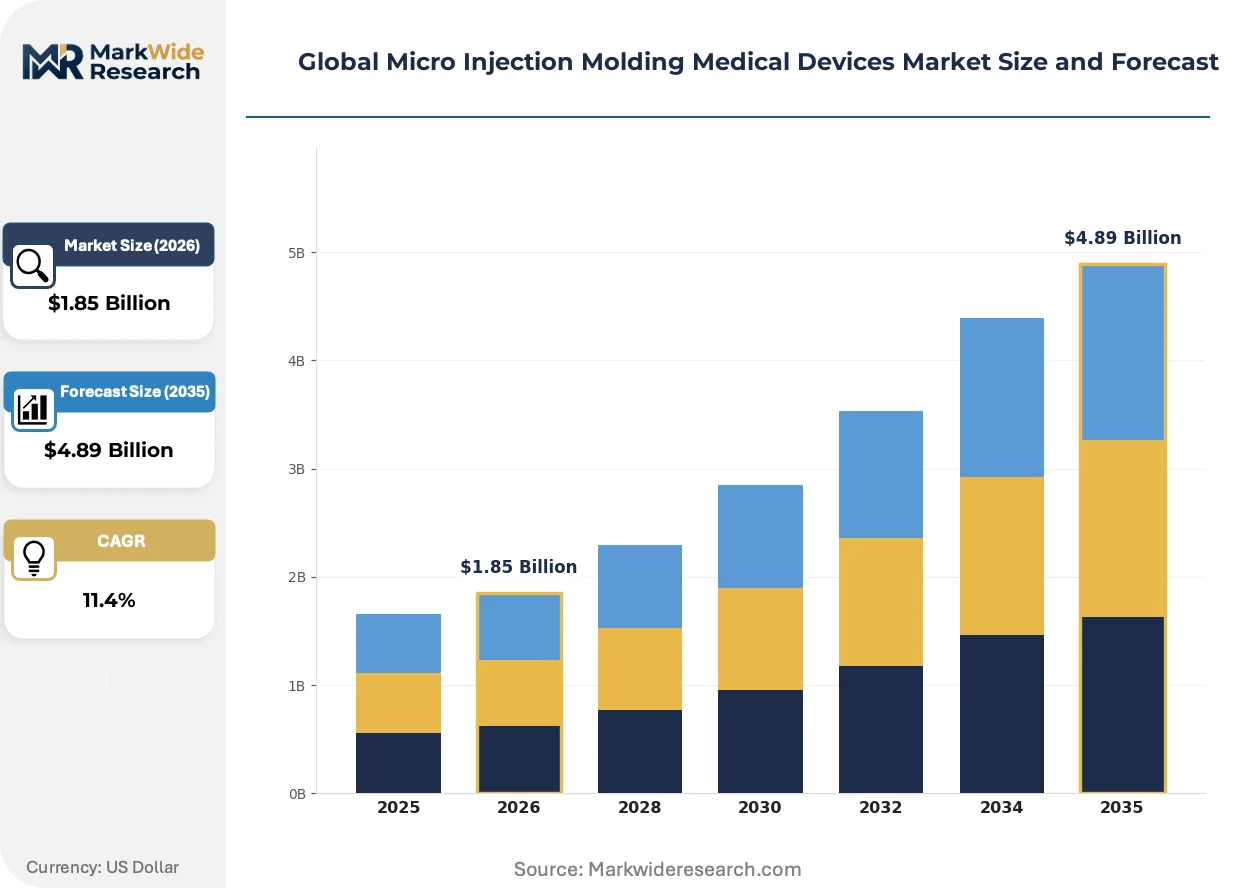
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Surgical Instruments, Diagnostic Devices, Drug Delivery Systems, Orthopedic Implants Technology: Micro-molding, Hot Runner, Cold Runner, Multi-shot Molding, Insert Molding End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Research Institutes Application: Minimally Invasive Surgery, Cardiovascular, Ophthalmology, Dental, Neurology |
| Companies Covered | Spectrum Plastics Group, SMC Ltd., Phillips-Medisize, TPI Plastics, Nolato MediTech, Accumold, Viant Medical, Seaskymedical, Röchling Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Micro Injection Molding Medical Devices Market Shifts & Advancements
Precision polymer processing is intersecting with software-defined diagnostics and automated quality systems to redefine how micro-molded components enter regulated supply chains.
Micro-molding process control systems are converging with machine vision inspection platforms to enable real-time cavity pressure monitoring and automatic rejection of dimensional outliers. High-volume drug delivery device manufacturers are adopting these integrated cells to reduce manual inspection headcount. This convergence is compressing validation timelines for multi-cavity tooling by embedding statistical process control directly into production workflows.
The EU AI Act's risk-based classification for software-integrated medical devices is forcing micro-molders to document electromagnetic compatibility of sensor housings alongside traditional biocompatibility credentials. Device manufacturers are responding by qualifying secondary suppliers with existing electronics encapsulation expertise. Diagnostic platforms containing wireless communication modules face the steepest compliance burden under this framework.
Hospital procurement consortia are consolidating vendor panels for disposable surgical instruments around full-service molders with captive toolmaking and sterilization validation capabilities. Small-batch diagnostic startups are losing access to tier-one cleanroom capacity as contract manufacturers prioritize volume commitments from integrated delivery networks. This concentration is most visible in the United States, where group purchasing organizations now mandate single-source accountability for entire instrument kits.
Global Micro Injection Molding Medical Devices Market Segmentation
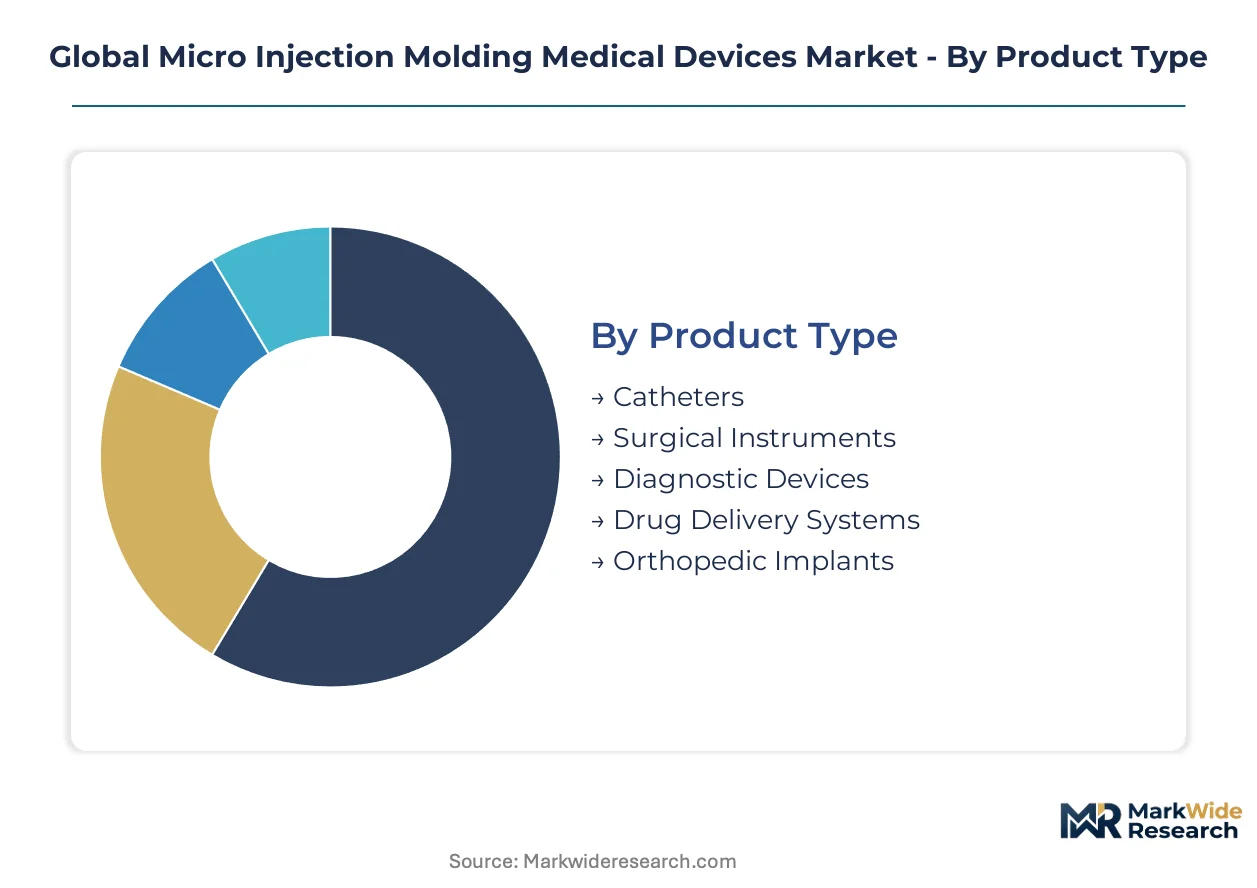
Micro injection molding medical devices demand precise segmentation because polymer selection, sterilization protocols, and dimensional tolerances vary dramatically across clinical applications. Regulatory pathways from FDA 510(k) to EU MDR conformity assessments impose distinct validation burdens on each segment category.
Product Type:
ISO 10993 biocompatibility testing intensity and FDA implantable device classifications determine which product types face the steepest regulatory barriers to commercialization.
- Catheters:Multi-lumen tubing and hub assemblies require validated bonding of dissimilar polymers under ISO 13485 protocols. Demand concentrates in Germany's Stuttgart-Freiburg medical technology corridor, where procurement of micro-molded catheter components is tightening around suppliers with captive toolmaking and sterilization validation.
- Drug Delivery Systems:Precision dosing mechanisms with sub-gram shot weights demand hardened steel molds achieving ±0.01mm tolerances. Hospitals in the United States prioritize these devices for minimally invasive surgery suites, though 18-24 month tooling amortization periods strain mid-tier contract manufacturers.
- Diagnostic Devices:Point-of-care testing platforms drive fastest-expanding demand for disposable micro-molded consumables.
- Surgical Instruments:Group purchasing organizations now mandate single-source accountability for entire instrument kits.
- Orthopedic Implants:PEEK displacement of metal alloys is compressing cost structures while load-bearing applications retain titanium and cobalt-chrome dominance.
Catheters sit at the top of the volume ranking, with diagnostic devices climbing the fastest.
Technology:
Capital intensity and cycle time economics separate technologies that justify premium tooling investment from legacy systems facing displacement.
- Multi-shot Molding:Two-shot bonding of dissimilar polymers enables complex geometries without secondary assembly. High-volume drug delivery programs in Japan and Switzerland adopt this technology where cycle time reduction justifies capital intensity, particularly for PMDA-approved diagnostic housings.
- Micro-molding:Shot weights below one gram with multi-cavity hardened steel molds define the precision threshold for implantable components. Cleanroom manufacturing scale across North American and European facilities anchors competitive positioning for ISO Class 7 production.
- Hot Runner:Eliminates cold runner waste in high-cavity layouts for disposable surgical instruments.
- Cold Runner:Retains cost advantage in low-volume diagnostic prototyping despite longer cycle times.
- Insert Molding:Encapsulates electronics for software-integrated sensor housings facing EU AI Act electromagnetic compatibility documentation.
Micro-molding commands the deepest installed base, with multi-shot molding gaining share fastest among new capital deployments.
End User:
Procurement consolidation and volume commitments determine which end users secure priority access to tier-one cleanroom capacity.
- Hospitals:Integrated delivery networks in the United States consolidate vendor panels around full-service molders with validated sterilization protocols. Minimally invasive surgery suites prioritize precision instrumentation with documented biocompatibility credentials.
- Diagnostic Laboratories:Clinical laboratory networks expand cavity utilization rates at contract manufacturers for rapid testing consumables. Point-of-care platform proliferation drives fastest-expanding demand cluster.
- Ambulatory Surgical Centers:Cost pressure favors disposable instrument kits over reusable metal alternatives.
- Research Institutes:Small-batch diagnostic startups lose tier-one cleanroom access as manufacturers prioritize volume commitments.
Hospitals sit at the top of the volume ranking, with diagnostic laboratories climbing the fastest.
Application:
Anatomical complexity and regulatory classification stringency shape polymer selection and mold design requirements across clinical specialties.
- Minimally Invasive Surgery:Precision instrumentation with geometric fidelity determining clinical performance requires ISO Class 7 or 8 cleanroom production. FDA's updated biocompatibility guidance tightens compliance thresholds for polymer suppliers serving this application.
- Cardiovascular:Catheter-based interventions demand multi-lumen micro-molding with validated sterilization protocols. The Stuttgart-Freiburg corridor concentrates European procurement for these components.
- Ophthalmology:Sub-millimeter tolerances for intraocular devices require specialized EDM and polishing competencies concentrated in Germany and Japan.
- Neurology:Implantable stimulator housings face EU AI Act risk classification for software-integrated devices.
- Dental:Orthodontic micro-implants adopt PEEK for cost compression in non-load-bearing applications.
Minimally invasive surgery sits at the top of the volume ranking, with ophthalmology climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Stuttgart-Freiburg medical technology corridor concentrates European procurement of micro-molded catheter components, while the United States and Japan anchor demand for precision diagnostic housings and drug delivery systems. Switzerland and Singapore offer specialized cleanroom capacity serving global polymer compounders seeking medical qualification.
United States
FDA 21 CFR Part 820 quality system regulations filter undercapitalized molders from the supplier base. Group purchasing organizations mandate single-source accountability for disposable surgical instrument kits, consolidating procurement around full-service manufacturers. Minnesota and Massachusetts host dense clusters of contract manufacturers serving integrated delivery networks with validated sterilization protocols.
Germany
The EU Medical Device Regulation imposes post-market surveillance obligations that consolidate procurement around ISO 13485-certified suppliers. The Stuttgart-Freiburg corridor concentrates demand for multi-lumen catheter micro-components, creating geographic vulnerability to regional logistics disruptions. Baden-Württemberg's tooling craftsmen supply hardened steel molds achieving ±0.01mm tolerances for orthopedic micro-implants.
Japan
PMDA streamlined approval pathways for micro-molded diagnostic housings create first-mover advantage for manufacturers with existing FDA 510(k) clearances. METI industrial policy supports domestic production of precision polymer components for minimally invasive surgery suites. Nagoya and Osaka host specialized EDM and polishing competencies for sub-gram shot weight molds.
Switzerland
Swissmedic certification requirements anchor premium positioning for implantable device suppliers serving European orthopedic and cardiovascular markets. Cleanroom-as-a-service models in the Zurich-Basel corridor allow asset-light entry for polymer compounders seeking medical qualification. The country's precision engineering heritage concentrates mold fabrication expertise for ophthalmic micro-components.
Singapore
The country's national biomedical regulator enforces ISO 13485 alignment for contract manufacturers serving Asia-Pacific diagnostic laboratory networks. Third-party validated ISO Class 7 capacity attracts polymer compounders seeking regional medical qualification without capital-intensive facility investment. The Tuas biomedical park clusters precision molding operations for point-of-care testing platforms.
Global Micro Injection Molding Medical Devices Market Competitive Landscape
Global majors compete with regional champions across cleanroom manufacturing scale and captive toolmaking capabilities. The vendor base stratifies into three tiers: integrated device manufacturers with sterilization validation, specialized contract molders with multi-shot technology, and regional fabricators serving prototyping and low-volume programs. Dominant competitive moves include backward integration into mold fabrication and geographic expansion through cleanroom-as-a-service partnerships.
Among North American fabricators, Spectrum Plastics Group and Accumold occupy positions within the precision-tier segment, while SMC Ltd. represents the cleanroom-scale archetype. These three exemplify divergent strategic postures: captive toolmaking compression of development cycles, two-shot micro-molding specialization for diagnostic consumables, and multi-continental ISO Class 7 manufacturing footprint. Each anchors a distinct value proposition within hospital procurement consortia and diagnostic laboratory supply chains.
| Leading Market Players |
|---|
| Spectrum Plastics Group |
| SMC Ltd. |
| Phillips-Medisize |
| TPI Plastics |
| Nolato MediTech |
| Accumold |
| Viant Medical |
| Seaskymedical |
| Röchling Medical |
| Others |
Supply & Pricing Matrix
Hospital group purchasing organizations in the United States anchor procurement consolidation for disposable surgical instrument kits, forcing contract manufacturers toward value-based pricing that bundles sterilization validation with multi-cavity tooling amortization. This buyer concentration rewards full-service molders with captive cleanroom capacity while squeezing mid-tier fabricators into commodity-tier positioning.
Pricing Analysis
Hardened steel mold fabrication costs and polymer formulation complexity drive input-cost pass-through into catheter and drug delivery system pricing. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified suppliers with validated sterilization protocols from uncertified regional fabricators. Pricing pressure stems from German supply concentration in the Stuttgart-Freiburg corridor, where logistics vulnerability compresses margin buffers. Small-batch diagnostic startups exhibit highest price sensitivity as they lose tier-one cleanroom access to volume-committed integrated delivery networks.
Supply Chain Analysis
Reverse-logistics flows for micro-molded components remain minimal given single-use disposable design, though implantable orthopedic devices trigger specialized recall and traceability protocols under FDA 21 CFR Part 820. Supply concentrates in Germany, the United States, and Japan, with Baden-Württemberg tooling craftsmen and Nagoya EDM specialists anchoring precision mold fabrication. The supply chain draws from medical-grade polymer compounders and hardened steel suppliers, with single-source vulnerability concentrated among aging technician cohorts. Distribution runs through hospital procurement consortia and diagnostic laboratory networks with validated supplier qualification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyether ether ketone displacement of metal alloys in orthopedic micro-implants creates margin-expansion headroom for compounders mastering biocompatibility validation timelines. Premium-tier positioning accrues to molders integrating multi-shot technology with ISO Class 7 cleanroom scale.
For Market Incumbents: Hedge against German supply concentration by diversifying mold fabrication partnerships to Switzerland and Singapore cleanroom-as-a-service operators. Deepen backward integration into polymer compounding to capture PEEK formulation premiums, while accelerating sterilization validation capacity to defend against emerging Asian contract manufacturers with cost-advantaged tooling. For New Entrants and Emerging Players: Begin with Japan's PMDA streamlined approval pathway for micro-molded diagnostic housings, leveraging existing FDA 510(k) clearances as qualification currency. Target point-of-care testing consumables as the most penetrable segment, where clinical laboratory network expansion outstrips tier-one cleanroom capacity. Pursue cleanroom-as-a-service partnerships in Singapore to bypass capital-intensive facility investment. For Investors and Strategic Acquirers: Integrated device manufacturers with sterilization validation and captive toolmaking represent the most active acquirer category in this space, consolidating regional fabricators into full-service platforms. Long-term viability centers on electromagnetic shielding integration capabilities for EU AI Act-compliant sensor housings. Monitor FDA biocompatibility guidance revisions as inflection signals for polymer supplier consolidation waves.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Scale Expansion | ISO Class 7 capacity in Switzerland and Singapore captures polymer compounders seeking medical qualification. |
| Multi-shot Technology Adoption | Two-shot bonding capabilities displace cold runner assemblies in high-volume drug delivery programs. |
| Captive Toolmaking Integration | In-house mold fabrication compresses development cycles for diagnostic consumables requiring rapid iteration. |
| Software-integrated Sensor Development | EU AI Act electromagnetic compatibility documentation opens specialized molding niches for neurology applications. |
| PEEK Formulation Investment | Polyether ether ketone compounding expertise captures orthopedic implant cost compression opportunities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at polymer compounders with secondary validation against FDA 510(k) filings, EU MDR conformity assessment databases, hospital procurement records, and ISO certification registries. Bottom-up segment sizing and top-down macroeconomic triangulation anchored market estimates.
Historical reference periods established baseline penetration rates for multi-shot molding technology and PEEK displacement trends, with projections extending across the analysis window through modeled segmentation by product type, technology tier, end-user concentration, and application complexity. CAGRs derived from weighted average of technology adoption curves and procurement consolidation patterns, incorporating sterilization validation timeline data and tooling amortization economics as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen polymer biocompatibility test failures, abrupt EU AI Act enforcement escalations, and regional logistics disruptions affecting German tooling corridors. Practitioners should monitor FDA guidance revisions on implantable polymer testing and PMDA approval pathway modifications for early signals of forecast variance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Australia Medtech Market
Medical Devices
Asia-Pacific Single-Use Medical Device Reprocessing Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Injectable Bulking Agents Market
Medical Devices
MRI Safe Defibrillator Market
Medical Devices
US Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Skin Rejuvenation Devices Market
Medical Devices
Bone Allografts Market
Medical Devices
Massage Equipment Market
Medical Devices
Polysomnography Devices Market
Medical Devices
Pericardial Patches Market
Medical Devices
Japan Hemostats Market
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
Pressure Mapping Systems in Healthcare Market
Medical Devices
Coronary Guidewires Market
Medical Devices
Electrosurgery Accessories Market