
 Blood Warmer Devices/Sample Warmer Market | 2026-2036
Blood Warmer Devices/Sample Warmer Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Warmer Devices/Sample Warmer Market Analysis
The EU Medical Device Regulation (MDR) is recalibrating design and documentation burdens for manufacturers serving European healthcare systems. 3M Company leverages its materials science heritage to sustain competitive positioning in conductive warming surfaces. Barkey GmbH & Co. KG anchors its presence through specialized stationary warming systems engineered for German hospital protocols. GE Healthcare competes on integrated monitoring platforms that bundle temperature management with broader perioperative workflows.
Blood warmer devices and sample warmers are electromechanical instruments that maintain biological fluids between 37°C and 42°C through resistive, infrared, or conductive heating elements, preventing hypothermia-induced coagulopathy during transfusion or preserving enzymatic stability in laboratory specimens. Portable warmers command premium positioning in emergency and prehospital settings where mobility constraints dominate purchasing criteria. Stationary warmers retain volume leadership in operating rooms and blood banks where throughput reliability and multi-line capacity determine procurement decisions. Resistive heating technology occupies the largest installed base due to proven clinical validation, though infrared systems are gaining traction in ambulatory applications where rapid warming cycles reduce turnaround pressure.
FDA 510(k) premarket notification requirements shape device classification and clinical evidence thresholds for US market entry, while EU MDR technical documentation demands strain smaller manufacturers with limited quality management resources. Japan's PMDA enforces Japan Industrial Standards (JIS) compatibility that influences heating element specifications and electrical safety testing protocols. Stakeholders must monitor evolving harmonization between ISO 13485 quality systems and national post-market surveillance obligations as regulatory divergence creates compliance complexity.
Market Dynamics
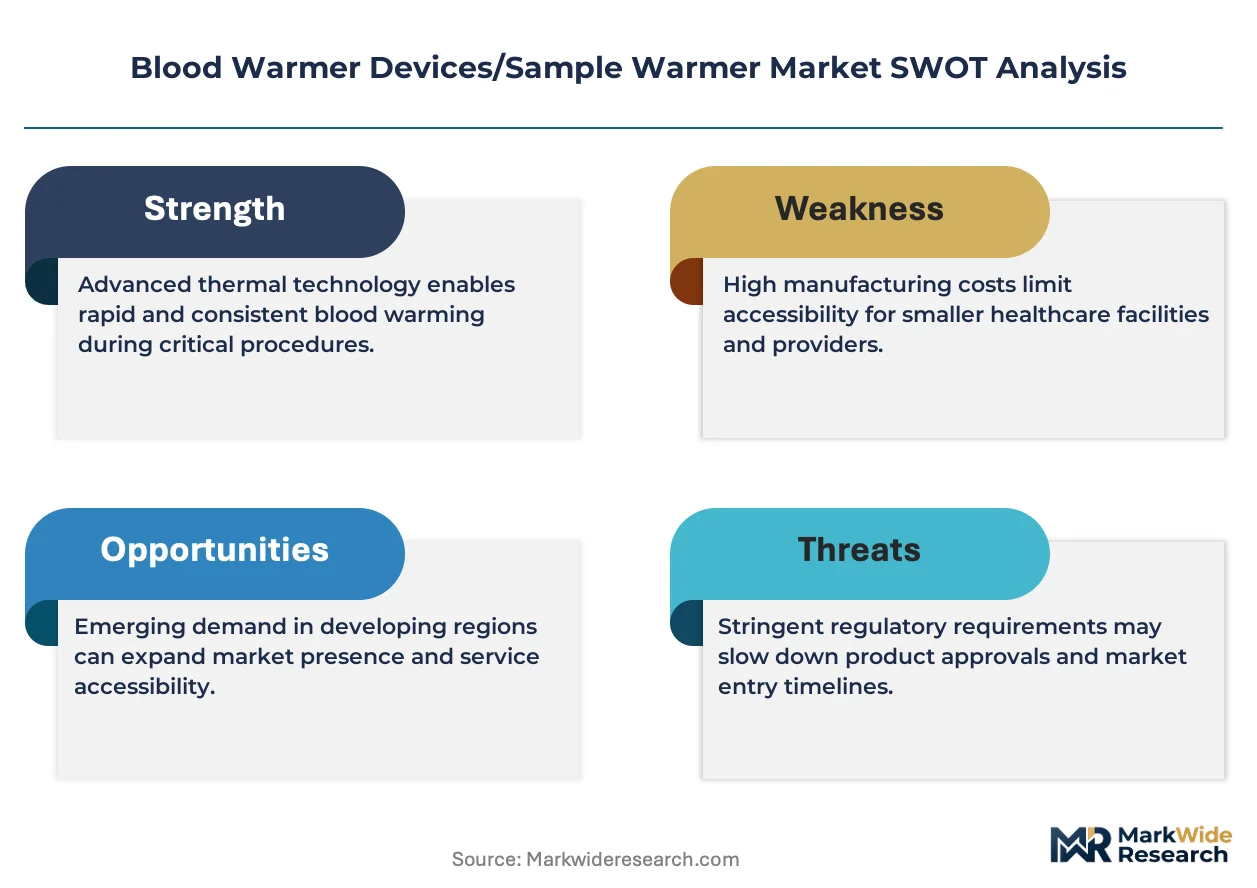
EU MDR documentation burdens and FDA 510(k) clearance pathways are compressing product development timelines while forcing smaller manufacturers to consolidate quality management resources or exit European markets entirely.
Growth Catalysts
- Trauma protocol standardization:US hospitals are embedding blood warming systems into massive transfusion protocols for hemorrhagic shock management, creating institutional purchasing mandates.
- EU MDR compliance services:Specialized regulatory consultancies are capturing value by guiding device manufacturers through technical documentation and notified body selection bottlenecks.
- Infrared warming technology:Ambulatory surgery centers are adopting rapid-cycle infrared systems to reduce specimen processing delays and improve throughput metrics.
Market Restraints
- Heating element supply concentration:Ceramic resistor and infrared emitter production clusters in East Asian manufacturing hubs, exposing buyers to logistics volatility and tariff exposure.
- EU MDR transition costs:Technical file remediation and notified body capacity constraints are extending time-to-market by months for mid-tier manufacturers with limited regulatory affairs staffing.
- Passive warming alternatives:Forced-air patient warming blankets and fluid warming cabinets compete for capital budget allocation in cost-constrained hospital systems.
Strategic Opportunities
- Prehospital emergency services:Ground and air ambulance fleets in Germany and Japan represent underpenetrated demand for battery-powered portable warmers with ruggedized enclosures.
- ISO 13485 harmonization:Converging quality system standards across FDA, PMDA, and EU MDR frameworks enable single-audit certification strategies that reduce compliance overhead.
- Sample warmer convergence:Laboratory automation platforms are integrating temperature-controlled specimen handling with LIS connectivity, opening OEM partnership channels for warming module suppliers.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies for warming surface materials create bottlenecks in design validation phases.
- Legacy system integration:Newer warming devices with digital monitoring outputs face interoperability friction with older perioperative documentation systems in US hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Warmer Devices/Sample Warmer Market |
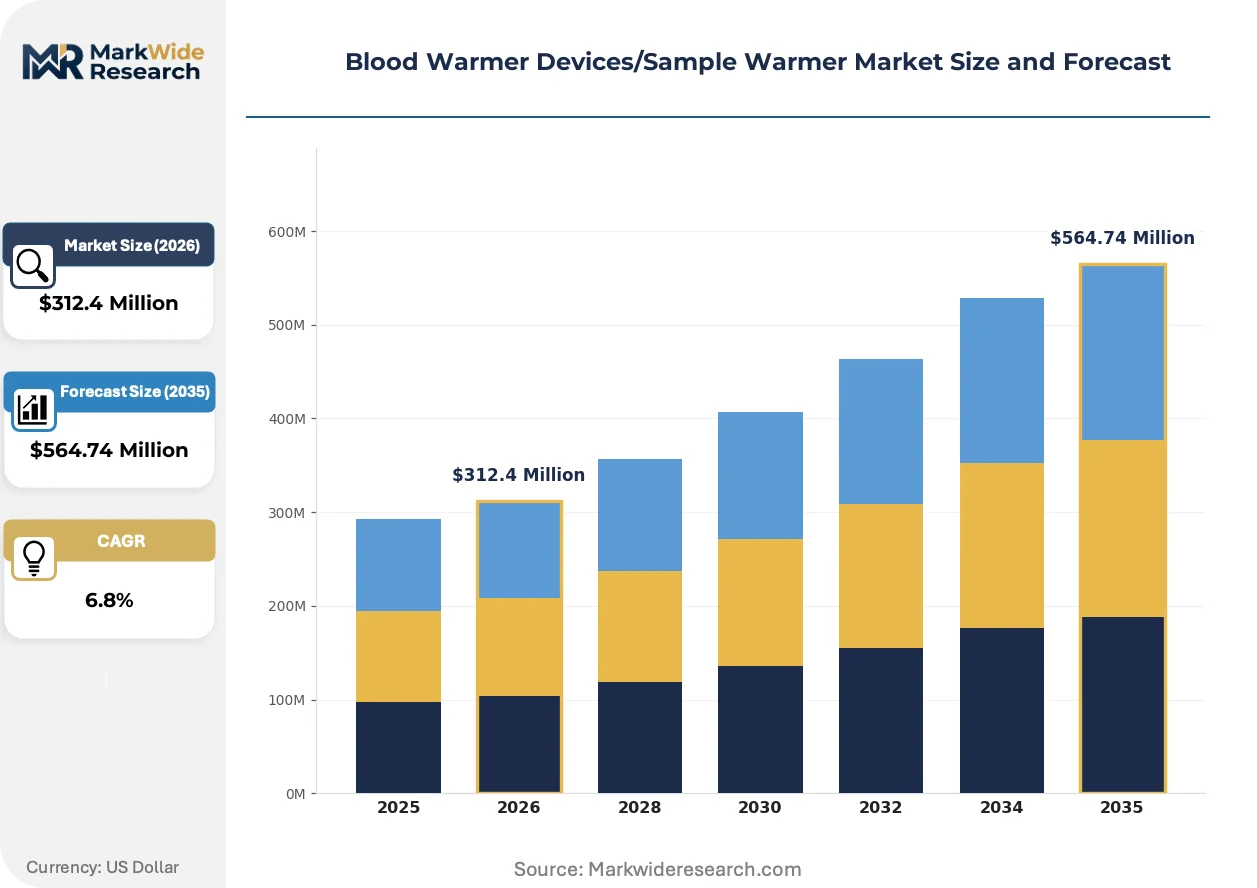
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Warmers, Stationary Warmers, Accessories, Consumables End User: Hospitals, Emergency Rooms, Ambulances, Blood Banks Technology: Resistive Heating, Infrared Heating, Conductive Heating, Microwave Technology Application: Surgery, Trauma Care, Blood Transfusion, Laboratory Procedures |
| Companies Covered | Belmont Medical Technologies, 3M Company, Becton, Dickinson and Company, Stryker Corporation, GE Healthcare, Barkey GmbH & Co. KG, The 37Company, GENTHERM, ICU Medical, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Warmer Devices/Sample Warmer Market Emerging Trajectories
Device manufacturers are racing to differentiate through embedded connectivity and predictive maintenance capabilities while regulatory documentation automation reshapes competitive economics.
Silicon carbide heating elements are absorbing thermal management demands in next-generation blood warmers, enabling faster ramp times and reduced energy consumption. German surgical centers are piloting these systems in high-throughput orthopedic procedures. This materials transition is absorbing market share from traditional nichrome resistor configurations by delivering superior temperature uniformity.
EU MDR post-market surveillance requirements are mandating systematic vigilance reporting and periodic safety update summaries for all Class IIa and above devices. Manufacturers must now maintain dedicated clinical affairs teams to manage complaint trending and risk documentation. Blood warmer suppliers with limited European revenue exposure are withdrawing from the market rather than absorbing compliance infrastructure costs.
Hospital procurement committees are consolidating temperature management device purchasing under integrated perioperative supply contracts rather than standalone capital acquisitions. This bundling behavior compresses vendor margins and favors suppliers with broad critical care portfolios. The shift is most pronounced in US health systems pursuing standardized equipment platforms across multi-hospital networks.
Blood Warmer Devices/Sample Warmer Market Segmentation
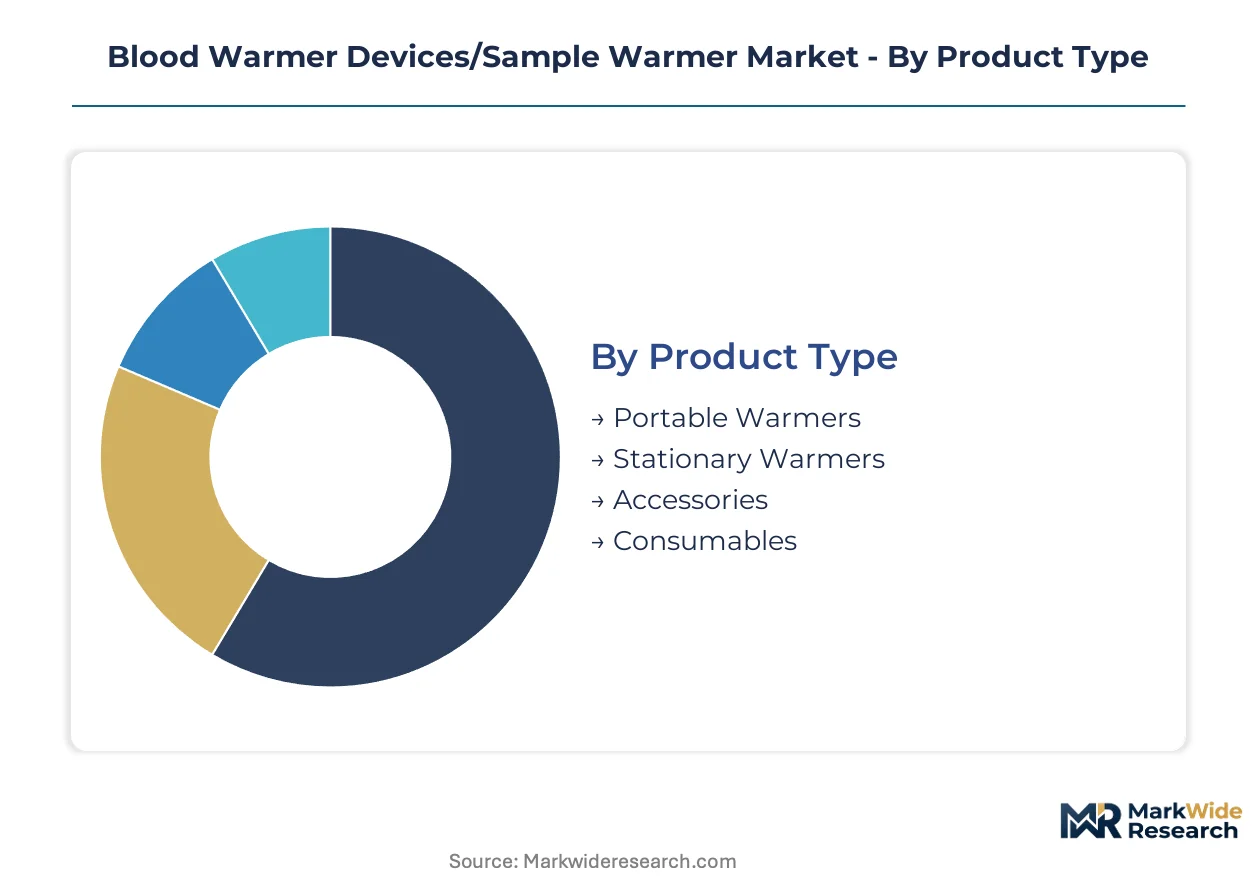
Segmentation in blood warming equipment reveals distinct regulatory pathways, technology maturities, and procurement economics that shape vendor strategy. Each dimension carries unique certification burdens, from FDA 510(k) premarket notifications for portable devices to EU MDR technical documentation for stationary systems used in surgical suites.
Product Type:
FDA 510(k) clearance timelines stretch longest for portable warmers with embedded software, while stationary systems face stricter biocompatibility testing under ISO 10993. Accessories and consumables navigate simpler regulatory routes but confront supply chain concentration risks.
- Portable Warmers:Battery-powered units with ruggedized enclosures deploy resistive or infrared elements in prehospital settings. German air ambulance fleets and Japanese ground emergency services are absorbing these devices fastest, driven by trauma protocol standardization and mobile blood administration mandates.
- Stationary Warmers:Multi-line systems with silicon carbide heating elements dominate operating room throughput. US hospitals embed these into massive transfusion protocols, while EU MDR compliance costs are compressing vendor margins and consolidating supplier bases.
- Accessories:Temperature probes, mounting brackets, and power adapters face lower regulatory barriers but depend on proprietary connector standards that lock hospitals into single-vendor ecosystems.
- Consumables:Disposable warming sleeves and sterile covers generate recurring revenue streams. Blood banks in Japan and Germany prioritize JIS-compatible and CE-marked variants respectively.
Leading the category by volume: Stationary Warmers. Expanding most quickly: Portable Warmers.
End User:
Procurement authority concentrates differently across settings — hospital committees bundle temperature management with perioperative contracts, while ambulance services make standalone capital decisions.
- Hospitals:Integrated health systems in the United States consolidate purchasing under standardized equipment platforms, favoring suppliers with broad critical care portfolios spanning warming, monitoring, and ventilation.
- Emergency Rooms:Rapid-cycle infrared systems reduce specimen processing delays. Ambulatory surgery centers in Germany pilot these configurations to improve throughput metrics.
- Ambulances:Battery-powered portable warmers with military-grade enclosures serve underpenetrated demand in German and Japanese prehospital fleets.
- Blood Banks:High-throughput facilities prioritize multi-line stationary warmers with LIS connectivity. Modernization programs in Japan and the United States drive replacement cycles.
Hospital procurement dominates absolute spend. Ambulance fleets climb fastest as prehospital warming protocols expand.
Technology:
Material science transitions are redistributing competitive advantage, with silicon carbide displacing nichrome configurations in premium segments.
- Resistive Heating:Nichrome and ceramic resistor elements occupy the largest installed base due to decades of clinical validation. US trauma centers rely on these systems for proven reliability in massive transfusion scenarios.
- Infrared Heating:Rapid warming cycles reduce turnaround pressure in ambulatory settings. German surgical centers pilot silicon carbide-enhanced infrared configurations in high-throughput orthopedic procedures.
- Conductive Heating:3M leverages materials science heritage in warming surface technologies. These systems compete with forced-air patient warming blankets for capital budget allocation.
- Microwave Technology:Emerging configurations target laboratory specimen applications where uniform heating without hot spots preserves enzymatic stability.
Resistive systems anchor installed base. Infrared configurations gain share fastest in ambulatory and prehospital segments.
Application:
Clinical use cases dictate performance specifications — surgical warming demands precise temperature uniformity, while trauma care prioritizes speed and portability.
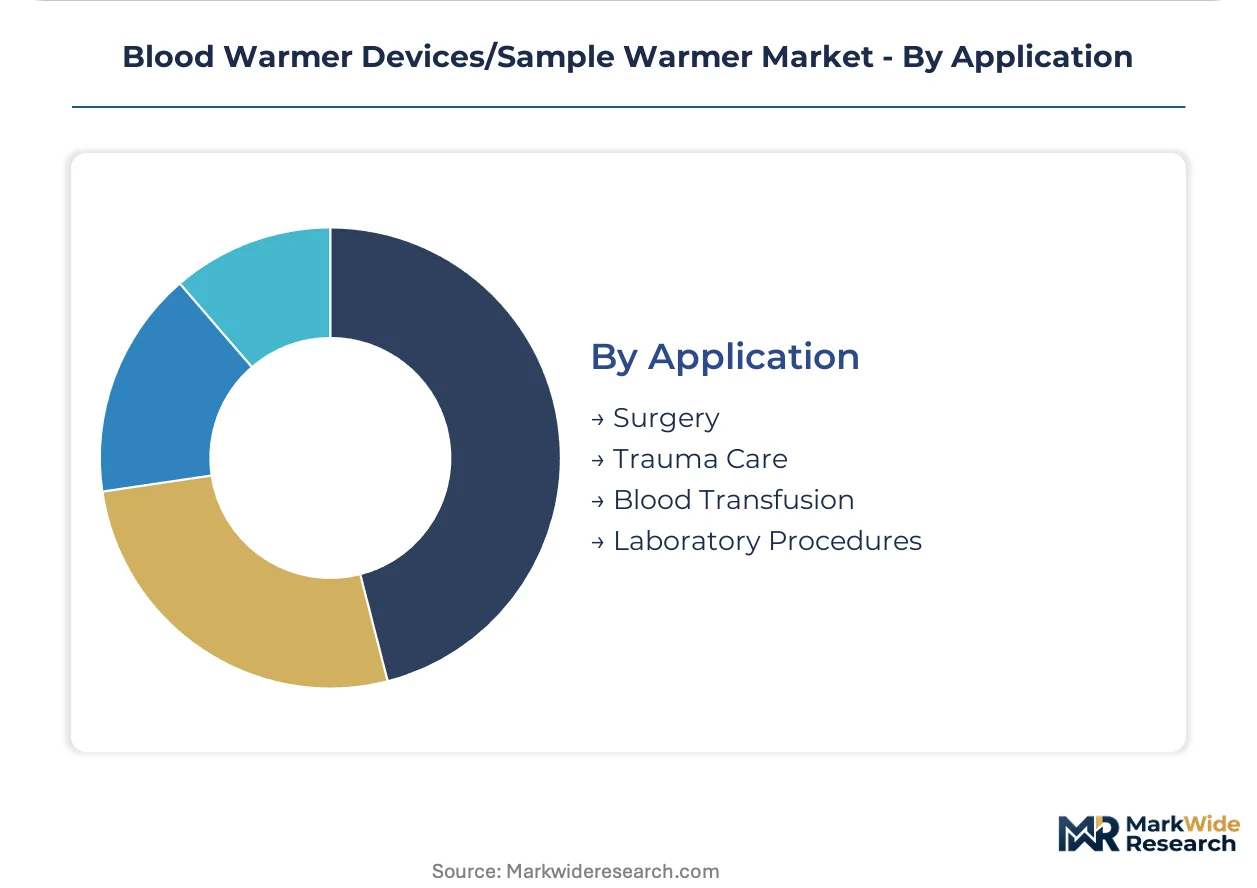
- Surgery:Perioperative temperature management prevents hypothermia-induced coagulopathy. US health systems embed warming into standardized surgical protocols across multi-hospital networks.
- Trauma Care:Hemorrhagic shock management drives institutional purchasing mandates for portable systems. German emergency medical services expand fleet deployments.
- Blood Transfusion:Blood banks in Japan modernize infrastructure under PMDA-guided safety frameworks. Multi-line capacity determines procurement decisions in high-volume facilities.
- Laboratory Procedures:Sample warmers preserve specimen integrity during automated handling. LIS-integrated modules open OEM partnership channels for warming component suppliers.
Surgery commands largest revenue pool. Trauma care demonstrates steepest expansion trajectory as prehospital protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts anchors North American device development through Boston's medical technology corridor, where trauma protocol standardization drives institutional purchasing mandates for blood warming systems.
United States
US hospitals embed warming systems into massive transfusion protocols for hemorrhagic shock management, creating institutional purchasing mandates. FDA 510(k) premarket notification requirements shape device classification and clinical evidence thresholds for market entry. The Boston-Worcester corridor concentrates R&D activity where trauma centers pilot next-generation warming configurations.
Germany
German surgical centers pilot silicon carbide heating elements in high-throughput orthopedic procedures, absorbing advanced warming technologies fastest in Europe. EU MDR technical documentation demands strain smaller manufacturers with limited quality management resources. The North Rhine-Westphalia cluster hosts specialized stationary warming system engineering aligned with German hospital protocols.
Japan
Japan's PMDA enforces Japan Industrial Standards compatibility that influences heating element specifications and electrical safety testing protocols. Blood bank modernization programs intersect with aging surgical volumes to concentrate demand. The Kanto region around Tokyo drives replacement cycles through high-throughput facility upgrades.
United Kingdom
NHS procurement committees consolidate temperature management device purchasing under integrated perioperative supply contracts. MHRA post-market surveillance requirements align with EU MDR vigilance reporting standards. London-Oxford-Cambridge corridor activity focuses on regulatory consultancy services guiding manufacturers through notified body selection.
Blood Warmer Devices/Sample Warmer Market Vendor Landscape
The competitive structure tilts toward diversified medical technology conglomerates with broad critical care portfolios. Hospital procurement consolidation favors vendors bundling warming systems with monitoring and ventilation platforms. Three archetypes dominate: materials science specialists leveraging conductive surface heritage, integrated health technology platforms embedding warming into perioperative workflows, and dedicated thermal management engineers focused on stationary throughput systems. Dominant competitive moves include strategic partnerships with laboratory information system providers and geographic withdrawal from European markets by manufacturers lacking EU MDR compliance infrastructure.
Within the diversified health technology tier, 3M Company and GE Healthcare exemplify conglomerate positioning, while Barkey GmbH & Co. KG anchors the specialized stationary systems segment. These three represent distinct strategic postures: materials science heritage, integrated platform bundling, and protocol-specific engineering depth.
| Leading Market Players |
|---|
| Belmont Medical Technologies |
| 3M Company |
| Becton, Dickinson and Company |
| Stryker Corporation |
| GE Healthcare |
| Barkey GmbH & Co. KG |
| The 37Company |
| GENTHERM |
| ICU Medical, Inc. |
| Others |
Supply Flow & Price Mechanics
Ceramic resistor and silicon carbide heating element costs cascade through blood warmer device pricing tiers, with East Asian manufacturing concentration compressing margins for mid-tier suppliers while premium OEMs absorb volatility through long-term offtake agreements with German and Japanese component specialists.
Pricing Analysis
Throughput-based value anchoring dominates hospital procurement, with stationary warmers commanding premiums tied to multi-line capacity and LIS integration depth. Price differentiation separates FDA-cleared systems from CE-marked alternatives, while customization for PMDA JIS compliance adds tier premiums. Cost compression in portable segments intensifies as battery and ruggedized enclosure inputs face logistics volatility. Emergency medical services exhibit highest price sensitivity; integrated health systems with perioperative bundling contracts show lowest.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume stationary system demand, while distributor networks serve fragmented ambulance fleet procurement. Ceramic resistor production clusters in China, Taiwan, and South Korea; silicon carbide elements source from German and Japanese specialty materials suppliers. Raw material dependencies include nichrome alloys, infrared emitter substrates, and medical-grade polymers. Single-source vulnerability around EU MDR-notified body capacity strains smaller manufacturers. Distribution runs through specialized medical device distributors with cold-chain logistics capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Notified body capacity constraints for EU MDR certification prop pricing power for compliant incumbents, as backlog delays extend time-to-market for non-compliant competitors.
For Market Incumbents: Anchor market position through backward integration into silicon carbide heating element supply, securing thermal management IP against emerging infrared specialists. Deepen ISO 13485 quality system harmonization across FDA, PMDA, and EU MDR frameworks to compress audit overhead. Defend against portable warmer entrants by locking hospital systems into multi-year perioperative equipment bundles with embedded service contracts. For New Entrants and Emerging Players: Capture white-space in German and Japanese prehospital emergency fleets, where battery-powered portable warmers with military-grade enclosures face limited incumbent penetration. Target ambulatory surgery centers adopting rapid-cycle infrared systems for throughput improvement. Pursue OEM partnership channels with laboratory automation platforms integrating temperature-controlled specimen handling modules. For Investors and Strategic Acquirers: EU MDR market withdrawals by non-compliant manufacturers is the leading indicator that consolidation opportunities are ripening for acquisition-ready platforms with notified body relationships. Frame long-term viability around 5-10 year regulatory harmonization trajectories favoring diversified critical care portfolios over standalone thermal management specialists. Watch for silicon carbide materials transition completion as inflection signal for technology obsolescence risk in nichrome-dependent targets.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Automation | Reduces notified body submission timelines for Class IIa blood warmers through AI-assisted risk management file generation. |
| Silicon Carbide Heating Element Integration | Enables faster ramp times and temperature uniformity in high-throughput orthopedic procedures at German surgical centers. |
| Prehospital Emergency Fleet Partnership | Opens underpenetrated demand in German air ambulance and Japanese ground emergency services for battery-powered portable systems. |
| LIS Connectivity Module Development | Creates OEM partnership channels with laboratory automation platforms integrating specimen warming into automated handling workflows. |
| ISO 13485 Harmonization Certification | Enables single-audit strategies across FDA, PMDA, and EU MDR frameworks, reducing compliance overhead for multi-market suppliers. |
Methodological Framework
Multi-period observation of FDA 510(k) clearance volumes, EU MDR notified body capacity utilization, and hospital capital equipment procurement cycles anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary validation drew from FDA 510(k) database filings, EU MDR EUDAMED vigilance reports, Japanese PMDA submission records, and hospital procurement databases. Bottom-up triangulation across product-type segmentation and top-down cross-check against regional surgical volume projections ensured consistency.
Input-output matrices modeled relationships between trauma protocol standardization rates, blood bank modernization program commitments, and heating element technology transitions across portable, stationary, and sample warmer configurations. Segmentation dimensions included product mobility class, end-user setting, heating technology type, and application-specific performance requirements. CAGRs derived from logistic diffusion curves fitted to adoption data across the projection horizon, with sensitivity testing around EU MDR compliance cost assumptions and silicon carbide materials substitution timelines.
The model holds under stable regulatory harmonization trajectories; deviation in notified body capacity constraints or heating element supply disruptions would shift volume projections. Forecasts reflect documented assumptions regarding trauma protocol penetration rates and laboratory automation integration velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Ovulation Microscope Market
Medical Devices
Global Microscopy Device Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
High Volume Dispensing Systems Market
Medical Devices
Polyether Ether Ketone (PEEK) Interbody Devices Market
Medical Devices
Intravascular Ultrasound [IVUS] Devices Market
Medical Devices
North America Ablation Devices Market
Medical Devices
High Intensity Focused Ultrasound (HIFU) Market
Medical Devices
Sterile Filtration Module Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Bariatric Beds Market
Medical Devices
Medical Devices Vigilance Market
Medical Devices
Ankle Syndesmosis Treatment Devices Market
Medical Devices
Multi Dose Drug Vial Adapters Market